
 Electric Sports Utility Vehicle (E-SUV) Market | 2026-2036
Electric Sports Utility Vehicle (E-SUV) Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Sports Utility Vehicle (E-SUV) Market Foresight
Fleet operators are collapsing the historical dominance of individual buyers in E-SUV procurement volumes. Tesla leverages its proprietary Supercharger network to sustain fleet conversion timelines. BMW Group anchors European corporate leasing channels with dedicated business sales divisions. Hyundai Motor Company competes aggressively on manufacturing scale across multiple battery-electric platforms.
An Electric Sports Utility Vehicle is a battery-powered or plug-in hybrid passenger vehicle with elevated ride height, all-wheel-drive capability, and typically 300-600 liters of cargo capacity, engineered for both urban commuting and light off-road duty. The primary commercial purpose centers on combining utility versatility with zero-emission powertrains to satisfy fleet decarbonization mandates and consumer preference shifts away from sedans. Mid-size E-SUVs occupy the largest volume tier due to balanced cabin dimensions and battery cost economics. Battery Electric Vehicle technology leads absolute sales while Plug-in Hybrid Electric Vehicle configurations retain residual demand among buyers with limited home charging access.
The EPA tailpipe standards and NHTSA Corporate Average Fuel Economy framework in the United States compel OEMs to expand E-SUV output or purchase regulatory credits. The EU Green Deal and F-Gas Regulation in Europe accelerate refrigerant transitions and battery supply chain due diligence requirements. China's MIIT new-energy vehicle credit system and dual carbon goals enforce production quotas that favor E-SUV scale programs. Stakeholders must monitor how IRA domestic content rules and evolving EU Battery Regulation traceability thresholds reshape cell sourcing strategies and final assembly location decisions.
Market Dynamics
Fleet procurement volumes are collapsing the historical dominance of individual buyers in E-SUV distribution channels, with corporate leasing contracts now commanding preferential allocation from cell suppliers and assembly plants.
Growth Catalysts
- IRA domestic content rules:US assembly and battery sourcing thresholds trigger tax credit eligibility, redirecting capital toward North American gigafactory construction.
- Silicon-anode chemistry:Higher energy density cells extend range thresholds without proportional pack weight increases, satisfying fleet duty-cycle requirements.
- Last-mile logistics electrification:Urban delivery operators face municipal zero-emission zone mandates in London, Amsterdam, and Singapore.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings compress cell margins and destabilize long-term fleet leasing rate structures.
- Cathode precursor concentration:Processing capacity clusters in Indonesia and the DRC, creating single-source vulnerability for nickel and cobalt supply.
- Charging deserts:Rural interstate corridors in the US Mountain West and Australian Outback lack DC fast-charging density sufficient for commercial route completion.
Strategic Opportunities
- Vehicle-to-grid integration:Bidirectional charging protocols enable fleet operators to monetize stationary battery capacity during peak grid demand windows.
- Solid-state commercialization:Toyota and QuantumScape timelines suggest 2027-2028 production readiness for energy-dense, thermally stable packs.
- EU Battery Regulation traceability:Digital product passport requirements create first-mover advantage for OEMs with audited, conflict-free supply chains.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance depots face recruitment gaps for 800V system certification, extending vehicle downtime.
- Pack thermal runaway containment:Cell-to-pack architectures complicate fire suppression protocols and insurance underwriting for underground parking installations.
- Software-defined vehicle integration:Over-the-air update pipelines require cybersecurity compliance across NHTSA, UNECE, and MIIT frameworks simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Sports Utility Vehicle (E-SUV) Market |
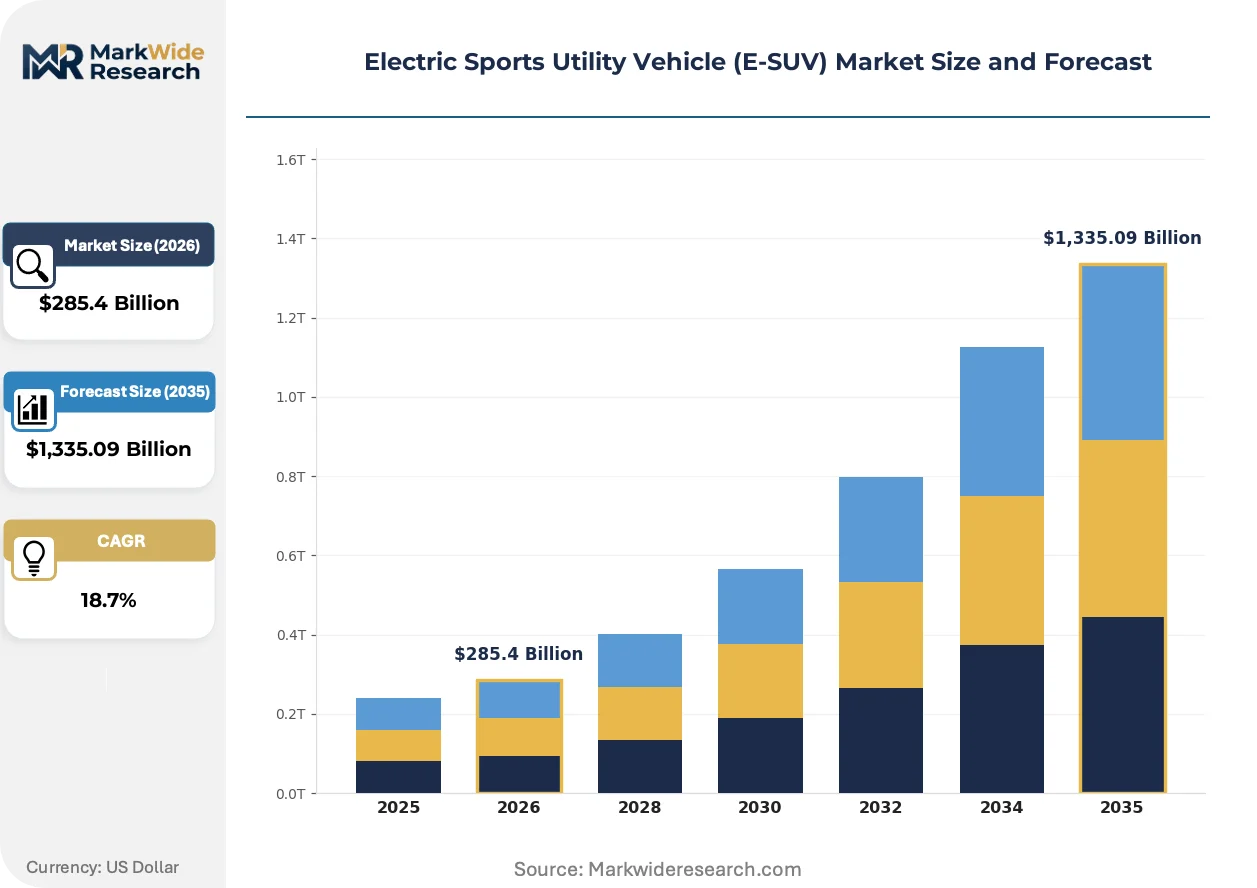
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $1,335.09 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact E-SUV, Mid-size E-SUV, Full-size E-SUV, Luxury E-SUV Technology: Battery Electric Vehicle, Plug-in Hybrid Electric Vehicle, Hydrogen Fuel Cell, Ultra-Fast Charging End User: Individual Customers, Fleet Operators, Government Agencies, Corporate Clients Distribution Channel: Direct Sales, Dealerships, Online Platforms, Leasing Services |
| Companies Covered | BMW Group, Volkswagen Group, Tesla, Rivian, Volvo Cars, Hyundai Motor Company, Mercedes-Benz, General Motors, Kia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Sports Utility Vehicle (E-SUV) Market Shifts & Advancements
Power electronics packaging and thermal management architectures are actively compressing vehicle form factors while extending duty-cycle capability. Three convergent developments dominate engineering roadmaps.
Silicon carbide inverters are replacing silicon IGBTs in traction powertrains, cutting switching losses and enabling higher motor speeds. Tier 1 suppliers are shipping 800V-capable modules to European and Chinese OEMs at volume. This semiconductor transition is miniaturizing onboard charger dimensions and liberating packaging space for cabin or cargo volume expansion.
The EU F-Gas Regulation mandates refrigerant transitions from R-134a to lower-GWP alternatives like R-1234yf and CO2 heat pumps. Thermal system suppliers must retool production lines and recalibrate range simulations. European fleet operators are prioritizing heat-pump-equipped variants to preserve winter range performance under new climate disclosure rules.
Fleet managers are consolidating procurement through direct OEM partnerships, bypassing traditional dealer networks for volume pricing and custom upfit specifications. Full-service lease providers are absorbing residual value risk in exchange for telemetry data access. This channel compression is most advanced in Germany, where corporate fleets represent over sixty percent of E-SUV registrations and have established dedicated business sales divisions with priority build slots.
Electric Sports Utility Vehicle (E-SUV) Market Segmentation
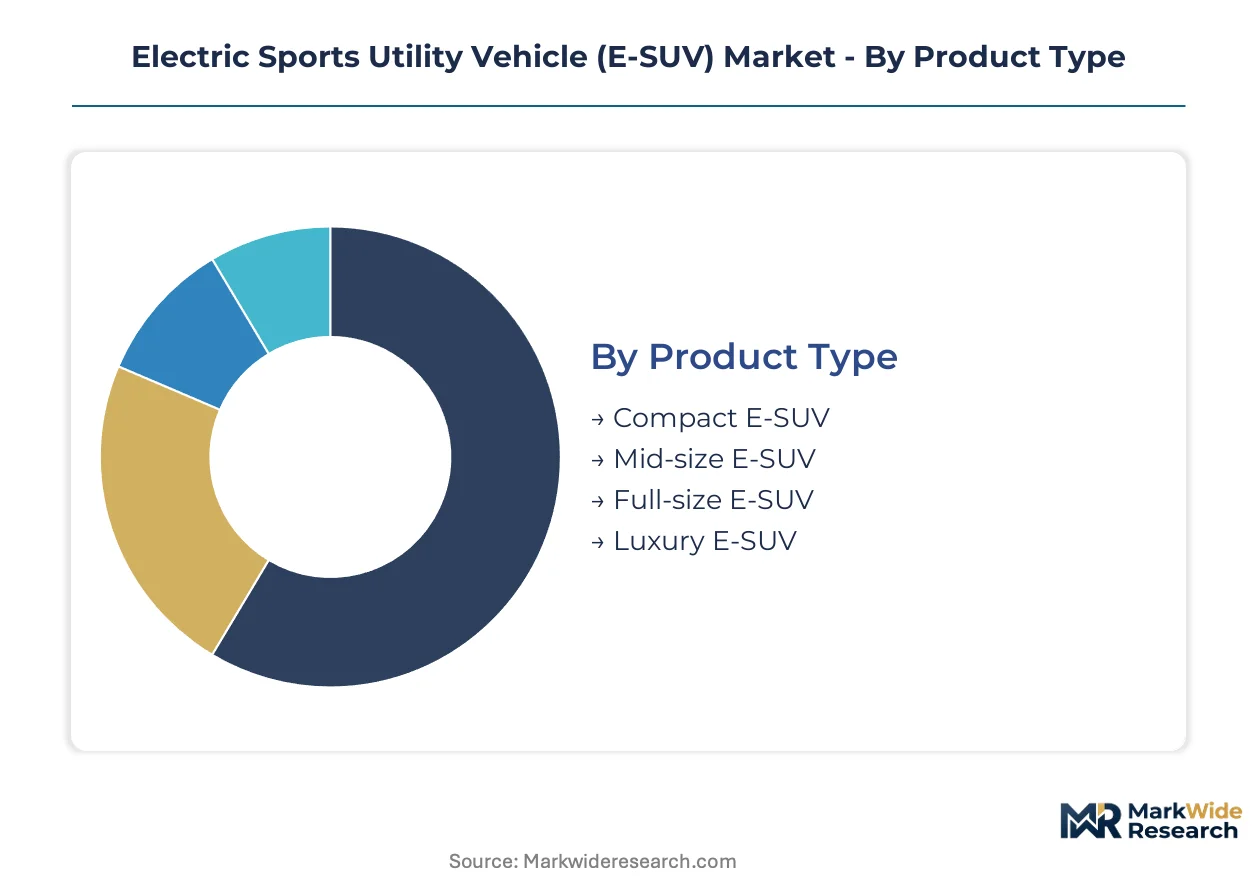
E-SUV segmentation reveals divergent margin economics across size tiers and powertrain architectures. Fleet procurement patterns and charging infrastructure maturity reshape which segments capture volume versus value concentration.
Product Type:
Margin pools concentrate in mid-size and full-size configurations where battery cost curves intersect with utility premiums.
- Mid-size E-SUV:Wheelbase dimensions between 2,700-2,900mm optimize cabin space against cell pack economics. Fleet operators in Germany and China prioritize this tier for executive transport contracts requiring range above 400km without disproportionate capital outlay.
- Full-size E-SUV:Three-row seating configurations and 600+ liter cargo volumes serve commercial logistics and premium family segments. US IRA domestic content rules favor North American assembly of this high-margin category.
- Compact E-SUV:Sub-4.5m length targets urban parking-constrained markets with 50-60kWh packs.
- Luxury E-SUV:Price points above premium tier incorporate air suspension, rear-axle steering, and bespoke interior materials.
Mid-size E-SUV holds installed capacity. Full-size E-SUV is rotating up the share rankings.
Technology:
Cost structures diverge sharply between pure-electric architectures and transitional hybrid configurations.
- Battery Electric Vehicle:Cell-to-pack architectures eliminate module housings, improving volumetric energy density above 250 Wh/L. MIIT credit quotas in China and EPA tailpipe standards in the United States mandate BEV scale programs.
- Plug-in Hybrid Electric Vehicle:40-60km electric-only range satisfies urban zero-emission zones while retaining combustion range security. European corporate fleets with limited depot charging access sustain residual PHEV demand.
- Ultra-Fast Charging:800V architectures enable 10-80% charging in under 20 minutes.
- Hydrogen Fuel Cell:PEM stack integration targets commercial fleet duty cycles with continuous high-speed operation.
Battery Electric Vehicle dominates production allocation. Ultra-Fast Charging is climbing the fastest on technical roadmaps.
End User:
Procurement volume is concentrating in institutional buyers with decarbonization mandates and scale economics.
- Fleet Operators:Last-mile logistics providers and ride-hail platforms command priority build slots through multi-year procurement contracts. Municipal zero-emission zones in London and Amsterdam accelerate fleet conversion timelines.
- Corporate Clients:ESG disclosure requirements under EU CSRD and similar frameworks in Germany drive leased vehicle electrification. Business sales divisions at European OEMs dedicate separate allocation channels.
- Individual Customers:Home charging access and purchase incentive eligibility determine conversion rates.
- Government Agencies:Public procurement rules favor domestic assembly and audited supply chains.
Fleet Operators command volume share. Corporate Clients are expanding fastest on lease penetration.
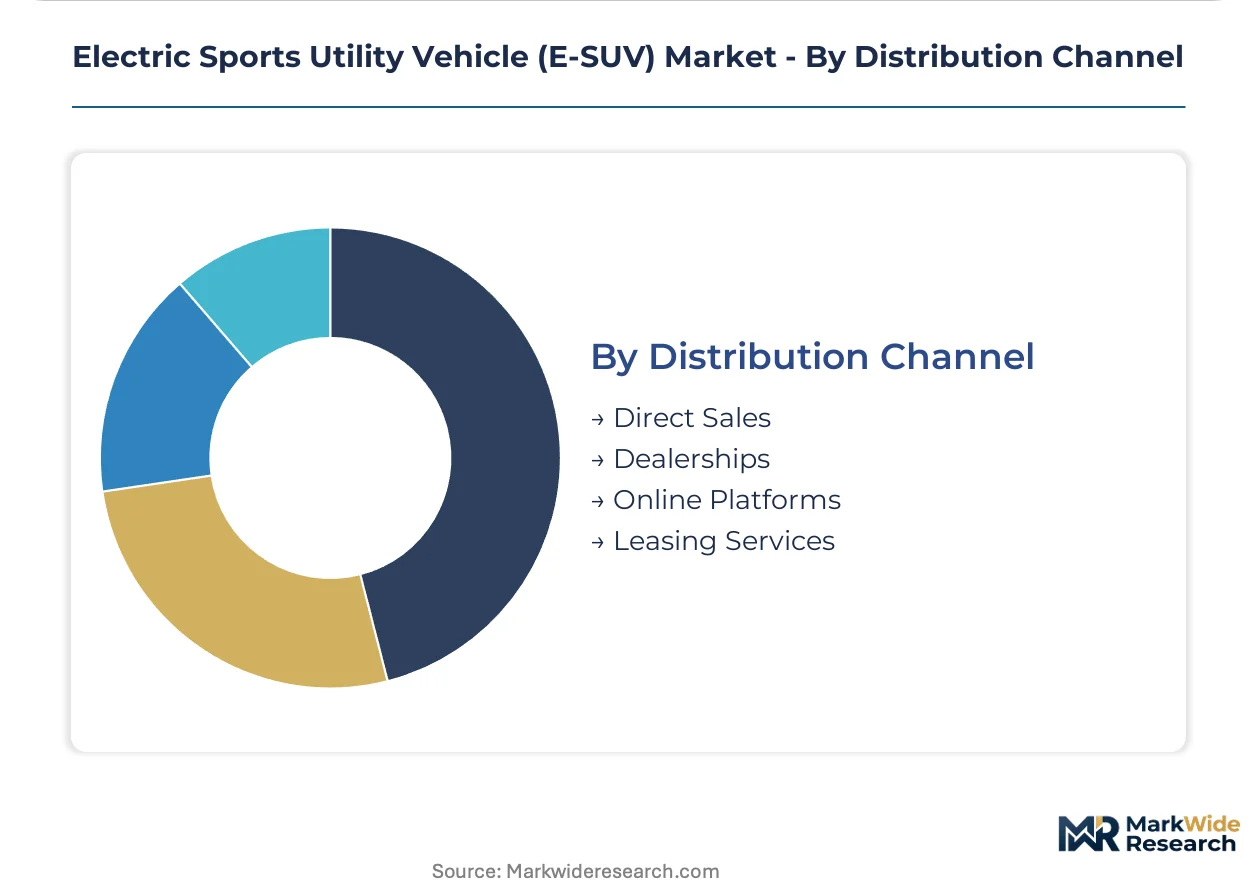
Distribution Channel:
Channel economics shift as direct OEM relationships displace traditional retail markups.
- Direct Sales:Proprietary retail and online configuration tools capture margin previously allocated to dealer networks. Tesla's Supercharger integration sustains this model in the United States and Germany.
- Leasing Services:Full-service providers absorb residual value risk in exchange for telemetry data access and maintenance bundling. This channel captures over sixty percent of German corporate registrations.
- Dealerships:Franchise networks retain rural coverage and service bay infrastructure.
- Online Platforms:Aggregator sites compare incentive eligibility and delivery timelines across OEMs.
Leasing Services holds contract volume. Direct Sales is gaining share fastest on margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell manufacturing and final assembly capacity cluster disproportionately in China, Germany, and the United States, with each geography deploying distinct regulatory levers to capture value from the electrification transition. National incentive structures and charging infrastructure density determine where fleet procurement accelerates fastest.
China
MIIT credit quotas and dual carbon goals enforce production volumes that favor E-SUV scale programs. The Yangtze River Delta hosts gigafactory clusters supplying cell-to-pack architectures to domestic OEMs. Shenzhen and Shanghai municipal authorities have expanded DC fast-charging networks along interstate corridors to support commercial fleet duty cycles.
Germany
Corporate leasing penetration exceeds sixty percent of E-SUV registrations, driven by EU CSRD disclosure requirements and favorable depreciation schedules. The EU Battery Regulation mandates digital product passports and audited supply chains. Bavaria and Baden-Württemberg concentrate R&D facilities for silicon-anode and solid-state chemistry development.
United States
IRA domestic content rules redirect capital toward North American assembly and qualifying battery sourcing. EPA tailpipe standards and NHTSA CAFE frameworks compel OEMs to expand E-SUV output or purchase regulatory credits. Texas and Michigan host final assembly plants prioritizing full-size configurations for fleet logistics contracts.
South Korea
Battery cell producers command priority allocation from cathode precursor suppliers in Indonesia and the DRC. METI-aligned industrial policy supports 800V architecture development and silicon carbide inverter integration. The Seoul Capital Area anchors domestic E-SUV demand while Busan-Ulsan handles export-oriented pack assembly.
Japan
Solid-state battery timelines from Toyota and QuantumScape suggest 2027-2028 production readiness for thermally stable, energy-dense packs. METI funding accelerates hydrogen fuel cell commercialization for continuous high-speed fleet duty cycles. Kanto and Nagoya industrial corridors concentrate power electronics packaging and thermal management R&D.
Electric Sports Utility Vehicle (E-SUV) Market Competitive Landscape
Concentration sits with diversified automotive conglomerates possessing captive battery supply and dedicated fleet sales divisions. The competitive structure stratifies across three tiers: legacy OEMs with multi-platform scale, pure-play electric specialists with direct-to-fleet channels, and emerging challengers competing on manufacturing velocity. Strategic moves center on backward integration into cell production and priority allocation agreements with cathode precursor processors.
Among legacy European conglomerates, BMW Group and Volkswagen Group exemplify the diversified archetype with dedicated business sales divisions and corporate leasing infrastructure. Tesla occupies a distinct position as a pure-play electric specialist with proprietary charging network integration. Within the emerging challenger tier, Rivian represents the manufacturing-scale archetype targeting commercial logistics contracts with custom upfit specifications.
| Leading Market Players |
|---|
| BMW Group |
| Volkswagen Group |
| Tesla |
| Rivian |
| Volvo Cars |
| Hyundai Motor Company |
| Mercedes-Benz |
| General Motors |
| Kia Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between cathode precursor processors and cell manufacturers lock in both lithium carbonate supply access and price visibility for fleet procurement cycles spanning three to five years. These arrangements concentrate pricing power with Indonesian nickel and DRC cobalt suppliers while compressing margins for European and North American pack assemblers subject to IRA domestic content thresholds.
Pricing Analysis
Volume-discount tiering structures separate fleet operators securing multi-thousand-unit commitments from individual buyers purchasing single units. Pricing stratifies across premium configurations with 800V architectures, standard mid-size variants with 400V systems, and economy compact tiers with reduced battery capacity. Cost compression in the economy tier is intensifying because Chinese cell producers are expanding LFP output for domestic OEMs. Fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership calculations, while individual buyers with limited home charging access remain most responsive to upfront sticker differentials.
Supply Chain Analysis
Strait of Malacca transit underwrites cathode precursor flows from Indonesian nickel processing facilities to South Korean cell plants. Manufacturing concentration in China, South Korea, and Japan feeds from lithium carbonate, nickel sulfate, and cobalt hydroxide inputs. Single-source vulnerability in DRC cobalt concentrate creates structural exposure to export restriction scenarios. Distribution runs through Tier 1 module suppliers delivering cell-to-pack architectures directly to OEM final assembly plants in Germany, China, and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified high-voltage technicians capable of servicing 800V architectures represent the binding constraint on fleet uptime guarantees, creating capability scarcity that determines competitive differentiation across maintenance networks.
For Market Incumbents: Fortify captive battery supply through direct cathode precursor offtake agreements with Indonesian processors, insulating against DRC cobalt disruption. Expand dedicated business sales divisions in Germany to secure priority allocation from cell suppliers. Channel control through proprietary charging networks defends against pure-play specialists integrating fleet telemetry. For New Entrants and Emerging Players: Aftermarket software services for predictive battery health monitoring present under-served demand where legacy OEMs lack real-time fleet analytics. Target municipal zero-emission zone logistics contracts in Amsterdam and Singapore where charging infrastructure density supports compact E-SUV deployment. Partner with full-service lease providers to absorb residual value risk while accessing telemetry data streams. For Investors and Strategic Acquirers: Silicon-anode chemistry developers with validated 2027 production timelines offer acquisition exposure to next-generation energy density improvements. Long-term viability hinges on solid-state commercialization trajectories and IRA domestic content rule stability. Watch NHTSA cybersecurity compliance timelines as inflection indicators for software-defined vehicle integration costs.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks cathode precursor allocation from Indonesian processors under IRA domestic content rules. |
| Platform Standardization | Reduces engineering overhead across mid-size and full-size E-SUV variants for fleet customization. |
| Charging Infrastructure Partnership | Expands DC fast-charging density along US interstate corridors serving commercial route completion. |
| Software-Defined Vehicle Investment | Enables over-the-air updates compliant with NHTSA, UNECE, and MIIT cybersecurity frameworks. |
| Geographic Manufacturing Footprint | Positions final assembly in Texas and Michigan to capture IRA tax credit eligibility. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and Tier 1 supplier production schedules anchors the qualitative findings on cell-to-pack adoption timelines. Primary interviews with fleet procurement directors, OEM business sales executives, charging infrastructure planners, and high-voltage technician training providers combine with secondary validation from EPA tailpipe standard filings, MIIT new-energy vehicle credit databases, and EU Battery Regulation traceability protocols. Bottom-up and top-down triangulation reconciles vehicle registration data with cathode precursor trade flows.
Sensitivity analysis around lithium carbonate price scenarios and IRA domestic content rule thresholds tests forecast robustness across the projection horizon. Segmentation dimensions modeled include vehicle size tier, propulsion architecture, end-user procurement type, and regional production cluster. CAGRs derive from production capacity buildout schedules and fleet conversion timelines. Silicon-anode chemistry readiness and solid-state battery commercialization trajectories serve as technology-specific forecast inputs.
Forecasts assume regulatory continuity in EPA tailpipe standards, EU Green Deal implementation, and MIIT credit quotas; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as cathode precursor supply concentration and high-voltage technician certification gaps evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
ASEAN Electric Bicycle Market
Electric Vehicles
Middle East Wireless EV Charging Market
Electric Vehicles
Europe Electric Car Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
Africa Electric Vehicle Market
Electric Vehicles
Luxembourg E-Bike Market
Electric Vehicles
China NEV Taxi Market
Electric Vehicles
Global Electric All Wheel Drive (AWD) Market
Electric Vehicles
North America E-Bike Market
Electric Vehicles
Mexico Solar E-Bike Market
Electric Vehicles
Vehicle Solar Panel Market
Electric Vehicles
Folding E-Scooter Market
Electric Vehicles
E-Lock for Electric Vehicle Charging Market
Electric Vehicles
High Voltage PTC Heaters for Electric Vehicles Market
Electric Vehicles
Electric Vehicle Operations Management Solutions Market
Electric Vehicles
Denmark Solar E-Bike Market