
 Car Battery Chargers Market | 2026-2036
Car Battery Chargers Market Size, Share, and Industry Trends Forecast 2026-2036
Car Battery Chargers Market Analysis
Lithium-ion cell chemistry is consolidating its position over lead-acid across mid-to-premium charger portfolios, compressing unit costs while extending cycle compatibility. CTEK leverages its Nordic engineering heritage to anchor the European smart-charger segment with temperature-compensated charging algorithms. Schumacher Electric sustains broad retail penetration through private-label and branded dual-channel distribution across North American auto-parts chains. Guangzhou Yunyang Electronic Technology dominates cost-engineered portable units through vertically integrated PCB and transformer production in Guangdong province.
Car battery chargers are electrochemical energy restoration devices that convert alternating or direct current into controlled direct-current output matched to battery voltage and chemistry, typically spanning 6V to 24V with amperage ratings from 0.75A trickle to 200A engine-start assist; their primary purpose is to replenish state-of-charge, condition sulfated plates, and maintain standby readiness for starter batteries across internal-combustion and hybrid-electric vehicles. Smart chargers now lead product-type value generation through microcontroller-based multi-stage profiles that command price premiums over basic portable units, while solar chargers remain a niche growth pocket constrained by panel cost and intermittent insolation. Within technology segmentation, lithium-ion compatibility represents the fastest-expanding engineering requirement as garage and fleet inventories shift toward newer chemistries, whereas lead-acid sustains volume dominance in emerging-market replacement cycles and legacy fleet maintenance.
The US EPA and NHTSA shape charger design through emissions-adjacent vehicle regulations that accelerate battery-electrification adoption, while the EU's CE marking and RoHS directives constrain substance content and electromagnetic compatibility for products entering European distribution. China's GB standards and MIIT circulars enforce domestic safety and efficiency benchmarks that filter import eligibility and shape local R&D priorities. Stakeholders must monitor divergence between regional certification regimes as charger platforms globalize, since multi-territory compliance costs will increasingly determine which product architectures achieve manufacturing scale.
Market Dynamics
Fleet electrification across commercial logistics is compressing charger replacement cycles while lithium-ion compatibility requirements are forcing hardware redesigns across mid-tier portfolios.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of fluorinated greenhouse gases in cooling-dependent charging stations accelerates demand for solid-state thermal management architectures in European markets.
- Commercial fleet operators:Electrification mandates from large logistics buyers are pulling smart-charger procurement into multi-year service contracts with predictive maintenance clauses.
- Lithium-ion chemistry:Garage and fleet inventories shifting from lead-acid are creating replacement demand for multi-chemistry charging platforms with adaptive voltage profiles.
Market Restraints
- Copper and rare-earth magnet costs:Transformer and inductor input volatility compresses margin on cost-engineered portable units from Guangdong manufacturing clusters.
- Single-source PCB substrate supply:Concentration of high-frequency laminate production in East Asian facilities creates vulnerability for smart-charger microcontroller boards.
- Intermittent solar insolation:Technical limitation on panel-integrated chargers constrains addressable market for off-grid automotive applications regardless of retail price compression.
Strategic Opportunities
- India aftermarket penetration:Underpenetrated two-wheeler and three-wheeler electrification creates white space for 12V-48V multi-voltage charger platforms with BIS certification pathways.
- Vehicle-to-grid bidirectional charging:Convergence of automotive power electronics with stationary energy storage enables new revenue models for fleet-grade charger deployments.
- US Inflation Reduction Act:Commercial clean vehicle tax credits are expanding charger infrastructure eligibility for qualified property investments at logistics depots.
Industry Challenges
- Multi-territory certification timelines:Divergence between CE marking, GB standards, and FCC Part 15 testing extends product launch schedules by 8-14 months for global platforms.
- Embedded firmware security:Connected-charger cybersecurity requirements under evolving automotive standards are forcing retooling of quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Battery Chargers Market |
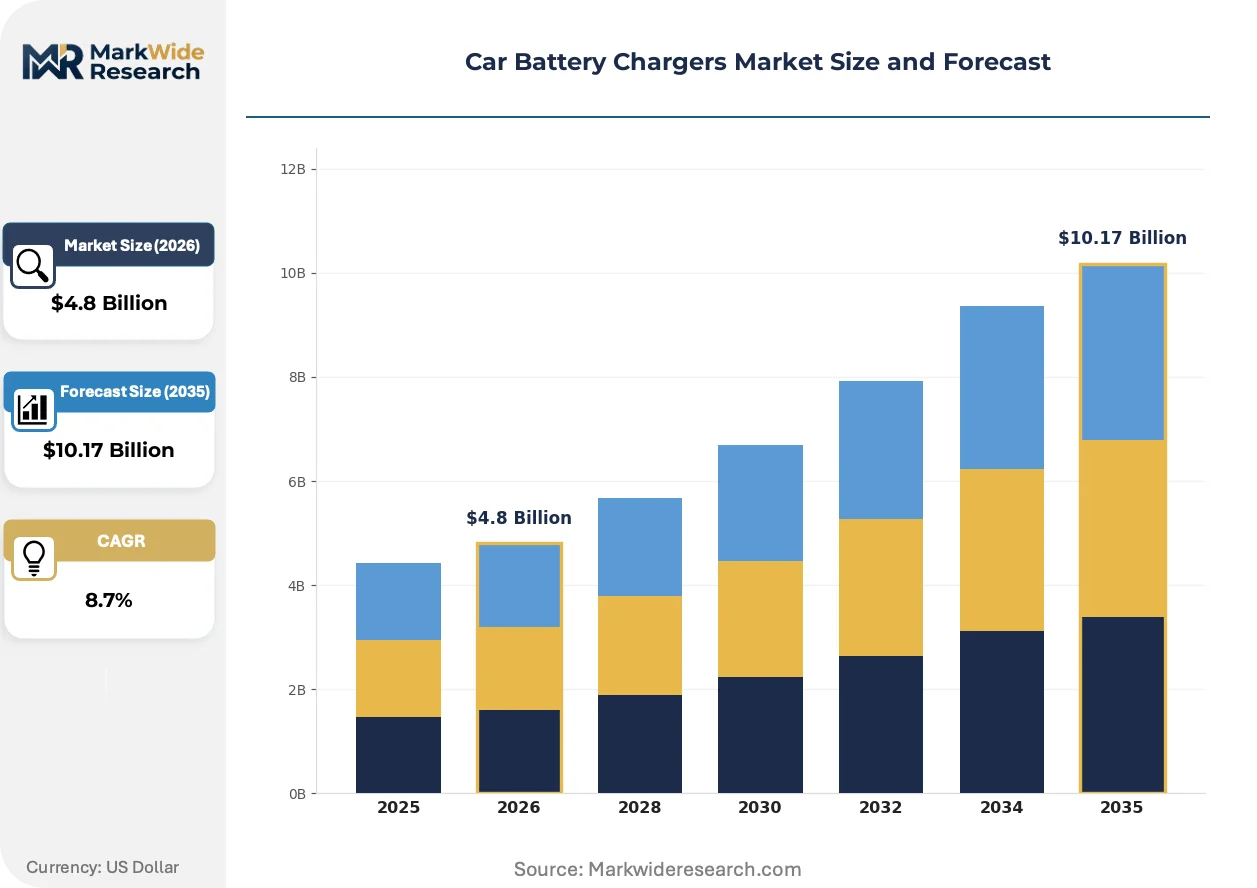
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Chargers, Wall-Mounted Chargers, Solar Chargers, Smart Chargers Technology: Lead-Acid, Lithium-Ion, Nickel-Metal Hydride, Inductive Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Boats End User: Individuals, Fleet Operators, Automotive Service Shops, Retail Customers |
| Companies Covered | NOCO, Optima Batteries, CTEK, Clore Automotive, Interstate Batteries, Schumacher Electric, Deltran, Guangzhou Yunyang Electronic Technology, Battery Tender, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Battery Chargers Market Emerging Trajectories
Microcontroller-based charging algorithms are displacing analog control circuits while regulatory pressure on substance content and electromagnetic compatibility is tightening design constraints across export-bound portfolios.
Gallium nitride (GaN) power semiconductors are integrating into high-frequency switching architectures for compact charger form factors. Tier-one automotive suppliers and premium aftermarket brands are adopting GaN-based designs at accelerating pace for 2025-2026 model year releases. This transition is integrating thermal efficiency gains that compress enclosure size and material cost for wall-mounted fleet units.
The EU's F-Gas Regulation and RoHS substance restrictions are constraining refrigerant choices and solder alloy compositions for products entering European distribution. Industrial consequence includes accelerated R&D spending on passive cooling alternatives and lead-free high-reliability interconnects. Smart-charger portfolios with temperature-compensated algorithms face the steepest compliance cost escalation due to integrated sensor and processing density.
Direct procurement from charger manufacturers by national fleet operators is disintermediating traditional auto-parts distribution in select European markets. Large logistics buyers are consolidating supplier relationships around multi-year service agreements with uptime guarantees. This pattern is most visible in Germany and the Netherlands where KBA vehicle registration data shows the fastest commercial EV penetration.
Car Battery Chargers Market Segmentation
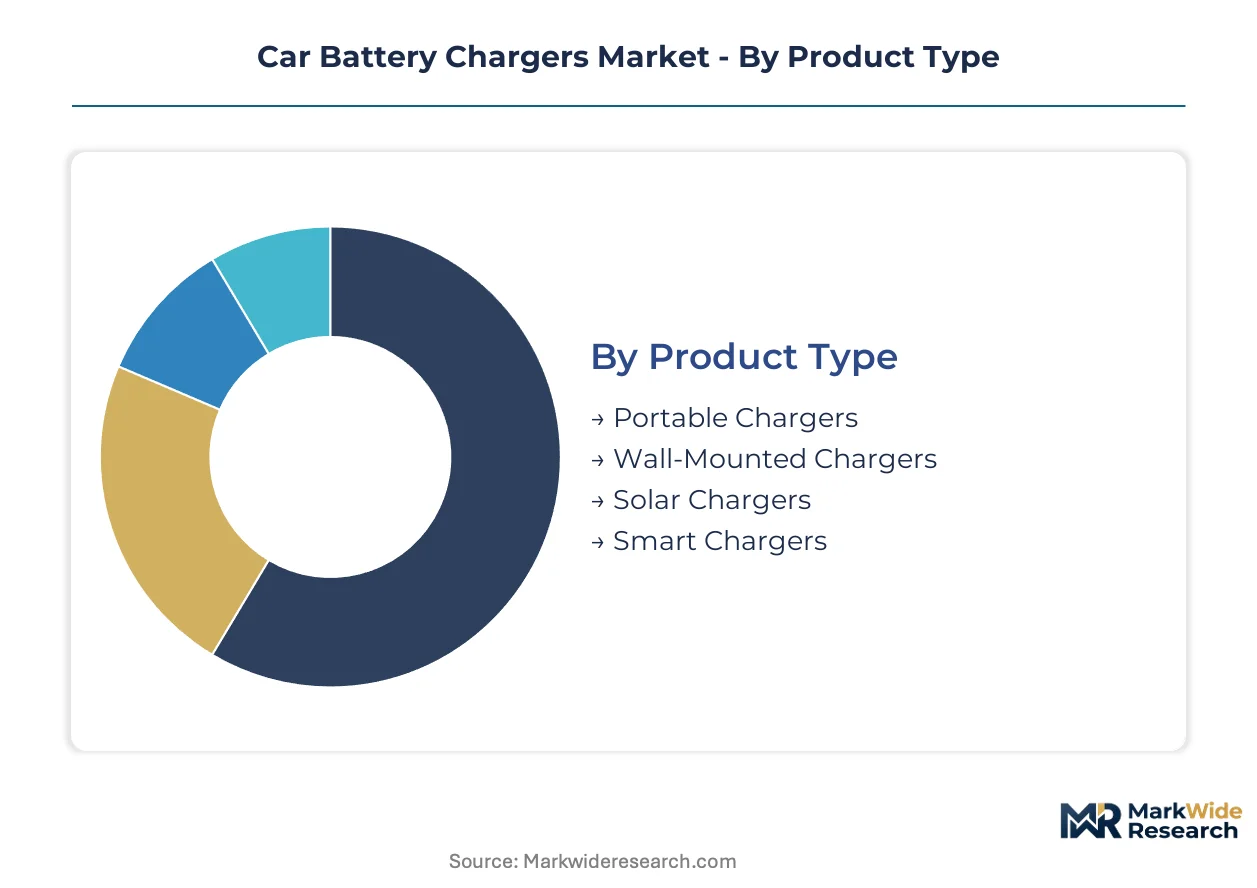
Segmentation in car battery chargers reveals how voltage compatibility, installation permanence, and buyer sophistication fragment manufacturing priorities. Charger architectures must simultaneously serve garage hobbyists with 12V trickle units and fleet depots demanding 48V multi-chemistry platforms with predictive maintenance integration.
Product Type:
Customization intensity varies sharply across this category, from commodity portable units to permanently installed smart systems with firmware update capabilities.
- Smart Chargers:Microcontroller-based multi-stage units with temperature compensation and adaptive voltage profiles command premium positioning. Fleet operators in Germany and the Netherlands are consolidating procurement around these platforms through multi-year service contracts with uptime guarantees mandated by commercial EV electrification timelines.
- Portable Chargers:Compact transformer-based units with 6V-12V selector switches and basic LED indicators dominate replacement cycles. Guangdong manufacturing clusters supply cost-engineered variants to North American auto-parts retail chains where private-label penetration sustains margin compression.
- Wall-Mounted Chargers:Fixed-installation units with higher amperage ratings serve fleet depots and service shops requiring sustained output.
- Solar Chargers:Panel-integrated trickle units remain constrained by intermittent insolation and panel cost structures despite retail price compression.
Most installed capacity flows through Portable Chargers. Expansion is steepest in Smart Chargers.
Technology:
Cost tier stratification in this category separates legacy lead-acid compatibility from lithium-ion adaptive architectures with chemistry-detection circuits.
- Lithium-Ion:Charging platforms with CC-CV (constant current-constant voltage) profiles and cell-balancing integration address garage and fleet inventories shifting from lead-acid. China's GB standards and MIIT circulars enforce safety benchmarks that filter import eligibility for these higher-voltage systems.
- Lead-Acid:Sulfation-recovery algorithms and desulfation pulse modes sustain volume dominance in emerging-market replacement cycles and legacy fleet maintenance across India and Southeast Asia.
- Nickel-Metal Hydride:Specialized voltage thresholds serve hybrid-electric vehicle auxiliary batteries with distinct charge termination requirements.
- Inductive:Wireless power transfer architectures remain developmental for automotive applications due to efficiency losses and alignment precision demands.
Lead-Acid retains the largest installed base. Lithium-Ion is gaining share fastest as electrification penetrates commercial logistics.
Application:
Volume concentration in this category tracks vehicle electrification maturity across passenger, commercial, and powersport segments with divergent voltage requirements.
- Commercial Vehicles:Heavy-duty charging platforms with 24V-48V capability and engine-start assist functions address logistics fleet electrification. The US Inflation Reduction Act's commercial clean vehicle tax credits are expanding charger infrastructure eligibility at qualified depot properties.
- Passenger Vehicles:12V maintainer and recovery units serve the largest addressable pool of internal-combustion and hybrid-electric vehicles across North American and European households.
- Motorcycles:Compact 6V-12V units with lighter form factors address powersport battery maintenance with seasonal storage patterns.
- Boats:Marine-rated chargers with corrosion-resistant enclosures and multi-bank capability serve dual-battery deep-cycle configurations.
Passenger Vehicles anchor current volume. Commercial Vehicles show the steepest expansion trajectory as fleet operators accelerate electrification procurement.
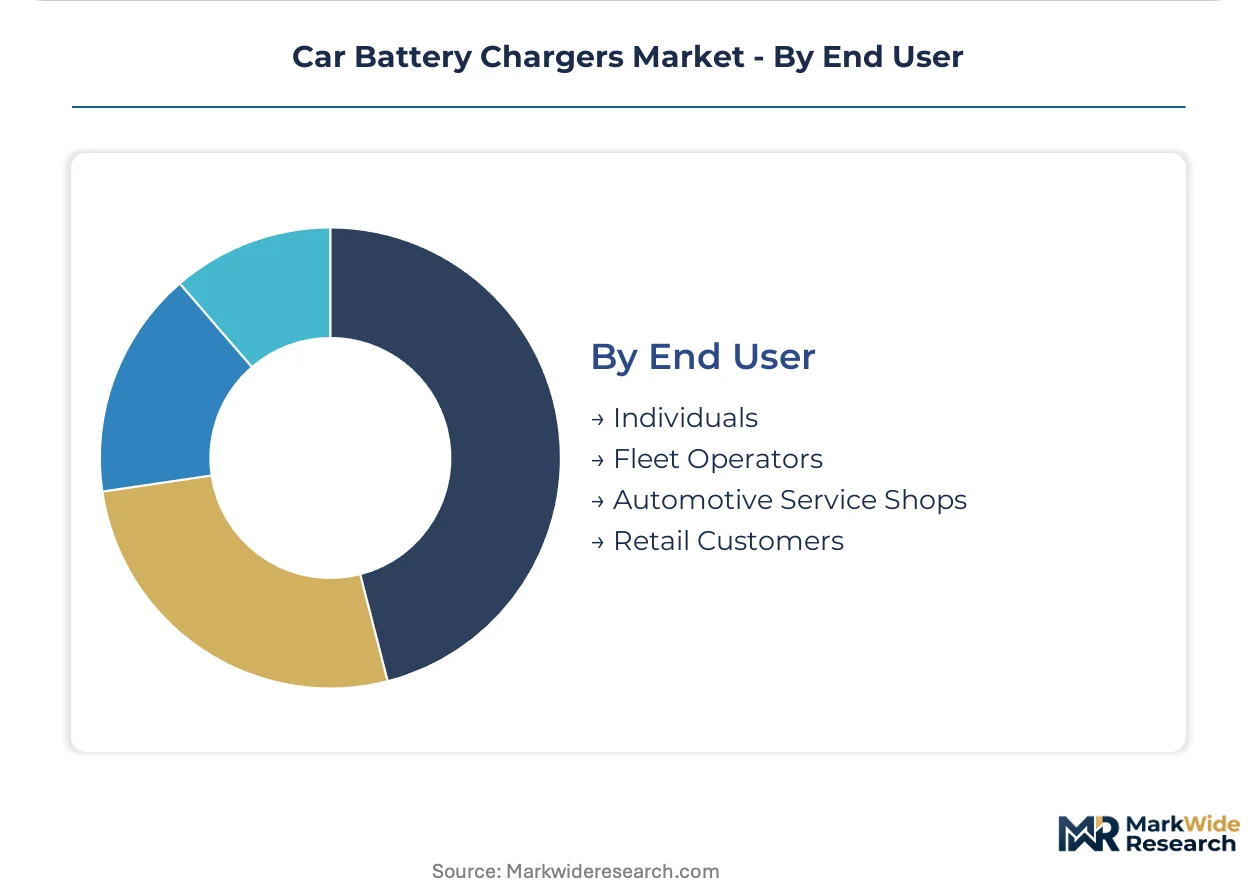
End User:
Customer type in this category determines whether procurement flows through retail auto-parts channels or direct manufacturer relationships with service-level agreements.
- Fleet Operators:Large logistics buyers are disintermediating traditional distribution through direct procurement with predictive maintenance clauses and multi-year uptime guarantees. KBA registration data in Germany shows this pattern concentrating where commercial EV penetration advances fastest.
- Automotive Service Shops:Multi-chemistry charging platforms with diagnostic integration support professional battery servicing and warranty documentation requirements.
- Individuals:Hobbyist buyers drive seasonal replacement cycles through retail channels with price-sensitive feature trade-offs.
- Retail Customers:Occasional-use purchasers respond to point-of-sale placement and promotional pricing in mass-market auto-parts chains.
Automotive Service Shops process the most installed units. Fleet Operators are climbing the fastest as electrification mandates reshape procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province anchors manufacturing scale for portable charger production, while fleet electrification in Germany and the Netherlands reshapes procurement patterns toward smart-charger platforms with predictive maintenance integration.
United States
Commercial fleet operators at logistics depots are expanding smart-charger procurement under multi-year service contracts with uptime guarantees. The EPA and NHTSA emissions-adjacent vehicle regulations accelerate battery-electrification adoption that pulls through aftermarket charging equipment. The Inflation Reduction Act's commercial clean vehicle tax credits expand charger infrastructure eligibility at qualified properties in Texas and California distribution corridors.
China
Domestic EV fleet growth creates pull-through demand for aftermarket charging equipment across garage and commercial service networks. GB standards and MIIT circulars enforce safety and efficiency benchmarks that filter import eligibility and shape local R&D priorities. Guangzhou Yunyang Electronic Technology leverages vertically integrated PCB and transformer production in Guangdong province to dominate cost-engineered portable unit supply.
Germany
KBA vehicle registration data shows the fastest commercial EV penetration in Europe, driving direct procurement from charger manufacturers by national fleet operators. The EU F-Gas Regulation phase-down of fluorinated greenhouse gases accelerates demand for solid-state thermal management architectures. Industrial concentration in Baden-Württemberg and Bavaria hosts tier-one automotive suppliers adopting gallium nitride power semiconductors for 2025-2026 model year releases.
India
Underpenetrated two-wheeler and three-wheeler electrification creates white space for 12V-48V multi-voltage charger platforms with BIS certification pathways. The country's national automotive regulator enforces safety benchmarks that filter import eligibility for higher-voltage lithium-ion systems. Maharashtra and Gujarat manufacturing clusters see emerging demand for lead-acid replacement cycles in legacy fleet maintenance alongside new chemistry adoption.
Netherlands
Large logistics buyers consolidate supplier relationships around multi-year service agreements with uptime guarantees mandated by commercial EV electrification timelines. CE marking and RoHS directives constrain substance content and electromagnetic compatibility for products entering European distribution. The Randstad logistics corridor exhibits the most visible pattern of distribution disintermediation as fleet operators bypass traditional auto-parts channels.
Car Battery Chargers Market Vendor Landscape
Global majors compete with regional champions across certification complexity and manufacturing scale, producing a tiered structure where premium smart-charger portfolios sit above cost-engineered portable units. The vendor base spans Nordic engineering specialists, North American retail-channel incumbents, and Chinese vertically integrated fabricators. Three archetypes dominate: microcontroller-based algorithm developers, transformer-based commodity producers, and GaN semiconductor early adopters. Competitive moves center on multi-territory compliance investment and backward integration into PCB substrate supply.
Among Nordic engineering specialists, CTEK anchors the European smart-charger segment with temperature-compensated charging algorithms. Schumacher Electric occupies a position within North American retail-channel distribution across auto-parts chains. Guangzhou Yunyang Electronic Technology exemplifies the cost-engineered portable unit archetype through captive supply of PCB and transformer components in Guangdong province.
| Leading Market Players |
|---|
| NOCO |
| Optima Batteries |
| CTEK |
| Clore Automotive |
| Interstate Batteries |
| Schumacher Electric |
| Deltran |
| Guangzhou Yunyang Electronic Technology |
| Battery Tender |
| Others |
Supply Flow & Price Mechanics
Captive PCB and transformer production in Guangdong province anchors both cost-engineered portable supply and the pricing power of vertically integrated fabricators serving North American auto-parts retail chains. This backward integration into high-frequency laminate and magnetic component supply compresses unit economics for commodity tiers while insulating margin against copper and rare-earth magnet volatility.
Pricing Analysis
Copper and rare-earth magnet pass-through from transformer and inductor suppliers compresses margin on cost-engineered portable units originating from Guangdong manufacturing clusters. Three-tier pricing structure across premium smart-charger, standard wall-mounted, and economy portable levels separates microcontroller-based algorithm portfolios from basic LED-indicator units. Pricing pressure stems from single-source PCB substrate concentration in East Asian facilities. Fleet operators demonstrate lowest price sensitivity due to uptime guarantee requirements, while retail hobbyist buyers drive seasonal replacement cycles with sharp feature trade-offs.
Supply Chain Analysis
Direct-to-fleet channels handle hyperscale buyer demand from German and Dutch logistics operators consolidating procurement around multi-year service agreements. Manufacturing concentrates in China, Vietnam, and Mexico for transformer winding and enclosure fabrication. Supply chains draw from copper magnet wire, ferrite cores, and high-frequency laminate substrates. Single-source vulnerability in East Asian PCB substrate facilities creates chokepoint exposure for smart-charger microcontroller boards. Distribution runs through auto-parts retail chains for portable units and direct manufacturer relationships for fleet-grade platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
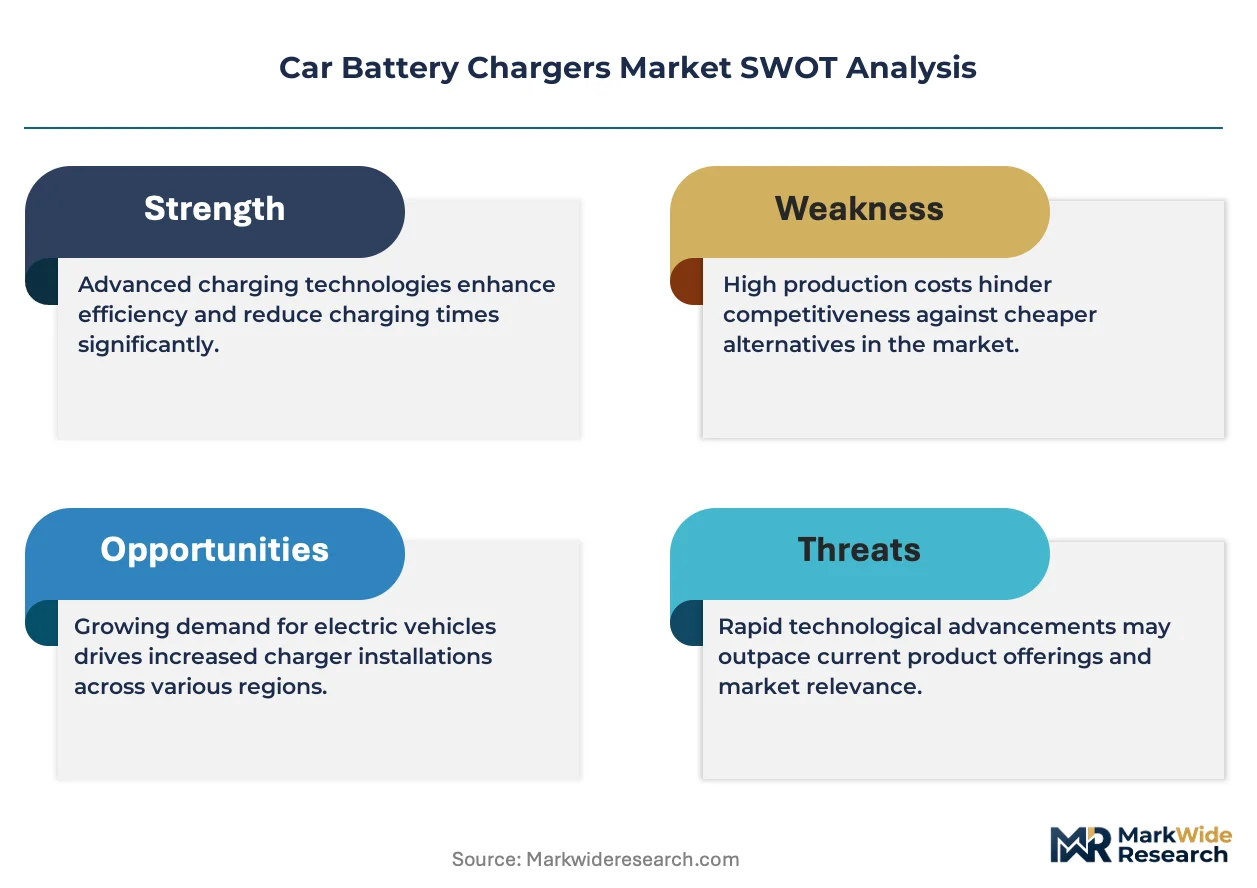
The car battery chargers market functions as a regulatory compounder where the EU F-Gas Regulation phase-down of fluorinated greenhouse gases accelerates demand for solid-state thermal management architectures and reshapes R&D allocation across European portfolios.
For Market Incumbents: Cement multi-territory certification capabilities as the primary defensive moat against emerging Chinese competitors with captive component supply. Prioritize backward integration into high-frequency laminate sourcing to mitigate single-source PCB substrate vulnerability. Expand predictive maintenance service bundling with fleet operators to lock in multi-year contract renewals before distribution disintermediation accelerates.
For New Entrants and Emerging Players: Gallium nitride power semiconductor adoption represents the most penetrable technology wedge for compact form-factor differentiation against legacy transformer-based incumbents. Target India's underpenetrated two-wheeler and three-wheeler electrification segment with 12V-48V multi-voltage platforms pursuing BIS certification pathways. Pursue white-label partnerships with Guangdong fabricators to compress initial capital requirements.
For Investors and Strategic Acquirers: Roll-up economics work for regional smart-charger specialists with established CE marking and GB standard compliance because multi-territory certification timelines extend product launch schedules by 8-14 months and create acquisition scarcity. Focus on targets with embedded firmware development capabilities and existing fleet service contracts. Watch KBA commercial EV registration velocity in Germany as the demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Chemistry Platform Development | Adaptive voltage profiles capture lithium-ion replacement demand from lead-acid fleet inventories. |
| GaN Semiconductor Integration | Thermal efficiency gains compress enclosure size for 2025-2026 model year fleet releases. |
| Predictive Maintenance Service Contracts | Uptime guarantees lock in multi-year revenue from German and Dutch logistics buyers. |
| India BIS Certification Pathway Investment | 12V-48V multi-voltage platforms address underpenetrated two-wheeler electrification white space. |
| Passive Cooling Architecture R&D | F-Gas Regulation compliance eliminates refrigerant-dependent thermal management from European portfolios. |
Methodological Framework
Multiple input streams — fleet operator procurement directors, automotive service shop owners, aftermarket distributor category managers, and Tier 1 supplier battery engineers — were reconciled with secondary validation from EPA emissions filings, NHTSA regulatory dockets, EU F-Gas Regulation implementation guidance, China MIIT circulars, and KBA vehicle registration databases. Bottom-up unit shipment estimates by product type and voltage tier were cross-referenced against top-down market value reconstruction.
Historical volume trajectories were cross-referenced against panel input from charger manufacturer executives and component supplier sales directors across the analysis window. Segmentation modeling captured product type, battery chemistry compatibility, installation permanence, vehicle application, and end-user procurement channel. CAGRs were derived from regression analysis of replacement cycle compression and fleet electrification penetration rates, with specific weighting applied to commercial vehicle tax credit eligibility under the US Inflation Reduction Act.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper and rare-earth magnet price volatility, divergence between regional certification regimes, and embedded firmware cybersecurity requirement evolution under automotive standards. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Global Industrial Electric Vehicle Market
Electric Vehicles
Electric Vehicle Operations Management Solutions Market
Electric Vehicles
Railway Lithium Battery Market
Electric Vehicles
North America Electric Vehicle Battery Market
Electric Vehicles
Luxury Electric Vehicle Market
Electric Vehicles
Automotive Battery Thermal Management System Market
Electric Vehicles
Solar Golf Cart Market
Electric Vehicles
Europe Automotive Battery Thermal Management System Market
Electric Vehicles
Solar Car Market
Electric Vehicles
Middle East Wireless EV Charging Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
Foldable Electric Car Market
Electric Vehicles
Commercial Electric Vehicle Dynamic Braking Resistors Market
Electric Vehicles
Golf Cart Battery Market
Electric Vehicles
Driveline Electric Vehicle Market
Electric Vehicles
Canada Solar E-Bike Market