
 Global IMSI Catcher Market | 2026-2036
Global IMSI Catcher Market Size, Share, and Industry Trends Forecast 2026-2036
Global IMSI Catcher Market Foresight
Defense contractors and intelligence agencies is bifurcating demand away from traditional law enforcement buyers as sovereign surveillance budgets expand. L3Harris Technologies leverages its deep integration with US defense programs to sustain long-term contracts for tactical cellular intelligence platforms. Rohde and Schwarz anchors European demand through its specialized communications test and measurement heritage applied to lawful interception. Septier Communication competes aggressively in the Middle East and Asia-Pacific with portable systems optimized for rapid deployment scenarios.
An IMSI catcher is a cellular surveillance device that masquerades as a legitimate base station to capture the International Mobile Subscriber Identity and associated metadata from mobile devices within its broadcast range, typically operating across 2G through 5G frequency bands with effective radii from hundreds of meters to several kilometers depending on transmit power and antenna configuration. Portable IMSI catchers dominate procurement volumes among special operations units requiring dismounted tactical flexibility, while drone-based platforms represent the fastest-growing product category as unmanned aerial systems extend coverage to remote border regions and maritime approaches. On the technology dimension, LTE interception capabilities remain the revenue backbone, though 5G decryption modules command premium pricing as networks migrate to standalone architectures with enhanced subscriber privacy protections.
The Federal Communications Commission in the United States restricts civilian sale and operation of IMSI catchers under wiretapping statutes, while the European Telecommunications Standards Institute publishes lawful interception frameworks that member regulators transpose into national licensing regimes. Israel's Ministry of Defense and India's Telecommunication Engineering Centre impose additional export control and type-approval requirements that shape vendor market access and product certification pathways. Stakeholders must monitor spectrum reallocation decisions and encryption standard evolutions that could render existing hardware obsolete before planned replacement cycles conclude.
Market Dynamics
The migration toward 5G standalone architectures with SUCI encryption is forcing premature obsolescence of legacy interception hardware and compressing replacement cycles across defense procurement programs.
Growth Catalysts
- 5G Network Expansion:Telecommunications operators in Germany and South Korea are accelerating 5G standalone rollouts, creating demand for next-generation decryption modules capable of penetrating enhanced subscriber privacy protections.
- FCC Wiretapping Statutes:Restrictions on civilian IMSI catcher operation in the United States channel procurement toward authorized defense and intelligence end users with sustained sovereign budgets.
- Border Security Modernization:Drone-mounted cellular intelligence platforms are displacing fixed-site installations along maritime approaches and remote frontiers where terrestrial infrastructure cannot reach.
Market Restraints
- Semiconductor Supply Concentration:Field-programmable gate arrays and software-defined radio chipsets concentrate fabrication in Taiwan and South Korea, exposing vendors to single-source vulnerability.
- Export Control Friction:Israel's Ministry of Defense and India's Telecommunication Engineering Centre impose type-approval requirements that extend certification timelines by 12-18 months for non-domestic suppliers.
- End-to-End Encryption Proliferation:Signal and WhatsApp default encryption is degrading the intelligence value of IMSI-derived metadata alone, forcing costly integration with companion lawful interception systems.
Strategic Opportunities
- Urban Counter-Terrorism Units:Portable systems optimized for rapid deployment in dense signal environments remain underpenetrated among municipal special weapons and tactical teams in France and Spain.
- AI-Assisted Signal Classification:Machine learning convergence with software-defined radio architectures enables real-time discrimination between target devices and collateral civilian traffic.
- EU Green Deal Procurement Incentives:Battery-efficient low-power designs qualify for preferential evaluation in European defense tenders emphasizing operational sustainability metrics.
Industry Challenges
- RF Engineering Talent Scarcity:Vendors compete for finite pools of specialists conversant in both cellular protocol stacks and military-grade hardware ruggedization.
- Cross-Border Certification Complexity:Each NATO member state transposes ETSI lawful interception frameworks through distinct national licensing regimes, fragmenting product homologation requirements.
- Legacy System Integration:New 5G-capable platforms must interoperate with existing command-and-control infrastructure designed around 2G/3G data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IMSI Catcher Market |
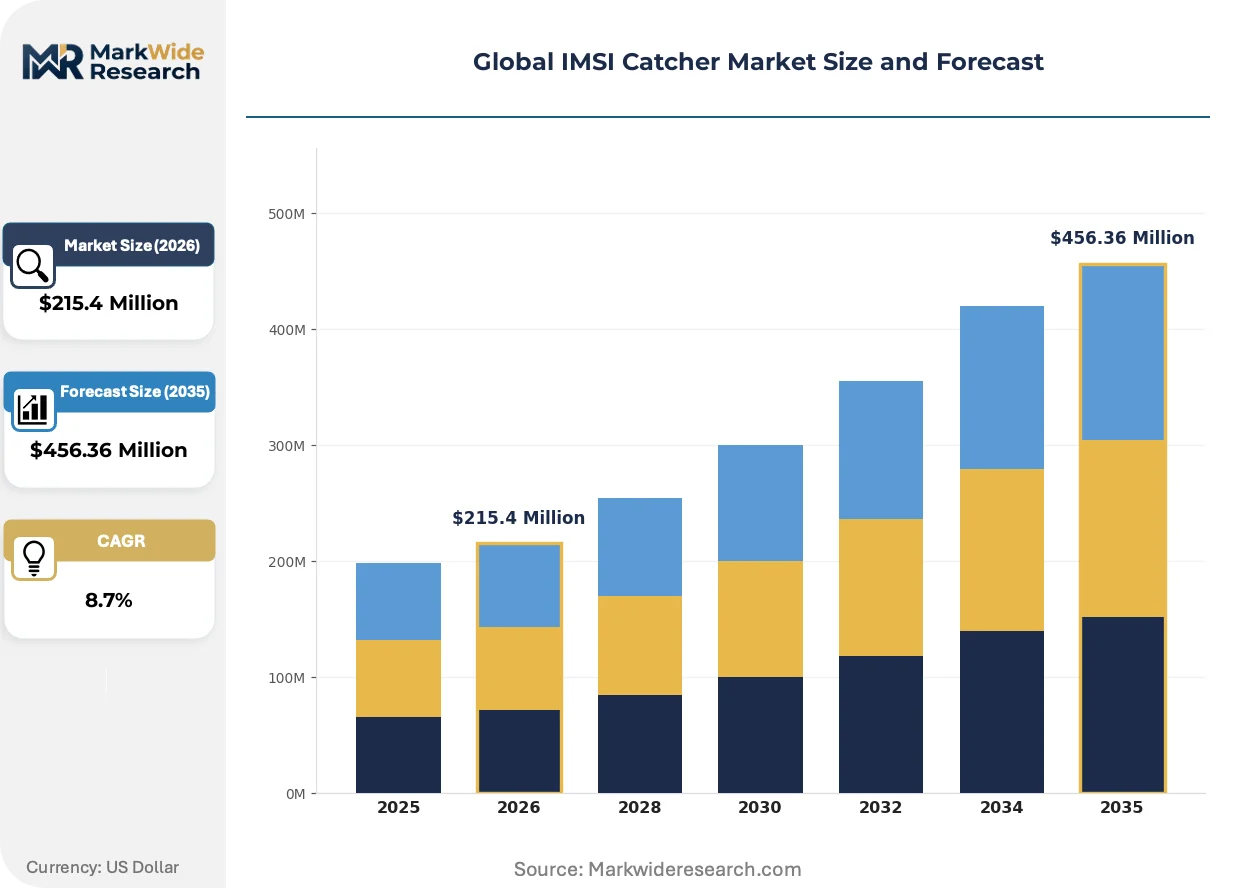
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $456.36 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed IMSI Catcher, Portable IMSI Catcher, Vehicle-Mounted IMSI Catcher, Drone-Based IMSI Catcher Technology: GSM, CDMA, LTE, 5G, UMTS Application: Law Enforcement, Counter-Terrorism, Military Surveillance, Corporate Security, Cybersecurity End User: Government Agencies, Security Firms, Defense Contractors, Telecommunication Providers |
| Companies Covered | L3Harris Technologies, Septier Communication, Rohde and Schwarz, PKI Electronic Intelligence, Phantom Technologies, 4Intelligence, KAVIT Electronics Industries, Proximus LLC, NeoSoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IMSI Catcher Market Shifts & Advancements
Hardware form factors and signal processing architectures are undergoing simultaneous compression and sophistication, reshaping competitive positioning around mobility, concealability, and cryptographic agility.
Software-defined radio on embedded FPGA substrates is miniaturizing tactical IMSI catchers to handheld dimensions without sacrificing multi-band coverage. Special operations units in the United Kingdom and Australia are fielding these systems for dismounted urban surveillance where bulkier vehicle-mounted platforms compromise operational security. The structural consequence is collapsing price premiums historically attached to portability, compressing margins for vendors lacking in-house semiconductor design capability.
ETSI's lawful interception framework revisions are mandating enhanced audit trails and judicial oversight integration for all member state deployments. This industrial consequence elevates compliance engineering to a core differentiator, favoring European vendors with established regulatory affairs infrastructure. Border security agencies in Poland and Romania are responding by consolidating procurement around suppliers offering pre-certified end-to-end solutions rather than component hardware.
Defense buyers are unbundling hardware acquisition from training and maintenance contracts, shifting toward multi-vendor system integration responsibilities retained in-house. This pattern disrupts traditional prime contractor relationships and elevates value capture by specialized subsystem suppliers with open-architecture interfaces. The shift is most visible in United States special operations command programs, where technical officers specify interoperability standards rather than turnkey solutions.
Global IMSI Catcher Market Segmentation
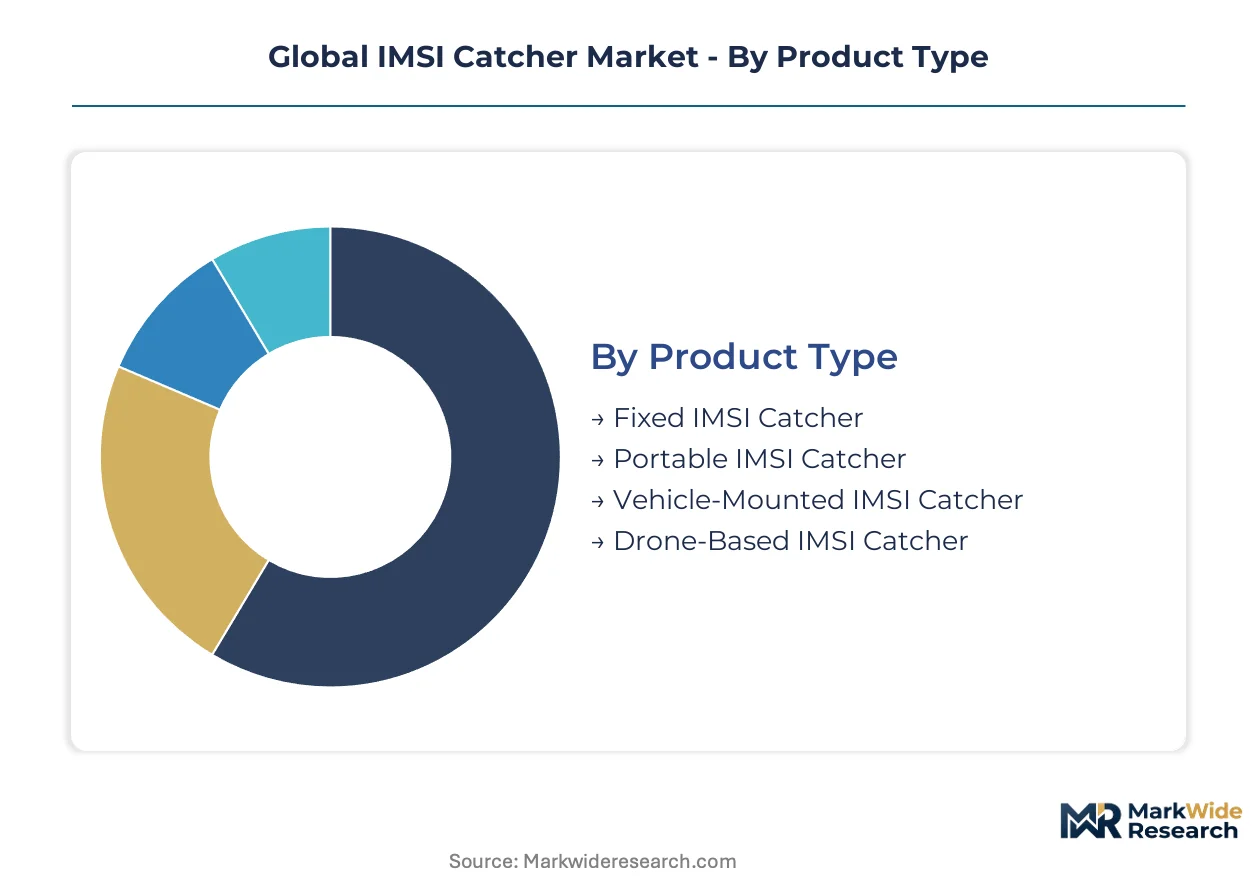
IMSI catcher procurement patterns diverge sharply across deployment scenarios, with mobility requirements and interception sophistication driving distinct margin structures. Understanding these segment boundaries clarifies where vendors capture value and where commoditization pressures concentrate.
Product Type:
Margin pools concentrate in systems balancing concealability with multi-band coverage, rewarding vendors with integrated RF engineering capabilities.
- Fixed IMSI Catcher:Permanent installations anchor perimeter defense at critical infrastructure sites and border crossings. Demand clusters in Germany and Poland where agencies prioritize sustained coverage over tactical flexibility, though lengthy procurement cycles compress vendor cash conversion.
- Portable IMSI Catcher:Handheld and backpack configurations dominate special operations procurement in the United States and United Kingdom. Dis-mounted urban surveillance requirements sustain premium pricing for miniaturized multi-band units despite collapsing portability premiums from FPGA substrate advances.
- Vehicle-Mounted IMSI Catcher:Rooftop and trunk-integrated systems serve mobile border patrol and convoy protection roles. Israeli and Indian agencies favor these for extended rural operations where terrestrial infrastructure gaps demand vehicular power and antenna elevation.
- Drone-Based IMSI Catcher:Unmanned aerial platforms extend cellular intelligence to maritime approaches and remote frontiers inaccessible by ground vehicles. NATO border security modernization programs are accelerating field trials across Romania and Baltic member states.
The dominant share belongs to Portable IMSI Catcher, while Drone-Based IMSI Catcher is closing the gap fastest.
Technology:
Technology selection tracks network infrastructure migration curves, with decryption complexity creating tiered capability premiums.
- GSM:Legacy 2G interception remains operationally relevant in developing markets and for backward compatibility. African and Southeast Asian security services continue procurement for cost-constrained rural deployments where 3G/4G penetration remains incomplete.
- CDMA:Declining carrier adoption limits new investment, though maintenance contracts persist for existing installed bases in parts of South America and Asia-Pacific where CDMA networks retain residual operational life.
- LTE:4G interception capabilities constitute the current revenue backbone across defense procurement programs. ETSI lawful interception frameworks in European member states mandate LTE coverage as baseline compliance for vendor qualification.
- 5G:Standalone architecture decryption commands substantial capability premiums due to SUCI encryption and network slicing complexity. South Korean and German operators are accelerating 5G rollouts that force premature replacement of legacy hardware.
- UMTS:3G systems bridge coverage gaps in transitional network environments. Procurement concentrates in regions with staggered infrastructure upgrade timelines where UMTS retains intelligence value for target device tracking.
LTE maintains the largest installed base, though 5G is expanding most quickly as sovereign surveillance budgets prioritize next-generation decryption.
Application:
Application segmentation reveals divergent buyer sophistication and funding stability across civilian and military end uses.
- Law Enforcement:Municipal and national police units deploy IMSI catchers for organized crime and missing persons investigations. FCC wiretapping statutes in the United States restrict civilian operation, channeling procurement toward federally authorized programs with sustained budget visibility.
- Counter-Terrorism:Specialized units in France and Spain require rapid-deployment systems optimized for dense urban signal environments. Intelligence integration mandates and judicial oversight requirements elevate compliance engineering to core procurement criteria.
- Military Surveillance:Defense agencies represent the most stable demand pool with multi-year procurement horizons. Tactical cellular intelligence platforms support force protection, target acquisition, and signals intelligence fusion across NATO expeditionary operations.
- Corporate Security:Private sector adoption remains constrained by regulatory uncertainty and liability exposure. Critical infrastructure operators in energy and finance sectors evaluate IMSI catchers for facility perimeter monitoring against industrial espionage threats.
- Cybersecurity:Integration with threat intelligence platforms creates hybrid use cases spanning cellular and network-layer interception. Demand is nascent but climbing fastest as cyber-physical convergence blurs traditional security domain boundaries.
Military Surveillance commands the dominant share, while Cybersecurity is gaining share fastest as cyber-physical threat convergence accelerates.
End User:
End user structure reflects sovereign control over lawful interception authorization and certification pathways.
- Government Agencies:National intelligence and interior ministries constitute the primary procurement authority in most jurisdictions. Israel's Ministry of Defense and India's Telecommunication Engineering Centre impose type-approval requirements that shape vendor market access.
- Security Firms:Private contractors operate under government license for specific facility protection and event security contracts. European regulatory fragmentation across ETSI national transpositions complicates cross-border service provision.
- Defense Contractors:Prime and subsystem suppliers integrate IMSI catcher modules into broader signals intelligence platforms. United States special operations command programs increasingly specify interoperability standards rather than turnkey solutions, elevating subsystem vendor value capture.
- Telecommunication Providers:Carrier deployment of lawful interception infrastructure serves regulatory compliance rather than autonomous intelligence operations. Network equipment vendors embed interception capabilities within core infrastructure under national licensing regimes.
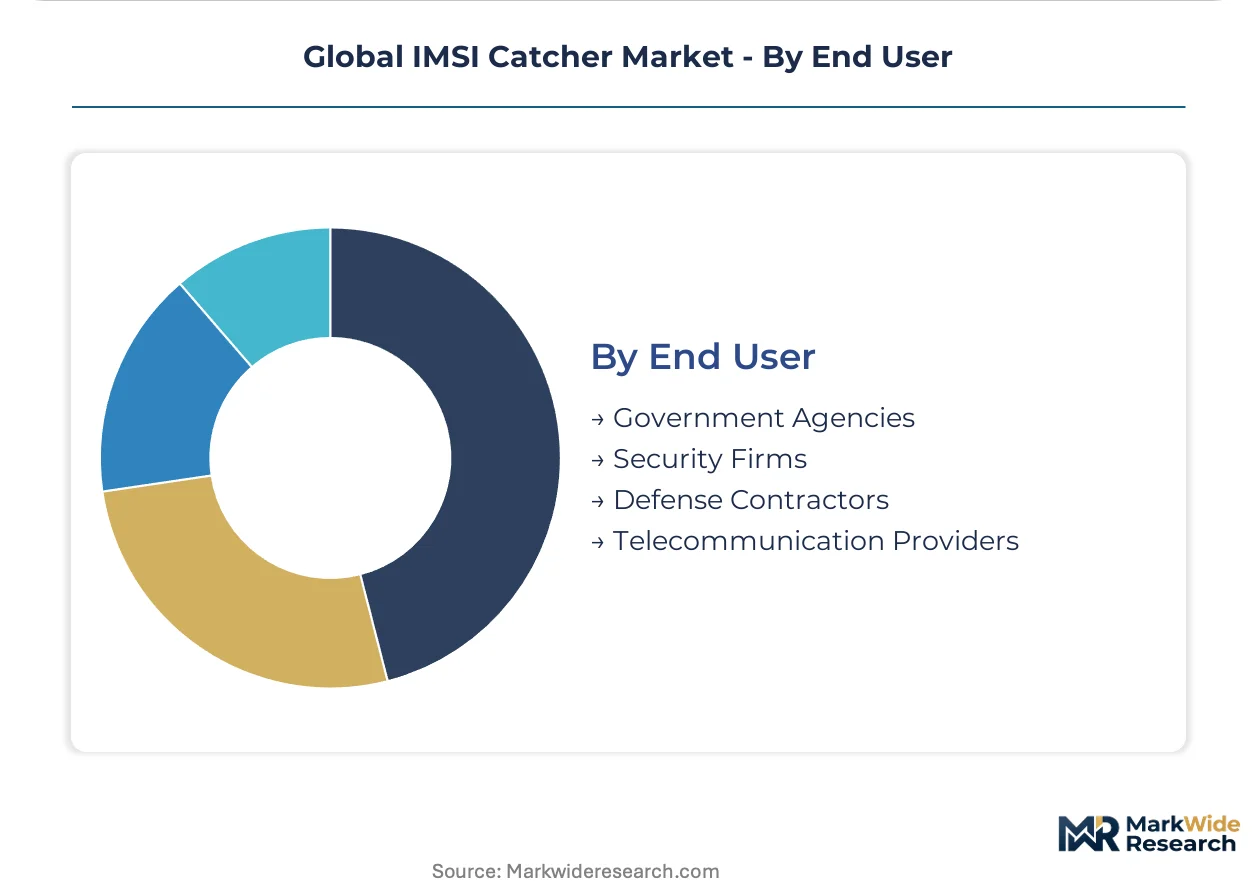
Government Agencies retain the dominant share, while Defense Contractors are climbing the fastest as unbundled procurement patterns disrupt traditional prime relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli manufacturers export tactical cellular intelligence platforms to NATO member states and Asia-Pacific security services, while German engineering firms supply interception hardware across European interior ministries. This trade corridor shapes procurement standardization and certification reciprocity agreements.
United States
Defense procurement dominates demand as special operations commands specify interoperability standards for tactical cellular intelligence platforms. FCC wiretapping statutes restrict civilian operation, channeling sovereign budgets toward authorized defense and intelligence end users. Northern Virginia's defense contracting corridor hosts subsystem vendors integrating IMSI catcher modules into broader signals intelligence architectures.
Germany
Federal interior and defense ministries accelerate 5G standalone rollout timelines, forcing premature replacement of legacy interception hardware. ETSI lawful interception frameworks mandate enhanced audit trails and judicial oversight integration for all deployments. Bavaria's communications technology cluster anchors European manufacturing for next-generation decryption modules.
Israel
Ministry of Defense export controls shape vendor market access across Middle Eastern and Asian security services. Type-approval requirements extend certification timelines for non-domestic suppliers seeking entry. Tel Aviv's defense technology corridor concentrates portable system development for rapid deployment scenarios in border security applications.
South Korea
Telecommunications operators accelerate 5G standalone infrastructure deployment, creating demand for SUCI encryption penetration capabilities. National intelligence service procurement prioritizes next-generation decryption modules for cyber-physical threat convergence. Seoul's electronics manufacturing basin supplies software-defined radio chipsets to regional interception hardware vendors.
India
Telecommunication Engineering Centre type-approval requirements fragment vendor qualification pathways for imported equipment. Border security modernization programs drive vehicle-mounted system procurement along remote frontiers with limited terrestrial infrastructure. Bangalore's defense electronics cluster incubates indigenous lawful interception capability development for domestic security agencies.
Global IMSI Catcher Market Competitive Landscape
Listed defense conglomerates compete with private specialists across certification depth and procurement channel access. Market structure concentrates around three tiers: prime contractors with multi-year sovereign relationships, subsystem vendors capturing unbundled integration value, and regional specialists optimizing for rapid deployment portability. Strategic moves center on FPGA substrate miniaturization for handheld form factors and open-architecture interface standardization to displace turnkey procurement patterns.
Within the prime contractor tier, L3Harris Technologies and Rohde and Schwarz exemplify divergent geographic anchoring strategies. L3Harris occupies a position tied to US defense program integration, while Rohde and Schwarz represents European regulatory affairs infrastructure depth. Septier Communication sits within the rapid-deployment specialist archetype, competing across Middle Eastern and Asia-Pacific markets where portable system optimization commands procurement priority.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Septier Communication |
| Rohde and Schwarz |
| PKI Electronic Intelligence |
| Phantom Technologies |
| 4Intelligence |
| KAVIT Electronics Industries |
| Proximus LLC |
| NeoSoft |
| Others |
Supply & Pricing Matrix
ETSI lawful interception frameworks and national type-approval regimes gate both vendor qualification and price differentiation simultaneously, compressing margins for non-compliant suppliers while rewarding certified incumbents with sustained premium capture across European defense procurement channels.
Pricing Analysis
5G-capable decryption modules command substantial premiums over LTE backbone systems and legacy GSM interceptors, with three-tier pricing structure across premium, standard, and economy levels separating SUCI-penetration platforms from backward-compatible units and rural-deployment hardware. Price differentiation rests on certification depth and FPGA substrate integration sophistication. Cost compression in portable handheld configurations is intensifying because FPGA miniaturization collapses historical mobility premiums. Municipal special weapons and tactical teams in France and Spain exhibit highest price sensitivity, while United States special operations commands prioritize capability over unit economics.
Supply Chain Analysis
Strategic stockpiling of field-programmable gate arrays and software-defined radio chipsets prevails over just-in-time preferences given Taiwan and South Korea fabrication concentration and single-source vulnerability exposure. Raw material dependencies center on gallium nitride substrates, high-frequency RF components, and military-grade ruggedization materials. Tariff exposure runs through semiconductor import restrictions and export control friction from Israel's Ministry of Defense and India's Telecommunication Engineering Centre. Distribution runs through prime contractor integration channels and direct government agency procurement with extended certification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where ETSI framework entrenchment and national type-approval complexity create switching costs that protect incumbent positions across multi-year sovereign procurement cycles.
For Market Incumbents: Compound defensive positioning through backward integration into FPGA substrate design and captive supply of software-defined radio chipsets to offset Taiwan and South Korea single-source vulnerability. Deepen certification engineering investments across ETSI national transpositions to extend 12-18 month qualification timelines that deter emerging subsystem vendors. Prioritize open-architecture interface standardization in United States special operations command programs to capture unbundled integration value as prime contractor relationships fragment. For New Entrants and Emerging Players: Differentiate on AI-assisted signal classification capabilities that address RF engineering talent scarcity constraining incumbent capacity expansion. Target urban counter-terrorism units in France and Spain with rapid-deployment portable systems optimized for dense signal environments, the most penetrable segment given sustained premium pricing and underpenetrated municipal procurement. Pursue go-to-market positioning through defense contractor subsystem partnerships rather than direct government agency certification pathways. For Investors and Strategic Acquirers: ETSI framework revisions reshaping audit trail and judicial oversight mandates reshape the acquisition landscape toward vendors with established regulatory affairs infrastructure. Long-term viability centers on 5G standalone decryption capability development given premature obsolescence risk facing legacy hardware. Acquisition target archetype: specialized subsystem vendors with open-architecture interfaces and FPGA design capability. Watch for SUCI encryption standard evolution as inflection indicator requiring hardware refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| FPGA Substrate Miniaturization | Collapses portability premiums and reshapes competitive positioning around concealability. |
| Open-Architecture Interface Standardization | Captures unbundled integration value as United States special operations commands fragment procurement. |
| 5G Decryption Module Development | Addresses SUCI encryption complexity driving South Korean and German operator rollout timelines. |
| Regulatory Affairs Infrastructure Expansion | Accelerates ETSI national transposition compliance across Poland and Romania border security programs. |
| AI-Assisted Signal Classification Integration | Mitigates RF engineering talent scarcity constraining real-time target discrimination development. |
Research Methodology
A standing panel of defense procurement officers, signals intelligence technical directors, regulatory affairs specialists at lawful interception vendors, and RF engineering program managers provided ongoing calibration throughout the study. Primary interview insights combined with secondary validation from FCC wiretapping statute filings, ETSI framework documentation, Israel Ministry of Defense export control registers, and India Telecommunication Engineering Centre type-approval records. Bottom-up unit shipment modeling and top-down sovereign budget allocation analysis triangulated market sizing across product type, technology generation, and application segments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled deployment scenario mobility requirements, interception technology sophistication tiers, and end-user procurement authority structures. CAGRs derived from sovereign surveillance budget trajectories and network infrastructure migration curves. Industry-specific forecast inputs included 5G standalone rollout timelines and semiconductor supply concentration risk assessments.
Forecasts assume regulatory continuity in ETSI member state transpositions, FCC wiretapping restrictions, and Israel Ministry of Defense export controls; material policy shifts would require re-modeling. Specific risk factors encompass spectrum reallocation decisions, encryption standard evolutions, and semiconductor supply disruption. Revision becomes warranted when SUCI encryption penetration capability gaps or FPGA supply constraints cross operational viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Social Media Security Market
Security Software
Hardware Encryption Market
Security Software
Quantum Key Distribution System Market
Security Software
Mobile Data Protection Solutions and Services Market
Security Software
Identity-As-A-Service (Idaas) Market
Security Software
Web Content Filtering Market
Security Software
Bot Mitigation Market
Security Software
Decentralized Identity Software Market
Security Software
Global Data Classification Market
Security Software
Global Secure Mobile Communications Software Market
Security Software
Global Data Protection As a Service (Dpaas) Market
Security Software
Asia Pacific Video Management System Market
Security Software
Global SMS Firewall Market
Security Software
Identity Verification Software Market
Security Software
Security Information and Event Management Software Market
Security Software
Anti-Fraud Management System Market