
 Asia Pacific Video Management System Market | 2026-2036
Asia Pacific Video Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Video Management System Market Insights
Subscription-based software maintenance is rebalancing revenue models away from perpetual licenses across the Asia Pacific Video Management System landscape. Hangzhou Hikvision Digital Technology Co., Ltd. leverages its domestic manufacturing scale to control pricing in China's provincial security tenders. Genetec Inc. anchors its regional presence through federated architecture deployments across multi-site transportation hubs. Honeywell International Inc. navigates fragmented municipal procurement standards by specializing in compliance-ready hybrid cloud stacks.
A Video Management System constitutes software infrastructure that aggregates, processes, and distributes video feeds from distributed camera networks, typically supporting H.265 compression and ONVIF protocol interoperability for real-time situational awareness. The platform serves commercial and government operators requiring centralized command over security, traffic, and facility operations. Cloud-based deployments now capture the fastest expansion as telecom infrastructure in Indonesia and Vietnam matures, while on-premises installations retain dominance in China's government vertical where data sovereignty requirements restrict off-premise storage. Video analytics represents the highest-margin technology layer, with edge-based AI inference displacing centralized server processing in large-scale retail and transportation deployments.
China's GB standards for networked video security and India's BIS certification for electronic surveillance equipment shape product compliance requirements across the region. Japan's METI guidelines on critical infrastructure protection further constrain foreign vendor participation in utility and transport sectors. Stakeholders must monitor divergence between national data-localization mandates and the operational flexibility offered by hybrid deployment architectures.
Market Dynamics
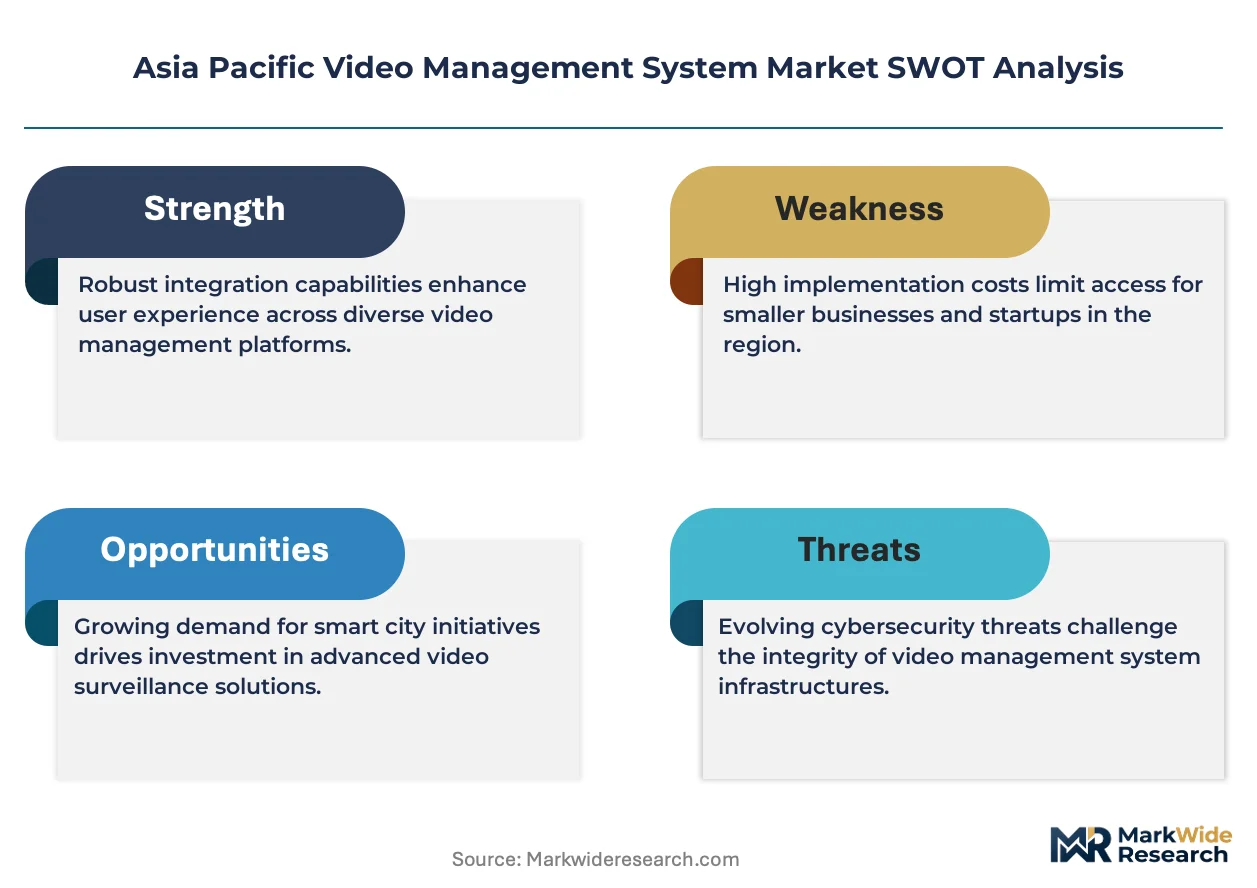
China's GB standards for networked video security and India's BIS certification for electronic surveillance equipment are compressing vendor margins while accelerating platform consolidation across municipal procurement channels.
Growth Catalysts
- Smart city infrastructure mandates:Southeast Asian metros are accelerating centralized surveillance platform procurement as urban density rises and public safety digitization becomes a political priority in Indonesia, Vietnam, and the Philippines.
- PLI scheme incentives:India's production-linked incentive program for electronics manufacturing is reshaping domestic supply chains for video analytics hardware, reducing import dependency and lowering landed costs for government tenders.
- AI-integrated public safety networks:Tier-one urban clusters in China now mandate municipal deployment of machine-learning-enabled video platforms, creating sustained demand for inference-capable edge hardware.
Market Restraints
- Semiconductor input volatility:GPU and AI accelerator chip pricing fluctuations constrain margin predictability for edge-based analytics hardware manufacturers serving price-sensitive provincial governments.
- Supply concentration in camera modules:Over-reliance on domestic Chinese lens and sensor fabricators creates procurement risk for foreign VMS software vendors seeking hardware-agnostic deployments.
- Data-localization technical barriers:China's GB standards effectively prohibit cloud-native architectures for government verticals, forcing hybrid stack complexity that elongates deployment timelines.
Strategic Opportunities
- Underpenetrated Indonesian cloud migration:Telecom infrastructure maturation in secondary Indonesian cities is opening subscription-based VMS deployment channels previously blocked by connectivity constraints.
- Transportation hub federated architecture:Multi-site airport and port operators across Malaysia and Thailand present demand for centralized command platforms spanning geographically distributed camera networks.
- Retail edge-AI convergence:Video analytics fusion with point-of-sale and inventory systems in Vietnam's modern trade sector is creating integrated operational intelligence opportunities beyond pure security applications.
Industry Challenges
- AI/ML engineering talent scarcity:Shortage of computer vision specialists and edge inference optimization engineers constrains product development velocity for mid-tier software vendors.
- Multi-jurisdiction certification complexity:Divergent BIS, GB, and METI compliance timelines force redundant testing cycles that delay product launches by quarters.
- Legacy analog infrastructure integration:Hybrid deployment requirements for coaxial-to-IP migration in aging commercial buildings inflate implementation costs and extend project durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Video Management System Market |
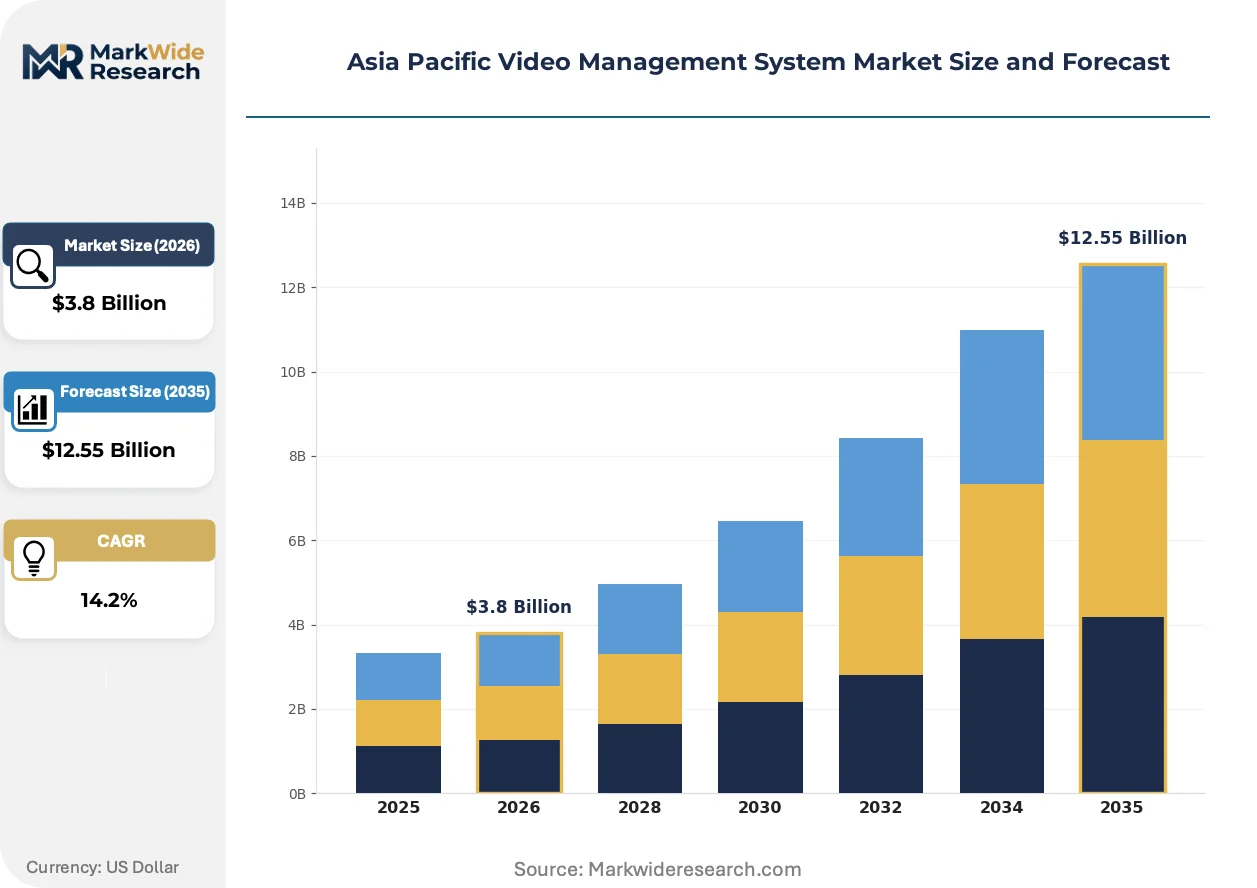
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premises, Cloud-Based, Hybrid, Standalone Deployment: Video Surveillance, Access Control, Incident Management, Data Storage End User: Retail, Transportation, Hospitality, Education Technology: IP Cameras, Analog Cameras, PTZ Cameras, Video Analytics |
| Companies Covered | Johnson Controls, Genetec Inc., Hangzhou Hikvision Digital Technology Co., Ltd., Hanwha Techwin, Axis Communications AB, Zhejiang Dahua Technology Co., Ltd., Honeywell International Inc., Panasonic Holdings Corporation, Bosch Security and Safety Systems, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Video Management System Market Trends and Innovations
Video Management System architecture is fragmenting into composable microservices as buyers reject monolithic platforms, while regulatory pressure on data sovereignty accelerates edge-native design priorities across Asia Pacific procurement.
Edge-based AI inference engines are modularizing VMS functionality into discrete analytics containers that deploy independently across camera networks. Large-scale retail operators in South Korea and transportation authorities in Singapore are adopting these containerized modules to match compute provisioning to specific use cases. This modularization is compressing centralized server hardware demand while redistributing software revenue toward per-camera licensing models.
Japan's METI guidelines on critical infrastructure protection are constraining foreign vendor participation in utility and transport sector tenders. The policy mandates domestic data custody and supply chain provenance documentation that many international software providers cannot satisfy. Japanese power generation and railway operators are responding by prioritizing domestic system integrators with established compliance track records, fragmenting competitive access.
Subscription-based software maintenance is displacing perpetual license structures across municipal and commercial procurement channels. Government buyers in Australia's state capitals and enterprise facilities managers in India's tech parks are unbundling upfront platform acquisition from ongoing support and analytics upgrades. This preference shift is most visible in hybrid cloud deployments where operational expenditure models align with annual budget cycles and reduce capital approval friction.
Asia Pacific Video Management System Market Segmentation
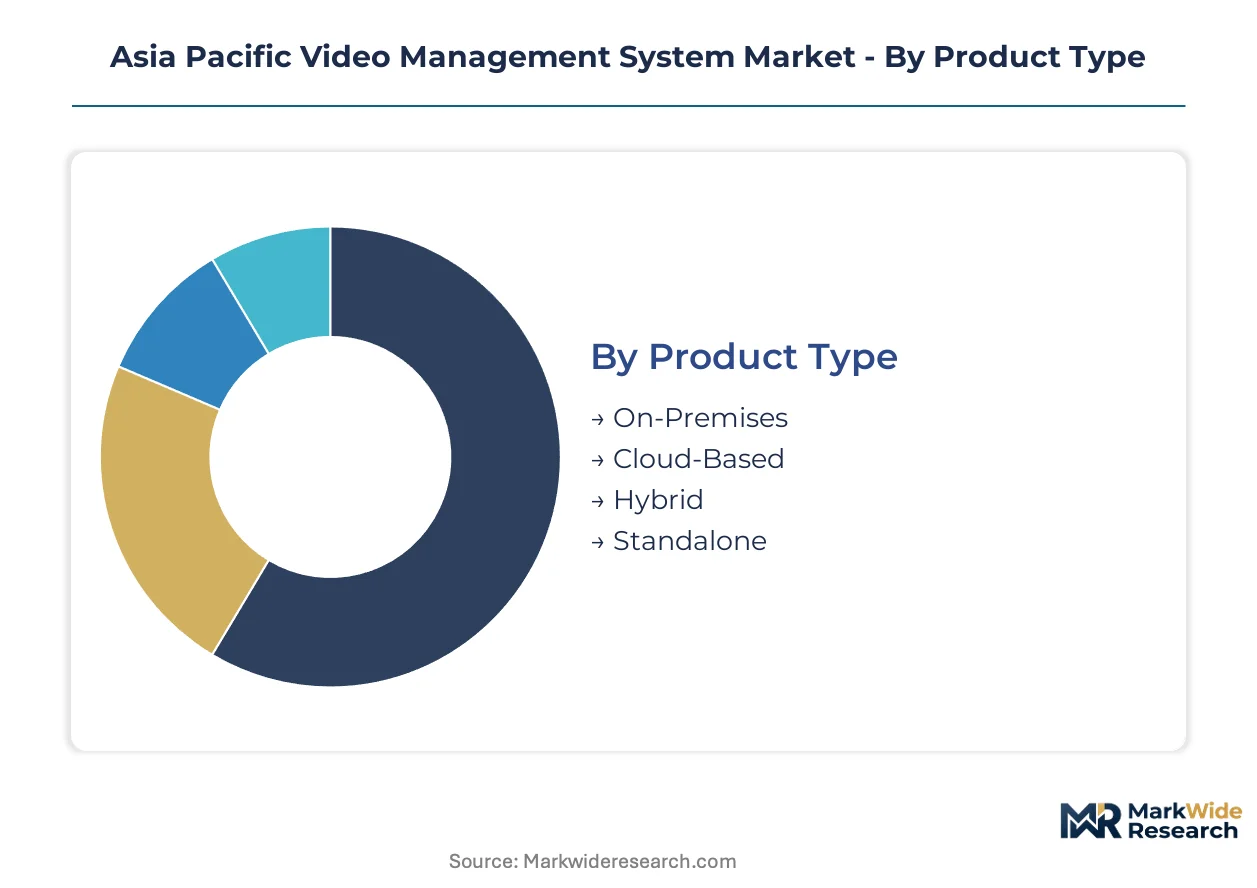
Deployment architecture and end-use verticals determine procurement specifications across Asia Pacific Video Management System procurement. Buyers prioritize compliance posture, data sovereignty requirements, and integration complexity when selecting between on-premises, cloud-native, and hybrid configurations.
Product Type:
Total cost of ownership and regulatory data-localization mandates drive platform selection decisions across municipal and enterprise procurement channels.
- On-Premises:Fully localized server infrastructure with direct hardware control satisfies China's GB standards for government network security. Municipal tenders in tier-one Chinese urban clusters mandate this architecture to enforce data sovereignty compliance.
- Cloud-Based:Subscription delivery eliminates capital expenditure approval cycles and accelerates deployment timelines. Telecom infrastructure maturation in Indonesian secondary cities is unlocking this procurement channel for commercial operators previously blocked by connectivity constraints.
- Hybrid:Split processing between edge devices and centralized cloud repositories balances latency performance with storage economics. Australian state capitals and Indian tech park facilities managers favor this model for annual budget cycle alignment.
- Standalone:Single-site software packages serve small commercial installations requiring minimal integration overhead. Price-sensitive provincial governments in Vietnam and Philippines deploy these for basic surveillance coverage without analytics layers.
Volume sits with On-Premises; growth tilts toward Cloud-Based.
Deployment:
Functional application scope shapes hardware-software bundling strategies and determines integration partner selection.
- Video Surveillance:Core platform functionality aggregating distributed camera feeds for real-time monitoring and forensic review. China's tier-one urban clusters mandate AI-integrated deployments for municipal public safety networks.
- Access Control:Credential verification and entry management integration with video identity confirmation. Singapore transportation authorities and Malaysian port operators deploy these for multi-site federated command architectures.
- Incident Management:Workflow automation for security response coordination and evidence chain documentation. Japanese power generation operators under METI guidelines prioritize domestic system integrators with compliance track records.
- Data Storage:Compression optimization and retention policy management for long-term video archives. India's PLI scheme for electronics manufacturing is reshaping domestic supply chains for storage hardware components.
Revenue concentrates in Video Surveillance; Incident Management is climbing the fastest on regulatory compliance spending.
End User:
Vertical-specific operational requirements dictate analytics sophistication and integration depth.
- Transportation:Multi-site airport and port operators across Malaysia and Thailand require centralized command platforms spanning geographically distributed camera networks with low-latency edge processing.
- Retail:Video analytics fusion with point-of-sale and inventory systems in Vietnam's modern trade sector creates integrated operational intelligence beyond pure security applications.
- Hospitality:Guest safety and property protection across integrated resort complexes in Philippines and Indonesia drives demand for unified lobby-to-perimeter coverage.
- Education:Campus-wide monitoring for student safety and facility protection in Australian state capital school districts operates under strict privacy compliance frameworks.
Transportation commands premium pricing; Retail shows steepest expansion trajectory on edge-AI convergence.
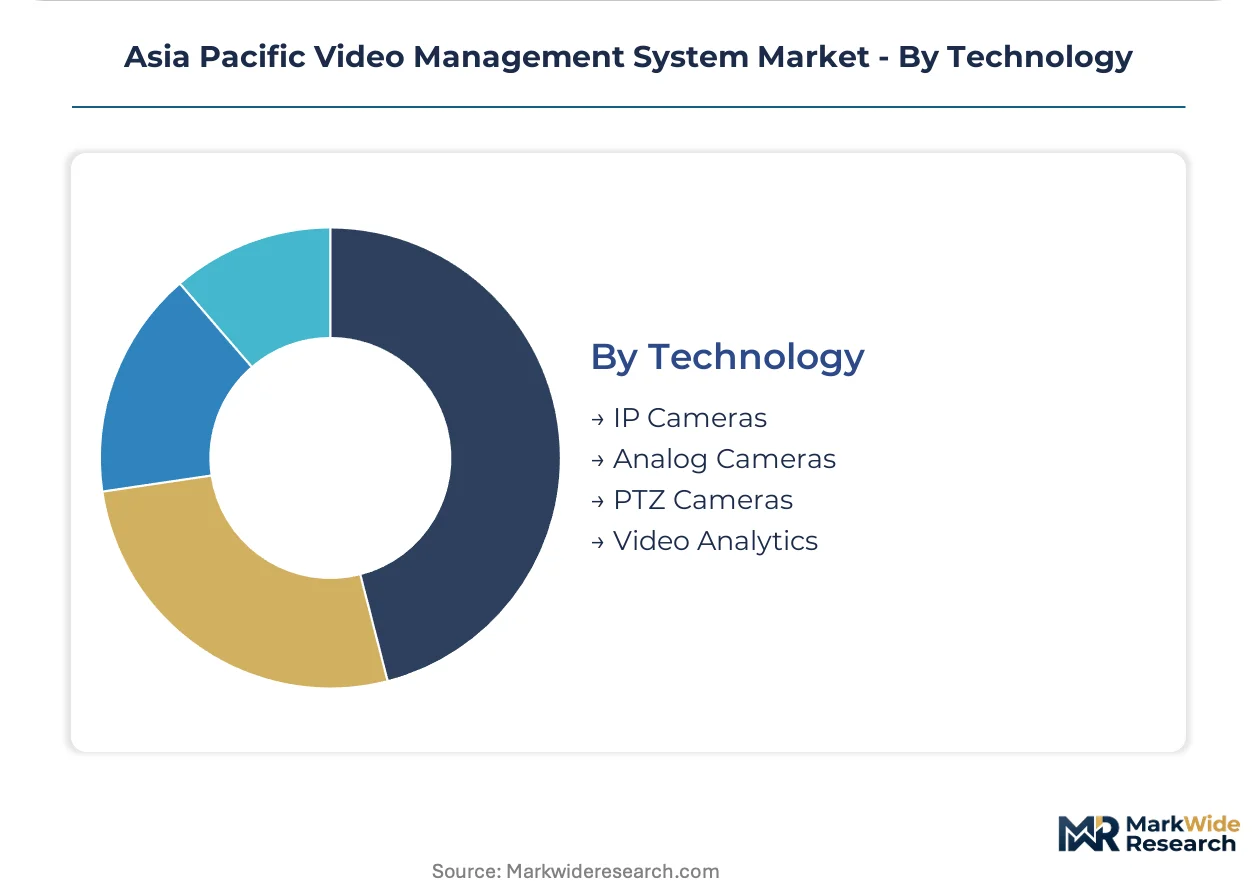
Technology:
Camera hardware specifications and processing location determine system architecture and margin distribution.
- IP Cameras:Network-addressable digital endpoints supporting H.265 compression and ONVIF protocol interoperability. Migration from analog infrastructure in aging commercial buildings across Southeast Asia inflates implementation costs and extends project timelines.
- Video Analytics:Edge-based AI inference engines modularizing VMS functionality into discrete analytics containers. Large-scale retail operators in South Korea and Singapore transportation authorities adopt these for use-case-matched compute provisioning.
- PTZ Cameras:Pan-tilt-zoom mechanical positioning for active tracking and wide-area coverage with motorized lens control. Stadium and critical infrastructure operators in Japan deploy these under METI-mandated domestic custody requirements.
- Analog Cameras:Coaxial-connected legacy devices requiring encoder bridges for IP network integration. Hybrid deployment requirements for coaxial-to-IP migration constrain upgrade velocity in Indonesia's aging commercial building stock.
IP Cameras dominate unit shipments; Video Analytics captures margin expansion on per-camera licensing models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangtze River Delta anchors Asia Pacific Video Management System procurement volume. Municipal governments across tier-one Chinese urban clusters mandate AI-integrated public safety networks. Smart city infrastructure projects in Southeast Asian metros accelerate centralized surveillance platform deployment.
China
Provincial security tenders in Jiangsu and Guangdong provinces drive sustained demand for inference-capable edge hardware. GB standards for networked video security effectively prohibit cloud-native architectures for government verticals. Shenzhen's technology corridor concentrates domestic manufacturing scale for camera modules and analytics hardware.
India
Government tenders for urban surveillance and critical infrastructure protection expand procurement channels for video analytics hardware. The PLI scheme for electronics manufacturing reshapes domestic supply chains and reduces import dependency. Karnataka's tech parks and Maharashtra's industrial corridors concentrate facilities management demand for hybrid cloud VMS deployments.
Japan
Utility and railway operators under METI guidelines prioritize domestic system integrators with compliance track records. Critical infrastructure protection mandates constrain foreign vendor participation in transport sector tenders. The Kanto region around Tokyo concentrates power generation and railway operator demand for incident management platforms.
Australia
State capital governments unbundle upfront platform acquisition from ongoing support and analytics upgrades. Annual budget cycle alignment favors hybrid cloud deployments with operational expenditure models. New South Wales and Victoria lead procurement for campus-wide monitoring in education and hospitality sectors.
Singapore
Transportation authorities adopt containerized analytics modules for use-case-matched compute provisioning. Multi-site airport and port operators require centralized command platforms spanning geographically distributed camera networks. The city-state's status as a regional logistics hub drives premium-tier demand for federated architecture deployments.
Asia Pacific Video Management System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Asia Pacific Video Management System landscape. The vendor base fragments across integrated hardware-software conglomerates, pure-play software developers, and regional system integrators. Three strategic archetypes dominate: domestic Chinese manufacturers with captive supply chains, Western specialists in federated multi-site architectures, and Japanese conglomerates serving METI-regulated critical infrastructure. Competitive moves concentrate on hybrid cloud stack certification and edge-AI inference optimization.
Within the domestic Chinese manufacturing tier, Hangzhou Hikvision Digital Technology Co., Ltd. and Zhejiang Dahua Technology Co., Ltd. exemplify scale-driven positioning through integrated hardware-software offerings. Among Western specialists, Genetec Inc. occupies a position representing federated architecture expertise for multi-site transportation deployments. These anchors illustrate how geographic origin and corporate structure shape competitive access to regulated procurement channels across the region.
| Leading Market Players |
|---|
| Johnson Controls |
| Genetec Inc. |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Hanwha Techwin |
| Axis Communications AB |
| Zhejiang Dahua Technology Co., Ltd. |
| Honeywell International Inc. |
| Panasonic Holdings Corporation |
| Bosch Security and Safety Systems |
| Others |
Pricing and Supply Chain Analysis
Municipal procurement officers in China's tier-one urban clusters dominate purchasing volume and enforce subscription-based SaaS-tiered pricing for AI-integrated public safety networks. This buyer concentration compresses margins for foreign VMS software vendors while amplifying pricing power for domestic manufacturers with captive supply chains.
Pricing Analysis
Value-based pricing anchored to inference throughput and edge-device uptime dominates large-scale retail and transportation deployments in South Korea and Singapore. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled analytics containers from basic video aggregation and legacy analog bridge solutions. Cost compression in China's provincial security tenders is intensifying because Hangzhou Hikvision leverages domestic manufacturing scale to undercut foreign competitors. Provincial governments in Vietnam and the Philippines exhibit highest price sensitivity, while Japanese railway operators under METI guidelines show lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Certification gating through China's GB standards, India's BIS certification, and Japan's METI guidelines fragments vendor access and elongates product launch timelines. Manufacturing concentration centers on China for camera modules and edge analytics hardware, South Korea for advanced semiconductor components, and Taiwan for GPU and AI accelerator chips. The supply chain draws from CMOS image sensors, H.265 encoder chipsets, and ruggedized edge-computing enclosures. Single-source vulnerability in domestic Chinese lens fabricators creates procurement risk for hardware-agnostic software vendors. Distribution runs through municipal tender channels, regional system integrators, and telecom operator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where China's GB standards for networked video security erect formidable barrier-to-entry moats for certified domestic players.
For Market Incumbents: Extend federated architecture capabilities across multi-site transportation hubs in Malaysia and Thailand to defend against pure-play cloud-native entrants. Deepen backward integration into edge-AI inference chipsets to offset GPU pricing volatility and secure margin predictability in provincial tenders. Prioritize METI compliance documentation to maintain access to Japan's critical infrastructure vertical. For New Entrants and Emerging Players: Indonesian commercial operators in secondary cities represent the most penetrable buyer archetype as telecom infrastructure maturation unlocks subscription-based cloud deployments previously blocked by connectivity constraints. Target Vietnam's modern trade retail sector for video analytics fusion with point-of-sale systems, bypassing saturated government verticals. Pursue channel partnerships with domestic system integrators possessing established BIS certification track records rather than direct sales approaches. For Investors and Strategic Acquirers: The window for entry favors asset-light software developers with modular microservices architectures and per-camera licensing models. Long-term viability hinges on edge-native design capabilities that align with data-localization mandates across the region. Monitor divergence between national data-sovereignty requirements and hybrid cloud operational flexibility as the primary inflection signal for platform consolidation waves.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Inference Optimization | Containerized analytics modules align compute provisioning to specific use cases in Singapore transportation authorities. |
| Hybrid Cloud Stack Certification | Compliance-ready architectures satisfy Australia's state capital budget cycles and China's data sovereignty requirements. |
| Federated Architecture Deployment | Centralized command platforms span geographically distributed camera networks across Malaysian port operators. |
| Domestic Supply Chain Integration | India's PLI scheme reduces import dependency for video analytics hardware in Karnataka tech park deployments. |
| Regulatory Compliance Documentation | METI-mandated domestic custody requirements constrain foreign vendor participation in Japanese railway tenders. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with municipal procurement officers, VMS platform engineers, system integration specialists, and edge-AI hardware product managers. Bottom-up triangulation across deployment architecture specifications and top-down validation against national smart city budget allocations ensured cross-verification. Secondary sources included China's GB standards documentation, India's BIS certification registries, Japan's METI infrastructure protection guidelines, and ASEAN municipal tender databases.
Data-stream reconciliation across product type, deployment model, end-use vertical, and technology layer informed the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit assumptions. Modeled dimensions encompassed on-premises versus cloud-native adoption curves, AI inference localization trends, and subscription revenue conversion rates across government and commercial procurement channels.
Revisions become necessary when semiconductor input volatility disrupts edge hardware manufacturing economics or when data-localization mandates tighten beyond hybrid architecture accommodation. Forecasts reflect assumptions about telecom infrastructure maturation timelines and regulatory certification pathway stability. A model refresh is warranted upon material change in AI accelerator chip pricing or municipal procurement standard harmonization across the region.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
DNS Protection Software Market
Security Software
Spam Blocking Software Market
Security Software
Confidential Computing Market
Security Software
Employee Fraud Detection Market
Security Software
Parental Monitoring Software Market
Security Software
Messaging Security Market
Security Software
Mass Notification System Market
Security Software
Data Privacy Software Market
Security Software
Certification Authority Market
Security Software
Privileged Access Management (PAM) Market
Security Software
Europe Enterprise Firewall Market
Security Software
Employee Surveillance and Monitoring Software Market
Security Software
Secure Flash Drive Market
Security Software
Global Security Assertion Markup Language (SAML) Authentication Market
Security Software
Hardware OTP Token Authentication Market
Security Software
Video Intercom Devices and Equipment Market