
 Quantum Key Distribution System Market | 2026-2036
Quantum Key Distribution System Market Size, Share, and Industry Trends Forecast 2026-2036
Quantum Key Distribution System Market Insights
Direct sales channels for quantum key distribution hardware is fragmenting as system integrators and national telecom carriers build captive procurement arms. ID Quantique leverages its Geneva-based manufacturing to anchor European government contracts. QuantumCTek Co., Ltd. dominates domestic Chinese deployment through state-backed quantum communication backbone projects. Toshiba Digital Solutions Corporation sustains its position via integrated quantum random number generator and QKD module portfolios.
A quantum key distribution system transmits cryptographic keys using photonic quantum states, typically operating at telecom wavelengths near 1550 nm with decoy-state protocols to resist photon-number-splitting attacks. Its primary purpose is to establish information-theoretically secure keys between distant parties, rendering interception detectable through quantum mechanical disturbance. BB84 protocol implementations currently occupy the largest installed base, while measurement-device-independent QKD represents the fastest-growing technology segment as it closes critical detector side-channel vulnerabilities. Financial transactions and government communications applications concentrate the deepest margin pools due to compliance-driven procurement budgets.
The National Institute of Standards and Technology in the United States, the European Telecommunications Standards Institute, and China's State Administration for Market Regulation each shape QKD demand through divergent quantum-safe migration timelines and certification frameworks. ETSI's standardization of quantum key distribution interface protocols directly determines product interoperability and market access across European member states. Stakeholders must monitor which regulatory jurisdiction's certification requirements their target customers will adopt first, as this choice locks in supplier selection for decade-long deployment cycles.
Market Dynamics
Measurement-device-independent QKD protocols are collapsing the traditional detector-side-channel vulnerability window, forcing incumbent hardware suppliers to redesign photon detection subsystems around trusted-node architectures.
Growth Catalysts
- China's national cryptographic standards:Mandatory quantum-safe migration timelines for critical infrastructure operators are pulling deployment contracts toward domestic system integrators.
- Financial transaction networks:Compliance-driven procurement budgets from central banks and clearing houses are accelerating BB84 protocol installations in payment backbone facilities.
- Decoy-state protocol maturation:Resistance to photon-number-splitting attacks at telecom wavelengths is expanding addressable use cases beyond government communications into enterprise data centers.
Market Restraints
- Single-photon detector supply concentration:Cryogenic superconducting nanowire manufacturing remains concentrated among specialized Japanese and European component suppliers.
- ETSI certification friction:Divergent interface protocol requirements across EU member states are fragmenting product interoperability and extending validation cycles.
- Classical encryption substitution threat:Post-quantum cryptographic algorithms from NIST standardization processes are competing for budget share in latency-sensitive applications.
Strategic Opportunities
- South Korean metropolitan technology corridors:Underpenetrated deployment of quantum communication backbones in Busan and Incheon technology zones offers first-mover positioning.
- Quantum random number generator convergence:Integration of QRNG modules with QKD hardware is creating bundled security appliance opportunities in gaming and lottery regulatory compliance.
- EU Cybersecurity Act tailwind:Certification framework mandates for critical infrastructure are opening decade-long supplier lock-in windows across European energy and transport operators.
Industry Challenges
- Quantum photonics engineering talent scarcity:Specialized workforce for single-photon source characterization and fiber-coupling optimization remains concentrated in academic laboratories.
- Legacy PKI integration complexity:Hybrid deployment models combining QKD key management with existing certificate infrastructure require custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quantum Key Distribution System Market |
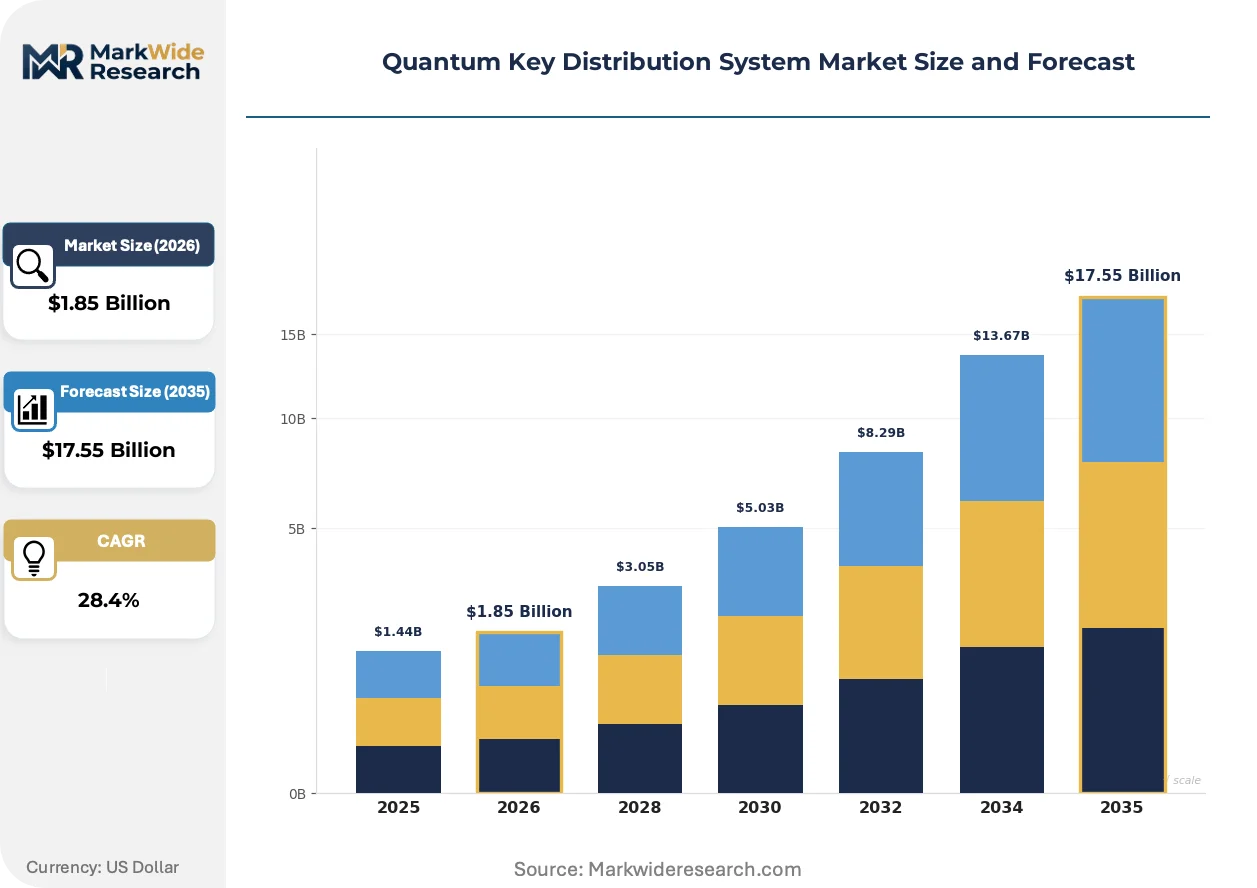
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $17.55 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: BB84, E91, Quantum Repeaters, Measurement-Device-Independent QKD Application: Financial Transactions, Government Communications, Military Applications, Cloud Security End User: Enterprises, Research Institutions, Defense Organizations, Telecommunications Providers Distribution Channel: Direct Sales, Online Channels, Retail Partnerships, System Integrators |
| Companies Covered | ID Quantique, QuantumCTek Co., Ltd., Toshiba Digital Solutions Corporation, QuintessenceLabs Pty Ltd., MagiQ Technologies Inc., NEC Corporation, SK Telecom Co., Ltd., KETS Quantum Security Ltd, LuxQuanta Technologies S.L., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quantum Key Distribution System Market Trends and Innovations
Photonic integration and trusted-node architectures are compressing system form factors while expanding deployable distance ranges. These shifts are reconfiguring supplier competitive advantages around semiconductor packaging capabilities rather than discrete optical bench assembly.
Twin-field QKD protocols are collapsing the rate-distance tradeoff that previously constrained metropolitan area network deployments. Japanese telecommunications operators are piloting these systems across Tokyo-Osaka fiber links. The structural consequence is collapsing the premium pricing power of early-generation discrete-variable systems in high-latency-tolerance applications.
China's State Administration for Market Regulation is finalizing mandatory certification timelines for quantum-safe equipment in financial and energy sectors. Domestic manufacturers must complete GB standards compliance testing before accessing state-backed quantum backbone procurement. QuantumCTek and state-affiliated system integrators are accelerating in-house testing laboratory investments to preempt foreign competitor market entry.
Buyer committees at major European financial institutions are unbundling hardware procurement from integration services. System integrators and national telecom carriers are building captive procurement arms that displace direct OEM relationships. This pattern concentrates most visibly in Swiss and German private banking networks where compliance officers now specify quantum key management as a separate budget line from transport hardware.
Quantum Key Distribution System Market Segmentation
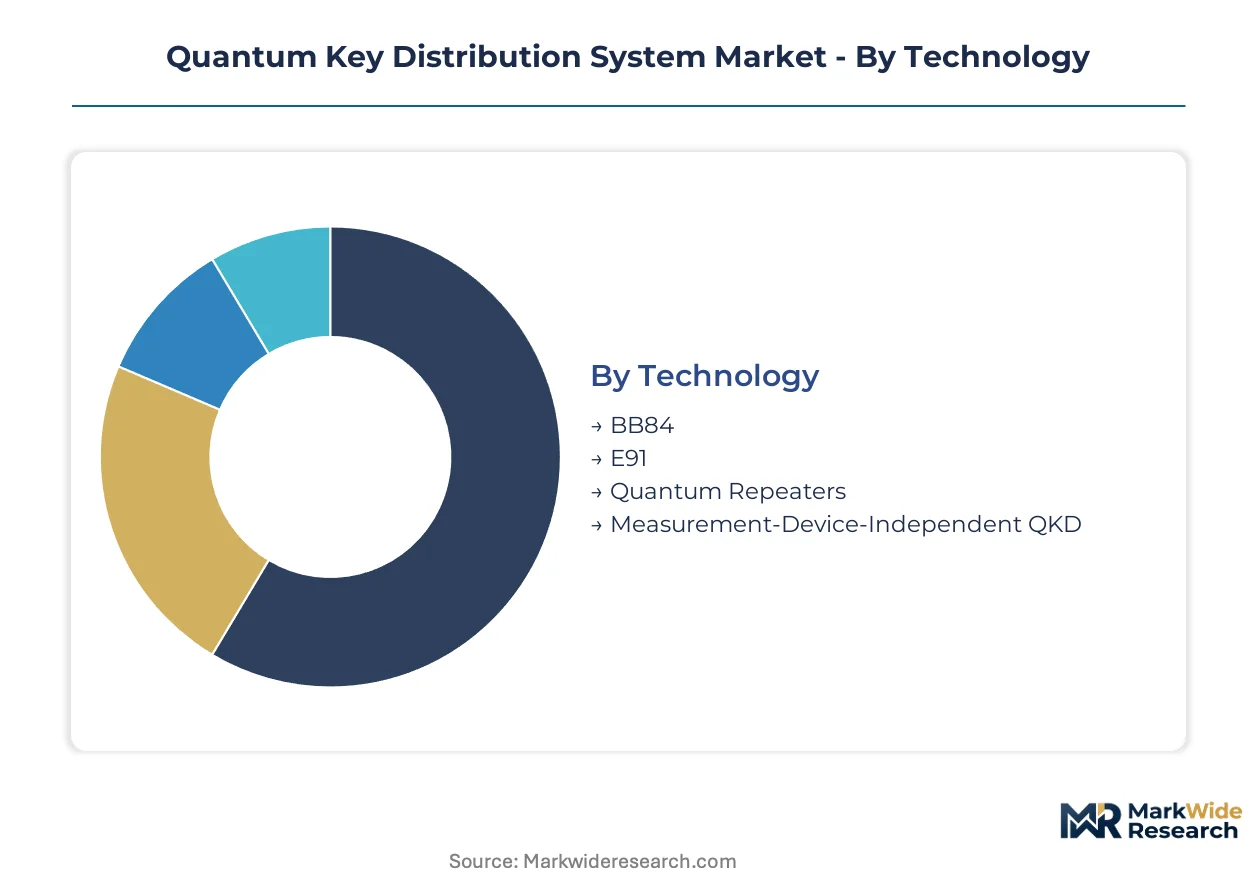
Segmentation in quantum key distribution systems reveals how procurement cycles, certification requirements, and integration complexity vary dramatically across technology types and buyer categories. Understanding these structural differences enables suppliers to align R&D roadmaps with the specific deployment timelines and compliance burdens of each segment.
Technology:
BB84 implementations turn over on decade-long replacement cycles tied to fiber infrastructure amortization, while measurement-device-independent QKD refreshes every 3-4 years as trusted-node architectures evolve. Quantum repeaters remain pre-commercial with extended validation horizons.
- BB84:Decoy-state implementations at 1550 nm telecom wavelengths constitute the dominant installed protocol base. Financial clearing houses in Switzerland and government backbone networks across China concentrate demand for this mature, NIST-validated approach.
- Measurement-Device-Independent QKD:Trusted-node architectures eliminate detector side-channel vulnerabilities that plagued first-generation systems. Japanese metropolitan fiber deployments and EU energy sector pilots are driving the steepest expansion trajectory as certification frameworks stabilize.
- E91:Entanglement-based protocols serve specialized research consortiums requiring Bell inequality verification.
- Quantum Repeaters:Memory-based entanglement swapping remains confined to national laboratory testbeds awaiting deterministic photon source maturation.
BB84 dominates installed base. Measurement-device-independent QKD is where expansion concentrates.
Application:
Cost tiers separate compliance-mandated deployments from discretionary security upgrades, with government budgets absorbing premium pricing and financial institutions demanding performance-per-dollar optimization.
- Financial Transactions:Payment backbone facilities require sub-microsecond latency tolerance combined with quantum-safe key exchange. Central banks in Germany and private clearing networks in Singapore are concentrating procurement for real-time gross settlement systems.
- Government Communications:Classified diplomatic and intelligence networks absorb the highest per-link pricing due to information-theoretic security mandates. China's state-backed quantum backbone projects and EU Council secure fiber initiatives anchor volume.
- Military Applications:Tactical battlefield networks prioritize miniaturization over distance.
- Cloud Security:Hyperscale data centers are piloting QKD for inter-facility key management.
Government communications absorbs the deepest margin pools. Financial transactions is gaining share fastest as compliance deadlines accelerate.
End User:
Customer type determines integration complexity, with telecommunications providers demanding turnkey solutions and research institutions tolerating custom optical bench configurations.
- Telecommunications Providers:National carriers in South Korea and Japan are building captive quantum network operations centers. These buyers require seamless integration with existing SDN orchestration layers and multi-tenant key management.
- Defense Organizations:Military procurement prioritizes tamper-evident hardware and air-gapped trusted nodes. Classified programs in the United States and France are concentrating demand for ruggedized form factors.
- Enterprises:Banking consortia and pharmaceutical multinationals are emerging as mid-scale buyers.
- Research Institutions:Academic laboratories tolerate higher maintenance overhead for experimental protocol access.
Telecommunications providers anchor volume commitment. Defense organizations sustain premium pricing power.
Distribution Channel:
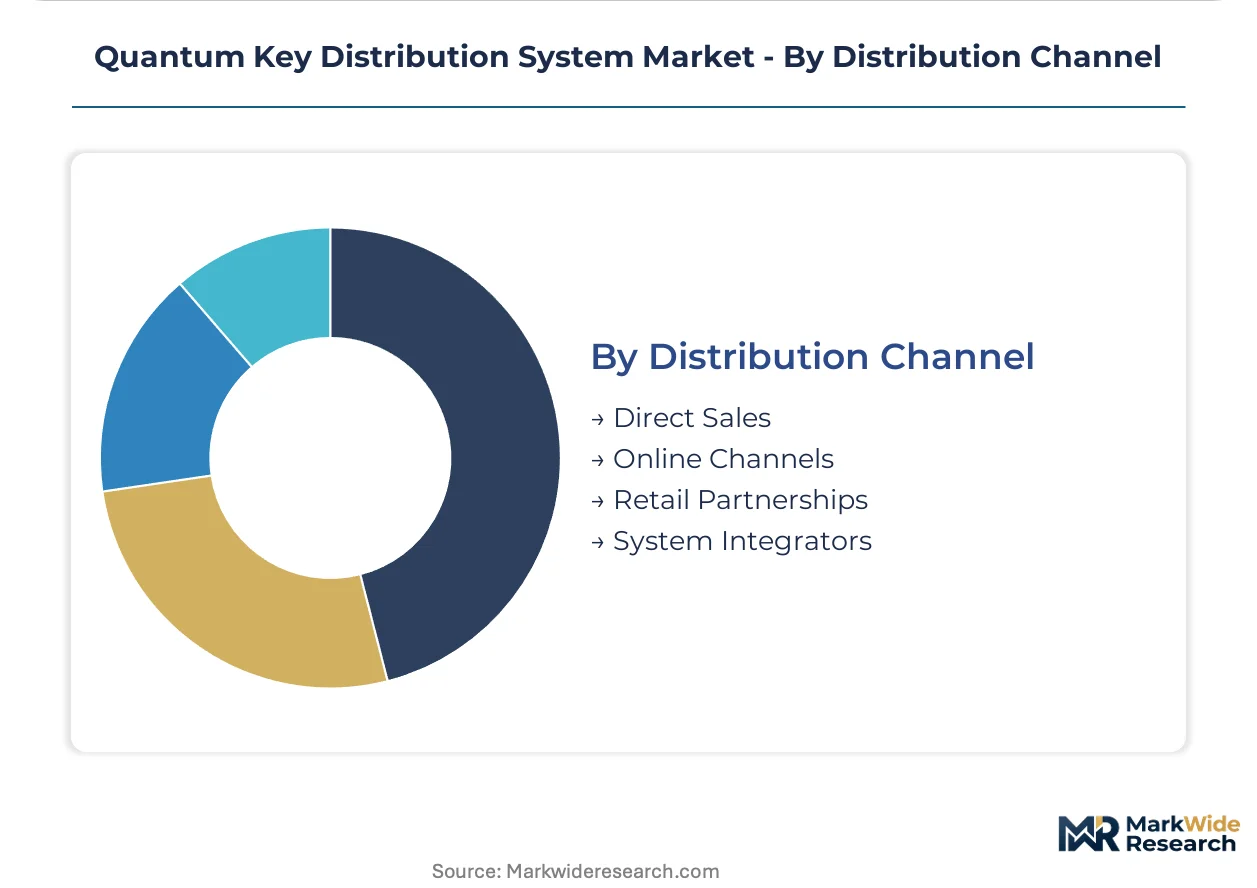
Supply concentration among specialized photonics component vendors is forcing channel restructuring, with system integrators capturing margin that previously flowed to hardware OEMs.
- System Integrators:Swiss and German private banking networks now specify quantum key management as separate from transport hardware procurement. These intermediaries are building captive testing laboratories to accelerate ETSI certification cycles.
- Direct Sales:ID Quantique and QuantumCTek maintain direct relationships for national quantum backbone tenders requiring security-cleared personnel.
- Online Channels:QRNG modules for gaming compliance are migrating to distributor platforms.
- Retail Partnerships:Minimal penetration given specialized installation requirements.
System integrators are displacing direct OEM relationships fastest. Direct sales retains lock-in for sovereign infrastructure projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's national cryptographic standards and the EU's Cybersecurity Act are accelerating certification requirements for quantum-safe infrastructure across major economies. Financial institutions deploying quantum-secured transaction networks represent a rapidly expanding buyer segment. Demand concentrates in East Asian metropolitan technology corridors spanning China, Japan, and South Korea.
China
State-backed quantum communication backbone projects anchor domestic deployment volume. The State Administration for Market Regulation mandates GB standards compliance testing for quantum-safe equipment in financial and energy sectors. Beijing-Tianjin-Hebei and Yangtze River Delta technology corridors concentrate manufacturing and integration capacity.
Japan
Japanese telecommunications operators pilot twin-field QKD systems across Tokyo-Osaka fiber links to collapse rate-distance tradeoffs. METI supports metropolitan quantum network testbeds through national research programs. Kanto and Kansai regions host the densest concentration of cryogenic superconducting nanowire detector suppliers.
South Korea
National carriers build captive quantum network operations centers requiring seamless SDN orchestration integration. The Seoul Capital Area anchors government-funded quantum cryptography deployment in defense and financial sectors. Busan and Incheon technology zones offer underpenetrated backbone deployment opportunities.
Switzerland
Swiss private banking networks unbundle hardware procurement from integration services, with compliance officers specifying quantum key management separately. FINMA and federal cybersecurity frameworks mandate quantum-safe migration for systemically important financial institutions. Geneva-based manufacturing anchors European government contract fulfillment.
Germany
The Bundesbank and private clearing networks concentrate procurement for real-time gross settlement systems with sub-microsecond latency requirements. BSI certification requirements for critical infrastructure operators accelerate compliance-driven procurement cycles. Frankfurt and Munich financial centers drive demand for BB84 protocol installations in payment backbone facilities.
Quantum Key Distribution System Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: sovereign-backed system integrators with captive testing laboratories, semiconductor packaging specialists leveraging photonic integration capabilities, and component suppliers controlling cryogenic detector manufacturing. Competitive positioning hinges on ETSI certification velocity and trusted-node architecture redesign. Dominant moves include backward integration into single-photon source characterization and strategic partnerships with national telecom carriers for quantum network operations center deployment.
Within the sovereign-anchored tier, ID Quantique exemplifies European government contract positioning, while QuantumCTek Co., Ltd. occupies the state-backed system integrator archetype in East Asian deployment. Toshiba Digital Solutions Corporation represents the integrated portfolio approach, combining quantum random number generator modules with QKD hardware for bundled security appliance opportunities.
| Leading Market Players |
|---|
| ID Quantique |
| QuantumCTek Co., Ltd. |
| Toshiba Digital Solutions Corporation |
| QuintessenceLabs Pty Ltd. |
| MagiQ Technologies Inc. |
| NEC Corporation |
| SK Telecom Co., Ltd. |
| KETS Quantum Security Ltd |
| LuxQuanta Technologies S.L. |
| Others |
Pricing and Supply Chain Analysis
Beijing-Tianjin-Hebei technology corridors anchor cryogenic superconducting nanowire detector fabrication, concentrating upstream capacity among specialized Japanese and European component suppliers. This geographic chokepoint grants incumbent photonics vendors substantial pricing leverage over QKD hardware OEMs facing ETSI certification deadlines.
Pricing Analysis
Certification level creates the primary spread between sovereign-grade and enterprise-tier deployments. Three-tier pricing structure across premium, standard, and economy levels reflects GB standards compliance depth, with China's State Administration for Market Regulation mandates absorbing the deepest margin pools. Cost compression in mid-tier BB84 systems is intensifying because post-quantum cryptographic algorithms from NIST processes compete for budget share. Financial institutions demonstrate highest price sensitivity due to performance-per-dollar procurement mandates, while defense organizations sustain premium tolerance for tamper-evident trusted-node architectures.
Supply Chain Analysis
Export-control regimes limiting cryogenic detector and single-photon source technology flows constrain supply elasticity across the sector. Manufacturing concentrates in Japan, Switzerland, and China, with Kanto region suppliers dominating superconducting nanowire fabrication. QKD hardware draws from specialized fiber-coupling assemblies, indium phosphide modulators, and dilution refrigeration units. Single-source vulnerability in cryogenic component supply creates structural exposure to logistics disruption. Distribution runs through national telecom carriers and system integrators building captive procurement arms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as buyer committees unbundle hardware from integration services, creating specialized niches for certification-velocity specialists and trusted-node architecture redesigners.
For Market Incumbents: Insulate sovereign infrastructure revenue streams by accelerating in-house testing laboratory investments ahead of foreign competitor GB standards compliance. Deepen backward integration into single-photon source characterization to preempt supply disruption from Japanese cryogenic detector concentration. Lock decade-long supplier windows through strategic partnerships with national telecom carriers for quantum network operations center deployment. For New Entrants and Emerging Players: Establish a beachhead in South Korean metropolitan technology corridors where Busan and Incheon zones offer underpenetrated backbone deployment opportunities. Target bundled quantum random number generator and QKD appliance opportunities in gaming and lottery regulatory compliance segments. Pursue system integrator channel partnerships rather than direct OEM competition to bypass incumbent certification velocity advantages. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors semiconductor packaging specialists with photonic integration capabilities over discrete optical bench assemblers. Five-to-ten year viability hinges on trusted-node architecture maturation and twin-field protocol commercialization. Acquisition target archetype: captive testing laboratory assets with ETSI certification velocity. Signal to watch: GB standards compliance completion rates among domestic Chinese manufacturers as foreign market entry barrier indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Single-Photon Sources | Cryogenic detector supply concentration in Japanese vendors creates captive supply urgency for QKD hardware OEMs. |
| ETSI Certification Velocity Investment | Divergent EU member state interface protocols fragment product interoperability and extend validation cycles. |
| Trusted-Node Architecture Redesign | Measurement-device-independent protocols eliminate detector side-channel vulnerabilities, collapsing premium pricing of first-generation systems. |
| Quantum Network Operations Center Partnership | South Korean national carriers demand seamless SDN orchestration integration and multi-tenant key management capabilities. |
| GB Standards Compliance Laboratory Buildout | China's State Administration for Market Regulation mandates pre-access testing for state-backed quantum backbone procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ETSI technical specifications, NIST post-quantum cryptographic standardization documents, and SAMR regulatory filings. Primary interviews engaged quantum photonics engineering directors, central bank cybersecurity procurement leads, and national telecom carrier network architects. Secondary validation drew from SEC filings of listed component suppliers, customs records of cryogenic detector trade flows, and patent databases tracking twin-field protocol development. Bottom-up unit deployment estimates triangulate against top-down addressable infrastructure spend across financial and energy sector compliance mandates.
Forecast inputs span technology protocol maturation curves, regulatory certification timeline assumptions, and fiber infrastructure replacement cycles across the analysis window. Segmentation dimensions modeled include protocol type, application compliance tier, end-user integration complexity, and geographic regulatory cluster. CAGRs derive from installed base turnover rates and penetration assumptions across government, financial, and telecommunications verticals. Industry-specific inputs incorporate ETSI interface protocol adoption velocity and GB standards compliance completion rates.
Stress conditions across single-photon detector supply disruption, post-quantum cryptographic algorithm standardization acceleration, and sovereign procurement preference shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding metropolitan fiber deployment timelines and trusted-node architecture commercialization trajectories. Material shifts in NIST post-quantum cryptographic migration timelines or export-control regime expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Extended Detection and Response Market
Security Software
Global Security Assertion Markup Language (SAML) Authentication Market
Security Software
North America Video Management System Market
Security Software
Privileged Access Management (PAM) Market
Security Software
Security Software for Consumers Market
Security Software
Network Video Recorder (NVR) Market
Security Software
Global Password Management Software Market
Security Software
Cyber Attack Simulation Software Market
Security Software
United States Consumer Identity and Access Management Market
Security Software
Business Email Compromise (BEC) Market
Security Software
Europe Video Management System Market
Security Software
Global Security Operation Center As a Service Market
Security Software
Privacy Management Software Market
Security Software
Mobile Antivirus Software Market
Security Software
Global Data Breach Notification Software Market
Security Software
Mobile Identity Management Market