
 Global Data Protection As a Service (Dpaas) Market | 2026-2036
Global Data Protection As a Service (Dpaas) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Protection As a Service (Dpaas) Market Foresight
Subscription-based continuous data protection is decoupling backup infrastructure from enterprise capital budgets. IBM Corporation leverages its mainframe heritage to anchor high-assurance workloads. Microsoft competes through native Azure integration. Commvault specializes in cross-cloud portability for heterogeneous environments.
Data Protection as a Service delivers automated backup, replication, and recovery orchestration through cloud-native control planes with policy-driven retention spanning 15 minutes to seven years. Its primary purpose is eliminating tape-dependent recovery point objectives while enabling regulatory defensibility. Hybrid cloud deployment captures the widest margin pool as enterprises retain sensitive workloads on-premises while bursting archive tiers to public infrastructure. Continuous data protection represents the fastest-growing solution offering as ransomware recovery timelines compress from days to minutes.
FDA 21 CFR Part 11, SEC cybersecurity disclosure rules, and EU GDPR Article 32 collectively mandate immutable backup retention and demonstrable recovery testing. These frameworks shift procurement criteria from feature checklists toward audit-ready compliance attestation. Stakeholders must evaluate vendor cryptographic key escrow models before committing to multi-tenant architectures.
Market Dynamics
Immutable backup architectures are displacing tape-dependent recovery frameworks as ransomware actors systematically target backup repositories. Financial institutions now demand continuous data protection with sub-15-minute recovery point objectives.
Growth Catalysts
- SEC Cybersecurity Disclosure Rules:Public companies must now report material cybersecurity incidents within four business days. This compresses recovery timeline requirements and accelerates DPaaS procurement.
- Healthcare digitization:FDA 21 CFR Part 11 mandates immutable audit trails for electronic records. Pharmaceutical manufacturers are deploying cloud-native backup to satisfy predicate rule compliance.
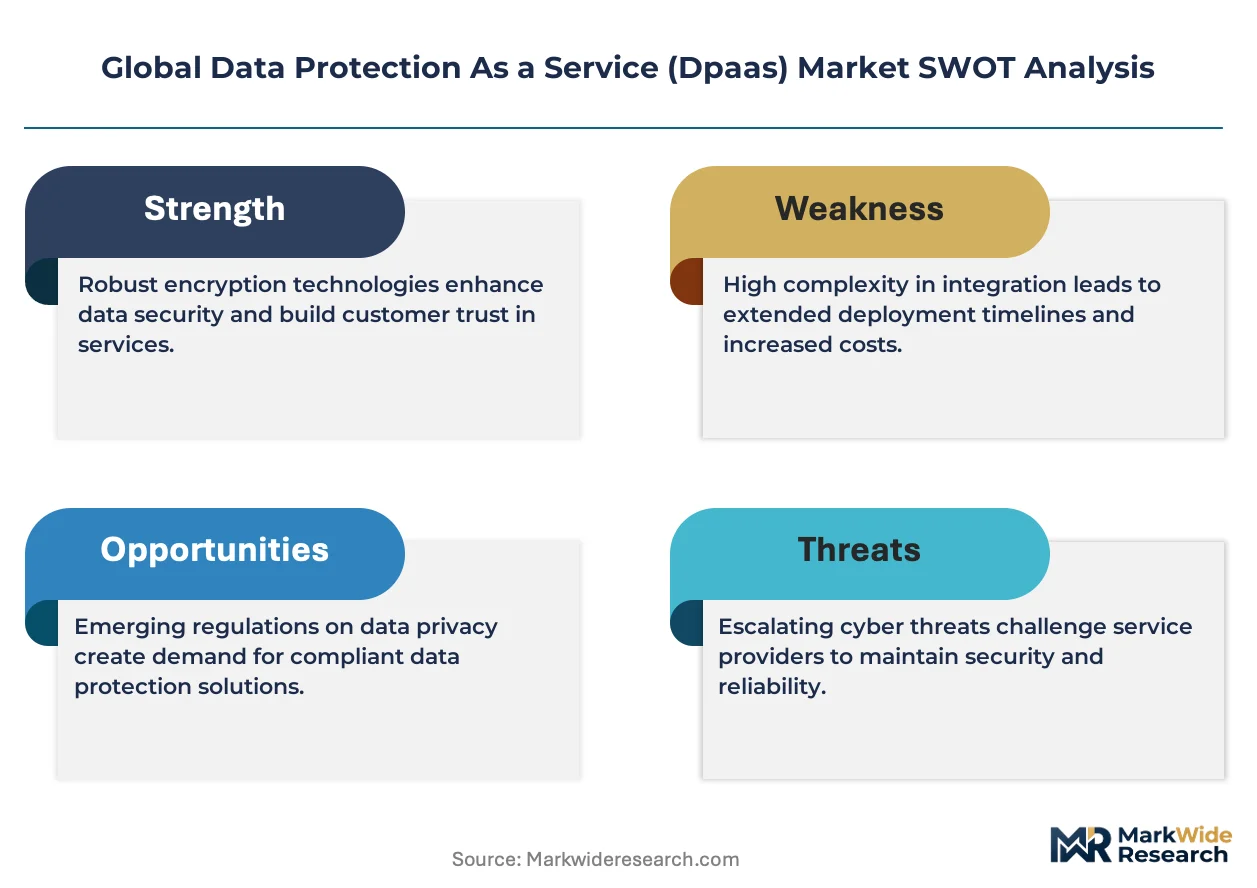
- Quantum-resistant cryptography:NIST post-quantum standards are forcing certificate lifecycle rearchitecture. DPaaS vendors integrating crypto-agility capture early-mover positioning.
Market Restraints
- Multi-tenant key escrow concentration:Cryptographic key management in shared infrastructure creates systemic failure risk. German BSI guidelines explicitly warn against single-vendor key custody.
- Cross-border data localization mandates:Russia, China, and Indonesia require in-country backup retention. This fragments vendor economics and prevents true global service consolidation.
- Legacy mainframe dependency:Financial services retain critical workloads on IBM zSystems. Cloud-native DPaaS lacks native mainframe integration, forcing hybrid complexity.
Strategic Opportunities
- India's data center expansion:MeitY data localization requirements and PLI scheme subsidies are creating captive demand. Mumbai and Hyderabad clusters lack mature DPaaS penetration.
- AI training data protection:Large language model datasets require versioned immutability. This emerging workload class has no established backup paradigm.
- EU AI Act audit trails:High-risk AI systems must maintain training data provenance. DPaaS vendors offering lineage-coupled backup capture regulatory tailwind.
Industry Challenges
- Immutable storage skill scarcity:Object-lock configuration and air-gap orchestration require specialized SRE expertise. Financial services report 18-month hiring cycles for qualified architects.
- SaaS-to-SaaS backup integration:Microsoft 365 and Salesforce native APIs change quarterly. Vendor engineering teams struggle to maintain connector stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Protection As a Service (Dpaas) Market |
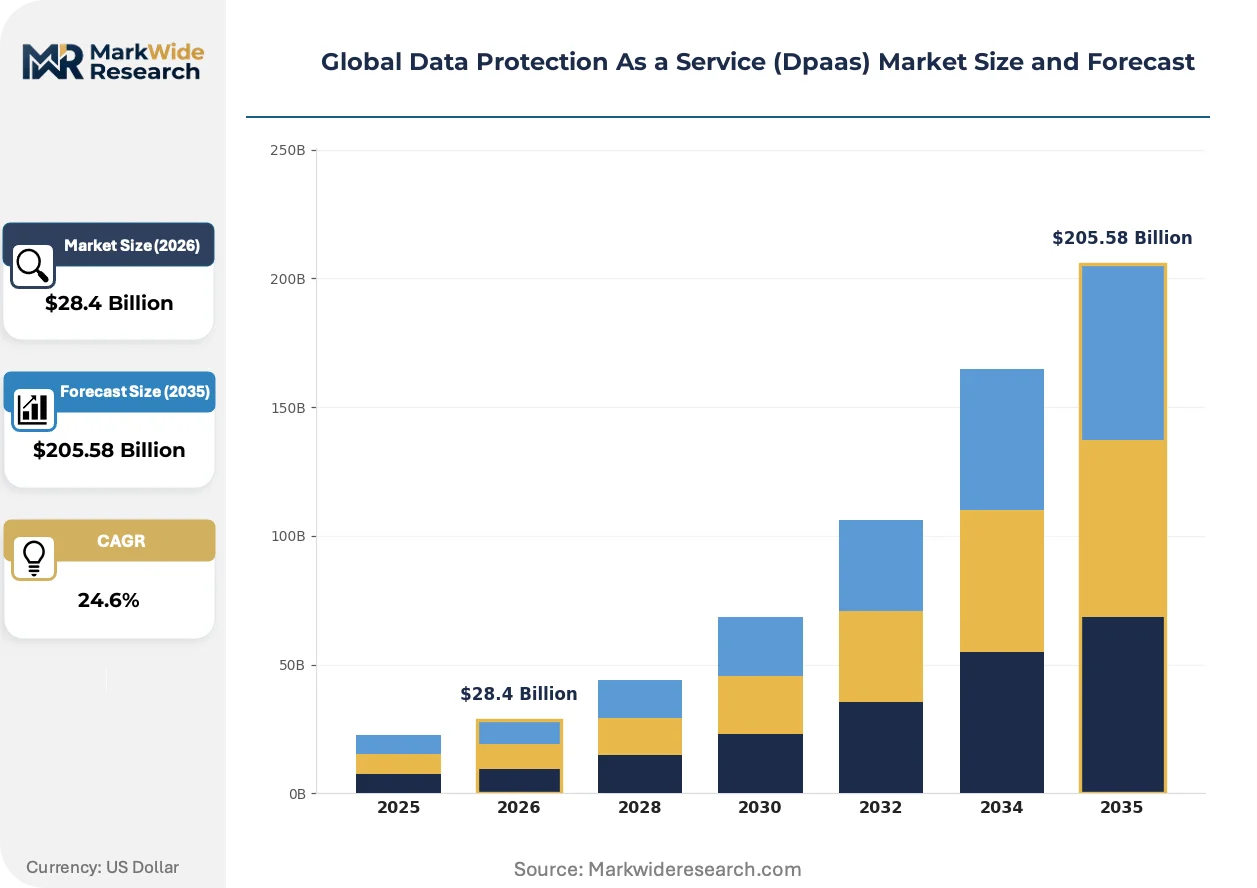
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $205.58 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Offering: Backup and Recovery, Disaster Recovery, Archiving, Continuous Data Protection Application: Enterprise Data Backup, Compliance Management, Business Continuity, Data Migration End User Industry: Banking & Financial Services, IT & Telecom, Manufacturing, Government, Education |
| Companies Covered | Amazon Web Services, IBM Corporation, Microsoft, Hewlett Packard Enterprise, Oracle Corporation, Dell Technologies, Veritas Technologies, Commvault, Veeam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Protection As a Service (Dpaas) Market Shifts & Advancements
Continuous data protection architectures are collapsing recovery point objectives from hours to minutes. This compression is restructuring vendor competitive advantage around orchestration speed rather than storage density.
Immutable object storage with native ransomware detection is automating threat response workflows. Healthcare providers in the United States are deploying these systems ahead of HIPAA Security Rule updates. The technology is automating isolation decisions that previously required human security operations center intervention.
EU GDPR Article 32 enforcement through CNIL and other national DPAs is mandating demonstrable recovery testing. French and German regulators now request annual backup restoration attestations. Financial services institutions maintain dedicated compliance engineering teams to satisfy documentation requirements.
Consumption-based pricing models are displacing perpetual license structures in enterprise procurement. German automotive manufacturers now negotiate backup capacity as operational expenditure. This shift is most visible in DACH region manufacturing, where CFOs prioritize cash flow preservation over capital efficiency metrics.
Global Data Protection As a Service (Dpaas) Market Segmentation
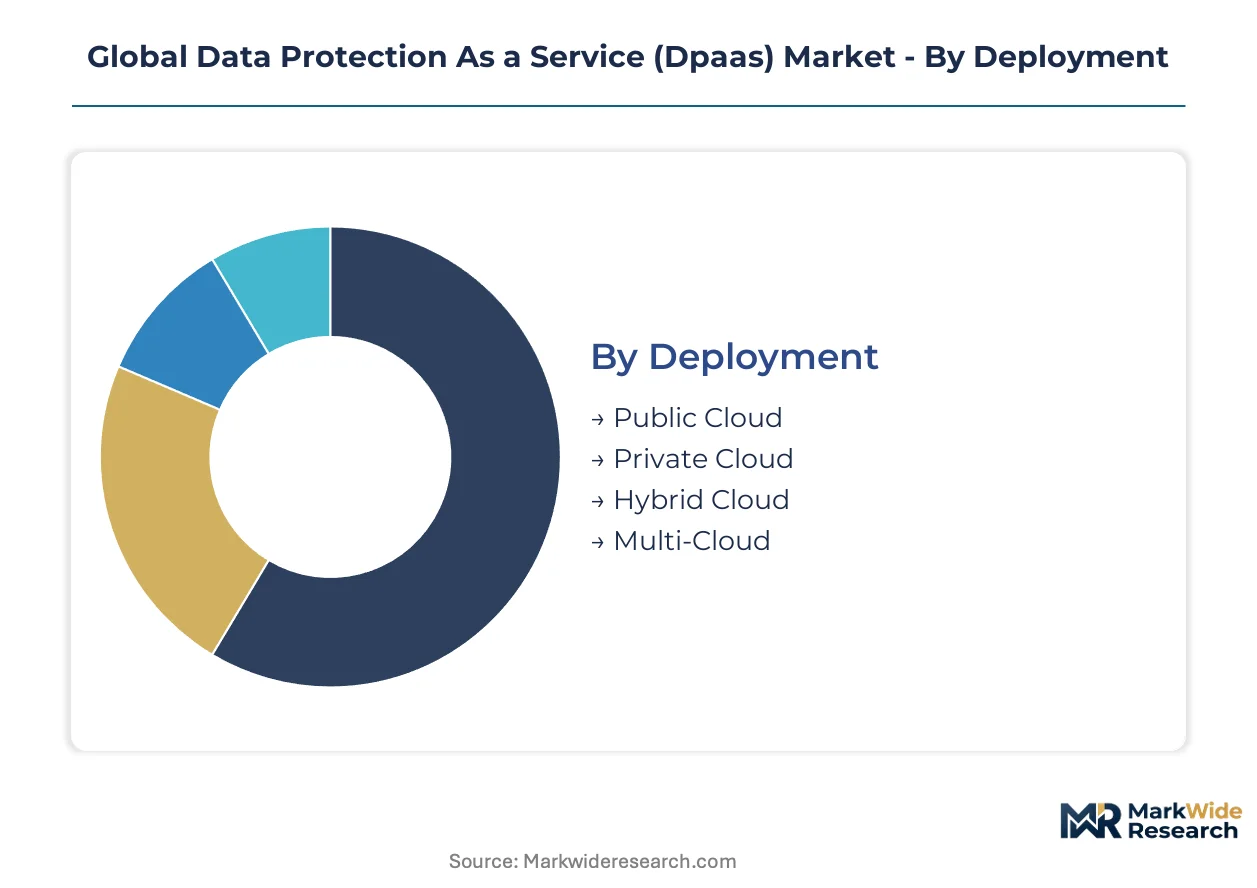
DPaaS procurement decisions hinge on recovery point objectives, regulatory jurisdiction, and data gravity constraints. Segmentation reveals where vendor specialization creates pricing power versus commodity competition.
Deployment:
GDPR Article 32, SEC cybersecurity disclosure rules, and India's MeitY localization mandates each favor distinct deployment architectures. Certification burden varies sharply across these models.
- Hybrid Cloud:Combines on-premises immutable storage with public cloud archive tiers. Financial services in the United States and Germany concentrate procurement here to satisfy SEC four-day incident reporting and BSI key escrow guidance simultaneously.
- Multi-Cloud:Orchestrates replication across AWS, Azure, and GCP control planes. Pharmaceutical manufacturers deploying FDA 21 CFR Part 11-compliant systems favor this model for vendor-agnostic defensibility.
- Public Cloud:Native SaaS backup with consumption-based metering.
- Private Cloud:Dedicated infrastructure for air-gapped retention requirements.
Hybrid Cloud sits at the top of the volume ranking, with Multi-Cloud climbing the fastest.
Solution Offering:
Margin structure stratifies by recovery speed guarantees and automation depth. Continuous data protection commands premium pricing against traditional backup.
- Continuous Data Protection:Journal-based replication with sub-15-minute recovery point objectives. Ransomware recovery compression from days to minutes drives healthcare and banking procurement in France and the United States.
- Backup and Recovery:Scheduled snapshot orchestration with policy-driven retention from 15 minutes to seven years. Manufacturing CFOs in Germany's DACH region negotiate this as operational expenditure.
- Disaster Recovery:Automated failover with runbook orchestration.
- Archiving:Cold tier storage with legal hold and e-discovery integration.
Backup and Recovery maintains the largest installed base, though Continuous Data Protection is gaining share fastest.
Application:
End-use sophistication determines whether procurement emphasizes feature depth or audit-ready compliance attestation.
- Compliance Management:Immutable retention with demonstrable recovery testing for CNIL, BSI, and SEC examinations. French and German regulators now request annual restoration attestations.
- Business Continuity:Orchestrated failover for revenue-critical workloads. Indian IT services exporters in Hyderabad and Mumbai deploy this for client SLA preservation.
- Enterprise Data Backup:General-purpose protection for unstructured data estates.
- Data Migration:Versioned consistency during cloud repatriation or consolidation.
Enterprise Data Backup leads by volume, while Compliance Management shows the steepest expansion trajectory.
End User Industry:
Industry-specific regulatory density shapes vendor selection criteria and contract duration.
- Banking & Financial Services:Sub-15-minute RPO requirements with quantum-resistant cryptography roadmaps. NIST post-quantum standards are forcing certificate lifecycle rearchitecture in this segment.
- IT & Telecom:SaaS-to-SaaS backup for Microsoft 365 and Salesforce with quarterly API stability challenges.
- Manufacturing:German automotive producers prioritize cash flow preservation through consumption pricing.
- Government:FedRAMP and country-specific sovereign cloud mandates.
- Education:Cost-optimized retention for research data and student records.
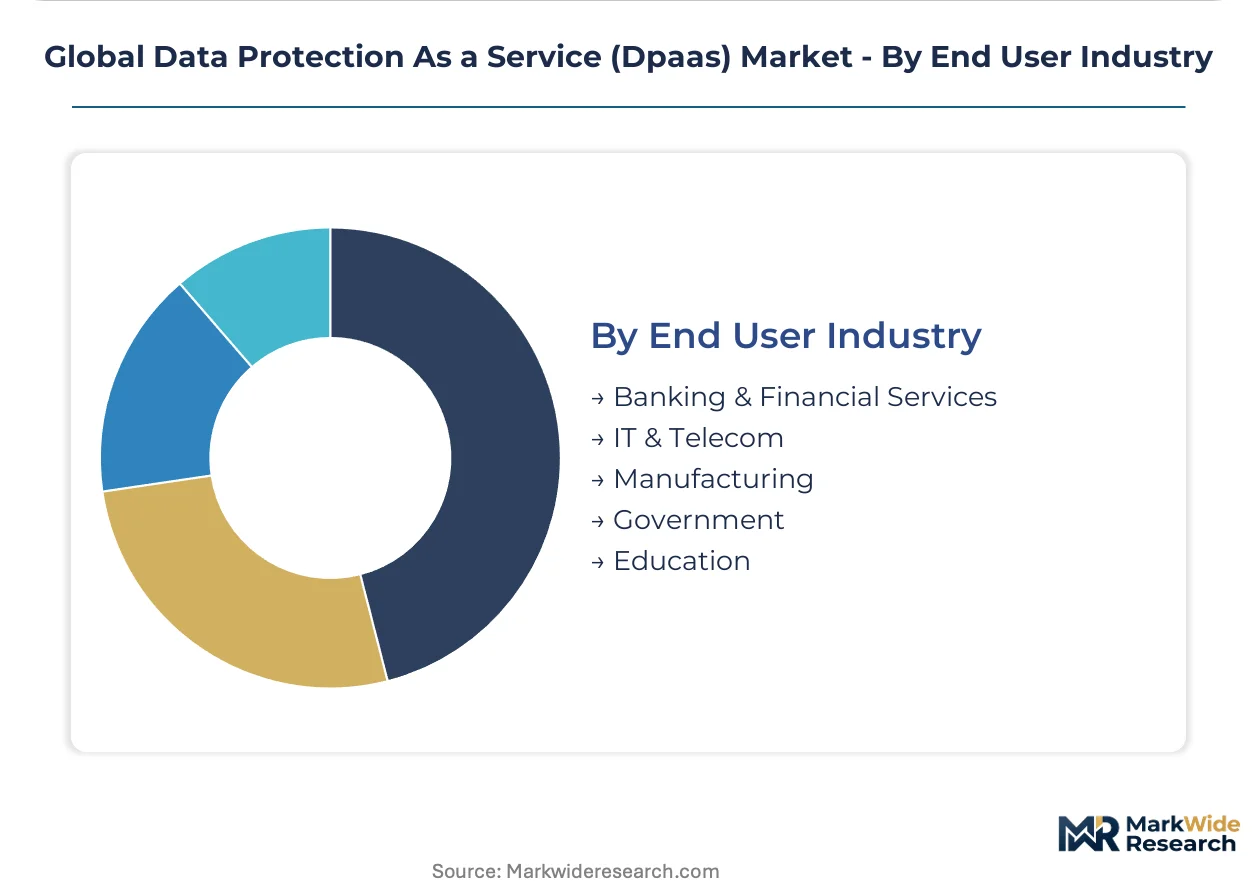
Banking & Financial Services dominates revenue concentration, with IT & Telecom expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States financial institutions deploy sub-15-minute recovery point objectives under SEC pressure, while German manufacturers negotiate consumption-based backup contracts to preserve cash flow. India's data center clusters in Mumbai and Hyderabad remain underpenetrated despite MeitY localization mandates driving captive demand.
United States
Banking and healthcare sectors dominate procurement as ransomware recovery timelines compress from days to minutes. SEC cybersecurity disclosure rules mandate four-day incident reporting, forcing institutions to maintain dedicated compliance engineering teams. The New York financial district and Northern Virginia data center corridor concentrate hybrid cloud deployment for immutable backup architectures.
Germany
Automotive manufacturers in the DACH region prioritize operational expenditure models over capital efficiency metrics. BSI guidelines explicitly warn against single-vendor cryptographic key custody, reshaping procurement evaluation criteria. Bavaria and Baden-Württemberg host the densest concentration of quantum-resistant cryptography roadmaps among European industrial enterprises.
India
IT services exporters in Hyderabad and Mumbai deploy business continuity orchestration to preserve client SLAs. MeitY data localization requirements and PLI scheme subsidies create structural demand for domestic DPaaS infrastructure. The country's data center expansion in Mumbai and Hyderabad clusters lacks mature vendor penetration despite regulatory tailwinds.
France
CNIL enforcement of GDPR Article 32 now requests annual backup restoration attestations from financial services institutions. Pharmaceutical manufacturers deploy FDA 21 CFR Part 11-compliant systems with vendor-agnostic multi-cloud replication. The Île-de-France region concentrates healthcare provider adoption of immutable object storage with native ransomware detection.
United Kingdom
Financial services institutions maintain sub-15-minute RPO requirements while navigating post-quantum certificate lifecycle rearchitecture. The country's national data protection regulator enforces demonstrable recovery testing standards comparable to continental counterparts. London's financial district anchors hybrid cloud procurement combining on-premises immutable storage with public cloud archive tiers.
Global Data Protection As a Service (Dpaas) Market Competitive Landscape
Top-tier vendors anchor high-assurance workload segments, while mid-tier specialists compete on cross-cloud portability and consumption-based pricing flexibility. The market structure consolidates around three strategic archetypes: mainframe-heritage incumbents, hyperscale-native integrators, and cross-platform portability specialists. Dominant competitive moves include strategic partnerships for quantum-resistant cryptography integration and geographic expansion into underpenetrated data center clusters.
Among hyperscale-native providers, Amazon Web Services and Microsoft exemplify the cloud-integrated archetype through native control plane embedding. IBM Corporation represents the mainframe-heritage segment, leveraging high-assurance workload anchoring for financial services institutions. Commvault occupies a position within the cross-platform portability tier, specializing in heterogeneous environment orchestration.
| Leading Market Players |
|---|
| Amazon Web Services |
| IBM Corporation |
| Microsoft |
| Hewlett Packard Enterprise |
| Oracle Corporation |
| Dell Technologies |
| Veritas Technologies |
| Commvault |
| Veeam |
| Others |
Supply & Pricing Matrix
Cloud storage unit economics in hyperscale data centers cascade through DPaaS vendor cost structures, compressing price floors for continuous data protection while inflating premiums for air-gapped private cloud deployments. This commodity input dynamic stratifies end-user pricing across consumption-based, subscription-tiered, and perpetual license models.
Pricing Analysis
Capacity additions in India's Mumbai and Hyderabad data center clusters are reshaping price floors for Asia-Pacific DPaaS procurement. Three-tier pricing structure across premium, standard, and economy levels dominates enterprise contracts, with quantum-resistant cryptography integration and sub-15-minute RPO guarantees commanding top-tier positioning. Cost compression in standard-tier backup and recovery stems from hyperscale storage commoditization. German automotive manufacturers exhibit lowest price sensitivity due to operational expenditure prioritization, while education sector buyers in India drive economy-tier volume.
Supply Chain Analysis
MeitY data localization requirements and PLI scheme subsidies are reshaping vendor sourcing patterns toward Indian domestic infrastructure development. Supply concentration rests on United States, Germany, and India for hybrid cloud control plane development, with cryptographic hardware security modules drawing from Taiwan and South Korea manufacturing bases. Single-source vulnerability in quantum-resistant algorithm implementations poses structural risk as NIST standards finalize. Distribution runs through direct enterprise sales teams for financial services, supplemented by hyperscale marketplace integrations for mid-market consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between India's underpenetrated data center clusters and Germany's compliance-intensive manufacturing base, where localization mandates in Mumbai create cost advantages absent in BSI-regulated Bavaria procurement.
For Market Incumbents: Cement high-assurance workload anchoring through quantum-resistant cryptography roadmaps ahead of NIST standard finalization. Deepen backward integration into immutable object storage hardware to offset hyperscale commoditization pressure. Defend against cross-platform portability specialists by locking financial services institutions into mainframe-native control plane architectures. For New Entrants and Emerging Players: Enter via India's MeitY-compliant data center corridors in Hyderabad and Mumbai, where PLI subsidies reduce infrastructure capex burdens. Target pharmaceutical manufacturers seeking FDA 21 CFR Part 11-compliant multi-cloud replication with vendor-agnostic positioning. Pursue consumption-based pricing flexibility as the primary go-to-market wedge against perpetual-license incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with cross-platform portability specialists possessing heterogeneous environment orchestration capabilities. Five-to-ten-year viability hinges on crypto-agility engineering depth rather than storage density scale. Monitor SEC cybersecurity disclosure enforcement intensity as the signal for DPaaS procurement acceleration in United States financial services.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Resistant Cryptography Integration | NIST post-quantum standards force certificate lifecycle rearchitecture in banking procurement. |
| Geographic Expansion into Indian Data Centers | MeitY localization mandates and PLI subsidies create structural demand in Mumbai and Hyderabad. |
| Immutable Object Storage Hardware Development | Air-gapped retention requirements in healthcare drive specialized SRE skill acquisition. |
| AI Training Data Provenance Coupling | EU AI Act audit trail mandates position lineage-integrated backup for high-risk system compliance. |
| Consumption-Based Pricing Model Migration | German automotive CFOs prioritize cash flow preservation over capital efficiency metrics. |
Research Methodology
Multiple input streams — chief technology officers at financial services institutions, data protection officers in pharmaceutical manufacturing, hyperscale cloud procurement leads, compliance engineering directors, and channel integration specialists — were reconciled against SEC regulatory filings, FDA 21 CFR Part 11 guidance documents, MeitY localization circulars, and BSI technical guidelines. Bottom-up sizing of vendor-reported deployment metrics combined with top-down triangulation against enterprise IT spending surveys produced volume and value estimates.
Historical growth trajectories in ransomware recovery timeline compression were cross-referenced against panel input from DPaaS vendor product management teams. Segmentation modeling spanned deployment architecture, solution offering recovery speed tiers, application sophistication levels, and end-user industry regulatory density. CAGRs were derived from regression analysis of subscription revenue expansion rates, with quantum cryptography readiness timelines and data localization mandate phase-in schedules as industry-specific forecast inputs.
The model holds under stable regulatory enforcement intensity; deviation in SEC disclosure rule expansion or EU AI Act audit scope would shift procurement priority weightings. Forecasts reflect documented assumptions regarding hybrid cloud adoption curves and immutable storage skill availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Secure Digital Card Market
Security Software
Cloud File Security Software Market
Security Software
Global Secure Access Service Edge Market
Security Software
Identity Verification Software Market
Security Software
United States Consumer Identity and Access Management Market
Security Software
US Hardware OTP Token Authentication Market
Security Software
Privileged Access Management (PAM) Market
Security Software
Global Digital Signature Software Market
Security Software
Passwordless Authentication Market
Security Software
Global Background Check Software Market
Security Software
US Hardware Encryption Market
Security Software
Security Information and Event Management Software Market
Security Software
Device-Embedded Biometric Authentication Market
Security Software
Global Optical Encryption Market
Security Software
Data Leakage Prevention Product Market
Security Software
Asia-Pacific Encryption Software Market