
 Nuclear Imaging Devices Market | 2026-2036
Nuclear Imaging Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Imaging Devices Market Outlook
The capital-intensity divergence between cyclotron-equipped and non-cyclotron players is unwinding competitive hierarchies in nuclear imaging. Siemens Healthineers leverages its vertically integrated radiopharmaceutical network to dominate premium hybrid system installations. GE HealthCare sustains R&D intensity across digital PET detector architectures, while United Imaging Healthcare competes aggressively on cost-optimized SPECT platforms in emerging markets.
Nuclear imaging devices generate tomographic or planar images by detecting gamma rays emitted from radiopharmaceuticals administered to patients, with PET systems achieving spatial resolution below 4 millimeters through lutetium-based scintillator crystals. These instruments enable functional visualization of metabolic processes for diagnostic and treatment-monitoring purposes across oncology, cardiology, and neurology. Hybrid systems combining PET with CT or MRI lead installed base expansion due to superior anatomical co-registration and higher reimbursement rates. Gamma cameras occupy a mature, price-sensitive segment where margin pools have compressed to service and refurbishment revenue. Diagnostic centers represent the fastest-growing end user category as outpatient imaging networks decentralize from hospital campuses.
FDA oversight of radiopharmaceutical INDs and NDA pathways shapes device demand by determining which tracers justify capital investment in corresponding imaging platforms. EMA's MDR requirements for software-driven reconstruction algorithms and the EU F-Gas Regulation restricting cooling agents in PET systems are elevating compliance costs for manufacturers. Stakeholders must monitor reimbursement decisions by CMS and parallel bodies in Germany and Japan, as these determine hospital capital allocation cycles independent of technological advancement.
Market Dynamics
Cyclotron infrastructure scarcity is compressing radiopharmaceutical availability, forcing device manufacturers to engineer platform flexibility that accommodates tracer supply volatility across hospital networks.
Growth Catalysts
- Oncology throughput expansion:Tertiary hospitals in the United States and Germany are expanding PET-CT suites to manage rising cancer screening volumes. Hybrid system installations accelerate where reimbursement frameworks cover molecular imaging procedures.
- FDA NDA pathway streamlining:Updated FDA guidance for radiopharmaceutical new drug applications is compressing device qualification timelines. Accelerated tracer approvals expand the addressable installed base for corresponding imaging platforms.
- Lutetium-based scintillator diffusion:Crystal manufacturing scale-up in China is reducing detector material costs. Domestic production of lutetium oxyorthosilicate is enabling cost-optimized PET system assembly for emerging market deployment.
Market Restraints
- Helium-3 and molybdenum-99 supply concentration:Production of critical isotopes concentrates in aging research reactors in the Netherlands, South Africa, and Australia. Geopolitical disruption or scheduled maintenance creates acute tracer shortages that idle installed gamma cameras.
- EU F-Gas Regulation compliance costs:Restrictions on hydrofluorocarbon cooling agents in PET systems elevate engineering expenditures for European market access. Manufacturers must redesign thermal management architectures or absorb certification penalties.
- Long replacement cycles:Hybrid PET-CT and PET-MRI systems operate on 10-12 year depreciation schedules. Capital equipment inertia limits refresh revenue even when detector technology advances substantially.
Strategic Opportunities
- Diagnostic center decentralization:Outpatient imaging networks in India and Brazil are fragmenting from hospital campuses. Freestanding PET-CT facilities bypass radiology department queue constraints and capture direct patient volumes.
- Digital PET detector convergence:Silicon photomultiplier arrays are replacing photomultiplier tubes, enabling magnetic field compatibility for PET-MRI integration. Dual-modality platforms command premium reimbursement in neurology and pediatric oncology.
- Japan's dementia screening mandate:METI-directed national amyloid imaging programs are institutionalizing PET biomarker protocols. Amyloid tracer availability is driving dedicated system procurement in geriatric care networks.
Industry Challenges
- Qualified medical physicist scarcity:Dosimetry calculation and radiopharmaceutical handling certification requirements exceed training pipeline output. Hospital imaging departments compete for specialists capable of hybrid system optimization.
- Legacy PACS integration friction:New reconstruction algorithms and quantitative imaging outputs require middleware adaptation. Vendor-neutral archive compatibility gaps delay clinical workflow deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Imaging Devices Market |
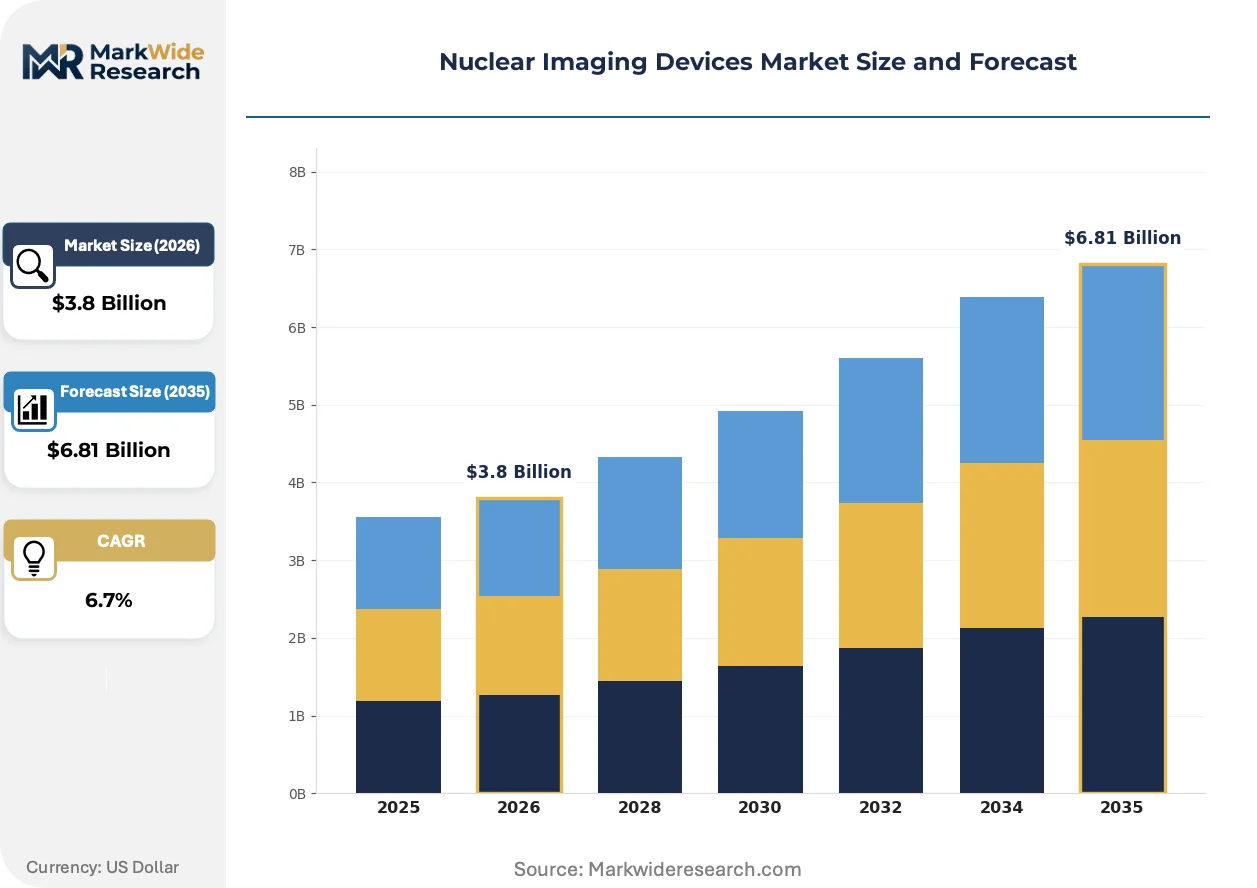
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Photon Emission Computed Tomography, Positron Emission Tomography, Hybrid Systems, Gamma Cameras End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Clinics Technology: Computed Tomography, Magnetic Resonance Imaging, Digital Radiography, Optical Imaging Application: Cardiology, Oncology, Neurology, Thyroid Imaging |
| Companies Covered | Canon Medical Systems Corporation, Shimadzu Corporation, GE HealthCare, Bracco Imaging, United Imaging Healthcare, Siemens Healthineers, Mediso, Neusoft Medical Systems, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Imaging Devices Market Strategic Shifts
Detector architecture evolution and software-defined reconstruction are dismantling the hardware-software bundling that historically protected incumbent margins in nuclear imaging.
Digital PET detector technology is bifurcating the installed base between premium silicon photomultiplier systems and legacy photomultiplier tube platforms. Academic medical centers in Germany and the United States are prioritizing time-of-flight resolution below 300 picoseconds for research applications. The performance gap is compressing resale values for analog detector inventories and accelerating obsolescence cycles in secondary markets.
EMA's Medical Device Regulation is elevating software validation requirements for iterative reconstruction algorithms deployed in European clinical settings. Manufacturers must submit clinical evidence packages demonstrating diagnostic equivalence to filtered back-projection baselines. PET system vendors with pre-MDR algorithm libraries face retrospective compliance costs that favor newer market entrants with clean-sheet software architectures.
Subscription-based tracer supply contracts are displacing per-dose purchasing in United States hospital networks. Radiology departments lock in fluorodeoxyglucose and prostate-specific membrane antigen agent availability through multi-year commitments that bundle cyclotron access with device service agreements. This procurement consolidation concentrates purchasing authority within integrated delivery networks and marginalizes independent diagnostic centers lacking contract scale.
Nuclear Imaging Devices Market Segmentation
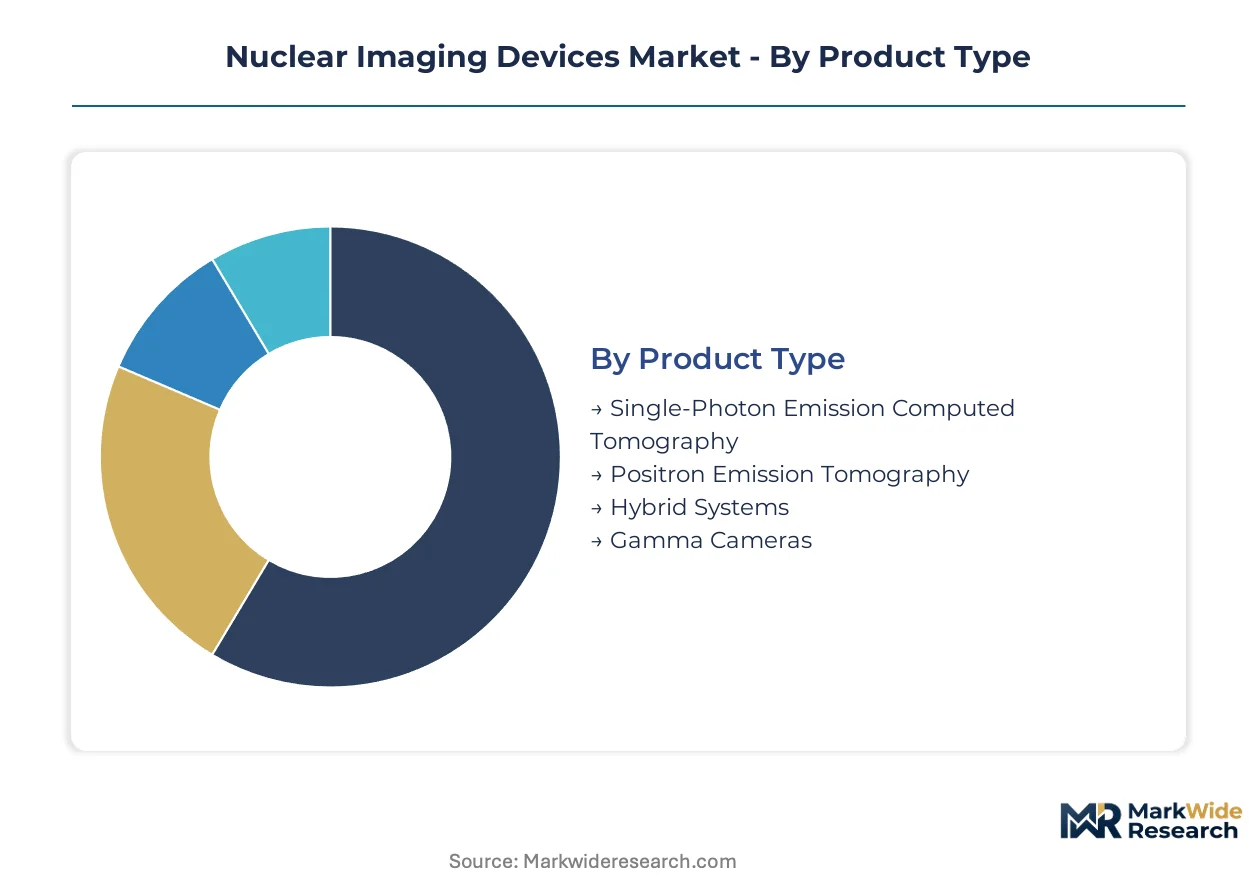
Nuclear imaging device procurement patterns diverge sharply across clinical settings and technological platforms. Understanding segment substitution dynamics reveals which categories face displacement pressure from alternative diagnostic modalities.
Product Type:
Hybrid systems exert acute substitution pressure on standalone SPECT and PET platforms through superior anatomical co-registration capabilities.
- Single-Photon Emission Computed Tomography:Detects gamma-emitting radiopharmaceuticals using sodium iodide crystal arrays and Anger camera geometry. Demand concentrates in cardiology departments across Germany and Japan where myocardial perfusion imaging protocols remain entrenched despite PET tracer advances.
- Positron Emission Tomography:Achieves sub-4mm spatial resolution through lutetium-based scintillator detection of positron annihilation events. United States oncology networks drive installation growth where FDG reimbursement codes support capital recovery timelines.
- Hybrid Systems:PET-CT and PET-MRI configurations dominate tertiary hospital procurement through fused functional-anatomical outputs. Premium pricing reflects dual-modality reimbursement eligibility.
- Gamma Cameras:Planar scintigraphy platforms occupy mature replacement cycles in thyroid and bone imaging. Margin compression limits manufacturer R&D commitment to detector upgrades.
Gamma cameras retain volume leadership across installed base; hybrid systems hold the steepest expansion curve.
End User:
Capital allocation authority determines segment hierarchy, with integrated delivery networks consolidating purchasing power away from standalone facilities.
- Hospitals:Tertiary academic centers command PET-CT and PET-MRI procurement through cyclotron infrastructure access and fellowship-trained nuclear medicine staffing. CMS reimbursement frameworks shape capital cycle timing.
- Diagnostic Centers:Freestanding outpatient imaging networks in India and Brazil fragment from hospital campuses to capture direct patient volumes. Queue bypass advantages accelerate PET-CT deployment outside radiology department constraints.
- Research Institutions:Preclinical micro-PET and micro-SPECT systems support tracer development and theranostic pipeline validation. Grant funding volatility constrains equipment refresh frequency.
- Outpatient Clinics:Limited to gamma camera and portable SPECT platforms where procedure volume justifies neither hybrid system capital nor radiopharmaceutical logistics investment.
Hospitals dominate absolute equipment value; diagnostic centers are climbing the fastest.
Technology:
Digital detector convergence is collapsing historical modality boundaries in hybrid system architecture.
- Computed Tomography:X-ray attenuation mapping provides anatomical localization for PET functional data. Low-dose CT protocols in lung cancer screening programs sustain detector tube replacement demand.
- Magnetic Resonance Imaging:PET-MRI integration requires silicon photomultiplier arrays for magnetic field compatibility. Pediatric oncology and neurology applications command premium reimbursement through superior soft tissue contrast.
- Digital Radiography:Flat-panel detector advances in interventional suites create workflow overlap with nuclear medicine hybrid rooms. Cost per study economics favor DR for skeletal assessment over bone scintigraphy.
- Optical Imaging:Near-infrared fluorescence and bioluminescence platforms compete for preclinical molecular imaging budgets. Limited clinical translation constrains hospital adoption.
Computed tomography anchors hybrid system attach rates; magnetic resonance imaging delivers the highest value-per-procedure premium.
Application:
Tracer availability and reimbursement coding density determine which clinical domains justify dedicated system investment.
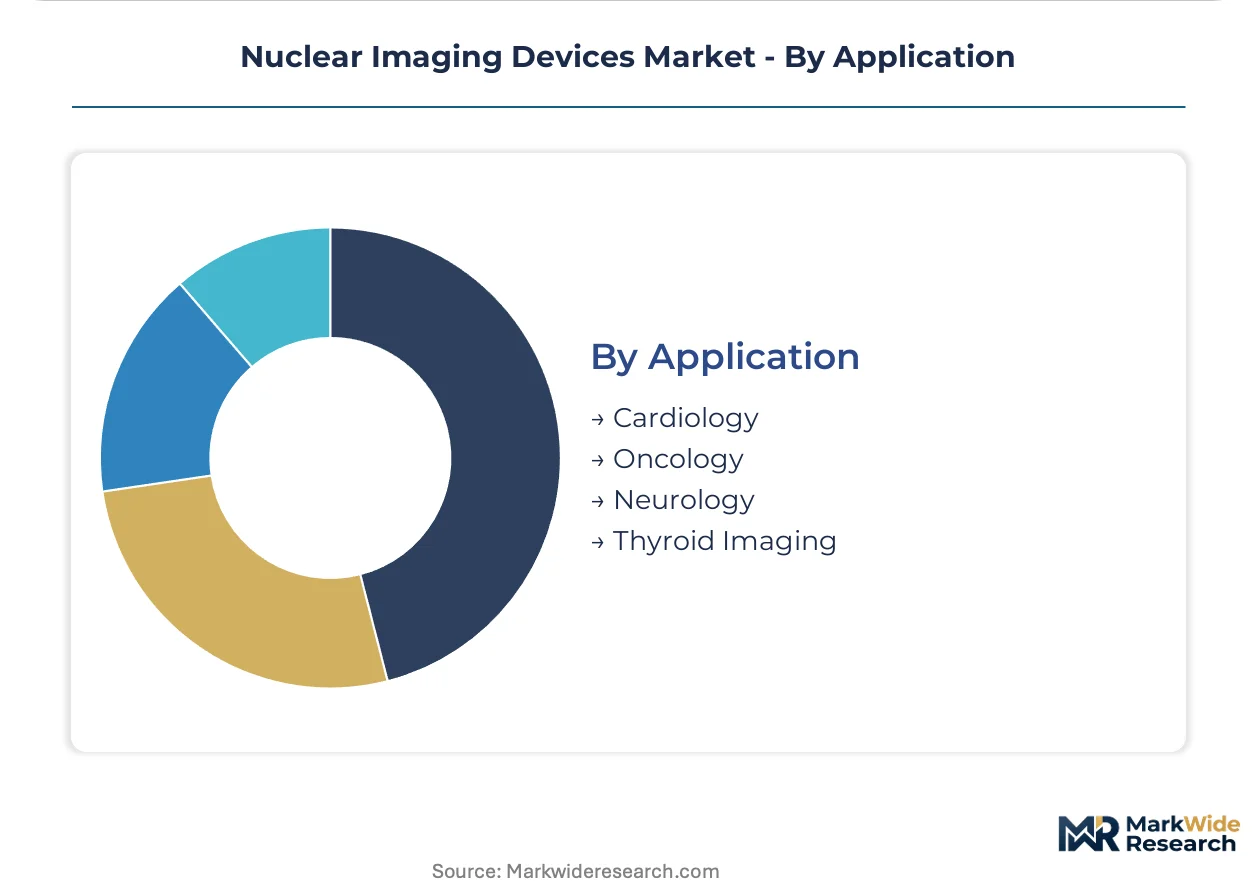
- Cardiology:Myocardial perfusion SPECT persists through established CAD assessment protocols despite PET rubidium-82 stress imaging advantages. United States cardiology group practices resist capital conversion due to depreciation schedule lock-in.
- Oncology:FDG-PET dominates staging and response assessment across solid tumor categories. PSMA tracer expansion for prostate cancer is driving dedicated prostate PET system procurement in tertiary networks.
- Neurology:Amyloid and tau PET biomarkers gain institutionalization through Japan's METI-directed dementia screening mandate. Geriatric care networks in Germany and the United States follow with system deployment.
- Thyroid Imaging:Iodine-131 whole-body scintigraphy and I-123 uptake studies remain gamma camera-dependent. Low procedure reimbursement limits technology upgrade incentives.
Cardiology maintains procedure volume leadership; oncology claims the steepest value expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States demonstrate low price elasticity where reimbursement frameworks guarantee capital recovery, while procurement in India and Brazil remains acutely cost-sensitive. This divergence shapes regional vendor strategies and product-mix priorities.
United States
Tertiary hospitals in Houston and Boston are expanding PET-CT suite capacity to manage rising prostate cancer screening volumes. CMS reimbursement codes for molecular imaging procedures determine capital allocation timing across integrated delivery networks. The Mayo Clinic Rochester campus anchors hybrid system standardization protocols that diffuse through academic medical center procurement committees.
Germany
University hospitals in Munich and Heidelberg prioritize time-of-flight PET-MRI platforms for neuro-oncology research applications. The EU F-Gas Regulation forces thermal management redesigns for European market access, elevating engineering expenditures. The Baden-Württemberg medical technology cluster concentrates detector crystal finishing operations serving domestic OEM assembly lines.
China
Provincial hospital networks in Shanghai and Guangzhou are replacing imported gamma cameras with cost-optimized domestic SPECT platforms. NMPA streamlined registration pathways for iterative reconstruction software reduce algorithm validation timelines. United Imaging Healthcare's Suzhou manufacturing base scales silicon photomultiplier array output for emerging market export.
Japan
Geriatric care networks in Osaka and Nagoya are deploying amyloid PET systems under METI-directed dementia screening mandates. PMDA accelerated tracer approval pathways expand the addressable installed base for corresponding imaging platforms. The Chubu region's scintillator crystal foundries supply lutetium oxyorthosilicate to domestic PET system integrators.
India
Freestanding diagnostic centers in Mumbai and Bengaluru fragment from hospital campuses to capture direct patient volumes bypassing radiology department queues. CDSCO import licensing requirements for radiopharmaceuticals create tracer supply bottlenecks that constrain device utilization rates. The Karnataka medical device corridor assembles refurbished gamma cameras for tier-2 city deployment.
Nuclear Imaging Devices Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes in nuclear imaging devices. Vertically integrated radiopharmaceutical networks dominate premium hybrid system installations, while modular component suppliers capture price-sensitive replacement markets. Two strategic archetypes define competitive positioning: cyclotron-equipped full-stack providers and detector-focused hardware specialists. M&A activity concentrates tracer supply networks, while strategic partnerships bridge software reconstruction algorithm gaps.
Among diversified health technology conglomerates, Siemens Healthineers and GE HealthCare exemplify the integrated archetype through captive radiopharmaceutical production and hybrid system portfolios. United Imaging Healthcare occupies a position within the cost-optimized platform tier, leveraging domestic manufacturing scale for emerging market penetration. These three anchors illustrate the divergence between premium reimbursement-dependent and volume-driven procurement channels.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Shimadzu Corporation |
| GE HealthCare |
| Bracco Imaging |
| United Imaging Healthcare |
| Siemens Healthineers |
| Mediso |
| Neusoft Medical Systems |
| Koninklijke Philips N.V. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day lutetium oxyorthosilicate crystal lead times from Chinese foundries compress manufacturer inventory buffers while amplifying pricing power for domestic PET detector integrators serving cost-optimized emerging market deployments.
Pricing Analysis
Service contract renewals and cyclotron access subscriptions generate lifetime value exceeding initial hardware margins by substantial multiples. Pricing stratifies across premium, standard, and economy tiers based on detector time-of-flight resolution specifications and bundled radiopharmaceutical supply guarantees. Cost compression in gamma camera refurbishment tiers is intensifying because Indian and Brazilian diagnostic centers prioritize capital efficiency over detector sensitivity specifications. Independent imaging networks exhibit acute price sensitivity; tertiary academic centers with captive cyclotron infrastructure demonstrate minimal elasticity where FDG reimbursement codes support capital recovery.
Supply Chain Analysis
Strategic stockpiling of molybdenum-99 and helium-3 isotopes dominates procurement behavior among United States and German hospital networks confronting aging research reactor maintenance schedules. Lutetium crystal finishing concentrates in China and Japan; silicon photomultiplier array fabrication rests on South Korean and Taiwanese semiconductor foundries. Single-source vulnerability in Netherlands and South African research reactor output creates acute tracer shortage risks that idle installed gamma camera fleets. Distribution runs through integrated delivery network procurement committees that consolidate purchasing authority away from standalone diagnostic facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital PET detector convergence is disrupting established hardware-software bundling patterns, with silicon photomultiplier arrays displacing photomultiplier tubes and FDA streamlining of radiopharmaceutical NDA pathways accelerating platform qualification timelines.
For Market Incumbents: Secure cyclotron infrastructure access through multi-year radiopharmaceutical supply contracts that bundle tracer availability with device service agreements, insulating installed base positions from emerging market cost-optimized competitors. Deepen backward integration into lutetium crystal manufacturing to capture detector material cost advantages as Chinese domestic production scales. For New Entrants and Emerging Players: Lead with portable SPECT platforms and refurbished gamma camera assemblies targeting tier-2 Indian cities and Brazilian outpatient networks where radiology department queue bypass drives patient volume capture. White-space opportunity concentrates in amyloid PET system deployment for Japan's METI-directed dementia screening mandate and PSMA tracer-compatible prostate imaging suites in United States urology networks. For Investors and Strategic Acquirers: Long-term, this sits as a reimbursement-anchored infrastructure play because molecular imaging capital allocation cycles track CMS and parallel payer decisions rather than pure technology advancement. Target acquisition profiles emphasize cyclotron-equipped service networks with captive radiopharmaceutical production and established hospital GPO contracts. The signal to watch is CMS National Coverage Determination timing for novel amyloid and tau tracers.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Infrastructure Partnership | Captive tracer supply locks in hospital system loyalty and secures multi-year service contract renewals. |
| Silicon Photomultiplier Array Manufacturing Scale-Up | Domestic Chinese production reduces detector costs for emerging market PET system deployment. |
| FDA NDA Pathway Engagement | Accelerated radiopharmaceutical approvals expand addressable installed base for corresponding imaging platforms. |
| Diagnostic Center Network Fragmentation | Freestanding outpatient imaging in India and Brazil bypasses hospital radiology department queue constraints. |
| Reimbursement Strategy Investment | CMS and Germany's G-BA coverage decisions determine capital allocation timing across integrated delivery networks. |
Study Parameters
Desk research of FDA 510(k) filings, EMA MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement records preceded structured interviews with nuclear medicine department heads, biomedical equipment procurement managers, cyclotron facility operators, and GPO contracts specialists. Primary fieldwork across United States, German, and Chinese hospital networks combined with secondary validation from NMPA registration databases and Japan's PMDA submission records. Bottom-up installation base modeling and top-down expenditure flow analysis provided cross-verification.
Variance decomposition across product type, end user category, technology platform, and application segment drove analytical framework construction throughout the projection horizon. CAGRs derived from equipment shipment trajectories, replacement cycle analysis, and tracer approval pipeline assessment. Modeled inputs incorporated reimbursement code expansion timelines, EU F-Gas Regulation compliance cost pass-through, and digital detector adoption curves across academic and community hospital settings.
Forecasts assume regulatory continuity in FDA, EMA, and NMPA oversight regimes; material policy shifts affecting radiopharmaceutical approval pathways or medical device software validation requirements would necessitate re-modeling. Specific risk factors include research reactor maintenance disruptions affecting isotope supply, CMS coverage determination delays for novel tracers, and EMA MDR retrospective compliance costs for legacy algorithm libraries. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Stroke Post Processing Software Market
Medical Imaging
South Korea Magnetic Resonance Imaging Market
Medical Imaging
Medical Digital Imaging Devices Market
Medical Imaging
Fluoroscopy and Mobile C-Arms Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
PET Radiotracer Market
Medical Imaging
Brazil Diagnostic Imaging Equipment Market
Medical Imaging
Argentina Digital X-Ray Market
Medical Imaging
Surgical Imaging Robots Market
Medical Imaging
Spain Nuclear Imaging Market
Medical Imaging
Global Ultrasound Imaging Devices Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market
Medical Imaging
France Digital Radiology Market
Medical Imaging
Molecular Imaging Market
Medical Imaging
AI in Diagnostic Imaging Market
Medical Imaging
US Medical Imaging Market