
 Global Human Capital Management Software Market | 2026-2036
Global Human Capital Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
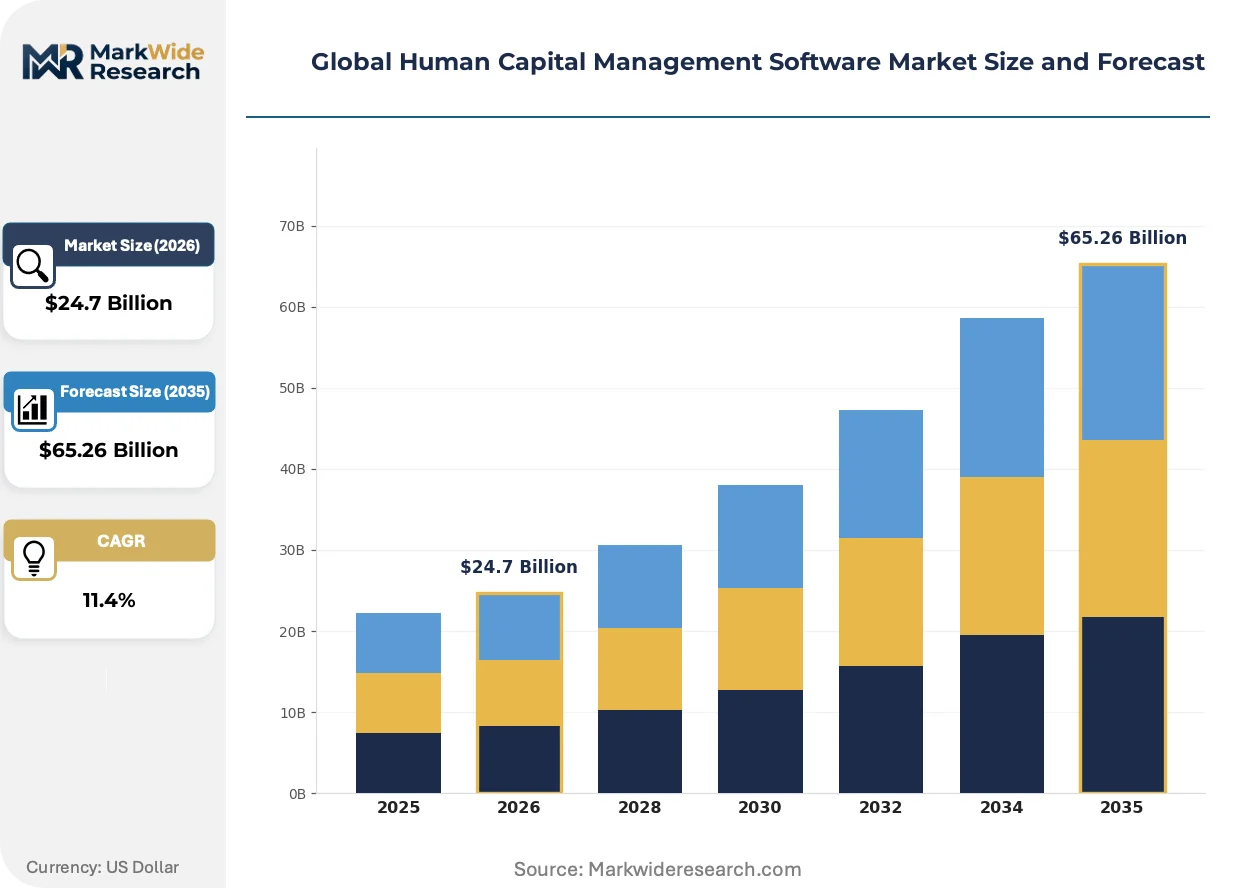
Global Human Capital Management Software Market Outlook
Multi-source vendor strategies is broadening as enterprises diversify beyond single-suite dependencies. SAP SE leverages deep ERP integration to anchor complex payroll and workforce planning deployments across European manufacturing clients. Oracle Corporation competes through database-layer connectivity that sustains high-volume transactional processing for large enterprise accounts. Workday, Inc. specializes in cloud-native architecture that dominates talent management and financial planning convergence.
Human capital management software constitutes an integrated technology stack that automates employee lifecycle processes through modular applications spanning recruitment, compensation, benefits administration, and workforce analytics, typically deployed via cloud infrastructure with API-based interoperability standards. Core HR and payroll functions represent mature revenue pools with stable renewal rates, while talent management and workforce management segments attract faster growth as organizations prioritize retention analytics and shift-based scheduling optimization. Cloud-based deployment leads absolute spending as SMEs accelerate SaaS adoption, though hybrid configurations persist in regulated industries requiring localized data residency controls.
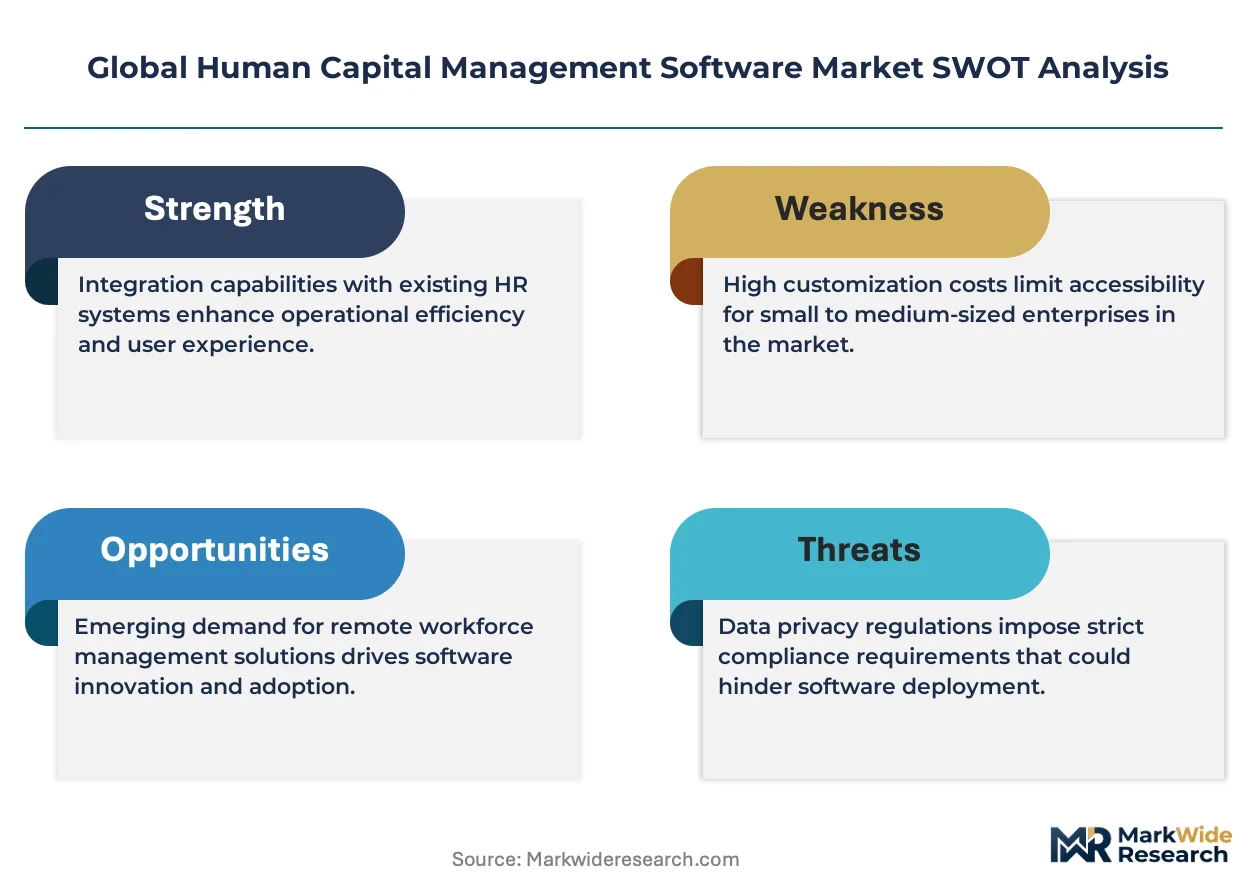
FDA oversight of clinical trial workforce tracking, GDPR data localization requirements across European member states, and HIPAA privacy safeguards for healthcare sector HR data collectively elevate compliance module spending within platform procurement decisions. ISO 30414 human capital reporting standards and SEC climate disclosure rules are extending reporting obligations into workforce metrics, forcing software vendors to embed standardized disclosure templates. Stakeholders must evaluate whether emerging AI hiring tools will trigger new algorithmic accountability frameworks before committing to long-term platform roadmaps.
Market Dynamics
Cloud-native architectures are displacing on-premise legacy stacks across healthcare, manufacturing, and public sector organizations, with compliance mandates under HIPAA and GDPR functioning as the primary accelerant for platform replacement cycles.
Growth Catalysts
- GDPR Data Localization Mandates:European healthcare and financial services organizations must maintain workforce data within member-state boundaries, driving demand for region-hosted cloud HCM deployments with embedded residency controls.
- Shift-Based Scheduling Optimization:Healthcare systems and retail logistics operators require AI-enabled workforce management modules to reduce overtime expenditure and improve coverage ratios across distributed facilities.
- API-First Interoperability Standards:The HL7 FHIR framework and emerging ISO 30414 human capital reporting specifications force platform vendors to expose standardized data interfaces, reducing switching costs for enterprise buyers.
Market Restraints
- Data Sovereignty Fragmentation:Conflicting localization requirements across Germany, France, and emerging EU member states force vendors to maintain redundant infrastructure footprints, elevating operational complexity.
- Legacy System Entrenchment:Large manufacturing and public sector employers in the United States carry decades-old customized payroll engines with embedded business logic that resists cloud migration without expensive reconfiguration.
- Skills Concentration Bottlenecks:Implementation partners with certified expertise in SAP SuccessFactors, Oracle HCM Cloud, and Workday Financial Management are concentrated in London, Frankfurt, and New York, creating deployment queue delays.
Strategic Opportunities
- India SME Digitization Wave:The country's Production-Linked Incentive scheme and expanding services export sector are pushing mid-market employers toward SaaS-based payroll and compliance automation.
- Embedded Climate Disclosure Workflows:The SEC's climate disclosure rules and EU CSRD are extending reporting obligations into workforce metrics, creating module demand for standardized ESG-HR data templates.
- Convergence of HCM and Financial Planning:Unified platforms integrating talent cost modeling with enterprise resource planning are overtaking siloed point solutions in technology and professional services verticals.
Industry Challenges
- Algorithmic Accountability Uncertainty:Emerging AI hiring tools face regulatory scrutiny under the EU AI Act and proposed US federal frameworks, creating compliance timeline risk for vendors embedding predictive analytics.
- Integration Complexity with Heterogeneous Stacks:Enterprises operating mixed environments of SAP ERP, Salesforce CRM, and custom-built operational systems require expensive middleware development to achieve unified workforce data visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Human Capital Management Software Market |
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $65.26 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
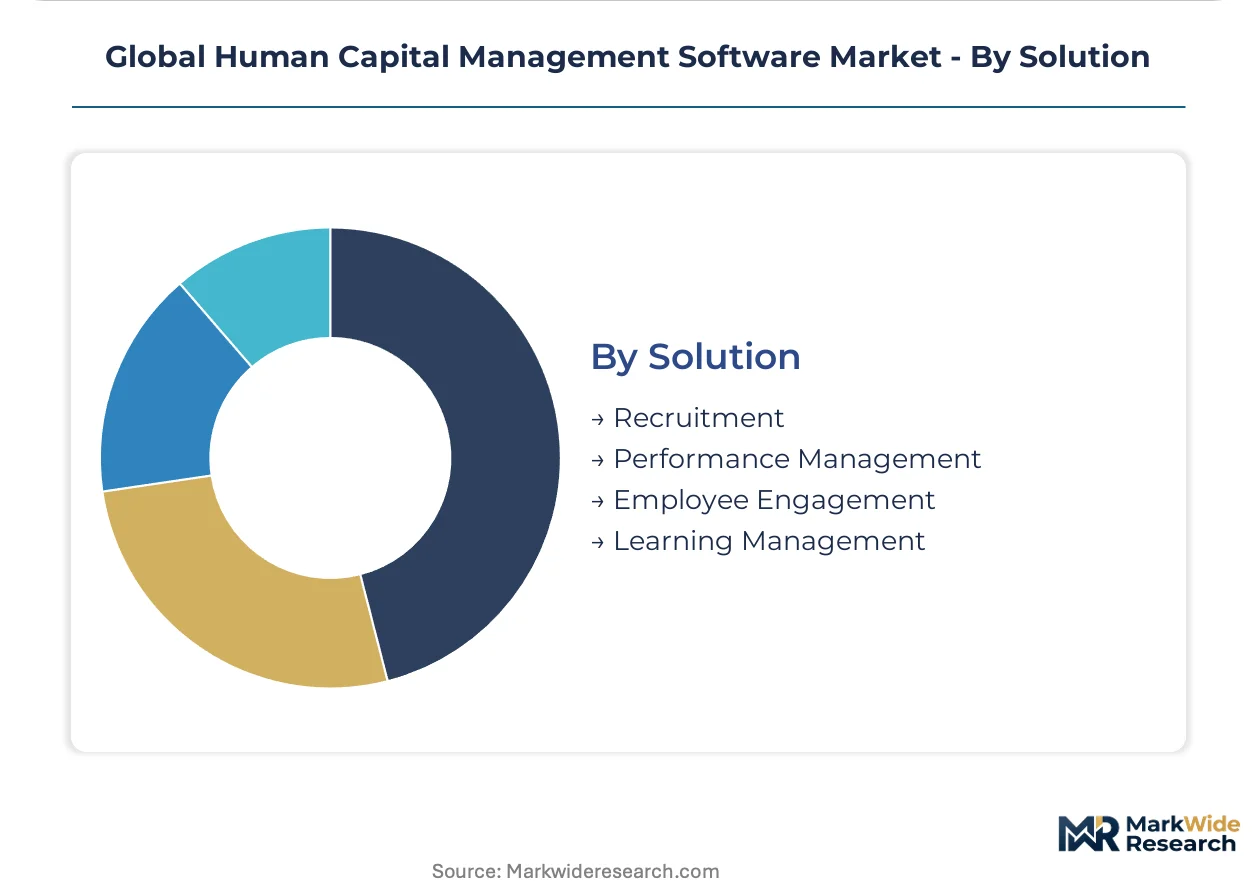
| Segmentation | Product Type: Core HR, Talent Management, Workforce Management, Payroll Deployment: Cloud-based, On-Premise, Hybrid, Mobile End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Solution: Recruitment, Performance Management, Employee Engagement, Learning Management |
| Companies Covered | Workday, Inc., SAP SE, Oracle Corporation, ADP, Inc., UKG Inc., Paycom Software, Ceridian HCM Holding Inc., Paylocity Corporation, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Human Capital Management Software Market Strategic Shifts
Generative AI capabilities are embedding directly into recruitment, performance management, and employee self-service interfaces, compressing development cycles for conversational analytics and automated content generation.
Large language model-powered candidate screening and interview scheduling is overtaking rules-based applicant tracking systems in high-volume hiring environments. Enterprise employers in technology and business process outsourcing sectors are deploying these tools to reduce time-to-fill metrics by automating initial candidate engagement. The structural consequence is a compression in demand for standalone recruitment marketing platforms as HCM suites absorb matching and outreach functionality natively.
The EU AI Act's risk-based classification framework for employment-related algorithmic systems is forcing vendors to implement explainability requirements and human-in-the-loop safeguards. Vendors must now document training data provenance and bias testing protocols for AI features deployed in European jurisdictions. Healthcare and financial services employers in Germany and France are prioritizing procurement of platforms with pre-certified compliance documentation to accelerate internal governance approvals.
Subscription-based pricing with usage-scaled modules is displacing perpetual license models across mid-market segments. Human resources departments in professional services and technology verticals are demanding consumption-aligned contracts that scale with headcount fluctuations rather than fixed enterprise agreements. This pattern is most visible in the United States, where private equity-backed portfolio companies prioritize operational flexibility over long-term capital commitments.
Global Human Capital Management Software Market Segmentation
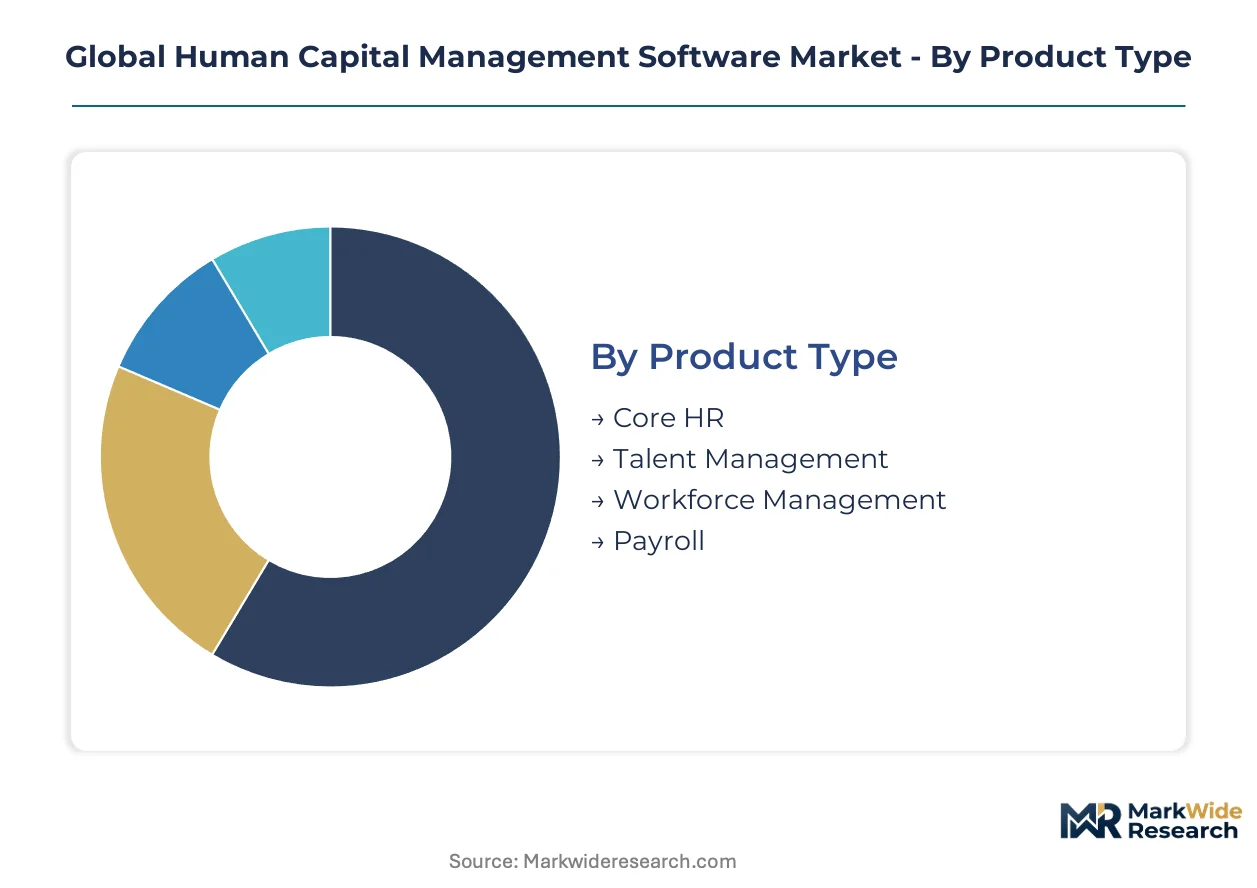
Segmentation in human capital management software reveals how procurement patterns diverge across organizational scale, regulatory exposure, and technical sophistication. Cloud-native platforms command premium positioning in talent-intensive verticals, while legacy payroll engines retain entrenched positions in regulated industries with complex collective bargaining requirements.
Product Type:
Supply concentration in core HR and payroll modules anchors vendor revenue stability, while talent management solutions attract disproportionate R&D investment from emerging entrants.
- Core HR:Employee record management, organizational hierarchy tools, and benefits administration form the foundational layer. Demand concentrates in United States healthcare systems replacing legacy systems under HIPAA interoperability mandates. Compliance-driven replacement cycles sustain renewal rates despite slower feature innovation.
- Talent Management:Recruitment pipelines, succession planning, and skills mapping applications dominate new logo acquisition. European technology employers in Germany and France prioritize these modules to address EU AI Act documentation requirements for algorithmic hiring tools.
- Workforce Management:Shift scheduling, time tracking, and absence management for distributed operations. Retail logistics operators in the United Kingdom deploy these tools to optimize coverage ratios across multi-site networks.
- Payroll:Compensation calculation, tax withholding, and regulatory filing engines with localized compliance rules. Manufacturing employers in India adopt cloud payroll to automate Provident Fund and Professional Tax calculations under expanding PLI scheme coverage.
Today's leader: Core HR. Tomorrow's challenger: Talent Management.
Deployment:
Cost tier differentiation separates enterprise-grade cloud implementations from mid-market SaaS offerings, with hybrid configurations capturing regulated industries requiring data residency controls.
- Cloud-based:Multi-tenant SaaS architectures with API-first interoperability and automatic updates. SMEs across India's services export sector accelerate adoption to eliminate on-premise infrastructure overhead.
- On-Premise:Single-tenant installations with localized data storage and custom configuration capabilities. United States defense contractors maintain these deployments to satisfy federal security clearance requirements.
- Hybrid:Split configurations with sensitive payroll data on-premise and talent applications in cloud. German financial services employers favor this model to reconcile GDPR residency mandates with workforce analytics demands.
- Mobile:Native iOS and Android applications for manager self-service and field workforce engagement. Shift-based employers in Australia's mining and construction sectors prioritize mobile-first time capture.
Cloud-based deployments scale fastest among new adopters. Hybrid architectures defend position in compliance-heavy verticals.
End User:
Customer type determines module bundling complexity, with large enterprises demanding integrated suites and SMEs selecting point solutions with rapid implementation timelines.
- SMEs:Employers with under 500 employees seeking rapid deployment and consumption-based pricing. India's mid-market manufacturing and IT services firms drive volume growth through PLI-linked digitization incentives.
- Large Enterprises:Complex organizations with multi-country payroll, matrix reporting, and union negotiation requirements. United States-based multinational manufacturers anchor demand for SAP and Oracle integrated suites.
- Government Agencies:Public sector employers with civil service classification systems and pension administration needs. State and municipal governments across the United States modernize legacy COBOL-based systems under federal grant programs.
- Educational Institutions:Universities and K-12 districts with academic calendar alignment and grant-funded position management. Research-intensive institutions in Switzerland and the Netherlands prioritize these solutions for European Research Council compliance reporting.
SMEs expand the addressable market fastest. Large enterprises concentrate vendor profitability.
Solution:
Maturity gradients separate established performance management workflows from emerging employee engagement platforms with unproven ROI measurement frameworks.
- Recruitment:Applicant tracking, candidate relationship management, and onboarding automation. High-volume hiring environments in India's business process outsourcing sector compress time-to-fill through AI-enabled screening.
- Performance Management:Goal-setting frameworks, continuous feedback tools, and calibration workflows. Professional services firms in the United Kingdom deploy these modules to align consultant utilization targets with partnership promotion criteria.
- Employee Engagement:Pulse surveys, recognition platforms, and sentiment analysis applications. Technology employers in Israel and Singapore experiment with these tools to address retention pressure in competitive talent markets.
- Learning Management:Course delivery, skills certification tracking, and compliance training administration. Healthcare systems in France integrate these with ANSM-mandated continuing medical education requirements.
Performance management retains the largest installed base. Learning management climbs fastest on skills-based hiring mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Francisco Bay Area anchors enterprise software development for human capital management platforms, housing dense clusters of cloud-native architecture teams and venture-backed workforce analytics startups. Federal contractor compliance mandates and state pay transparency statutes generate concentrated procurement activity across specific metropolitan markets.
United States
Healthcare systems in Texas and California are replacing legacy on-premise HR installations with HIPAA-compliant cloud platforms to satisfy interoperability mandates. The SEC's climate disclosure rules and emerging algorithmic accountability frameworks at the federal level are extending reporting obligations into workforce metrics. Federal contractors in the Washington DC metro area drive demand for compliance-embedded suites under OFCCP audit requirements.
Germany
Manufacturing employers in Bavaria and Baden-Württemberg deploy integrated payroll and workforce planning systems to manage complex collective bargaining agreements across automotive and industrial machinery supply chains. GDPR data localization requirements force vendors to maintain member-state hosted infrastructure with embedded residency controls. Frankfurt-based financial services firms prioritize procurement of platforms with pre-certified EU AI Act documentation for algorithmic hiring modules.
United Kingdom
Professional services firms in London and the Southeast deploy performance management modules to align consultant utilization targets with partnership promotion criteria. The Information Commissioner's Office enforces GDPR workforce data protections alongside emerging algorithmic accountability guidance. Retail logistics operators in the Midlands optimize shift-based scheduling across multi-site distribution networks using AI-enabled workforce management tools.
India
Mid-market manufacturing and IT services employers in Maharashtra and Karnataka accelerate SaaS adoption under Production-Linked Incentive scheme digitization incentives. The Reserve Bank of India's data localization directives for financial services HR data complement broader compliance automation demand. Business process outsourcing clusters in Hyderabad and Chennai compress time-to-fill metrics through AI-enabled candidate screening integrated into native recruitment modules.
France
Healthcare systems in Île-de-France integrate learning management platforms with ANSM-mandated continuing medical education requirements for clinical workforce tracking. The CNIL enforces GDPR workforce data protections with specific attention to algorithmic decision-making in employment contexts. Research-intensive universities in the Auvergne-Rhône-Alpes region prioritize solutions for European Research Council compliance reporting on grant-funded position management.
Global Human Capital Management Software Market Competitive Environment
Global majors compete with regional champions across cloud architecture depth and compliance module specialization. Enterprise-grade suites with deep ERP integration anchor complex payroll deployments, while cloud-native specialists capture talent management and financial planning convergence opportunities. Three archetypes dominate: integrated ERP-anchored platforms, standalone cloud-native suites, and vertical-focused compliance specialists. M&A activity concentrates on workforce analytics capabilities, while geographic expansion targets India's mid-market digitization wave.
Within the integrated ERP tier, SAP SE and Oracle Corporation occupy positions defined by database-layer connectivity and manufacturing client entrenchment. Workday, Inc. exemplifies the cloud-native archetype with architecture built for talent management and financial planning convergence. These three entities anchor competitive dynamics across enterprise procurement cycles, with differentiation emerging through API interoperability standards and embedded AI explainability features rather than core module breadth.
| Leading Market Players |
|---|
| Workday, Inc. |
| SAP SE |
| Oracle Corporation |
| ADP, Inc. |
| UKG Inc. |
| Paycom Software |
| Ceridian HCM Holding Inc. |
| Paylocity Corporation |
| Microsoft Corporation |
| Others |
Value Chain & Pricing Dynamics
EU AI Act compliance documentation gates both qualified supply and premium-tier pricing access for algorithmic hiring modules, forcing vendors to absorb certification costs or cede European healthcare and financial services procurement to pre-certified competitors. Cloud-native platforms with embedded explainability features command subscription premiums, while uncertified entrants face exclusion from German and French enterprise RFPs regardless of price positioning.
Pricing Analysis
Input-cost pass-through from ISO 30414 reporting template development and GDPR residency infrastructure elevates SaaS base rates for compliance-heavy verticals. Pricing stratifies across premium, standard, and economy tiers based on module depth and geographic data hosting requirements. Cost compression in mid-market segments intensifies as India's PLI-digitized employers demand consumption-scaled contracts over fixed enterprise agreements. SMEs exhibit highest price sensitivity, while United States federal contractors accept premium positioning to satisfy OFCCP audit readiness.
Supply Chain Analysis
ISO 27001 and SOC 2 Type II certification gating concentrates qualified implementation capacity in the United States, Germany, and India. Cloud infrastructure draws from hyperscaler data centers in Frankfurt, Virginia, and Mumbai, with workforce analytics R&D anchored in Tel Aviv and Singapore clusters. Single-source vulnerability persists for EU AI Act compliance documentation specialists concentrated in Paris and Berlin consulting ecosystems. Distribution runs through direct enterprise sales teams supplemented by certified implementation partners in London, New York, and Frankfurt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as healthcare systems and federal contractors prioritize audit-ready compliance modules over lowest-cost alternatives, elevating vendors with pre-certified GDPR and EU AI Act documentation.
For Market Incumbents: Lock in channel control by acquiring certified implementation partners in India and Germany to defend against queue-delay churn. Invest in backward integration into explainability tooling R&D to neutralize emerging AI-native entrants threatening European healthcare accounts. Prioritize embedded climate disclosure templates to capture SEC and CSRD-driven module demand before point-solution specialists consolidate this workflow layer. For New Entrants and Emerging Players: GDPR data localization mandates in France and Germany open a window for region-hosted cloud deployments with native residency controls, bypassing incumbent hybrid-configuration complexity. Target India's mid-market manufacturing digitization wave under PLI scheme coverage with rapid-deployment payroll automation priced below SAP and Oracle implementation thresholds. Lead with API-first interoperability certification to reduce enterprise switching-cost friction against entrenched suite vendors. For Investors and Strategic Acquirers: Roll-up economics work for workforce analytics specialists because platform consolidation compresses customer acquisition costs while expanding cross-sell attach rates for compliance modules. Focus on targets with pre-built EU AI Act documentation and existing German healthcare referenceability. Watch for inflection when United States federal agencies mandate algorithmic accountability frameworks comparable to European standards, triggering replacement cycles among current OFCCP-compliant incumbents lacking explainability infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies talent cost modeling with ERP systems for technology and professional services verticals. |
| Acquisition of Specialist Firm | Captures workforce analytics capabilities and EU AI Act compliance documentation expertise. |
| Geographic Expansion | Establishes India-based implementation capacity to serve PLI-digitized mid-market manufacturing demand. |
| Product Launch | Introduces embedded climate disclosure templates aligned with SEC rules and EU CSRD requirements. |
| Strategic Partnership | Secures hyperscaler co-location agreements for GDPR-compliant data residency in Frankfurt and Mumbai. |
Study Parameters
Direct dialogue with HCM platform product managers, enterprise IT procurement officers, certified implementation partners, and regulatory compliance leads grounded qualitative findings in deployment friction and procurement decision criteria. Secondary validation drew from SEC filings of publicly traded vendors, EU AI Act implementation guidance documents, HL7 FHIR interoperability specifications, and ISO 30414 human capital reporting standards. Bottom-up sizing of module-level deployments triangulated against top-down enterprise software spending estimates across healthcare, manufacturing, and professional services verticals.
Bottom-up demand modeling tracked adoption rates across cloud-native, hybrid, and on-premise deployment configurations, segmented by organization size and regulatory exposure intensity. Top-down validation cross-referenced vendor-reported subscription revenue against addressable employer counts in HIPAA-covered healthcare systems, federal contractor populations, and PLI-eligible Indian manufacturing. CAGRs were derived from replacement cycle timing for legacy COBOL payroll systems and cloud migration acceleration under interoperability mandates. Forecast inputs incorporated GDPR enforcement escalation patterns and SEC climate disclosure rule adoption timelines.
Revisions become necessary when EU AI Act enforcement intensity exceeds current compliance documentation preparation timelines or when United States federal algorithmic accountability frameworks materialize with retroactive application requirements. Model outputs reflect assumptions regarding hyperscaler data center expansion pace and certified implementation partner capacity growth. A model refresh is warranted upon material change in HIPAA interoperability mandate compliance deadlines or Production-Linked Incentive scheme eligibility expansion in India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global App Store Optimization Software Market
Software & Services
Global Mobile User Interface Services Market
Software & Services
Global Electronic Dictionary Market
Software & Services
Drone Mapping Software Market
Software & Services
Global Equity Management Software Market
Software & Services
Global Diagram Software Market
Software & Services
Global Automotive Software Market
Software & Services
Storyboarding Software Market
Software & Services
Enterprise Software Market
Software & Services
Tag Management Software Market
Software & Services
Global Document Management Software Market
Software & Services
Software Publishers Market
Software & Services
Data Integration Software Market
Software & Services
Executive Search (Headhunting) Software Market
Software & Services
Service Scheduling Software Market
Software & Services
Indoor Cycling Software Market