
 Global Diagram Software Market | 2026-2036
Global Diagram Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diagram Software Market Foresight
Subscription-based financing and asset-light deployment models are tilting competitive dynamics toward vendors with low customer acquisition costs and scalable cloud infrastructure. Microsoft Corporation leverages its entrenched Office ecosystem to bundle diagramming capabilities into broader enterprise contracts. Lucid Software Inc. anchors its position through deep integration with collaboration platforms and real-time co-editing features. SmartDraw LLC competes by targeting regulated industries with compliance-oriented template libraries and on-premise deployment options.
Diagram software encompasses digital tools that generate structured visual representations—flowcharts, network topology maps, entity-relationship diagrams, and UI wireframes—using standardized notation libraries, vector rendering engines, and collaborative editing protocols. These applications serve process documentation, system architecture design, and cross-functional communication across technical and non-technical teams. Cloud-based deployment leads in new customer acquisition due to minimal setup friction and automatic version synchronization, while on-premise solutions retain strongholds in defense contracting and classified government environments where data residency mandates apply. Mind mapping and wireframe categories within solution type are capturing disproportionate growth as product management and UX design disciplines expand into mid-market companies previously underserved by specialized tools.
The EU AI Act, GDPR data-processing requirements, and U.S. FedRAMP authorization standards collectively shape vendor eligibility for public-sector and regulated-industry contracts, forcing architecture changes in data storage and access logging. ISO/IEC 27001 certification has become a baseline expectation for enterprise procurement evaluations, particularly in German automotive supply chains and Japanese financial institutions. Stakeholders must monitor evolving cross-border data transfer restrictions and anticipate which compliance frameworks will become mandatory disqualifiers rather than competitive differentiators.
Market Dynamics
Cloud-native diagramming platforms are compressing deployment cycles from months to hours, forcing legacy desktop vendors to re-architect around browser-first rendering engines and real-time synchronization protocols.
Growth Catalysts
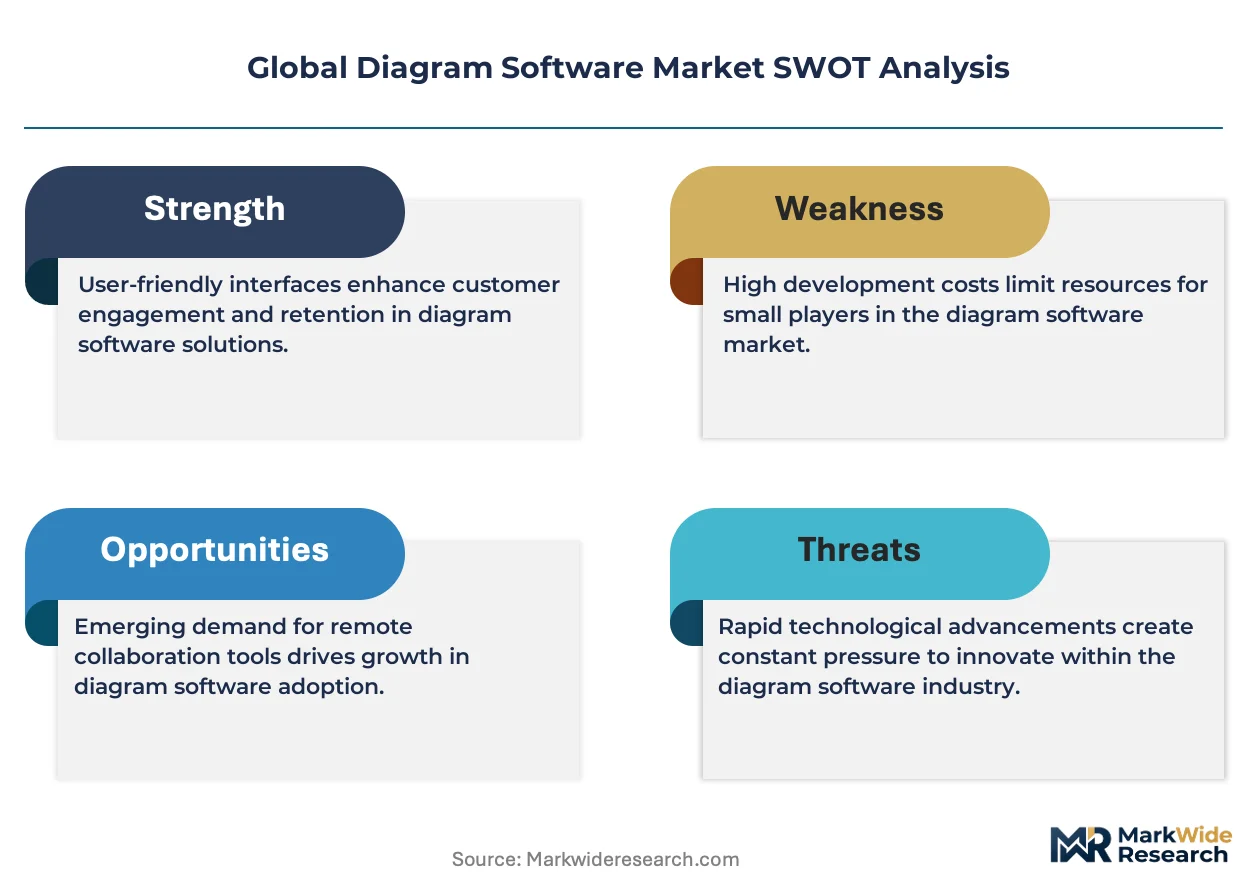
- EU AI Act compliance mandates:Automated documentation requirements for high-risk AI systems in German automotive and French financial services are driving procurement of traceable diagramming workflows with embedded audit trails.
- Mid-market UX design expansion:Product management disciplines in SaaS-native enterprises across California and Texas are adopting specialized wireframing tools previously restricted to Fortune 500 budgets.
- Network topology visualization:Zero-trust security architectures in U.S. defense contracting require dynamic infrastructure mapping that traditional static tools cannot deliver.
Market Restraints
- Data residency compliance costs:Germany's BSI IT-Grundschutz and France's ANSSI certification requirements force vendors to maintain sovereign cloud instances, fragmenting infrastructure economics.
- Vector rendering engine concentration:Browser-based canvas performance depends on WebKit and Chromium optimizations controlled by Apple and Google, creating upstream dependency risk.
- Substitution by generalist platforms:Whiteboarding tools from established collaboration suites absorb basic diagramming use cases in price-sensitive procurement evaluations.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Design documentation requirements for subsidized semiconductor and telecom equipment production create localized demand for compliant diagramming solutions.
- Convergence of diagramming and digital twin platforms:Real-time sensor data overlay on process diagrams enables predictive maintenance visualization in Japanese automotive supply chains.
- Embedded finance workflow documentation:API architecture mapping for open banking compliance in UK and Australian markets represents an underserved vertical specialization.
Industry Challenges
- ISO/IEC 27001 certification timelines:Enterprise procurement in Japanese financial institutions requires 12-18 month audit cycles that delay vendor onboarding and revenue recognition.
- Legacy CAD system integration:Defense contractors maintaining classified environments must bridge on-premise AutoCAD and MicroStation archives with modern collaborative platforms without data egress.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diagram Software Market |
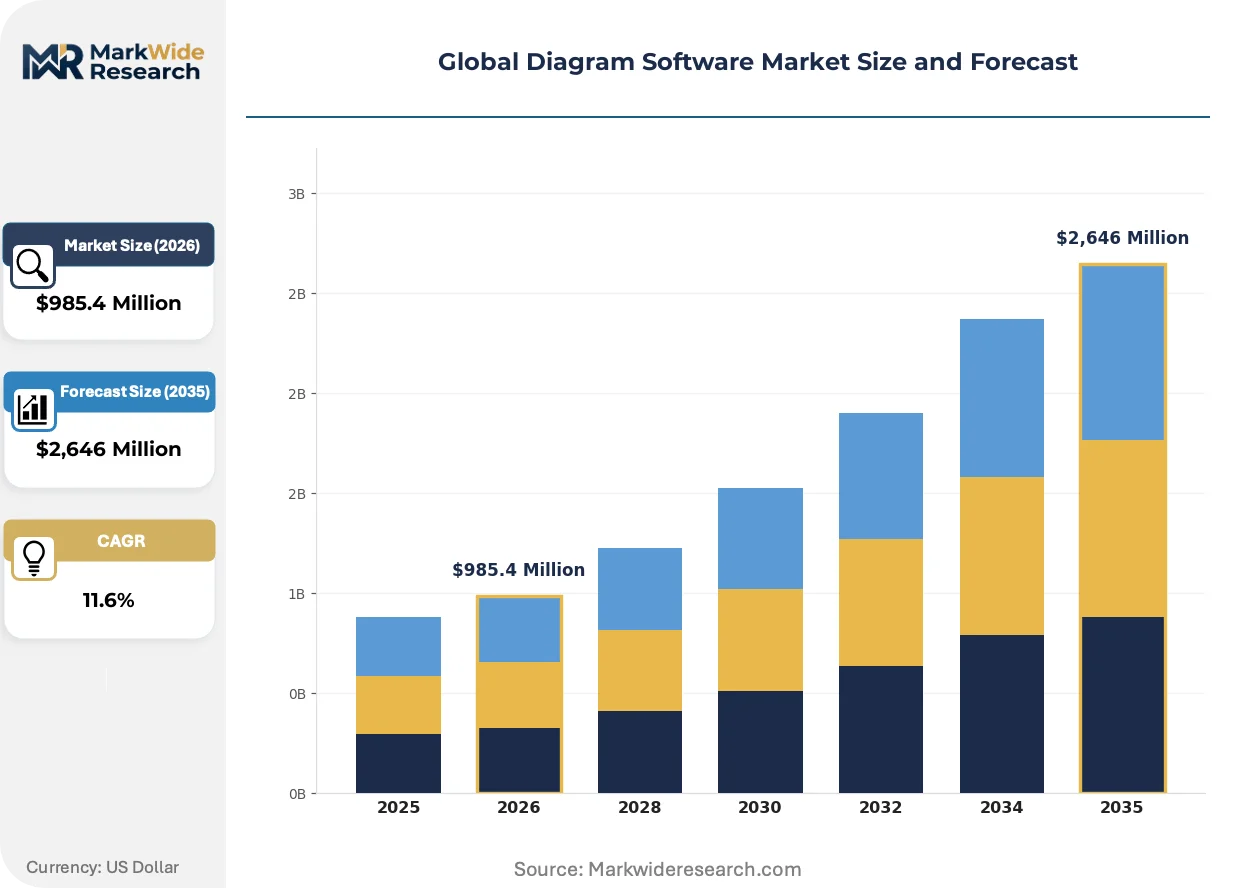
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $2,646 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Web-Based, Mobile Solution Type: Flowchart, Network Design, Mind Mapping, UML, Wireframe, Org Chart End User: Enterprise, Small & Medium Business, Freelancers, Educational Institutions, Government Agencies Integration Capability: API Support, Third-Party Plugins, Cloud Storage, Collaboration Tools, CRM Systems |
| Companies Covered | Cinergix Pty Ltd., Gliffy Inc., Microsoft Corporation, Creately, EdrawSoft, Lucid Software Inc., The Omni Group, JGraph, SmartDraw LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diagram Software Market Shifts & Advancements
Generative AI is restructuring how diagramming tools interpret natural language inputs, compressing the gap between conceptual description and executable visual output while forcing vendors to retrain user interaction models.
AI-assisted diagram generation is hybridizing structured notation engines with large language model interpretation layers. Enterprise architecture teams in U.S. federal agencies are piloting automated system documentation that converts policy text into compliance flowcharts. This convergence is collapsing the traditional boundary between business analysts and technical draftspersons, redistributing workflow ownership toward domain specialists.
CSRD sustainability reporting mandates in the European Union require supply chain visualization with embedded emissions tracking. Industrial equipment manufacturers in Germany must document Scope 3 carbon flows through tiered supplier networks. The regulation is elevating diagramming tools from static documentation to dynamic ESG data interfaces, with French automotive OEMs leading procurement of integrated reporting platforms.
Subscription fatigue among mid-market buyers is fragmenting purchasing authority toward departmental procurement. Product teams in Texas energy startups now evaluate diagramming tools against standalone ROI metrics rather than enterprise-wide standardization. This decentralization favors vendors with transparent per-seat pricing and self-service onboarding over those requiring IT department approval cycles.
Global Diagram Software Market Segmentation
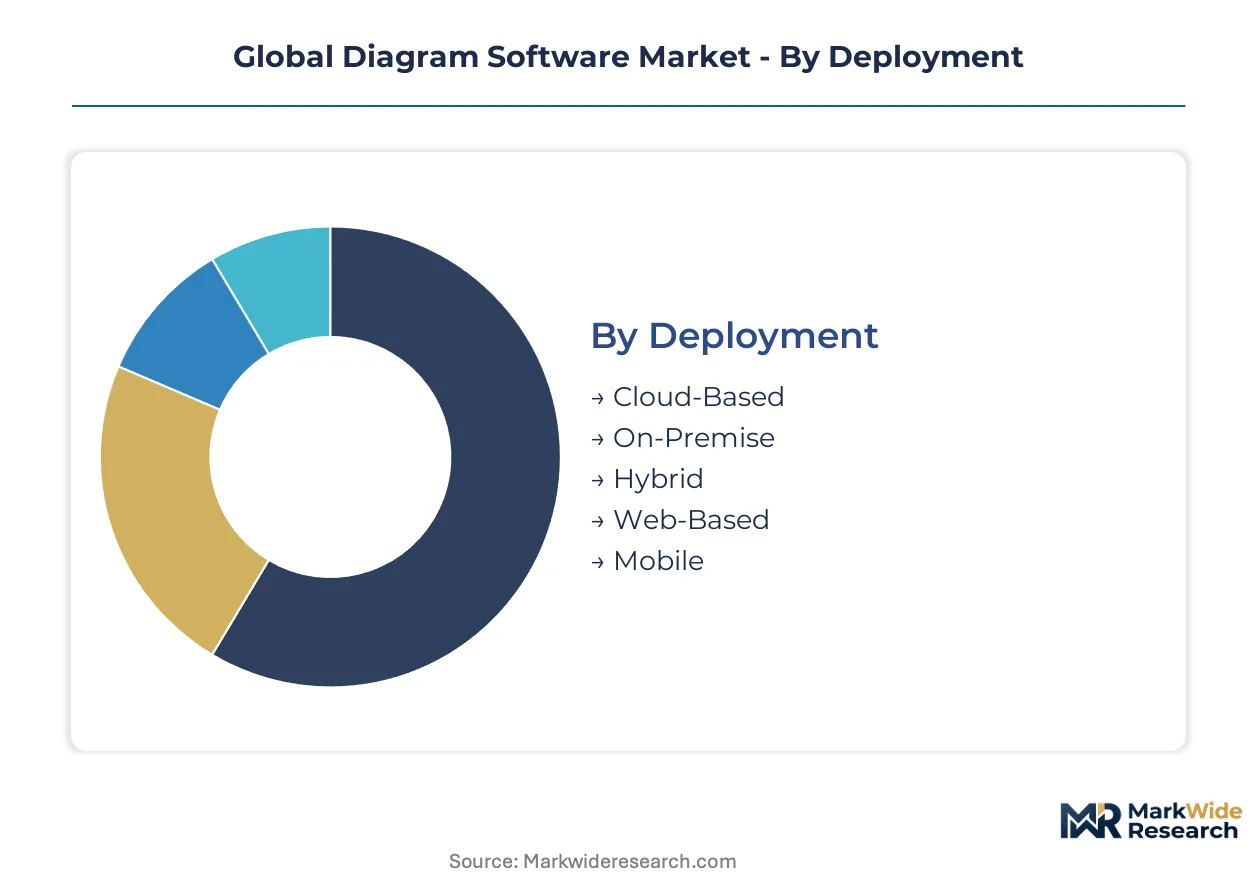
Deployment modality and solution architecture determine procurement cycles, compliance burdens, and integration complexity across buyer segments. Understanding how these dimensions intersect reveals where vendor resources generate disproportionate returns versus commoditized battlegrounds.
Deployment:
Cloud-based deployments compress sales cycles to days while on-premise implementations stretch across quarters due to security reviews and infrastructure provisioning.
- Cloud-Based:Browser-first architectures with automatic version synchronization serve SaaS-native enterprises in California and Texas. Procurement teams favor subscription models that bypass capital expenditure approvals and IT department queue bottlenecks.
- On-Premise:Air-gapped installations with local data residency satisfy defense contracting requirements and classified government environments. Germany's BSI IT-Grundschutz and France's ANSSI certification mandates force vendors to maintain sovereign infrastructure instances.
- Hybrid:Selective cloud synchronization with core on-premise repositories bridges legacy AutoCAD archives with modern collaborative workflows.
- Web-Based:Lightweight rendering engines dependent on WebKit and Chromium optimizations eliminate client-side installation friction.
- Mobile:Touch-optimized canvas interfaces with offline editing capabilities extend diagramming to field engineering and construction site workflows.
On-premise deployments dominate installed base in regulated industries. Cloud-based solutions are where expansion concentrates among mid-market adopters.
Solution Type:
Functional specialization separates tools commanding premium pricing from those facing substitution by generalist whiteboarding platforms.
- Flowchart:Standardized notation libraries for process documentation remain the entry-point category. Manufacturing operations teams in German automotive supply chains leverage embedded audit trails for EU AI Act compliance.
- Network Design:Dynamic topology mapping with real-time sensor data overlay serves zero-trust security architectures in U.S. defense contracting. Static legacy tools cannot deliver the infrastructure visualization this segment demands.
- Mind Mapping:Non-linear ideation structures capture disproportionate growth as product management disciplines expand into Texas energy startups and California SaaS enterprises.
- UML:Standardized software engineering notation supports enterprise architecture teams in Japanese financial institutions requiring ISO/IEC 27001-aligned documentation.
- Wireframe:UI prototyping capabilities previously restricted to Fortune 500 budgets now penetrate mid-market UX design functions.
- Org Chart:Hierarchical personnel visualization integrates with HRIS systems for workforce planning in enterprise environments.
Flowchart and network design tools anchor established revenue streams. Mind mapping and wireframe categories are climbing the fastest as previously underserved disciplines adopt specialized tooling.
End User:
Organizational scale dictates purchasing authority location, evaluation criteria weighting, and price sensitivity thresholds.
- Enterprise:Centralized procurement with ISO/IEC 27001 certification requirements and 12-18 month vendor onboarding timelines. German automotive OEMs and Japanese financial institutions represent concentrated demand.
- Small & Medium Business:Departmental purchasing authority with transparent per-seat pricing and self-service onboarding preferences. Subscription fatigue favors vendors eliminating IT approval cycles.
- Freelancers:Individual license models with project-based billing and cross-platform portability requirements.
- Educational Institutions:Volume licensing with academic pricing tiers and collaborative classroom features.
- Government Agencies:FedRAMP authorization standards and data residency mandates restrict vendor eligibility for U.S. federal contracts.
Enterprise accounts dominate lifetime value metrics. Small and medium business segments are where customer acquisition velocity concentrates.
Integration Capability:
Connectivity depth determines whether diagramming functions as standalone software or embedded workflow infrastructure.
- API Support:Programmatic diagram generation enables automated system documentation converting policy text into compliance flowcharts for U.S. federal agencies.
- Third-Party Plugins:Extension ecosystems allow customization without core platform modification.
- Cloud Storage:Native connectors to enterprise file repositories eliminate manual export-import friction.
- Collaboration Tools:Deep integration with real-time co-editing platforms anchors competitive positioning against bundled whiteboarding substitutes.
- CRM Systems:Customer journey visualization and sales process mapping extend diagramming into revenue operations workflows.
API support and collaboration tool integration dominate technical evaluation criteria. CRM connectivity represents the steepest expansion trajectory as revenue operations teams adopt visualization tooling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software vendors command 40% higher subscription pricing in the United States compared to Germany, where data residency compliance costs compress margins. This pricing-power asymmetry shapes where vendors prioritize cloud infrastructure investment versus regulatory adaptation.
United States
FedRAMP authorization standards and zero-trust security architectures drive procurement from defense contractors and federal agencies. SaaS-native enterprises in California and Texas demand real-time collaboration features with minimal IT friction. Austin and San Francisco host the densest concentrations of product teams adopting specialized wireframing tools.
Germany
BSI IT-Grundschutz certification mandates force vendors to maintain sovereign cloud instances for automotive and financial services procurement. EU AI Act documentation requirements for high-risk AI systems accelerate traceable diagramming workflow adoption. Stuttgart's automotive OEMs lead regional demand for compliance-oriented template libraries.
Japan
ISO/IEC 27001 certification timelines of 12-18 months delay vendor onboarding for financial institutions in Tokyo and Osaka. Enterprise architecture teams require standardized UML notation aligned with security documentation protocols. METI guidelines on software procurement reinforce centralized vendor evaluation frameworks.
India
PLI scheme subsidies for electronics manufacturing create localized demand for design documentation tools in semiconductor and telecom equipment production. Bangalore and Hyderabad SaaS enterprises drive cloud-native adoption with departmental purchasing authority. RBI guidelines on data localization shape vendor infrastructure decisions.
United Kingdom
Open banking API architecture mapping requirements generate specialized demand from financial services firms in London. CSRD sustainability reporting mandates elevate diagramming tools to dynamic ESG data interfaces for supply chain visualization. Manchester and Edinburgh fintech clusters adopt embedded finance workflow documentation platforms.
Global Diagram Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower functional scope. The market exhibits tiered concentration where bundled collaboration suites absorb basic use cases while specialized vendors defend premium positions through compliance depth. Three archetypes dominate: ecosystem bundlers anchoring enterprise contracts, cloud-native independents with deep collaboration integration, and compliance-focused specialists targeting regulated verticals. M&A activity concentrates on API infrastructure acquisitions, while geographic expansion into sovereign cloud instances represents the secondary competitive vector.
Within the ecosystem bundler tier, Microsoft Corporation exemplifies platform leverage through Office ecosystem integration. Cloud-native specialists include Lucid Software Inc. and Cinergix Pty Ltd., occupying positions defined by real-time synchronization capabilities and browser-first architectures. SmartDraw LLC represents the compliance-focused archetype with on-premise deployment options targeting defense and government verticals.
| Leading Market Players |
|---|
| Cinergix Pty Ltd. |
| Gliffy Inc. |
| Microsoft Corporation |
| Creately |
| EdrawSoft |
| Lucid Software Inc. |
| The Omni Group |
| JGraph |
| SmartDraw LLC |
| Others |
Supply & Pricing Matrix
Regulatory chokepoints in cross-border data transfer determine both pricing tier spreads and supply chain shape across the diagram software market. Vendors absorbing sovereign cloud infrastructure costs in Germany and France must recoup through premium positioning, while browser-first architectures dependent on WebKit and Chromium optimizations concentrate upstream technical risk.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command separation through ISO/IEC 27001 certification depth and FedRAMP authorization status, while standard tiers compete on per-seat subscription transparency and self-service onboarding velocity. Cost compression in economy tiers intensifies as whiteboarding tools from bundled collaboration suites absorb basic diagramming use cases. Mid-market SaaS enterprises in Texas and California exhibit highest price sensitivity, prioritizing departmental procurement autonomy over enterprise-wide standardization.
Supply Chain Analysis
Extended payment terms from hyperscale cloud providers reshape vendor working capital requirements across the diagram software supply chain. Core infrastructure draws from sovereign cloud instances in Germany, France, and India mandated by BSI IT-Grundschutz, ANSSI, and RBI data localization guidelines. Vector rendering engines rest on WebKit and Chromium optimizations controlled by Apple and Google, creating single-source vulnerability. Distribution runs through direct enterprise sales teams for regulated verticals and self-service digital channels for mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diagram software market functions as a defensive-moat story where regulatory entrenchment creates durable competitive advantage. Switching costs compound through embedded workflow integration and compliance certification timelines that delay vendor displacement.
For Market Incumbents: Pre-empt substitution threats from generalist whiteboarding platforms by deepening API infrastructure investments that embed diagramming into automated system documentation workflows. Accelerate sovereign cloud capacity additions in Germany and France ahead of EU AI Act enforcement timelines. Fortify position through acquisition of specialized digital twin visualization capabilities serving Japanese automotive supply chains.
For New Entrants and Emerging Players: India's PLI-subsidized electronics manufacturing corridors offer underpenetrated demand for design documentation tools compliant with localized data residency requirements. Target semiconductor and telecom equipment producers in Bangalore and Hyderabad with API-first architectures bypassing IT department procurement bottlenecks. Establish beachhead through embedded finance workflow documentation partnerships serving UK and Australian open banking compliance needs.
For Investors and Strategic Acquirers: EU AI Act documentation mandates reshape the acquisition landscape toward vendors with traceable workflow capabilities and embedded audit trail architectures. Long-term viability concentrates in platforms demonstrating cross-vertical compliance adaptability across automotive, financial services, and defense contracting segments. Monitor FedRAMP authorization pipeline velocity as the signal indicating public-sector procurement inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Microsoft 365 and Google Workspace embedding captures enterprise procurement decisions in California and Texas. |
| Acquisition of Specialist Firm | Digital twin visualization capabilities enable predictive maintenance overlays for German automotive OEMs. |
| Geographic Expansion | Sovereign cloud instances in Stuttgart and Paris satisfy BSI IT-Grundschutz and ANSSI certification mandates. |
| Strategic Partnership | Collaboration platform alliances anchor real-time co-editing features against bundled whiteboarding substitutes. |
| Product Launch | AI-assisted diagram generation compresses policy-to-flowchart conversion timelines for U.S. federal agencies. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews across enterprise IT procurement officers, platform engineering leads, compliance auditors at German automotive OEMs, and product managers at Texas SaaS enterprises. Secondary validation drew from SEC filings of publicly traded software vendors, hyperscaler infrastructure capex disclosures, EU regulatory filings documenting AI Act implementation timelines, and ISO certification registry databases. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Calibration against historical adoption curves and vendor-reported customer metrics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass deployment modality, organization size tier, vertical industry, integration complexity level, and regional regulatory cluster. CAGRs were derived through slope analysis of normalized adoption velocity curves, with specific inputs including FedRAMP authorization pipeline data and PLI scheme disbursement trajectories.
Practitioners should monitor regulatory enforcement timelines and cross-border data transfer restriction announcements for early signals of vendor eligibility shifts. Forecasts reflect documented assumptions regarding compliance framework adoption rates and cloud infrastructure investment continuity. Macroeconomic contraction affecting enterprise software budgets, accelerated EU AI Act enforcement, or WebKit rendering engine deprecation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Saas Backup Software Market
Software & Services
Global Church Management Software Market
Software & Services
3D CAD Software Market
Software & Services
Global Microscope Software Market
Software & Services
Vlog Editing Software Market
Software & Services
RFP Software Market
Software & Services
Global Absence and Leave Management Software Market
Software & Services
Global Voip Software Market
Software & Services
Over-The-Air Software Update Market
Software & Services
Account-Based Data Software Market
Software & Services
Global Bill of Material Management Software Market
Software & Services
Europe Servicenow Store Apps Market
Software & Services
Custom Software Development Market
Software & Services
Global Board Management Software Market
Software & Services
Category Management Software Market
Software & Services
User Feedback Software Market