
 Drone Mapping Software Market | 2026-2036
Drone Mapping Software Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Mapping Software Market Intelligence
Australia is tilting toward drone mapping capacity as mining operators expand autonomous survey fleets across Western Australia and Queensland. Pix4D leverages its photogrammetry engine to dominate European infrastructure inspection workflows. DroneDeploy sustains channel control through native cloud processing that eliminates local workstation dependency. Agisoft Metashape anchors the desktop segment with perpetual-license pricing that appeals to cost-sensitive surveyor practices.
Drone mapping software converts aerial imagery and sensor data into georeferenced orthomosaics, digital elevation models, and dense point clouds through photogrammetric or LiDAR fusion algorithms, typically processing sub-centimeter ground sample distances for engineering-grade deliverables. The solution serves construction progress monitoring, mineral volume calculations, and environmental boundary delineation where terrestrial methods prove slow or hazardous. Photogrammetry-based solutions lead volume as hardware costs fall below LiDAR entry thresholds, though terrain analysis commands premium pricing where bare-earth extraction accuracy determines project economics. Government agencies represent the most concentrated end-user budget pool, particularly for cadastral and disaster-response mandates.
FAA Part 107 mandates in the United States and EASA open-category frameworks in Europe dictate flight authorization, data security, and beyond-visual-line-of-sight capabilities that software vendors must embed. EASA's specific category requirements for operations over populated areas force mapping platforms to integrate real-time telemetry logging and geofencing compliance. China's MIIT drone identification standards and GB airworthiness protocols create a parallel compliance architecture for vendors accessing that production base. Stakeholders must weigh regulatory divergence against platform standardization when selecting multi-territory deployment architectures.
Market Dynamics
Construction firms now replace ground-based surveying with aerial photogrammetry workflows, compressing project timelines from weeks to days while FAA Part 107 and EASA open-category rules force vendors to embed compliance features directly into processing pipelines.
Growth Catalysts
- FAA Part 107 certification:Standardized remote pilot requirements in the United States reduce operator training friction and expand the addressable workforce for aerial survey contractors.
- Photogrammetry algorithm advancement:Sub-centimeter ground sample distance accuracy from consumer-grade cameras eliminates LiDAR hardware cost barriers for engineering-grade deliverables.
- Mineral volume calculation demand:Mining operators across Western Australia and Queensland deploy autonomous survey fleets to replace hazardous terrestrial measurement methods in open-pit extraction sites.
Market Restraints
- LiDAR sensor cost concentration:Terrain analysis requiring bare-earth extraction accuracy depends on hardware supply chains concentrated among specialized German and Swiss component manufacturers.
- EASA specific category friction:Operations over populated areas mandate real-time telemetry logging and geofencing compliance that extends software development cycles and certification timelines.
- Terrestrial surveyor substitution threat:Traditional ground-based total station workflows retain preference among municipal cadastral authorities with legacy equipment investments and established contractor relationships.
Strategic Opportunities
- Environmental boundary delineation:Government agencies with concentrated disaster-response mandates represent underpenetrated budget pools for rapid-deployment orthomosaic generation after wildfire and flood events.
- Cloud-native processing convergence:Elimination of local workstation dependency through browser-based photogrammetry pipelines enables subscription revenue models and reduces customer acquisition costs.
- China MIIT identification standards:Parallel compliance architecture for drone identification and GB airworthiness protocols creates white space for vendors building multi-territory deployment architectures.
Industry Challenges
- Photogrammetry-to-LiDAR fusion expertise:Surveyor practices lack personnel trained in sensor fusion algorithms and point cloud registration methods required for hybrid deliverables.
- Cross-border data residency compliance:Cloud processing platforms face operational complexity mapping customer data to jurisdiction-specific storage requirements under GDPR, state privacy laws, and national security frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Mapping Software Market |
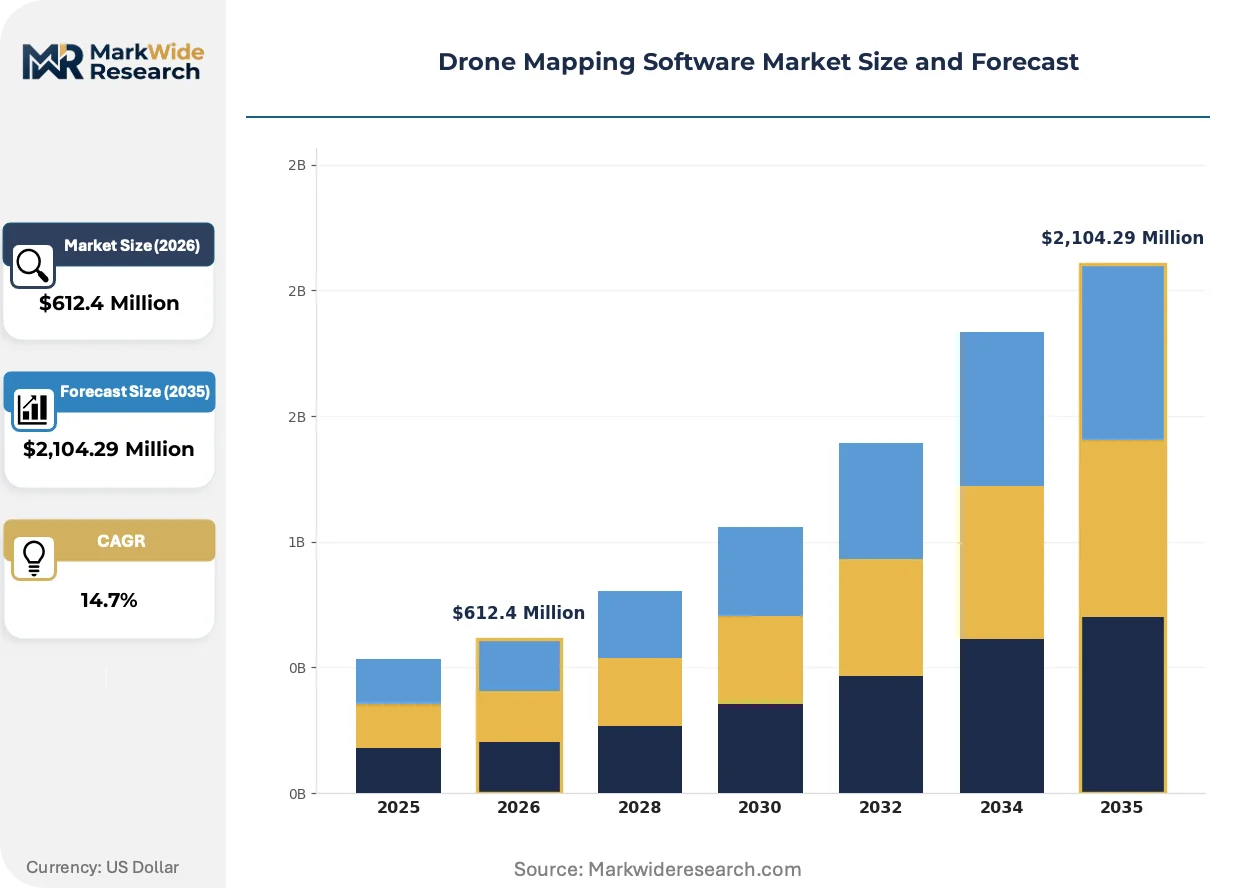
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,104.29 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Agriculture, Construction, Mining, Wildlife Conservation Solution Type: 3D Mapping, Terrain Analysis, Surveying, Inspection End User: Government Agencies, Environmentalists, Surveyors, Construction Firms Technology: LiDAR, Photogrammetry, GPS, Computer Vision |
| Companies Covered | DJI Terra, FlytBase, Pix4D, OpenDroneMap, Airdata, DroneDeploy, UgCS, 3Dsurvey, Agisoft Metashape, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Mapping Software Market Strategic Shifts & Innovations
Real-time processing architectures and regulatory automation are compressing traditional workflow timelines while procurement patterns shift toward consumption-based models that decouple software access from capital expenditure cycles.
Edge computing photogrammetry pipelines are collapsing the gap between image capture and deliverable generation. Mining operators in Western Australia now process orthomosaics on-site using GPU-equipped ground stations rather than transmitting raw imagery to remote servers. This compression eliminates bandwidth constraints in remote extraction sites and reduces project turnaround from days to hours for volume reconciliation workflows.
EASA's specific category framework for operations over populated areas is mandating embedded geofencing and telemetry logging as standard platform features. Vendors must architect real-time compliance verification into flight planning modules or face exclusion from European infrastructure inspection contracts. German engineering consultancies now require automated airspace authorization checks before awarding aerial survey procurement.
Subscription pricing for cloud-native processing is displacing perpetual-license desktop software among mid-sized surveyor practices. Agisoft Metashape's installed base faces erosion as DroneDeploy and Pix4D capture recurring revenue from construction progress monitoring workflows. This shift concentrates most visible in the American Midwest where precision agriculture corridors favor operational expenditure models aligned with seasonal cash flow patterns.
Drone Mapping Software Market Segmentation
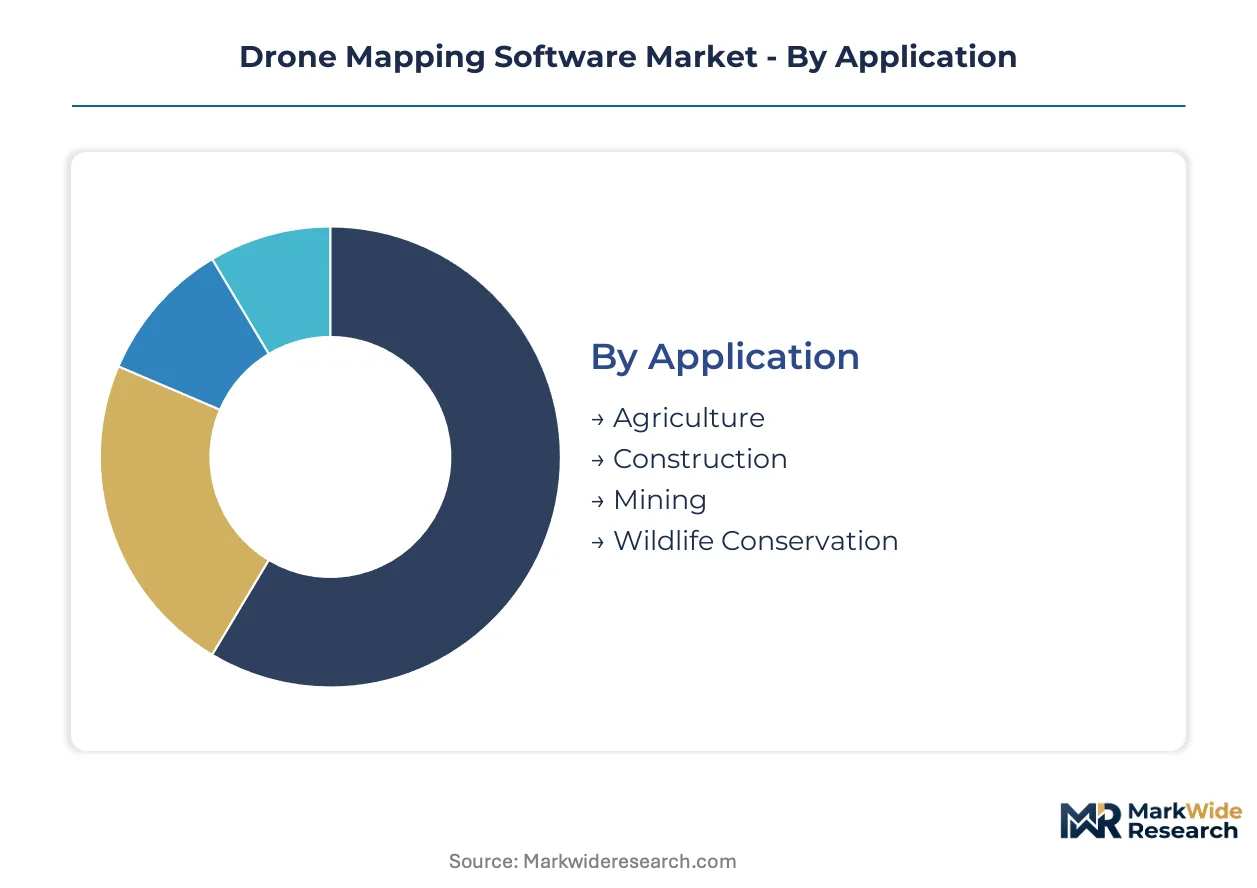
Drone mapping software segments diverge sharply by payload economics and regulatory compliance burden. Application workflows determine sensor fusion requirements while end-user procurement cycles shape vendor pricing architecture.
Application:
Application segmentation tracks where aerial photogrammetry displaces terrestrial measurement methods based on terrain hazard and timeline pressure.
- Agriculture:Sub-centimeter ground sample distance enables precision variable-rate fertilization across Midwest corn and soybean operations. Australian wheat belt operators deploy autonomous flight planning for seasonal crop health monitoring where field-scale heterogeneity demands frequent resurvey.
- Construction:Progress orthomosaics compress earthwork volume reconciliation from weeks to days. FAA Part 107 certified contractors now dominate site documentation for commercial development in Texas and Florida where vertical construction velocity outpaces traditional surveyor availability.
- Mining:Autonomous pit surveys replace hazardous terrestrial methods in Western Australia iron ore extraction. Queensland coal operators use real-time stockpile calculations for export logistics optimization.
- Wildlife Conservation:Boundary delineation for protected habitat corridors relies on low-altitude thermal mapping. Government agencies in Kenya and Tanzania deploy anti-poaching patrol route planning using vegetation penetration indices.
Construction holds installed capacity. Mining is rotating up the share rankings.
Solution Type:
Solution architecture determines computational load distribution between edge devices and cloud infrastructure.
- 3D Mapping:Dense point cloud generation from multi-angle imagery reconstructs structural as-built conditions for facility management handover. German engineering consultancies mandate BIM-compatible deliverables for infrastructure inspection contracts.
- Terrain Analysis:Bare-earth extraction algorithms require LiDAR fusion or advanced photogrammetric filtering where vegetation cover obscures ground truth. Premium pricing attaches to hydrological flow modeling for flood risk assessment in Netherlands polder systems.
- Surveying:Georeferenced orthomosaic production with ground control point integration serves cadastral boundary disputes. Municipal authorities in India and Brazil retain preference for terrestrial verification despite aerial cost advantages.
- Inspection:Automated defect detection on transmission towers and pipeline corridors uses computer vision classifiers trained on historical failure imagery. EASA specific category compliance now embeds telemetry logging for European utility procurement.
Surveying maintains legacy revenue concentration. 3D Mapping is expanding most quickly as BIM mandates proliferate.
End User:
Customer type governs procurement modality between capital expenditure cycles and operational subscription models.
- Government Agencies:Disaster response orthomosaic generation commands concentrated budget pools for wildfire perimeter mapping and flood damage assessment. FEMA and state emergency management authorities in California and Louisiana maintain rapid-deployment contractor rosters.
- Environmentalists:Non-governmental organizations prioritize open-source processing pipelines for cost containment on restricted funding. Coastal erosion monitoring in Bangladesh and Vietnam relies on low-cost photogrammetry without LiDAR hardware investment.
- Surveyors:Traditional practices defend total station workflows through established municipal relationships. Perpetual-license desktop software retains preference among small practices in France and Spain where seasonal cash flow resists subscription conversion.
- Construction Firms:General contractors integrate aerial progress documentation into project management software for stakeholder reporting. Cloud-native processing adoption concentrates among mid-sized regional builders in the American Southeast.
Government Agencies anchor procurement volume. Construction Firms are climbing the fastest as general contracting consolidation accelerates.
Technology:
Technology stack selection hinges on accuracy requirements against hardware cost thresholds and operator training depth.
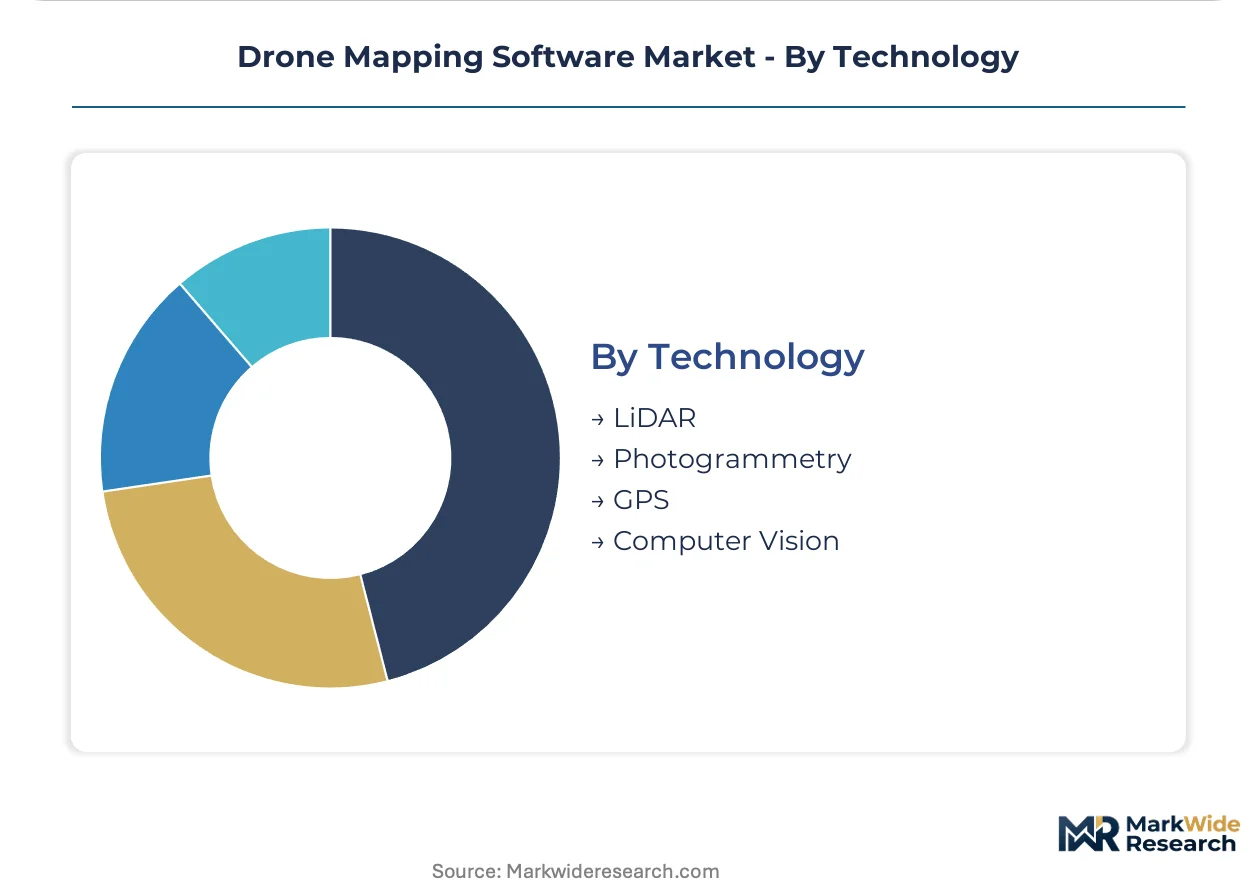
- Photogrammetry:Consumer-grade camera compatibility eliminates specialized sensor investment for engineering-grade deliverables. Algorithm advancement now achieves sub-centimeter accuracy from 20-megapixel RGB imagery in controlled ground control point environments.
- LiDAR:Direct distance measurement penetrates vegetation canopy for bare-earth extraction in forestry and hydrology applications. German and Swiss component manufacturers concentrate supply for terrain analysis where photogrammetric filtering proves insufficient.
- GPS:Real-time kinematic correction enables survey-grade georeferencing without ground control point deployment. Mining operators in remote Western Australia sites rely on satellite-based augmentation where cellular correction service is unavailable.
- Computer Vision:Automated feature extraction and change detection algorithms reduce manual interpretation labor for inspection workflows. Convolutional neural networks trained on defect libraries now classify structural anomalies on concrete and steel infrastructure.
Photogrammetry dominates unit volume. Computer Vision is gaining share fastest as automated classification displaces manual interpretation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Part 107 certification requirements anchor the United States as the regulatory template that shapes software feature roadmaps across multiple jurisdictions. Construction progress monitoring and precision agriculture drive adoption clusters in distinct geographic corridors.
United States
Commercial development in Texas and Florida compresses earthwork volume reconciliation timelines from weeks to days. FAA Part 107 mandates standardized remote pilot requirements that reduce operator training friction and expand contractor workforces. Midwest corn and soybean operations deploy sub-centimeter ground sample distance photogrammetry for variable-rate fertilization across Iowa and Illinois.
Australia
Autonomous survey fleets expand across Western Australia iron ore extraction sites and Queensland coal operations. TGA drone identification standards align with operational safety frameworks for mining logistics optimization. Perth-based contractors process orthomosaics on-site using GPU-equipped ground stations to eliminate bandwidth constraints in remote extraction locations.
Germany
Engineering consultancies mandate BIM-compatible deliverables for infrastructure inspection contracts. EASA open-category frameworks dictate flight authorization and data security requirements that vendors embed into processing pipelines. Bavarian construction firms integrate aerial progress documentation into project management software for stakeholder reporting.
China
MIIT drone identification standards and GB airworthiness protocols create parallel compliance architecture for production base access. Yangtze River Delta manufacturing clusters supply hardware components for terrain analysis applications. Shenzhen-based technology providers develop embedded geofencing for multi-territory deployment architectures.
United Kingdom
Cadastral boundary disputes sustain demand for georeferenced orthomosaic production with ground control point integration. EASA specific category requirements for operations over populated areas extend software development cycles. London engineering practices adopt cloud-native processing to displace perpetual-license desktop software among mid-sized surveyor operations.
Drone Mapping Software Market Key Industry Players
Cloud-native platforms and desktop perpetual-license providers split the market along procurement modality lines. The vendor base concentrates around photogrammetry engines and regulatory compliance modules rather than hardware integration. Established European specialists and North American cloud platforms represent distinct strategic archetypes. Competitive moves center on subscription revenue model conversion and embedded compliance feature development.
Within the cloud-native tier, DroneDeploy exemplifies browser-based processing that eliminates local workstation dependency, while Pix4D occupies a position anchoring European infrastructure inspection workflows through photogrammetry engine dominance. Agisoft Metashape represents the desktop archetype with perpetual-license pricing that appeals to cost-sensitive surveyor practices in France and Spain.
| Leading Market Players |
|---|
| DJI Terra |
| FlytBase |
| Pix4D |
| OpenDroneMap |
| Airdata |
| DroneDeploy |
| UgCS |
| 3Dsurvey |
| Agisoft Metashape |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta freight corridors channel GPU components and precision optics from Shenzhen manufacturing clusters to Western Australian mining sites, where remote logistics costs compound with EASA compliance investments to widen price spreads between cloud-native subscriptions and desktop perpetual licenses. This corridor's cost dynamics concentrate pricing power among photogrammetry engine vendors while forcing tiered differentiation based on regulatory certification depth.
Pricing Analysis
Geographic price spreads between American Midwest agricultural deployments and Western Australian mining operations reflect divergent compliance burdens and bandwidth constraints. Three-tier pricing structure across premium, standard, and economy levels separates EASA-certified inspection platforms from Part 107-compliant construction tools and open-source environmental monitoring pipelines. Cost compression in the standard tier intensifies because DroneDeploy and Pix4D compete for construction firm subscriptions with embedded project management integrations. Government agencies demonstrate least price sensitivity due to disaster-response mandate funding, while environmental NGOs exhibit highest sensitivity favoring OpenDroneMap deployments.
Supply Chain Analysis
German and Swiss export-control regimes restrict high-precision LiDAR component flows to Chinese system integrators, concentrating advanced terrain analysis hardware among specialized European manufacturers. Component supply draws from Germany, Switzerland, and China for LiDAR sensors, GPU accelerators, and flight control modules respectively. Single-source vulnerability persists in bare-earth extraction algorithms where photogrammetric filtering alternatives remain immature. Distribution runs through direct enterprise sales for mining and government verticals, while construction and agriculture segments channel through regional UAV service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone mapping software sits in early-cycle expansion as FAA Part 107 certification standardization unlocks contractor workforce scalability previously constrained by bespoke pilot training regimes.
For Market Incumbents: Insulate photogrammetry engine dominance through backward integration into GPU-equipped ground station hardware for edge processing workflows, while embedding EASA specific category compliance modules to preempt European procurement exclusion. Cloud-native platforms face margin pressure from open-source alternatives in environmental segments, warranting certification investment in ISO-compliant inspection classifiers for infrastructure verticals. For New Entrants and Emerging Players: Mid-market surveyor practices in France and Spain represent the most penetrable entry point where perpetual-license fatigue meets resistance to subscription conversion. Queensland coal logistics optimization and Kenyan wildlife corridor monitoring offer parallel white-space targets with limited incumbent saturation. Go-to-market execution should anchor in channel partnerships with regional UAV service providers rather than direct enterprise sales. For Investors and Strategic Acquirers: Carve-out targets emerge from engineering consultancy software divisions where BIM-compatible deliverable capabilities outstrip parent-company strategic focus. Long-term viability hinges on regulatory automation moats rather than algorithmic accuracy alone. Watch for FAA beyond-visual-line-of-sight rulemaking as inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Compliance Module Development | EASA telemetry logging integration secures European infrastructure inspection procurement from German engineering consultancies. |
| Edge Computing Hardware Partnership | GPU ground station alliances with Perth-based contractors eliminate bandwidth constraints in Western Australian extraction sites. |
| Open-Source Pipeline Commercialization | OpenDroneMap support services capture environmental NGO budgets in Bangladesh coastal erosion monitoring applications. |
| Multi-Territory Certification Investment | Parallel FAA Part 107 and China MIIT compliance architectures unlock Yangtze River Delta manufacturing cluster access. |
| Cloud-Native Subscription Conversion | Browser-based processing displaces Agisoft Metashape perpetual licenses among American Southeast mid-sized regional builders. |
Research Approach
Initial hypotheses were tested against primary input from remote pilot certification instructors, mining survey operations managers, construction project documentation leads, and agricultural precision technology coordinators and refined through secondary validation. FAA Part 107 examination databases, EASA open-category implementation reports, Australian TGA drone identification standards, and China MIIT airworthiness protocols anchored regulatory trajectory assessment. Bottom-up triangulation across software vendor revenue disclosures and top-down validation from UAV hardware shipment data converged on segment sizing.
Demand-supply-balance framing modeled photogrammetry algorithm advancement against LiDAR sensor availability constraints across the analysis window. Segmentation dimensions spanned application workflow, solution architecture, end-user procurement modality, and technology stack selection. CAGRs derived from installed base expansion rates in construction progress monitoring and precision agriculture corridors, cross-referenced against regulatory certification timeline assumptions and cloud processing adoption curves in seasonal cash flow environments.
Practitioners should monitor FAA beyond-visual-line-of-sight rulemaking, EASA specific category enforcement intensity, and China MIIT identification standard harmonization for early signals of platform consolidation or geographic expansion feasibility. Forecasts reflect assumptions on photogrammetry accuracy advancement and LiDAR cost curves. Material shifts in regulatory divergence timelines or GPU supply chain concentration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Non-Profit Software Market
Software & Services
RFP Software Market
Software & Services
Global Product Management and Road Mapping Tool Market
Software & Services
Global Bill of Material Management Software Market
Software & Services
Case Management Software (CMS) Market
Software & Services
Android Emulator Market
Software & Services
Curriculum Mapping Software Market
Software & Services
Data Integration Software/Tool Market
Software & Services
Automotive Operating Systems Market
Software & Services
Europe HR Payroll Software Market
Software & Services
Global Retail Sourcing and Procurement Software Market
Software & Services
UI Design Software Market
Software & Services
Executive Search (Headhunting) Software Market
Software & Services
Business Productivity Software Market
Software & Services
Canada HR Payroll Software Market
Software & Services
Mobile Application Development Market