
 Global Electronic Dictionary Market | 2026-2036
Global Electronic Dictionary Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Dictionary Market Analysis
Specialty retail channels for language-learning hardware is narrowing as direct-to-consumer platforms and educational procurement systems capture volume. Casio Computer Co. Ltd. dominates dedicated handheld dictionaries through decades of brand equity in Japanese and East Asian markets. iFLYTEK Corporation leverages voice recognition technology to differentiate its electronic dictionary products with real-time translation capabilities. ECTACO Inc. sustains niche positioning through specialized multilingual devices targeting military and government end users.
An electronic dictionary is a portable or software-based lexical reference system incorporating microprocessors, liquid crystal or e-paper displays, and structured linguistic databases to deliver instant word lookup, pronunciation guidance, and contextual translation. These devices typically operate on battery power with storage capacities ranging from several hundred thousand to millions of entries, serving educational institutions, corporate training programs, and individual language acquisition needs. Standalone devices retain substantial share in examination-heavy education systems where smartphone restrictions apply, while mobile applications capture growth among casual learners seeking subscription-based content expansion. Bilingual content types anchor revenue in East Asian markets driven by English proficiency testing requirements, whereas multilingual configurations compete in European professional segments where cross-border business communication demands broader linguistic coverage.
Japan's METI oversees electronics quality labeling and energy efficiency standards that constrain device specifications and manufacturing costs for domestic producers. China's SAMR and MIIT coordinate compulsory certification under GB standards for electronic learning products, creating compliance barriers for imported devices. The EU's RoHS and REACH frameworks restrict hazardous substances in handheld electronics, affecting component sourcing for devices sold across European markets. Stakeholders must monitor regulatory divergence between hardware certification regimes and emerging software-based dictionary applications that increasingly fall under digital service governance rather than traditional electronics standards.
Market Dynamics
Smartphone proliferation is collapsing the standalone handheld segment while examination halls and military installations sustain dedicated device demand through institutional procurement lock-ins. Regulatory fragmentation between hardware certification and software governance creates compliance bifurcation that advantages incumbent producers with established testing laboratory relationships.
Growth Catalysts
- GB Standards Compliance:China's MIIT mandates compulsory certification for electronic learning products, creating procurement preference for pre-qualified domestic and imported devices in education tenders.
- Voice Recognition Integration:Real-time speech-to-text translation capabilities embedded in handheld units address business communication needs in Japan and South Korea.
- Examination Hall Restrictions:Smartphone bans in standardized testing environments across East Asian education systems preserve captive demand for dedicated lexical reference hardware.
Market Restraints
- Lithium-Ion Cell Volatility:Battery component cost fluctuations and supply concentration in East Asian cell manufacturers squeeze margin structures for portable device producers.
- Application Substitution:Free and subscription-based mobile dictionary applications on iOS and Android platforms capture casual learners and dilute addressable market for dedicated hardware.
- REACH Compliance Burden:EU restrictions on hazardous substances in electronics force component requalification cycles that extend product development timelines for European market entry.
Strategic Opportunities
- Vietnam Education Procurement:Emerging examination infrastructure and English proficiency testing expansion create first-mover advantage for bilingual device vendors establishing distribution partnerships.
- Offline AI Edge Processing:On-device neural network inference enables translation without connectivity, addressing military and aviation use cases with stringent data security requirements.
- Institutional Leasing Models:Subscription-based hardware-as-a-service arrangements with universities and corporate training departments convert capital expenditure to recurring revenue streams.
Industry Challenges
- Lexical Database Licensing:Negotiating rights with established dictionary publishers for authoritative content creates IP friction and royalty cost uncertainty.
- GB 4943.1 Testing Backlogs:Compulsory safety certification queues at China accredited laboratories extend product launch timelines and inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Dictionary Market |
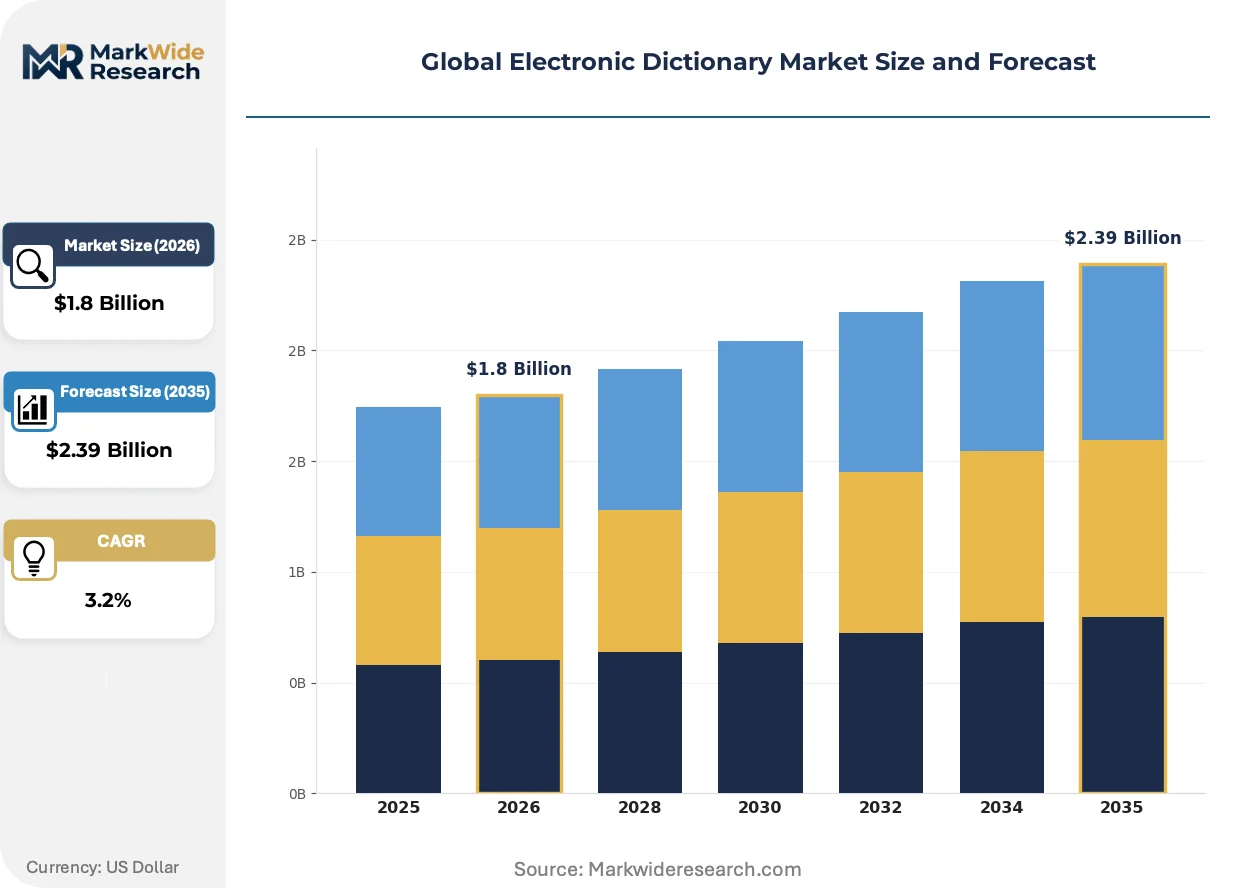
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Device, Mobile Application, Online Platform, Wireless Dictionary End User: Students, Professionals, Travelers, Language Learners Deployment: Cloud-Based, On-Premises, Hybrid, Desktop Application Content Type: Monolingual, Bilingual, Multilingual, Specialized |
| Companies Covered | Casio Computer Co. Ltd., Canon Electronic Business Machines (H.K.) Co. Ltd., ECTACO Inc., Ellton Enterprise Pte Ltd., iFLYTEK Corporation, Hanvon Technology Co. Ltd., Vasco Electronics LLC, Alfa Link, Sharp Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Dictionary Market Emerging Trajectories
E-ink display technology and edge AI inference are compressing the functional gap between dedicated devices and smartphones while regulatory divergence between hardware and software governance accelerates product architecture decisions. Procurement patterns in institutional segments are fragmenting across direct-to-educator platforms and traditional distributor networks.
Neural machine translation on low-power edge processors is collapsing the latency and accuracy differential that previously justified cloud-connected smartphone applications. Japanese examination preparation centers and South Korean corporate training facilities are adopting these devices for secure-environment deployment. The technology is collapsing premium pricing tiers for real-time bilingual communication hardware.
China's MIIT and SAMR coordination on GB standards for electronic learning products is tightening electromagnetic compatibility and safety requirements. Domestic producers with established testing relationships capture procurement preference in education sector tenders. Imported devices face extended certification timelines and laboratory queue congestion that disadvantage new market entrants.
Educational procurement in Japan and South Korea is fragmenting across ministry-level bulk purchasing, municipal education authority tenders, and individual school discretionary budgets. Traditional electronics distributors lose volume to direct manufacturer relationships with examination boards and institutional buyers. This pattern is most visible in urban China where provincial education commissions consolidate purchasing power while retaining device specification autonomy.
Global Electronic Dictionary Market Segmentation
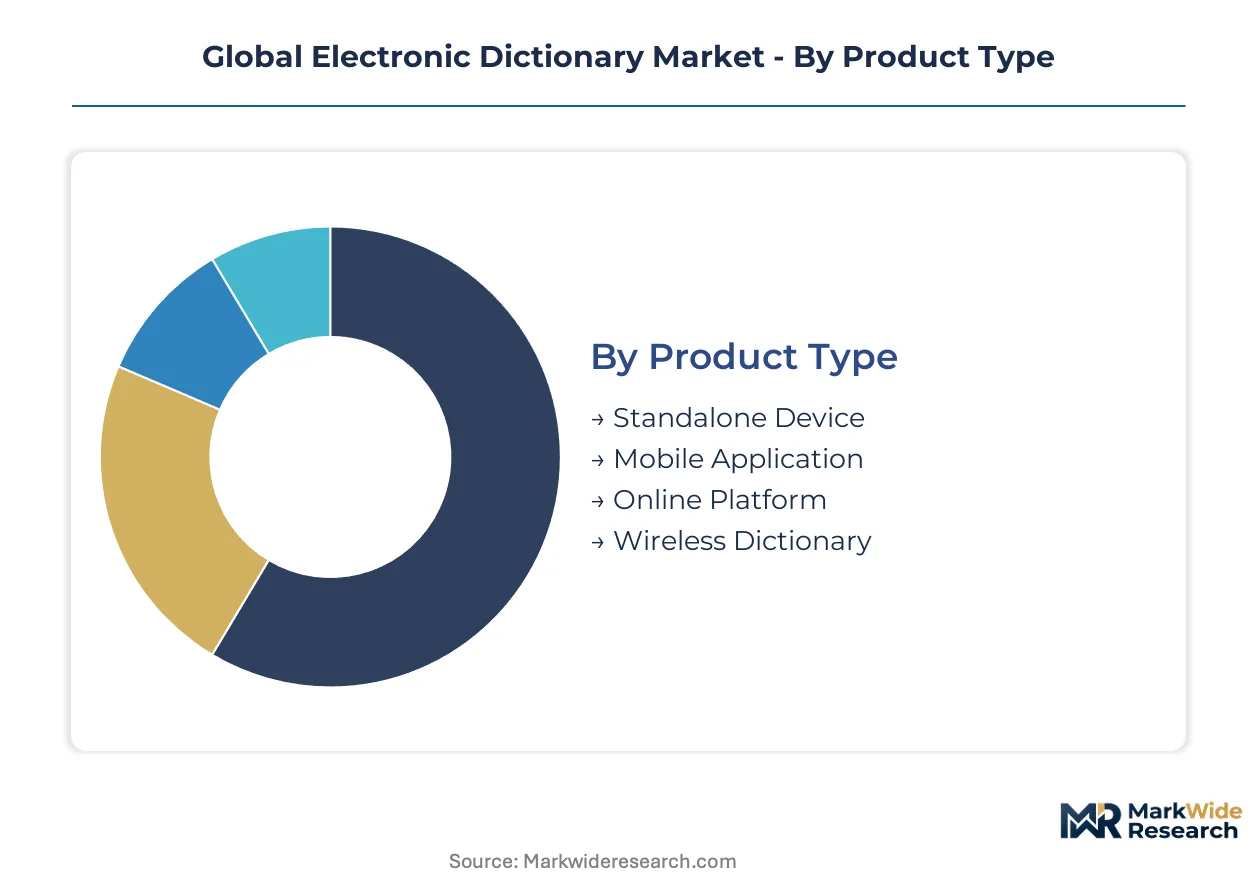
Electronic dictionary segmentation reveals divergent hardware-software economics and regulatory exposure across form factors. Procurement patterns fragment sharply between institutional buyers seeking certified standalone units and individual consumers migrating to subscription-based mobile platforms.
Product Type:
After-sales-service intensity varies dramatically across hardware and software delivery models, with standalone devices requiring repair networks and cloud platforms demanding uptime guarantees.
- Standalone Device:Handheld units incorporate e-paper or LCD displays, lithium-ion power systems, and offline lexical databases. Procurement concentrates in Japanese and South Korean education sectors where examination hall smartphone bans preserve institutional demand.
- Mobile Application:iOS and Android deployments leverage smartphone penetration to capture casual learners through freemium subscription models. User acquisition costs dominate economics as voice recognition and neural translation features displace basic lookup functionality.
- Online Platform:Browser-based access with cloud-stored dictionaries and collaborative editing tools serves corporate training departments.
- Wireless Dictionary:Wi-Fi or cellular-connected handhelds bridge offline reliability with dynamic content updates for business travelers.
Standalone Device holds the largest share; momentum sits with Mobile Application.
End User:
Customer acquisition costs stratify sharply between examination-driven institutional procurement and discretionary individual purchases.
- Students:Primary and secondary education systems in urban China and Japan drive volume through ministry-level tenders. Device specifications align with curriculum standards and testing authority requirements.
- Professionals:Corporate training budgets in South Korea and cross-border business users in European markets prioritize real-time translation accuracy and specialized terminology databases.
- Travelers:Casual international visitors favor smartphone applications with offline packs over dedicated hardware.
- Language Learners:Self-directed study participants span all age cohorts, with subscription retention rates determining platform profitability.
Students command the largest installed base; Professionals are expanding most quickly.
Deployment:
Data sovereignty requirements and connectivity reliability shape architecture decisions across military, aviation, and education use cases.
- Cloud-Based:Centralized lexical databases and machine translation APIs enable continuous model improvement. Latency constraints limit adoption in examination environments with connectivity restrictions.
- On-Premises:Local server installations serve defense and intelligence agencies with classified network requirements. Hardware procurement follows specialized security certification protocols.
- Hybrid:Edge caching with cloud fallback balances offline functionality against content freshness for corporate deployments.
- Desktop Application:Institutional site licenses for Windows and macOS persist in university library systems and translation bureaus.
Cloud-Based dominates new deployments; On-Premises retains premium pricing in security-sensitive segments.
Content Type:
Licensing economics and editorial investment intensity separate commodity bilingual offerings from authoritative specialized databases.
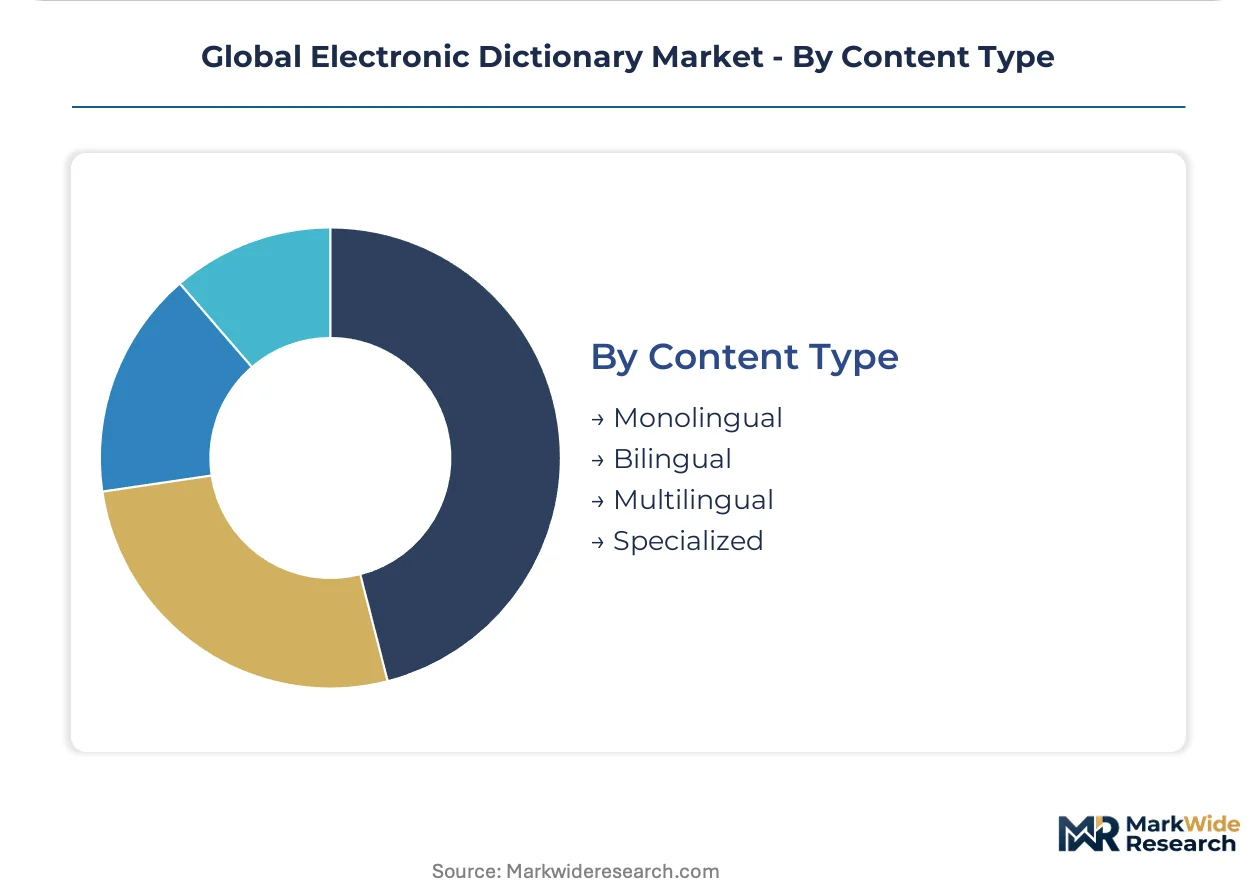
- Bilingual:English paired with Japanese, Korean, or Mandarin anchors revenue in East Asian markets driven by proficiency testing requirements. Royalty negotiations with established dictionary publishers constrain margin expansion.
- Multilingual:Five-plus language configurations target European Union cross-border professionals and international organization staff. Database maintenance costs scale non-linearly with language count.
- Monolingual:Advanced native-language dictionaries serve academic researchers and editorial professionals seeking etymological depth.
- Specialized:Medical, legal, and technical terminology databases command subscription premiums from professional practitioners.
Bilingual captures the greatest volume; Specialized shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT enforces GB standards that reshape procurement preferences across East Asian education systems. Japan's METI oversees electronics quality labeling that constrains domestic manufacturing specifications. South Korea's MFDS coordinates device safety protocols alongside national English proficiency testing expansion.
China
Urban education commissions in Beijing, Shanghai, and Guangzhou drive bilingual handheld procurement for gaokao and English proficiency examinations. SAMR and MIIT coordinate compulsory GB 4943.1 safety certification that creates laboratory queue backlogs for imported devices. The Yangtze River Delta manufacturing cluster hosts domestic producers with established testing relationships that capture ministry-level tenders.
Japan
Examination preparation centers and corporate training facilities sustain demand for secure-environment lexical hardware. METI administers electronics quality labeling and energy efficiency standards that constrain device specifications and manufacturing costs. The Kanto region around Tokyo concentrates distribution networks serving ministry-level bulk purchasing and municipal education authority tenders.
South Korea
Corporate training budgets and suneung examination requirements preserve institutional procurement of dedicated translation devices. MFDS oversees medical and electronic device safety frameworks applicable to learning hardware. The Seoul Capital Area anchors both device distribution and voice recognition technology development for real-time bilingual communication.
United States
Military and defense installations sustain demand for offline-capable multilingual reference systems with stringent data security requirements. The Department of Defense procurement protocols favor on-premises deployment architectures. The Washington DC corridor and Texas defense clusters host specialized vendors serving government end users with classified network requirements.
Germany
Cross-border business communication within the European Union drives demand for multilingual configurations. ECHA administers REACH restrictions on hazardous substances that force component requalification cycles for electronics manufacturers. The Rhine-Ruhr industrial region and Bavarian technology corridors concentrate corporate training procurement and specialized terminology database licensing.
Global Electronic Dictionary Market Vendor Landscape
On the supply side, the industry is bifurcated between entrenched handheld hardware specialists and emerging voice-recognition platform operators. Decades of brand equity in East Asian education systems sustain incumbent positions despite smartphone proliferation. Three strategic archetypes dominate: examination-focused hardware manufacturers, voice-technology integrators, and specialized government contractors. Competitive dynamics center on certification laboratory relationships and lexical database licensing negotiations rather than price-based rivalry.
Within the established hardware tier, Casio Computer Co. Ltd. exemplifies the examination-market archetype through sustained presence in Japanese and East Asian education procurement. iFLYTEK Corporation occupies a position at the voice-technology frontier, representing the shift toward real-time speech recognition capabilities. ECTACO Inc. anchors the specialized government contractor segment, serving military and intelligence end users with multilingual offline systems. These three entities collectively illustrate the market's segmentation across institutional, technological, and security-sensitive demand vectors.
| Leading Market Players |
|---|
| Casio Computer Co. Ltd. |
| Canon Electronic Business Machines (H.K.) Co. Ltd. |
| ECTACO Inc. |
| Ellton Enterprise Pte Ltd. |
| iFLYTEK Corporation |
| Hanvon Technology Co. Ltd. |
| Vasco Electronics LLC |
| Alfa Link |
| Sharp Corporation |
| Others |
Supply Flow & Price Mechanics
Lithium-ion cell manufacturing concentration in China, South Korea, and Japan anchors cost structures for handheld electronic dictionaries, with battery pack expenses consuming disproportionate margin pools in economy-tier devices while premium units absorb volatility through brand premium capture.
Pricing Analysis
Volume-discount tiering structures dominate institutional procurement, with education ministry tenders commanding standard-tier pricing at scale while individual retail purchases face premium markups. Price differentiation rests on GB 4943.1 certification status and voice recognition capability integration, with certified devices capturing procurement preference. Cost compression in the wireless dictionary segment is intensifying because smartphone substitution erodes willingness-to-pay for connectivity features. Students in examination-heavy systems show lowest price sensitivity due to institutional budget absorption, whereas casual travelers exhibit highest elasticity.
Supply Chain Analysis
Upstream feedstock for e-paper displays and edge AI processors draws from Taiwan, South Korea, and Japan, with semiconductor fabrication and display panel manufacturing anchoring component costs. Lexical database licensing fees, lithium-ion battery cells, and electromagnetic shielding materials constitute critical input dependencies. Single-source vulnerability concentrates in specialized e-ink display supply, where alternative qualified suppliers remain limited. Distribution runs through direct manufacturer relationships with examination boards and education commissions, bypassing traditional electronics distributors in urban China and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory certification entrenchment creates switching costs that lock institutional buyers into pre-qualified supplier relationships.
For Market Incumbents: Build certification laboratory relationship moats by deepening GB standards pre-qualification with China's MIIT-accredited testing bodies. Incumbents should secure exclusive lexical database licensing with established dictionary publishers to block entrant access to authoritative content. Voice recognition platform entrants threaten hardware-centric margins; counter by embedding offline AI edge processing to match capability without connectivity dependency. For New Entrants and Emerging Players: Vietnam's expanding examination infrastructure and English proficiency testing adoption represents the most penetrable white-space geography. New entrants should pursue distribution partnerships with provincial education authorities before domestic incumbents consolidate relationships. A specialized multilingual device targeting military and aviation use cases with stringent data security requirements offers alternative entry path around examination-market saturation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with voice-recognition platform operators seeking hardware manufacturing capabilities to complete vertical integration. Long-term viability over a five-to-ten year window hinges on institutional procurement retention against smartphone substitution. Watch for inflection signals in GB standards enforcement intensity, as tightened certification timelines would advantage incumbents with established laboratory relationships.| Strategic Initiative | Industry Significance |
|---|---|
| GB Standards Pre-Qualification Investment | MIIT certification lock-in secures education ministry tender access against imported competition. |
| Lexical Database Exclusive Licensing | Publisher royalty agreements with Oxford or Merriam-Webster block entrant content access. |
| Offline AI Edge Processing Integration | On-device neural translation addresses military data security requirements without cloud dependency. |
| Direct Examination Board Partnerships | Bypassing distributors captures ministry-level procurement volume in Japan and South Korea. |
| Vietnam Distribution Network Establishment | First-mover positioning in emerging English proficiency testing infrastructure builds regional anchor. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with education procurement officers, handheld device product managers, GB standards testing laboratory directors, and lexical database licensing executives. Secondary validation drew from MIIT certification registries, METI electronics quality labeling databases, REACH substance restriction filings, and customs trade records for electronic learning product categories. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Calibration approaches anchored volume projections to historical procurement patterns across education sector tenders and corporate training budgets. Segmentation dimensions modeled include product type, deployment architecture, content language configuration, and end-user institutional versus individual purchase behavior. CAGRs were derived from trend extrapolation moderated by smartphone substitution elasticity and regulatory certification timeline assumptions. Voice recognition adoption curves and e-ink display cost trajectories provided industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by voice-recognition platform operators into hardware manufacturing would shift outcomes beyond modeled ranges. Material shifts in GB standards enforcement intensity or REACH substance restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
UI Design Software Market
Software & Services
Global Archiving Software Market
Software & Services
Architectural Rendering Software Market
Software & Services
Eclinical Solutions and Software Market
Software & Services
Stock Footage Software Market
Software & Services
Spend Analysis Software Market
Software & Services
Customer Advocacy Software Market
Software & Services
Asia-Pacific Saas-Based SCM Market
Software & Services
Middle East and Africa Automotive Software Market
Software & Services
Server Software Market
Software & Services
VFX Software Market
Software & Services
Freight Forwarding Software Market
Software & Services
Africa HR Payroll Software Market
Software & Services
Tenant Billing System Market
Software & Services
AR Remote Collaboration Software Market
Software & Services
API Testing Market