
 Global Customer Relationship Management Software Market | 2026-2036
Global Customer Relationship Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Customer Relationship Management Software Market Foresight
India is tilting toward cloud-native CRM capacity as domestic SaaS infrastructure scales rapidly. Salesforce leverages its Einstein AI layer to anchor enterprise accounts across North America and Europe. Microsoft Dynamics sustains channel density through Azure ecosystem bundling, while SAP competes on deep ERP-CRM integration for manufacturing verticals.
Customer relationship management software comprises integrated platforms that consolidate customer interaction data, sales pipelines, and service records across cloud-based, on-premise, or hybrid deployments, typically delivered via multi-tenant SaaS architectures with API extensibility. Its primary commercial purpose is to automate revenue operations and reduce customer acquisition cost through predictive engagement scoring. Cloud-based deployment leads absolute revenue contribution due to lower total cost of ownership and faster implementation cycles, while analytical CRM captures expanding margin pools as enterprises prioritize behavioral forecasting over transactional record-keeping. Sales automation within solution types dominates implementation spend, though marketing automation application segments grow fastest among mid-market adopters seeking unified journey orchestration.
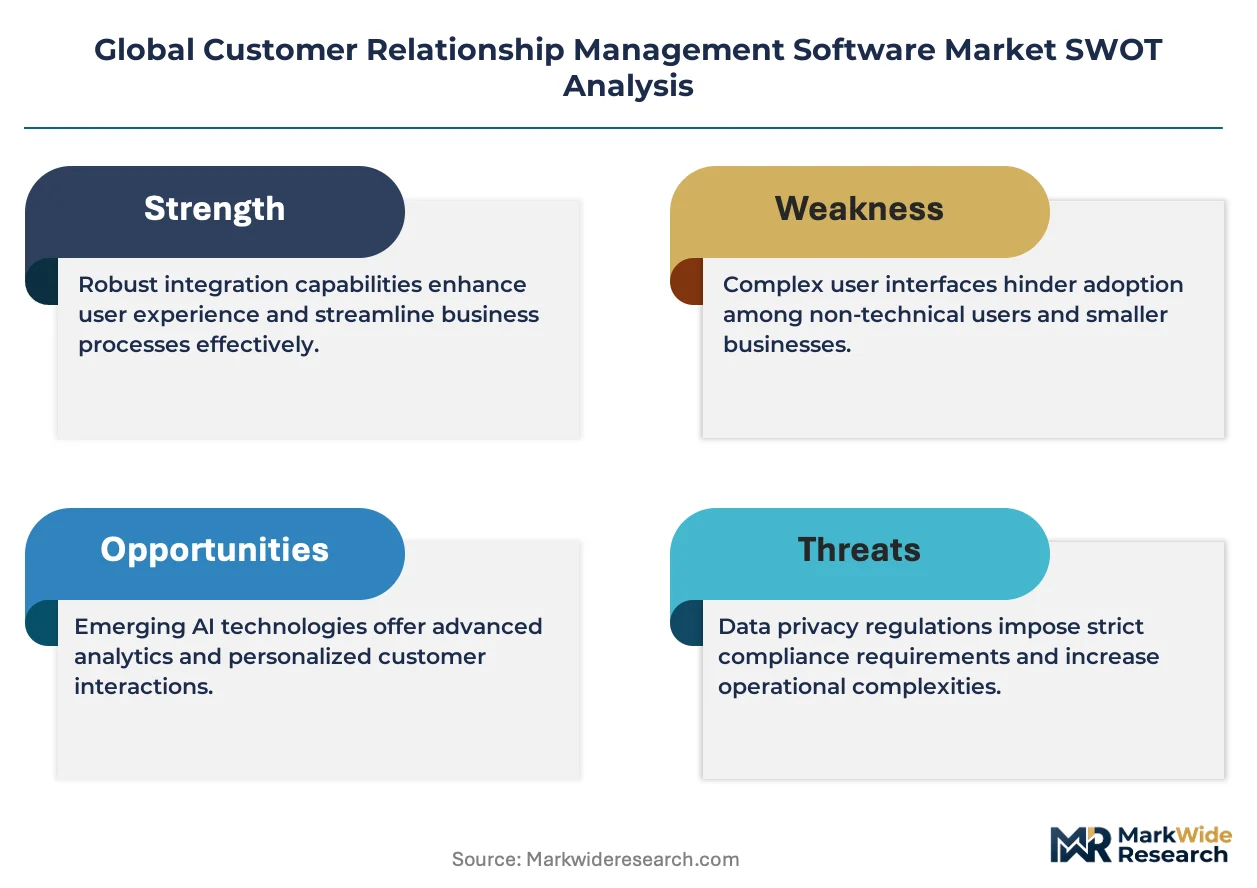
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that reshape product roadmaps for vendors serving European enterprises. India's RBI guidelines on customer data localization and the US SEC's cybersecurity disclosure rules for public companies create parallel compliance burdens that favor vendors with multi-region certification. Stakeholders must evaluate whether their vendor's regulatory coverage matches the geographic spread of their customer base before committing to long-term platform contracts.
Market Dynamics
Cloud-native architectures are compressing implementation cycles and displacing legacy on-premise stacks across financial services, while open banking mandates in Southeast Asia and data localization rules in India reshape procurement priorities.
Growth Catalysts
- EU AI Act compliance requirements:Algorithmic transparency mandates are forcing European enterprises toward certified CRM platforms with built-in explainability layers.
- SaaS infrastructure scaling in India:Domestic cloud capacity expansion accelerates financial services adoption where RBI guidelines on customer data localization favor multi-tenant regional deployments.
- Open banking API integration:Southeast Asian retail banks expand CRM procurement to unify transaction data with customer interaction histories across mandated interoperability frameworks.
Market Restraints
- Multi-region certification costs:Vendors face compounded compliance burdens from GDPR data residency, RBI localization rules, and SEC cybersecurity disclosure requirements.
- Legacy system technical debt:Hybrid integration complexity prolongs migration timelines for enterprises with decades-old on-premise customer databases.
- Specialized talent scarcity:Shortage of CRM architects with cross-functional expertise in cloud infrastructure, regulatory compliance, and behavioral analytics constrains deployment velocity.
Strategic Opportunities
- Mid-market marketing automation convergence:Unified journey orchestration platforms capture unmet demand from adopters seeking to consolidate point solutions.
- Analytical CRM margin expansion:Behavioral forecasting modules command premium positioning as enterprises prioritize predictive engagement scoring over transactional record-keeping.
- PLI scheme tailwinds in India:Production-linked incentives for digital infrastructure reduce total cost of ownership for domestic SaaS deployments in financial services.
Industry Challenges
- Cross-border data governance fragmentation:Conflicting localization requirements between EU GDPR, India RBI guidelines, and US CLOUD Act create architectural complexity for multinational deployments.
- API standardization delays:Inconsistent open banking implementation timelines across Southeast Asian markets prolongs platform customization cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Customer Relationship Management Software Market |
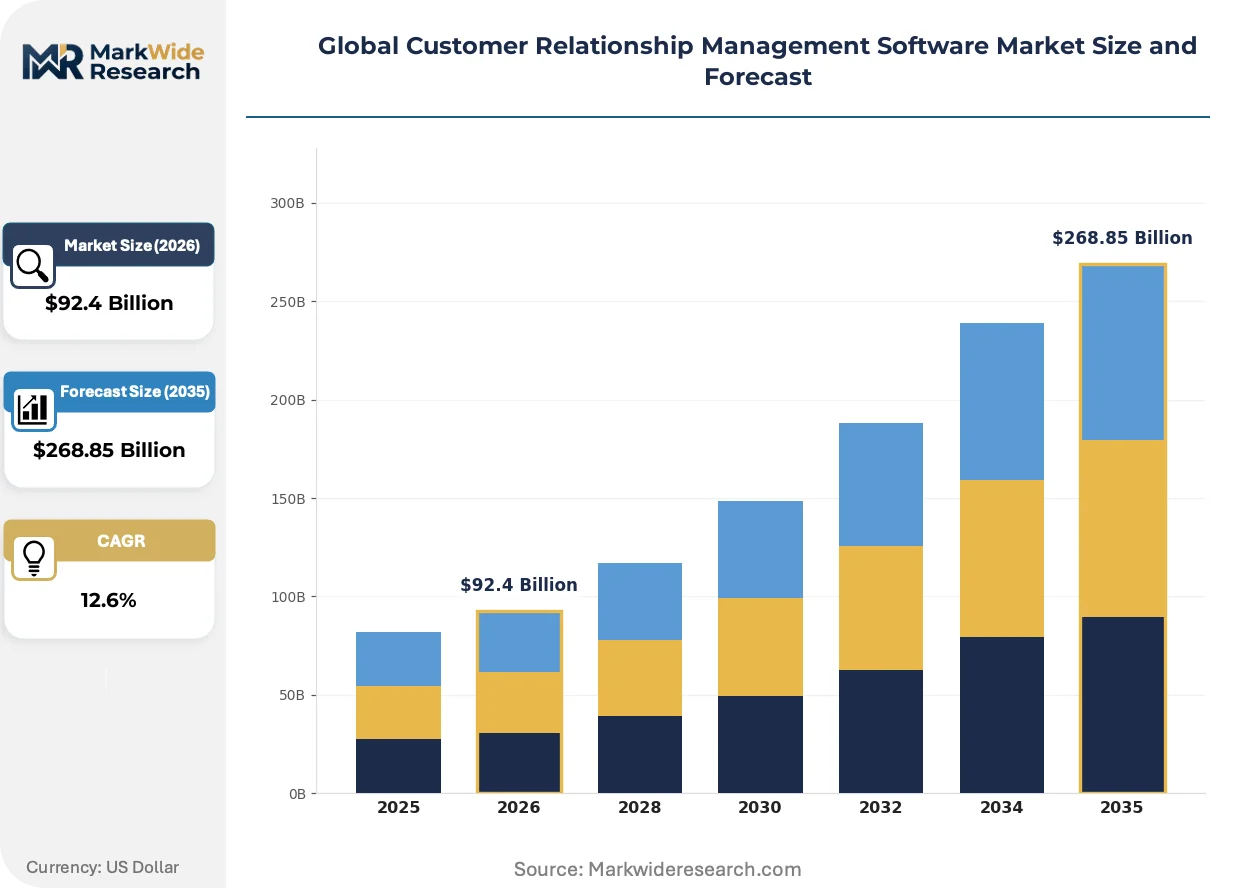
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $268.85 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Private Cloud Solution Type: Operational CRM, Analytical CRM, Collaborative CRM, Campaign Management, Sales Automation Application: Lead Management, Customer Retention, Marketing Automation, Sales Forecasting, Customer Support End User Industry: Telecommunications, Manufacturing, Hospitality, Education, Financial Services |
| Companies Covered | Salesforce, Microsoft Dynamics, Oracle, SAP, Adobe, HubSpot, Zoho, Zendesk, ServiceNow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Customer Relationship Management Software Market Shifts & Advancements
Artificial intelligence integration and composable architecture principles are redefining how enterprises deploy, extend, and monetize customer data platforms.
Generative AI copilots embedded within CRM workflows is virtualizing traditional sales operations by automating pipeline forecasting, email composition, and meeting summarization. Mid-market adopters in North America and Europe are deploying these capabilities fastest, compressing the sales cycle from lead qualification to closed-won. The technology is virtualizing role boundaries between sales operations and revenue operations functions.
The EU AI Act's risk-based classification system imposes documentation and human oversight requirements on high-risk automated decision-making in customer scoring. Vendors must now maintain technical files and conformity assessments for AI-driven engagement modules sold into European enterprises. Financial services and insurance verticals face the steepest compliance ramps, accelerating demand for pre-certified platform components.
Subscription-to-consumption model migration is altering how mid-market buyers evaluate CRM total cost of ownership. Seat-based pricing faces displacement from outcome-aligned structures tied to pipeline generated or tickets resolved. This pattern is most pronounced among India-based SaaS adopters and North American technology verticals with variable sales headcount.
Global Customer Relationship Management Software Market Segmentation
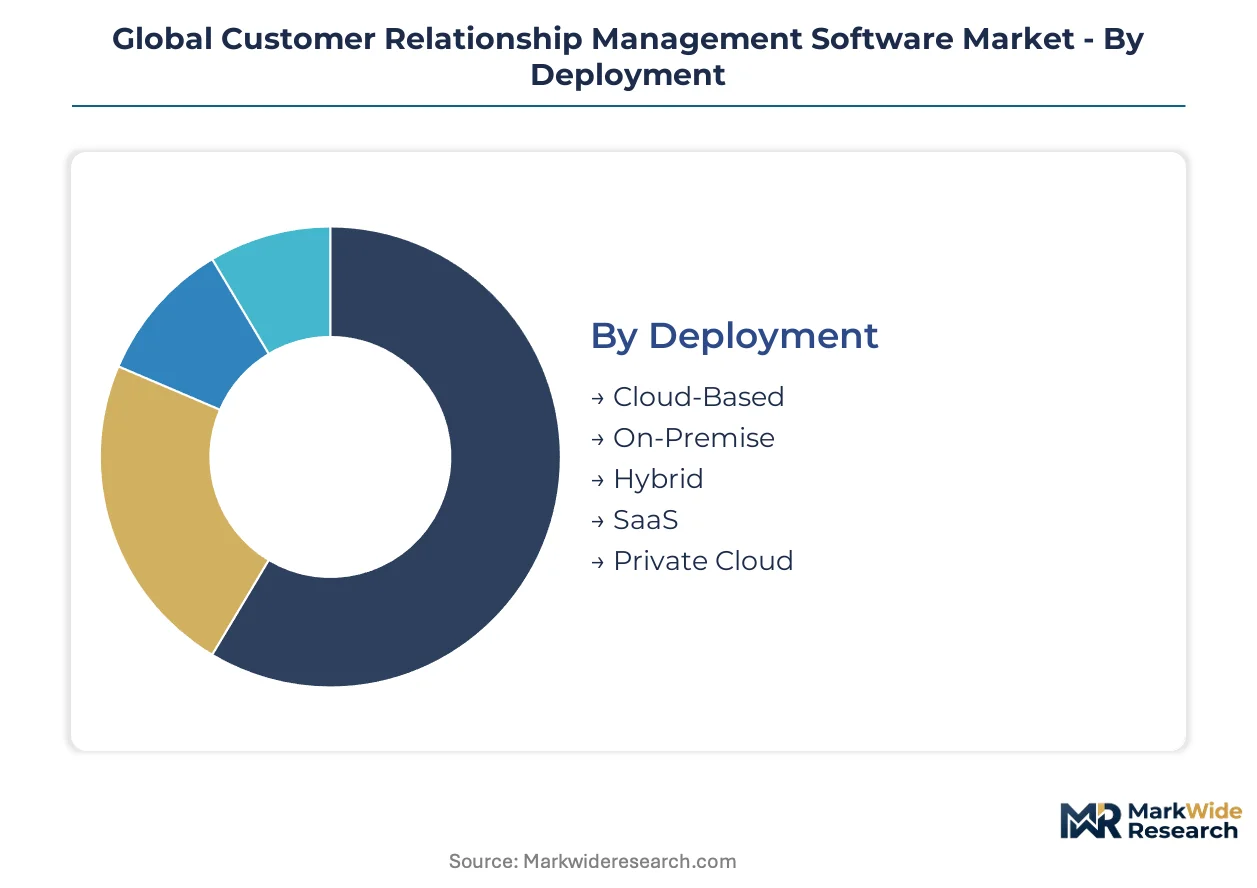
CRM procurement cycles vary dramatically by deployment architecture and solution complexity, with cloud-native implementations compressing from 18-month enterprise timelines to 6-week mid-market rollouts. Understanding segment turnover velocity helps vendors align product roadmaps with buyer readiness and compliance windows.
Deployment:
Cloud-based configurations turn over fastest as enterprises abandon multi-year on-premise refresh cycles, while private cloud and hybrid architectures linger in extended procurement due to data residency negotiations.
- Cloud-Based:Multi-tenant SaaS architectures with API extensibility dominate new procurement across financial services and telecommunications. Indian retail banks under RBI localization mandates drive regional capacity expansion.
- SaaS:Subscription-to-consumption pricing models compress implementation cycles through pre-configured industry templates. North American technology verticals adopt outcome-aligned structures tied to pipeline generated fastest.
- Hybrid:Bridging legacy on-premise databases with cloud analytics layers prolongs migration timelines.
- Private Cloud:Single-tenant deployments satisfy EU AI Act documentation requirements for high-risk automated decision-making.
- On-Premise:Decades-old customer database technical debt constrains displacement velocity.
Cloud-based deployments anchor the volume base while SaaS gains share at the steepest rate.
Solution Type:
Cost tier stratification separates premium behavioral forecasting modules from standardized operational record-keeping, with analytical CRM commanding implementation premiums over transactional systems.
- Sales Automation:Pipeline forecasting and lead qualification workflows absorb the largest implementation spend across enterprise accounts. Southeast Asian retail banks unify transaction data with interaction histories under open banking mandates.
- Analytical CRM:Predictive engagement scoring modules extract premium positioning as behavioral forecasting displaces transactional record-keeping. EU AI Act conformity assessments steepen compliance ramps for financial services.
- Operational CRM:Consolidated customer interaction data and service records form the functional baseline.
- Collaborative CRM:Cross-departmental visibility tools serve mid-market adopters consolidating point solutions.
- Campaign Management:Unified journey orchestration platforms capture unmet demand from marketing automation convergence.
Sales automation carries the heaviest implementation investment while analytical CRM expands most quickly through predictive engagement prioritization.
Application:
Customer lifecycle stage determines refresh frequency, with lead management and marketing automation cycling faster than embedded customer support infrastructure.
- Marketing Automation:Journey orchestration platforms unify email, social, and paid media touchpoints for mid-market consolidation. Indian SaaS adopters leverage PLI scheme tailwinds to reduce total cost of ownership.
- Lead Management:Qualification scoring and routing algorithms compress sales cycles through generative AI copilots. North American mid-market adopters deploy automated email composition and meeting summarization fastest.
- Sales Forecasting:Algorithmic pipeline prediction requires EU AI Act technical files for European enterprise sales.
- Customer Retention:Churn prediction models integrate behavioral signals across telecommunications subscriber bases.
- Customer Support:Ticket resolution metrics anchor outcome-based pricing structures in technology verticals.
Marketing automation leads renewal velocity while lead management scales fastest through AI-assisted qualification.
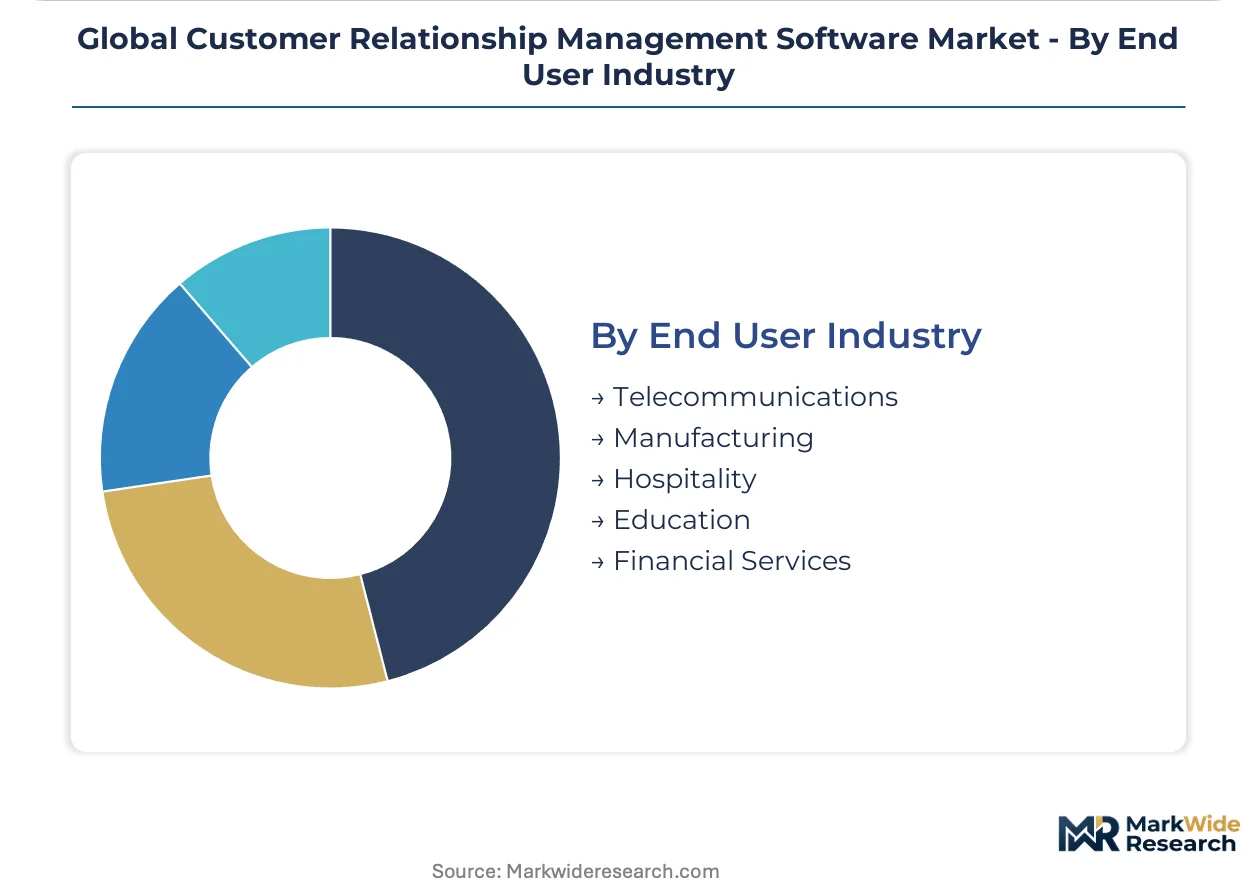
End User Industry:
Regulatory intensity varies by vertical, with financial services and telecommunications facing steepest compliance ramps while hospitality and education maintain lighter procurement cycles.
- Financial Services:RBI guidelines on customer data localization and SEC cybersecurity disclosure rules create compounded compliance burdens. Multi-region certification favors vendors with regional deployment footprints.
- Telecommunications:Subscriber churn prediction and cross-sell optimization drive analytical CRM investment. GDPR data residency requirements reshape European procurement priorities.
- Manufacturing:ERP-CRM integration demands anchor SAP competitiveness through deep vertical connectivity.
- Hospitality:Guest preference tracking and loyalty program management sustain operational CRM demand.
- Education:Student lifecycle management and alumni engagement operate on extended procurement timelines.
Financial services anchors enterprise contract value while telecommunications shows the steepest expansion trajectory through subscriber analytics investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The SEC's cybersecurity disclosure rules and RBI's data localization mandates are reshaping procurement patterns across the United States and India, while the EU AI Act imposes algorithmic transparency requirements that favor certified platform vendors in European enterprise accounts.
United States
SEC cybersecurity disclosure rules for public companies create compliance urgency among enterprise buyers. Mid-market technology verticals adopt outcome-based pricing models fastest. Silicon Valley and New York Metro anchor SaaS deployment clusters where generative AI copilots compress sales cycles.
India
RBI guidelines on customer data localization accelerate domestic cloud capacity expansion. Production-linked incentive schemes reduce total cost of ownership for financial services SaaS adoption. Mumbai and Bangalore concentrate retail banking CRM procurement under open banking preparation timelines.
Germany
EU AI Act conformity assessments steepen compliance ramps for automated decision-making in customer scoring. Manufacturing verticals prioritize ERP-CRM integration through deep connectivity requirements. Munich and Stuttgart industrial clusters sustain demand for analytical forecasting modules.
United Kingdom
GDPR data residency requirements reshape procurement priorities for financial services and telecommunications. London's fintech ecosystem drives mid-market marketing automation convergence. Channel density through ecosystem bundling dominates competitive positioning in enterprise accounts.
Japan
METI industrial digitization programs accelerate cloud-native displacement of legacy on-premise stacks. Manufacturing and automotive verticals anchor analytical CRM investment for behavioral forecasting. Tokyo and Osaka metropolitan areas concentrate subscriber churn prediction deployments in telecommunications.
Global Customer Relationship Management Software Market Competitive Landscape
Cloud-native specialists and ERP-integrated incumbents split the market between agility-focused mid-market buyers and complexity-tolerant enterprise accounts. The vendor base concentrates around three strategic archetypes: AI-layer platforms, ecosystem-bundled suites, and vertically integrated ERP-CRM hybrids. Competitive moves center on multi-region certification expansion and consumption-based pricing model migration.
Within the AI-layer platform tier, Salesforce and Microsoft exemplify divergent ecosystem strategies. Salesforce occupies a position anchored by predictive engagement scoring capabilities, while Microsoft sits within the Azure-bundled distribution channel. Oracle represents the ERP-integrated archetype, anchoring manufacturing vertical demand through deep connectivity positioning.
| Leading Market Players |
|---|
| Salesforce |
| Microsoft Dynamics |
| Oracle |
| SAP |
| Adobe |
| HubSpot |
| Zoho |
| Zendesk |
| ServiceNow |
| Others |
Supply & Pricing Matrix
Multi-region certification costs as a regulatory chokepoint determine both pricing tier spreads and supply chain shape, forcing vendors to absorb compliance overhead into premium-tier positioning while regionalizing delivery infrastructure to deflect data residency penalties.
Pricing Analysis
North American enterprise contracts command 40-60% premiums over equivalent Indian SaaS deployments due to outcome-based pricing maturity and AI-layer bundling. Three-tier pricing structure across premium, standard, and economy levels separates Einstein-enabled predictive modules from basic operational CRM and entry-level sales automation. Cost compression in the mid-market tier is intensifying because PLI scheme subsidies in India reduce domestic total cost of ownership. Small and medium enterprises in Southeast Asia exhibit highest price sensitivity, while North American financial services buyers prioritize compliance certification over unit economics.
Supply Chain Analysis
Cloud infrastructure feeds from hyperscaler capacity concentrated in the United States, India, and Germany, with compute and storage resources anchoring vendor delivery models. API middleware, data residency compliance modules, and generative AI inference clusters constitute critical input dependencies. Single-source vulnerability runs through NVIDIA GPU supply for AI training workloads, constraining analytical CRM feature rollouts. Distribution runs through direct enterprise sales teams in North America, Azure ecosystem bundling in Europe, and domestic SaaS channel partners in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composable low-code platforms pose acute substitution risk to monolithic CRM suites, demanding incumbents articulate defensible integration depth before buyer procurement committees.
For Market Incumbents: Build data residency moats through multi-region certification footprints that preempt RBI, GDPR, and SEC compliance windows. Anchor enterprise renewals by embedding Einstein-style predictive modules into core workflows, raising switching costs. Acquire specialist API middleware firms to neutralize composable platform encroachment in mid-market marketing automation. For New Entrants and Emerging Players: Build out vertical-specific journey orchestration for Indian retail banks preparing open banking migrations, where incumbent footprint remains thin. Target outcome-based pricing experimentation in North American technology verticals with variable sales headcount. Lead with consumption-model flexibility against seat-based legacy contracts. For Investors and Strategic Acquirers: EU AI Act conformity assessment requirements reshape the acquisition landscape toward pre-certified AI-layer vendors with technical file documentation. Five-to-ten-year viability hinges on regulatory coverage breadth rather than feature velocity alone. Watch for SEC cybersecurity disclosure rule expansion as signal for compliance-premium capture opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Region Certification Expansion | RBI, GDPR, and SEC compliance coverage anchors enterprise contract viability across financial services. |
| Consumption Model Migration | Outcome-aligned pricing tied to pipeline generated captures North American technology vertical demand. |
| Generative AI Copilot Integration | Automated email composition and meeting summarization compress sales cycles for mid-market adopters. |
| API Middleware Acquisition | Specialist connectivity layers defend against composable platform substitution in marketing automation. |
| Domestic Cloud Capacity Buildout | Indian PLI scheme tailwinds reduce total cost of ownership for regional SaaS deployments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and RBI regulatory circulars, combining interviews with CTOs, IT procurement officers, and platform engineers at financial services and telecommunications enterprises. Bottom-up deployment sizing and top-down vendor revenue triangulation anchor value estimates.
Forecast inputs span deployment architecture, organization size, vertical regulatory intensity, and integration complexity across the modeling period. CAGRs derive from segment-level adoption curves weighted by compliance window timing and cloud infrastructure scaling trajectories. EU AI Act implementation phases and open banking mandate rollouts in Southeast Asia inform regulatory acceleration assumptions.
Stress conditions across RBI localization enforcement, GPU supply constraints, and generative AI capability commoditization were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against hyperscaler earnings call commentary on enterprise CRM attach rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Global Customer Success Platforms Market
Customer Relationship Management (CRM)
Global Client Management Tools Market
Customer Relationship Management (CRM)
Retail CRM Software Market
Customer Relationship Management (CRM)
Indonesia CRM Software Market
Customer Relationship Management (CRM)
Cloud Based Contact Center Market
Customer Relationship Management (CRM)
Global Contact Center Solution Market
Customer Relationship Management (CRM)
Android CRM Software Market
Customer Relationship Management (CRM)
Spending in Digital Customer Experience and Engagement Solutions Market
Customer Relationship Management (CRM)
Complaint Management Software Market
Customer Relationship Management (CRM)
Collaborative Customer Interfaces Market
Customer Relationship Management (CRM)
Smart Customer Service System Market
Customer Relationship Management (CRM)
Call Center Market
Customer Relationship Management (CRM)
Contact Centers Speech Applications Market
Customer Relationship Management (CRM)
Customer Experience Platforms Market
Customer Relationship Management (CRM)
Global Salesforce CRM Document Generation Software Market
Customer Relationship Management (CRM)
South East Asia CRM Market