
 Global Home Health Care Services Market | 2026-2036
Global Home Health Care Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Home Health Care Services Market Foresight
India is narrowing its skilled nursing workforce gap through government-backed training institutes and public-private partnerships in tier-two cities. Amedisys leverages its Medicare-certified footprint across southern US states to sustain recurring revenue density. LHC Group anchors its position through joint-venture hospital partnerships that embed discharge planning into acute-care workflows. Kindred Healthcare competes on post-acute episode management, differentiating through bundled-payment contracts with Medicare Advantage plans.
Home health care services encompass medically necessary skilled care delivered in a patient's residence by licensed professionals under physician oversight, including wound care, infusion therapy, and mobility rehabilitation with clinical documentation transmitted through interoperable EHR systems. The primary purpose is to reduce preventable hospital readmissions while maintaining clinical outcomes equivalent to institutional settings. Skilled nursing occupies the largest revenue pool due to reimbursement weighting for complex clinical tasks, while telehealth services represent the fastest-expanding delivery model as remote physiological monitoring achieves parity with in-person vital assessment. Post-surgery patients generate concentrated demand spikes tied to elective procedure backlogs and accelerated discharge protocols.
CMS Conditions of Participation govern Medicare-certified agency operations in the United States, mandating specific clinical assessment frequencies and OASIS data submission that directly determine reimbursement rates and market access eligibility. EMA guidance on digital health technologies and Japan's PMDA framework for remote monitoring devices are converging on software-as-medical-device classifications that reshape product standards across export markets. Stakeholders must monitor how reimbursement parity between virtual and in-person encounters evolves under divergent national health technology assessment regimes.
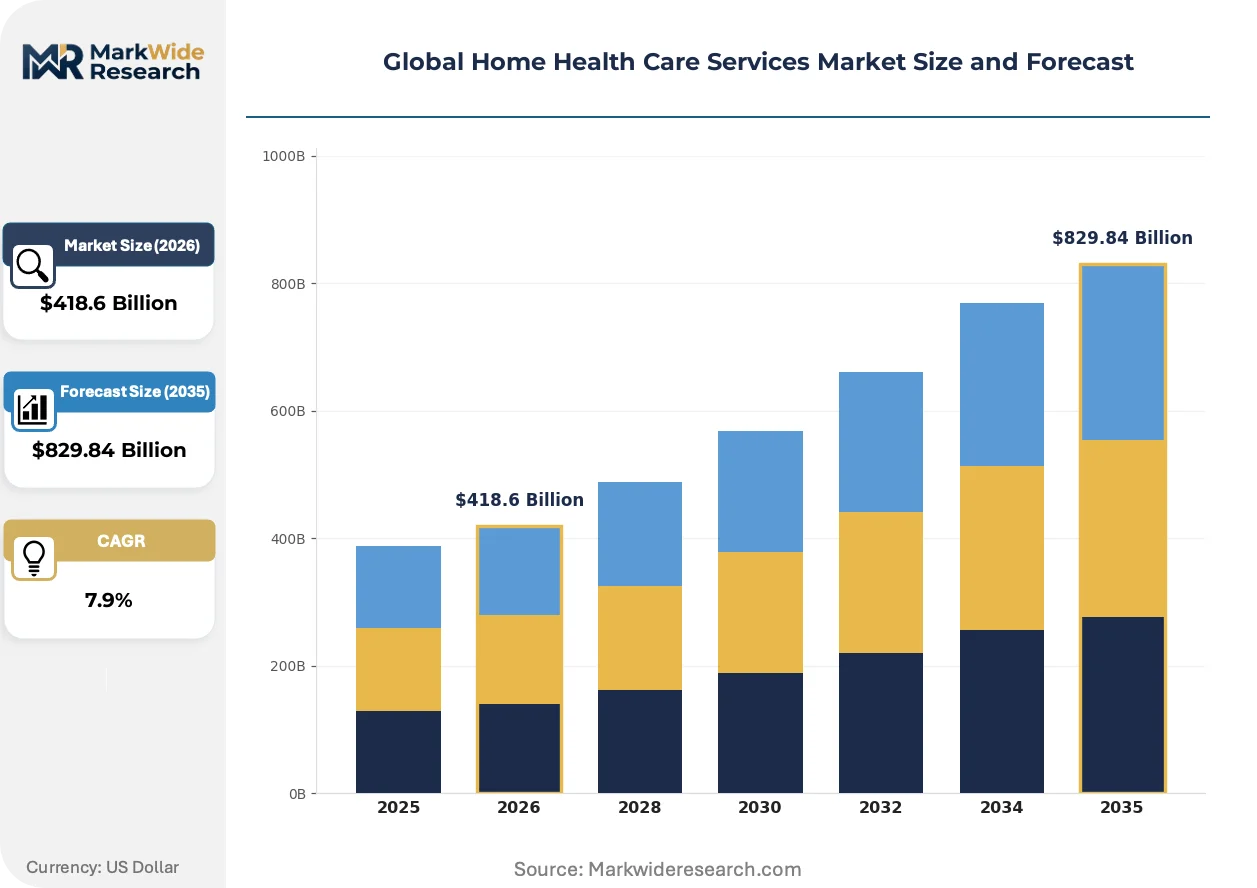
Market Dynamics
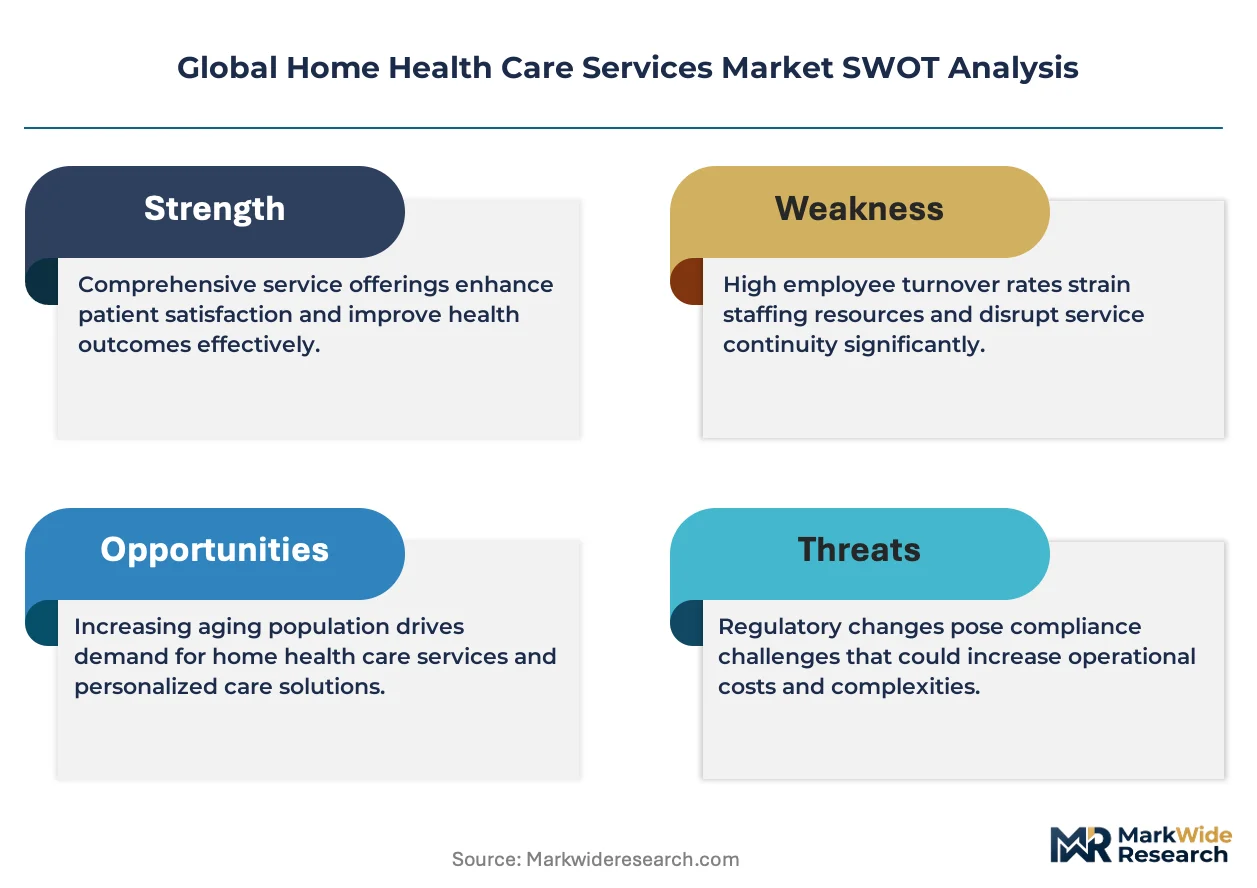
Hospital-at-home reimbursement parity under CMS waiver programs is compressing traditional institutional post-acute volumes while forcing Medicare-certified agencies to restructure clinical workflows around remote monitoring documentation requirements.
Growth Catalysts
- Hospital-at-Home Waivers:CMS emergency waivers in the United States now reimburse acute-level care delivered in residential settings at institutional rates, pulling surgical recovery and chronic disease management out of skilled nursing facilities.
- Remote Physiological Monitoring:Bluetooth-enabled pulse oximetry and weight scales transmit data through cloud-based platforms that trigger automated nurse triage protocols, reducing emergency department utilization among heart failure cohorts.
- Germany's SVB Reforms:The Social Code Book V amendments expanded statutory health insurance coverage for domiciliary nursing to 45 hours weekly, creating predictable demand for skilled nursing visits among the 4.1 million receiving Pflegegeld benefits.
Market Restraints
- Skilled Labor Supply Concentration:Registered nurse availability concentrates in urban hospital systems across the United States and Germany, leaving rural Medicare-certified agencies dependent on traveling clinicians at 40-60% premium wage rates.
- OASIS Documentation Burden:CMS-mandated Outcome and Assessment Information Set data collection consumes 45-90 minutes per admission, creating administrative drag that compresses billable visit time and margins.
- Substitution by Family Caregiving:Unpaid informal caregivers in Japan and Southern Europe absorb 70-80% of long-term care hours, capping addressable market expansion for formal skilled nursing services.
Strategic Opportunities
- India's Tier-Two City Expansion:Government-backed training institutes in Lucknow and Indore are graduating 12,000 auxiliary nurse midwives annually, creating deployable workforce pools for home health franchises targeting 340 million aging in second-tier urban centers.
- AI-Enabled Fall Detection:Computer vision algorithms analyzing ambient sensor data converge with voice-activated emergency response systems to enable predictive intervention before injury events, opening premium reimbursement tiers.
- Medicare Advantage Bundled Contracts:CMS innovation center demonstrations reward agencies that achieve 30-day readmission rates below 10% with shared savings allocations, shifting revenue models from fee-for-service to episode accountability.
Industry Challenges
- Interoperability Fragmentation:Proprietary EHR systems from Epic, Cerner, and MEDITECH lack standardized APIs, forcing home health agencies to maintain parallel documentation workflows that duplicate clinical assessment entries.
- Wound Care Certification Bottlenecks:Wound, Ostomy and Continence Nursing Certification Board examination backlogs extend 8-14 months in the United States, delaying specialized service line launches and Medicare billing eligibility for complex dressing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Home Health Care Services Market |
| Market Size in 2026 | $418.6 Billion |
| Market Size in 2035 | $829.84 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Skilled Nursing, Physical Therapy, Occupational Therapy, Medical Social Services, Home Health Aide End User: Elderly Patients, Disabled Individuals, Chronic Disease Patients, Post-Surgery Patients, Terminally Ill Delivery Model: Agency-Based, Private Pay, Managed Care, Telehealth Services, Community-Based Programs Care Setting: Residential Homes, Assisted Living Facilities, Rehabilitation Centers, Hospice Care Centers, Independent Households |
| Companies Covered | Amedisys, LHC Group, BAYADA Home Health Care, Kindred Healthcare, Almost Family, Gentiva Health Services, Addus Homecare, AccentCare, Trinity Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Home Health Care Services Market Shifts & Advancements
Continuous glucose monitors and implantable cardiac sensors are generating real-time biometric streams that demand new clinical staffing models and liability frameworks for remote decision-making.
Continuous passive monitoring through ambient radar and thermal imaging is rendering obsolete the scheduled vital-sign visit model that has structured home health revenue for three decades. Medicare Advantage plans in Florida and Arizona now reimburse exclusively for exception-based nursing contacts triggered by algorithmic alerts, compressing routine visit volumes by 60% while maintaining outcome metrics. This shift forces agencies to retrain field staff toward acute intervention competencies rather than assessment documentation.
Japan's PMDA revised software-as-medical-device classifications in 2023 to require clinical validation for AI-driven deterioration prediction algorithms used in home settings. The industrial consequence is a 18-24 month regulatory runway for digital health vendors seeking reimbursement under Japan's long-term care insurance system. Home health agencies deploying unvalidated remote monitoring tools risk claim denials and program exclusion.
Post-acute procurement by health systems is consolidating around single-source episode managers rather than fragmented specialty vendors. Hospital partners in Texas and California now require home health agencies to assume 90-day total cost of care accountability for joint replacement and cardiac surgery patients, replacing per-visit fee structures with prospective payment arrangements. This concentrates contract awards on agencies with predictive analytics capabilities and skilled nursing density sufficient to absorb readmission risk.
Global Home Health Care Services Market Segmentation
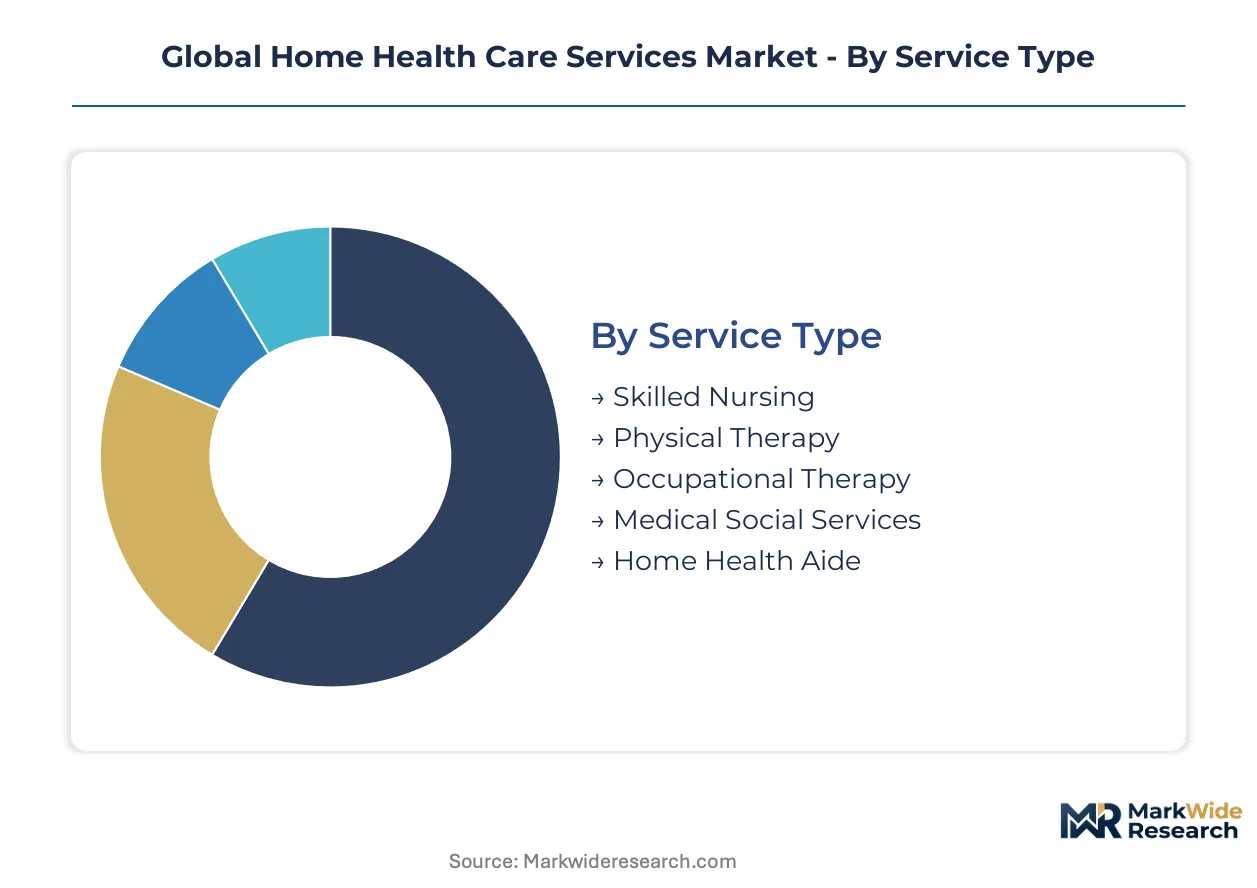
Service mix and reimbursement pathways segment the Global Home Health Care Services Market into distinct operational archetypes. Each category shapes workforce deployment, technology integration, and margin structures differently across Medicare-certified and private-pay environments.
Service Type:
After-sales service intensity peaks with wound care protocols and infusion therapy management requiring 24/7 nurse triage availability.
- Skilled Nursing:Complex clinical tasks including medication administration, wound dressing, and catheter care performed by registered nurses under physician orders. Demand concentrates in the United States and Germany where CMS and SVB reimbursement weighting rewards clinical complexity. Hospital-at-home waivers are accelerating volume shifts from skilled nursing facilities to residential settings.
- Physical Therapy:Mobility rehabilitation and post-surgical recovery protocols delivered by licensed therapists with standardized outcome measurement tools. Post-surgery patients in Japan and the United States drive concentrated demand spikes tied to elective procedure backlogs and accelerated discharge protocols.
- Occupational Therapy:Activities of daily living retraining and adaptive equipment assessment for functional independence restoration.
- Medical Social Services:Care coordination, resource linkage, and psychosocial assessment for complex patient populations.
- Home Health Aide:Personal care assistance with bathing, dressing, and meal preparation under nurse supervision.
Skilled Nursing holds the largest share; momentum sits with Home Health Aide services as workforce training programs expand in India.
End User:
Cost tier differentiation separates acute-episode patients with bundled payment eligibility from chronic cohorts requiring longitudinal management.
- Elderly Patients:Individuals aged 65 and older requiring assistance with chronic condition management and functional decline. Germany's 4.1 million Pflegegeld recipients and Japan's aging population generate predictable demand for domiciliary nursing hours.
- Post-Surgery Patients:Acute recovery needs following joint replacement, cardiac surgery, and other procedures requiring skilled monitoring. Texas and California health systems now mandate 90-day total cost of care accountability from home health agencies.
- Disabled Individuals:Long-term functional support needs arising from congenital conditions or traumatic injury.
- Chronic Disease Patients:Ongoing management of heart failure, diabetes, and COPD with remote physiological monitoring integration.
- Terminally Ill:Palliative and hospice care focused on comfort measures and family support services.
Elderly Patients dominate volume; Post-Surgery Patients are expanding most quickly under hospital-at-home reimbursement parity.
Delivery Model:
Volume concentration varies sharply between fee-for-service agency structures and capitated managed care arrangements.
- Agency-Based:Medicare-certified organizations delivering skilled care under CMS Conditions of Participation with OASIS documentation requirements. Southern United States markets sustain recurring revenue density through established certification footprints.
- Telehealth Services:Remote patient monitoring and virtual nursing visits enabled by Bluetooth-enabled biometric devices and cloud-based triage platforms. Medicare Advantage plans in Florida and Arizona now reimburse exception-based nursing contacts triggered by algorithmic alerts.
- Private Pay:Direct consumer payment for non-medical care and premium service tiers outside insurance coverage.
- Managed Care:Capitated arrangements with Medicare Advantage and Medicaid managed care organizations.
- Community-Based Programs:Nonprofit and government-funded services targeting underserved populations.
Agency-Based delivery holds the largest share; Telehealth Services show the steepest expansion trajectory as PMDA and EMA software-as-medical-device frameworks mature.
Care Setting:
Geographic clustering follows urban hospital referral patterns and rural access gaps where traveling clinician premiums reach 40-60%.
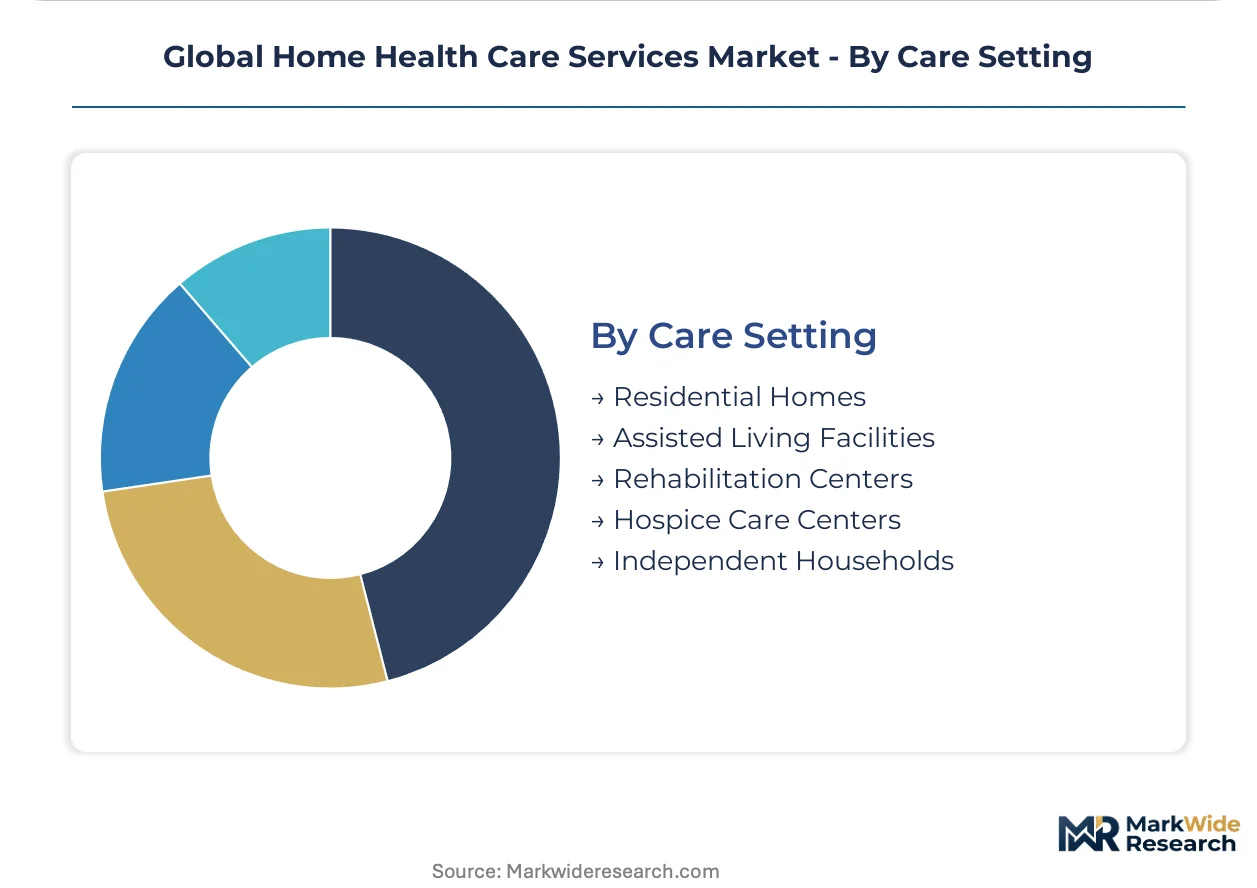
- Residential Homes:Private dwellings where patients receive skilled nursing and therapy services through Medicare-certified agencies. CMS waiver programs now reimburse acute-level care at institutional rates, pulling surgical recovery into residential settings.
- Assisted Living Facilities:Residential care settings combining housing with supportive services and intermittent skilled care.
- Rehabilitation Centers:Transitional facilities bridging acute hospital discharge and home-based recovery.
- Hospice Care Centers:Dedicated palliative care environments for terminally ill patients.
- Independent Households:Self-directed living arrangements with family caregiver support and minimal formal service integration.
Residential Homes command the largest share; Assisted Living Facilities are gaining share fastest as discharge planning embeds into acute-care workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMS Conditions of Participation govern Medicare-certified agency operations across the United States, mandating OASIS data submission that directly determines reimbursement rates and market access eligibility. Demand concentrates in the United States, Germany, and Japan where aging demographics and hospital-at-home reimbursement reforms are most advanced.
United States
Hospital-at-home reimbursement parity under CMS waiver programs is compressing traditional institutional post-acute volumes while forcing Medicare-certified agencies to restructure clinical workflows around remote monitoring documentation requirements. Southern states sustain recurring revenue density through established certification footprints. Texas and California health systems now mandate 90-day total cost of care accountability from home health agencies.
Germany
The Social Code Book V amendments expanded statutory health insurance coverage for domiciliary nursing to 45 hours weekly, creating predictable demand for skilled nursing visits among the 4.1 million receiving Pflegegeld benefits. Registered nurse availability concentrates in urban hospital systems, leaving rural agencies dependent on traveling clinicians at premium wage rates. Industrial clusters in Bavaria and North Rhine-Westphalia anchor service delivery networks.
Japan
Japan's PMDA framework for remote monitoring devices converges on software-as-medical-device classifications that reshape product standards across export markets. The 2023 PMDA revision requires clinical validation for AI-driven deterioration prediction algorithms used in home settings. Kanto and Kansai regions generate concentrated demand from the aging population receiving long-term care insurance benefits.
India
Government-backed training institutes in Lucknow and Indore are graduating 12,000 auxiliary nurse midwives annually, creating deployable workforce pools for home health franchises. The country's national pharmaceutical regulator oversees infusion therapy protocols while public-private partnerships expand tier-two city coverage. Maharashtra and Karnataka host emerging service networks targeting 340 million aging in second-tier urban centers.
United Kingdom
NHS England integrated care systems are embedding discharge planning into acute-care workflows, pulling surgical recovery into residential settings. The Care Quality Commission regulates domiciliary care standards while local authorities manage commissioning frameworks. London and Southeast England concentrate skilled nursing workforce pools amid national staffing shortages.
Global Home Health Care Services Market Competitive Landscape
Medicare-certified national networks and regional specialists split the market into distinct operational archetypes with divergent scale advantages. Consolidation pressures intensify as health systems demand single-source episode managers rather than fragmented specialty vendors. Three strategic archetypes dominate: scale-driven national platforms, hospital-integrated joint ventures, and technology-enabled remote monitoring specialists. Competitive moves center on Medicare Advantage bundled contract acquisition and predictive analytics capability deployment.
Among Medicare-certified national platforms, Amedisys and LHC Group exemplify the scale-driven archetype, while Kindred Healthcare occupies a position within the post-acute episode management tier. These entities anchor competitive positioning through recurring revenue density in CMS-regulated environments and joint-venture hospital partnerships that embed discharge planning into acute-care workflows.
| Leading Market Players |
|---|
| Amedisys |
| LHC Group |
| BAYADA Home Health Care |
| Kindred Healthcare |
| Almost Family |
| Gentiva Health Services |
| Addus Homecare |
| AccentCare |
| Trinity Health |
| Others |
Supply & Pricing Matrix
Bavaria and North Rhine-Westphalia anchor Germany's skilled nursing workforce training capacity, creating regional supply density that translates into pricing power for Medicare-certified agencies serving Pflegegeld recipients across Central European markets.
Pricing Analysis
Geographic price spreads between urban hospital systems and rural Medicare-certified agencies in the United States reach 40-60% premium wage differentials for traveling registered nurses. Three-tier pricing structure across premium, standard, and economy levels separates agencies with AI-enabled remote monitoring capabilities from basic skilled nursing providers and family caregiver substitution models. Cost compression in standard-tier services is intensifying because OASIS documentation burdens consume 45-90 minutes per admission, compressing billable margins. Post-surgery patients under bundled payment contracts exhibit lowest price sensitivity, while chronic disease patients in private-pay segments demonstrate highest elasticity.
Supply Chain Analysis
Export control regimes limiting software-as-medical-device flows under Japan's PMDA framework and EMA digital health guidance create regulatory friction for remote monitoring technology vendors seeking multi-market deployment. Workforce supply concentrates in India, Germany, and the United States where government-backed training institutes in Lucknow and Indore graduate 12,000 auxiliary nurse midwives annually. Raw material dependencies include Bluetooth-enabled biometric sensors, cloud-based triage platforms, and interoperable EHR systems. Single-source vulnerability runs through proprietary EHR systems from Epic, Cerner, and MEDITECH lacking standardized APIs. Distribution runs through Medicare-certified agency networks and hospital-integrated joint ventures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Home Health Care Services Market sits in early-cycle recovery as hospital-at-home reimbursement parity under CMS waivers pulls surgical recovery volumes from skilled nursing facilities into residential settings.
For Market Incumbents: Build certification moats around wound care specialization and OASIS documentation efficiency to defend against technology-enabled remote monitoring entrants. Pursue backward integration into AI-driven triage platform development to capture algorithmic alert revenue streams. Consolidate joint-venture hospital partnerships in Texas and California where 90-day total cost of care accountability mandates concentrate contract awards. For New Entrants and Emerging Players: Pursue India's tier-two city expansion where 340 million aging populations lack established Medicare-certified agency footprints. Target auxiliary nurse midwife deployment models in Maharashtra and Karnataka as the most penetrable workforce arbitrage opportunity. Launch with public-private partnership structures leveraging government-backed training institute graduate pipelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors agencies with predictive analytics capabilities and skilled nursing density sufficient to absorb readmission risk under bundled payment contracts. Long-term viability hinges on reimbursement parity evolution between virtual and in-person encounters across divergent national health technology assessment regimes. Monitor CMS innovation center demonstration results as the inflection signal for episode-based revenue model adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Remote Monitoring Deployment | PMDA clinical validation requirements reshape 18-24 month regulatory runway for algorithmic deterioration prediction tools. |
| Hospital System Partnership Consolidation | Single-source episode manager mandates in Texas and California concentrate contract awards on predictive analytics-capable agencies. |
| Workforce Training Institute Expansion | Lucknow and Indore auxiliary nurse midwife programs create deployable talent pools for tier-two city franchise growth. |
| OASIS Documentation Automation Investment | CMS-mandated data collection consuming 45-90 minutes per admission creates administrative drag compressing billable margins. |
| Medicare Advantage Bundled Contract Acquisition |
Research Methodology
A spread of perspectives from home health agency executives, hospital discharge planners, Medicare Advantage contracting officers, and biomedical engineers converged on the working assumptions shaping this analysis. Primary interviews with skilled nursing workforce training directors and GPO contracts managers combined with secondary validation against CMS Medicare data, hospital procurement databases, and EMA digital health guidance documents. Bottom-up service line volume builds and top-down reimbursement flow analysis provided cross-check triangulation.
Demand-supply balance framing anchored the analytical framework across the projection horizon, modeling workforce availability constraints against hospital-at-home waiver expansion trajectories. Segmentation dimensions included service type, end user category, delivery model, and care setting with regional regulatory cluster differentiation. CAGRs were derived from fitted growth curves calibrated to historical reimbursement policy shift patterns and technology adoption S-cycles in remote physiological monitoring.
Macroeconomic conditions sit as an overlay; deviation in statutory health insurance funding levels or long-term care insurance benefit generosity would shift the trajectory. Forecasts reflect documented assumptions about reimbursement parity evolution and software-as-medical-device classification harmonization. Material shifts in CMS Conditions of Participation or Japan's PMDA validation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Global Home Health Hub Market
Home Healthcare
UK Home Healthcare Market
Home Healthcare
Global Home Healthcare Software Market
Home Healthcare
US House Calls Market
Home Healthcare
US Home Healthcare Market
Home Healthcare
Elderly Care Apps Market
Home Healthcare
Home Care Products Market
Home Healthcare
House Call Market
Home Healthcare
US Home Infusion Therapy Market
Home Healthcare
Smart Pillow Market
Home Healthcare
Home Care Service Market
Home Healthcare
Chemotherapy at Home Services Market
Home Healthcare
Home Healthcare Market
Home Healthcare
Germany Home Healthcare Market
Home Healthcare
Adult Day Care Market
Home Healthcare
Europe Home Care Market