
 Cellulose Acetate Fiber Market | 2026-2036
Cellulose Acetate Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Cellulose Acetate Fiber Market Outlook
Specialty chemical distribution is fragmenting as regional distributors lose leverage to direct mill relationships and integrated supply platforms. Solvay leverages its European acetylation infrastructure to control premium filament grades. Eastman Chemical Company sustains dominant tow positions through captive cellulose sourcing from Rayonier Advanced Materials. Sichuan Push Acetate Co. Ltd. anchors Chinese domestic filter supply with cost-optimized staple operations.
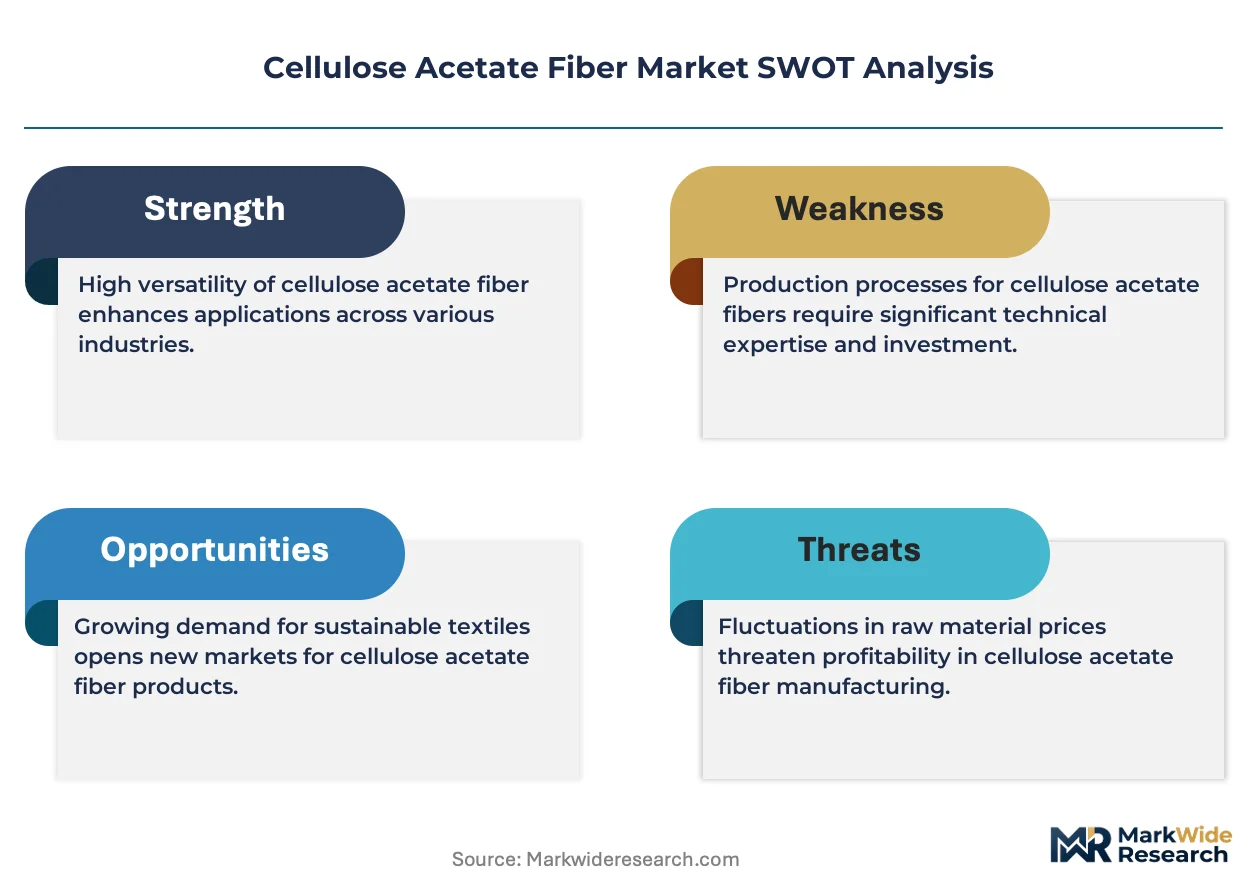
Cellulose acetate fiber consists of regenerated cellulosic filaments derived from wood pulp acetylation, typically containing 55–62% combined acetic acid by weight and extruded through spinnerets into continuous tow or cut staple lengths for industrial processing. The material functions primarily as a controlled-permeability matrix in cigarette filters and as a drapable, biodegradable textile input. Tow commands the largest value pool given tobacco industry offtake volumes, while nonwoven grades represent the fastest-expanding segment driven by medical wipe and filtration demand. Staple fiber competes on price with viscose in apparel applications, though filament yarn retains margin concentration in luxury upholstery.
EPA oversees volatile organic compound emissions from acetic anhydride processing facilities in the United States, while REACH mandates substance registration and hazard communication for European cellulose acetate importers. China's MEE enforces wastewater discharge standards on acetylation plants along the Yangtze corridor. Stakeholders must monitor evolving extended producer responsibility frameworks for cellulosic waste streams and calibrate capacity investments against regional environmental enforcement intensity.
Market Dynamics
Tobacco filter compliance mandates and EU chemical disclosure protocols are forcing acetylation capacity relocations and supply chain reconfigurations across the cellulose acetate fiber value chain.
Growth Catalysts
- REACH substance registration:European chemical disclosure requirements are accelerating substitution away from petroleum-based synthetic filters toward biodegradable cellulosic alternatives in consumer goods.
- Medical nonwoven demand:Surgical wipe and filtration applications are absorbing specialty-grade staple fiber volumes as healthcare facilities prioritize compostable single-use materials.
- Yangtze corridor expansion:Chinese acetylation plant clusters are capturing cost efficiencies from integrated pulp-to-fiber processing and captive acetic anhydride supply.
Market Restraints
- Wood pulp input volatility:Dissolving pulp prices fluctuate with construction-sector demand swings for paper-grade pulp, compressing acetate fiber margin stability.
- Acetylation plant concentration:European and North American tow production relies on a limited number of legacy acetic anhydride processing facilities with aging emission control infrastructure.
- Viscose substitution threat:Lower-cost regenerated cellulose alternatives are displacing acetate staple in mass-market apparel applications where drapability specifications permit.
Strategic Opportunities
- Indian textile integration:Domestic spinning mills are backward-integrating into acetylation to secure filter and specialty yarn feedstock against import duty exposure.
- EU Green Deal tailwinds:Extended producer responsibility frameworks for cellulosic waste streams are creating preferential procurement channels for certified biodegradable fiber grades.
- Filament-luxury upholstery convergence:High-denier continuous yarn is penetrating automotive and furniture markets as synthetic leather face fabrics face regulatory scrutiny.
Industry Challenges
- Acetylation technician scarcity:Specialized process engineering expertise for anhydride handling and spinneret maintenance is concentrating at legacy European and Japanese facilities.
- Emission control capex cycles:EPA and MEE enforcement intensification requires continuous investment in volatile organic compound recovery systems at existing plants.
- Multi-jurisdiction certification complexity:Divergent biodegradable testing protocols between ASTM, ISO, and EU harmonized standards delay new grade commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellulose Acetate Fiber Market |
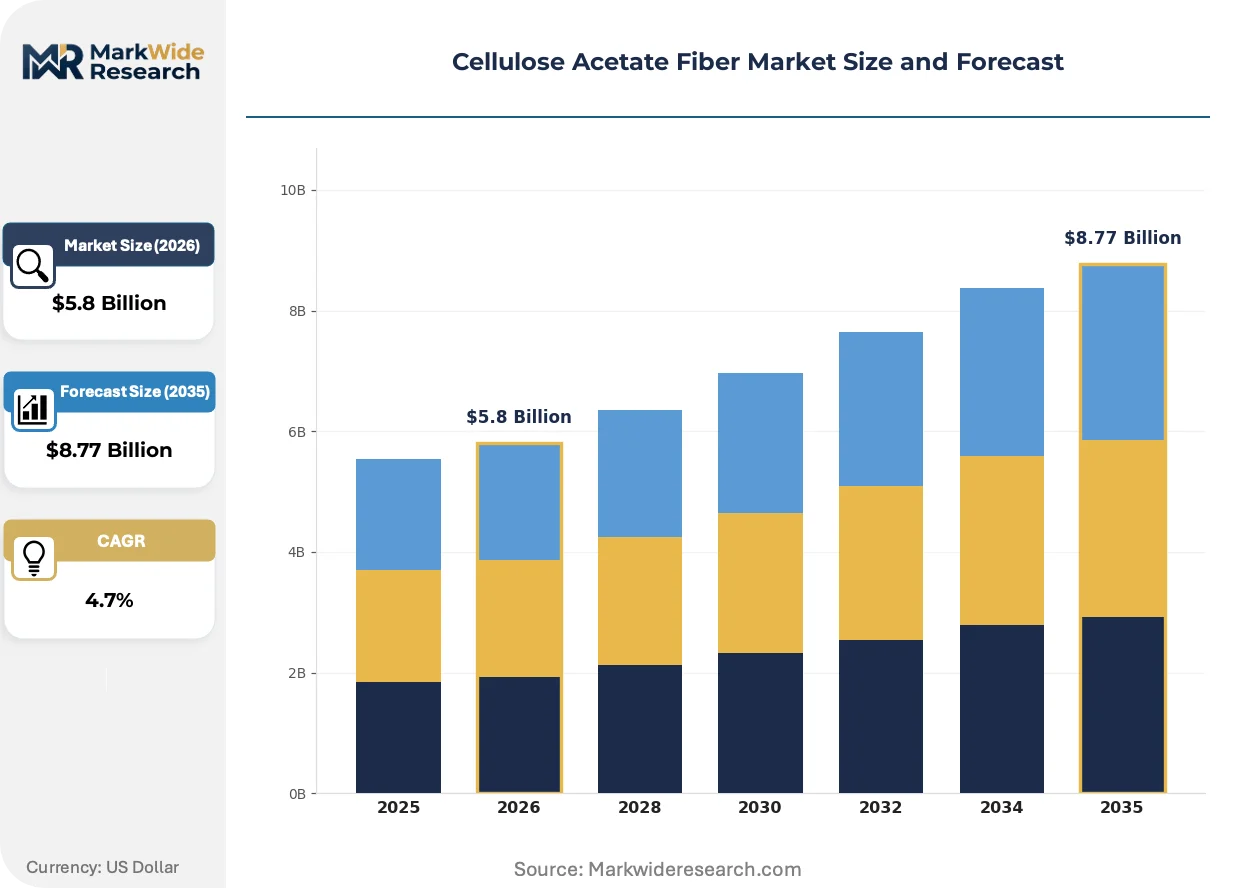
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filament, Tow, Staple Fiber, Nonwoven End Use Industry: Textiles, Automotive, Medical, Filters Form: Natural, Synthetic, Blends, Specialty Application: Clothing, Upholstery, Composites, Packaging |
| Companies Covered | Solvay, China National Tobacco Corporation, Eastman Chemical Company, Rayonier Advanced Materials, Sappi, Celanese Corporation, Mitsubishi Chemical Holdings Corporation, Sichuan Push Acetate Co. Ltd., Daicel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellulose Acetate Fiber Market Strategic Shifts
Process control systems and chemical traceability platforms are transforming how acetylation plants manage quality consistency and regulatory documentation across dispersed production networks.
Closed-loop solvent recovery technology is digitizing acetic acid reclamation rates at acetylation facilities. Tow manufacturers in Germany and Belgium are deploying sensor arrays to monitor anhydride consumption in real time. This precision is compressing raw material waste coefficients and narrowing batch-to-batch viscosity variation for cigarette filter specifications.
EU Green Deal chemical footprinting mandates are extending disclosure obligations to cellulosic derivative importers. Downstream textile brands must now document acetylation-stage energy inputs and wood pulp provenance. Filter tow suppliers are responding by segregating certified sustainable pulp streams into dedicated production lines.
Direct mill procurement contracts are displacing traditional distributor networks for industrial staple volumes. Large nonwoven converters in the United States and China are negotiating long-term offtake agreements with acetylation plants. This channel consolidation is visible most acutely in medical wipe supply chains where lot traceability requirements favor integrated supplier relationships.
Cellulose Acetate Fiber Market Segmentation
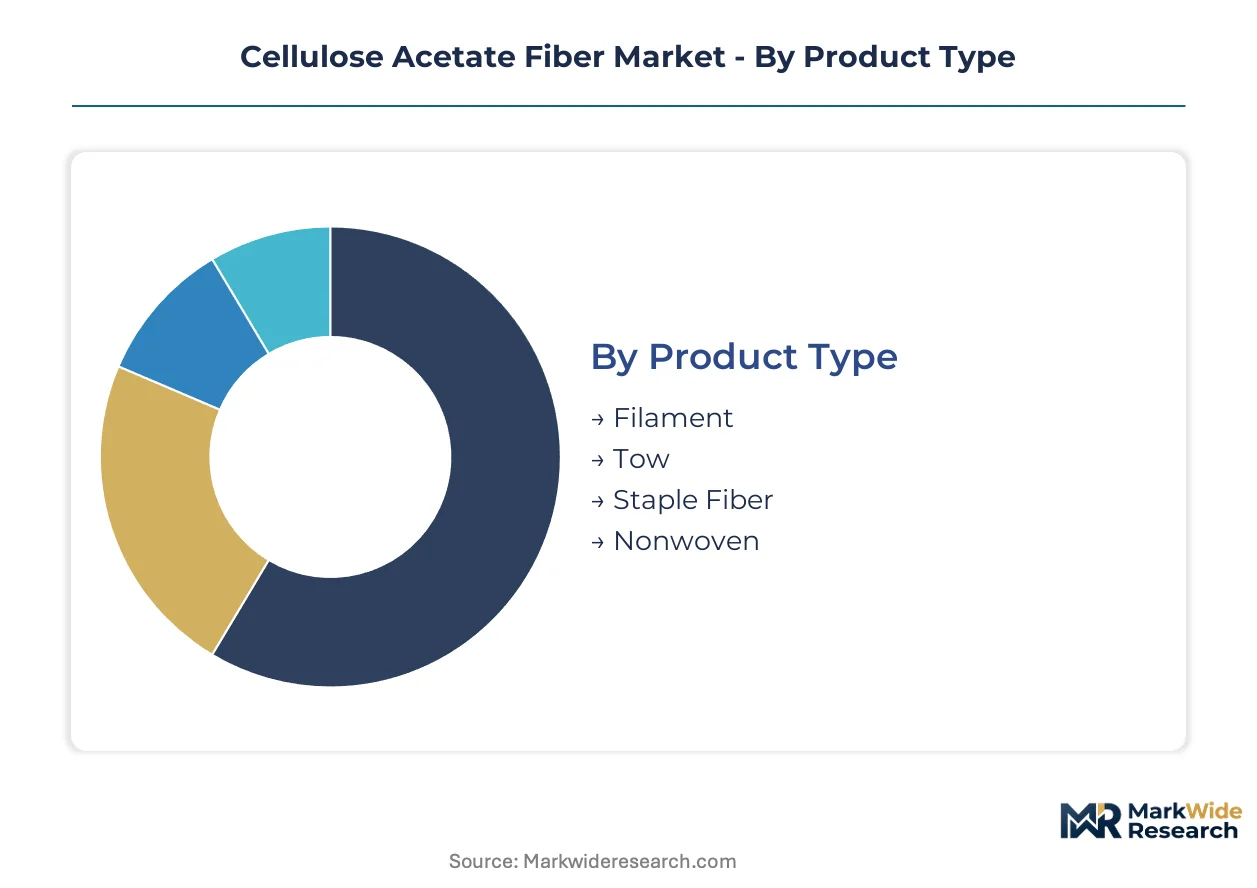
Cellulose acetate fiber segments diverge sharply in production cadence and margin structure. Tow turns on tobacco contract cycles measured in years, while nonwoven grades respond to quarterly healthcare procurement shifts.
Product Type:
Tow cycles stretch across multi-year tobacco supply agreements, while filament and staple fiber turn faster on textile seasonality.
- Tow:Continuous filament bundles extruded for cigarette filter manufacturing contain 55–62% combined acetic acid by weight. Demand concentrates with tobacco manufacturers in China and the United States as FDA and SAMR compliance mandates harden against petroleum-based alternatives.
- Nonwoven:Random-laid fiber webs engineered for medical wipes and filtration media feature controlled fiber diameter distributions for liquid absorption. German and Belgian converters are absorbing specialty-grade volumes as EU Green Deal procurement rules favor compostable single-use materials.
- Filament:Continuous yarn grades for luxury upholstery and automotive fabrics.
- Staple Fiber:Cut-length fibers competing with viscose in apparel applications.
Tow dominates installed base. Nonwoven is where expansion concentrates.
End Use Industry:
Margin tiers separate regulated medical and filter applications from price-sensitive textile markets.
- Filters:Cigarette filter tow specifications demand precise denier control and pressure-drop consistency. Chinese and Indian tobacco manufacturers are securing long-term offtake agreements as REACH and EU Green Deal protocols tighten chemical disclosure requirements for cellulosic derivatives.
- Medical:Surgical wipe and sterilization wrap applications require biocompatibility certification and lot traceability. United States nonwoven converters are negotiating direct mill contracts with acetylation plants to satisfy FDA documentation requirements.
- Textiles:Apparel and home furnishing applications competing on drape and hand feel.
- Automotive:Headliner and seating fabrics facing synthetic leather substitution pressure.
Filters command the value pool. Medical is climbing the fastest.
Form:
Input material sourcing separates certified sustainable grades from commodity cellulosic streams.
- Natural:Wood pulp-derived acetate with documented provenance from managed forestry. EU textile brands are segregating certified pulp streams into dedicated production lines to satisfy extended producer responsibility frameworks.
- Specialty:Modified acetylation grades for high-performance filtration and controlled-release applications.
- Synthetic:Petrochemical-derived alternatives facing substitution pressure.
- Blends:Hybrid formulations combining cellulosic and synthetic fiber properties.
Natural forms anchor volume. Specialty commands the steepest expansion trajectory.
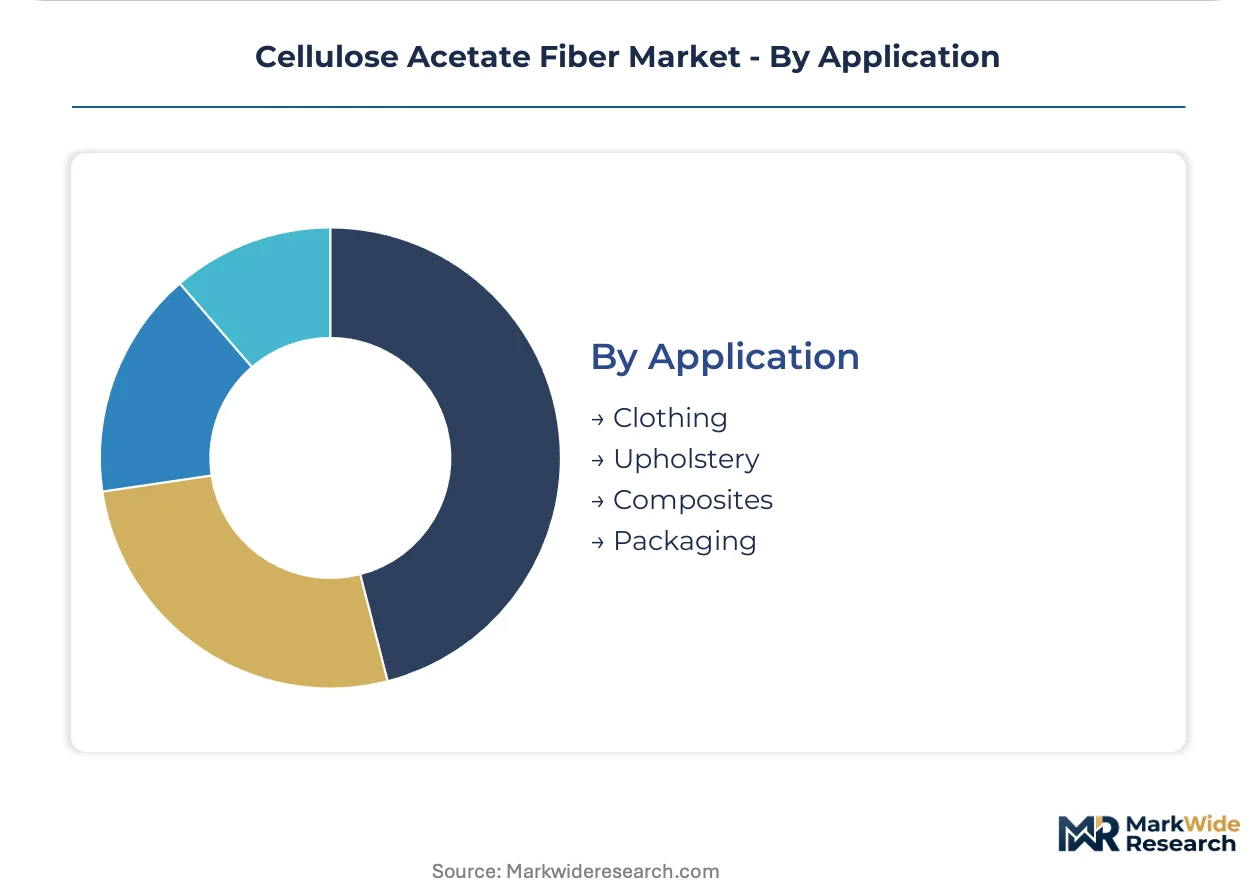
Application:
End-product durability requirements stretch from single-use medical wipes to decade-long automotive upholstery cycles.
- Clothing:Staple fiber applications in dresses, linings, and knitwear competing with viscose on price. Indian spinning mills are backward-integrating into acetylation to secure filter and specialty yarn feedstock against import duty exposure.
- Upholstery:High-denier filament yarn for furniture and automotive face fabrics. German manufacturers are penetrating luxury seating markets as synthetic leather faces regulatory scrutiny under REACH substance registration protocols.
- Composites:Reinforced fiber matrices for industrial and transportation applications.
- Packaging:Biodegradable film and molded fiber substitutes.
Clothing absorbs the most volume. Upholstery is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in European acetylation clusters where REACH compliance costs filter weak competitors, while Chinese producers along the Yangtze corridor capture volume through integrated pulp-to-fiber economics.
China
Tobacco filter demand and textile staple expansion drive capacity additions in Sichuan and Jiangsu provinces. SAMR enforces chemical disclosure standards for cellulosic derivatives used in consumer goods. The Yangtze River Delta cluster hosts integrated acetylation plants with captive acetic anhydride supply.
Germany
Medical nonwoven converters and luxury upholstery manufacturers absorb specialty-grade filament volumes. ECHA administers REACH substance registration and extended producer responsibility frameworks for cellulosic waste streams. The Cologne-Düsseldorf industrial corridor maintains legacy acetylation infrastructure with digitized solvent recovery systems.
United States
Cigarette filter tow contracts and surgical wipe applications sustain industrial demand for controlled-permeability fiber grades. EPA regulates volatile organic compound emissions from acetic anhydride processing facilities in Tennessee and Virginia. Eastman Chemical's Kingsport operations anchor North American acetylation capacity through captive cellulose sourcing arrangements.
India
Domestic spinning mills and tobacco manufacturers are securing long-term feedstock agreements against import duty exposure. BIS implements standards for textile-grade cellulose acetate staple fiber quality certification. Gujarat and Maharashtra host backward-integrated acetylation projects targeting filter and specialty yarn applications.
Belgium
EU Green Deal procurement rules channel demand toward certified biodegradable fiber grades for medical and filtration end uses. ECHA coordinates hazard communication requirements for cellulosic derivative importers across the single market. The Port of Antwerp cluster specializes in segregated sustainable pulp streams for dedicated production lines.
Cellulose Acetate Fiber Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in acetylation and pulp supply. The vendor base organizes around three tiers: integrated chemical conglomerates with captive cellulose sourcing, regional acetylation specialists serving domestic tobacco and textile markets, and pulp processors diversifying into derivative fiber production. Consolidation pressures concentrate in European tow manufacturing where emission control capex requirements filter marginal operators. Competitive moves center on backward integration into dissolving pulp supply and strategic partnerships with nonwoven converters seeking lot traceability.
Within the integrated chemical tier, Solvay and Eastman Chemical Company exemplify platform dominance through European and North American acetylation infrastructure. Sichuan Push Acetate Co. Ltd. anchors the regional specialist archetype with cost-optimized staple operations serving Chinese domestic filter demand. These three entities represent distinct competitive positions: multinational conglomerates with diversified cellulosic portfolios, legacy North American producers with captive pulp arrangements, and emerging Chinese specialists leveraging integrated Yangtze corridor economics.
| Leading Market Players |
|---|
| Solvay |
| China National Tobacco Corporation |
| Eastman Chemical Company |
| Rayonier Advanced Materials |
| Sappi |
| Celanese Corporation |
| Mitsubishi Chemical Holdings Corporation |
| Sichuan Push Acetate Co. Ltd. |
| Daicel Corporation |
| Others |
Value Chain & Pricing Dynamics
Wood pulp input volatility determines both pricing tier spreads and supply chain shape across cellulose acetate fiber manufacturing. Dissolving pulp price swings compress margin stability at acetylation plants while forcing geographic relocation toward integrated pulp-to-fiber corridors.
Pricing Analysis
Configured-to-order pricing for specialty filament grades commands substantial premiums over standard tow contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Price erosion runs through commodity staple fiber as viscose substitution intensifies in mass-market apparel. Tobacco filter manufacturers exhibit lowest price sensitivity due to regulatory compliance requirements, while nonwoven converters for medical wipes face acute cost compression.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk calculus for Asian acetylation capacity. Production concentrates in China, Belgium, and the United States, with each cluster drawing from distinct dissolving pulp supply basins. Acetic anhydride and wood pulp dependencies create single-source vulnerability at legacy European facilities. Distribution runs through direct mill procurement contracts that displace traditional distributor networks for industrial staple volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. REACH compliance costs and emission control capex requirements create barriers that filter marginal operators and protect incumbent returns.
For Market Incumbents: Insulate tow manufacturing margins through captive cellulose sourcing arrangements with Rayonier-grade pulp suppliers. Secure acetylation technician pipelines against scarcity concentration at legacy European and Japanese facilities. Expand solvent recovery digitization at German and Belgian plants to compress raw material waste coefficients below competitor benchmarks. For New Entrants and Emerging Players: Establish a beachhead in Indian textile integration by backward-integrating into acetylation for domestic spinning mill feedstock. Target medical nonwoven grades where lot traceability requirements favor new supplier relationships over legacy distributor networks. Pursue EU Green Deal certification pathways to access preferential procurement channels for biodegradable fiber grades. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated chemical conglomerates with emission control infrastructure already deployed. Long-term viability hinges on dissolving pulp supply security and regulatory compliance capability across multiple jurisdictions. Watch acetylation plant relocation announcements toward Yangtze corridor clusters as the inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dissolving Pulp | Captive wood pulp supply secures margin stability against construction-sector demand swings. |
| Emission Control Infrastructure Upgrade | EPA and MEE enforcement intensification filters marginal operators from European and Chinese markets. |
| EU Green Deal Certification Pathway | Extended producer responsibility frameworks create preferential channels for certified biodegradable grades. |
| Direct Mill Procurement Contracts | Lot traceability requirements in medical nonwovens favor integrated supplier relationships over distributors. |
| Acetylation Capacity Relocation | Yangtze corridor economics capture cost efficiencies from integrated pulp-to-fiber processing. |
Study Parameters
The analysis maps tow, filament, staple fiber, and nonwoven segments, each validated through acetylation plant managers, tobacco procurement leads, textile spinning mill directors, and medical nonwoven converters. Primary interviews combined with secondary validation from customs/trade data, SEC 10-K filings, Cefic chemical industry reports, and SAMR disclosure databases. Bottom-up capacity modeling and top-down demand triangulation anchored volume and value outputs.
Assumption sets held regulatory enforcement intensity and dissolving pulp price corridors fixed while varying tobacco consumption trajectories and EU Green Deal implementation pace across the projection horizon. Segmentation dimensions modeled include product type, end-use industry, form, and application with regional production hub overlays. CAGRs derived from installed capacity utilization rates and contract renewal cycles specific to cigarette filter tow agreements.
Stress conditions across acetic anhydride supply disruptions, REACH substance registration timeline acceleration, and viscose substitution penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about emission control capex cycles and technician availability constraints. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Silk Market
Natural Fibers
Asia-Pacific Alpaca Fiber Market
Natural Fibers
Natural Fiber Reinforced Composites Market
Natural Fibers
Silk Mask Market
Natural Fibers
Lignocellulosic Fibers Market
Natural Fibers
Apple Fiber Market
Natural Fibers
Sugarcane Fiber Market
Natural Fibers
Natural Fibers Market
Natural Fibers
Cashmere Clothing Market
Natural Fibers
Green Fibers Market
Natural Fibers
Acacia Fiber Powder Market
Natural Fibers
North America Alpaca Fiber Market
Natural Fibers
Fenugreek Fiber Market
Natural Fibers
Modal Fiber Market
Natural Fibers
Cellulose Market
Natural Fibers
Global Cotton Market