
 Fenugreek Fiber Market | 2026-2036
Fenugreek Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Fenugreek Fiber Market Foresight
The EU Green Deal and its Farm to Fork Strategy is restructuring procurement priorities across European food and beverage formulators. Altrafine Gums leverages its Indian extraction infrastructure to supply standardized galactomannan fractions to EU buyers navigating EFSA novel food dossiers. Sabinsa Corporation competes through vertically integrated botanical sourcing and patented bioavailability enhancement processes. Frutarom Health anchors its position in flavor-masked fiber systems for functional beverage applications.
Fenugreek fiber comprises galactomannan polysaccharides derived from Trigonella foenum-graecum seed endosperm, typically containing 25-30% protein and 45-60% soluble fiber by dry weight, extracted through aqueous milling and alcohol precipitation for use as a viscosity-building, cholesterol-modulating, and glycemic-control agent in formulated products. Powder dominates volume throughput due to its compatibility with bakery and dry-mix applications, while extract commands premium positioning in pharmaceutical-grade encapsulation where standardization to 40-60% galactomannan content determines contract pricing. Dietary supplements represents the most contested application segment as direct-to-consumer brands consolidate around clinically substantiated dosage formats.
EFSA novel food regulations, FDA GRAS self-affirmation pathways, and India's FSSAI functional food claims framework collectively determine market access velocity and labeling permissions for fenugreek fiber products across the three largest demand jurisdictions. Compliance with REACH registration for imported botanical extracts shapes European supplier qualification timelines and testing cost structures. Stakeholders must monitor evolving glycemic health claim substantiation requirements as regulators tighten evidence standards for prebiotic and blood-sugar-management positioning statements.
Market Dynamics
EFSA novel food dossier requirements and FDA GRAS self-affirmation pathways are bifurcating market access velocity, forcing suppliers to maintain parallel regulatory infrastructures while India's FSSAI framework accelerates domestic functional food claims approval.
Growth Catalysts
- EU Green Deal procurement mandates:Farm to Fork Strategy targets are redirecting European formulator sourcing toward verified sustainable botanical extracts, creating qualified supplier slots for Indian galactomannan processors with EFSA-compliant traceability systems.
- Prebiotic health claim substantiation:Tightening glycemic management evidence standards are favoring fenugreek fiber's established clinical dossier over newer soluble fiber entrants in dietary supplement positioning.
- Soluble fiber extraction capacity expansion:Gujarat and Rajasthan processing clusters are scaling aqueous milling infrastructure to capture contract manufacturing demand from North American functional food brands.
Market Restraints
- Seed price volatility:Monsoon-dependent fenugreek harvests in India's cultivation belt create raw material cost instability that compresses processor margins during deficit crop cycles.
- REACH registration burden:ECHA compliance timelines and testing cost structures for imported botanical extracts extend European supplier qualification periods beyond eighteen months.
- Guar gum substitution pressure:Lower-cost galactomannan alternatives from established supply chains displace fenugreek fiber in viscosity-building applications where glycemic claims are not required.
Strategic Opportunities
- Pharmaceutical-grade encapsulation:Standardization to 40-60% galactomannan content for contract manufacturing of clinician-directed metabolic health formulations commands premium positioning unavailable in commodity fiber markets.
- Flavor-masked fiber systems:Functional beverage applications requiring bitterness suppression represent white space where extraction technology convergence with taste modulation creates defensible product differentiation.
- Direct-to-consumer dosage formats:Clinically substantiated capsule and sachet delivery systems bypass traditional ingredient supplier relationships, capturing margin from consolidated supplement brands.
Industry Challenges
- Novel food dossier compilation expertise:EFSA-compliant toxicology and exposure assessment capabilities remain scarce among Indian extraction facilities, creating bottlenecks for EU market entry.
- Batch-to-batch standardization:Protein content variation in seed endosperm sources complicates pharmaceutical-grade contract specifications, requiring in-process analytical chemistry investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fenugreek Fiber Market |
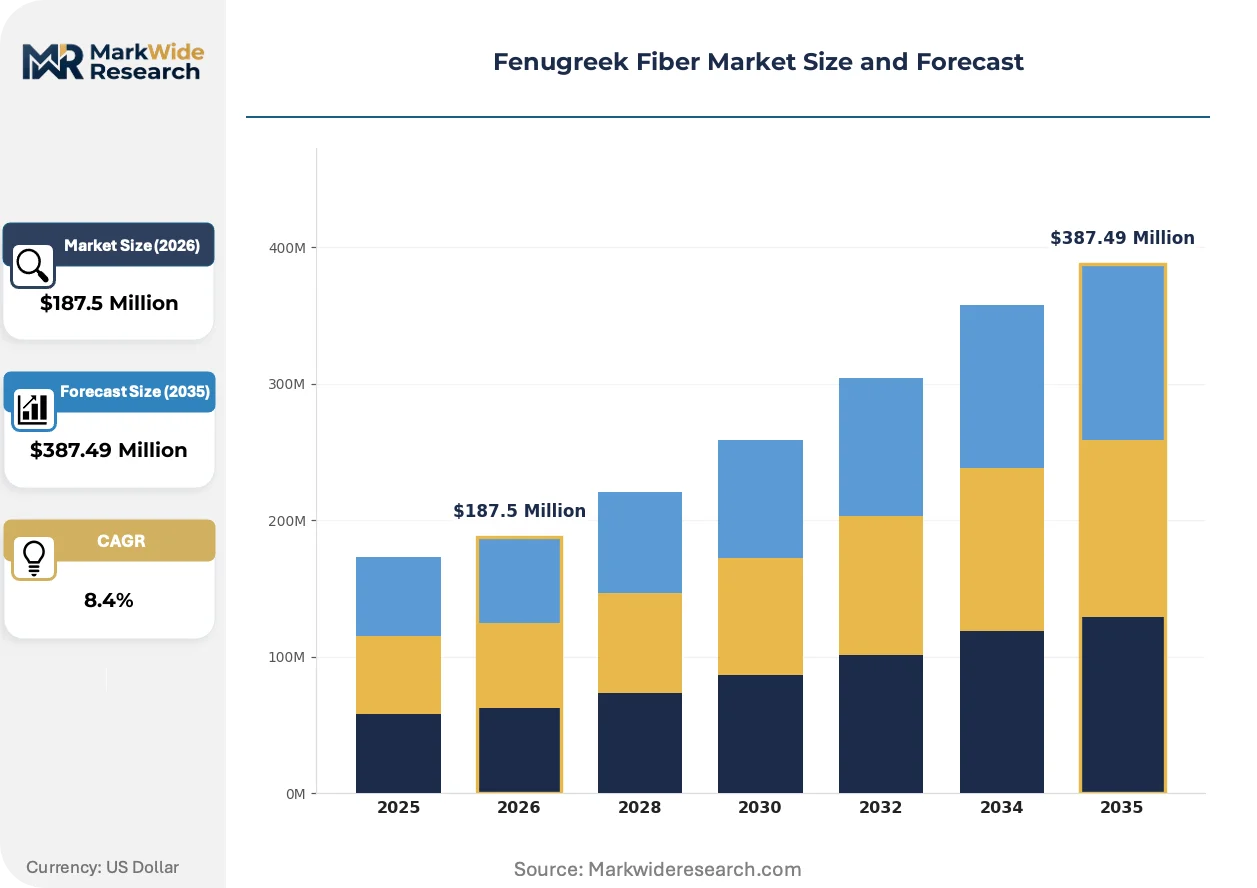
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $387.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Extract, Granules, Capsules End Use Industry: Food & Beverage, Pharmaceuticals, Nutraceuticals, Cosmetics Application: Dietary Supplements, Functional Foods, Herbal Remedies, Natural Health Products Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | Altrafine Gums, Natural Agro Products, Frutarom Health, Nature’s Own, GlucoBliss Pure, GNC Herbal Plus, Nature’s Plus, Sabinsa Corporation, NutraGreen Biotechnology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fenugreek Fiber Market Shifts & Advancements
Supercritical CO2 extraction and enzyme-assisted galactomannan refinement are compressing processing timelines while improving functional consistency, enabling new applications in precision nutrition formulations.
Enzyme-assisted aqueous extraction is electrifying the technical capabilities of mid-scale Indian processors. Functional beverage manufacturers in Germany and the Netherlands are adopting these refined fractions for clean-label prebiotic positioning. This technology is electrifying contract pricing structures by collapsing the historical premium gap between commodity powder and pharmaceutical-grade extract categories.
REACH registration requirements for botanical imports are restructuring European supplier qualification protocols. ECHA documentation burdens now favor processors with captive analytical laboratories capable of generating substance identity profiles. Dietary supplement contract manufacturers in France and Italy are consolidating purchase orders around REACH-registered Indian suppliers with established safety data packages.
Clean-label procurement criteria are displacing cost-first sourcing among North American functional food brands. Direct relationships between CPG product developers and Indian extraction facilities are replacing traditional ingredient distributor intermediaries. This pattern concentrates in California and New York metropolitan areas where metabolic health positioning drives premium ingredient acceptance.
Fenugreek Fiber Market Segmentation
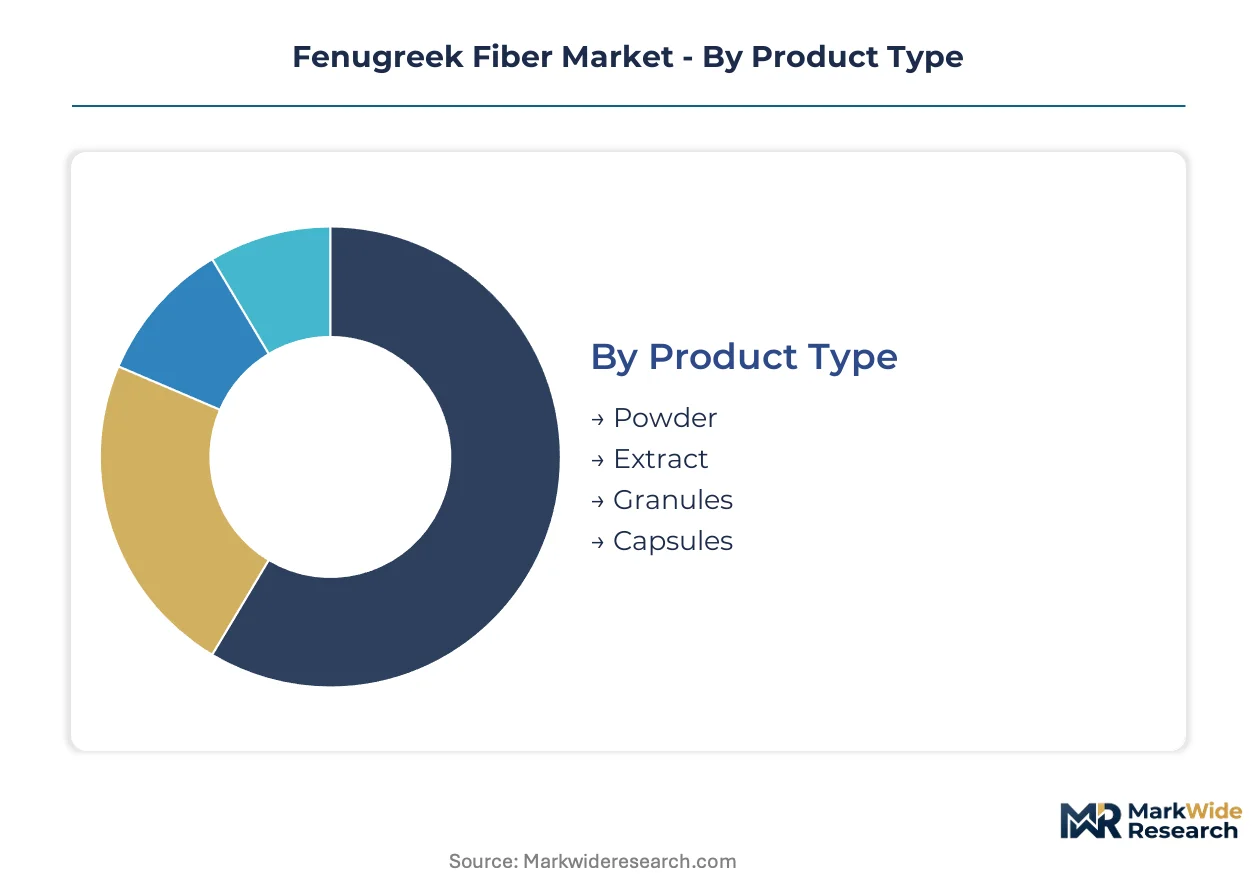
Fenugreek fiber's commercial value hinges on specification differentiation across extraction grades and delivery formats. Galactomannan content thresholds and particle size distributions determine contract eligibility for pharmaceutical versus food-grade applications.
Product Type:
Specification tiers separate commodity viscosity builders from clinically validated therapeutic inputs.
- Powder:Ground seed endosperm containing 45-60% soluble fiber by dry weight serves bakery and dry-mix applications where cost efficiency outweighs standardization requirements. Demand concentrates in North American functional food manufacturing as clean-label prebiotic positioning displaces synthetic hydrocolloids.
- Extract:Alcohol-precipitated galactomannan fractions standardized to 40-60% active content command pharmaceutical-grade encapsulation contracts. European dietary supplement formulators in Germany and France drive specification tightening as EFSA novel food dossiers require batch-to-batch consistency documentation.
- Granules:Agglomerated powder forms improve flow properties for tablet compression operations in Indian nutraceutical contract manufacturing.
- Capsules:Pre-filled dosage units bypass intermediate ingredient handling for direct-to-consumer metabolic health brands in California and New York metropolitan markets.
Mature deployment sits with Powder. Newer deployment is concentrated in Extract.
End Use Industry:
Regulatory pathway complexity fragments addressable market access across jurisdiction-specific claim permissions.
- Food & Beverage:Functional positioning requires glycemic management substantiation under FDA GRAS self-affirmation or EFSA health claim frameworks. Clean-label procurement from Indian extraction facilities is displacing traditional distributor intermediaries in North American CPG development pipelines.
- Pharmaceuticals:Clinician-directed metabolic health formulations demand REACH-registered supply chains with captive analytical laboratories generating substance identity profiles for ECHA compliance. Sabinsa Corporation and Altrafine Gums compete on vertically integrated botanical sourcing and patented bioavailability enhancement.
- Nutraceuticals:Direct-to-consumer brands consolidate around clinically substantiated capsule and sachet formats capturing margin from consolidated supplement distribution.
- Cosmetics:Emulsion-stabilizing applications leverage fenugreek fiber's viscosity-building properties in natural formulation positioning for EU Green Deal-aligned personal care brands.
Volume concentration remains in Food & Beverage. Value expansion is climbing fastest in Pharmaceuticals.
Application:
Health claim substantiation requirements determine competitive moat depth across positioning categories.
- Dietary Supplements:Prebiotic and blood-sugar-management claims face tightening evidence standards favoring fenugreek fiber's established clinical dossier over newer soluble fiber entrants. Frutarom Health anchors positioning in flavor-masked fiber systems for functional beverage applications.
- Functional Foods:Bakery and beverage integration requires bitterness suppression technology convergence with galactomannan extraction to achieve clean-label acceptance in German and Dutch markets.
- Herbal Remedies:Traditional medicine positioning in India's FSSAI framework accelerates domestic approval velocity compared to EU novel food dossier timelines.
- Natural Health Products:Health Canada registration requirements for imported botanical extracts shape North American supplier qualification protocols beyond eighteen-month horizons.
Established penetration dominates Dietary Supplements. Accelerating formulation activity is concentrating in Functional Foods.
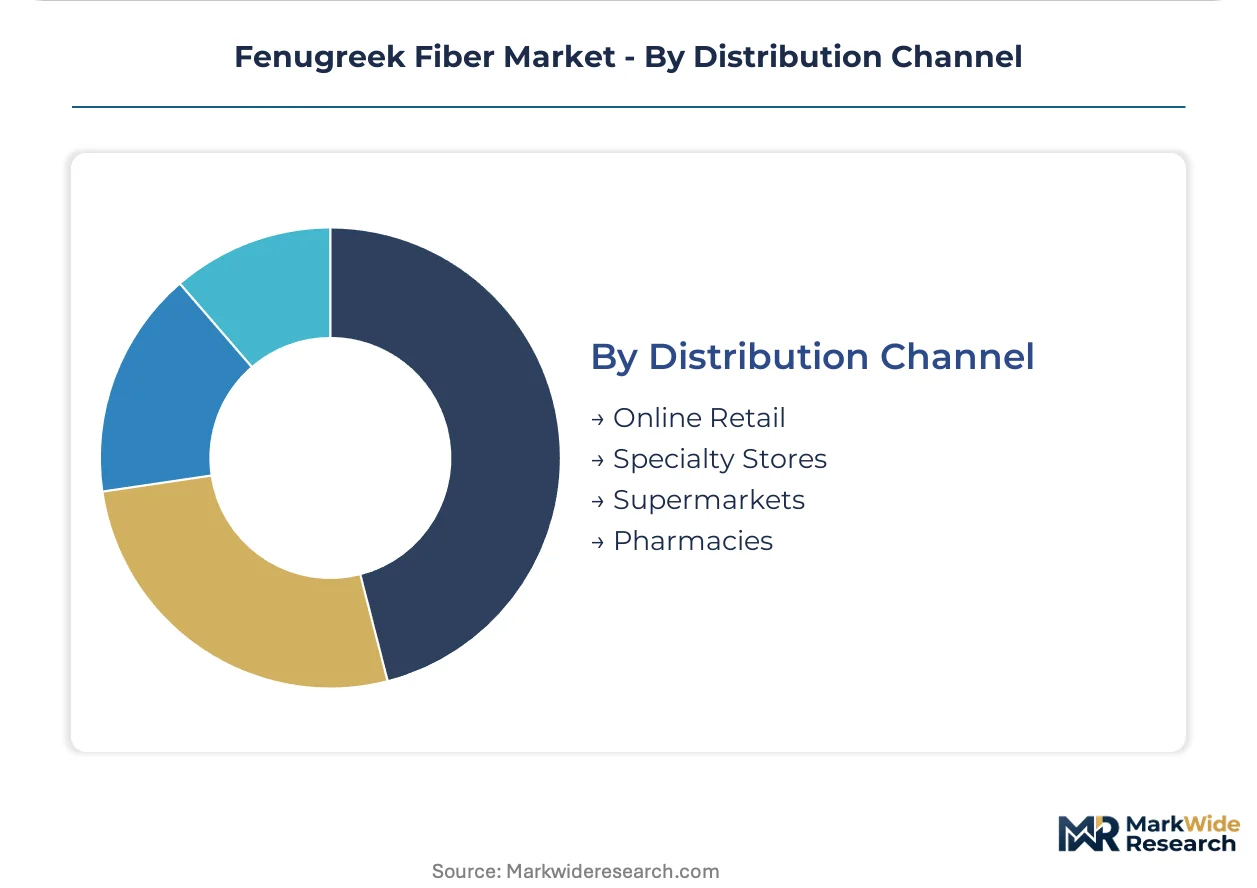
Distribution Channel:
Channel selection correlates with dosage format complexity and end-user technical sophistication.
- Online Retail:Direct-to-consumer brands bypass traditional ingredient supplier relationships through clinically substantiated capsule formats. California and New York metropolitan areas drive premium ingredient acceptance for metabolic health positioning.
- Specialty Stores:Curated natural product assortments in EU member states prioritize REACH-registered suppliers with established safety data packages.
- Supermarkets:Mass-market functional food placement requires cost-competitive powder forms from Gujarat and Rajasthan processing clusters scaling aqueous milling infrastructure.
- Pharmacies:Clinician-directed recommendation channels demand pharmaceutical-grade extract standardization with batch documentation for metabolic health formulations.
Traditional volume flows through Supermarkets. Channel expansion is gaining share fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India cultivates the bulk of raw fenugreek seed while the United States and Germany absorb refined galactomannan fractions for finished formulations. This production-consumption divide shapes logistics infrastructure and regulatory compliance investments across supplier networks.
United States
Functional food manufacturers in California and New York metropolitan areas drive clean-label prebiotic procurement from Indian extraction facilities. FDA GRAS self-affirmation pathways accelerate market entry velocity compared to European novel food timelines. Direct relationships between CPG developers and Gujarat-based processors are displacing traditional ingredient distributor intermediaries.
Germany
Functional beverage formulators in Germany adopt enzyme-refined fenugreek fractions for clean-label positioning in prebiotic applications. REACH registration requirements for imported botanical extracts extend supplier qualification periods beyond eighteen months. Bavarian and North Rhine-Westphalian processing hubs consolidate purchase orders around REACH-registered Indian suppliers with established safety data packages.
India
Gujarat and Rajasthan processing clusters scale aqueous milling infrastructure to capture contract manufacturing demand from North American brands. FSSAI functional food claims framework accelerates domestic approval velocity compared to EFSA dossier timelines. Mumbai and Ahmedabad serve as export logistics nodes for standardized galactomannan shipments.
France
Dietary supplement contract manufacturers in France prioritize REACH-registered supply chains with captive analytical laboratories. ANSM oversight of botanical health products shapes importer qualification protocols. Lyon and Paris metropolitan areas concentrate formulation activity for clinician-directed metabolic health products.
Netherlands
Frutarom Health anchors flavor-masked fiber system development for functional beverage applications targeting German and Dutch markets. EFSA novel food dossier requirements favor suppliers with established toxicology and exposure assessment capabilities. Rotterdam logistics infrastructure facilitates Indian extract importation for EU-wide distribution.
Fenugreek Fiber Market Competitive Landscape
The competitive structure tilts toward vertically integrated botanical processors with captive cultivation relationships and standardized extraction capabilities. Mid-scale Indian facilities compete on aqueous milling capacity while European and North American players differentiate through formulation technology and regulatory dossier expertise. Two strategic archetypes dominate: regional extraction specialists with backward integration into seed sourcing, and end-product formulators with patented delivery systems. Capacity expansion in Gujarat and Rajasthan processing clusters and strategic partnerships for REACH registration support represent the dominant competitive moves.
Among Indian extraction specialists, Altrafine Gums and Sabinsa Corporation occupy positions reflecting vertically integrated operational models. Frutarom Health exemplifies the formulation-technology archetype through flavor system integration. These three entities represent distinct competitive vectors: captive supply chain control, regulatory compliance infrastructure, and end-product application expertise.
| Leading Market Players |
|---|
| Altrafine Gums |
| Natural Agro Products |
| Frutarom Health |
| Nature's Own |
| GlucoBliss Pure |
| GNC Herbal Plus |
| Nature's Plus |
| Sabinsa Corporation |
| NutraGreen Biotechnology Co., Ltd. |
| Others |
Supply & Pricing Matrix
Monsoon-dependent fenugreek seed harvests in India's Gujarat and Rajasthan cultivation belt cascade downstream through three pricing strata, with raw material cost instability compressing processor margins during deficit crop cycles and forcing buyers toward long-term offtake contracts or spot-market premiums.
Pricing Analysis
Galactomannan standardization percentage anchors contract pricing across pharmaceutical-grade encapsulation tiers. Pricing stratifies across premium, standard, and economy tiers based on batch-to-batch consistency documentation and REACH registration status. Cost compression in commodity powder segments is intensifying because guar gum substitutes displace fenugreek fiber in viscosity-building applications. North American functional food manufacturers exhibit highest price sensitivity, while European dietary supplement formulators prioritize specification compliance over unit economics.
Supply Chain Analysis
Direct-to-CPG channels handle clean-label procurement demand from California and New York metropolitan developers. Raw material sourcing draws from Gujarat and Rajasthan processing clusters, with aqueous milling infrastructure scaling to capture North American contract manufacturing. Alcohol precipitation and enzyme-assisted refinement inputs hinge on specialized chemical supply chains. Single-source vulnerability concentrates in Indian seed cultivation belts exposed to monsoon variability. Distribution runs through Mumbai and Ahmedabad export logistics nodes for EU and North American pharmaceutical and nutraceutical buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures are mounting as EFSA novel food dossier requirements and REACH registration burdens force smaller Indian extraction facilities toward acquisition or exit.
For Market Incumbents: Acquire captive analytical laboratory capabilities to generate ECHA-compliant substance identity profiles. Altrafine Gums and Sabinsa Corporation should deepen upstream control over seed sourcing in Rajasthan to defend against margin compression from guar gum substitution. Certification investment in FSSAI functional food claims acceleration provides defensive moat against slower EU approval timelines. For New Entrants and Emerging Players: Functional beverage channels in Germany and the Netherlands offer lowest barrier to entry for enzyme-refined fenugreek fractions with clean-label prebiotic positioning. Flavor-masked fiber systems represent penetrable white space where extraction technology convergence with taste modulation creates defensible differentiation. Direct relationships with California CPG developers bypass established distributor intermediaries. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Indian processors with aqueous milling infrastructure but lacking EFSA dossier expertise. Long-term viability hinges on regulatory compliance capabilities spanning FDA GRAS self-affirmation, REACH registration, and FSSAI frameworks. Watch for consolidation signals when seed price volatility triggers margin distress among non-integrated processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Sourcing | Captive supply from Rajasthan cultivation belts insulates processors from monsoon-driven raw material cost spikes. |
| REACH Registration Completion | ECHA-compliant safety data packages unlock eighteen-month supplier qualification timelines for German and French pharmaceutical buyers. |
| Enzyme-Assisted Extraction Scale-Up | Refined galactomannan fractions command premium positioning in Dutch and German functional beverage prebiotic applications. |
| Flavor-Masked Fiber System Development | Bitterness suppression technology convergence creates defensible product differentiation for direct-to-consumer metabolic health brands. |
| Direct-to-CPG Channel Establishment | Bypassing traditional ingredient distributors captures margin from California and New York metropolitan clean-label procurement shifts. |
Research Methodology
Document review covered EFSA novel food dossier filings, FSSAI functional food claims registrations, and REACH registration databases, complemented by interviews with extraction facility technical directors, European dietary supplement formulators, and North American CPG procurement leads. Secondary validation drew from customs trade data, pharmaceutical-grade botanical extract import records, and aqueous milling capacity disclosures. Bottom-up triangulation across processing cluster outputs and top-down demand validation across end-use industries anchored market sizing.
Segment-level value projections across the analysis window reflect modeled galactomannan content tiers, pharmaceutical versus food-grade specification splits, and regional regulatory pathway velocities. CAGRs derived from regression analysis of historical seed price volatility, extraction capacity expansion rates, and substitution elasticity between fenugreek fiber and guar gum alternatives. Forecast inputs incorporated EFSA approval timeline distributions and FDA GRAS self-affirmation velocity patterns.
Caveats apply where EFSA toxicology evidence standard tightening, REACH registration cost escalation, or monsoon failure frequency could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Lignocellulosic Fibers Market
Natural Fibers
Jute Bags Market
Natural Fibers
Natural Fiber Reinforced Composites Market
Natural Fibers
Bamboo Fibers Market
Natural Fibers
Textile Staples Market
Natural Fibers
Global Alpaca Fiber Market
Natural Fibers
Silk Textiles Market
Natural Fibers
Sugarcane Fiber Bowls Market
Natural Fibers
Down and Feather Market
Natural Fibers
Indonesia Textiles Market
Natural Fibers
Eco Fibers Market
Natural Fibers
North America Alpaca Fiber Market
Natural Fibers
Hessian Sacks Market
Natural Fibers
Apple Fiber Market
Natural Fibers
Acacia Fiber Powder Market
Natural Fibers
Silk Fabric Market