
 Global Alpaca Fiber Market | 2026-2036
Global Alpaca Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Global Alpaca Fiber Market Foresight
Premium-grade fiber tiers is rotating toward the center of commercial strategy as spinners and brands command higher unit economics for Baby Royal Alpaca and Royal Alpaca classifications. Michell Group leverages its integrated Peruvian operations to secure consistent micron counts for luxury clients. Inca Tops S.A. sustains vertical control from raw fleece to finished tops, insulating margin pools from spot fiber volatility. The Alpaca Yarn Company differentiates through artisan-scale batch production for specialty retail channels.
Alpaca fiber is a protein-based natural textile material composed of keratin with a hollow core structure that delivers thermal insulation at weights lighter than sheep wool, typically grading between 15 and 30 microns depending on animal age and breed. Its primary commercial purpose centers on cold-weather apparel, luxury accessories, and interior textiles where warmth-to-weight ratio and hypoallergenic properties justify price premiums over competing natural fibers. Huacaya fiber dominates volume throughput due to its crimped structure and broader availability across Andean herds, while Suri commands narrower supply and higher price realization in couture applications. The End Use Industry dimension shows Luxury Goods and Apparel segments capturing the majority of value pools as direct-to-consumer channels bypass traditional wholesale markups.
Peru's national quality certification system and the EU REACH framework govern chemical inputs in dyeing and finishing stages, restricting azo dyes and formaldehyde-based treatments that processors in Arequipa and Lima must now replace with bio-based alternatives. ISO 9001 and OEKO-TEX standards shape export eligibility for European and North American buyers, effectively filtering market access to facilities with documented traceability and environmental management systems. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's due diligence requirements recalibrate sourcing priorities for fiber traders and finished goods importers.
Market Dynamics
Peru's dominance in raw alpaca supply is concentrating bargaining power among Arequipa-based processors while EU REACH compliance costs filter out smaller dye houses across Europe. This structural asymmetry between fiber origin and finished goods markets shapes margin distribution along the value chain.
Growth Catalysts
- EU Green Deal due diligence:Mandatory supply chain disclosure requirements favor traceable Peruvian fiber with documented chain of custody over untraceable alternatives.
- Cold-weather performance apparel:Outdoor brands specify hollow-core alpaca insulation for expedition-grade base layers where warmth-to-weight ratios command technical premiums.
- China:Dual carbon goals accelerate substitution of synthetic fleece with low-carbon natural fibers in domestic luxury apparel manufacturing.
Market Restraints
- Feed input volatility:Altitude-dependent pasture degradation in the Peruvian Andes creates irregular fleece quality and micron count variation.
- Single-origin supply risk:Over 80% of global alpaca herds concentrate in Peru's Puno and Arequipa regions, exposing buyers to climate and political disruption.
- Merino wool substitution:Australian superfine merino below 18 microns competes directly with Baby Alpaca in luxury knitwear applications.
Strategic Opportunities
- Bio-based dye convergence:Partnerships between Peruvian processors and European natural dye innovators unlock EU market access without synthetic chemistry.
- Direct-to-consumer channels:Heritage alpaca brands bypass wholesale markups through owned e-commerce and flagship retail in Germany and Japan.
- Interior textiles:High-end hospitality and residential upholstery specifications for hypoallergenic, flame-resistant throws and blankets remain underdeveloped versus apparel saturation.
Industry Challenges
- Master sorter scarcity:Traditional hand-sorting expertise for micron-grade classification is not transferring to younger workers in Andean processing centers.
- OEKO-TEX certification timelines:Small-batch artisan spinners face 12-18 month documentation gaps that exclude them from European department store procurement.
- Legacy inventory systems:Peruvian cooperatives lack lot-level traceability software to meet EU CSRD supply chain disclosure mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Alpaca Fiber Market |
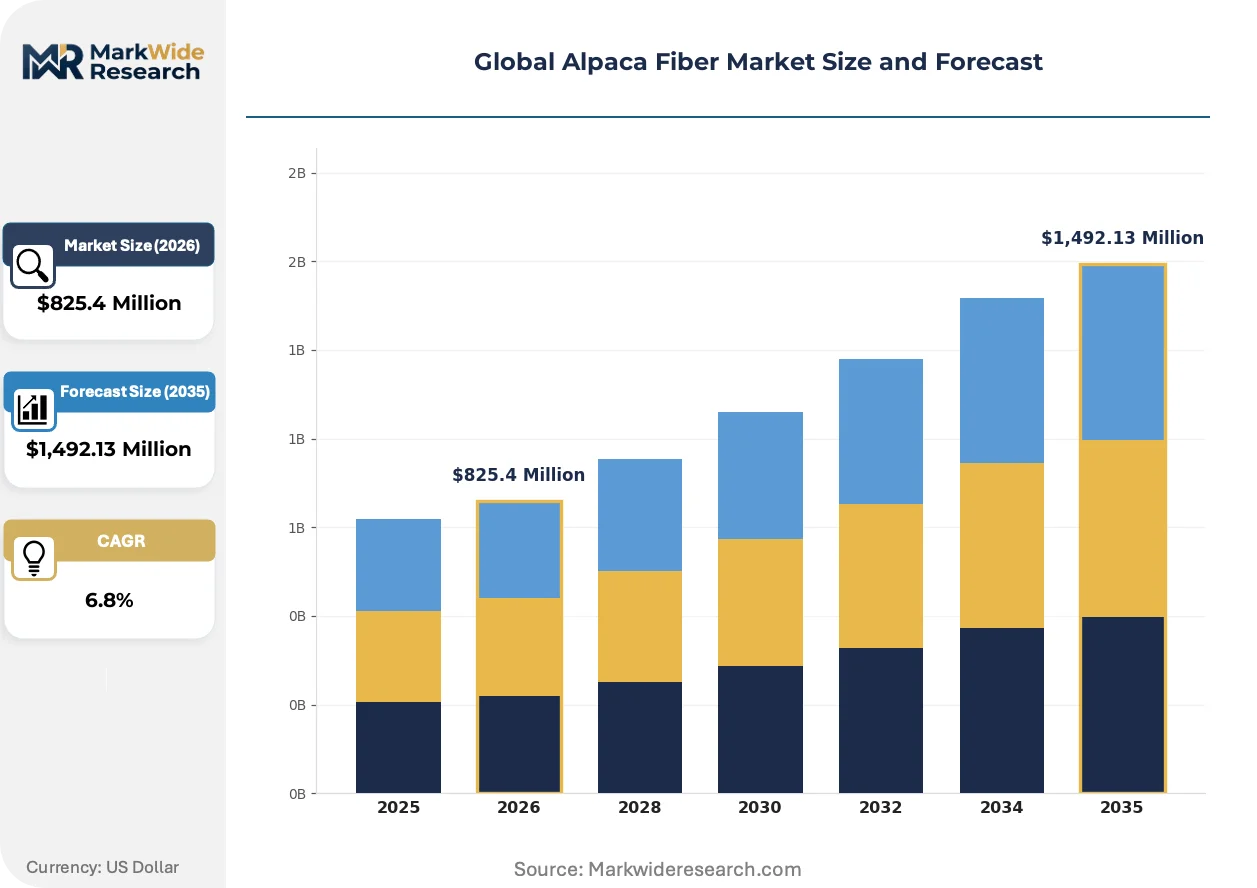
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,492.13 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fiber Type: Huacaya, Suri, Royal Alpaca, Baby Alpaca, Baby Royal Alpaca End Use Industry: Apparel, Home Textiles, Handicrafts, Luxury Goods, Interior Décor Processing Method: Carding, Spinning, Dyeing, Weaving, Knitting Distribution Channel: Wholesalers, Retailers, Online Platforms, Specialty Stores, Exporters |
| Companies Covered | Michell Group, Inca Tops S.A., The Alpaca Yarn Company, The Natural Fibre Company, AHA Bolivia, Altifibers S.A., Plymouth Yarn Company, New Era Fiber, Zeilinger Wool Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Alpaca Fiber Market Shifts & Advancements
Digital traceability infrastructure and bio-processing chemistry are compressing the gap between Andean raw fiber and finished European luxury goods, collapsing traditional intermediary layers.
NIR spectroscopy grading is decomposing the artisan sorter bottleneck in Peruvian collection facilities. Large-scale Huacaya processors deploy portable near-infrared devices to classify fleece micron counts at shearing points, compressing the classification timeline from weeks to hours. This compression enables just-in-time fiber allocation to European spinners with tight delivery windows.
REACH Annex XVII restrictions on azo dyes and formaldehyde-based finishing agents are forcing Arequipa dye houses to replace conventional chemistry with bio-based alternatives. ECHA enforcement actions against non-compliant textile imports have accelerated adoption of enzyme-based scouring and natural mordant systems. German and Swiss luxury brands now require REACH-compliant dye documentation as a condition of purchase order release.
Certification-driven procurement is fragmenting buyer concentration as smaller direct-to-consumer labels bypass traditional wholesale distributors. North American specialty retailers specify OEKO-TEX Standard 100 and Responsible Wool Standard equivalents for alpaca accessories, shifting volume toward vertically integrated Peruvian mills with in-house certification capability. This fragmentation is most visible in the United States and Canadian markets where boutique e-commerce brands command premium positioning through documented provenance storytelling.
Global Alpaca Fiber Market Segmentation
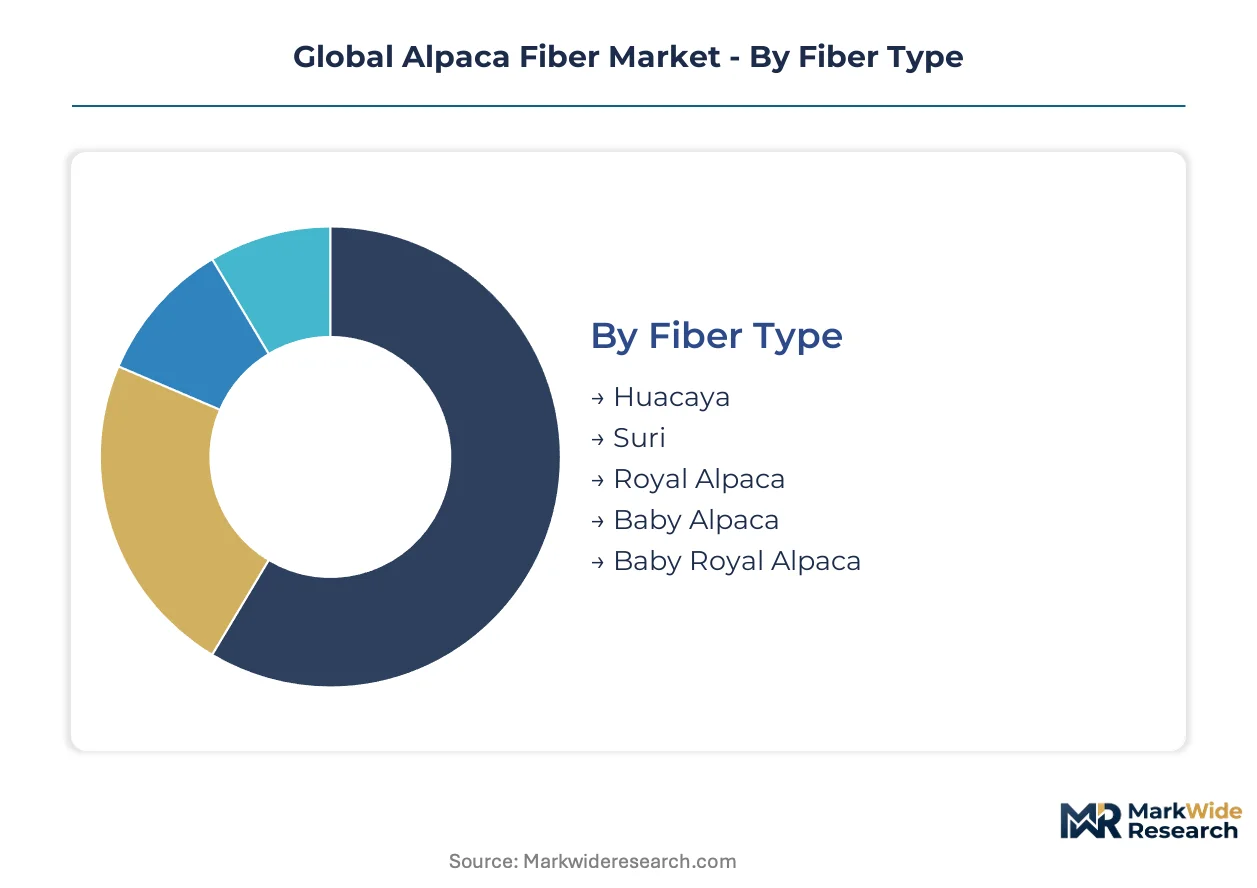
Alpaca fiber markets stratify across micron-grade tiers and processing stages that command vastly different price realizations. Distinct certification thresholds and end-use specifications create non-substitutable demand pools that processors must navigate separately.
Fiber Type:
Domestic Peruvian consumption concentrates in standard Huacaya grades for local textile manufacturing, while export-led demand drives premiums for certified Baby Royal Alpaca and Royal Alpaca classifications in European and Japanese luxury markets.
- Huacaya:Crimped fiber structure delivers loft and elasticity for bulk knitwear applications. Arequipa-based spinners process this grade for German and US outdoor apparel brands seeking warmth-to-weight performance at accessible price points.
- Suri:Silky, lustrous locks with minimal crimp suit high-end draped garments and couture accessories. Italian and French fashion houses specify Suri for limited-run evening wear where drape and sheen justify procurement premiums over Huacaya alternatives.
- Royal Alpaca:Sub-19 micron classification reserved for elite fiber batches meeting strict diameter uniformity standards. Japanese luxury retailers and Swiss heritage brands dominate offtake.
- Baby Alpaca:First shearing fiber from young animals, typically 22-23 microns, bridging premium and accessible luxury segments. North American direct-to-consumer labels favor this grade for provenance storytelling.
- Baby Royal Alpaca:Rare intersection of youth-derived fineness and Royal-grade micron thresholds. Parisian and Milanese couture houses secure forward contracts for this classification.
Huacaya commands the established base. The steepest expansion runs through Baby Royal Alpaca.
End Use Industry:
Margin structures diverge sharply between volume-driven apparel categories and specification-heavy interior applications where flame resistance and hypoallergenic certification unlock architectural procurement channels.
- Apparel:Cold-weather knitwear, base layers, and outerwear represent the dominant throughput channel. Outdoor technical brands in the United States and Germany specify hollow-core alpaca insulation for expedition-grade performance.
- Luxury Goods:Scarves, wraps, and accessories carry the highest unit economics per kilogram of fiber. Japanese department stores and Parisian boutiques drive consistent offtake for micron-certified small-batch production.
- Home Textiles:Blankets and throws for residential use compete with cashmere and merino alternatives on warmth and tactile properties. North American specialty retailers represent the primary demand concentration.
- Interior Décor:Hospitality upholstery and residential drapery applications remain underdeveloped versus apparel saturation. Dubai and London high-end hotel fit-outs increasingly specify alpaca for hypoallergenic, flame-resistant properties.
- Handicrafts:Artisan knitting and small-batch weaving sustain local Andean economies. Tourist markets in Cusco and Lima absorb significant domestic volume.
Apparel absorbs the majority of raw fiber volume. Luxury Goods generates the highest value per kilogram.
Processing Method:
Capital intensity and regulatory compliance requirements concentrate advanced processing stages in Peruvian coastal facilities with EU REACH certification, while inland carding and preliminary sorting serve domestic and regional markets.
- Carding:Mechanical fiber alignment prepares fleece for subsequent spinning stages. Arequipa processors deploy automated carding lines for Huacaya volume throughput destined for export markets.
- Spinning:Worsted and woolen spinning systems convert prepared tops into yarn counts specified by European and Japanese knitwear manufacturers. Michell Group and Inca Tops S.A. operate integrated spinning capacity.
- Dyeing:REACH Annex XVII restrictions on azo dyes and formaldehyde-based finishing agents force Arequipa dye houses toward enzyme-based scouring and natural mordant systems. ECHA enforcement actions accelerate compliance investment.
- Weaving:Loom-based fabric production for interior textiles and apparel suiting concentrates in Lima-based mills with OEKO-TEX certification. German and Swiss buyers require documented dye documentation as a purchase order condition.
- Knitting:Circular and flat-bed knitting of finished yarn occurs across Peru, Italy, and Scotland for brand-specific garment production. Scottish knitwear manufacturers source certified Baby Alpaca tops for heritage sweater lines.
Carding and spinning anchor the volume base. Dyeing commands the steepest compliance-driven investment trajectory.
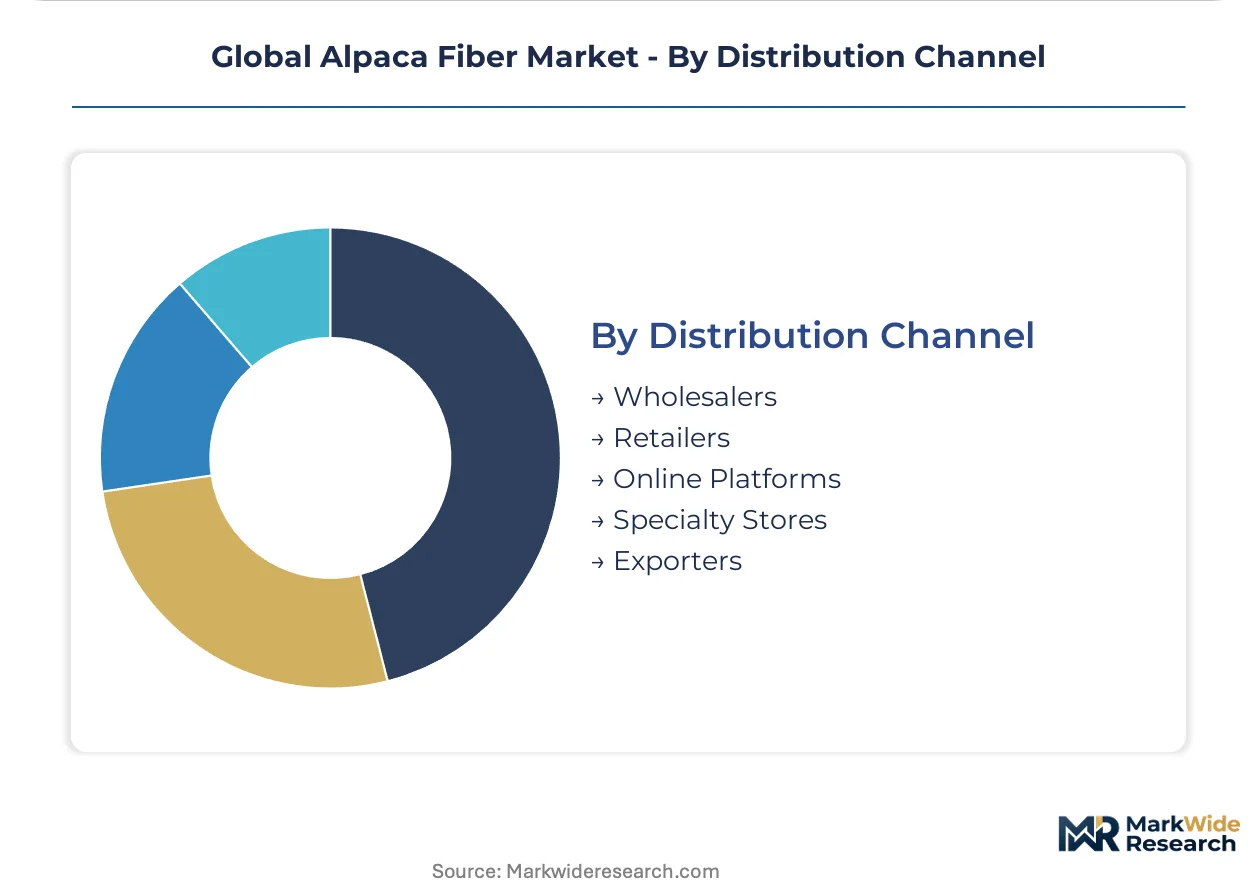
Distribution Channel:
Direct-to-consumer fragmentation is displacing traditional wholesale concentration as North American and European specialty retailers build owned e-commerce and flagship retail networks.
- Wholesalers:Traditional fiber traders and yarn distributors in Arequipa and Lima aggregate production from multiple cooperatives for export to Italian and Scottish spinning mills. Margin compression from certification requirements is filtering smaller traders from European market access.
- Specialty Stores:Boutique retailers in Germany, Japan, and Canada emphasize provenance storytelling and micron certification for premium positioning. These channels bypass wholesale markups through vertical relationships with Peruvian mills.
- Online Platforms:Direct-to-consumer e-commerce enables heritage alpaca brands to reach end-users without intermediary layers. US and Canadian boutique labels leverage Shopify and owned sites for margin capture.
- Retailers:Department store and multi-brand boutique networks in Paris, Tokyo, and New York maintain selective alpaca accessory assortments. OEKO-TEX and Responsible Wool Standard equivalents are becoming mandatory for shelf placement.
- Exporters:Peruvian export houses manage customs documentation, phytosanitary certification, and logistics for raw fiber and finished yarn shipments. EU CSRD supply chain disclosure mandates are forcing upgrades to lot-level traceability systems.
Wholesalers retain volume dominance in raw fiber. Specialty stores and online platforms are gaining share fastest in finished goods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peruvian buyers exhibit the lowest price elasticity as domestic processors absorb standard Huacaya grades for local textile manufacturing. German and Japanese luxury consumers demonstrate the highest willingness to pay premiums for certified Baby Royal Alpaca and Royal Alpaca classifications.
Peru
Domestic consumption of standard Huacaya grades sustains Arequipa-based spinning mills for local knitwear production. The national quality certification system governs micron-grade classification for export eligibility. Puno and Arequipa regions concentrate over 80 percent of global alpaca herds, with climate-driven pasture degradation creating irregular fleece quality.
Germany
Outdoor technical brands specify hollow-core alpaca insulation for expedition-grade base layers where warmth-to-weight ratios command technical premiums. REACH Annex XVII restrictions on azo dyes and formaldehyde-based finishing agents enforce strict import documentation requirements. Berlin and Munich specialty retailers drive direct-to-consumer channel expansion through owned e-commerce platforms.
Japan
Department stores in Tokyo and Osaka maintain consistent offtake for micron-certified small-batch luxury accessories. METI guidelines on sustainable textile procurement favor documented chain-of-custody fiber from Peruvian exporters. Japanese luxury retailers dominate forward contracting for Royal Alpaca and Baby Royal Alpaca classifications.
United States
North American specialty retailers emphasize provenance storytelling for Baby Alpaca accessories through boutique e-commerce labels. OEKO-TEX Standard 100 certification is becoming mandatory for department store shelf placement in New York and Los Angeles. Direct-to-consumer brands leverage Shopify and owned sites to bypass wholesale markups.
China
Dual carbon goals accelerate substitution of synthetic fleece with low-carbon natural fibers in domestic luxury apparel manufacturing. MIIT standards on textile sustainability shape procurement priorities for Shanghai and Beijing-based fashion houses. Yangtze River Delta processors increasingly specify traceable Peruvian fiber for premium outerwear lines.
Global Alpaca Fiber Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the alpaca fiber value chain. Vertically integrated Peruvian processors command micron consistency and certification capabilities that fragmented artisan spinners cannot replicate. The market stratifies into three archetypes: integrated Andean processors with captive raw fiber supply, European specialty spinners with heritage brand relationships, and North American direct-to-consumer labels with owned retail channels. Dominant competitive moves include backward integration into raw fiber sourcing and geographic expansion into Asian luxury markets.
Among Peruvian integrated processors, Michell Group and Inca Tops S.A. exemplify the archetype of operators with captive control from raw fleece through finished tops. The Alpaca Yarn Company represents the artisan-scale batch production segment serving specialty retail channels with differentiated provenance positioning. These three anchors illustrate the divergence between volume-driven integrated operations and niche-focused craft-oriented suppliers.
| Leading Market Players |
|---|
| Michell Group |
| Inca Tops S.A. |
| The Alpaca Yarn Company |
| The Natural Fibre Company |
| AHA Bolivia |
| Altifibers S.A. |
| Plymouth Yarn Company |
| New Era Fiber |
| Zeilinger Wool Company |
| Others |
Supply & Pricing Matrix
Long-term forward contracting between Arequipa-based processors and European luxury spinners locks in both fiber access and price visibility for Baby Royal Alpaca and Royal Alpaca grades, insulating premium tiers from spot market volatility while concentrating margin capture among vertically integrated Peruvian operators with documented REACH compliance.
Pricing Analysis
EU REACH Annex XVII dictates the pricing tier structure across the alpaca fiber market, separating certified bio-based dye lots from conventional chemistry-dependent inventory. Pricing stratifies across premium, standard, and economy tiers based on micron certification grade and OEKO-TEX Standard 100 compliance status. Cost compression in standard Huacaya grades is intensifying because Australian superfine merino below 18 microns competes directly in knitwear applications. Domestic Peruvian processors exhibit the lowest price elasticity as they absorb local supply, while Japanese department store buyers demonstrate minimal sensitivity for Royal Alpaca forward contracts.
Supply Chain Analysis
Peru and Bolivia anchor global raw alpaca fiber production, with over 80 percent of herds concentrated in Puno and Arequipa regions. Processing draws from altitude-dependent pasture inputs, traditional hand-sorting labor pools, and enzyme-based dye chemistry substitutes for azo dye restrictions. Single-origin concentration in the Peruvian Andes exposes buyers to climate-driven pasture degradation and political disruption risks. Distribution runs through Arequipa-based export houses managing phytosanitary documentation for European and North American spinners, with direct-to-consumer channels bypassing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australian superfine merino substitution in luxury knitwear represents the immediate threat that alpaca fiber incumbents must navigate through certification differentiation and provenance storytelling.
For Market Incumbents: Consolidate micron-grade classification capabilities through NIR spectroscopy deployment at shearing points, compressing classification timelines from weeks to hours. Secure backward integration into cooperative-level fiber sourcing to lock in Baby Royal Alpaca supply before competitors. Counter merino substitution by embedding OEKO-TEX and REACH documentation into every purchase order release for European buyers. For New Entrants and Emerging Players: Artisan-scale batch production for North American specialty retailers represents the most penetrable white-space target, as incumbent processors optimize for volume throughput over small-batch flexibility. Direct-to-consumer e-commerce channels enable margin capture without wholesale markups through Shopify-native provenance storytelling. Target interior textiles for hospitality upholstery in Dubai and London, where hypoallergenic flame-resistant specifications remain underdeveloped versus apparel saturation. For Investors and Strategic Acquirers: Mid-scale Peruvian processors with in-house dye house REACH certification and lot-level traceability software represent the priority acquisition archetype for exposure to EU Green Deal due diligence tailwinds. Long-term viability hinges on fiber origin concentration persisting as a sourcing risk that commands premium pricing for diversified supply chain solutions. Watch for ECHA enforcement acceleration against non-compliant textile imports as the inflection signal for certification-capable asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperative Sourcing | Captive Baby Royal Alpaca supply secures forward contracts with Parisian couture houses. |
| NIR Spectroscopy Deployment | Portable grading devices at Puno shearing points compress classification timelines for just-in-time European allocation. |
| Bio-Based Dye House Certification | Enzyme-based scouring systems unlock German and Swiss luxury brand procurement conditional on REACH Annex XVII documentation. |
| Direct-to-Consumer Channel Launch | Owned e-commerce platforms bypass wholesale markups for North American specialty retail margin capture. |
| Interior Textile Specification Push | Hypoallergenic flame-resistant throws penetrate Dubai and London hospitality fit-outs beyond apparel saturation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork, including alpaca fiber processors in Arequipa and Lima, luxury knitwear procurement managers at German and Japanese brands, and specialty retail buyers in North America. Secondary validation drew from EU ECHA enforcement records, Peruvian national quality certification system documentation, OEKO-TEX Standard 100 registry data, and customs trade statistics for raw fiber shipments. Bottom-up fiber volume estimates from cooperative-level production data were triangulated against top-down apparel and luxury goods consumption patterns across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions including fiber type tier, end-use industry, processing stage, and distribution channel. CAGRs were derived from trend extrapolation of micron-grade price realizations and certification-driven procurement shifts. Forecast inputs incorporated pasture degradation patterns affecting fleece quality variation and dual carbon goal acceleration in Chinese luxury apparel manufacturing.
Forecasts assume regulatory continuity in EU REACH Annex XVII enforcement and METI sustainable textile guidelines; material policy shifts would require re-modeling. Specific risks that could revise projections include ECHA import restriction escalation, Peruvian political disruption affecting Puno herd access, and breakthrough merino wool marketing campaigns displacing Baby Alpaca positioning. Recalibration cycles align with material shifts in certification mandate adoption and climate-driven fleece quality variation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Global Rattan Products Market
Natural Fibers
Silk Mask Market
Natural Fibers
North America Textile Market
Natural Fibers
Spent Coffee Grounds Fiber Market
Natural Fibers
Silk Textiles Market
Natural Fibers
Sugarcane Fiber Bowls Market
Natural Fibers
Lignocellulosic Fibers Market
Natural Fibers
Natural Fiber Composite (NFC) Market
Natural Fibers
Cellulose Fiber Market
Natural Fibers
Textile Staples Market
Natural Fibers
Down and Feather Market
Natural Fibers
Natural Fibers Market
Natural Fibers
Global Cotton Market
Natural Fibers
Eco Fibers Market
Natural Fibers
Silk Market
Natural Fibers
Woolen Textiles Market