
 Spent Coffee Grounds Fiber Market | 2026-2036
Spent Coffee Grounds Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Spent Coffee Grounds Fiber Market Insights
The performance gap between premium functional textiles and commodity-grade fillers is broadening as certification standards tighten. SINGTEX Industrial leverages proprietary spinning technology to command top-tier positioning in moisture-wicking fabrics. FASLINK JSC anchors its supply chain through direct partnerships with Vietnamese coffee processors. Bio-bean differentiates by converting London-collected grounds into standardized feedstock for multiple downstream sectors.
Spent coffee grounds fiber comprises cellulose, hemicellulose, and lignin extracted from post-brewing residue, typically yielding fibers 10-50 micrometers in diameter with inherent antimicrobial and UV-blocking properties suitable for textile and composite applications. Dry fiber dominates current output volumes due to lower processing energy requirements, while activated carbon commands the strongest margin pool from filtration and energy storage buyers. Composite materials represents the fastest-growing application channel as automotive and construction sectors seek density-reduced, bio-sourced reinforcement.
REACH compliance in Europe and FDA GRAS recognition in the United States shape ingredient acceptance for cosmetics and food-contact packaging applications, while BIS textile labeling rules in India govern fiber content disclosure for consumer garments. The EU F-Gas Regulation indirectly accelerates coffee ground valorization by raising costs on synthetic refrigerants used in conventional cold-chain logistics for fresh biomass. Stakeholders must track evolving compostability certifications and polymer-blend ratio caps that will determine which processing technologies achieve commercial scale.
Market Dynamics
The EU Green Deal's binding bio-based material quotas are redirecting R&D budgets toward agricultural waste valorization, compressing development timelines for fiber extraction technologies while tightening certification requirements for textile applications.
Growth Catalysts
- EU F-Gas Regulation:Synthetic refrigerant cost escalation under the 2024 phase-down schedule is accelerating cold-chain biomass logistics redesign, favoring stabilized dry fiber feedstocks over perishable alternatives.
- Antimicrobial yarn demand:Performance apparel manufacturers in Vietnam's export-oriented spinning mills are integrating spent coffee grounds fiber into moisture-wicking base layers for outdoor and athletic wear.
- REACH compliance pathways:ECHA's streamlined notification procedures for bio-based polymers are reducing registration barriers for cellulose-hemicellulose fiber blends in EU consumer textiles.
Market Restraints
- Input cost volatility:Robusta and Arabica bean price swings transmit directly to ground residue availability, squeezing processor margins during harvest shortfalls in Brazil and Vietnam.
- Supply concentration risk:Over 60% of collectible grounds originate from three metropolitan roasting clusters, creating single-point vulnerability for standardized feedstock contracts.
- Technical limitation:Lignin content above 15% degrades tensile strength in fine-denier yarn spinning, restricting applications to coarser textile grades and composite fillers.
Strategic Opportunities
- Underpenetrated geography:Indonesia's nascent specialty coffee sector generates 400,000+ tonnes of untreated grounds annually, with minimal current collection infrastructure outside Jakarta and Surabaya.
- Technology convergence:Supercritical CO2 extraction paired with enzymatic lignin reduction is opening medical-grade fiber grades for wound dressing and surgical mesh applications.
- Regulatory tailwind:India's BIS textile labeling amendments are mandating fiber origin disclosure, creating premium positioning potential for traceable agricultural waste inputs.
Industry Challenges
- Certification timeline compression:OEKO-TEX and GOTS organic textile standards require 18-24 month validation cycles for novel fiber blends, delaying commercial launches.
- Skill gap in polymer blending:Formulation chemists with simultaneous expertise in natural fiber surface modification and thermoplastic compounding remain scarce in Southeast Asian manufacturing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spent Coffee Grounds Fiber Market |
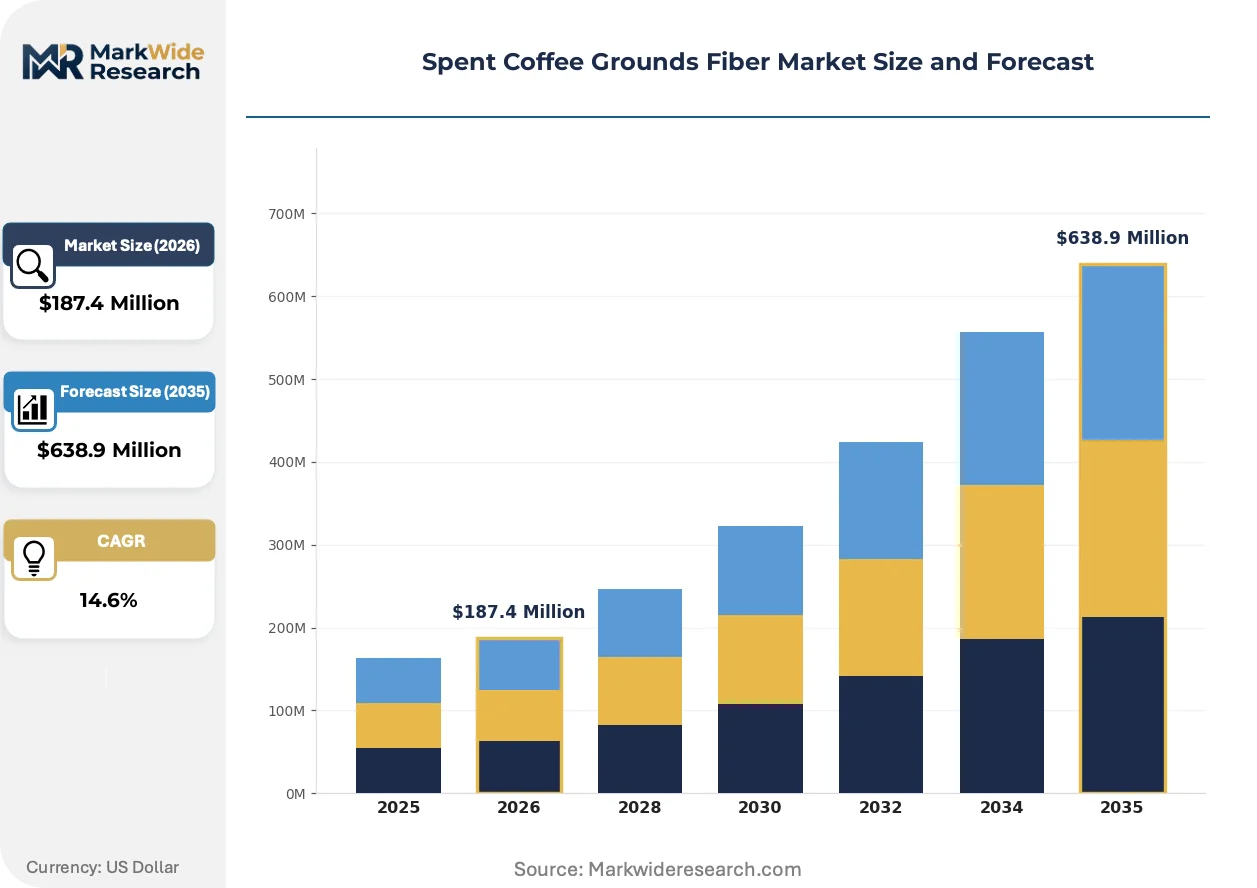
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Fiber, Biochar, Activated Carbon, Pellets, Liquid Extract Application: Composite Materials, Animal Feed, Biofuel, Cosmetics, Packaging Processing Technology: Mechanical Extraction, Thermal Treatment, Chemical Modification, Enzymatic Hydrolysis End User Industry: Construction, Personal Care, Agriculture, Energy, Textiles |
| Companies Covered | SINGTEX Industrial, FASLINK JSC, Smartex Yarn Corp., Bao Lan Textile, Thai Son S.P Sewing Factory, Jay Ho Corp., Jia-Zhan Textile, Bio-bean, FLOCUS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spent Coffee Grounds Fiber Market Trends and Innovations
Processing technology maturation is bifurcating the competitive landscape between premium functional grades and commodity fillers, with certification standards acting as the decisive sorting mechanism rather than raw material cost alone.
Enzymatic lignin extraction is consolidating technical leadership among fiber processors capable of achieving sub-10% lignin content. Automotive interior suppliers in Germany and Japan are qualifying these grades for dashboard and door panel substrates under OEM sustainability scorecards. The technology is consolidating market share in density-reduced composite applications where synthetic glass fiber substitution carries explicit carbon accounting value.
REACH substance restriction updates are tightening extractable heavy metal limits for textile-grade cellulose fibers. ECHA's 2024 draft guidance on recycled biomass contaminants is forcing processors to install additional washing and ion-exchange purification stages. Vietnamese and Indonesian exporters are responding by segregating collection streams between food-service and industrial roasting residues to reduce contamination risk.
Brand sustainability teams are rewriting fiber procurement specifications to require third-party verified agricultural waste content. Direct contracting between spinning mills and coffee processors is displacing spot-market trading in Vietnam's Central Highlands and Brazil's Minas Gerais states. This pattern is most visible in premium outdoor apparel supply chains where fiber origin traceability commands measurable price premiums over undifferentiated recycled polyester alternatives.
Spent Coffee Grounds Fiber Market Segmentation
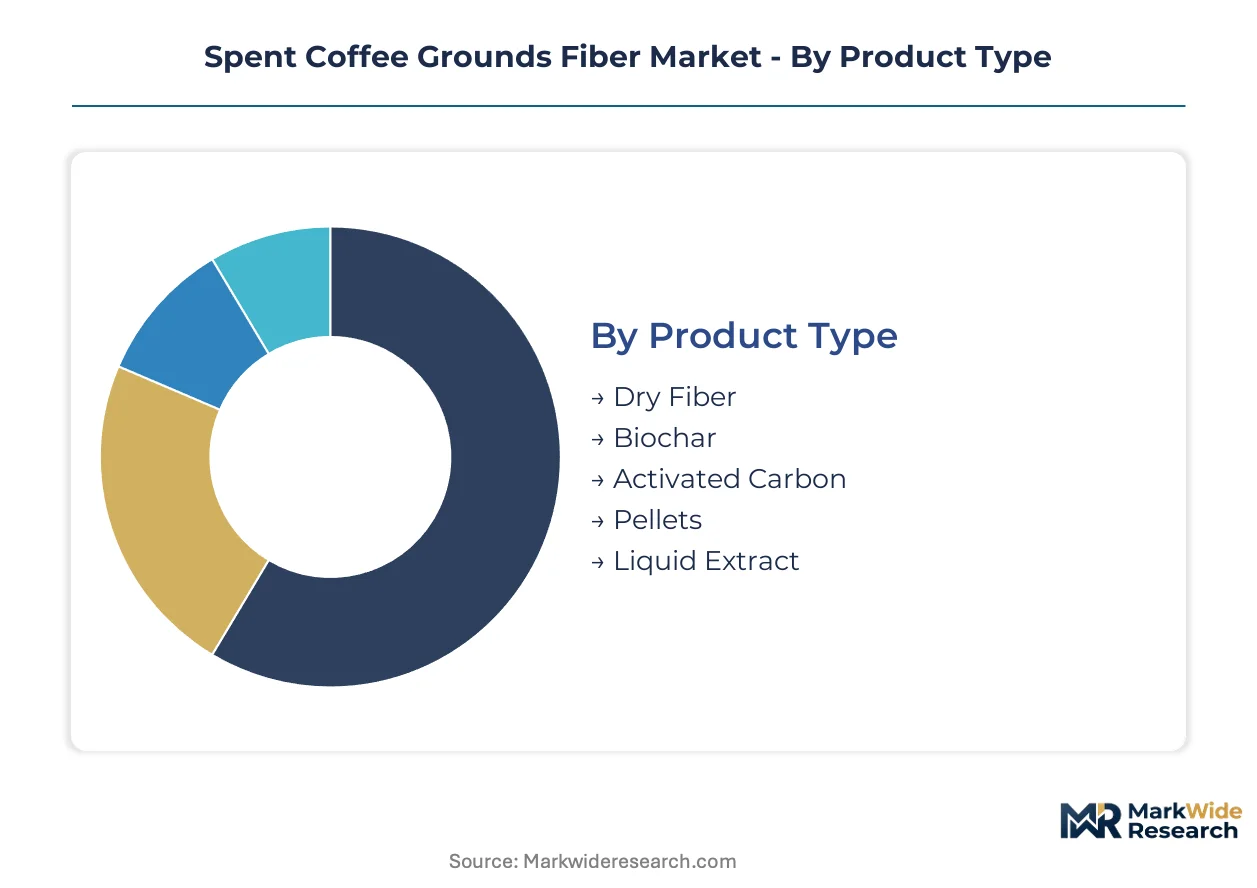
Segmentation in the spent coffee grounds fiber market reveals how capital deployment and technical capability determine competitive position. Processing intensity varies dramatically across product grades, with downstream certification requirements dictating which segments justify equipment investment.
Product Type:
Dry fiber production demands the lowest capital outlay, while activated carbon and enzymatically refined grades require multi-million dollar processing trains.
- Dry Fiber:Cellulose-hemicellulose matrix with 10-50 micrometer diameters extracted through mechanical pressing and thermal stabilization. Vietnam's export-oriented spinning mills absorb the majority of commodity-grade output for moisture-wicking textile applications, constrained by lignin content limits in fine-denier yarn spinning.
- Activated Carbon:High-surface-area filtration media produced through controlled pyrolysis and steam activation. Energy storage and water purification buyers in Germany and Japan command the strongest margin pool, driven by OEM sustainability scorecards requiring bio-sourced carbon alternatives.
- Biochar:Soil amendment grade with lower porosity than activated carbon, serving agricultural carbon sequestration programs.
- Pellets:Densified fuel feedstock for biomass boilers and industrial heat applications.
- Liquid Extract:Aqueous suspensions of coffee ground compounds for cosmetics and food-contact packaging formulations.
Dry fiber absorbs the bulk of installed capacity; activated carbon is expanding most quickly.
Application:
End-use diversification separates commodity processors from integrated solution providers with formulation expertise.
- Composite Materials:Density-reduced reinforcement for automotive dashboards and construction panels. German and Japanese automotive interior suppliers are qualifying sub-10% lignin grades under explicit carbon accounting frameworks, displacing synthetic glass fiber in door panel substrates.
- Textiles:Antimicrobial yarn for performance apparel. SINGTEX Industrial commands premium positioning through proprietary spinning technology that achieves consistent fiber diameter distribution.
- Cosmetics:Exfoliant and active ingredient applications governed by FDA GRAS recognition in the United States and REACH compliance in Europe.
- Packaging:Bio-based filler for food-contact materials requiring heavy metal limits under ECHA's 2024 draft guidance on recycled biomass contaminants.
- Animal Feed:Protein-supplemented fiber additive for ruminant nutrition, limited by mycotoxin risk in unsegregated collection streams.
- Biofuel:Pelletized combustion feedstock and anaerobic digestion substrate for biogas production.
Composite materials deployment is climbing the fastest as automotive lightweighting mandates intensify; textiles maintain the deepest existing penetration.
Processing Technology:
Technology selection locks in margin structure and certification eligibility for downstream segments.
- Mechanical Extraction:Dry fiber production through pressing and milling without chemical intervention. Lowest energy input but highest lignin retention, restricting output to coarser textile grades and composite fillers.
- Enzymatic Hydrolysis:Selective lignin reduction using cellulase and laccase cocktails. Medical-grade fiber grades for wound dressing applications are opening through this route, with supercritical CO2 extraction integration consolidating technical leadership among premium processors.
- Thermal Treatment:Pyrolysis and carbonization for biochar and activated carbon production.
- Chemical Modification:Surface functionalization and bleaching for cosmetic and packaging-grade purity.
Mechanical extraction holds the largest equipment base; enzymatic hydrolysis is gaining share fastest among new capacity announcements.
End User Industry:
Industry verticals impose distinct purity, traceability, and volume requirements that reshape procurement patterns.
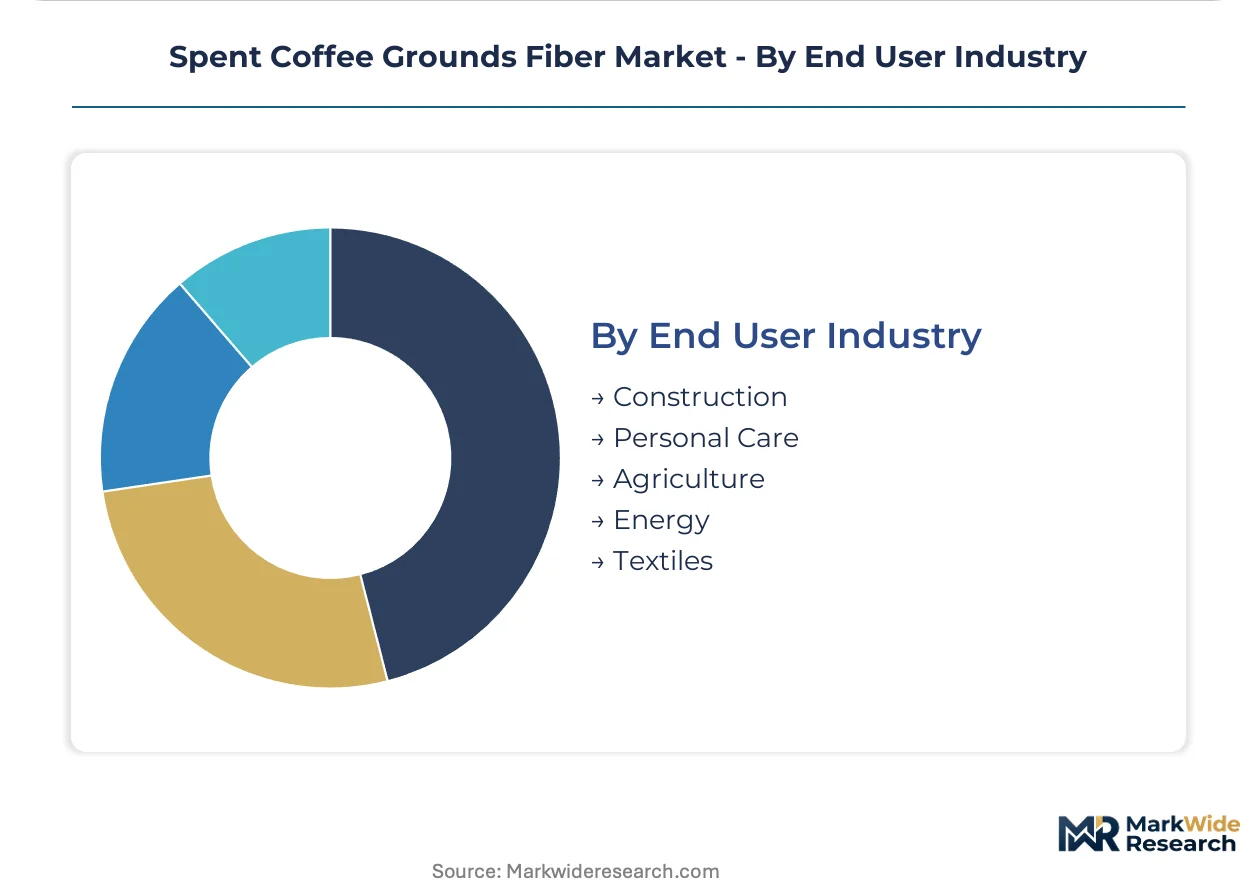
- Textiles:Performance apparel and technical fabric manufacturers. India's BIS textile labeling amendments mandating fiber origin disclosure are creating premium positioning for traceable agricultural waste inputs.
- Construction:Insulation and lightweight concrete reinforcement. Density-reduced composite specifications favor dry fiber with controlled moisture content.
- Personal Care:Cosmetics and personal hygiene product formulators. REACH substance restriction updates on extractable heavy metals are forcing additional washing and ion-exchange purification stages.
- Energy:Battery anode materials and filtration media for energy storage systems.
- Agriculture:Soil amendment and controlled-release fertilizer applications.
Textiles commands the greatest volume absorption; personal care is expanding most quickly as clean beauty formulations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ho Chi Minh City anchors the densest concentration of spent coffee grounds fiber processing infrastructure, with Vietnamese spinning mills commanding export volumes to European and North American apparel brands.
Vietnam
Export-oriented textile manufacturers in the Central Highlands and Ho Chi Minh City industrial corridors integrate spent coffee grounds fiber into antimicrobial yarn for performance apparel. The country's national standards body enforces textile labeling rules that align with EU import requirements. Da Lat and Buon Ma Thuot roasting clusters supply standardized feedstock through direct mill partnerships, displacing spot-market trading.
Germany
Automotive interior suppliers in Bavaria and Baden-Württemberg qualify sub-10% lignin fiber grades for dashboard and door panel substrates under OEM sustainability scorecards. ECHA's REACH substance restriction updates tighten extractable heavy metal limits for textile-grade cellulose fibers. Stuttgart and Munich technical centers drive enzymatic lignin reduction R&D for medical-grade fiber applications.
United States
Cosmetics and food-contact packaging formulators seek FDA GRAS-recognized coffee ground extracts for clean beauty and sustainable packaging formulations. EPA industrial waste guidelines influence collection stream segregation between food-service and industrial roasting residues. Brooklyn and Seattle specialty coffee roasting hubs generate concentrated feedstock for downstream fiber processors.
Japan
Automotive and electronics manufacturers source density-reduced composite materials for lightweighting applications under METI carbon neutrality roadmaps. JIS standards govern fiber content specifications for industrial composite grades. Nagoya and Osaka industrial corridors host qualification programs for bio-sourced carbon alternatives in energy storage components.
Indonesia
Specialty coffee sector expansion in Sumatra and Java generates 400,000+ tonnes of untreated grounds annually with minimal collection infrastructure outside Jakarta and Surabaya. The country's national industrial ministry promotes agricultural waste valorization through regional development incentives. Bandung textile research institutes pilot mechanical extraction systems for coarser-grade fiber output.
Spent Coffee Grounds Fiber Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-tier differentiation, with OEKO-TEX and GOTS validation separating functional textile grades from bulk composite fillers. The vendor base stratifies into three tiers: integrated spinning mills with proprietary extraction technology, regional collectors with direct roasting partnerships, and technology licensors supplying equipment to third-party processors. Capacity expansion and strategic partnerships dominate competitive moves, with processors securing captive supply agreements to lock in feedstock volumes.
Within the integrated mill tier, SINGTEX Industrial and FASLINK JSC exemplify divergent geographic anchoring strategies, with the former representing Taiwan-based functional textile specialization and the latter embodying Vietnamese upstream supply chain control. Bio-bean occupies a distinct position as a UK-based urban waste collector converting metropolitan grounds into standardized feedstock for multiple downstream sectors. These three entities collectively illustrate how feedstock access, processing intensity, and end-market certification requirements determine margin capture in this emerging value chain.
| Leading Market Players |
|---|
| SINGTEX Industrial |
| FASLINK JSC |
| Smartex Yarn Corp. |
| Bao Lan Textile |
| Thai Son S.P Sewing Factory |
| Jay Ho Corp. |
| Jia-Zhan Textile |
| Bio-bean |
| FLOCUS |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal bio-based material quotas gate qualified supply and premium-tier pricing access, compressing development timelines for fiber extraction technologies while forcing commodity-grade processors toward cost-competitive positioning or exit.
Pricing Analysis
Certification-attained yield performance anchors value-based pricing, with OEKO-TEX and GOTS validated grades commanding measurable premiums over undifferentiated dry fiber. Three-tier pricing structure across premium, standard, and economy levels separates enzymatically refined medical-grade output from mechanical-extraction commodity volumes. Cost compression in standard-tier dry fiber is intensifying because Vietnamese spinning mills consolidate procurement through direct roasting partnerships. Small-scale regional collectors exhibit highest price sensitivity, while German automotive interior suppliers demonstrate lowest sensitivity due to explicit carbon accounting value in sustainability scorecards.
Supply Chain Analysis
Urban collection networks operate as reverse-logistics systems, consolidating spent grounds from coffee shops and roasting facilities into standardized feedstock streams. Vietnam, Brazil, and Indonesia anchor geographic supply concentration, with over sixty percent of collectible volumes originating from Ho Chi Minh City, São Paulo, and Jakarta metropolitan clusters. Processor operations draw from Robusta and Arabica bean price swings, lignin content variability, and mycotoxin contamination risk in unsegregated streams. Single-source vulnerability concentrates in Vietnamese Central Highlands roasting partnerships. Distribution runs through direct mill-processor contracts displacing spot-market trading in premium textile supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification timeline compression functions as a consolidation mechanism, forcing capital-constrained mechanical-extraction operators toward acquisition or equipment obsolescence.
For Market Incumbents: Deploy captive supply agreements to lock in feedstock volumes against emerging urban-waste collector competition. Incumbents should accelerate enzymatic lignin reduction R&D investment to qualify medical-grade fiber grades before supercritical CO2 extraction technology diffuses to second-tier processors. SINGTEX Industrial's proprietary spinning technology exemplifies defensible positioning through formulation expertise rather than raw material scale alone.
For New Entrants and Emerging Players: Supercritical CO2 extraction paired with enzymatic lignin reduction offers technology-first entry into wound dressing and surgical mesh applications where incumbent qualification cycles lag. Indonesia's untreated ground surplus outside Jakarta and Surabaya represents the most penetrable geography, with minimal collection infrastructure and expanding specialty coffee processing. New entrants should pursue direct contracting with Bandung textile research institutes to pilot mechanical extraction systems for coarser-grade composite filler output.
For Investors and Strategic Acquirers: First commercial launch of medical-grade fiber grades under ECHA streamlined notification procedures is the leading indicator that premium-tier margin pools will sustain expansion financing. The five-to-ten year viability window favors acquisition targets with integrated enzymatic hydrolysis capacity and existing OEKO-TEX validation rather than pure-play collection infrastructure. Investors should monitor BIS textile labeling amendment enforcement in India for early signals of traceability-premium market formation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Roasting Partnerships | Direct mill-processor contracts in Vietnam's Central Highlands reduce feedstock cost volatility and contamination risk. |
| Enzymatic Lignin Reduction Scale-Up | Sub-ten-percent lignin grades qualify for German automotive interior supplier sustainability scorecards under OEM carbon accounting frameworks. |
| Medical-Grade Fiber Certification | ECHA streamlined notification procedures for bio-based polymers reduce registration barriers for cellulose-hemicellulose wound dressing applications. |
| Urban Collection Network Expansion | Jakarta and Surabaya infrastructure buildout captures Indonesia's four-hundred-thousand-tonne annual untreated ground surplus. |
| Traceability Technology Investment | Third-party verified agricultural waste content systems align with India's BIS textile labeling amendments mandating fiber origin disclosure. |
Research Methodology
Independent corroboration across primary interviews with textile plant managers, coffee roasting facility operators, automotive interior procurement leads, and enzymatic processing R&D directors underwrites the qualitative findings. Secondary validation draws from ECHA REACH substance restriction updates, EU F-Gas Regulation phase-down schedules, BIS textile labeling amendments, and Vietnamese national standards body enforcement records. Bottom-up fiber production capacity estimates triangulate against top-down end-use demand absorption across composite materials, textiles, and personal care applications.
Rate-of-change decomposition separates volume growth drivers from price elasticity effects across the analysis window. Segmentation dimensions modeled include product grade tier, processing technology intensity, end-use industry vertical, and regional regulatory cluster. CAGRs derive from installed capacity expansion announcements, qualification timeline benchmarks, and substitution elasticity assumptions for synthetic glass fiber displacement. Forecast inputs incorporate OEM sustainability scorecard adoption curves and compostability certification evolution timelines.
Several conditions sit outside the modeled scope, including abrupt Robusta and Arabica commodity price shocks, unilateral REACH heavy metal limit revisions, and trade restriction impositions on Vietnamese textile exports. Forecasts reflect documented assumptions regarding enzymatic hydrolysis technology diffusion rates and collection infrastructure buildout pacing. Practitioners should monitor ECHA draft guidance finalization on recycled biomass contaminants and Indonesian national industrial ministry incentive disbursement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Natural Fibers and Sisal Market
Natural Fibers
Cashmere Clothing Market
Natural Fibers
Global Alpaca Fiber Market
Natural Fibers
Fenugreek Fiber Market
Natural Fibers
Lignocellulosic Fibers Market
Natural Fibers
Cellulose Fiber Market
Natural Fibers
Modal Fiber Market
Natural Fibers
Down and Feather Market
Natural Fibers
Bamboo Fibers Market
Natural Fibers
Indonesia Textiles Market
Natural Fibers
Acacia Fiber Powder Market
Natural Fibers
Natural Fibers Market
Natural Fibers
North America Textile Market
Natural Fibers
Natural Fiber Reinforced Composites Market
Natural Fibers
Hessian Sacks Market
Natural Fibers
Silk Market