
 Thrombocytopenia Treatment Market | 2026-2036
Thrombocytopenia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Thrombocytopenia Treatment Market Analytics
A shortage of hematology-specialized clinical pharmacists is reorganizing how thrombocytopenia protocols deploy across inpatient and outpatient settings. Pfizer Inc. leverages its hospital formulary relationships to sustain access for corticosteroid and immunoglobulin portfolios. Amgen Inc. anchors its position through biologic manufacturing scale in thrombopoietin receptor agonist supply. Novartis AG competes via oncology-hematology crossover expertise, particularly in chemotherapy-induced thrombocytopenia management.
Thrombocytopenia treatment encompasses therapeutic interventions that elevate platelet counts above clinically critical thresholds, typically targeting counts below 50,000 per microliter through pharmacologic stimulation of megakaryopoiesis, platelet transfusion support, or immunosuppressive modulation of peripheral platelet destruction. These interventions serve primarily to prevent hemorrhagic complications in patients undergoing myelosuppressive chemotherapy, managing autoimmune platelet disorders, or addressing viral-induced bone marrow suppression. Immunoglobulin and eltrombopag segments command premium positioning due to chronic therapy requirements in immune thrombocytopenia, while platelet transfusion maintains volume leadership in acute oncology settings. The intravenous administration route retains institutional dominance, though subcutaneous delivery is gaining traction in homecare transitions.
The FDA's orphan drug designation framework and EMA's PRIME eligibility pathway for hematology therapies create divergent market access timelines across jurisdictions, with FDA breakthrough therapy status compressing development cycles for novel thrombopoietin mimetics. ISO 14155 clinical investigation standards govern trial integrity for platelet-count surrogate endpoints, while WHO prequalification pathways shape emerging market procurement for transfusion products. Stakeholders must monitor evolving biosimilar entry dynamics around reference eltrombopag products and corresponding payer formulary repositioning strategies.
Market Dynamics
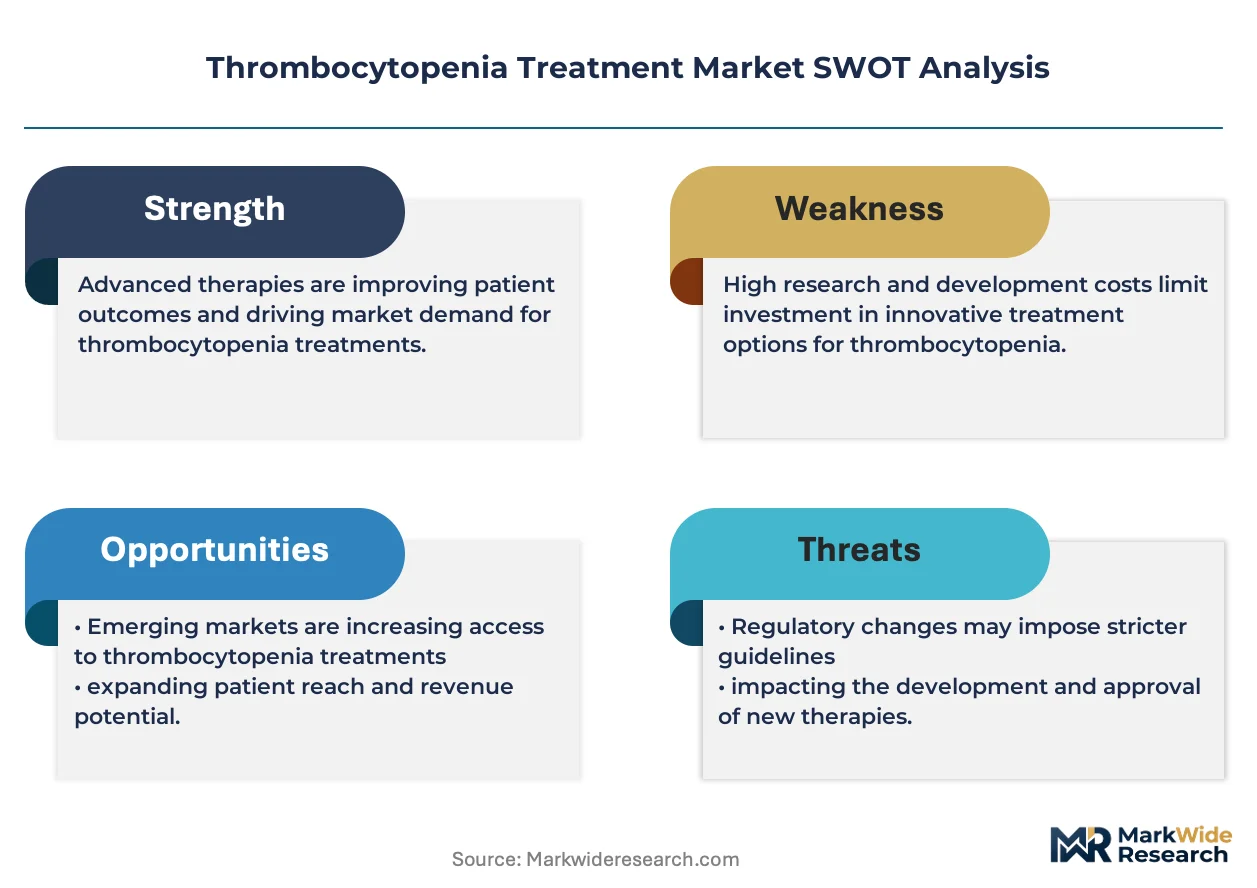
FDA accelerated approval pathways for orphan hematology indications are compressing development timelines for novel thrombopoietin mimetics while hospital formulary committees reorganize protocol deployment around hematology-specialized clinical pharmacist availability.
Growth Catalysts
- Orphan Drug Incentives:The FDA's orphan drug designation framework provides seven-year market exclusivity and tax credits for qualifying thrombocytopenia therapies, stimulating pipeline investment in immune thrombocytopenia indications.
- Medicare Reimbursement Structures:United States Medicare Part B reimbursement for chronic immune thrombocytopenia biologics sustains patient access and provider prescribing confidence across outpatient infusion centers.
- Thrombopoietin Receptor Agonist Manufacturing:Advances in mammalian cell culture bioprocessing have scaled production of recombinant thrombopoietin mimetics, reducing batch-to-batch variability and supply constraints.
Market Restraints
- Plasma-Derived Immunoglobulin Supply:Fractionation capacity constraints and donor plasma collection volatility create intermittent shortages of intravenous immunoglobulin for acute immune thrombocytopenia episodes.
- Biosimilar Entry Dynamics:Reference eltrombopag products face imminent biosimilar competition in European markets, pressuring originator pricing and payer formulary repositioning strategies.
- Specialized Infusion Infrastructure:Hospital-based hematology departments require dedicated nursing staff and adverse event monitoring protocols that limit outpatient capacity expansion.
Strategic Opportunities
- Homecare Subcutaneous Delivery:Subcutaneous thrombopoietin receptor agonist administration enables patient self-management outside infusion centers, reducing institutional overhead and travel burden.
- Chemotherapy-Induced Indications:Oncology-hematology crossover protocols for myelosuppressive regimens represent underpenetrated demand within solid tumor and hematologic malignancy treatment pathways.
- EMA PRIME Eligibility:The European Medicines Agency's PRIority MEdicines pathway accelerates assessment timelines for novel thrombocytopenia therapies addressing unmet medical need.
Industry Challenges
- Hematology Clinical Pharmacist Shortage:Specialized expertise in platelet count surrogate endpoint interpretation and biologic dosing titration remains scarce across inpatient and outpatient settings.
- ISO 14155 Trial Integrity:Clinical investigation standards for platelet-count surrogate endpoints require rigorous central laboratory standardization that extends study startup timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thrombocytopenia Treatment Market |
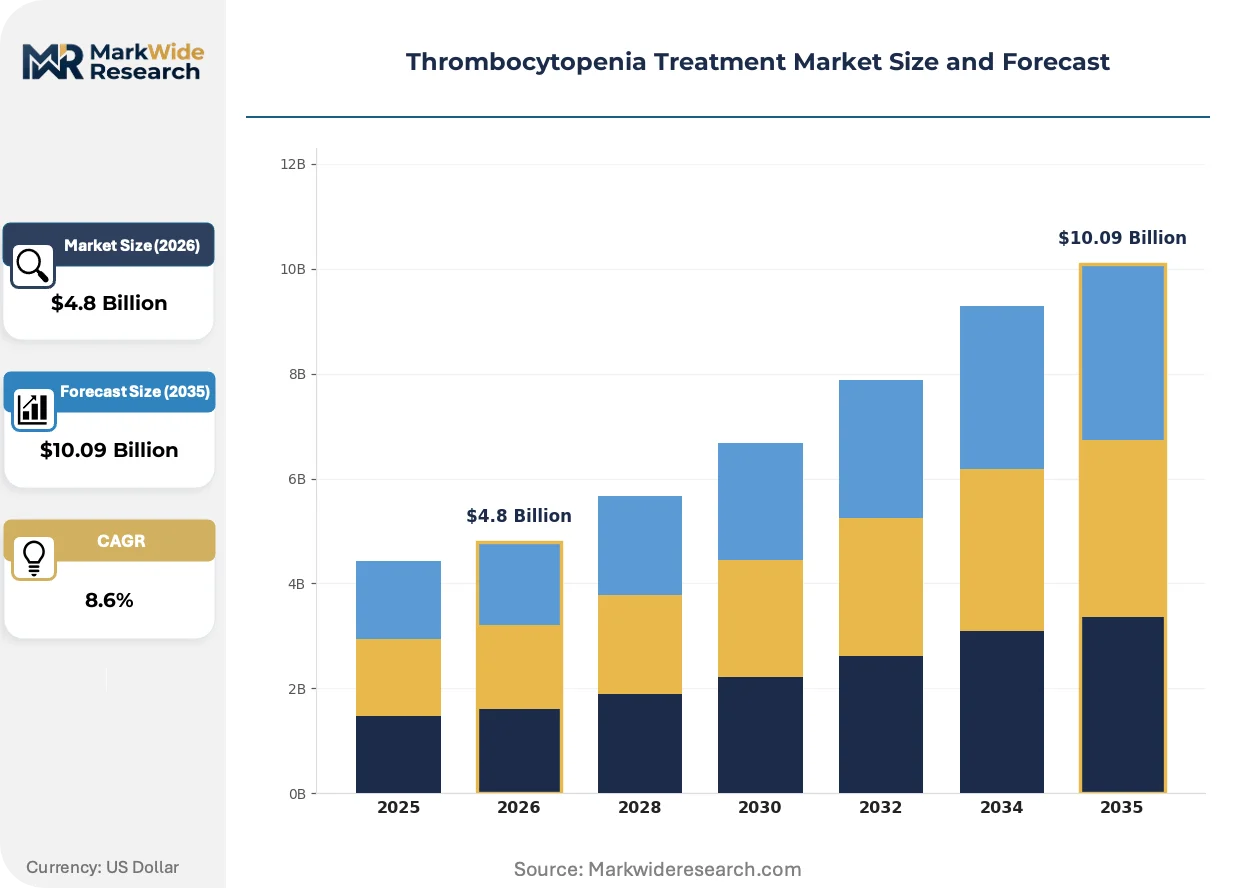
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Platelet Transfusion, Corticosteroids, Immunoglobulins, Eltrombopag End User: Hospitals, Clinics, Ambulatory Surgical Centers, Homecare Administration Route: Intravenous, Subcutaneous, Oral, Intramuscular Therapy Area: Oncology, Hematology, Autoimmune Disorders, Viral Infections |
| Companies Covered | Sobi, Pfizer Inc., Amgen Inc., UCB S.A., Sanofi S.A., Novartis AG, F. Hoffmann-La Roche Ltd., CSL Behring, Rigel Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thrombocytopenia Treatment Market Evolving Landscape
Thrombocytopenia treatment protocols are pivoting from institutional infusion dependence toward patient-empowered administration models, with technology and regulatory frameworks co-evolving to support this decentralization.
Next-generation thrombopoietin receptor agonists with modified half-life pharmacokinetics are displacing daily oral dosing regimens in chronic immune thrombocytopenia management. Hospital outpatient departments are adopting these extended-interval therapies to reduce chair time and nursing labor allocation. The shift is compressing visit frequency requirements while maintaining platelet count thresholds above hemorrhagic risk thresholds.
The EMA's PRIME eligibility pathway for hematology therapies creates divergent market access timelines against FDA frameworks, with European assessors demanding longer safety databases for thrombosis signal evaluation. Manufacturers are responding with parallel-track development strategies that front-load cardiovascular outcome data collection. Oncology-hematology crossover indications face the most pronounced regulatory friction under this divergence.
Hospital procurement committees are unbundling platelet transfusion support from bundled oncology care contracts, creating standalone purchasing categories for thrombopoietin pharmacologic interventions. Group purchasing organizations are consolidating thrombocytopenia biologic contracts across health system networks. The United States exhibits the most concentrated buyer aggregation, with three national GPOs controlling the majority of acute care procurement volume.
Thrombocytopenia Treatment Market Segmentation
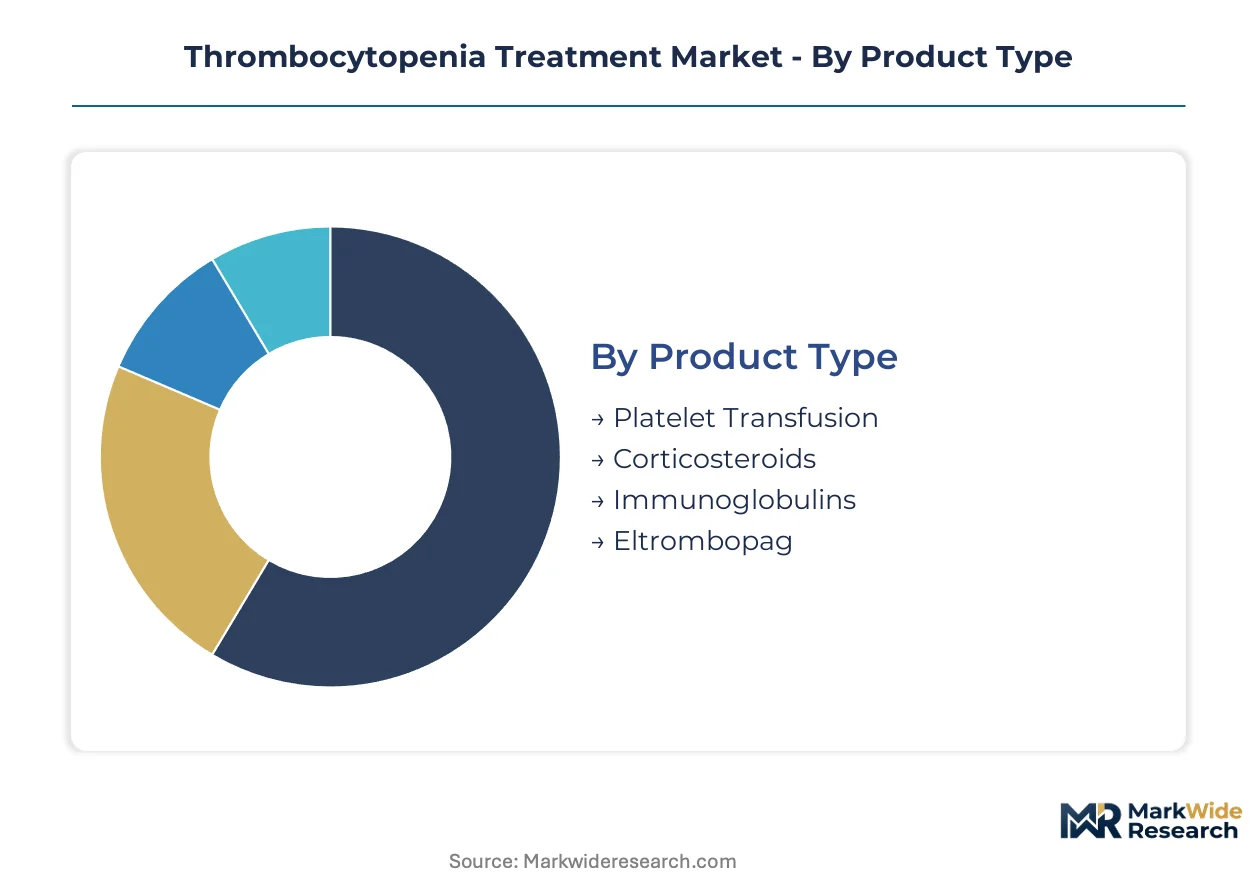
Thrombocytopenia treatment segments flow through distinct procurement and reimbursement channels that determine commercial access. Hospital formulary committees gate institutional segments while Medicare Part B structures shape outpatient biologic prescribing patterns.
Product Type:
Channel mix varies sharply across product categories, with acute hospital procurement dominating transfusion products and specialty pharmacy networks controlling chronic oral therapies.
- Platelet Transfusion:Blood component therapy requiring ABO-matched apheresis units stored at controlled temperatures. Demand concentrates in United States oncology centers performing myelosuppressive chemotherapy, constrained by platelet donor availability and AABB accreditation requirements.
- Immunoglobulins:Plasma-derived polyclonal antibodies administered intravenously for acute immune thrombocytopenia episodes. United States hospital infusion centers represent the primary channel, with supply volatility from fractionation capacity limiting protocol deployment.
- Corticosteroids:First-line immunosuppressive therapy available through standard hospital and retail pharmacy distribution.
- Eltrombopag:Oral thrombopoietin receptor agonist dispensed through specialty pharmacy channels with REMS monitoring requirements.
Platelet transfusion dominates installed base volume. Eltrombopag is where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive institutional settings from emerging lower-acuity channels.
- Hospitals:Comprehensive hematology departments managing complex thrombocytopenia cases with 24-hour transfusion capability and specialized nursing staff. United States academic medical centers anchor demand for biologic therapies with Medicare cost-report reimbursement.
- Homecare:Patient-administered subcutaneous therapies reducing institutional overhead and travel burden. United States Medicare home health benefit expansion is accelerating channel migration for stable chronic immune thrombocytopenia patients.
- Clinics:Outpatient infusion centers handling routine immunoglobulin administration.
- Ambulatory Surgical Centers:Limited thrombocytopenia management for perioperative platelet optimization.
Hospitals dominate installed base infrastructure. Homecare is where expansion concentrates.
Administration Route:
Application requirements dictate route selection, with acute hemorrhagic risk favoring intravenous delivery and chronic maintenance enabling patient-directed administration.
- Intravenous:Direct vascular delivery for platelet transfusion and immunoglobulin requiring immediate bioavailability. United States hospital outpatient departments retain institutional dominance due to hypersensitivity monitoring protocols and infusion nursing specialization.
- Subcutaneous:Depot-style thrombopoietin receptor agonist delivery enabling weekly or biweekly dosing intervals. Patient self-administration in United States home settings is gaining share fastest as extended-half-life formulations reduce injection frequency.
- Oral:Daily eltrombopag tablets for chronic immune thrombocytopenia maintenance.
- Intramuscular:Limited corticosteroid administration for select acute protocols.
Intravenous dominates installed base encounters. Subcutaneous is where expansion concentrates.
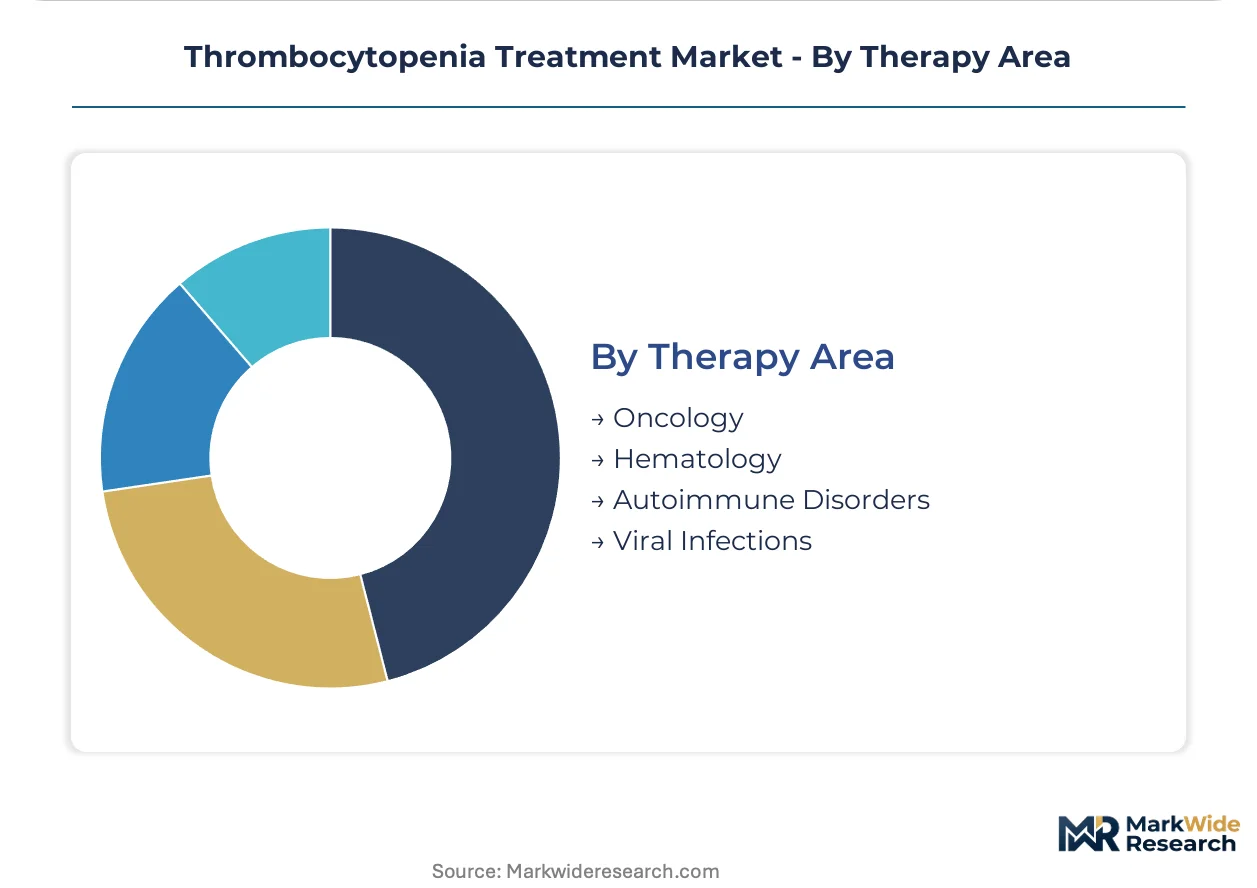
Therapy Area:
Customer type specialization separates oncology-hematology crossover protocols from discrete autoimmune and infectious disease management.
- Oncology:Chemotherapy-induced thrombocytopenia management in solid tumor and hematologic malignancy patients. United States National Comprehensive Cancer Network guidelines standardize thrombopoietin receptor agonist use across myelosuppressive regimens, with FDA breakthrough therapy designations compressing novel agent access timelines.
- Hematology:Primary bone marrow disorders and chronic platelet production deficiencies. United States academic hematology centers drive biologic adoption with specialized megakaryopoiesis monitoring protocols.
- Autoimmune Disorders:Immune thrombocytopenia with peripheral platelet destruction mechanisms.
- Viral Infections:Hepatitis C and HIV-associated bone marrow suppression.
Oncology dominates installed base patient volume. Hematology is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways for orphan hematology indications anchor United States market access, while EMA PRIME eligibility and Japan's PMDA Sakigake designation create divergent regulatory timelines across major pharmaceutical markets.
United States
Medicare Part B reimbursement structures sustain patient access for chronic immune thrombocytopenia biologics across outpatient infusion centers. The FDA's breakthrough therapy designation compresses development cycles for novel thrombopoietin mimetics. Boston and San Francisco biotech clusters concentrate hematology-specialized clinical trial infrastructure.
Germany
Hospital formulary committees at university medical centers drive adoption of thrombopoietin receptor agonists for chemotherapy-induced indications. EMA centralized marketing authorization procedures govern pan-European market entry for platelet-stimulating biologics. The Rhine-Ruhr metropolitan region anchors plasma fractionation capacity for immunoglobulin supply.
Japan
PMDA Sakigake designation accelerates priority review timelines for innovative thrombocytopenia therapies addressing unmet need. National health insurance reimbursement listing procedures determine commercial access for chronic oral therapies. The Kanto region surrounding Tokyo concentrates hematology department infrastructure at academic medical centers.
United Kingdom
NICE technology appraisal processes evaluate cost-effectiveness of biologic therapies against corticosteroid first-line standards. NHS England specialized commissioning frameworks govern access to thrombopoietin receptor agonists for refractory immune thrombocytopenia. The Greater London area hosts the majority of hematology specialist centers with transfusion capability.
China
NMPA priority review pathways for orphan drugs accelerate market entry for imported thrombopoietin mimetics. National reimbursement drug list negotiations determine patient out-of-pocket exposure for chronic therapies. The Yangtze River Delta region surrounding Shanghai concentrates oncology-hematology crossover treatment capacity at tertiary hospitals.
Thrombocytopenia Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the thrombocytopenia treatment market, with hospital formulary relationships and biologic manufacturing scale serving as primary competitive moats. The upper tier commands institutional procurement contracts through established hematology department partnerships. Three archetypes dominate: plasma fractionation specialists with immunoglobulin portfolios, recombinant biologic manufacturers with thrombopoietin receptor agonist platforms, and diversified pharmaceutical conglomerates with corticosteroid and oncology crossover assets. Competitive moves concentrate on biosimilar defense strategies and subcutaneous formulation transitions for homecare channel expansion.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Novartis AG occupy positions shaped by hospital formulary anchoring and oncology-hematology crossover expertise respectively. Amgen Inc. exemplifies the recombinant biologic manufacturing archetype through thrombopoietin receptor agonist supply scale. These three entities represent distinct strategic positions without overlapping therapeutic focus areas.
| Leading Market Players |
|---|
| Sobi |
| Pfizer Inc. |
| Amgen Inc. |
| UCB S.A. |
| Sanofi S.A. |
| Novartis AG |
| F. Hoffmann-La Roche Ltd. |
| CSL Behring |
| Rigel Pharmaceuticals, Inc. |
| Others |
Value Network & Pricing Analysis
FDA orphan drug designation status gates both supply qualification for thrombopoietin receptor agonists and price differentiation across reimbursement tiers, compressing development timelines for qualifying therapies while anchoring premium positioning for chronic immune thrombocytopenia indications.
Pricing Analysis
United States Medicare Part B reimbursement rates for biologic therapies sit substantially above European hospital procurement benchmarks, creating transatlantic price spreads exceeding standard pharmaceutical differentials. Three-tier pricing structure across originator biologics, biosimilar entrants, and generic corticosteroids segments buyer sensitivity, with hospital formulary committees exhibiting lowest price elasticity for acute transfusion-dependent patients. Pricing pressure stems from imminent eltrombopag biosimilar entry in European markets, forcing originator discounting to defend access contracts.
Supply Chain Analysis
Just-in-time inventory models dominate hospital-based platelet transfusion logistics, with apheresis units requiring controlled-temperature transport within narrow collection-to-infusion windows that preclude strategic stockpiling. Plasma fractionation for immunoglobulin supply concentrates in the United States, Germany, and Japan, drawing from paid and volunteer donor bases with varying collection economics. Single-source vulnerability pervades recombinant thrombopoietin mimetic production, where mammalian cell culture capacity at limited biologics manufacturing sites creates supply concentration risk. Distribution runs through hospital blood banks and specialty pharmacy networks with divergent cold-chain requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biosimilar substitution for reference thrombopoietin receptor agonists threatens incumbent pricing power, requiring defensive repositioning around administration convenience and patient support services.
For Market Incumbents: Consolidate hospital formulary relationships through extended-half-life formulation transitions that reduce nursing labor allocation and defend against biosimilar commoditization. Deepen backward integration into mammalian cell culture capacity to secure supply continuity against single-source manufacturing vulnerabilities. Prioritize REMS program investment as a switching-cost anchor for chronic immune thrombocytopenia patients.
For New Entrants and Emerging Players: Differentiate on subcutaneous delivery platforms that enable homecare channel bypass of infusion center bottlenecks. Target chemotherapy-induced thrombocytopenia in solid tumor indications as the most penetrable oncology-hematology crossover segment with unmet need. Pursue EMA PRIME eligibility to compress European market access timelines against FDA-first competitors.
For Investors and Strategic Acquirers: FDA accelerated approval pathway expansion for orphan hematology indications reshapes the acquisition landscape toward clinical-stage assets with breakthrough therapy designation. Long-term viability centers on platforms with multi-indication thrombopoietin receptor agonist potential spanning autoimmune and oncology applications. Watch thrombosis signal resolution in extended safety databases as the critical inflection indicator for portfolio valuation.
| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Half-Life Formulation Development | Reduces patient chair time in United States hospital outpatient departments and defends against biosimilar entry. |
| Homecare Subcutaneous Delivery Transition | Enables Medicare home health benefit capture and reduces institutional overhead burden for chronic patients. |
| Biosimilar Defense Contracting | Locks in group purchasing organization volume commitments ahead of European reference product exclusivity expiry. |
| Hematology Clinical Pharmacist Training Programs | Addresses specialized expertise scarcity that limits protocol deployment across inpatient and outpatient settings. |
| Oncology-Hematology Crossover Trial Design | Expands addressable patient population beyond primary immune thrombocytopenia into myelosuppressive chemotherapy support. |
Research Methodology
The analysis maps thrombopoietin receptor agonist segments, platelet transfusion logistics, and immunoglobulin supply channels, each validated through hematology department directors, specialty pharmacy procurement managers, and blood bank operations leads. Primary interviews with drug development executives and payer access specialists combined with secondary validation against FDA orphan drug designations, EMA PRIME eligibility records, ClinicalTrials.gov entries, and Medicare Part B reimbursement databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored volume estimates.
Consistency checks against external benchmarks validated projection outputs across the analysis window, with segmentation dimensions covering administration route, therapy area, and end-user setting. CAGRs derived from patient population epidemiology, treatment penetration assumptions, and pricing trajectory modeling. Forecast inputs incorporated thrombopoietin receptor agonist dosing frequency trends and plasma fractionation capacity expansion timelines.
Decision-makers should treat outputs as directional under stable regulatory reimbursement assumptions; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding biosimilar entry timing and hematology clinical pharmacist workforce growth. Revision becomes warranted when thrombosis safety signal frequency crosses regulatory action thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Hemoglobin Analyzer Market
Hematology
Acute Lymphoblastic Leukemia Market
Hematology
Lymphoma Treatment Market
Hematology
Blood Disorder Therapeutics Market
Hematology
Global Hemoglobin Meter Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Marginal Zone Lymphoma Treatment Market
Hematology
At-Home Hematology Testing Market
Hematology
Follicular Lymphoma Treatment Market
Hematology
Polycythemia Vera Market
Hematology
Hemoglobin Testing Systems Market
Hematology
Acute Myeloid Leukemia Treatment Market
Hematology
Small Lymphocytic Lymphoma Market
Hematology
Apheresis Market
Hematology
Global Hematology Diagnostics Market
Hematology
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market