
 Multi-Cuvette Spectrophotometer Market | 2026-2036
Multi-Cuvette Spectrophotometer Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Cuvette Spectrophotometer Market Outlook
The direct sales channel for analytical instruments is narrowing as OEMs consolidate regional distribution under fewer authorized partners. Thermo Fisher Scientific leverages its service network to sustain recurring revenue from installed multi-cuvette bases. Shimadzu Corporation anchors its position through captive manufacturing of optical components in Japan. Agilent Technologies competes by specializing in compliance-ready software bundles that streamline pharmaceutical validation workflows.
A multi-cuvette spectrophotometer measures absorbance or transmittance across multiple simultaneous sample positions using discrete cuvette holders, typically operating in UV-Vis wavelength ranges from 190 nm to 1100 nm with photodiode array or scanning monochromator detection. The instrument enables parallel quantification of protein concentrations, nucleic acid purity, or chemical contaminants in regulated laboratory environments. Bench-top configurations retain the largest installed base due to established pharmaceutical QC protocols, while high-throughput variants capture the fastest expansion as contract research organizations scale screening operations. Fluorescence detection technology commands premium positioning where trace-level sensitivity proves essential for environmental metabolite monitoring.
FDA 21 CFR Part 11 electronic records requirements and EPA Method compliance standards shape instrument software architecture and audit trail capabilities for vendors serving North American laboratories. ISO 17025 accreditation pressures in Europe and China GB standards for analytical instrument calibration create parallel certification demands that filter market access. Stakeholders must weigh modular upgrade paths against full-system replacement timelines as photonics component lifecycles compress and regulatory data integrity expectations intensify.
Market Dynamics
Pharmaceutical quality control laboratories are consolidating instrument procurement around compliance-ready platforms that satisfy simultaneous FDA, EMA, and NMPA validation requirements, compressing vendor qualification timelines and favoring established optical systems suppliers with multi-regional service footprints.
Growth Catalysts
- EPA Method 525.3 compliance mandates:Drinking water testing laboratories in the United States face expanded monitoring obligations for pharmaceutical residues and personal care products, forcing instrument upgrades to multi-cuvette configurations that process 8-16 samples in parallel.
- Contract research organization capacity expansion:CROs serving biologics developers are scaling high-throughput screening operations in China and Germany, driving demand for automated cuvette changers and integrated liquid handling modules.
- Photodiode array detection:Solid-state detector technology eliminates mechanical scanning delays, enabling sub-second full-spectrum acquisition that supports kinetic assay workflows in enzymology and protein stability screening.
Market Restraints
- Deuterium lamp supply concentration:Japanese and German specialty lamp manufacturers control 80% of UV source production for analytical instruments, exposing instrument OEMs to lead-time volatility and single-source qualification risks.
- Quartz cuvette cost structure:Far-UV transparency requirements below 200 nm demand synthetic fused silica substrates, with prices 4-6× higher than standard borosilicate alternatives, constraining routine testing economics.
- Monochromator grating fabrication:Holographic ruling and replication capabilities concentrate among three European optical houses, creating bottlenecks for custom wavelength range configurations.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's tightened API quality guidelines and the PLI scheme for active pharmaceutical ingredients are driving QC laboratory buildouts in Hyderabad and Ahmedabad clusters.
- Fluorescence-Raman convergence:Combined photoluminescence and Raman scattering detection modules enable orthogonal metabolite confirmation in environmental forensics, opening premium positioning above absorbance-only systems.
- Cloud-native audit trail architectures:Browser-based instrument control and centralized data lakes reduce on-premise IT infrastructure burdens for distributed laboratory networks.
Industry Challenges
- Photonics technician scarcity:Alignment and calibration of optical benches requires specialized expertise in interferometry and detector linearization, with training pipelines failing to match instrument deployment rates.
- Legacy LIMS integration friction:Pre-2015 laboratory information management systems lack REST API connectivity, forcing middleware development or manual data transcription for 21 CFR Part 11 compliance.
- Multi-regional certification parallelism:Simultaneous FDA, EMA, and NMPA submissions demand redundant documentation sets and divergent electromagnetic compatibility testing protocols, extending time-to-market by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Cuvette Spectrophotometer Market |
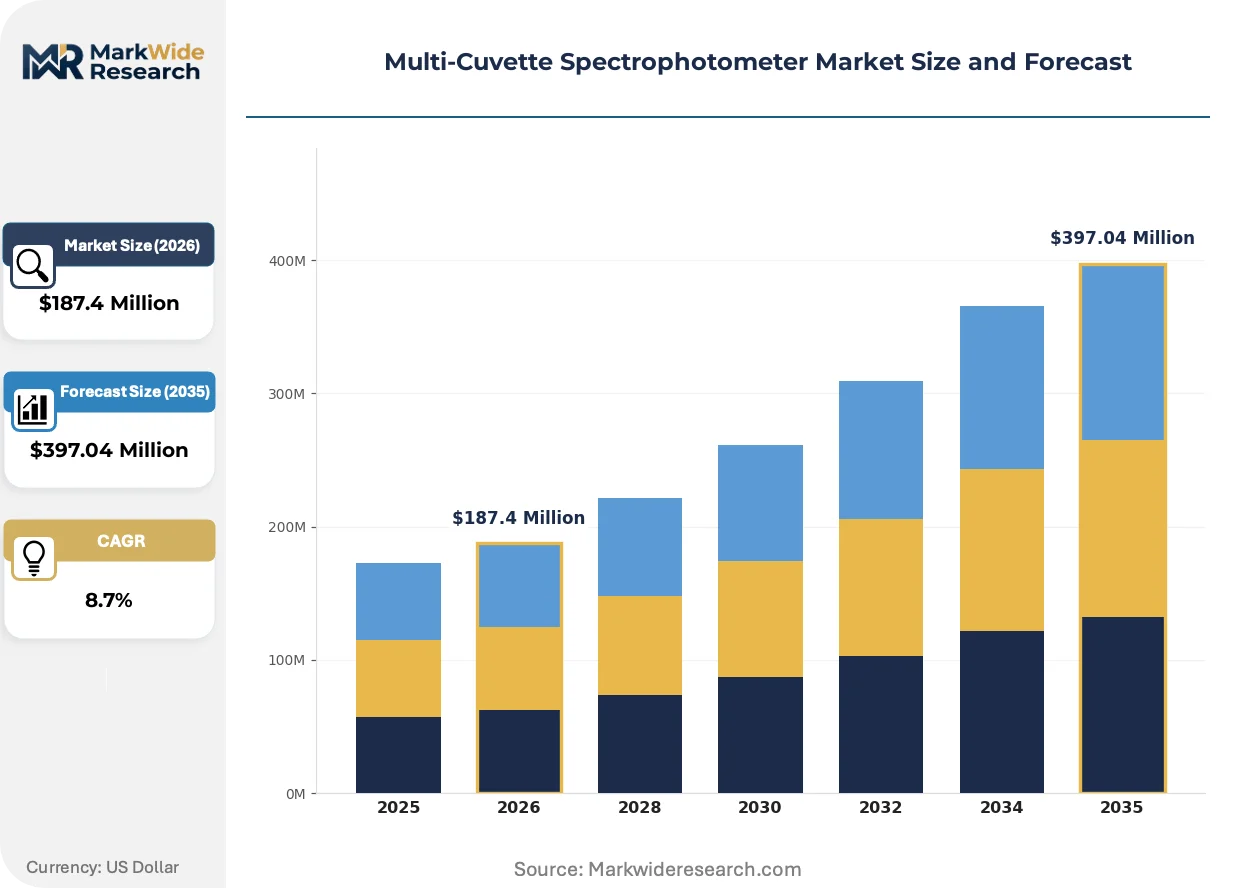
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Bench-top, High-throughput, Laboratory-grade Technology: UV-Vis, Near Infrared, Fluorescence, Raman End User: Pharmaceuticals, Academic Institutions, Environmental Testing, Food & Beverage Application: Quality Control, Research & Development, Process Monitoring, Education |
| Companies Covered | Shimadzu Corporation, Hitachi High-Tech, Thermo Fisher Scientific, Eppendorf, JASCO, Agilent Technologies, Hach Company, Beckman Coulter, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Cuvette Spectrophotometer Market Strategic Shifts
Spectrophotometer architecture is converging around modular detection platforms that separate optical core functions from application-specific sample handling, enabling field-upgradable configurations that extend asset lifecycles against compressed technology obsolescence cycles.
Photodiode array detection is digitizing wavelength selection and spectral acquisition workflows across pharmaceutical quality control laboratories. Thermo Fisher Scientific and Agilent Technologies have mainstreamed solid-state detector arrays that capture full UV-Vis spectra in under 100 milliseconds without mechanical grating movement. This capability is digitizing kinetic assay protocols that previously required stopped-flow accessories or dedicated fluorimeters, collapsing the distinction between steady-state and time-resolved instrumentation categories.
China's GB standards for analytical instrument calibration and Japan's revised JIS K0115 spectrophotometric testing protocols are mandating enhanced traceability documentation for photometric accuracy and wavelength calibration. Manufacturers serving Asia-Pacific markets must now embed certified reference material databases and automated performance qualification routines directly into instrument firmware. Pharmaceutical contract manufacturers in Shanghai and Osaka are prioritizing systems with pre-loaded Chinese and Japanese pharmacopeia methods to accelerate regulatory inspection readiness.
Service contract unbundling is fragmenting traditional after-sales revenue models as large pharmaceutical operators bring calibration and preventive maintenance in-house. Biogen and Lonza have established captive metrology groups that perform intermediate checks using certified absorbance standards, reducing reliance on OEM service engineers for routine compliance tasks. This pattern is most visible in the United States and Switzerland, where labor cost differentials favor internal technician deployment over dispatched service visits.
Multi-Cuvette Spectrophotometer Market Segmentation
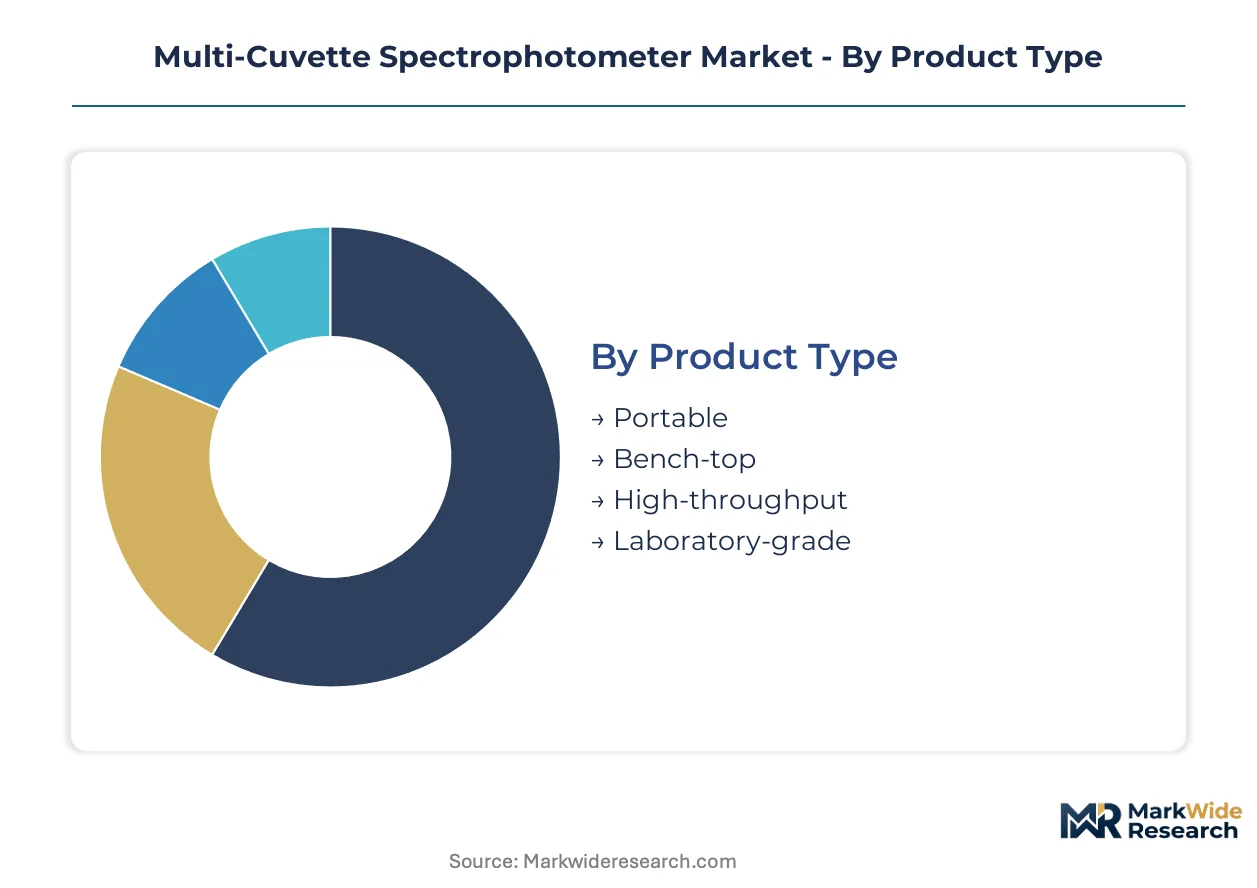
Segmentation in multi-cuvette spectrophotometers reveals how regulatory pressure and throughput demands split procurement across form factors, detection modalities, and user sophistication levels. Laboratories select configurations based on parallel sample capacity, compliance documentation depth, and integration with existing LIMS infrastructure.
Product Type:
Mature configurations dominate pharmaceutical quality control, while emerging formats capture expansion in field-deployable and automated screening environments.
- Bench-top:Fixed-position optical benches with 6-16 cuvette positions serve as the workhorse for FDA-validated pharmaceutical workflows. Demand concentrates in United States and German QC laboratories where 21 CFR Part 11 audit trails and EMA Annex 11 data integrity requirements mandate stable, documented platforms.
- High-throughput:Automated cuvette changers and integrated liquid handling modules process 96+ samples unattended. Contract research organizations in China and Germany are scaling these systems for biologics screening campaigns where sample volume overwhelms manual throughput limits.
- Portable:Battery-powered units with 2-4 cuvette positions enable on-site environmental monitoring. China's MEE and India's pollution control boards deploy these for river basin surveillance where laboratory access is impractical.
- Laboratory-grade:Research-dedicated systems emphasize modularity and spectral resolution over speed. Academic core facilities in Japan and Switzerland prioritize these for method development preceding regulatory submission.
Bench-top retains volume leadership; high-throughput holds the steepest expansion curve.
Technology:
Cost tiers separate commodity absorbance detection from premium photoluminescence modalities where trace sensitivity commands price premiums.
- UV-Vis:Photodiode array and scanning monochromator architectures cover 190-1100 nm for routine quantification. Pharmaceutical QC laboratories in the United States, Germany, and China standardize on UV-Vis for protein concentration and nucleic acid purity assays.
- Fluorescence:Photomultiplier-based detection achieves picomolar sensitivity for environmental metabolite and biomarker quantification. EPA Method compliance for pharmaceutical residues in drinking water drives adoption at premium price points.
- Near Infrared:Diffuse reflectance and transmission configurations bypass sample preparation for solid-state analysis. Food & beverage laboratories in Japan and Germany deploy NIR for rapid moisture and fat content verification.
- Raman:Combined photoluminescence-Raman modules enable orthogonal molecular confirmation. Environmental forensics laboratories pay premiums for metabolite identification without chromatographic separation.
UV-Vis dominates installed base by unit volume; fluorescence is expanding most quickly on value terms.
End User:
Customer type determines procurement authority, with centralized pharmaceutical metrology groups driving standardization versus distributed academic purchases.
- Pharmaceuticals:Corporate QC laboratories consolidate around compliance-ready platforms satisfying simultaneous FDA, EMA, and NMPA validation requirements. Biogen and Lonza have established captive metrology groups reducing OEM service dependence.
- Environmental Testing:Commercial and governmental laboratories face expanded EPA Method 525.3 monitoring obligations for pharmaceutical residues. United States drinking water testing laboratories upgrade to parallel-process configurations.
- Academic Institutions:Core facilities and individual research groups prioritize modularity and upgrade paths. Budget constraints favor bench-top UV-Vis over fluorescence for routine teaching applications.
- Food & Beverage:Quality laboratories emphasize rapid throughput for production-line integration. NIR configurations dominate where non-destructive solid analysis replaces wet chemistry.
Pharmaceuticals command the highest average selling prices; environmental testing shows the fastest procurement velocity.
Application:
Volume concentration in quality control reflects regulatory inspection frequency, while research applications demand flexibility over documentation depth.
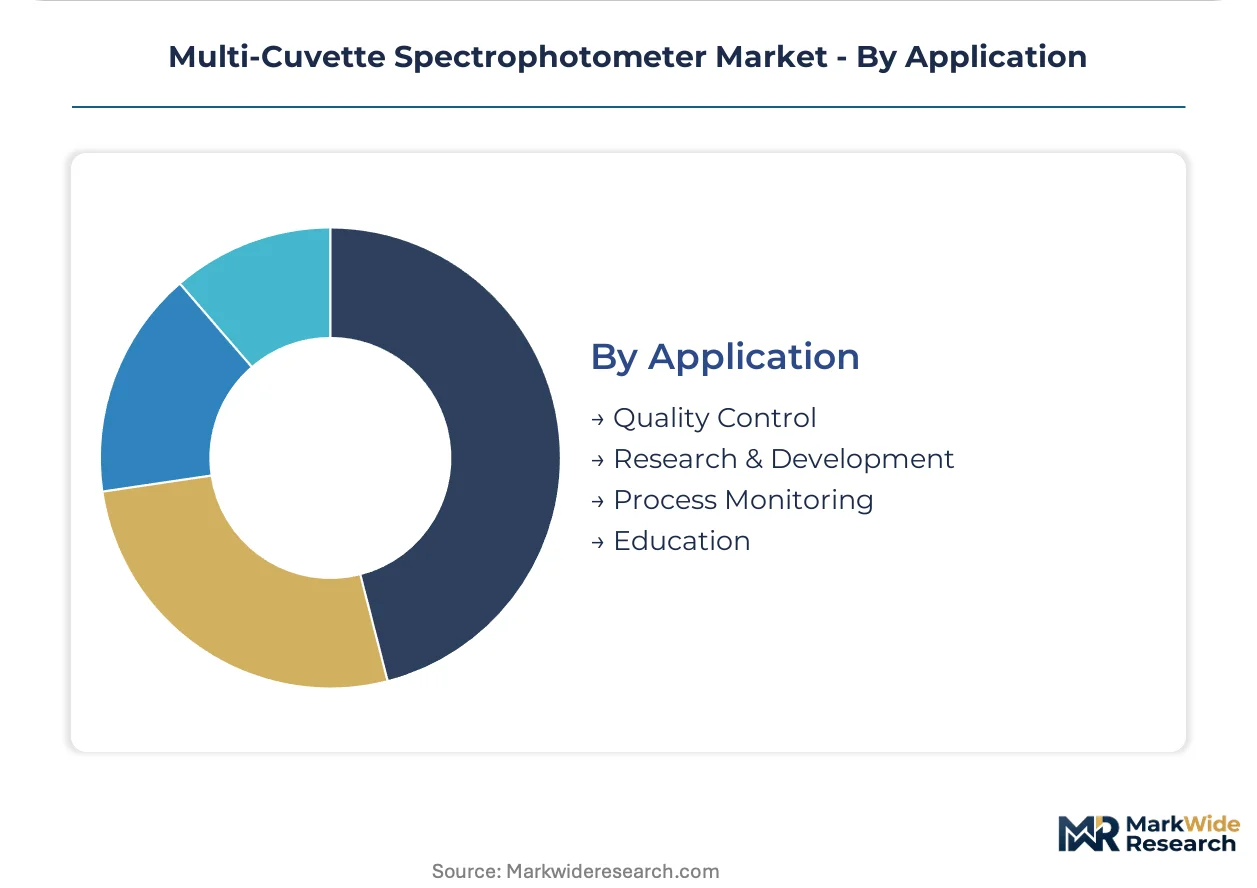
- Quality Control:Validated methods with locked parameters and automated performance qualification satisfy pharmacopeia requirements. Pharmaceutical manufacturers in the United States, Germany, and China embed these systems in release testing protocols.
- Research & Development:Method development and kinetic assay workflows prioritize spectral speed and software openness. Photodiode array sub-second acquisition supports enzymology and protein stability screening.
- Process Monitoring:At-line and in-line configurations track reaction progress in active pharmaceutical ingredient synthesis. India's CDSCO-tightened API guidelines drive QC laboratory buildouts in Hyderabad and Ahmedabad.
- Education:Teaching laboratories emphasize durability and simplified operation over performance specifications. Borosilicate cuvette compatibility reduces consumable costs for undergraduate instruction.
Quality Control anchors revenue concentration; Process Monitoring is gaining share fastest as continuous manufacturing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss pharmaceutical corridors where compliance documentation commands 40% premiums, while Chinese manufacturers compete on throughput economics at 60% discount levels.
United States
EPA Method 525.3 mandates are forcing drinking water laboratories toward 8-16 sample parallel processing. FDA 21 CFR Part 11 enforcement tightens audit trail requirements for pharmaceutical QC. Boston and San Diego biotech clusters drive replacement cycles for legacy single-cuvette systems.
Germany
EMA Annex 11 data integrity standards synchronize with FDA requirements, creating dual-compliance procurement specifications. ECHA chemical registration obligations expand environmental testing laboratory capacity. The Rhine-Main pharmaceutical corridor around Frankfurt anchors high-throughput instrument deployment.
China
NMPA pharmaceutical validation guidelines and GB standards for analytical calibration compress vendor qualification timelines. The dual carbon goals accelerate environmental monitoring buildouts. Shanghai and Suzhou contract manufacturing clusters scale automated cuvette systems for biologics export production.
Japan
Revised JIS K0115 spectrophotometric protocols mandate enhanced traceability documentation for photometric accuracy. PMDA pharmaceutical inspections prioritize pre-loaded pharmacopeia methods. Osaka pharmaceutical manufacturers and Tokyo academic core facilities sustain premium-tier demand.
India
CDSCO tightened API quality guidelines and the PLI scheme for active pharmaceutical ingredients drive QC laboratory construction. Hyderabad and Ahmedabad manufacturing clusters import high-throughput configurations for export compliance. BIS calibration standards filter market access for foreign OEMs.
Multi-Cuvette Spectrophotometer Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream controlling optical grating and detector supply. The market structures around three tiers: full-stack instrument OEMs with captive service networks, optical component houses supplying monochromators and photodiode arrays, and regional assemblers integrating imported subsystems. Strategic moves concentrate on modular platform architectures that extend asset lifecycles and cloud-native software unbundling that fragments traditional after-sales revenue.
Among Japanese precision instrument specialists, Shimadzu Corporation and Hitachi High-Tech occupy positions anchored by captive optical component manufacturing and domestic JIS certification authority. Thermo Fisher Scientific represents the platform-integrator archetype with service-network density sustaining recurring revenue streams. These three exemplify how geographic concentration of photonics expertise translates into qualification advantages across FDA, EMA, and NMPA submission pathways.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Hitachi High-Tech |
| Thermo Fisher Scientific |
| Eppendorf |
| JASCO |
| Agilent Technologies |
| Hach Company |
| Beckman Coulter |
| PerkinElmer |
| Others |
Value Chain & Pricing Dynamics
Japanese and German specialty lamp manufacturers control 80% of UV source production for analytical instruments, concentrating margin capture upstream while downstream instrument OEMs face qualification risks and lead-time volatility that compress their pricing flexibility.
Pricing Analysis
Configured-to-order pricing for compliance-ready systems with embedded FDA 21 CFR Part 11 software and automated performance qualification routines commands 40% premiums over standard bench-top configurations. Three-tier pricing structure across premium, standard, and economy levels separates fluorescence-Raman modules from photodiode array UV-Vis systems from portable field units. Cost compression in the economy tier is intensifying because Chinese manufacturers compete on throughput economics at discount levels. Academic institutions exhibit highest price sensitivity due to budget constraints favoring borosilicate cuvette compatibility, while pharmaceutical QC laboratories show lowest sensitivity where regulatory documentation depth determines procurement authority.
Supply Chain Analysis
Contract manufacturing for optical benches and detector assemblies concentrates among Japanese precision instrument specialists and German optical houses with holographic ruling capabilities. Component sourcing draws from Japan for photodiode arrays, Germany for monochromator gratings, and China for machined aluminum enclosures and electronic subassemblies. Single-source vulnerability in deuterium lamp supply exposes instrument OEMs to Japanese and German specialty lamp manufacturer lead-time volatility. Distribution runs through authorized regional partners consolidating under fewer OEM-certified service networks with captive calibration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-cuvette legacy systems and microplate readers present substitution threats that multi-cuvette incumbents must navigate through compliance bundling and throughput differentiation.
For Market Incumbents: Build switching-cost moats through cloud-native audit trail architectures that embed 21 CFR Part 11 compliance documentation directly into instrument firmware, reducing customer willingness to migrate. Deepen backward integration into optical component manufacturing to mitigate Japanese and German lamp supplier concentration risks. Expand high-throughput configuration portfolios to capture contract research organization capacity expansion in China and Germany. For New Entrants and Emerging Players: India's pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad offer geographic underpenetration where CDSCO-tightened API guidelines and PLI scheme incentives drive QC laboratory construction without entrenched incumbent relationships. Target portable environmental monitoring configurations for China's MEE river basin surveillance programs and India's pollution control board deployments. Pursue modular platform architectures enabling field-upgradable detection modules as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward optical component specialists with captive grating fabrication and detector linearization capabilities, as these upstream positions capture sustained margin pools amid downstream pricing pressure. Long-term viability hinges on regulatory data integrity intensification across FDA, EMA, and NMPA submission pathways. Watch for service contract unbundling signals from large pharmaceutical operators establishing captive metrology groups as inflection indicators for aftermarket revenue erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Software Unbundling | Browser-based instrument control reduces on-premise IT infrastructure burdens for distributed laboratory networks. |
| Modular Platform Architecture | Field-upgradable detection modules extend asset lifecycles against compressed photonics component obsolescence cycles. |
| Fluorescence-Raman Convergence | Combined photoluminescence and Raman scattering detection enables orthogonal metabolite confirmation in environmental forensics. |
| Captive Metrology Group Establishment | Biogen and Lonza internal calibration capabilities reduce OEM service dependence and fragment traditional after-sales revenue. |
| Multi-Regional Certification Parallelism | Simultaneous FDA, EMA, and NMPA submissions demand redundant documentation sets extending time-to-market timelines. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical QC laboratory managers, environmental testing facility directors, academic core facility administrators, and instrument OEM product development leads. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EPA Method 525.3 compliance protocols, NMPA pharmaceutical validation guidelines, and ISO 17025 accreditation standards. Bottom-up and top-down triangulation reconciled instrument shipment data with end-user procurement survey responses.
Calibration against historical replacement cycles and regulatory mandate implementation timelines anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, detection technology, end-user industry, and application workflow. CAGRs were derived from elasticity-adjusted adoption curves incorporating photodiode array detection penetration rates and high-throughput screening capacity expansion in contract research organizations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese instrument assemblers competing on throughput economics or microplate reader manufacturers bundling compliance software would shift outcomes. Quarterly review of EPA drinking water testing mandate expansion, CDSCO API quality guideline enforcement, and service contract unbundling announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Global Laboratory Grinders Market
Laboratory Equipment
Asia Pacific Cell Counting Market
Laboratory Equipment
Point of Care (POC) Coagulation Testing Devices Market
Laboratory Equipment
Automated Plate Readers Market
Laboratory Equipment
Asia-Pacific Laboratory Hoods and Enclosure Market
Laboratory Equipment
Automated Cell Counter Market
Laboratory Equipment
Laboratory Data Loggers Market
Laboratory Equipment
Laboratory Supplies Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Test Tube Market
Laboratory Equipment
Orbital Shakers Market
Laboratory Equipment
Histopathology Testing Equipment Market
Laboratory Equipment
Global Laboratory Equipment Services Market
Laboratory Equipment
Global Hematology Analyzers and Reagents Market
Laboratory Equipment
United States Pipette Tips Market
Laboratory Equipment
Benchtop Centrifuges Market