
 Adipic Acid Market | 2026-2036
Adipic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Adipic Acid Market Intelligence
Direct supply contracts between adipic acid producers and automotive tier-one suppliers is rewriting procurement patterns across the value chain. BASF SE leverages its Ludwigshafen Verbund complex to sustain captive cyclohexane-to-adipic acid integration. Ascend Performance Materials anchors North American supply through its Chocolate Bayou facility and integrated hexamethylenediamine operations. INVISTA competes on scale at its Victoria, Texas site, where backward integration into butadiene derivatives supports differentiated nylon intermediate positioning.
Adipic acid is a dicarboxylic acid with the formula (CH₂)₄(COOH)₂, produced industrially via nitric acid oxidation of cyclohexanol-cyclohexanone mixtures with a typical purity exceeding 99.7 percent; its primary function serves as the essential monomer for nylon 6,6 polycondensation and as a chain extender in polyurethane systems. The polyurethane segment leads volume consumption due to rigid foam demand from building insulation and automotive seating applications. Nylon applications concentrate margin pools around engineering resins for under-the-hood automotive components, while adipic acid derivatives remain a smaller but strategically targeted growth category for plasticizers and synthetic lubricant base stocks.
EPA emissions standards under the Clean Air Act constrain nitrous oxide release from adipic acid plants operating in the United States, while REACH registration requirements in Europe mandate comprehensive chemical safety dossiers for cyclohexane derivatives. China's MEE enforces dual carbon targets that pressure coal-based benzene-to-cyclohexane routes toward lower-carbon feedstock alternatives. Stakeholders must monitor regulatory divergence between jurisdictions to align capital allocation with emerging low-emission process technologies and shifting feedstock economics.
Market Dynamics
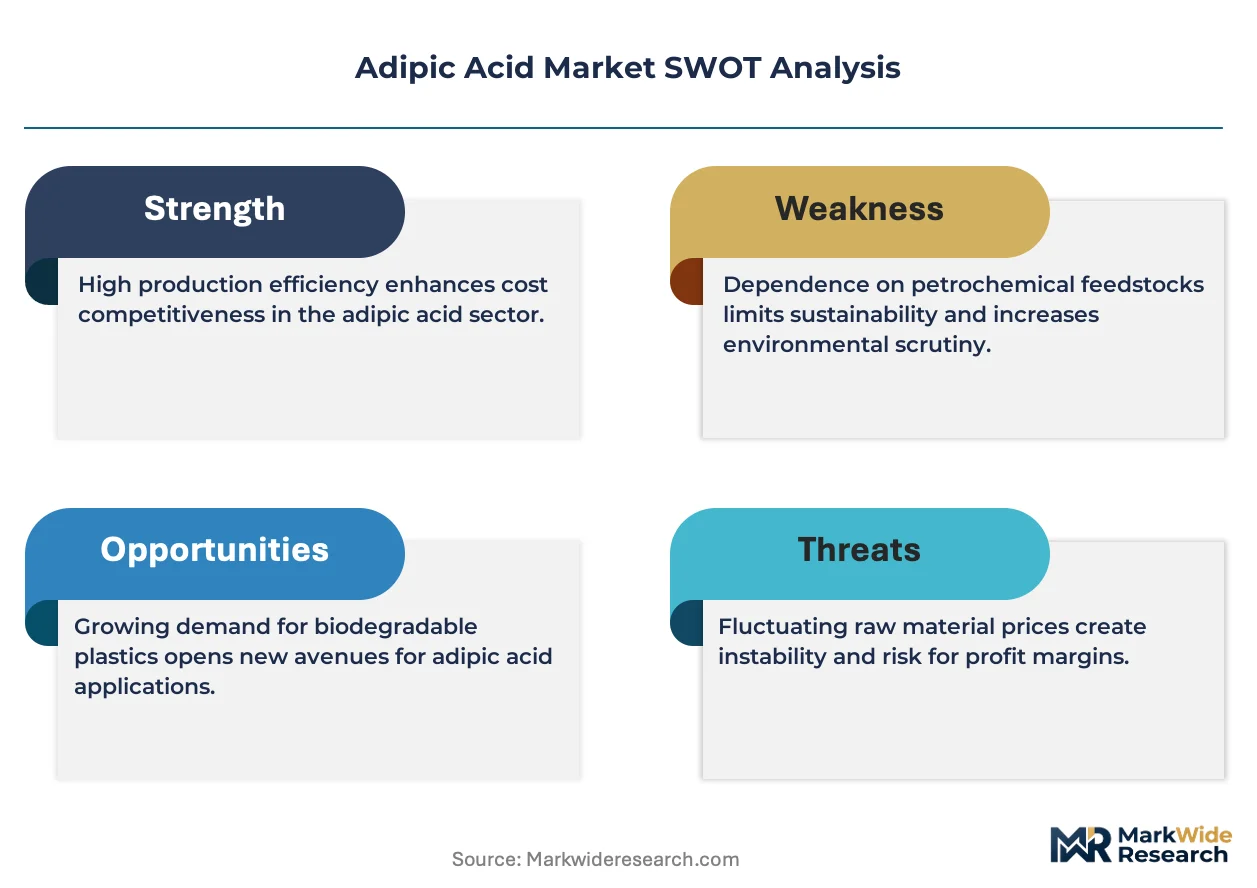
Automotive lightweighting mandates and polyurethane foam densification requirements are compressing specification tolerances for adipic acid purity and supply reliability, forcing producers to choose between capital-intensive cyclohexane route upgrades or bio-based platform investments.
Growth Catalysts
- Nylon 6,6 engineering resin specifications:Under-the-hood automotive components demand higher thermal resistance, pulling purified adipic acid volumes into polymer compounding operations serving powertrain and electrical housing applications.
- REACH chemical safety dossiers:ECHA registration requirements for cyclohexane derivatives are consolidating qualified supplier pools, advantaging producers with existing compliance infrastructure and documented nitrous oxide abatement systems.
- China's dual carbon targets:MEE enforcement pressures coal-based benzene-to-cyclohexane routes toward natural gas or bio-feedstock alternatives, accelerating process technology substitution in Shandong and Liaoning production clusters.
Market Restraints
- Cyclohexane feedstock volatility:Benzene price fluctuations transmit directly to adipic acid cash costs, compressing margins for non-integrated producers lacking captive aromatics supply.
- Nitrous oxide abatement capex:EPA Clean Air Act standards require catalytic decomposition or thermal destruction systems, adding fixed cost burdens that disadvantage smaller-scale facilities.
- Sebacic acid substitution:Castor oil-derived C10 diacid competes in flexible polyurethane and lubricant ester applications where bio-based content carries premium positioning.
Strategic Opportunities
- Bio-adipic acid fermentation platforms:Glucaric acid reduction pathways and direct sugar-to-dicarboxylic acid processes offer carbon-intensity reductions for brands targeting Scope 3 emissions disclosure.
- Synthetic lubricant base stock growth:Diester and polyol ester formulations for electric vehicle thermal management fluids represent specification-driven volume expansion outside traditional nylon and polyurethane demand.
- Direct automotive tier-one contracting:Seating and insulation foam manufacturers are consolidating supplier bases, creating preferred partnership positions for producers with integrated hexamethylenediamine capabilities.
Industry Challenges
- Process control engineering scarcity:Nitric acid oxidation unit optimization requires specialized expertise in reaction kinetics and emissions management that competes with broader chemical industry talent pools.
- Legacy asset retrofit complexity:Cyclohexane-based plants face stranded investment risk as low-carbon process routes mature, complicating depreciation schedules and refinancing decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adipic Acid Market |
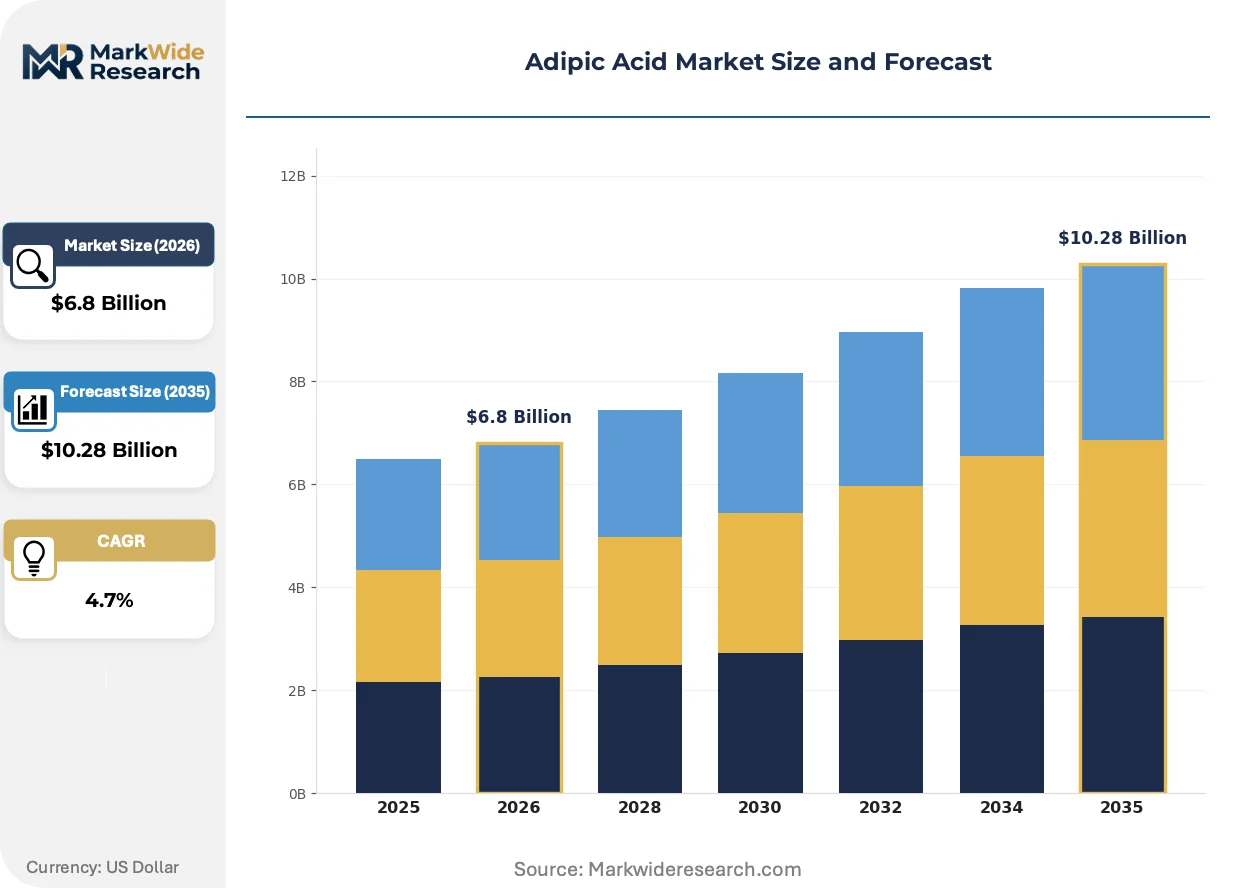
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nylon, Polyurethane, Coatings, Adipic Acid Derivatives End Use Industry: Textiles, Automotive, Building & Construction, Consumer Goods Application: Plastic Manufacturing, Synthetic Fibers, Adhesives, Sealants Distribution Channel: Direct Sales, Distributors, Online Stores, Retail |
| Companies Covered | BASF SE, Ascend Performance Materials, INVISTA, LANXESS, Asahi Kasei Corporation, Radici Partecipazioni SpA, Solvay, PetroChina Liaoyang Petrochemical, Shandong Haili Chemical Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adipic Acid Market Strategic Shifts & Innovations
Bio-based feedstock conversion technologies and precision fermentation platforms are disrupting the cyclohexane oxidation hegemony that has defined industrial adipic acid production for seven decades.
Microbial strain engineering for direct glucose-to-adipic acid biosynthesis is collapsing the capital intensity gap between petrochemical and fermentation routes. Specialty chemical producers in the Netherlands and California are piloting continuous fermentation systems with integrated product recovery. This technology is collapsing the historical 40-50 percent cost premium that confined bio-routes to niche cosmetic and pharmaceutical applications.
REACH authorization procedures for Substances of Very High Concern are tightening cyclohexane derivative handling requirements across EU member states. Downstream nylon compounders face extended compliance timelines for legacy adipic acid stocks lacking updated safety data sheets. Automotive seating manufacturers in Germany and Czechia are accelerating supplier audits to preempt production line interruptions from regulatory non-conformance.
Automotive OEMs are consolidating polyurethane foam specifications across platform architectures, reducing the number of approved adipic acid suppliers per seating program. Tier-one foam producers are responding with multi-year offtake agreements that exchange volume commitments for price indexing mechanisms. This concentration is most visible in North American light truck and SUV seating supply chains, where three platform families account for the majority of rigid foam consumption.
Adipic Acid Market Segmentation
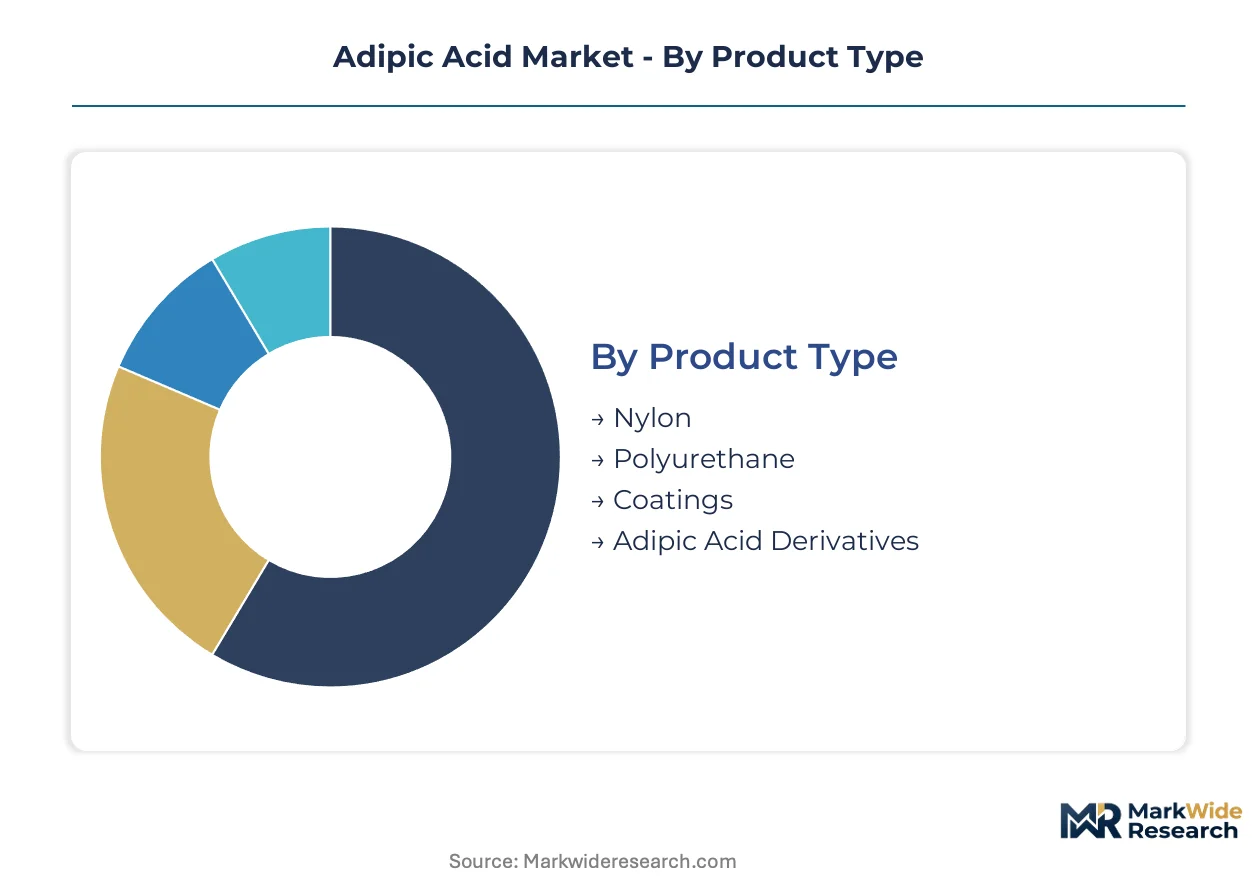
Adipic acid consumption patterns diverge sharply across product types and end-use industries, with purity specifications and supply reliability requirements varying by application. Understanding these segment boundaries reveals where margin pools concentrate and where procurement consolidation is reshaping supplier relationships.
Product Type:
Application-grade differentiation in adipic acid centers on purity thresholds and downstream processing requirements, with each product category serving distinct polymerization chemistries.
- Nylon:Polymer-grade adipic acid exceeding 99.7% purity serves as the essential co-monomer with hexamethylenediamine in nylon 6,6 polycondensation. Demand concentrates in under-the-hood automotive engineering resins where thermal resistance specifications from powertrain and electrical housing applications pull volumes into compounding operations.
- Polyurethane:Rigid foam formulations consume adipic acid as chain extenders in automotive seating and building insulation systems. Specification tolerances compress as automotive OEMs consolidate foam platforms across light truck and SUV architectures, forcing producers to guarantee supply reliability for multi-year offtake agreements.
- Coatings:Alkyd resin and polyester polyol applications utilize standard industrial grades for surface protection formulations.
- Adipic Acid Derivatives:Plasticizers and synthetic lubricant base stocks represent smaller but strategically targeted growth categories outside traditional polymer demand.
Polyurethane commands the established base. The steepest expansion trajectory runs through Adipic Acid Derivatives.
End Use Industry:
Customer-type segmentation in adipic acid reveals how regulatory pressure and lightweighting mandates concentrate demand among specific industrial buyers.
- Automotive:Tier-one seating and insulation foam manufacturers drive procurement consolidation through direct supply contracts. EPA Clean Air Act nitrous oxide standards and REACH registration requirements filter qualified supplier pools, advantaging producers with documented emissions abatement systems.
- Building & Construction:Rigid polyurethane foam for thermal insulation specifications in energy-efficient building codes. China's dual carbon targets and MEE enforcement pressure coal-based benzene-to-cyclohexane routes toward lower-carbon alternatives in Shandong and Liaoning production clusters serving this segment.
- Textiles:Nylon 6,6 fiber applications for apparel and industrial yarns.
- Consumer Goods:Packaging films, appliance components, and household durables utilizing engineering resin grades.
Automotive anchors the revenue base. Building & Construction is climbing the fastest amid energy-efficiency code adoption.
Application:
Volume concentration in adipic acid applications reflects the dominance of polymer manufacturing over specialty chemical uses.
- Synthetic Fibers:Nylon 6,6 filament and staple production for textile and industrial yarn applications. Shandong Haili Chemical Industry and PetroChina Liaoyang Petrochemical operate integrated caprolactam-adipic acid complexes serving domestic fiber producers in China.
- Plastic Manufacturing:Engineering resin compounding for injection-molded automotive and electrical components. Sebacic acid substitution from castor oil-derived C10 diacid competes in flexible applications where bio-based content carries premium positioning.
- Adhesives:Polyurethane reactive hot-melt and solvent-based formulations.
- Sealants:Construction and automotive gap-filling applications requiring moisture-cure chemistry.
Plastic Manufacturing holds the volume concentration. Synthetic Fibers is gaining share fastest through Asia-Pacific textile demand.
Distribution Channel:
Supply chain configuration in adipic acid reflects the tension between bulk commodity logistics and specification-driven partnership models.
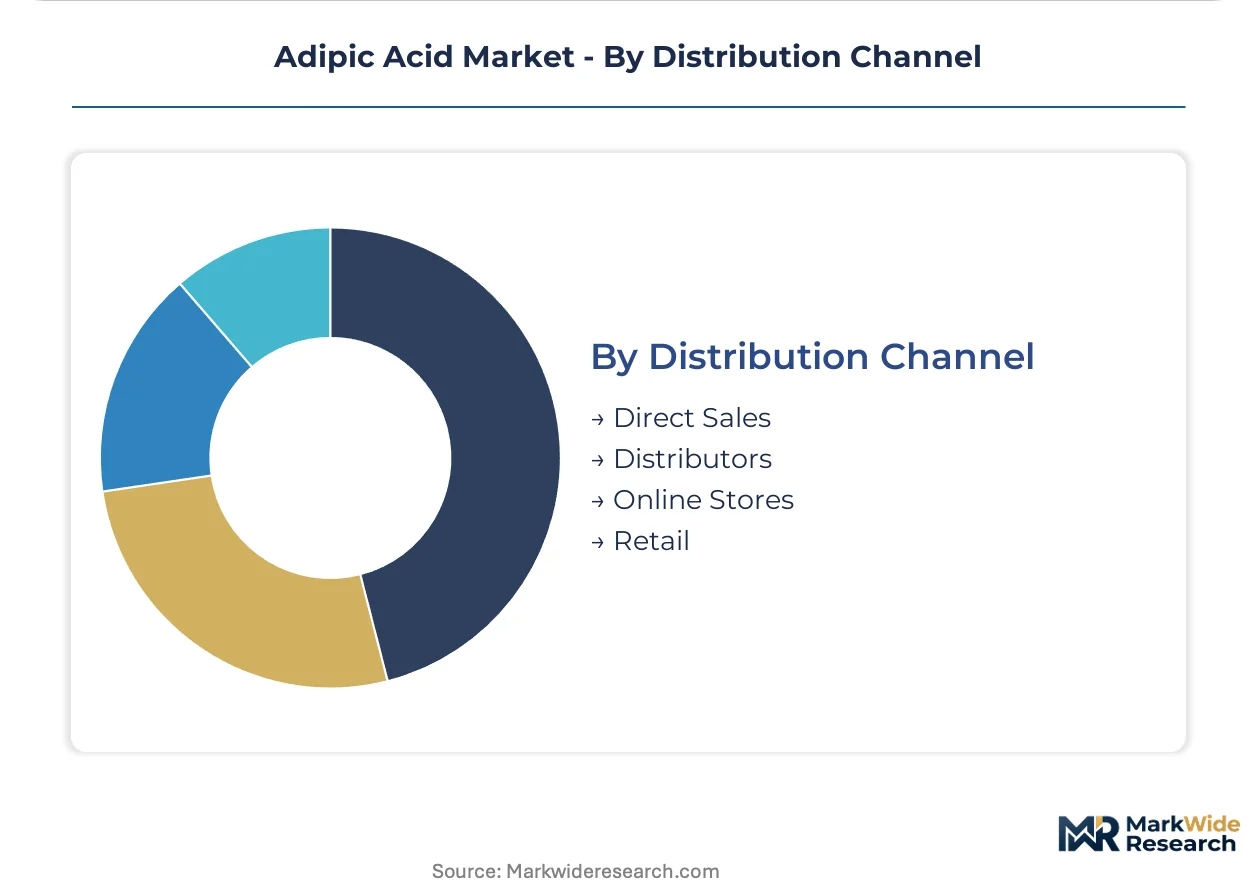
- Direct Sales:Multi-year offtake agreements between adipic acid producers and automotive tier-one suppliers. BASF SE leverages Ludwigshafen Verbund integration, Ascend Performance Materials anchors through Chocolate Bayou, and INVISTA competes on scale at Victoria, Texas with backward integration into butadiene derivatives.
- Distributors:Regional chemical distributors serving mid-scale nylon compounders and specialty polyurethane formulators lacking direct procurement scale.
- Online Stores:E-procurement platforms for standard industrial grades and smaller volume requirements.
- Retail:Limited specialty chemical outlets for laboratory and research quantities.
Direct Sales captures the premium-contract value. Distributors show the steepest expansion through mid-market consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Northwest Europe's role in adipic acid feedstock logistics, while the Yangtze River Delta's pipeline networks anchor Asia-Pacific supply chains.
United States
Automotive seating foam demand from Detroit's light truck platforms and Gulf Coast petrochemical integration shape procurement patterns. EPA Clean Air Act nitrous oxide standards filter qualified supplier pools along the Texas-Louisiana chemical corridor. Ascend Performance Materials operates its Chocolate Bayou facility with integrated hexamethylenediamine production serving domestic nylon compounders.
Germany
REACH registration requirements for cyclohexane derivatives consolidate qualified supplier pools around Ludwigshafen and Leverkusen chemical clusters. ECHA authorization procedures for Substances of Very High Concern extend compliance timelines for legacy adipic acid stocks. BASF SE leverages its Verbund complex to sustain captive cyclohexane-to-adipic acid integration for European automotive tier-one contracts.
China
Nylon 6,6 fiber demand from Zhejiang and Jiangsu textile producers concentrates procurement around Shandong and Liaoning production bases. MEE enforcement of dual carbon targets pressures coal-based benzene-to-cyclohexane routes toward natural gas alternatives. Shandong Haili Chemical Industry and PetroChina Liaoyang Petrochemical operate integrated caprolactam-adipic acid complexes serving domestic synthetic fiber manufacturers.
Japan
Engineering resin specifications for hybrid vehicle powertrain components pull purified adipic acid volumes into compounding operations. METI carbon neutrality roadmaps pressure petrochemical producers toward bio-feedstock pilot programs. Asahi Kasei Corporation anchors domestic supply through its integrated nylon intermediate operations serving Kansai and Chubu automotive manufacturing clusters.
India
Textile sector expansion in Gujarat and Maharashtra drives adipic acid consumption for nylon 6,6 filament production. BIS quality certification requirements for polymer-grade materials filter import sourcing toward established regional distributors. Reliance Industries and Gujarat State Fertilizers operate aromatics integration that supports emerging domestic adipic acid project development.
Adipic Acid Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in feedstock and intermediate positioning. The adipic acid sector exhibits consolidated structure around integrated petrochemical conglomerates and nylon-focused chemical producers. Three archetypes dominate: cyclohexane-integrated petrochemical majors, caprolactam-nylon vertical specialists, and regional state-owned energy enterprises. Competitive moves center on backward integration into aromatics supply and multi-year automotive offtake contracting.
Among European chemical conglomerates, BASF SE and LANXESS exemplify platform-integrated positioning through Rhineland chemical corridor assets. INVISTA and Ascend Performance Materials represent North American scale-driven specialization with Gulf Coast production bases. Asahi Kasei Corporation and Radici Partecipazioni SpA occupy positions within Asia-Pacific and Mediterranean nylon value chains respectively. Solvay sits within the specialty chemical tier with fluorinated materials adjacencies. Shandong Haili Chemical Industry Co., Ltd. and PetroChina Liaoyang Petrochemical anchor Chinese state-backed production capacity serving domestic textile and automotive demand.
| Leading Market Players |
|---|
| BASF SE |
| Ascend Performance Materials |
| INVISTA |
| LANXESS |
| Asahi Kasei Corporation |
| Radici Partecipazioni SpA |
| Solvay |
| PetroChina Liaoyang Petrochemical |
| Shandong Haili Chemical Industry Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Underutilized cyclohexane oxidation capacity in Shandong and Liaoning provinces compresses supplier leverage, forcing producers toward multi-year automotive offtake agreements that exchange volume commitments for price indexing mechanisms. This utilization dynamic simultaneously erodes spot-market pricing power while rewarding integrated producers with captive aromatics supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates adipic acid procurement. Price differentiation rests on polymer-grade purity certification and automotive OEM qualification status. Pricing pressure stems from benzene feedstock volatility transmitting directly to non-integrated producers. Tier-one automotive seating manufacturers show lowest price sensitivity due to specification-critical applications, while mid-scale nylon compounders exhibit highest sensitivity to cyclohexane cost pass-through.
Supply Chain Analysis
Tariff exposure between China and Western automotive manufacturing clusters dominates supply chain risk assessment. Geographic concentration centers on China, the United States, and Germany. Raw material dependencies draw from benzene, cyclohexane, and nitric acid feedstocks. Single-source vulnerability persists for polymer-grade material qualified under EPA Clean Air Act and REACH registration requirements. Distribution runs through direct sales contracts between adipic acid producers and automotive tier-one suppliers, with regional distributors serving mid-scale compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adipic acid procurement is evolving into a service-attach opportunity as nitrous oxide abatement compliance and technical specification support expand faster than commodity chemical margins. Recurring revenue from emissions monitoring and certification documentation now outpaces base product growth.
For Market Incumbents: Pre-empt bio-adipic acid fermentation platforms by securing glucose supply agreements and piloting glucaric acid reduction pathways before carbon-intensity disclosure mandates harden. Defend position through backward integration into cyclohexane supply and multi-year automotive offtake contracting that locks in specification-critical volumes. For New Entrants and Emerging Players: Synthetic lubricant base stocks for electric vehicle thermal management fluids represent the most penetrable entry point, with diester and polyol ester formulations offering specification-driven margin expansion outside consolidated nylon and polyurethane demand. Target flexible polyurethane applications where sebacic acid substitution has established bio-based premium positioning. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because nitrous oxide abatement capex and REACH dossier maintenance are consolidating qualified supplier pools around producers with documented emissions systems. Watch for MEE enforcement acceleration in Shandong and Liaoning as the signal for process technology substitution inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive cyclohexane supply insulates BASF and Ascend from benzene volatility. |
| Green Manufacturing Transition | Bio-adipic acid fermentation platforms reduce Scope 3 emissions for automotive OEM disclosure. |
| Long-term Supply Agreement | Multi-year offtake contracts with tier-one seating manufacturers lock in specification-critical volumes. |
| Capacity Expansion | Integrated caprolactam-adipic acid complexes in Shandong serve domestic nylon 6,6 fiber demand. |
| Joint Venture | Regional partnerships with glucose suppliers secure feedstock for fermentation platform scale-up. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with plant managers, procurement leads at automotive tier-one suppliers, distribution channel partners, and technical R&D directors; and secondary validation through customs/trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA emissions disclosures. Bottom-up volume modeling and top-down market sizing triangulated against operating metrics from integrated petrochemical complexes.
Forecast inputs considered grade tier, end-use industry, and regional production hub segmentation across the analysis window. CAGRs derived from historical operating rate trends, capacity addition pipelines, and demand elasticity by application. Industry-specific inputs included automotive lightweighting mandate intensity and MEE dual carbon target enforcement trajectory.
Macroeconomic conditions sit as an overlay; deviation in benzene pricing, automotive production schedules, or carbon credit valuations would shift the trajectory. Forecasts reflect assumptions around nitrous oxide abatement technology adoption and REACH authorization timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Tributyl Citrate Market
Bulk Chemicals
Europe Calcium Chloride Market
Bulk Chemicals
Ammonium Bromide Market
Bulk Chemicals
Asia Pacific Dry PVC Compound Market
Bulk Chemicals
Sodium Perborate Market
Bulk Chemicals
Zinc Carbonate Market
Bulk Chemicals
South America Carbon Black Market
Bulk Chemicals
Isatoic Acid Anhydride Market
Bulk Chemicals
Maleic Anhydride Market
Bulk Chemicals
Benzyl Acetate Market
Bulk Chemicals
Methyl Cyclohexane Market
Bulk Chemicals
Lignosulfonates Market
Bulk Chemicals
Global Quinine Sulphate Market
Bulk Chemicals
Europe Gamma Butyrolactone Market
Bulk Chemicals
Magnesium Sulfate Market
Bulk Chemicals
Global Naphthenic Base Oil Market