
 Global Geothermal Heat Pumps Market | 2026-2036
Global Geothermal Heat Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Geothermal Heat Pumps Market Analysis
The EU Green Deal is decoupling building heating demand from fossil fuel dependency across European member states. ClimateMaster leverages its domestic manufacturing footprint to anchor North American supply chains for closed-loop residential systems. Stiebel Eltron specializes in compact heat pump engineering for retrofitted multi-family housing across German-speaking markets. NIBE Industrier AB extends its Nordic distribution network into Central European contractor channels.
Geothermal heat pumps transfer thermal energy between the earth's subsurface and building interiors using refrigerant-filled ground loops typically installed meters below the frost line, achieving coefficient of performance ratios exceeding conventional air-source alternatives. These systems serve primary commercial and industrial purposes by reducing operational energy expenditure for space conditioning and domestic hot water production. Closed loop configurations dominate residential and light commercial deployment due to lower site-specific hydrogeological requirements, while vertical borehole installations command premium positioning in dense urban settings where surface area constraints eliminate horizontal trenching options. Open loop systems extract groundwater directly for heat exchange, occupying niche applications near productive aquifers where regulatory discharge permits remain obtainable.
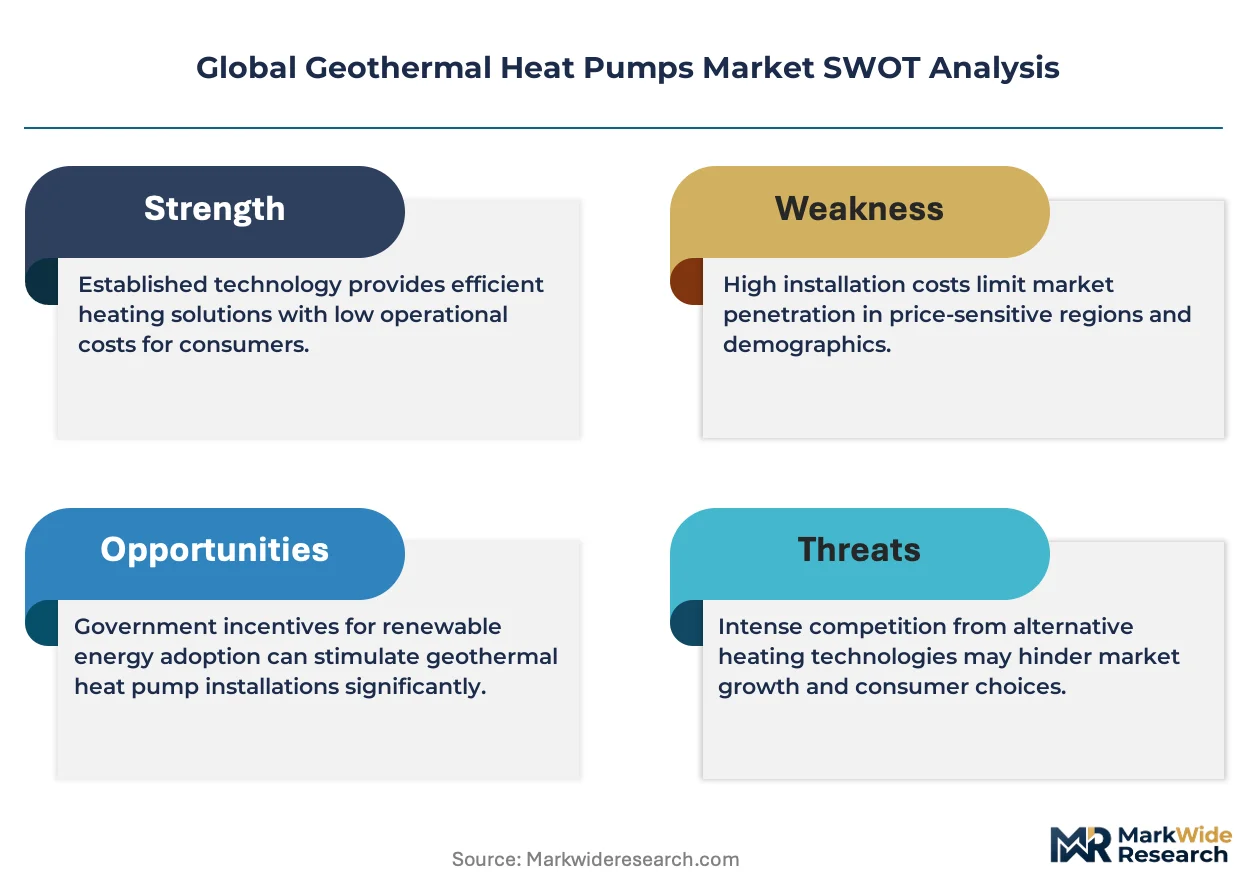
The EPA regulates geothermal loopfield construction under Underground Injection Control provisions, while the EU F-Gas Regulation phases down hydrofluorocarbon refrigerants with global warming potential above specified thresholds. China's MIIT enforces GB energy efficiency standards for electrically driven heat pumps sold into building renovation programs. Stakeholders must monitor refrigerant transition timelines and subsurface drilling permit backlogs as these constraints determine viable project pipelines and equipment specification requirements.
Market Dynamics
The EU F-Gas Regulation is forcing refrigerant transitions across closed-loop system manufacturing, compressing equipment specification timelines while EPA Underground Injection Control provisions extend drilling permit backlogs in dense US urban corridors. These dual regulatory pressures are restructuring project viability assessments and supplier qualification protocols.
Growth Catalysts
- EU Green Deal building mandates:Germany's tightened efficiency standards for residential retrofits are accelerating horizontal loop installations in suburban development zones.
- China's MIIT GB standards:Enforcement of energy efficiency benchmarks for electrically driven heat pumps is channeling renovation program subsidies toward certified equipment.
- Natural gas price volatility:Commercial facility operators in heating-intensive sectors are redirecting capex toward ground-source alternatives to stabilize operational expenditure.
Market Restraints
- Copper and refrigerant input costs:Ground loop piping and HFC phase-down transitions are compressing equipment margin structures for residential system assemblers.
- Vertical drilling supply concentration:Specialized borehole contractors in Germany and the northeastern United States are creating bottleneck risks for urban commercial projects.
- Aquifer proximity requirements:Open loop deployment remains constrained to sites within productive groundwater zones with obtainable discharge permits.
Strategic Opportunities
- Polish residential underpenetration:District heating legacy infrastructure creates white space for individual building retrofits as EU cohesion funds flow eastward.
- Hybrid heat pump convergence:Integration of geothermal loops with solar thermal collectors is opening multi-family housing applications previously excluded by space constraints.
- Contractor direct channels:Bypassing traditional HVAC wholesale networks through certified installer programs is capturing margin in fragmented Central European markets.
Industry Challenges
- Geotechnical assessment skill gaps:Site-specific thermal conductivity testing requires hydrogeological expertise that outpaces vocational training pipeline output.
- Legacy hydronic system integration:Retrofit compatibility with existing radiator configurations demands customized engineering that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Geothermal Heat Pumps Market |
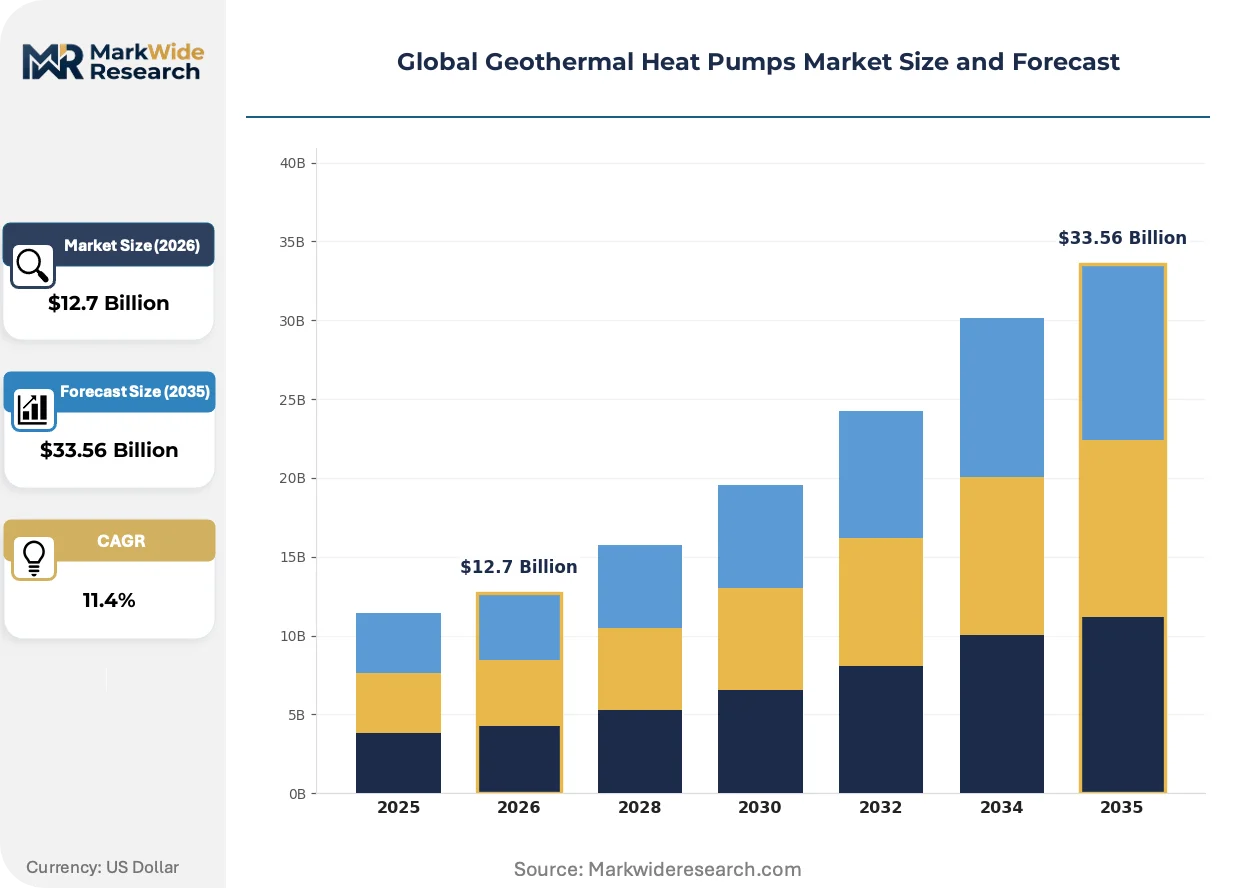
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $33.56 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Pond, Direct Exchange Installation Type: Residential, Commercial, Industrial, Government System Configuration: Closed Loop, Open Loop, Hybrid, Dual Source End User: Homeowners, Businesses, Contractors, Developers |
| Companies Covered | ClimateMaster, WaterFurnace International, Stiebel Eltron, Vaillant Group, Viessmann, Daikin, NIBE Industrier AB, Carrier, Ingersoll Rand (Trane), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Geothermal Heat Pumps Market Emerging Trajectories
Refrigerant chemistry transitions and digital monitoring platforms are restructuring equipment specification and long-term performance verification across project development cycles. These shifts are compressing supplier qualification windows while elevating lifecycle cost analytics in procurement decisions.
CO2 transcritical heat pump cycles are expanding into Nordic district heating networks and large-scale commercial applications where high output temperatures are required. Municipal utilities in Denmark and Sweden are deploying these systems for low-temperature grid supply. The technology is expanding into markets previously reserved for biomass and waste heat recovery, compressing the addressable base for conventional HFC-based equipment.
REACH and F-Gas phase-down schedules are eliminating hydrofluorocarbon refrigerants above specified global warming potential thresholds from new equipment placement. European manufacturers are accelerating propane and CO2 platform development to maintain market access. Residential and light commercial segments are absorbing compliance costs through premium positioning, while commercial project developers are extending equipment procurement timelines to align with refrigerant transition deadlines.
Lifecycle cost analytics are displacing first-cost procurement criteria in commercial and institutional buyer segments. Facility managers in Germany and the Netherlands are contracting energy service companies for performance-guaranteed installations. This shift is most visible in healthcare and educational end-uses where operational expenditure visibility outweighs capital budget constraints, compressing traditional equipment-only sales channels.
Global Geothermal Heat Pumps Market Segmentation
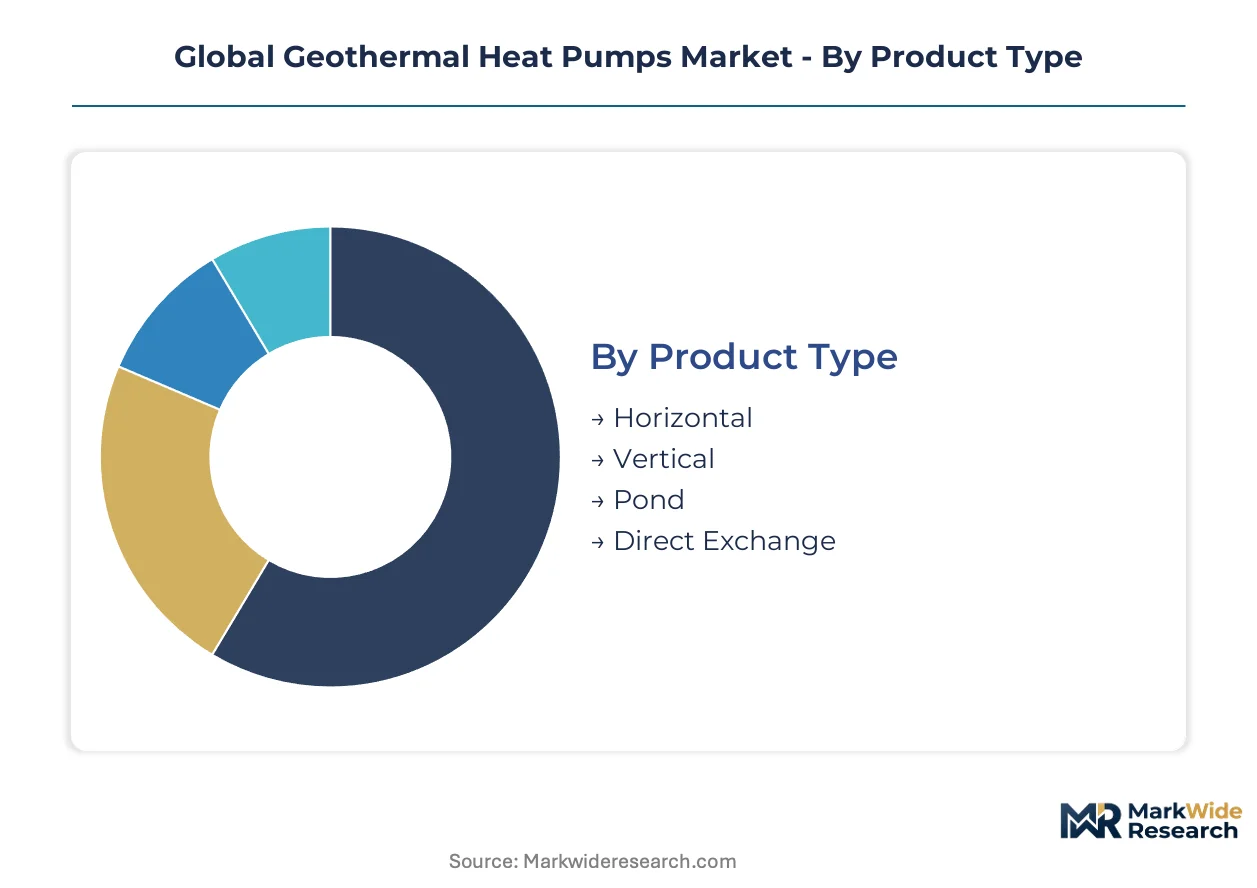
Ground-loop configuration, installation scale, and procurement channel each impose distinct engineering requirements and margin structures across geothermal heat pump deployment. Segment boundaries determine refrigerant selection, drilling contractor specialization, and regulatory compliance pathways.
Product Type:
Standardized trenching methods compete with site-customized borehole engineering across this spectrum, with cost predictability trading off against land-use efficiency.
- Horizontal:Parallel piping arrays sit 1-2 meters below grade in excavated trenches spanning 400-600 square meters per residential unit. German suburban retrofits favor this configuration where lot sizes exceed 800 square meters and EU Green Deal subsidies offset trenching labor costs.
- Vertical:U-bend probes descend 50-150 meters through drilled boreholes, concentrating thermal exchange in minimal surface footprints. Urban commercial projects in Chicago and Frankfurt specify vertical loops where surface constraints eliminate trenching options, though specialized drilling contractors extend lead times.
- Pond:Submerged coil systems exploit stable water temperatures in standing water bodies. Lakeside residential clusters in Minnesota and Bavaria deploy this variant where shoreline permits remain obtainable.
- Direct Exchange:Copper refrigerant lines contact soil directly without intermediate heat transfer fluid, achieving higher thermal conductivity. This configuration occupies niche applications in the US Southeast where soil chemistry permits copper burial.
Most installed capacity flows through Horizontal. Expansion is steepest in Vertical.
Installation Type:
Project scale determines loopfield engineering complexity and contractor qualification tiers, with single-family simplicity contrasting against multi-zone commercial integration.
- Residential:Single-family and multi-family dwellings under 500 square meters of conditioned space. Polish and Czech markets show accelerating uptake as EU cohesion funds channel subsidies toward individual building retrofits outside district heating zones.
- Commercial:Office buildings, retail facilities, and hospitality properties requiring 100-500 kilowatts of thermal capacity. German healthcare facilities and Dutch educational institutions dominate procurement through energy service company performance contracts.
- Industrial:Manufacturing plants and process facilities with constant baseload thermal demand. Food processing and pharmaceutical cleanrooms in Denmark specify geothermal for stable temperature control.
- Government:Municipal buildings, military installations, and public infrastructure projects subject to procurement transparency mandates. US federal new construction guidelines under the IRA direct agencies toward ground-source systems.
Residential claims the dominant share of unit volume. Commercial applications are climbing the fastest.
System Configuration:
Closed containment versus open water exchange defines regulatory exposure and site feasibility, with hybrid architectures emerging at the boundary.
- Closed Loop:Sealed piping circuits circulate water-glycol mixture or refrigerant without environmental discharge. This configuration dominates European markets where REACH and F-Gas regulations constrain fluid chemistry options and EPA Underground Injection Control governs US permitting.
- Open Loop:Groundwater extraction and reinjection achieve direct thermal exchange. Productive aquifers in the US Great Lakes region and parts of northern Germany sustain limited deployment where discharge permits remain obtainable.
- Hybrid:Geothermal loops paired with auxiliary heat sources optimize seasonal performance. Solar thermal integration is gaining traction in Swedish multi-family retrofits previously excluded by space constraints.
- Dual Source:Switchable ground-source and air-source operation provides backup capacity. This architecture addresses contractor risk aversion in markets with limited drilling service availability.
Closed Loop accounts for the preponderance of new installations. Hybrid configurations are expanding most quickly.
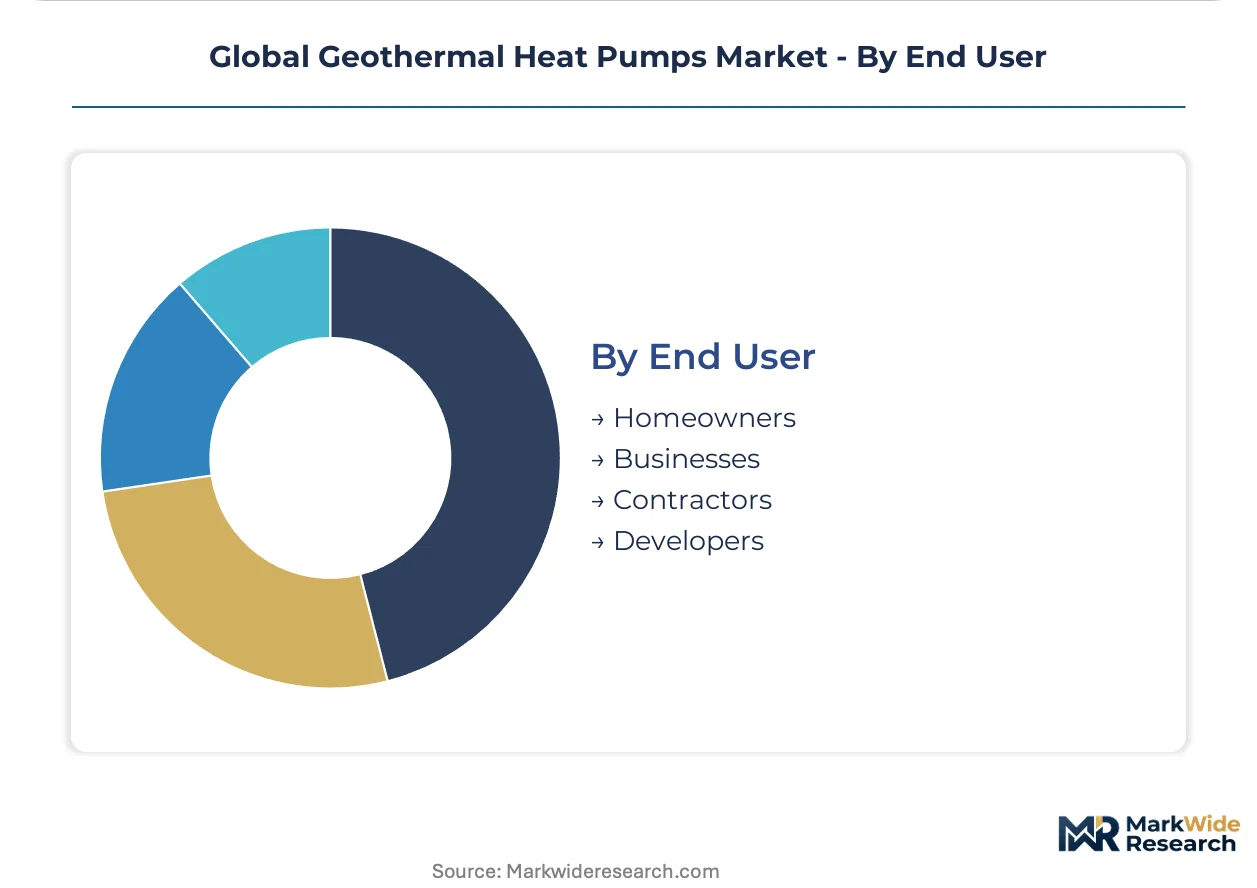
End User:
Procurement sophistication varies sharply across direct consumers, intermediary channels, and speculative developers, shaping specification authority and lifecycle accountability.
- Homeowners:Individual residential purchasers relying on contractor recommendations and subsidy program eligibility. German-speaking markets show high awareness of coefficient-of-performance metrics.
- Businesses:Corporate facility managers prioritizing operational expenditure predictability over capital cost minimization. Dutch logistics and data center operators lead commercial adoption.
- Contractors:HVAC installation firms specifying equipment for client projects. Certified installer programs in Austria and Switzerland bypass traditional wholesale channels.
- Developers:Real estate developers pre-installing loopfields in speculative construction. Chinese residential developers in Beijing and Shanghai integrate geothermal as standard efficiency feature.
Contractors mediate the largest share of equipment selection. Developer-direct procurement is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized drilling contractors and HVAC technicians cluster in Germany's Rhine-Ruhr corridor, Oklahoma's geothermal belt, and China's Shandong manufacturing zones. These workforce concentrations anchor equipment demand and installation capacity across distinct regulatory environments.
United States
Federal agencies under IRA construction guidelines specify ground-source systems for new public buildings. EPA Underground Injection Control provisions extend permit backlogs in dense urban corridors. Chicago and Minneapolis commercial districts favor vertical borehole installations where surface constraints eliminate trenching.
Germany
Horizontal loop arrays dominate suburban retrofits as EU Green Deal subsidies offset trenching labor costs. The F-Gas Regulation phases down hydrofluorocarbon refrigerants above specified global warming potential thresholds. Bavarian lakeside clusters deploy pond loop configurations where shoreline permits remain obtainable.
China
MIIT enforces GB energy efficiency standards for electrically driven heat pumps sold into building renovation programs. Beijing and Shanghai residential developers integrate geothermal as standard efficiency feature in speculative construction. Shandong Province concentrates manufacturing capacity for closed-loop residential equipment.
Sweden
CO2 transcritical heat pump cycles expand into district heating networks requiring high output temperatures. Municipal utilities deploy these systems for low-temperature grid supply. Stockholm's multi-family retrofits absorb solar thermal integration previously excluded by space constraints.
Poland
EU cohesion funds channel subsidies toward individual building retrofits outside legacy district heating zones. Contractors bypass traditional HVAC wholesale networks through certified installer programs. Krakow and Warsaw suburban corridors show accelerating horizontal loop uptake.
Global Geothermal Heat Pumps Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the geothermal heat pump value chain. The market structure consolidates around integrated equipment manufacturers with captive loopfield installation networks, while regional assemblers fragment the mid-tier residential segment. Three archetypes dominate: Nordic specialists in compact engineering, North American full-system integrators, and Asian scale producers. Competitive moves concentrate on refrigerant platform transitions and certified installer channel capture.
Among North American full-system integrators, ClimateMaster and WaterFurnace International anchor the closed-loop residential segment. Stiebel Eltron exemplifies the Nordic specialist archetype in compact heat pump engineering. These three occupy positions spanning domestic manufacturing footprints, refrigerant transition readiness, and direct contractor channel access.
| Leading Market Players |
|---|
| ClimateMaster |
| WaterFurnace International |
| Stiebel Eltron |
| Vaillant Group |
| Viessmann |
| Daikin |
| NIBE Industrier AB |
| Carrier |
| Ingersoll Rand (Trane) |
| Others |
Supply Flow & Price Mechanics
Copper futures volatility on the London Metal Exchange cascades through ground loop piping procurement, compressing equipment margin structures for residential system assemblers while forcing tiered pricing stratification across certified and uncertified installer channels. The interaction between refrigerant phase-down compliance costs and specialized drilling contractor availability concentrates pricing power with vertically integrated manufacturers possessing captive borehole installation networks.
Pricing Analysis
Bundled loopfield-plus-equipment contracts command premium positioning against unbundled component procurement favored by contractor-direct channels in fragmented Central European markets. Three-tier pricing structure across premium, standard, and economy levels separates F-Gas-compliant refrigerant platforms from legacy HFC equipment and basic air-source alternatives. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in economy tiers is intensifying because copper input volatility and drilling labor shortages squeeze residential assemblers. Homeowner segments in subsidy-dependent markets show highest price sensitivity, while Dutch healthcare facility managers prioritize operational expenditure predictability over capital cost minimization.
Supply Chain Analysis
Direct-to-developer channels handle speculative construction demand in China's Beijing and Shanghai corridors, while certified installer programs bypass traditional HVAC wholesale networks in Austria and Switzerland. Manufacturing gravity centers on Germany's Rhine-Ruhr corridor for compact heat pump engineering, Oklahoma's geothermal belt for North American closed-loop systems, and Shandong Province for Chinese residential equipment. Raw material dependencies include copper tubing for ground loops, refrigerant chemistry for compliant heat pump platforms, and specialized drilling rig capacity for vertical borehole installations. Single-source vulnerability concentrates in German and US Northeastern borehole contractors, where qualification backlogs extend project timelines. Distribution runs through developer-direct procurement for new Chinese construction, energy service companies for Dutch commercial performance contracts, and certified installer networks for Central European retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Geothermal Heat Pumps Market functions as a stable compounder anchored by EU Green Deal building mandates that institutionalize decarbonization expenditure across member state renovation programs.
For Market Incumbents: To counter refrigerant transition compliance cost compression, prioritize backward integration into copper tubing supply and captive drilling service networks in Germany's Rhine-Ruhr corridor. Expand certification investment for F-Gas-compliant propane and CO2 platforms to maintain European market access against Nordic specialist competition.
For New Entrants and Emerging Players: CO2 transcritical platform development offers entry into Nordic district heating networks and large-scale commercial applications previously reserved for biomass alternatives. Polish residential retrofits outside legacy district heating zones present the most penetrable geography, with EU cohesion fund subsidies channeling toward individual building efficiency upgrades. Pursue contractor certification programs to bypass fragmented wholesale channels in Krakow and Warsaw suburban corridors.
For Investors and Strategic Acquirers: Consolidation pressure builds where refrigerant transition timelines compress equipment specification windows and favor manufacturers with platform readiness. Five-to-ten-year viability favors integrated producers combining domestic manufacturing footprints with certified installer channel control. Target acquisition archetype: regional assemblers with established drilling contractor relationships and F-Gas transition-compliant product pipelines. Monitor EPA Underground Injection Control permit backlog resolution as inflection indicator for US urban commercial project viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Transition | F-Gas and REACH compliance secures European market access against chemistry-locked competitors. |
| Certified Installer Network Expansion | Direct contractor channels capture margin in fragmented Austrian and Swiss wholesale bypass markets. |
| Vertical Borehole Capacity Addition | Specialized drilling assets in Chicago and Frankfurt address urban surface constraint demand. |
| Hybrid System Integration | Solar thermal pairing opens Swedish multi-family retrofits previously excluded by space constraints. |
| Developer-Direct Procurement Partnership | Beijing and Shanghai speculative construction integration anchors volume in China's renovation programs. |
Methodological Framework
Multiple input streams — primary interviews with HVAC contractors, drilling service operators, and energy service company procurement leads; secondary validation through EPA Underground Injection Control permit databases, EU F-Gas Regulation implementation timelines, and MIIT GB standard enforcement records; plus customs trade data for copper tubing and refrigerant chemistry flows — were reconciled through bottom-up installation volume modeling and top-down equipment value triangulation.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, modeling ground-loop configuration, installation scale, system architecture, and procurement channel segmentation. CAGRs were derived from equipment shipment trajectories and loopfield installation capacity expansion rates, with MIIT subsidy program eligibility criteria and EU Green Deal building mandate compliance schedules serving as demand-side forecast inputs.
The model holds under stable regulatory enforcement and copper price band conditions; deviation in EPA permit backlog resolution or F-Gas phase-down acceleration would shift equipment procurement timelines and manufacturer margin structures. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geothermal Energy
Netherlands Geothermal Energy Market
Geothermal Energy
United Kingdom Geothermal Energy Market
Geothermal Energy
Hungary Geothermal Energy Market
Geothermal Energy
Geothermal Power Infrastructure Market
Geothermal Energy
Geothermal Power Market
Geothermal Energy
Enhanced Geothermal System Market
Geothermal Energy
Geothermal Power Generation Market
Geothermal Energy
Philippines Geothermal Energy Market
Geothermal Energy
Geothermal Energy Market
Geothermal Energy
US Geothermal Heat Pump Market
Geothermal Energy
Denmark Geothermal Energy Market
Geothermal Energy
Asia-Pacific Geothermal Energy Market
Geothermal Energy
Sweden Geothermal Energy Market
Geothermal Energy
Geothermal Power Infrastructure and Components Market
Geothermal Energy
Indonesia Geothermal Energy Market