
 Denmark Geothermal Energy Market | 2026-2036
Denmark Geothermal Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Geothermal Energy Market Outlook
The gap between deep geothermal projects and shallow heat pump installations is expanding in Denmark. Innargi A/S anchors the premium tier through its Arhus concession targeting sedimentary reservoirs at two to three kilometer depths. Danfoss A/S competes in the distributed segment with heat pump manufacturing that leverages its industrial scale. Ramboll Group A/S specializes in reservoir engineering and district heating integration, sustaining its advisory position across multiple concessions.
Denmark geothermal energy encompasses the extraction of thermal energy from subsurface rock formations and aquifers, primarily through doublet well systems circulating brine at temperatures between 40°C and 120°C for direct heat supply without conversion to electricity. Binary cycle technology dominates new installations because lower-temperature Danish reservoirs suit organic Rankine cycle systems rather than flash steam configurations. District heating application leads volume deployment, while enhanced geothermal systems represent the fastest-growing type as Innargi and partners test hydraulic stimulation in tight limestone formations. Municipal end users capture the most stable margin pools through long-term concession contracts with guaranteed offtake.
The Danish Energy Agency implements licensing rounds under the Subsoil Act, while the country's heat planning legislation requires municipalities to map geothermal potential in their supply areas. These frameworks shape project timelines and capital commitment sequences by mandating geological survey phases before drilling approvals. Stakeholders must monitor whether upcoming revisions to the Heat Supply Act will open municipal networks to private concession holders or reinforce incumbent utility structures.
Market Dynamics
The Danish geothermal market pivots on municipal heat planning mandates that require fossil-free district heating by 2030, forcing utilities to accelerate deep geothermal drilling timelines and reconfigure concession bidding strategies around sedimentary basin access.
Growth Catalysts
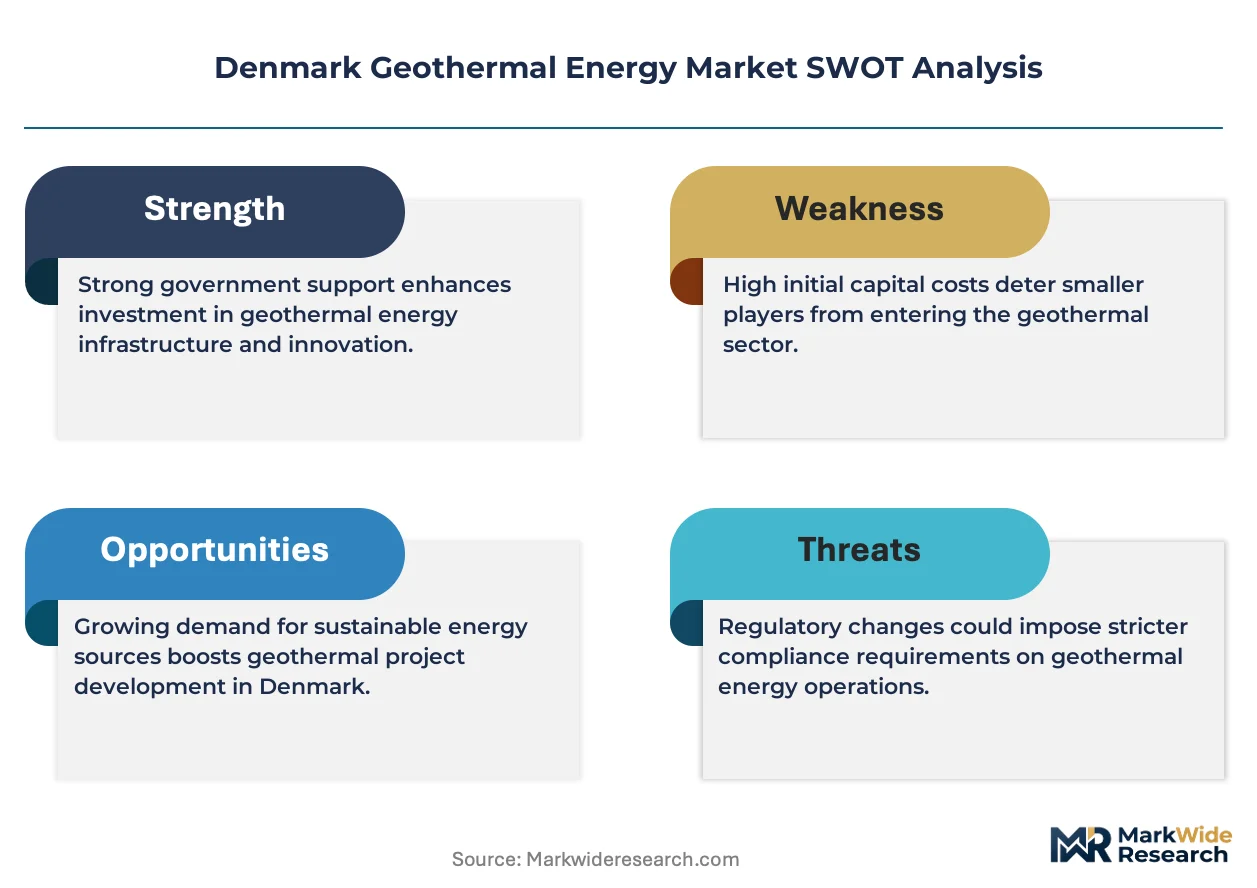
- Subsoil Act licensing rounds:The Danish Energy Agency's structured permitting framework accelerates project approval sequences for deep geothermal concessions in Zealand and Jutland sedimentary basins.
- Fossil-free heating mandate:Denmark's Climate Agreement for Energy and Industry creates binding demand pull for geothermal feed-in across Copenhagen, Aarhus, and Odense district heating networks.
- Sedimentary reservoir geology:Optimal thermal conductivity in Danish limestone formations enables binary cycle extraction at 40-120°C without hydraulic fracturing in most concession zones.
Market Restraints
- Capital intensity threshold:Deep doublet drilling to 2-3 kilometer depths requires EUR 50-80 million upfront commitment before reservoir confirmation, constraining municipal utility balance sheets.
- Geological uncertainty risk:Pre-drilling seismic surveys cannot eliminate permeability variance in tight limestone formations, exposing developers to dry-hole losses in 15-20% of targeted structures.
- Grid integration lead times:District heating network reinforcement and seasonal storage capacity expansion lag drilling schedules by 24-36 months in several Zealand municipalities.
Strategic Opportunities
- Enhanced geothermal systems:Hydraulic stimulation protocols for tight formations could unlock 40% additional reservoir capacity in Jutland limestone structures currently deemed marginal.
- Industrial process heat:Food processing and pharmaceutical manufacturing facilities in North Zealand represent untapped offtake segments beyond municipal district heating contracts.
- Heat Supply Act revision:Pending legislative amendments may open municipal networks to private concession holders, altering competitive entry dynamics for non-incumbent developers.
Industry Challenges
- Reservoir engineering specialization gap:Denmark lacks sufficient geophysicists and drilling engineers with deep sedimentary basin experience, forcing reliance on Dutch and German consultancy imports.
- Seasonal demand mismatch:Summer thermal offtake collapse requires costly aquifer storage or auxiliary heat dump infrastructure, compressing project IRRs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Geothermal Energy Market |
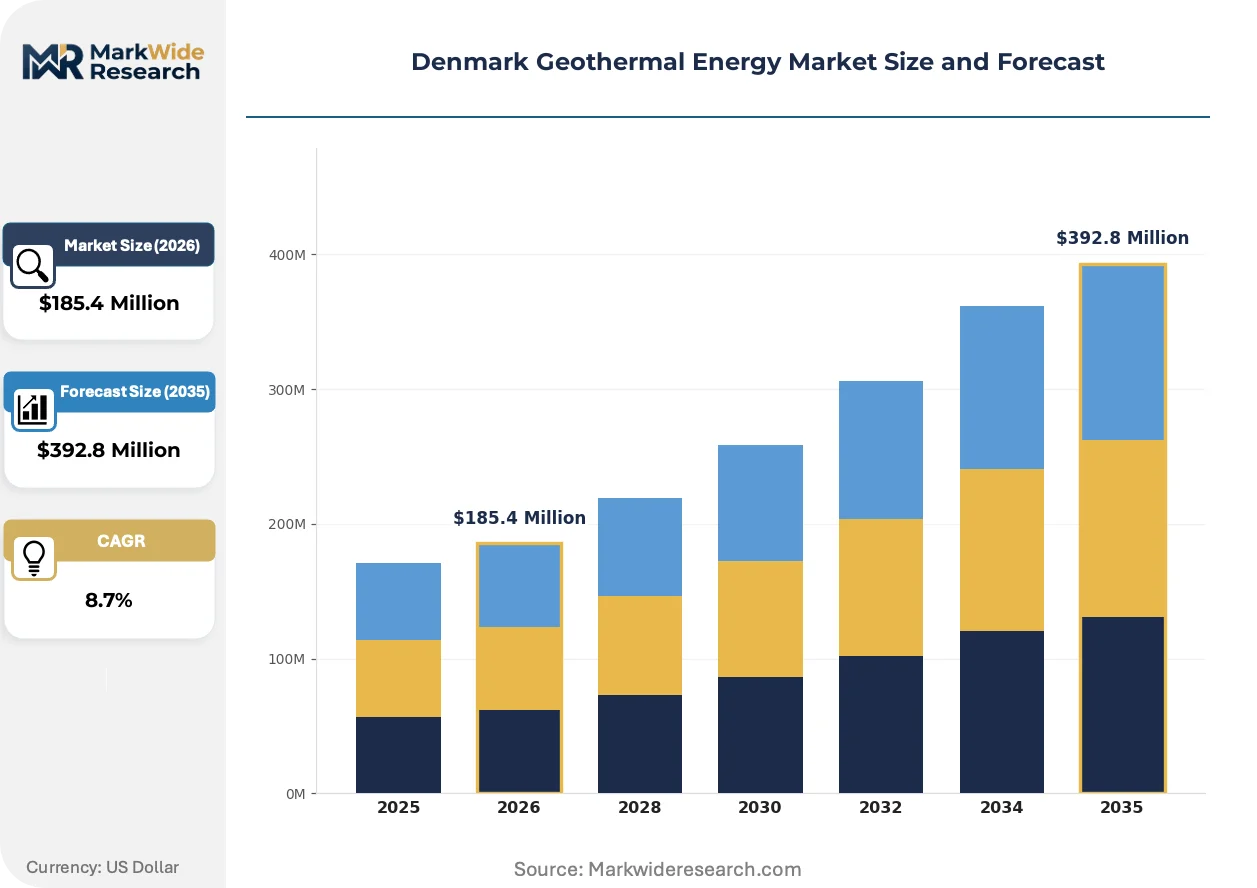
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $392.8 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hot Dry Rock, Enhanced Geothermal Systems, Geothermal Heat Pumps, Reservoir Geothermal Technology: Binary Cycle, Flash Steam, Dry Steam, Combined Heat and Power Application: District Heating, Agriculture, Industrial Heating, Spa Applications End User: Residential, Commercial, Industrial, Municipal |
| Companies Covered | Innargi A/S, Danfoss A/S, Ramboll Group A/S, Welltec A/S, NIRAS A/S, A.P. Møller Holding A/S, Geothermal Operations Company, Gate 21, MAN Energy Solutions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Geothermal Energy Market Strategic Shifts
Binary cycle organic Rankine systems are displacing flash steam configurations across Danish installations, while reservoir characterization software and municipal procurement models undergo simultaneous transformation.
Closed-loop geothermal systems is converging with advanced subsurface heat exchanger designs to enable extraction from lower-permeability formations without brine circulation. Aarhus and Copenhagen municipal utilities are piloting these configurations in marginal concession blocks where traditional doublet systems failed. This technology is converging with existing district heating infrastructure to extend reservoir viability and reduce geological risk exposure for developers.
Denmark's Heat Supply Act mandates municipal heat planning that maps geothermal potential before concession awards, compressing project development timelines by 18-24 months when geological surveys precede licensing rounds. The Danish Energy Agency now requires digital twin reservoir modeling as a condition for drilling permits. District heating cooperatives in Zealand are responding by pre-qualifying engineering partners before formal tender issuance.
Municipal procurement is consolidating around 20-25 year concession contracts with guaranteed thermal offtake floors, replacing earlier short-term pilot agreements. This compresses developer risk premiums but requires utilities to lock in long-term supply commitments before reservoir confirmation. Odense and Aalborg municipalities are pioneering this structure, with smaller Jutland cities now adopting similar templates.
Denmark Geothermal Energy Market Segmentation
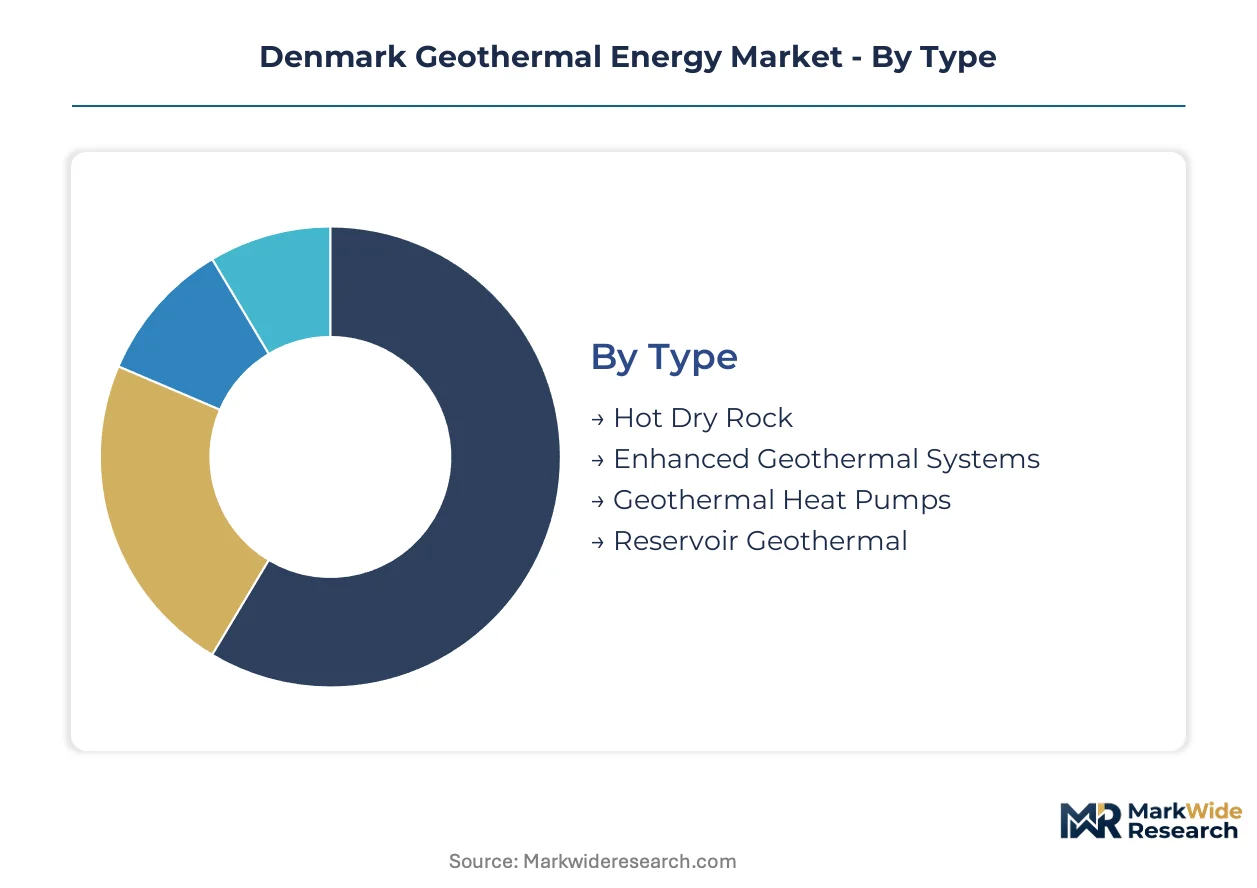
Segmentation reveals how Denmark's geothermal market stratifies across extraction depth, conversion technology, and customer contracting structures. Each dimension carries distinct capital requirements and regulatory exposure that shape project feasibility in Zealand sedimentary basins and Jutland limestone formations.
Type:
Buyer differentiation in this category centers on reservoir depth tolerance and risk appetite for geological uncertainty.
- Reservoir Geothermal:Conventional doublet systems extract brine from permeable aquifers at 1-3 kilometer depths using natural groundwater circulation. Copenhagen and Aarhus municipal utilities concentrate procurement here, drawn by proven flow rates in limestone formations that de-risk long-term offtake contracts.
- Enhanced Geothermal Systems:Hydraulic stimulation protocols fracture tight formations to create artificial permeability networks. These projects attract specialized developers testing Jutland structures previously deemed marginal, though higher capital intensity and regulatory scrutiny constrain municipal participation.
- Hot Dry Rock:Closed-loop configurations circulate working fluid through engineered borehole heat exchangers without reservoir fluid extraction. Pilot installations in Aarhus target impermeable crystalline basement where traditional doublets failed.
- Geothermal Heat Pumps:Shallow systems draw thermal energy from 100-400 meter depths for distributed building-scale heating. Danfoss A/S and equipment manufacturers serve residential and commercial customers outside district heating network coverage.
Reservoir geothermal leads volumes today; enhanced geothermal systems are gaining share fastest.
Technology:
Technology selection locks in plant efficiency and maintenance profiles across Denmark's low-to-moderate temperature resource base.
- Binary Cycle:Organic Rankine cycle systems transfer heat from geothermal brine to a secondary working fluid with lower boiling points. These dominate new Danish installations because 40-120°C reservoir temperatures suit binary conversion rather than flash configurations.
- Flash Steam:Direct vaporization of high-temperature brine drives turbine generators. Deployment remains minimal in Denmark given reservoir temperature ceilings, though future deep drilling in North Zealand sedimentary troughs could expand applicability.
- Dry Steam:Rare configurations utilizing naturally occurring steam reservoirs. No commercial Danish projects employ this technology given the country's sedimentary geology.
- Combined Heat and Power:Cogeneration plants extract electricity before cascading waste heat to district heating networks. Lower thermal efficiency in Danish temperature ranges limits adoption compared to pure heat service models.
Binary cycle systems anchor current deployment; combined heat and power holds expansion potential if reservoir temperatures rise with deeper drilling.
Application:
Application segmentation tracks heat offtake patterns and seasonal demand profiles that determine project economics.
- District Heating:Centralized networks distribute geothermal heat through insulated pipe systems serving multiple buildings. Zealand municipalities including Copenhagen, Roskilde, and Kalundborg anchor procurement volume through 20-25 year concession contracts with guaranteed thermal floors.
- Industrial Heating:Direct process heat supply to manufacturing facilities. Food processing plants in North Zealand and pharmaceutical operations near Copenhagen represent emerging offtake segments beyond municipal utilities.
- Agriculture:Greenhouse heating and soil warming applications. Danish horticulture clusters in West Zealand and Lolland-Falster utilize lower-temperature resources for season extension.
- Spa Applications:Balneotherapy and wellness facility heating. Limited commercial significance relative to district heating scale, concentrated in traditional thermal spring localities.
District heating commands installed capacity; industrial heating is expanding most quickly as manufacturing decarbonization pressures intensify.
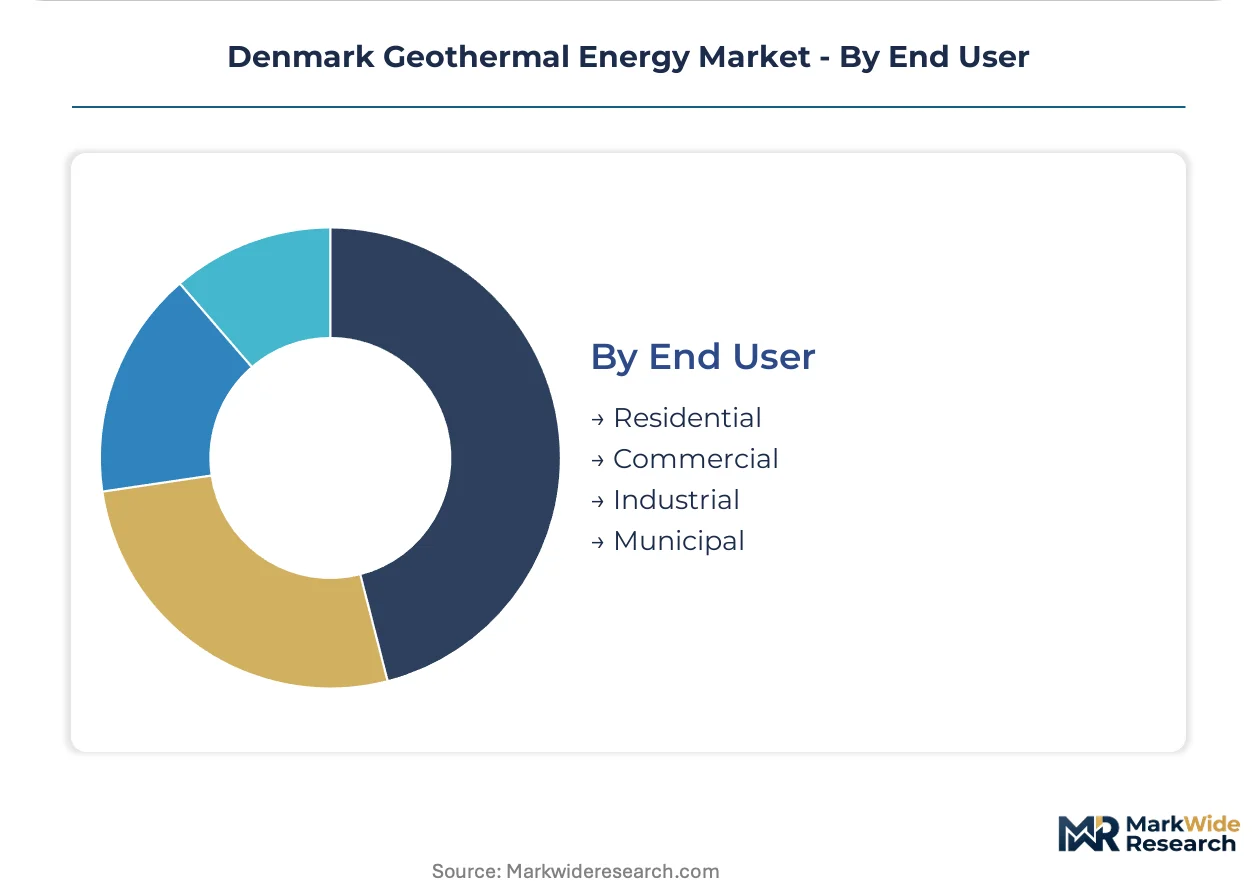
End User:
End user categories reflect contracting sophistication and balance sheet capacity for long-term capital commitment.
- Municipal:City-owned utilities and district heating cooperatives with concession authority under Denmark's Heat Supply Act. These entities capture the most stable margin pools through guaranteed offtake structures, though they face fossil-free heating mandates by 2030 that compress project timelines.
- Industrial:Manufacturing and processing facilities with continuous thermal demand profiles. North Zealand food and pharmaceutical clusters offer higher load factors than seasonal municipal heating, improving project IRRs.
- Commercial:Office buildings, retail complexes, and hospitality facilities. Smaller scale and fragmented ownership limit direct geothermal access outside district heating network coverage.
- Residential:Individual homeowners and housing cooperatives. Shallow heat pump installations serve this segment; deep geothermal remains economically inaccessible at single-building scale.
Municipal end users dominate contract value; industrial offtake is climbing the fastest as manufacturing facilities bypass utility intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's deep geothermal capacity exceeds Denmark's installed base by a factor of four, yet Danish sedimentary basin geology offers superior reservoir predictability for binary cycle deployment. The Nordic geothermal corridor is consolidating around shared drilling expertise and district heating infrastructure standards.
Zealand Region
Copenhagen and Roskilde municipal utilities drive procurement volume through 20-25 year concession contracts targeting limestone aquifers at 1.5-2.5 kilometer depths. The Danish Energy Agency's Subsoil Act licensing rounds prioritize this region's mapped sedimentary structures. Kalundborg's industrial cluster is piloting direct process heat supply to pharmaceutical manufacturing facilities.
Central Denmark Region
Aarhus anchors the country's deepest geothermal ambitions with doublet systems penetrating 3-kilometer reservoirs in the Aarhus Bay sedimentary trough. The municipality's heat planning mandate under Denmark's Climate Agreement accelerates drilling timelines. Local district heating cooperatives are testing closed-loop configurations in marginal concession blocks.
North Denmark Region
Aalborg's cement and chemical industries generate continuous thermal demand profiles that improve project economics against seasonal municipal heating. The region's tight limestone formations attract enhanced geothermal system pilots using hydraulic stimulation. Smaller Jutland cities are adopting Aalborg's long-term concession contract templates.
Southern Denmark Region
Odense municipal utility leads procurement innovation with guaranteed thermal offtake floors that compress developer risk premiums. The city's sedimentary basin access rivals Copenhagen's reservoir quality at lower land acquisition costs. Food processing clusters in North Funen are emerging as industrial heat offtake segments.
The region's geothermal potential remains undermapped relative to Zealand, creating first-mover advantages for developers securing early concession awards.
Denmark Geothermal Energy Market Competitive Environment
Top-tier vendors anchor deep drilling and reservoir engineering capabilities, while mid-tier specialists concentrate on distributed heat pump manufacturing and municipal advisory services. The market structures around three strategic archetypes: concession holders with exclusive sedimentary basin access, equipment fabricators leveraging industrial scale, and engineering consultancies capturing advisory fees across multiple projects. Competitive moves center on pre-qualification partnerships with district heating cooperatives and vertical integration into drilling asset ownership.
Among Denmark-based developers, Innargi A/S and Danfoss A/S occupy distinct tier positions that exemplify the market's bifurcation between premium deep geothermal and distributed heat pump segments. Ramboll Group A/S represents the advisory-centric archetype, capturing engineering margins across concession portfolios without direct reservoir risk exposure.
| Leading Market Players |
|---|
| Innargi A/S |
| Danfoss A/S |
| Ramboll Group A/S |
| Welltec A/S |
| NIRAS A/S |
| A.P. Møller Holding A/S |
| Geothermal Operations Company |
| Gate 21 |
| MAN Energy Solutions |
| Others |
Value Chain & Pricing Dynamics
Drilling rig day rates in North Sea markets cascade through project economics to shape long-term offtake contract pricing tiers for Danish municipal utilities. Steel casing and cementing costs feed directly into developer bidding strategies, with sedimentary basin access premiums separating concession winners from marginal bidders in Zealand licensing rounds.
Pricing Analysis
Capacity additions in Norwegian offshore drilling markets are reshaping price floors for deep doublet installations across Denmark's geothermal sector. Project-based long-term offtake contracts dominate municipal procurement, with price differentiation driven by reservoir confirmation status and guaranteed thermal floor commitments. Pricing pressure stems from geological uncertainty risk premiums that developers embed in pre-drilling bids. Municipal utilities exhibit lowest price sensitivity due to fossil-free heating mandates, while industrial offtake segments negotiate harder on unit thermal costs.
Supply Chain Analysis
Regional distribution centers in Hamburg and Rotterdam anchor hub-and-spoke patterns for specialized geothermal drilling equipment serving Danish concession zones. Manufacturing concentrates in Germany, the Netherlands, and Norway for high-pressure pumps and binary cycle turbines. Supply chains draw from nickel alloy forgings, precision heat exchangers, and directional drilling telemetry systems. Single-source vulnerability runs through European Union carbon border adjustment exposure on steel imports. Distribution runs through district heating cooperative procurement consortia that aggregate demand across multiple municipalities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Denmark's geothermal market offers margin expansion through reservoir engineering specialization premiums and long-term concession contract structures that lock in stable offtake. Cost compression in drilling automation technologies reinforces this trajectory.
For Market Incumbents: Anticipate enhanced geothermal system pilots in Jutland tight limestone formations as the primary competitive threat from specialized developers. Secure sedimentary basin access through early geological survey investments before Danish Energy Agency licensing rounds. Deepen backward integration into drilling asset ownership to control rig availability and compress project timelines. For New Entrants and Emerging Players: Direct-to-municipality digital procurement platforms offer lower-friction entry than traditional concession bidding channels. Target North Zealand industrial process heat segments where pharmaceutical and food manufacturing facilities bypass utility intermediaries. Lead with reservoir characterization software subscriptions that pre-qualify engineering partnerships before formal tender issuance. For Investors and Strategic Acquirers: Consolidation pressure builds where reservoir engineering consultancies lack captive drilling assets to capture full project value chains. Five-to-ten year viability hinges on Heat Supply Act amendments opening municipal networks to private concession holders. Watch for Danish Energy Agency digital twin modeling mandates as inflection indicators for engineering software acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Reservoir Confirmation Drilling | De-risks long-term offtake contracts for Copenhagen and Aarhus municipal utilities. |
| Binary Cycle Technology Licensing | Enables organic Rankine system deployment across Zealand sedimentary basin concessions. |
| District Heating Network Integration | Connects deep geothermal doublets to Copenhagen's fossil-free heating infrastructure backbone. |
| Enhanced Geothermal System Piloting | Unlocks marginal Jutland limestone formations through hydraulic stimulation protocols. |
| Industrial Process Heat Partnership | Captures North Zealand pharmaceutical manufacturing demand beyond municipal utility channels. |
Study Parameters
Coverage spans Zealand, Central Denmark, North Denmark, and Southern Denmark regions, with primary inputs from each. The analysis combines structured interviews with utility planning officers, geothermal project developers, EPC contractors, and district heating cooperative managers with secondary validation against Danish Energy Agency licensing databases, Subsoil Act regulatory filings, and European geothermal project development registries. Bottom-up project pipeline aggregation triangulates against top-down market sizing from sedimentary basin capacity assessments.
Rate-of-change decomposition across the analysis window separates volume growth from price evolution in binary cycle system deployment. The modeling framework segments by extraction depth tier, conversion technology type, application end-use, and end-user contracting structure. CAGRs derive from project commissioning timelines and concession award patterns. Forecast inputs incorporate Danish Climate Agreement fossil-free heating mandate compliance schedules and Heat Supply Act revision scenarios.
The model assumes a particular technology adoption path; alternative pathways for closed-loop geothermal systems would alter the outlook for traditional doublet configurations. Forecasts reflect stated assumptions on reservoir permeability confirmation rates and municipal procurement consolidation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geothermal Energy
Indonesia Geothermal Energy Market
Geothermal Energy
Netherlands Geothermal Energy Market
Geothermal Energy
Geothermal Power Generation Market
Geothermal Energy
US Geothermal Heat Pump Market
Geothermal Energy
Geothermal Power Infrastructure and Components Market
Geothermal Energy
Sweden Geothermal Energy Market
Geothermal Energy
United Kingdom Geothermal Energy Market
Geothermal Energy
Hungary Geothermal Energy Market
Geothermal Energy
Geothermal Energy Market
Geothermal Energy
Geothermal Power Infrastructure Market
Geothermal Energy
Philippines Geothermal Energy Market
Geothermal Energy
Asia-Pacific Geothermal Energy Market
Geothermal Energy
Enhanced Geothermal System Market
Geothermal Energy
Geothermal Power Market
Geothermal Energy
Global Geothermal Heat Pumps Market