
 Enhanced Geothermal System Market | 2026-2036
Enhanced Geothermal System Market Size, Share, and Industry Trends Forecast 2026-2036
Enhanced Geothermal System Market Foresight
High-temperature reservoir specifications above 150°C is redrawing investment thresholds across the Enhanced Geothermal System landscape. Ormat Technologies leverages its decades of binary cycle plant deployment to anchor utility-scale project development in established volcanic zones. Fervo Energy specializes in horizontal drilling techniques adapted from shale basins, while Eavor Technologies controls closed-loop architecture that eliminates reservoir fracking requirements entirely.
An enhanced geothermal system extracts heat from deep subsurface rock formations through engineered permeability, typically operating at depths of 3 to 10 kilometers where temperatures exceed hydrothermal resource thresholds. Electricity generation applications dominate commercial deployment, though direct use heating for district networks represents a concentrated margin pool in Nordic and Western European installations. Hydraulic stimulation technology leads current capacity additions, yet reservoir creation methods are capturing accelerated capital as developers target crystalline basement formations previously considered uneconomic.
The US IRA production tax credit and accelerated depreciation schedules shape American project finance structures, while EU Green Deal funding mechanisms and national renewable auction designs determine European deployment timelines. Japan's METI feed-in tariff framework and exploration subsidy programs sustain regional trial activity. Stakeholders must monitor permitting velocity for deep drilling operations and evolving seismicity protocols as projects scale beyond demonstration phase.
Market Dynamics
Horizontal drilling adaptations from shale basins are compressing development timelines for deep crystalline formations, while production tax credit extensions restructure project finance assumptions for utility-scale deployments.
Growth Catalysts
- US IRA Production Tax Credits:The Inflation Reduction Act's extended 30% investment credit and accelerated depreciation schedules de-risk capital deployment for deep drilling operations in Nevada and Utah.
- Hot Dry Rock Engineering:Reservoir creation technologies targeting crystalline basement formations at 4-7 kilometer depths unlock geothermal resources previously excluded from economic viability assessments.
- Baseload Power Procurement:Grid operators facing renewable intermittency constraints prioritize firm capacity contracts, directing utility RFPs toward geothermal's 90%+ capacity factor performance.
Market Restraints
- Steel Alloy Input Volatility:Corrosion-resistant tubing and drill string components face price pressure from nickel and molybdenum supply concentration in Indonesian and Russian export channels.
- Seismicity Protocol Uncertainty:State-level induced seismicity thresholds in California and Nevada lack federal harmonization, extending permitting timelines for hydraulic stimulation phases.
- Lithium-Ion Storage Substitution:Four-hour battery installations paired with solar PV capture peak pricing hours, compressing geothermal's merchant revenue capture in deregulated Texas and California markets.
Strategic Opportunities
- EU Green Deal Funding:The European Commission's Innovation Fund and national renewable auctions in Germany and France allocate dedicated envelopes for deep geothermal demonstration projects.
- District Heating Retrofit:Nordic municipal networks in Finland and Sweden seek baseload heat sources to displace natural gas boilers in 50+ year infrastructure cycles.
- Closed-Loop Architecture:Eavor's radiative heat exchanger design eliminates reservoir permeability requirements entirely, opening sedimentary basins in Poland and the Netherlands previously dismissed for geothermal development.
Industry Challenges
- Deep Drilling Talent Scarcity:Petroleum engineering graduates migrate toward carbon capture and hydrogen projects, constraining specialist availability for directional drilling in high-temperature crystalline formations.
- Reservoir Characterization Timelines:Extended flow testing and microseismic monitoring phases stretch development schedules, delaying revenue recognition and complicating project finance covenant structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enhanced Geothermal System Market |
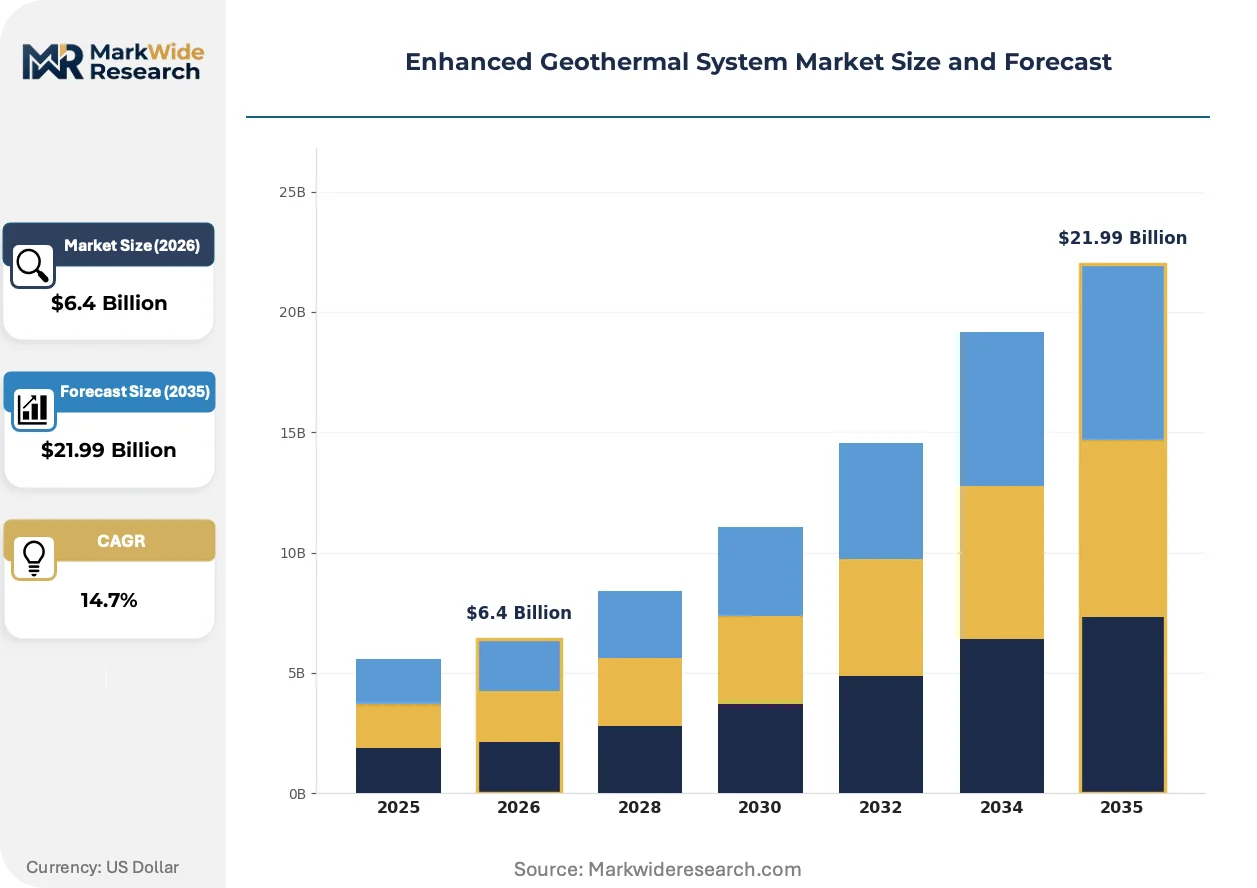
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $21.99 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydraulic Stimulation, Hot Dry Rock, Enhanced Oil Recovery, Reservoir Creation Application: Electricity Generation, Direct Use Heating, Ground Source Heat Pumps, Industrial Process Heating End User: Utilities, Commercial Buildings, Residential Buildings, Industrial Facilities Installation: Onshore, Offshore, Retrofit, New Construction |
| Companies Covered | Ormat Technologies, AltaRock Energy, Enel SpA, Calpine Corporation, Fuji Electric, Mitsubishi Heavy Industries, Fervo Energy, Eavor Technologies, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enhanced Geothermal System Market Shifts & Advancements
Binary cycle plant configurations and closed-loop architectures are redefining deployable resource temperatures, while regulatory frameworks scramble to accommodate induced seismicity monitoring protocols for scaled operations.
Closed-loop geothermal systems circulate working fluid through sealed wellbore networks without reservoir contact, eliminating hydraulic stimulation and induced seismicity risks entirely. European district heating operators in the Netherlands and Germany pilot these installations for urban deployment where population density constrains conventional approaches. This architecture is displacing open-loop designs in sensitive geological settings and accelerating permitting velocity in jurisdictions with strict groundwater protection statutes.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon working fluids forces binary plant operators to evaluate ammonia, hydrocarbon, and transcritical CO2 alternatives. Equipment manufacturers redesign heat exchanger configurations and pressure vessel ratings to accommodate lower-GWP refrigerants with altered thermodynamic properties. Off-the-shelf organic Rankine cycle packages face obsolescence pressure, driving custom engineering contracts for next-generation plant specifications.
Utility procurement departments now structure 20-25 year power purchase agreements with escalating escalation clauses rather than merchant exposure, transferring resource performance risk to developers. Independent power producers respond by bunding exploration insurance and drilling warranty products to secure project finance. This contractual evolution concentrates most visibly in ERCOT and CAISO jurisdictions where merchant price volatility has exceeded 300% intra-day swings during renewable ramp events.
Enhanced Geothermal System Market Segmentation
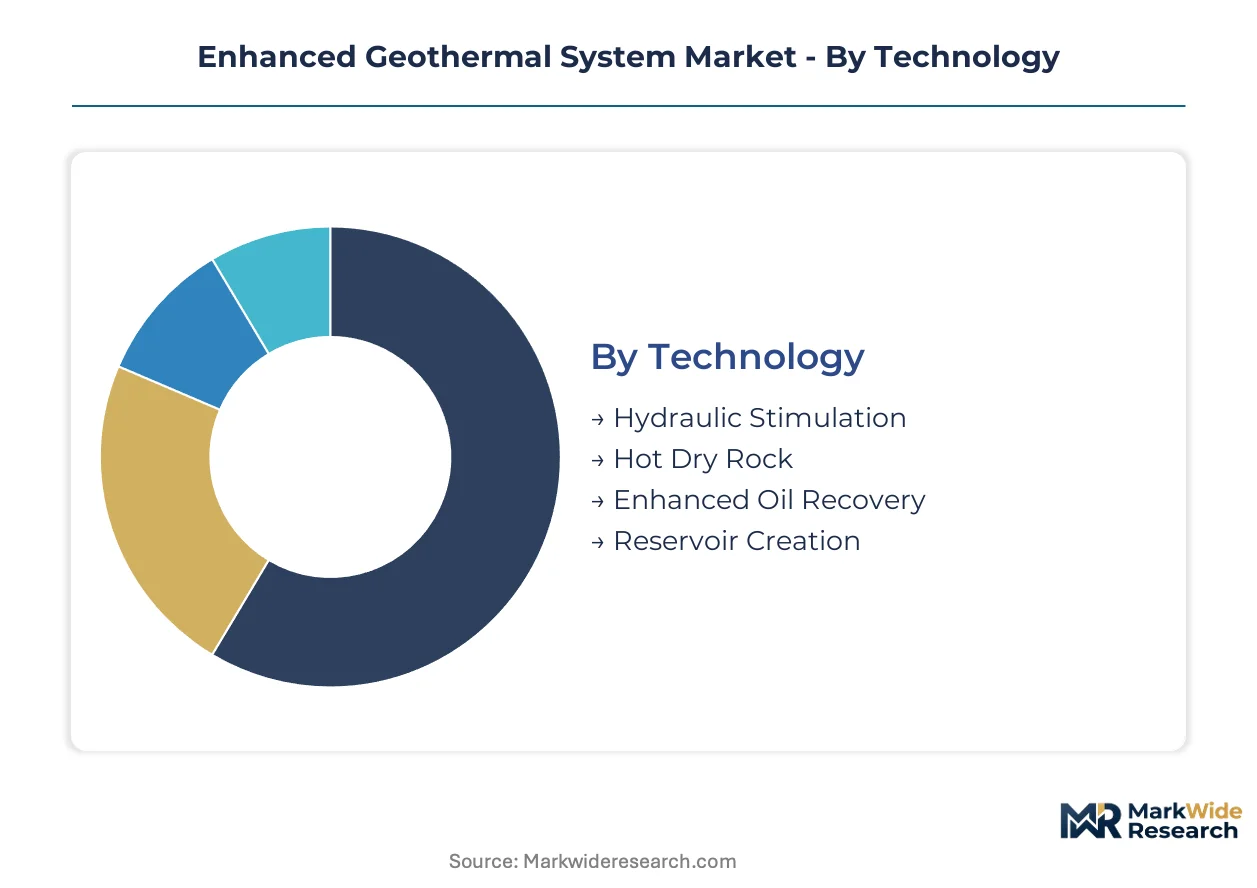
Technology choices in enhanced geothermal systems determine regulatory pathways, permitting timelines, and capital structure. Application segments diverge sharply on grid integration requirements versus thermal load profiles. End user categories and installation modes complete the segmentation matrix by defining project scale and site constraints.
Technology:
Regulatory frameworks distinguish hydraulic stimulation from closed-loop alternatives through induced seismicity protocols and groundwater protection statutes.
- Hydraulic Stimulation:Pressurized fluid injection creates fracture networks in crystalline basement formations to establish permeability. Nevada and Utah developers deploy this method for utility-scale power contracts, though state-level seismicity thresholds extend permitting timelines.
- Hot Dry Rock:Engineered reservoirs target high-temperature crystalline formations at 4-7 kilometer depths without natural hydrothermal circulation. Iceland's national energy company and Japanese METI-subsidized pilots concentrate demonstration activity where volcanic heat flux supports economic viability.
- Enhanced Oil Recovery:Co-produced geothermal fluids from petroleum reservoirs generate electricity or direct heat. Texas and California operators leverage existing wellbore infrastructure to reduce capital intensity.
- Reservoir Creation:Systematic fracturing and thermal cycling establish artificial hydrothermal systems in previously impermeable rock. European Innovation Fund recipients in Germany and France advance this approach for deep sedimentary basins.
Hydraulic stimulation handles the majority of throughput; reservoir creation is expanding most quickly on share.
Application:
Cost tiers separate grid-connected generation from distributed thermal applications through equipment scale and interconnection requirements.
- Electricity Generation:Binary cycle and flash steam plants convert reservoir heat to grid power with 90%+ capacity factors. ERCOT and CAISO utilities procure this baseload capacity under 20-25 year power purchase agreements with escalating clauses.
- Direct Use Heating:District networks in Finland and Sweden substitute geothermal for natural gas boilers in 50+ year infrastructure cycles. Nordic municipal operators prioritize this segment for decarbonization mandates under EU Green Deal funding.
- Ground Source Heat Pumps:Shallow closed-loop systems serve building-scale heating and cooling loads. Netherlands and Polish developers deploy these in urban settings where deep drilling faces population density constraints.
- Industrial Process Heating:Direct thermal integration serves cement, pulp, and food processing facilities. German industrial clusters seek this application to displace natural gas under national carbon pricing mechanisms.
Electricity generation commands the premium cost tier; direct use heating offers the steepest expansion trajectory in European markets.
End User:
Customer type determines project finance structures, with utilities accessing tax-advantaged capital and commercial developers facing merchant price exposure.
- Utilities:Vertically integrated power companies procure utility-scale installations under regulated cost-recovery or competitive RFP processes. US IRA production tax credits and accelerated depreciation reshape their capital deployment assumptions.
- Commercial Buildings:Office and retail developers install ground-source heat pumps for LEED certification and operational cost reduction. Netherlands urban pilots concentrate in Rotterdam and Amsterdam districts.
- Residential Buildings:Single-family and multi-family housing deploys shallow closed-loop systems. German KfW development bank subsidies support this segment under national building efficiency programs.
- Industrial Facilities:Energy-intensive manufacturers seek process heat and power cogeneration. Iceland's aluminum smelters and Hungary's chemical complexes anchor this demand category.
Utilities dominate installed capacity; industrial facilities are climbing the fastest on share as carbon border adjustments tighten.
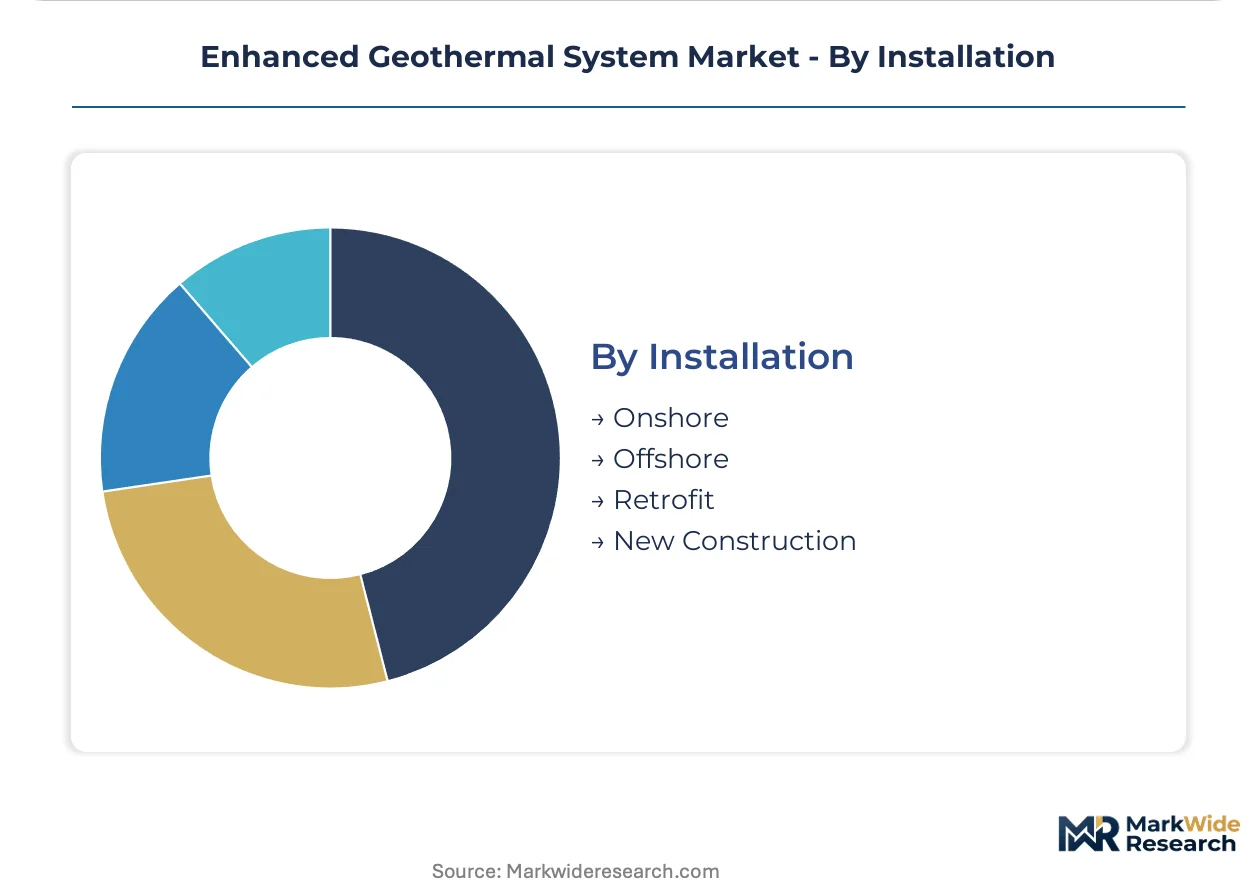
Installation:
Site maturity distinguishes greenfield drilling programs from brownfield retrofits through subsurface risk profiles and development timelines.
- Onshore:Terrestrial drilling targets volcanic zones, sedimentary basins, and crystalline shields. Nevada, Utah, and Iceland host the majority of active development.
- Offshore:Submarine geothermal resources remain pre-commercial, though Japan's METI funds exploratory drilling in coastal volcanic zones.
- Retrofit:Existing wellbore repurposing from oil and gas operations reduces capital intensity. Texas Permian Basin operators pilot this approach for co-produced geothermal power.
- New Construction:Greenfield sites enable optimized wellfield design and plant configuration. Greenfield developments concentrate in jurisdictions with streamlined permitting such as Utah.
Onshore installations carry the majority of throughput; retrofit projects are gaining share fastest where petroleum infrastructure exists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geothermal markets. US utilities negotiate aggressively on levelized cost thresholds under IRA tax credits. European district heating operators accept premium thermal pricing for decarbonization compliance. Japanese industrial buyers prioritize resource certainty over upfront capital minimization.
United States
Nevada and Utah host the most active project pipelines, driven by utility-scale baseload procurement from ERCOT and CAISO grid operators. The IRA's production tax credit extension and accelerated depreciation schedules reshape developer capital structures. Fervo Energy's horizontal drilling pilots in Utah's crystalline formations anchor technology demonstration activity.
Germany
Industrial process heat demand from Rhine-Ruhr chemical clusters and Bavarian manufacturing plants drives deep geothermal exploration. The EU Green Deal's Innovation Fund and national renewable auctions allocate dedicated envelopes for reservoir creation demonstrations. Munich's municipal utility pilots closed-loop systems for urban district heating retrofits.
Iceland
Aluminum smelters and data center operators anchor baseload power and direct heat demand in Reykjanes and Krafla volcanic zones. National energy company Landsvirkjun advances hot dry rock engineering at 4-7 kilometer depths without natural hydrothermal circulation. The Hellisheidi plant complex exemplifies utility-scale binary cycle deployment.
Japan
Industrial facilities in Kyushu and Tohoku seek geothermal cogeneration to displace imported LNG under national carbon neutrality targets. METI's feed-in tariff framework and exploration subsidy programs sustain regional trial activity. Japan's coastal volcanic zones host pre-commercial offshore drilling pilots funded by ministry programs.
Netherlands
Rotterdam and Amsterdam district heating networks pursue sedimentary basin geothermal to meet 2030 natural gas phaseout mandates. Closed-loop architecture gains traction where population density constrains conventional hydraulic stimulation. The EU F-Gas Regulation's hydrofluorocarbon phasedown forces working fluid substitution in binary plant designs.
Enhanced Geothermal System Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the enhanced geothermal system landscape. Established power plant operators leverage decades of binary cycle deployment experience for utility-scale project development. Horizontal drilling specialists adapted from shale basins compress development timelines for deep crystalline formations. The competitive arena shows moderate consolidation with tiered specialization rather than dominant integrated players. Strategic moves concentrate on reservoir creation technology licensing and closed-loop architecture partnerships to access sedimentary basin opportunities.
Among technology-integrated developers, Ormat Technologies, Fervo Energy, and Eavor Technologies occupy distinct positioning. Ormat Technologies anchors the established utility-scale segment through binary cycle plant deployment. Fervo Energy exemplifies the horizontal drilling adaptation archetype for crystalline basement formations. Eavor Technologies represents closed-loop system specialization that eliminates reservoir fracking requirements entirely.
| Leading Market Players |
|---|
| Ormat Technologies |
| AltaRock Energy |
| Enel SpA |
| Calpine Corporation |
| Fuji Electric |
| Mitsubishi Heavy Industries |
| Fervo Energy |
| Eavor Technologies |
| Baker Hughes |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation phasedown gates both binary plant working fluid qualification and price differentiation between ammonia-based and hydrocarbon-based system tiers. Developers face simultaneous supply chain requalification and pricing power compression as low-GWP refrigerant conversions reshape cost structures.
Pricing Analysis
Extended service contracts and reservoir performance warranties now drive lifetime value capture for EPC providers. Project-based pricing dominates utility-scale deployments, with differentiation anchored in drilling depth capability and binary cycle efficiency ratings. Cost compression in standard-depth crystalline formations intensifies as horizontal drilling techniques commoditize. Independent power producers exhibit highest price sensitivity due to merchant exposure, while municipal utilities under regulated cost-recovery frameworks accept premium thermal pricing.
Supply Chain Analysis
Strait of Malacca transit underwrites corrosion-resistant alloy delivery timelines for drill string and tubing manufacturers. Nickel and molybdenum supply concentrates in Indonesian mining operations and Russian export channels, with steel alloy fabrication anchored in German and Japanese specialty mills. Single-source vulnerability runs through high-temperature cement and directional drilling electronics. Distribution feeds from EPC contractors to utility procurement departments through long-term offtake frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reservoir performance guarantees and extended O&M service layers expand faster than hardware sales as developers bundle risk-transfer mechanisms. This service-attach dynamic restructures margin pools toward recurring revenue streams.
For Market Incumbents: Consolidate drilling service capabilities through captive supply of high-temperature directional equipment, insulating against petroleum engineering talent migration toward carbon capture projects. Deepen backward integration into nickel alloy supply through offtake agreements with Indonesian mining operations. Lock in utility-scale capacity additions in Nevada and Utah before IRA production tax credit windows compress. For New Entrants and Emerging Players: Differentiate on closed-loop architecture deployment for European district heating networks where hydraulic stimulation faces population density constraints. Target sedimentary basin opportunities in Poland and the Netherlands previously dismissed for conventional geothermal. Pursue technology licensing partnerships with municipal utilities seeking natural gas displacement under EU Green Deal funding. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across closed-loop system deployments as standardized radiative heat exchanger designs reduce custom engineering requirements. Acquisition targets should display reservoir creation technology portfolios or hot dry rock engineering capabilities in volcanic zones. Monitor permitting velocity in California and Nevada as inflection indicator for hydraulic stimulation scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Structuring | Twenty-five year offtake contracts with escalation clauses transfer resource performance risk to developers in ERCOT and CAISO markets. |
| Reservoir Creation Technology Licensing | Systematic fracturing IP unlocks deep sedimentary basin opportunities in Germany and France under EU Innovation Fund support. |
| Closed-Loop Architecture Partnership | Eavor-style radiative heat exchanger designs eliminate induced seismicity risks and accelerate urban permitting in Rotterdam and Amsterdam. |
| Backward Integration into Alloy Supply | Captive nickel and molybdenum sourcing insulates against Indonesian export concentration and Russian channel disruption. |
| Horizontal Drilling Capability Acquisition | Shale-adapted directional techniques compress development timelines for crystalline basement formations in Utah and Nevada. |
Research Methodology
Cross-validation between utility procurement officer interviews and FERC interconnection queue data anchors the qualitative findings. Primary fieldwork captured perspectives from EPC contractors, IPP project developers, grid operators in ERCOT and CAISO territories, and drilling service specialists. Secondary validation drew from EIA generation statistics, IEA geothermal technology roadmaps, EU Innovation Fund award disclosures, and METI exploration subsidy records. Bottom-up project pipeline aggregation triangulates against top-down regulatory incentive modeling.
Sensitivity analysis around IRA credit extension timelines and EU auction price floors shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, application segment, end user category, and installation mode, with regional regulatory framework as an additional cross-cutting variable. CAGRs derive from installed capacity buildout curves and levelized cost trajectory assumptions. Forecast inputs incorporate drilling cost learning rates and binary plant efficiency improvement curves.
Decision-makers should treat outputs as directional under sustained IRA production tax credit availability and EU Green Deal funding continuity; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as state-level seismicity protocols and F-Gas Regulation implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geothermal Energy
Philippines Geothermal Energy Market
Geothermal Energy
US Geothermal Heat Pump Market
Geothermal Energy
Geothermal Power Infrastructure and Components Market
Geothermal Energy
Asia-Pacific Geothermal Energy Market
Geothermal Energy
Indonesia Geothermal Energy Market
Geothermal Energy
Geothermal Power Infrastructure Market
Geothermal Energy
Netherlands Geothermal Energy Market
Geothermal Energy
United Kingdom Geothermal Energy Market
Geothermal Energy
Hungary Geothermal Energy Market
Geothermal Energy
Geothermal Power Generation Market
Geothermal Energy
Geothermal Energy Market
Geothermal Energy
Sweden Geothermal Energy Market
Geothermal Energy
Global Geothermal Heat Pumps Market
Geothermal Energy
Denmark Geothermal Energy Market
Geothermal Energy
Geothermal Power Market