
 Geothermal Power Infrastructure Market | 2026-2036
Geothermal Power Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Geothermal Power Infrastructure Market Foresight
Modular plant packaging is pivoting buyer choice in geothermal power infrastructure, as developers now procure pre-fabricated binary cycle skids rather than field-assembled flash steam complexes. Ormat Technologies leverages its vertical integration across turbine manufacturing and plant operations to dominate turnkey project delivery. Mitsubishi Heavy Industries anchors its position through specialized corrosion-resistant turbine designs for high-salinity brine fields. Calpine Corporation sustains operational leadership across its installed base in the western United States through proprietary reservoir management protocols.
Geothermal power infrastructure encompasses subsurface drilling systems, surface heat exchange networks, and electricity conversion plants designed to extract thermal energy from hydrothermal reservoirs or engineered hot dry rock formations, typically operating at brine temperatures between 150°C and 300°C for flash steam generation or below 150°C for binary organic Rankine cycles. Binary cycle systems occupy the fastest-expanding margin pool due to their applicability in lower-temperature reservoirs that dominate untapped global resources. Enhanced Geothermal Systems represent the technology segment with the steepest R&D trajectory, though hydrothermal installations still lead in installed capacity and near-term revenue. Utility companies constitute the most concentrated end-user channel, while independent power producers are gaining share through merchant plant development in deregulated electricity markets.
The US Federal Energy Regulatory Commission governs interconnection standards for geothermal plants, while EPA permitting requirements shape drilling wastewater management and emissions profiles. Indonesia's Ministry of Energy and Mineral Resources regulates resource concession allocation through its Geothermal Fund Facility, and Kenya's Energy and Petroleum Regulatory Authority sets feed-in tariffs that determine project bankability. Stakeholders must monitor how evolving carbon border mechanisms and domestic content requirements in key markets reshape equipment sourcing strategies and project development timelines.
Market Dynamics
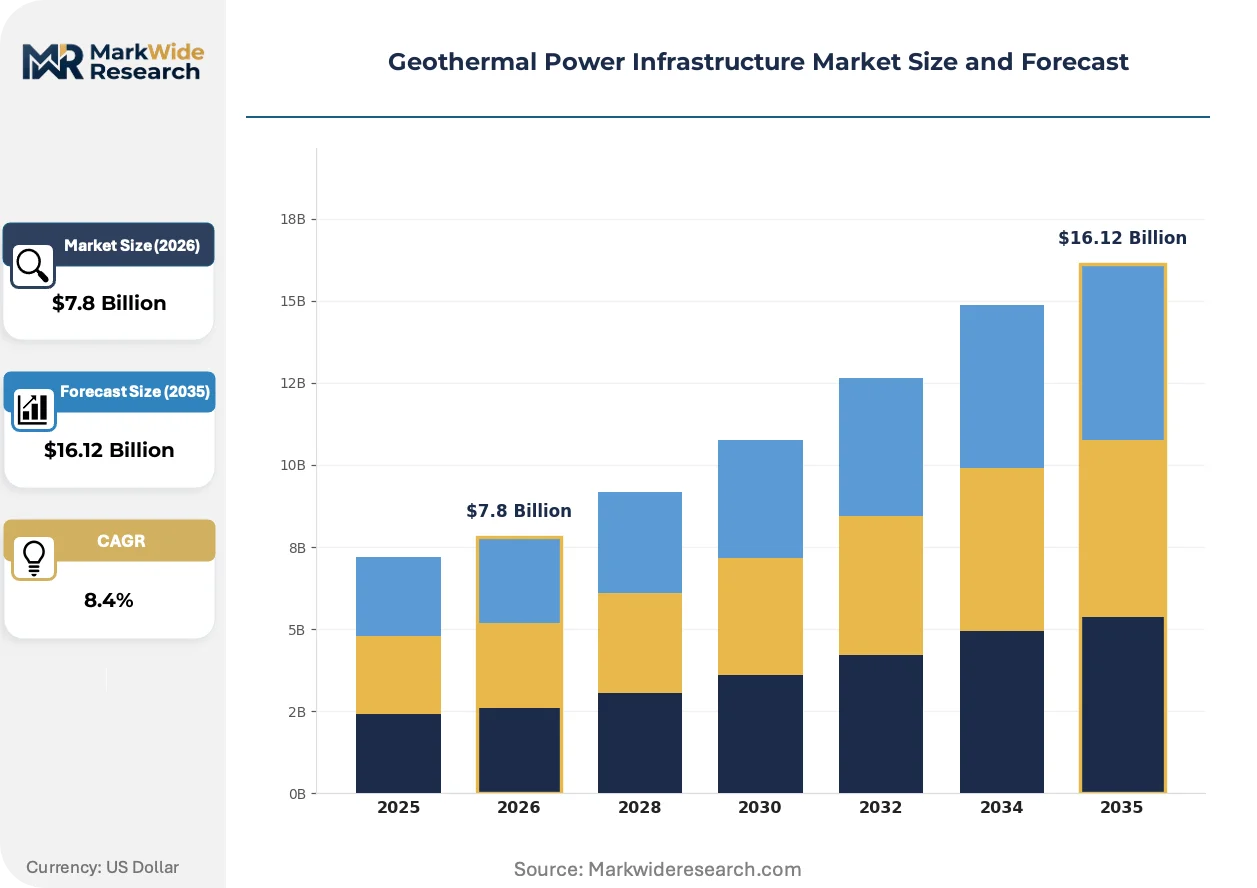
Modular plant packaging is compressing project development timelines and reshaping capital allocation across geothermal power infrastructure, as standardized binary cycle skids displace field-assembled flash steam complexes and reduce engineering procurement construction risk for developers.
Growth Catalysts
- US Inflation Reduction Act tax credits:Accelerated depreciation and production tax credits shorten drilling-to-generation timelines for utility-scale projects in volcanic zones.
- Binary cycle technology maturation:Organic Rankine cycle systems now unlock sub-150°C reservoirs that constitute the majority of untapped global geothermal resources.
- Indonesia Geothermal Fund Facility:The Ministry of Energy and Mineral Resources streamlines concession allocation and de-risks exploration drilling through public cost-sharing mechanisms.
Market Restraints
- Drilling cost volatility:Steel alloy prices and specialized rig availability constrain project economics, with deep wells in hot dry rock formations requiring precision directional drilling capabilities concentrated in limited contractor pools.
- Reservoir uncertainty:Subsurface permeability mapping remains probabilistic, forcing developers to absorb exploration risk before securing construction financing.
- Grid interconnection queues:FERC interconnection standards create multi-year backlogs for remote geothermal sites seeking transmission access in the western United States.
Strategic Opportunities
- East African Rift expansion:Kenya's feed-in tariff structure and Ethiopia's untapped Aluto-Langano field offer first-mover positioning for binary cycle developers targeting volcanic margin resources.
- Enhanced Geothermal Systems commercialization:Engineered reservoir creation through hydraulic stimulation and closed-loop designs is unifying subsurface engineering with oilfield service capabilities.
- Carbon border mechanism alignment:EU CBAM certification pathways for zero-emission baseload power create premium offtake contracts for geothermal electricity in European industrial decarbonization strategies.
Industry Challenges
- Reservoir engineering talent scarcity:Geothermal-specific subsurface modeling and brine chemistry expertise concentrates in legacy hydrothermal regions, constraining project staffing in emerging markets.
- Binary working fluid compliance:EPA permitting for isobutane and pentane handling adds operational complexity and safety protocol costs for organic Rankine cycle plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geothermal Power Infrastructure Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Infrastructure Type: Power Plant, Heat Exchanger, Wells, Binary Cycle Systems, Flash Steam Systems Technology: Enhanced Geothermal Systems, Hydrothermal, Direct Use, Geothermal Heat Pumps Application: Electricity Generation, District Heating, Agriculture Drying, Spa & Wellness, Industrial Process Heat End User: Independent Power Producers, Utility Companies, Industrial Manufacturers, Agricultural Enterprises |
| Companies Covered | Ormat Technologies, Calpine Corporation, Enel Green Power, Mitsubishi Heavy Industries, Tetra Tech Inc., Turboden S.p.A, Mannvit HF, Terra-Gen Power LLC, Fuji Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geothermal Power Infrastructure Market Shifts & Advancements
Technology convergence between oilfield services and renewable power generation is compressing development cycles and expanding addressable resource bases beyond traditional hydrothermal locations.
Closed-loop geothermal systems are eliminating subsurface water consumption and induced seismicity risks that have constrained conventional hydrothermal expansion. Oilfield service contractors are repurposing directional drilling and reservoir monitoring capabilities from shale operations toward hot dry rock development. This technical migration is unifying geothermal project delivery with established hydrocarbon supply chains, reducing capital intensity and accelerating deployment timelines.
Indonesia's Geothermal Fund Facility now mandates domestic content thresholds for drilling equipment and turbine components as a condition of concession awards. The policy is redirecting procurement patterns toward local manufacturing partnerships and joint ventures with international technology licensors. Developers are responding by establishing component assembly facilities in Java and Sulawesi to maintain concession eligibility.
Utility offtake agreements are fragmenting into shorter-term contracts with merchant price exposure as deregulated markets mature in the Philippines and Kenya. Independent power producers are absorbing wholesale price volatility in exchange for faster permitting and grid access. This contracting evolution is most visible in Luzon, where geothermal developers now balance baseload reliability premiums against spot market participation upside.
Geothermal Power Infrastructure Market Segmentation
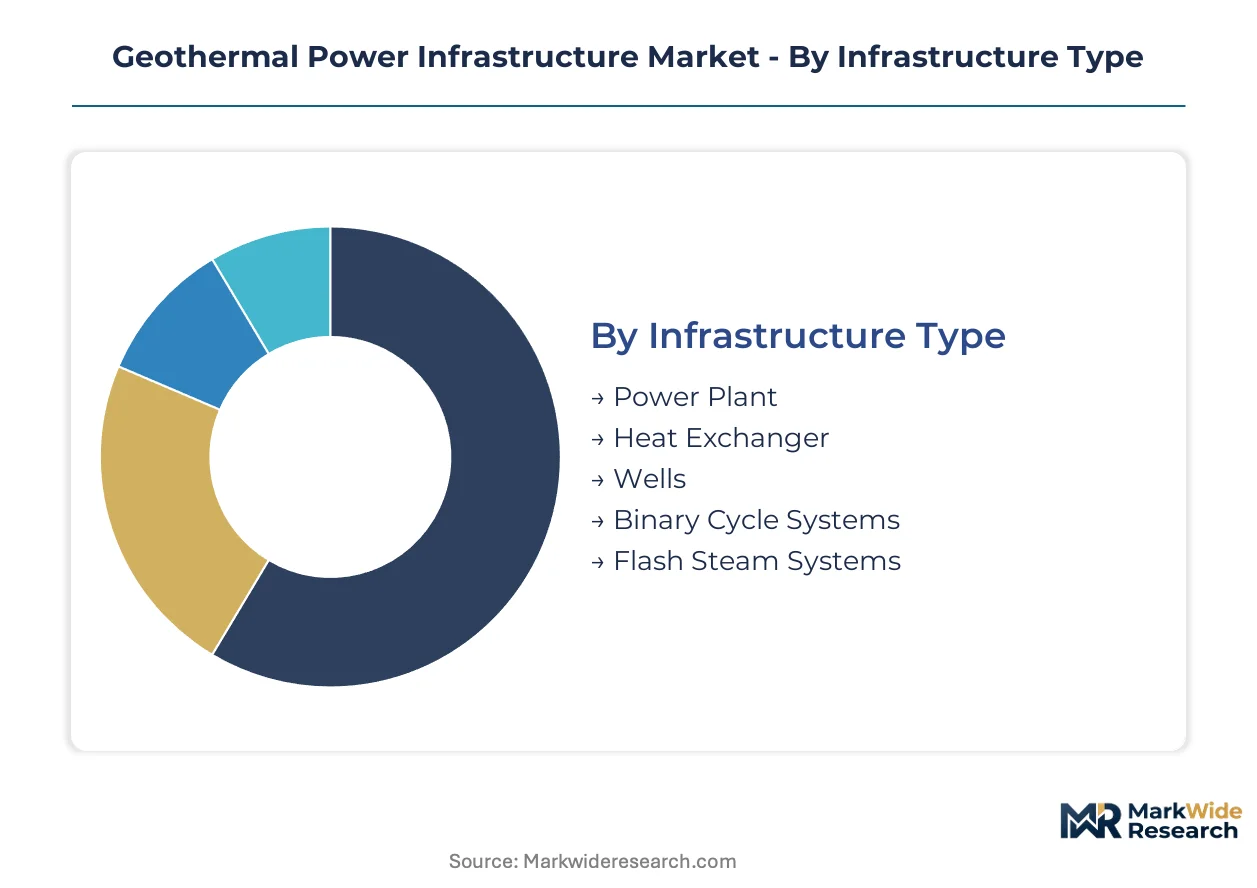
Geothermal power infrastructure segmentation reveals distinct procurement patterns between integrated plant developers and component specialists. Technology maturity and reservoir temperature profiles determine where buyers concentrate capital deployment across infrastructure categories.
Infrastructure Type:
Standalone power plants command the highest capital allocation, while heat exchangers and wells function as embedded subsystems within integrated project delivery.
- Power Plant:Surface electricity conversion facilities integrate turbines, generators, and control systems for grid-synchronized output. Utility companies in Indonesia and Kenya prioritize turnkey plant procurement under feed-in tariff structures. Binary cycle configurations dominate new orders due to lower temperature resource applicability.
- Binary Cycle Systems:Organic Rankine cycle skids extract energy from sub-150°C brine using isobutane or pentane working fluids. Developers across Ethiopia's Aluto-Langano field favor pre-fabricated modular packages that compress installation timelines. EPA permitting requirements for hydrocarbon handling shape operational protocol design.
- Heat Exchanger:Brine-to-working fluid thermal transfer equipment manufactured from corrosion-resistant alloys.
- Wells:Directional drilling infrastructure penetrating hydrothermal reservoirs or engineered hot dry rock formations.
- Flash Steam Systems:High-temperature separation plants for 150°C-300°C brine resources common in legacy volcanic zones.
Power plants lead volumes today; binary cycle systems are gaining share fastest.
Technology:
Cost tier differentiation separates mature hydrothermal deployment from capital-intensive engineered reservoir creation.
- Hydrothermal:Conventional extraction from naturally permeable water-bearing formations with proven subsurface characteristics. The Philippines and Indonesia anchor installed capacity through decades of reservoir characterization. Grid interconnection queues in the western United States constrain expansion timelines for new projects.
- Enhanced Geothermal Systems:Engineered reservoir creation through hydraulic stimulation and closed-loop circulation in hot dry rock formations. Oilfield service contractors from shale operations are repurposing directional drilling capabilities toward EGS development. FERC interconnection standards and induced seismicity monitoring requirements shape project permitting.
- Direct Use:Non-electric thermal extraction for district heating and industrial applications bypassing electricity conversion.
- Geothermal Heat Pumps:Building-scale ground-source climate systems operating at shallow drilling depths.
Hydrothermal dominates current capacity; enhanced geothermal systems carry the steepest R&D investment trajectory.
Application:
Customer type determines contract structure, with merchant generators accepting price volatility that baseload utilities refuse.
- Electricity Generation:Grid-connected baseload power production from utility-scale plants. Kenya's Energy and Petroleum Regulatory Authority feed-in tariffs secure long-term offtake for independent power producers. Shorter-term merchant contracts are fragmenting in Luzon as deregulated markets mature.
- Industrial Process Heat:Direct thermal integration with manufacturing operations requiring consistent temperature profiles. EU carbon border adjustment mechanisms create premium contract opportunities for zero-emission heat supply.
- District Heating:Centralized thermal distribution networks serving municipal building clusters.
- Agriculture Drying:Crop dehydration and greenhouse climate control using moderate-temperature brine.
- Spa & Wellness:Direct utilization of mineralized thermal springs for recreational and therapeutic facilities.
Electricity generation commands the largest capital deployment; industrial process heat is expanding most quickly under decarbonization mandates.
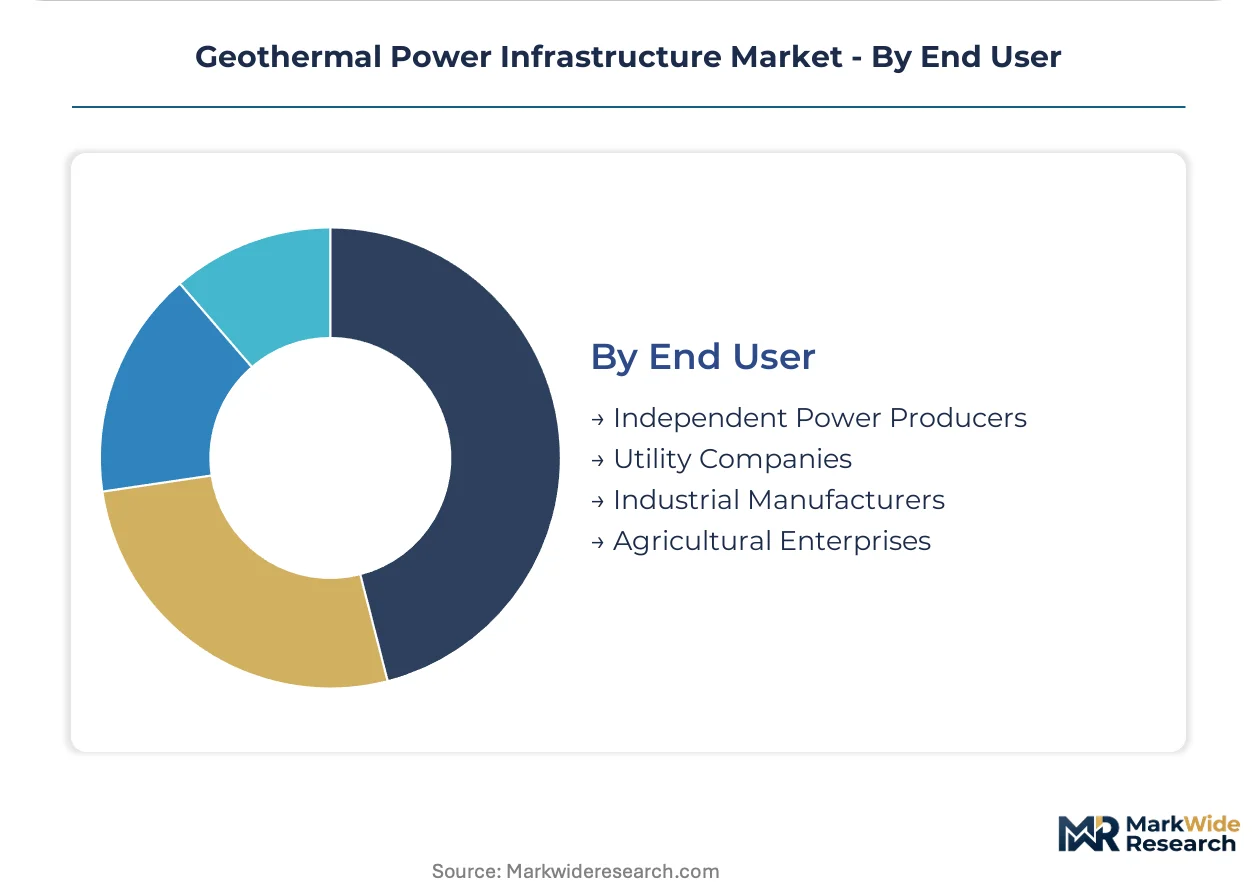
End User:
Supply concentration varies by procurement scale, with utilities demanding integrated solutions and industrial buyers sourcing discrete components.
- Utility Companies:Vertically integrated electricity distributors procuring baseload capacity through concession-based development. Indonesia's Geothermal Fund Facility mandates domestic content thresholds for drilling equipment and turbine components. Public cost-sharing mechanisms de-risk exploration drilling budgets.
- Independent Power Producers:Merchant developers absorbing wholesale price exposure for faster permitting and grid access. IPPs in the Philippines balance baseload reliability premiums against spot market participation upside. Binary cycle technology unlocks lower-temperature resources outside traditional utility development zones.
- Industrial Manufacturers:Process heat consumers negotiating direct thermal supply agreements.
- Agricultural Enterprises:Direct-use thermal applications for crop processing and controlled-environment agriculture.
Utility companies anchor procurement volumes today; independent power producers are capturing share fastest in deregulated markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Geothermal power infrastructure traces its commercial lineage to Italy's Larderello field, where Prince Piero Ginori Conti first generated electricity from steam in 1904, establishing the technical template that Philippine, Indonesian, and Kenyan utilities later scaled across volcanic zones.
United States
The Bureau of Land Management administers geothermal leasing on federal lands across Nevada, Utah, and California, where FERC interconnection queues currently backlog remote site approvals by three to four years. The Inflation Reduction Act's production tax credits compress drilling-to-generation timelines for developers in the Salton Sea and Snake River Plain. Calpine Corporation maintains operational leadership across its western installed base through proprietary reservoir management protocols.
Indonesia
State utility PLN procures baseload capacity from concession holders across Java, Sumatra, and Sulawesi, where volcanic arc geology supports high-temperature flash steam development. The Ministry of Energy and Mineral Resources mandates domestic content thresholds for drilling equipment and turbine components through its Geothermal Fund Facility. Developers have established component assembly partnerships in Surabaya and Makassar to maintain concession eligibility under local content rules.
Philippines
Independent power producers now absorb wholesale price exposure through shorter-term merchant contracts in Luzon, balancing baseload reliability premiums against spot market participation upside. The Energy Regulatory Commission oversees feed-in tariff structures that historically secured long-term offtake for utility-scale plants. Leyte and Negros Islands host concentrated binary cycle development targeting lower-temperature volcanic margin resources.
Kenya
The Energy and Petroleum Regulatory Authority sets feed-in tariffs that determine project bankability for developers in the Olkaria and Menengai fields along the East African Rift. KenGen and independent producers expand installed capacity through binary cycle systems suited to volcanic margin temperatures below 150°C. The Olkaria complex anchors East Africa's largest geothermal generation cluster, with transmission infrastructure extending to Nairobi's industrial demand centers.
Ethiopia
The Ethiopian Electric Power corporation partners with international developers to unlock the Aluto-Langano field's untapped resource base through pre-fabricated modular binary packages. The government's public-private partnership framework de-risks exploration drilling budgets for foreign capital participation. The Rift Valley corridor between Addis Ababa and Djibouti represents the continent's fastest-concentrating demand pocket for lower-temperature geothermal development.
Geothermal Power Infrastructure Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with turnkey project developers commanding pricing power over component fabricators. The vendor base stratifies between vertically integrated plant operators, specialized turbine manufacturers, and oilfield service contractors repurposing directional drilling capabilities. Three archetypes dominate: integrated energy companies with captive geothermal portfolios, industrial conglomerates with power generation divisions, and pure-play renewable developers. Competitive moves concentrate on strategic partnerships for concession access and technology licensing agreements for binary cycle system deployment.
Among vertically integrated specialists, Ormat Technologies exemplifies the turnkey project delivery archetype through its combined turbine manufacturing and plant operations capabilities. Mitsubishi Heavy Industries occupies a position within the industrial conglomerate tier, anchoring its market presence through specialized equipment designs for corrosive brine environments. Calpine Corporation represents the pure-play renewable developer model, sustaining operational leadership across its installed base through proprietary technical protocols rather than manufacturing integration.
| Leading Market Players |
|---|
| Ormat Technologies |
| Calpine Corporation |
| Enel Green Power |
| Mitsubishi Heavy Industries |
| Tetra Tech Inc. |
| Turboden S.p.A |
| Mannvit HF |
| Terra-Gen Power LLC |
| Fuji Electric |
| Others |
Supply & Pricing Matrix
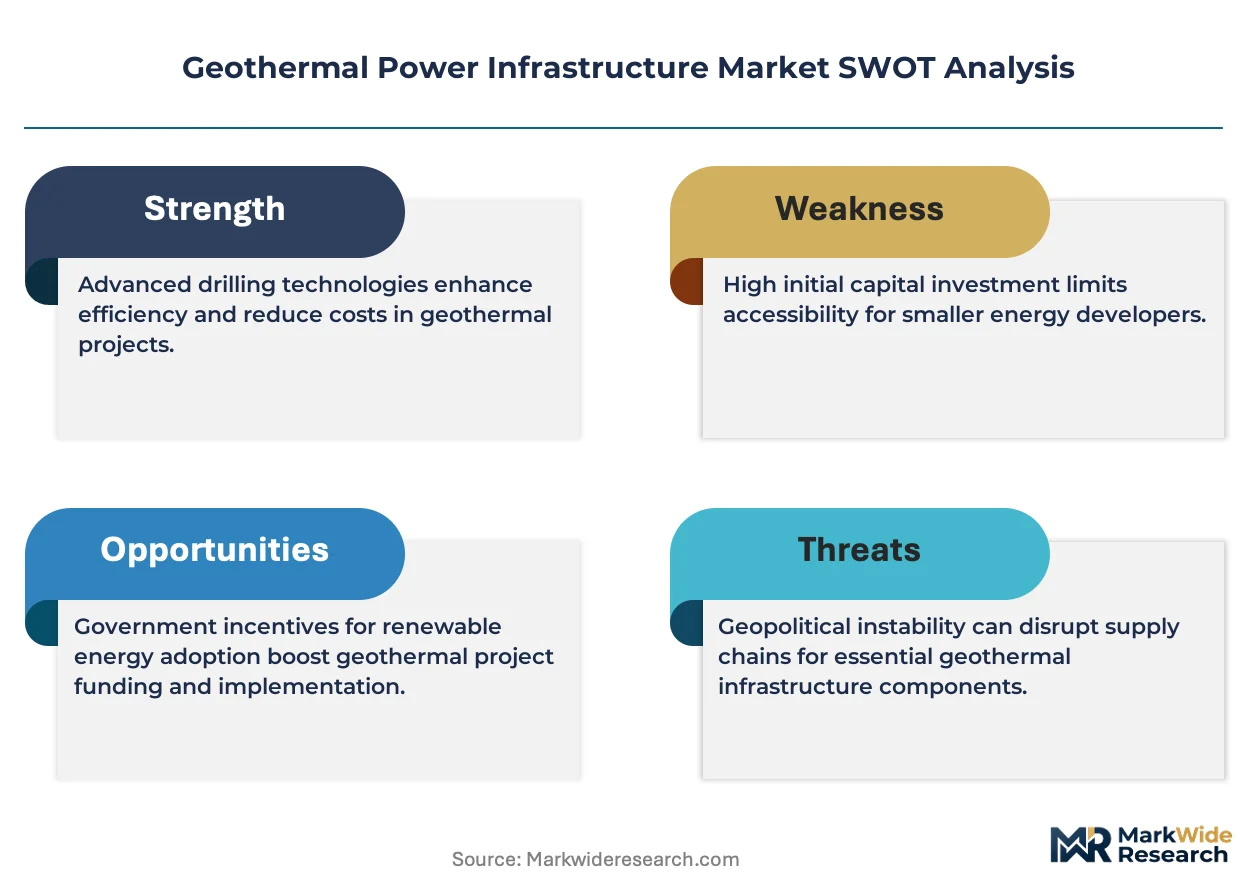
Modular binary cycle packaging simultaneously compresses capital costs and concentrates procurement leverage among pre-fabricated skid suppliers, forcing field-assembled flash steam developers to absorb margin erosion or surrender market share. This technology transition rewards vertically integrated plant operators with captive turbine manufacturing while squeezing independent component fabricators competing on unit economics.
Pricing Analysis
Turnkey project-based contracting dominates procurement, with developers purchasing integrated plant solutions rather than discrete equipment tiers. Price differentiation rests on reservoir temperature applicability and domestic content compliance thresholds. Cost compression in flash steam segments intensifies as binary cycle systems capture lower-temperature resource development. Independent power producers exhibit highest price sensitivity due to merchant market exposure, while utility companies under feed-in tariff structures prioritize reliability premiums over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with precision directional drilling contractors concentrated in the United States, Japan, and Germany. Turbine manufacturing draws from corrosion-resistant alloy suppliers in South Korea and specialized working fluid producers in the European Union. Tariff exposure on steel alloys and rare earth magnets creates margin volatility for component fabricators. Distribution runs through engineering-procurement-construction consortiums delivering integrated plant solutions to concession holders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as buyers shift procurement criteria toward reservoir certainty and operational uptime guarantees rather than lowest capital cost. Premium specifications for corrosion-resistant turbines and modular binary packages command pricing power.
For Market Incumbents: Hedge against binary cycle commoditization by locking exclusive concession partnerships in Indonesia and Kenya before domestic content rules harden. Deepen backward integration into precision drilling capabilities to capture exploration risk premiums that independent contractors currently extract. Prioritize proprietary reservoir management protocols as a service layer above hardware sales. For New Entrants and Emerging Players: Begin with Ethiopia's Aluto-Langano field and the Philippine volcanic margins, where first-mover positioning in sub-150°C binary development remains penetrable. Target independent power producer segments in Luzon accepting merchant price exposure for faster permitting. Pursue joint venture structures with established oilfield service contractors repurposing shale drilling capabilities toward hot dry rock applications. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play renewable developers lacking captive manufacturing, presenting acquisition targets with operational expertise but procurement cost disadvantages. Long-term viability favors integrated energy companies with concession portfolios and technology licensing revenue streams. Watch FERC interconnection queue clearance rates as the inflection signal for US development velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Binary Cycle Technology Licensing | Unlocks lower-temperature reservoirs for developers across East African Rift concessions. |
| Domestic Content Partnership | Satisfies Indonesia's Geothermal Fund Facility thresholds for turbine assembly eligibility. |
| Reservoir Management Service | Captures recurring revenue from utility operators seeking brine chemistry optimization. |
| Closed-Loop System Deployment | Eliminates induced seismicity risks constraining conventional hydrothermal expansion. |
| Power Purchase Agreement Restructuring | Balances baseload reliability premiums against spot market participation in Luzon. |
Research Methodology
Multiple input streams — executive interviews with utility planning officers and IPP project developers, EPC contractor bid documentation, and FERC interconnection filings — were reconciled against secondary validation from EIA generation statistics, IEA renewable technology roadmaps, and national regulator concession databases. Bottom-up project pipeline aggregation and top-down macroeconomic scenario modeling were triangulated to establish market sizing boundaries.
Data-stream reconciliation across infrastructure type, technology maturity, and end-user procurement scale produced volume and value outputs across the projection horizon. Segmentation dimensions modeled include plant configuration, reservoir temperature tier, and regulatory framework cluster. CAGRs were derived from project development timeline compression rates and feed-in tariff escalation assumptions. Forecast inputs incorporated steel alloy price volatility and drilling rig availability constraints.
Several conditions sit outside the modeled scope, including unannounced policy shifts in carbon border mechanisms and breakthroughs in enhanced geothermal systems commercialization. Forecasts reflect documented assumptions about interconnection queue clearance and exploration success rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geothermal Energy
Geothermal Power Generation Market
Geothermal Energy
US Geothermal Heat Pump Market
Geothermal Energy
Sweden Geothermal Energy Market
Geothermal Energy
Geothermal Power Market
Geothermal Energy
United Kingdom Geothermal Energy Market
Geothermal Energy
Geothermal Energy Market
Geothermal Energy
Enhanced Geothermal System Market
Geothermal Energy
Geothermal Power Infrastructure and Components Market
Geothermal Energy
Global Geothermal Heat Pumps Market
Geothermal Energy
Asia-Pacific Geothermal Energy Market
Geothermal Energy
Hungary Geothermal Energy Market
Geothermal Energy
Denmark Geothermal Energy Market
Geothermal Energy
Philippines Geothermal Energy Market
Geothermal Energy
Netherlands Geothermal Energy Market
Geothermal Energy
Indonesia Geothermal Energy Market