
 Indonesia Geothermal Energy Market | 2026-2036
Indonesia Geothermal Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Geothermal Energy Market Outlook
Indonesia's New and Renewable Energy Bill is consolidating the licensing landscape for geothermal developers by reducing overlapping authority between central and provincial governments. Pertamina Geothermal Energy leverages its upstream oilfield expertise to manage reservoir drilling campaigns across the volcanic arc. Star Energy Geothermal anchors the Sarulla complex in North Sumatra, sustaining output from one of the world's largest single-contract geothermal facilities. Sarulla Operations Limited competes on operational scale, navigating regulatory coordination between Jakarta and local authorities.
Geothermal energy in Indonesia harnesses heat from subsurface hydrothermal reservoirs, typically accessed through directional drilling to depths exceeding two kilometers where temperatures range from 150°C to 300°C, to drive steam turbines for baseload electricity production. Flash steam installations dominate installed capacity given Indonesia's abundance of high-enthalpy volcanic fields, while binary cycle technology extends economic viability to lower-temperature resources previously deemed sub-commercial. Enhanced Geothermal Systems represent an emerging technology frontier where reservoir stimulation could unlock deep, dry heat zones beneath Java's crowded grid infrastructure.
PLN Gas and Geothermal coordinates with the Ministry of Energy and Mineral Resources to align exploration timelines with national electrification targets, while the Geological Agency of Indonesia enforces resource classification standards that directly affect project financing terms. The country's Feed-in Tariff framework, administered by the Energy Regulatory Commission, shapes developer returns by fixing long-term power purchase agreement rates against exploration risk. Stakeholders must monitor whether Jakarta accelerates geothermal auction rounds or tightens local content requirements for drilling equipment procurement.
Market Dynamics
Indonesia's geothermal sector faces a structural tension between reservoir depletion rates at mature fields and the Ministry of Energy and Mineral Resources' electrification deadlines. The New and Renewable Energy Bill compresses permitting timelines while exploration risks remain concentrated in volcanic terrain with limited surface access.
Growth Catalysts
- Feed-in Tariff Framework:The Energy Regulatory Commission fixes long-term power purchase agreement rates that de-risk developer returns against exploration failure. This mechanism draws capital toward high-enthalpy volcanic fields.
- Direct-Use Industrial Expansion:Process heat applications at Java and Sumatra manufacturing facilities diversify revenue streams beyond electricity export. Food processing and textile plants anchor off-take demand.
- Binary Cycle Technology:Lower-temperature resource commercialization extends project viability to sub-150°C reservoirs previously excluded from development pipelines.
Market Restraints
- Upstream Supply Concentration:Specialized directional drilling rigs and high-temperature cementing services concentrate with a limited pool of international oilfield service providers.
- Exploration Cost Structure:Deep drilling campaigns exceeding two kilometers require capital commitments before reservoir confirmation, locking developer balance sheets during extended appraisal phases.
- Grid Interconnection Friction:Transmission capacity constraints in Eastern Indonesia limit offtake pathways for remote volcanic field discoveries.
Strategic Opportunities
- Enhanced Geothermal Systems:Reservoir stimulation technology unlocks deep dry-heat zones beneath Java's congested grid infrastructure where conventional hydrothermal resources are depleted.
- Eastern Indonesia Greenfield:Flores and Sulawesi volcanic arcs host underexplored high-enthalpy fields with lower land-use competition than crowded Western islands.
- Local Content Requirements:Proposed drilling equipment procurement mandates create openings for domestic fabrication capacity expansion.
Industry Challenges
- Geoscience Talent Scarcity:Reservoir engineering and subsurface modeling expertise concentrates with aging specialists at state-owned upstream operators.
- Regulatory Coordination Complexity:Overlapping authority between Jakarta ministries and provincial governors delays environmental permitting for multi-district developments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Geothermal Energy Market |
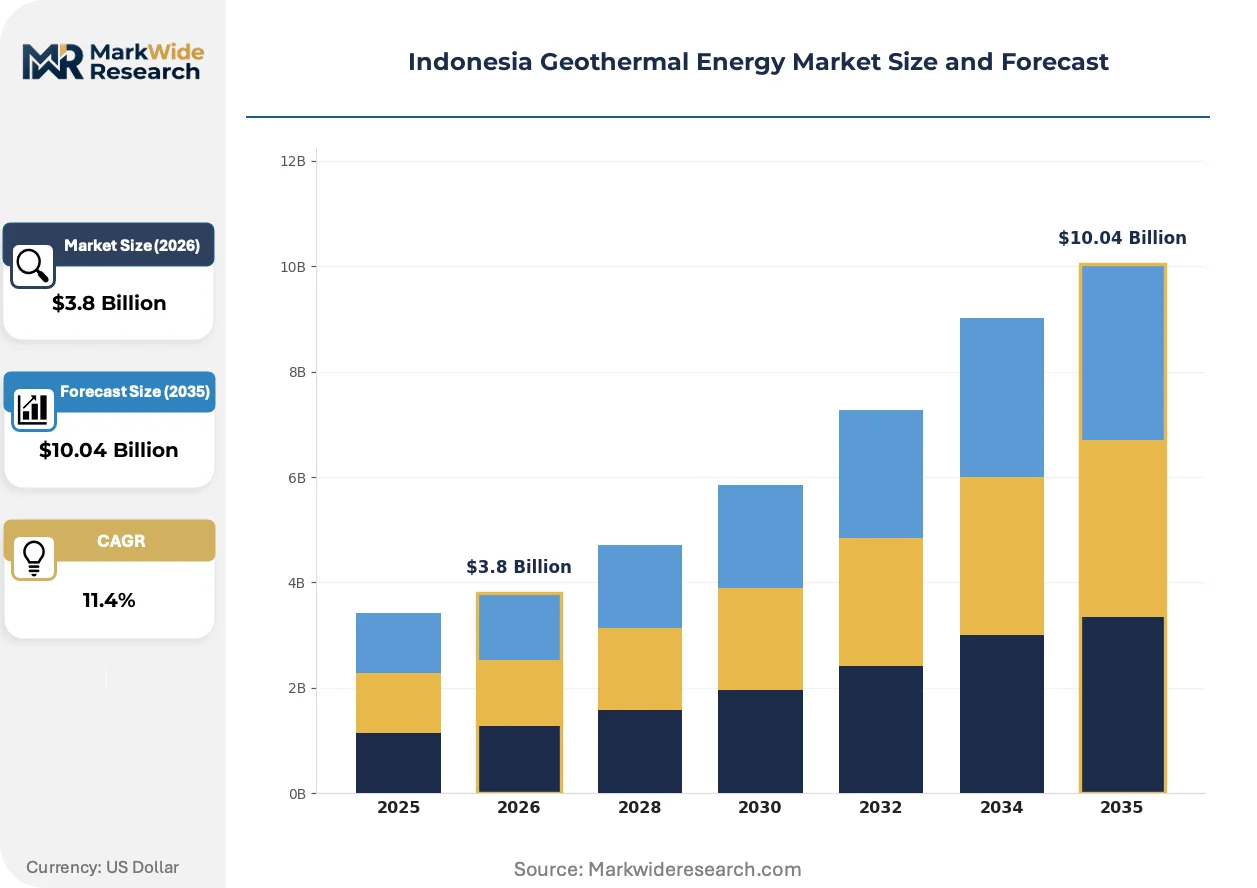
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Flash Steam, Binary Cycle, Dry Steam, Hot Water Application: Power Generation, Direct Use, District Heating, Greenhouse Heating End User: Utility Companies, Industrial Plants, Residential Consumers, Commercial Establishments Technology: Combined Cycle, Ormat System, Kalina Cycle, Enhanced Geothermal Systems |
| Companies Covered | Pertamina Geothermal Energy, Star Energy Geothermal, Sarulla Operations Limited, PT Supreme Energy, Medco Cahaya Geothermal, Geo Dipa Energi, PLN Gas and Geothermal, Enel SpA, Toshiba Energy Systems & Solutions Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Geothermal Energy Market Strategic Shifts
Technology convergence and regulatory compression are reshaping how Indonesian developers access subsurface heat. Flash steam dominance faces pressure from binary adaptation and reservoir stimulation advances.
Binary cycle technology is unifying previously marginal low-temperature resources into commercial project pipelines. Industrial off-takers in Sumatra's agricultural processing corridor adopt modular binary units for distributed heat-and-power applications. This convergence compresses the minimum viable resource threshold and expands the addressable reservoir inventory.
The Ministry of Energy and Mineral Resources' New and Renewable Energy Bill consolidates licensing authority previously fragmented across provincial and central agencies. Developers now navigate a single-window clearance system for exploration permits and production concessions. Large-scale complexes in North Sumatra benefit most from streamlined coordination between Jakarta regulators and district authorities.
Buyer concentration around state-owned PLN Gas and Geothermal is compressing developer negotiation leverage and accelerating procurement standardization. Independent power producers face standardized power purchase agreement templates with limited tariff escalation clauses. This pattern concentrates most visibly in Java where grid-connected capacity additions dominate the pipeline.
Indonesia Geothermal Energy Market Segmentation
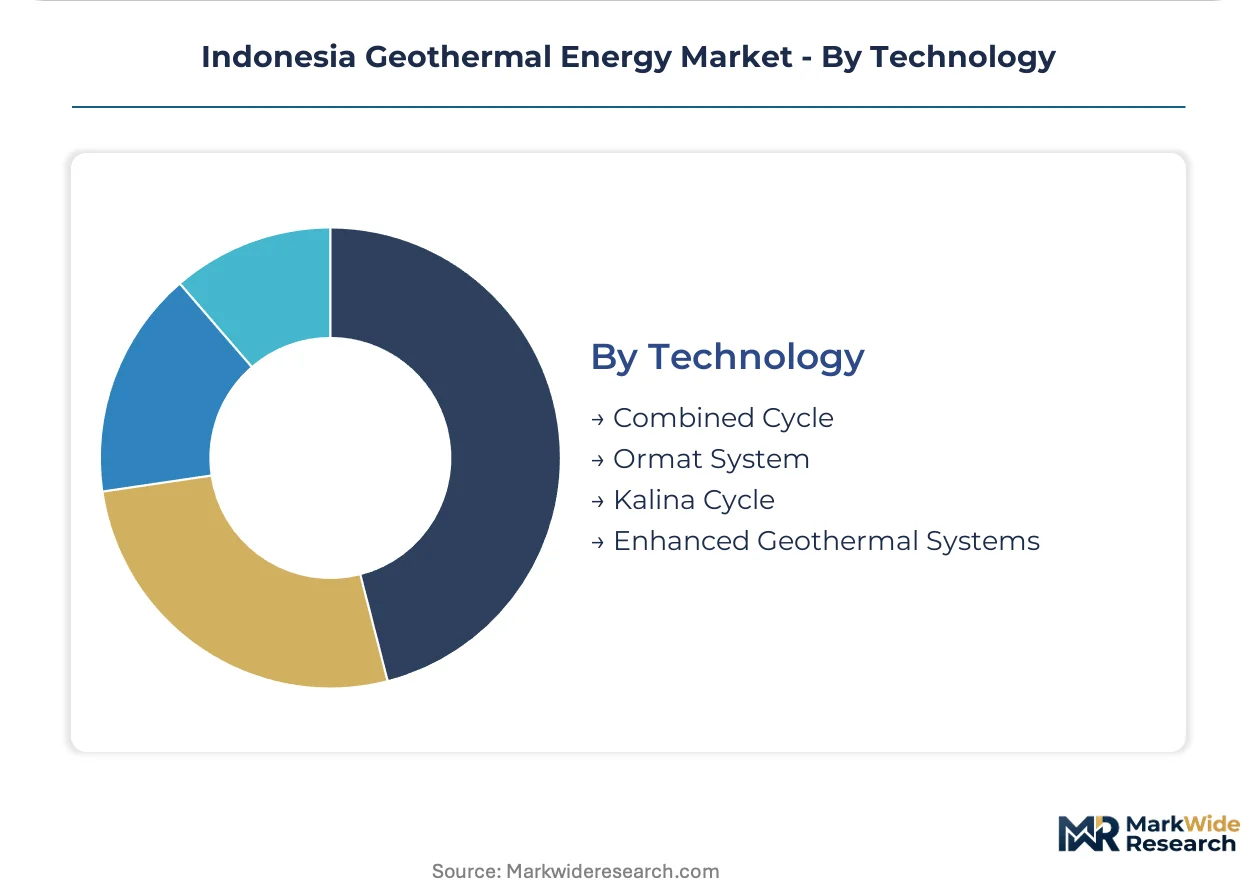
Technology selection in Indonesia's geothermal sector determines project economics against volcanic field characteristics. Segment boundaries shift as binary cycles penetrate lower-temperature resources and enhanced systems target deep reservoirs beneath Java's congested grid.
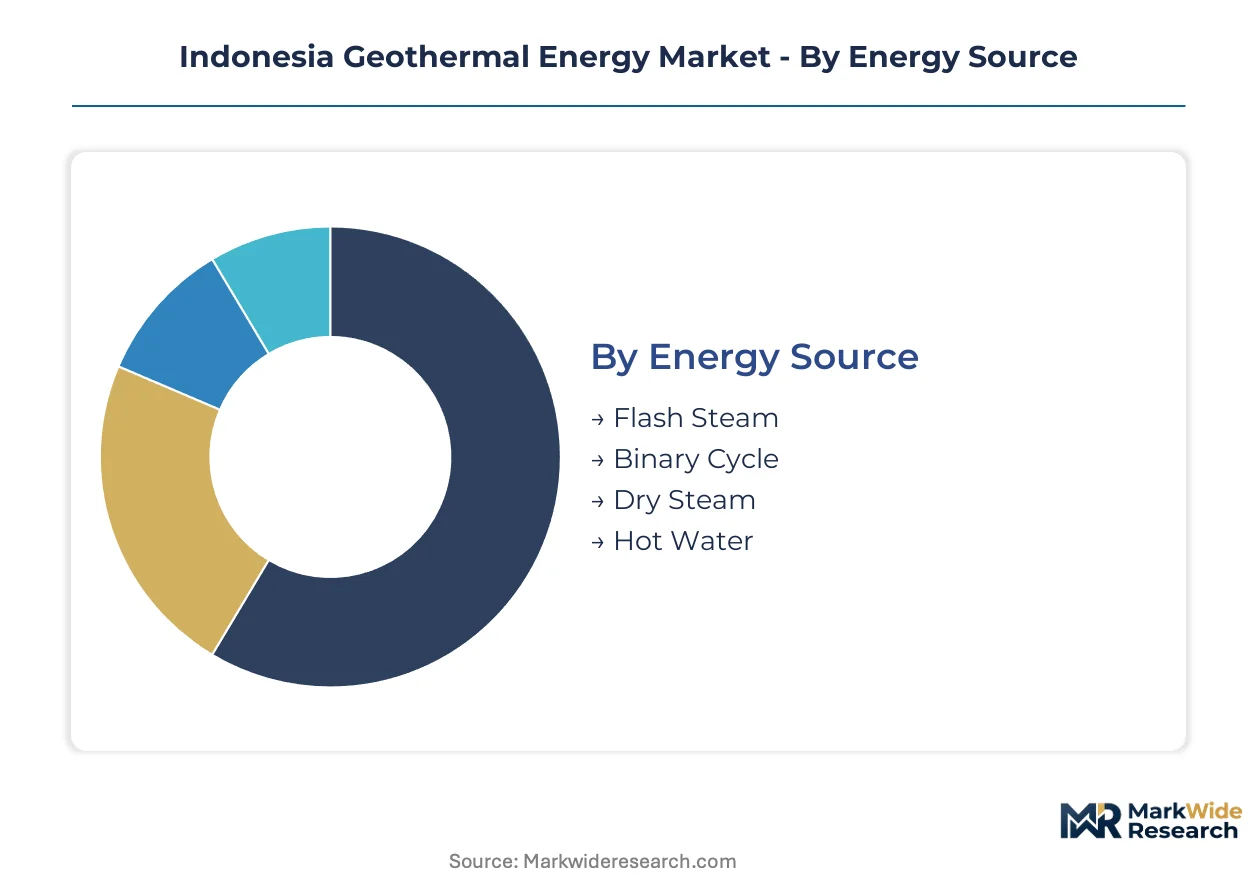
Energy Source:
Flash steam systems operate as standalone baseload plants while binary cycles embed within distributed industrial heat networks.
- Flash Steam:High-enthalpy reservoirs above 180°C drive steam turbines through pressure-reducing separators. Utility-scale installations across Java and Sumatra anchor national capacity additions under PLN Gas and Geothermal offtake agreements.
- Binary Cycle:Organic Rankine cycle engines extract energy from sub-150°C fluids via secondary working fluids. Food processing corridors in North Sumatra adopt modular binary units for captive process heat, bypassing grid interconnection constraints.
- Dry Steam:Rare natural steam reservoirs require minimal surface equipment. Limited to specific volcanic formations with direct vapor discharge.
- Hot Water:Low-enthalpy thermal fluids suit direct-use applications without electricity conversion. District heating pilots in Bandung test shallow aquifer viability.
Volume placements concentrate in Flash Steam; the faster expansion belongs to Binary Cycle.
Application:
Revenue concentration tilts toward bulk electricity sales while direct-use applications capture margin through avoided fuel costs.
- Power Generation:Baseload electricity supply to state-owned grids dominates project pipelines. Sarulla Operations Limited and Pertamina Geothermal Energy anchor multi-hundred-megawatt complexes feeding Java-Bali transmission networks.
- Direct Use:Industrial process heat bypasses generation losses for thermal efficiency. Textile dyeing and agricultural drying operations in Central Java contract dedicated brine supply from adjacent power fields.
- District Heating:Urban thermal networks distribute reservoir heat through insulated piping. Regulatory frameworks from the Ministry of Energy and Mineral Resources remain underdeveloped for municipal concessions.
- Greenhouse Heating:Controlled-environment agriculture in highland regions leverages stable geothermal temperatures. Flower export zones near Mount Papandayan trial closed-loop circulation systems.
Revenue weight sits with Power Generation; Direct Use climbs fastest as industrial tariffs escalate.
End User:
Procurement scale separates centralized utility buyers from fragmented industrial offtakers with divergent risk appetites.
- Utility Companies:PLN Gas and Geothermal contracts standardize twenty-five-year power purchase agreements with fixed escalation clauses. State-owned procurement concentrates drilling investment in proven volcanic fields with transmission access.
- Industrial Plants:Process heat buyers negotiate bilateral thermal supply contracts independent of electricity markets. Paper mills and chemical processors in Riau Province source direct brine for steam-intensive operations.
- Residential Consumers:Distributed heating remains negligible due to network infrastructure gaps. Rural electrification programs prioritize grid extension over standalone geothermal microgrids.
- Commercial Establishments:Hotels and spas near volcanic tourism zones exploit shallow thermal springs. Regulatory classification disputes with the Geological Agency of Indonesia complicate small-scale extraction permits.
Contract volume aggregates at Utility Companies; Industrial Plants show steepest expansion trajectory as manufacturing relocates from imported fuel dependence.
Technology:
Proven thermodynamic cycles command deployment capital while experimental systems seek demonstration funding.
- Combined Cycle:Sequential flash and binary stages maximize energy extraction from variable-enthalpy resources. Large field developments in North Sumatra integrate multiple conversion technologies across separated reservoir zones.
- Ormat System:Proprietary binary cycle configurations dominate international developer technology selections. Standardized modular designs reduce engineering risk for remote Eastern Indonesia projects.
- Kalina Cycle:Ammonia-water working fluids improve thermal efficiency at specific temperature ranges. Limited commercial deployment due to maintenance complexity and spare parts supply chains.
- Enhanced Geothermal Systems:Reservoir stimulation creates artificial permeability in deep dry-heat zones. Java's depleted conventional fields attract pilot funding for hydraulic fracturing adaptation from upstream oilfield techniques.
Deployment scale favors Combined Cycle; Enhanced Geothermal Systems gain share fastest as exploration depth requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian geothermal development clusters along volcanic arcs where reservoir temperatures exceed 200°C and transmission infrastructure reaches state-owned offtakers. Provincial permitting authority under the New and Renewable Energy Bill shapes investment timing across archipelago sub-regions.
Java
Utility-scale power generation dominates Java's geothermal pipeline, with flash steam plants feeding the Java-Bali transmission backbone. The Ministry of Energy and Mineral Resources prioritizes this corridor for national electrification targets. Industrial process heat contracts in Central Java's textile corridor diversify revenue beyond PLN Gas and Geothermal offtake agreements.
Sumatra
North Sumatra hosts Indonesia's largest operating geothermal complex, where multi-hundred-megawatt capacity anchors regional baseload supply. The Geological Agency of Indonesia classifies high-enthalpy resources across the Toba volcanic field for priority exploration licensing. Sarulla's operational scale demonstrates commercial viability for large-field development under streamlined central-provincial coordination.
Sulawesi
Eastern Indonesia's underexplored volcanic arcs attract greenfield investment where land-use competition remains lower than western islands. Grid interconnection constraints limit immediate offtake pathways despite confirmed high-temperature reservoirs. The Energy Regulatory Commission's feed-in tariff framework extends to remote fields as transmission expansion proceeds.
Flores
Flores volcanic formations host geothermal potential with minimal competing land claims from agriculture or urban settlement. Exploration drilling campaigns face logistical challenges from limited port infrastructure and seasonal weather windows. District governments in East Nusa Tenggara negotiate production sharing terms under revised provincial authority allocations.
Bali
Bali's geothermal prospects concentrate in the island's volcanic interior, constrained by tourism-driven land-use restrictions and cultural site protections. Direct-use applications for hospitality thermal spas operate under small-scale extraction permits disputed with the Geological Agency of Indonesia. Utility-scale development remains stalled pending transmission reinforcement from Java interconnection.
Indonesia Geothermal Energy Market Competitive Environment
State-owned enterprises anchor one competitive tier; international technology providers and independent power producers hold specialized positions across project development and equipment supply. Market structure concentrates around vertically integrated upstream operators with reservoir drilling capabilities and long-term power purchase agreement access. Three archetypes dominate: national oil company subsidiaries leveraging upstream expertise, dedicated geothermal developers with operational scale, and engineering firms supplying binary cycle and flash steam turbine packages. Competitive dynamics center on securing exploration permits ahead of regulatory deadlines and locking twenty-five-year offtake contracts with PLN Gas and Geothermal.
Within the state-affiliated tier, Pertamina Geothermal Energy exemplifies upstream oilfield adaptation to geothermal reservoir management. Star Energy Geothermal occupies a position among dedicated developers with operational concentration in North Sumatra. Sarulla Operations Limited represents the large-field complex archetype, navigating multi-layered regulatory coordination for sustained output from one of Indonesia's signature installations.
| Leading Market Players |
|---|
| Pertamina Geothermal Energy |
| Star Energy Geothermal |
| Sarulla Operations Limited |
| PT Supreme Energy |
| Medco Cahaya Geothermal |
| Geo Dipa Energi |
| PLN Gas and Geothermal |
| Enel SpA |
| Toshiba Energy Systems & Solutions Corporation |
| Others |
Value Chain & Pricing Dynamics
PLN Gas and Geothermal's standardized twenty-five-year power purchase agreement templates compress developer negotiation leverage and lock tariff structures early in project lifecycles. This procurement consolidation forces equipment suppliers to absorb cost volatility and extend payment terms, squeezing margins across drilling contractors and turbine packagers.
Pricing Analysis
Volume placements concentrate in utility-scale flash steam installations while margins concentrate in modular binary cycle units for industrial direct-use applications. Pricing stratifies across premium, standard, and economy tiers based on reservoir temperature grade and grid interconnection proximity. Cost compression in binary equipment packages is intensifying as Ormat System and Toshiba Energy Systems & Solutions Corporation expand standardized modular designs. Industrial process heat buyers in Sumatra's agricultural corridor exhibit highest price sensitivity due to competing biomass and natural gas alternatives, while state-owned utility offtakers demonstrate lowest sensitivity given electrification mandate backing.
Supply Chain Analysis
Specialized directional drilling rig supply rests on Japanese and American oilfield service providers, with high-temperature cementing services concentrating among a limited pool of international contractors. Critical inputs include nickel-based alloys for turbine blades, high-specification drilling mud formulations, and precision wellhead equipment. Single-source vulnerability runs through deep drilling campaign contractors capable of two-kilometer directional boreholes. Distribution runs through state-owned procurement channels for utility-scale projects and bilateral thermal supply contracts for industrial direct-use applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's geothermal sector sits at a technology-transition inflection where binary cycle systems displace flash steam dominance in marginal reservoir development. This shift reconfigures competitive positioning around modular equipment supply and distributed industrial offtake relationships.
For Market Incumbents: Cement reservoir engineering capabilities through captive geoscience talent programs targeting the aging specialist pool at Pertamina Geothermal Energy and Geo Dipa Energi. Defend against binary technology displacement by integrating combined cycle configurations across large-field developments in North Sumatra. Prioritize backward integration into drilling equipment maintenance facilities to reduce dependency on international oilfield service providers.
For New Entrants and Emerging Players: Capture Eastern Indonesia greenfield opportunities in Flores and Sulawesi where land-use competition remains minimal and provincial permitting authority under the New and Renewable Energy Bill offers streamlined access. Target modular binary cycle deployments for captive industrial process heat in Central Java's textile corridor. Pursue joint development structures with established reservoir operators to mitigate exploration risk during extended appraisal phases.
For Investors and Strategic Acquirers: The window for entry favors technology-agnostic developers with proven power purchase agreement execution track records and operational scale in multi-hundred-megawatt complexes. Long-term viability hinges on portfolio diversification across high-enthalpy volcanic fields and lower-temperature binary-adaptable resources. Monitor feed-in tariff framework revisions by the Energy Regulatory Commission as the primary inflection signal for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Reservoir Stimulation Pilot Programs | Enhanced Geothermal Systems unlock deep dry-heat zones beneath Java's congested transmission infrastructure. |
| Binary Cycle Technology Licensing | Ormat System proprietary configurations reduce engineering risk for remote Eastern Indonesia project development. |
| Local Content Procurement Mandates | Domestic drilling equipment fabrication openings align with Ministry of Energy and Mineral Resources policy direction. |
| Industrial Direct-Use Partnerships | Captive process heat contracts with Sumatra food processing plants diversify revenue beyond state-owned utility offtake. |
| Geoscience Talent Development Programs | Reservoir engineering expertise concentration at aging state-owned operators creates acquisition and training imperatives. |
Study Parameters
Document review covered regulatory filings with the Ministry of Energy and Mineral Resources, project development databases tracking exploration permits, and power purchase agreement templates from PLN Gas and Geothermal, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from IEA geothermal market reports, EIA international energy data, and FERC comparative regulatory frameworks. Bottom-up project pipeline aggregation and top-down macroeconomic triangulation anchored market sizing.
Historical capacity addition patterns were cross-referenced against expert panel assessments of exploration timeline feasibility and reservoir confirmation rates. Segmentation modeling spanned technology type, application category, end-user procurement scale, and regional grid infrastructure maturity across the analysis window. CAGRs were derived from regression analysis of investment commitment trajectories and electrification target alignment, incorporating feed-in tariff evolution and drilling cost inflation assumptions specific to volcanic terrain access constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to reservoir depletion rates at mature fields, regulatory coordination complexity between Jakarta and provincial authorities, and grid interconnection expansion timing in Eastern Indonesia. Forecasts reflect documented assumptions regarding permitting streamlining under the New and Renewable Energy Bill and technology cost curves for binary cycle equipment. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geothermal Energy
Geothermal Power Market
Geothermal Energy
Netherlands Geothermal Energy Market
Geothermal Energy
Asia-Pacific Geothermal Energy Market
Geothermal Energy
Global Geothermal Heat Pumps Market
Geothermal Energy
Enhanced Geothermal System Market
Geothermal Energy
Philippines Geothermal Energy Market
Geothermal Energy
Geothermal Power Infrastructure and Components Market
Geothermal Energy
Geothermal Power Infrastructure Market
Geothermal Energy
Hungary Geothermal Energy Market
Geothermal Energy
Geothermal Power Generation Market
Geothermal Energy
United Kingdom Geothermal Energy Market
Geothermal Energy
Sweden Geothermal Energy Market
Geothermal Energy
US Geothermal Heat Pump Market
Geothermal Energy
Denmark Geothermal Energy Market
Geothermal Energy
Geothermal Energy Market