
 Asia-Pacific Geothermal Energy Market | 2026-2036
Asia-Pacific Geothermal Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Geothermal Energy Market Outlook
Utility procurement is rebalancing toward baseload geothermal contracts as intermittent renewable exposure rises across Southeast Asian grids. Energy Development Corporation leverages its vertical presence across exploration and plant operations to sustain project economics in the Philippines. Pertamina Geothermal Energy PT anchors Indonesia's installed capacity through state-backed field development. Toshiba Corp. competes on turbine-generator technology leadership for high-enthalpy resource conditions.
Asia-Pacific geothermal energy harnesses heat from subsurface hydrothermal reservoirs, typically accessed through wells drilled to depths of one to three kilometers where temperatures exceed 150 degrees Celsius, to drive turbine-based electricity generation or direct thermal applications. Binary cycle installations dominate new capacity additions across lower-temperature fields, while flash steam systems retain share in high-enthalpy volcanic zones where resource quality supports simpler plant configurations. The electricity generation method captures the majority of capital deployment, though direct use applications for industrial process heat represent an expanding margin pool as offtake agreements diversify beyond pure power sales.
Indonesia's Ministry of Energy and Mineral Resources coordinates geothermal licensing with environmental clearances from the country's environmental regulator, compressing approval timelines for strategic projects. Japan's METI maintains feed-in tariff mechanisms and safety standards under its Hot Spring Law framework, shaping project viability in onsen-adjacent regions. Stakeholders must track regulatory harmonization between national mineral resource codes and renewable energy procurement mandates as permitting complexity determines development velocity.
Market Dynamics
Utility procurement across Southeast Asian grids is rebalancing toward baseload geothermal contracts as intermittent renewable penetration rises and grid stability concerns intensify. This structural force compresses development timelines and rewards vertically integrated developers with proven resource access.
Growth Catalysts
- Indonesia's streamlined licensing:The Ministry of Energy and Mineral Resources has compressed approval timelines through revised upstream frameworks, accelerating field development across volcanic arc provinces.
- Industrial heat offtake:Manufacturing clusters in the Philippines are signing direct thermal supply agreements, diversifying revenue beyond electricity sales.
- Binary cycle technology maturation:Lower-temperature field viability is expanding deployable resource inventory across previously marginal subsurface conditions.
Market Restraints
- Exploration capital intensity:Deep drilling to one-to-three-kilometer depths requires sustained upfront commitment before resource confirmation.
- Specialized turbine supply concentration:High-enthalpy turbine-generator manufacturing concentrates among limited equipment vendors, creating procurement bottlenecks.
- Japan's Hot Spring Law friction:METI's regulatory framework creates permitting complexity in onsen-adjacent regions, constraining development in otherwise favorable geologies.
Strategic Opportunities
- Direct use application expansion:Agricultural drying and aquaculture heating represent underpenetrated thermal offtake segments with stable demand profiles.
- Indonesia's eastern provinces:Sulawesi and Maluku volcanic arcs hold substantial unlicensed resource potential with limited competing land use.
- Feed-in tariff mechanisms:Japan's METI maintains purchase guarantees that improve project financeability for developers navigating complex surface access negotiations.
Industry Challenges
- Geoscientist talent scarcity:Reservoir engineering and subsurface characterization expertise concentrates among aging specialist cohorts with limited training pipeline replenishment.
- Environmental clearance synchronization:Indonesia's environmental regulator operates on separate timelines from mineral resource licensing, creating approval coordination friction.
- Legacy grid interconnection standards:Provincial utility technical specifications vary across the archipelago, forcing plant design customization that fragments equipment procurement scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Geothermal Energy Market |
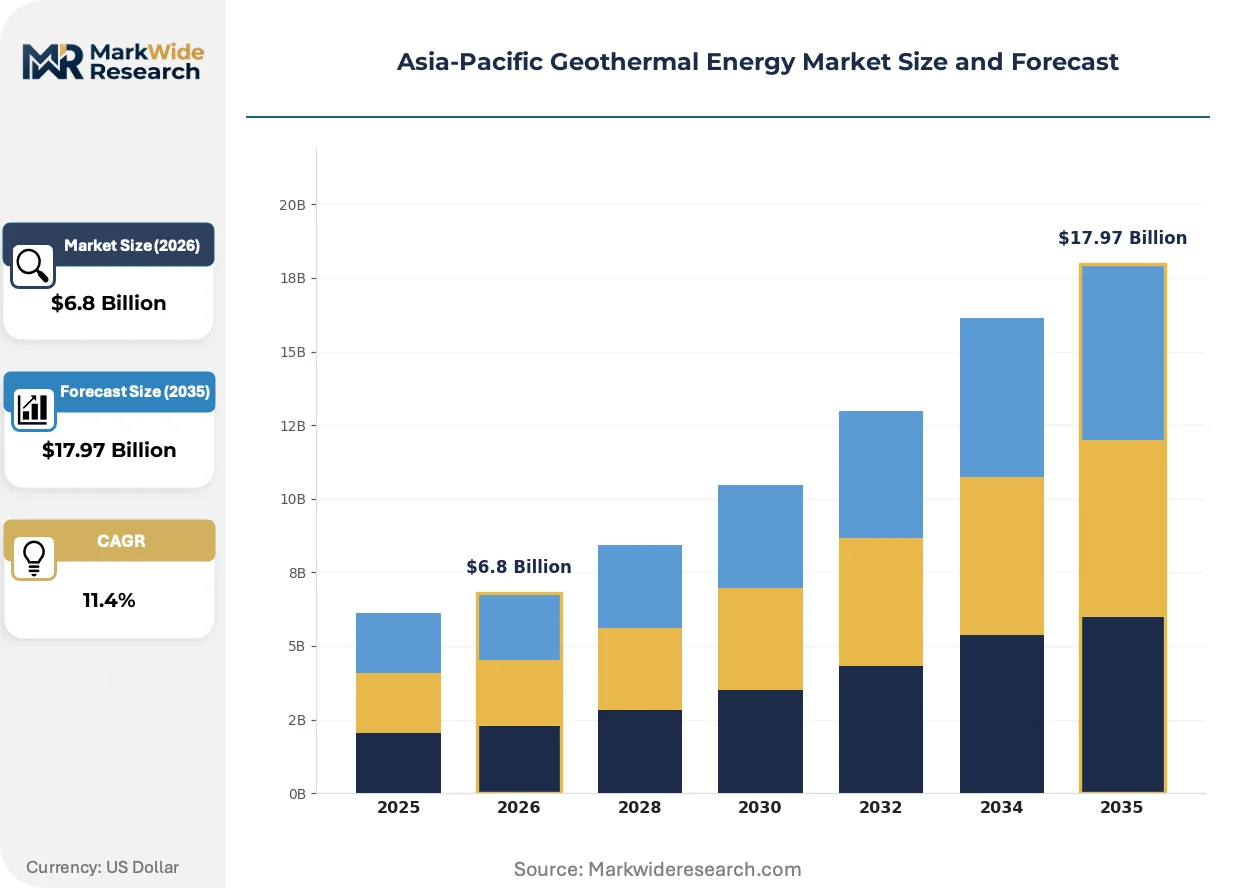
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Resource Type: Hydrothermal, Enhanced Geothermal Systems, Hot Dry Rock, Geopressured Installation Type: Binary Cycle, Flash Steam, Dry Steam, Organic Rankine Cycle Power Generation Method: Electricity Generation, Direct Use Applications, Combined Heat and Power, District Heating End User Sector: Utilities, Industrial, Residential, Commercial |
| Companies Covered | Energy Development Corporation, Pertamina Geothermal Energy PT, Toshiba Corp., Mercury NZ Ltd., PT Supreme Energy, PT Medco Power Indonesia, Star Energy Geothermal (Wayang Windu) Limited, PT WIJAYA KARYA (Persero) Tbk., Trienergy PT, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Geothermal Energy Market Strategic Shifts
Technology deployment across Asia-Pacific geothermal fields is automating reservoir monitoring and plant optimization while regulatory frameworks evolve to accommodate hybrid renewable configurations. These shifts compress operational expenditure structures and reshape competitive positioning among developers.
Advanced downhole sensor arrays are automating real-time reservoir pressure and temperature monitoring, replacing manual wellhead measurement regimes. Philippine operators are deploying these systems across mature fields to optimize extraction rates and extend reservoir life. This technology is automating production decline prediction, enabling proactive workover scheduling that reduces unplanned outage frequency.
Indonesia's Ministry of Energy and Mineral Resources has integrated geothermal licensing with carbon credit eligibility frameworks, creating dual revenue stream potential for new projects. This policy convergence alters project finance structures by improving debt service coverage ratios through supplemental income. Developers in Sumatra and Java are restructuring offtake agreements to capture this regulatory tailwind.
Industrial buyers are consolidating thermal procurement through multi-site master service agreements, displacing single-plant bilateral contracts. Food processing and textile manufacturers across the Philippines are aggregating demand to secure volume-discounted heat supply. This concentration is most visible in Luzon manufacturing corridors where clustered facilities enable pipeline infrastructure sharing.
Asia-Pacific Geothermal Energy Market Segmentation
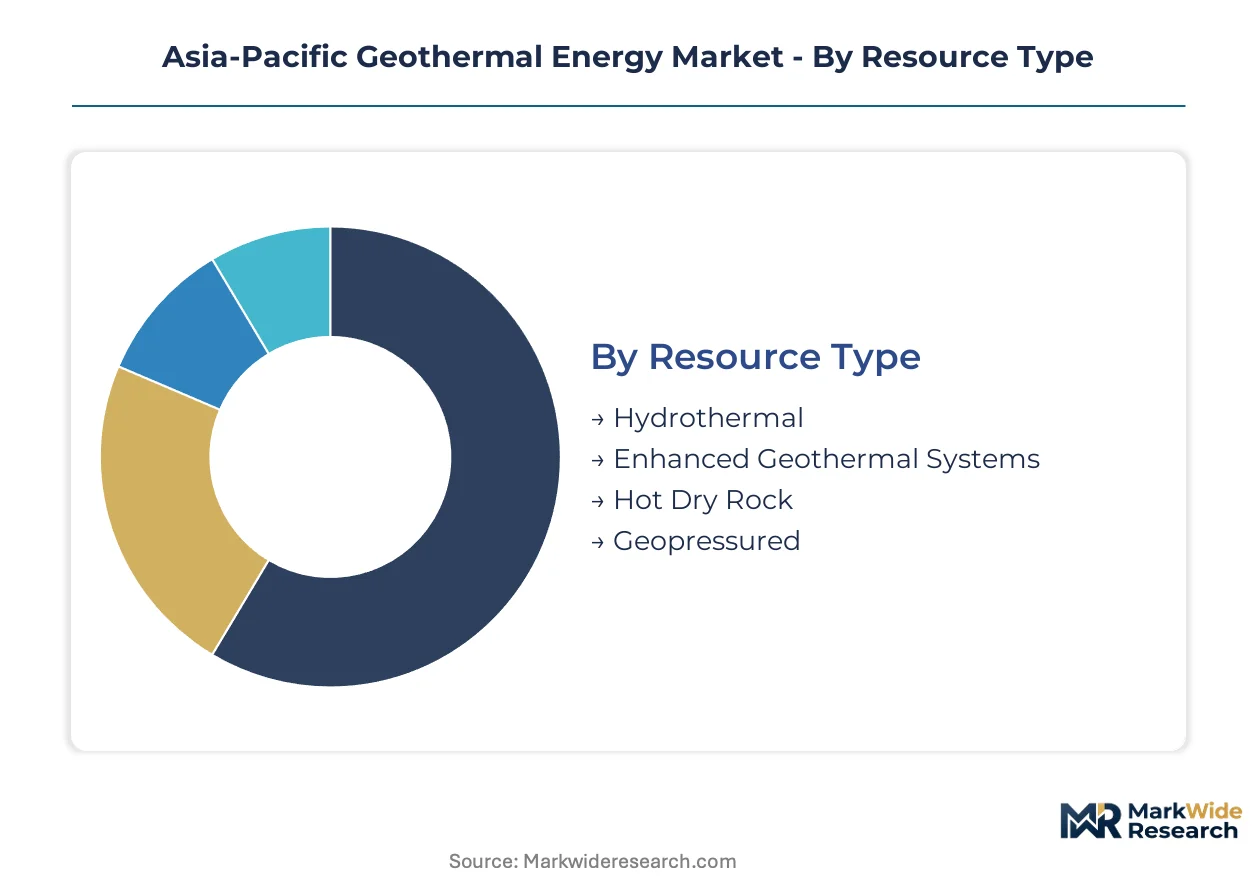
Geothermal project economics vary dramatically across resource temperatures, plant configurations, and offtake arrangements. Understanding these segment boundaries clarifies where capital deployment concentrates and which technology pathways offer viable returns under Asia-Pacific regulatory and geological conditions.
Resource Type:
Hydrothermal reservoirs demand the heaviest upfront drilling investment but deliver confirmed resource certainty that underwrites project finance.
- Hydrothermal:Naturally occurring steam or hot water reservoirs accessed through conventional drilling. Indonesia's volcanic arc provinces concentrate development here, with state-backed licensing frameworks compressing approval timelines for confirmed resources.
- Enhanced Geothermal Systems:Engineered reservoirs created through hydraulic stimulation of hot dry formations. Japan's METI feed-in tariffs partially offset higher capital intensity in onsen-adjacent regions where surface access negotiations prolong development.
- Hot Dry Rock:Deep crystalline formations requiring artificial fluid circulation. Exploration drilling costs remain prohibitive without targeted government research subsidies.
- Geopressured:Deep sedimentary basins combining thermal energy with dissolved methane. Limited Asia-Pacific prospectivity outside specific Philippine sedimentary troughs.
Most installed capacity flows through Hydrothermal. Expansion is steepest in Enhanced Geothermal Systems.
Installation Type:
Plant configuration selection hinges on reservoir temperature, with binary systems opening lower-grade resources that flash steam economics cannot justify.
- Binary Cycle:Closed-loop systems using secondary working fluids to extract heat from moderate-temperature reservoirs. Philippine operators deploy these across mature fields below 180 degrees Celsius, extending economic viability to previously marginal resources.
- Flash Steam:Direct steam separation from high-pressure hydrothermal fluids. Indonesia's high-enthalpy volcanic zones favor this simpler configuration, reducing equipment complexity and maintenance overhead.
- Dry Steam:Direct turbine drive from saturated steam reservoirs. Rare in Asia-Pacific outside specific Philippine caldera systems.
- Organic Rankine Cycle:Specialized binary variant optimized for ultra-low temperature differentials. Emerging deployment in Japanese onsen district heating applications.
Binary Cycle plants dominate new capacity additions. Flash Steam retains share in Indonesia's premium resource zones.
Power Generation Method:
Revenue model diversification separates pure electricity sellers from developers capturing thermal value through direct industrial offtake.
- Electricity Generation:Grid-connected power sales under long-term power purchase agreements. Indonesian state utility PLN remains the primary offtaker, with procurement rebalancing toward baseload contracts as intermittent renewable penetration rises.
- Direct Use Applications:Industrial process heat supply bypassing electricity conversion. Philippine textile and food processing manufacturers aggregate demand through multi-site master service agreements, securing volume-discounted thermal supply.
- Combined Heat and Power:Simultaneous electricity and thermal output maximizing exergy efficiency. Limited deployment due to complex offtake coordination requirements.
- District Heating:Centralized thermal distribution to building clusters. Japanese onsen towns leverage existing hot spring infrastructure for seasonal heating loads.
Electricity Generation absorbs the majority of capital deployment. Direct Use Applications are climbing the fastest as industrial buyers diversify procurement.
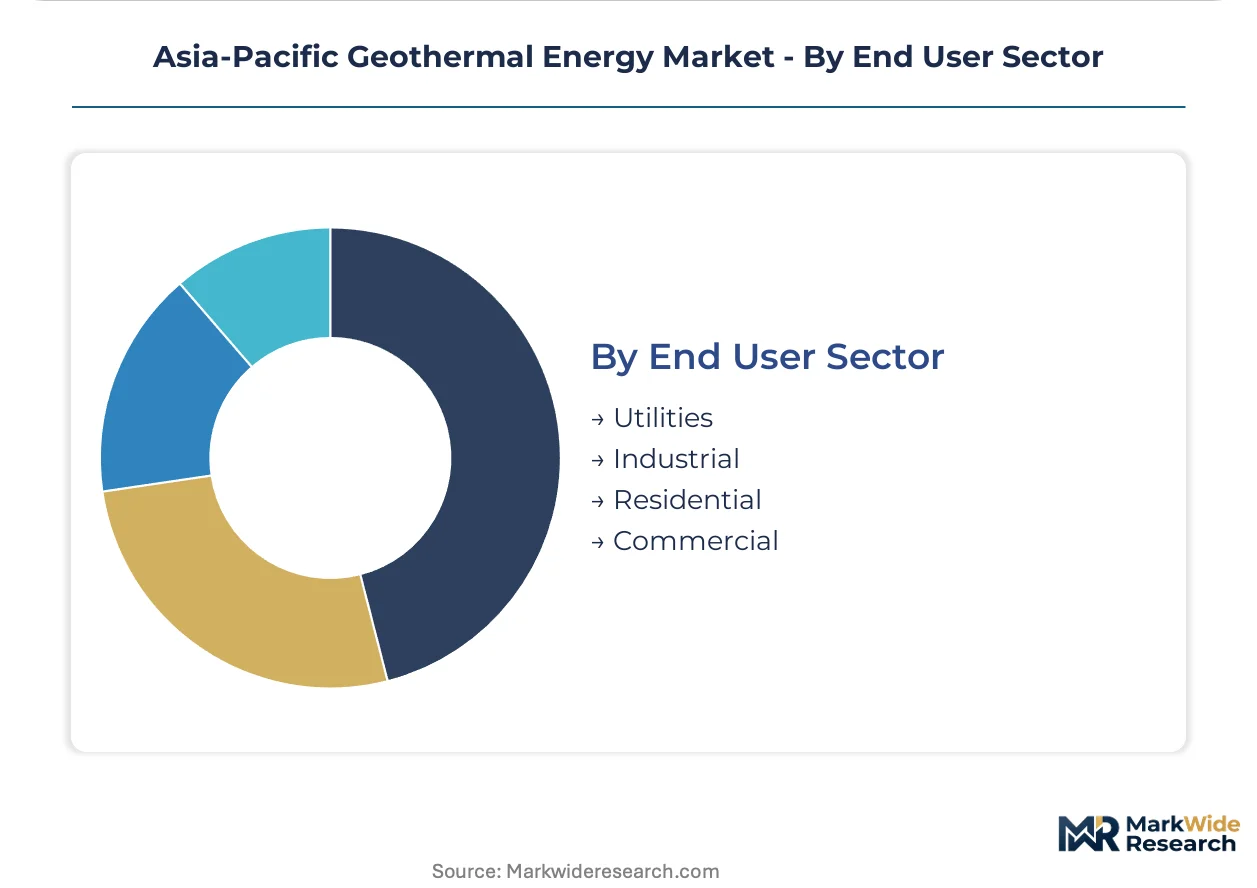
End User Sector:
Customer concentration shapes project scale and contract duration, with utilities offering volume stability that industrial offtake cannot match.
- Utilities:Grid operators procuring baseload capacity under 20-30 year power purchase agreements. Indonesia's PLN and Philippine distribution utilities anchor demand, with procurement criteria weighting dispatch reliability against levelized cost.
- Industrial:Manufacturing facilities seeking thermal supply for process heat. Luzon manufacturing corridors enable pipeline infrastructure sharing across clustered food processing and textile facilities.
- Residential:Individual building heating through ground-source heat pumps. Limited penetration outside Japan's established onsen heating networks.
- Commercial:Hotels, hospitals, and institutional buildings seeking heating and cooling. Small-scale deployment constrained by high per-connection infrastructure costs.
Utilities command the largest project scale. Industrial offtake is gaining share fastest as manufacturing clusters consolidate thermal procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials across the Asia-Pacific region are redirecting geothermal development capital toward jurisdictions with streamlined permitting frameworks. Indonesia and the Philippines offer compressed approval timelines that accelerate project velocity relative to Japan's more complex surface access negotiations. This compliance-cost arbitrage concentrates exploration drilling investment in volcanic arc provinces with favorable licensing environments.
Indonesia
State utility PLN is rebalancing procurement toward baseload geothermal contracts as intermittent renewable penetration strains grid stability across Java and Sumatra. The Ministry of Energy and Mineral Resources has integrated upstream licensing with carbon credit eligibility, creating dual revenue streams for developers in volcanic arc provinces. Exploration activity concentrates in Sulawesi and Maluku where unlicensed resource potential faces limited competing land use.
Philippines
Industrial heat consumers in Luzon manufacturing corridors are consolidating thermal procurement through multi-site master service agreements that displace single-plant contracts. Energy Development Corporation leverages vertical presence across exploration and plant operations to sustain project economics in mature fields. Textile and food processing clusters in Batangas and Laguna enable pipeline infrastructure sharing across clustered facilities.
Japan
METI maintains feed-in tariff mechanisms that improve project financeability for developers navigating complex surface access negotiations in onsen-adjacent regions. The Hot Spring Law framework creates permitting friction that constrains development velocity despite favorable geologies in Kyushu and Tohoku. Binary cycle installations dominate new capacity additions as operators target lower-temperature fields below 180 degrees Celsius.
New Zealand
Mercury NZ Ltd. anchors installed capacity through utility-scale development across the Taupo Volcanic Zone where high-enthalpy resources support flash steam configurations. The country's emissions trading scheme reinforces geothermal competitiveness against fossil baseload alternatives. Regulatory stability attracts international capital seeking exposure to proven resource provinces with established grid interconnection standards.
Asia-Pacific Geothermal Energy Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated developers commanding premium positions in confirmed resource provinces while equipment vendors compete on turbine-generator technology leadership. The market structure concentrates around state-backed entities with secured field access and private operators with specialized exploration capabilities. Two strategic archetypes dominate: integrated developers controlling upstream-to-generation value chains, and technology suppliers capturing margin through high-enthalpy equipment specialization. Competitive dynamics center on securing priority licensing positions and securing long-term power purchase agreements with creditworthy offtakers.
Among Philippines-based integrated developers, Energy Development Corporation exemplifies the vertical-control archetype through its presence across exploration and plant operations. Pertamina Geothermal Energy PT anchors the state-backed tier in Indonesia with field development spanning multiple volcanic provinces. Toshiba Corp. occupies the equipment-specialist position, competing on turbine-generator systems optimized for high-enthalpy resource conditions across the region.
| Leading Market Players |
|---|
| Energy Development Corporation |
| Pertamina Geothermal Energy PT |
| Toshiba Corp. |
| Mercury NZ Ltd. |
| PT Supreme Energy |
| PT Medco Power Indonesia |
| Star Energy Geothermal (Wayang Windu) Limited |
| PT WIJAYA KARYA (Persero) Tbk. |
| Trienergy PT |
| Others |
Value Chain & Pricing Dynamics
Drilling rig day-rates and specialized turbine forgings cascade through project development economics, with high-enthalpy equipment premiums compressing returns on lower-temperature binary installations across Philippine and Indonesian fields. Procurement officers at independent power producers negotiate long-term offtake terms that lock in fuel-cost pass-through structures, insulating developers from geothermal steam variability while exposing them to grid interconnection tariff revisions.
Pricing Analysis
Direct-to-utility power purchase agreements dominate transaction structures, bypassing distributor markups entirely. Price differentiation hinges on resource temperature grade and PLN creditworthiness tier, with high-enthalpy volcanic arc projects commanding baseload premiums against intermittent renewable competition. Cost compression in binary cycle segments is intensifying because standardized working fluid systems displace custom engineering. Industrial thermal offtakers in Luzon manufacturing corridors exhibit highest price sensitivity, while Japanese onsen-adjacent developers absorbing METI feed-in tariffs show lowest.
Supply Chain Analysis
Refurbishment flows for turbine rotors and generator stators concentrate service revenue in Japan and South Korea, where OEM technical capabilities support extended asset life. Manufacturing of high-pressure drilling equipment draws from Japan, Germany, and the United States, with forged wellhead components resting on alloy steel supply from specialty mills. Single-source vulnerability concentrates in high-enthalpy turbine-generator sets where Toshiba and Mitsubishi Heavy Industries anchor regional availability. Distribution runs through engineering-procurement-construction contractors delivering turnkey plants to Indonesian state utility and Philippine independent power producer offtakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific geothermal energy market compounds steadily as baseload procurement rebalances away from intermittent renewable exposure across Southeast Asian grids. Utility procurement officers prioritize dispatch reliability, creating durable demand for confirmed hydrothermal resources.
For Market Incumbents: Lock in priority licensing positions across Sulawesi and Maluku volcanic arcs before competing land use escalates. Secure long-term power purchase agreement extensions with PLN and Philippine distribution utilities ahead of feed-in tariff renegotiation cycles. Vertical integration into carbon credit monetization improves debt service coverage ratios as Indonesia's Ministry of Energy and Mineral Resources integrates licensing with eligibility frameworks.
For New Entrants and Emerging Players: Capture direct use thermal supply contracts in Luzon manufacturing corridors where food processing and textile clusters aggregate demand through multi-site master service agreements. Target lower-temperature binary cycle deployments in Japanese onsen-adjacent regions where METI purchase guarantees improve project financeability despite surface access complexity. Lead with industrial process heat specialization rather than competing head-to-head with integrated electricity generators.
For Investors and Strategic Acquirers: Consolidation pressure builds where exploration capital intensity and geoscientist talent scarcity strand sub-scale developers with licensed but undeveloped fields. Position portfolios for five-to-ten year holding periods that capture full reservoir development cycles and multiple tariff renewal negotiations. Monitor PLN procurement rebalancing announcements and Philippine industrial heat aggregation trends as early signals of contract structure inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Expands baseload supply to PLN and Philippine utilities facing grid stability constraints. |
| Power Purchase Agreement | Locks in twenty-to-thirty year revenue visibility under creditworthy state utility offtake. |
| Technology Licensing | Transmits binary cycle expertise to lower-temperature fields previously deemed marginal. |
| Vertical Integration into Exploration | Captures upstream resource confirmation value that underwrites project finance structures. |
| Green Certification Program | Qualifies projects for Indonesia's integrated carbon credit eligibility frameworks. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with utility planning officers, IPP project developers, EPC contractors, and geothermal reservoir engineers with secondary validation. Primary fieldwork drew from IEA geothermal reports, Indonesia's Ministry of Energy and Mineral Resources licensing databases, Philippine Energy Regulatory Commission filings, and METI feed-in tariff disclosure documents. Bottom-up project pipeline aggregation and top-down regulatory framework assessment provided cross-verification.
Segment-weighting approaches distributed value and volume across resource type, installation configuration, power generation method, and end user sector dimensions. Growth trajectories were derived from capacity addition run-rates, licensing velocity indicators, and procurement announcement tracking across the projection horizon. Modeled inputs incorporated drilling cost inflation indices, turbine equipment lead time assumptions, and carbon credit price sensitivity ranges.
Regulatory framework revisions, exploration success rate variability, and grid interconnection standard harmonization are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding PLN procurement rebalancing velocity and METI tariff continuity. Practitioners should monitor licensing timeline compression indicators and industrial heat aggregation contract announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geothermal Energy
Philippines Geothermal Energy Market
Geothermal Energy
Denmark Geothermal Energy Market
Geothermal Energy
Global Geothermal Heat Pumps Market
Geothermal Energy
Sweden Geothermal Energy Market
Geothermal Energy
Geothermal Power Infrastructure and Components Market
Geothermal Energy
Geothermal Energy Market
Geothermal Energy
Indonesia Geothermal Energy Market
Geothermal Energy
Geothermal Power Generation Market
Geothermal Energy
Enhanced Geothermal System Market
Geothermal Energy
US Geothermal Heat Pump Market
Geothermal Energy
Geothermal Power Infrastructure Market
Geothermal Energy
Netherlands Geothermal Energy Market
Geothermal Energy
United Kingdom Geothermal Energy Market
Geothermal Energy
Geothermal Power Market
Geothermal Energy
Hungary Geothermal Energy Market