
 Sweden Geothermal Energy Market | 2026-2036
Sweden Geothermal Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Geothermal Energy Market Analytics
Swedish geothermal developers is broadening installed capacity across southern county networks. Climeon AB leverages modular low-temperature power technology for distributed deployment. MalmbergGruppen AB anchors drilling and plant construction competence in domestic project pipelines. NIBE Industrier AB dominates residential ground-source heat pump manufacturing for Nordic climate loads.
Sweden geothermal energy encompasses subsurface heat extraction from bedrock and aquifers at depths from 100 to 6,000 meters, using binary-cycle turbines or heat exchangers to deliver thermal or electric output for district heating and industrial processes. Ground source heat pumps occupy the largest installed base due to decades of residential penetration and mature drilling supply chains. Enhanced Geothermal Systems represent the fastest-growing technology segment as developers target deeper crystalline formations for power generation. District Heating commands the dominant application share through municipal utility procurement and established pipe infrastructure.
The Swedish Energy Agency and Svenska Kraftnät shape project economics through heat pump subsidies and grid connection standards for renewable power. Boverket building codes mandate renewable heat shares in new construction, directing residential and commercial end users toward geothermal compliance. Environmental permitting under the Swedish Environmental Code governs drilling impact assessments and groundwater protection requirements. Stakeholders must monitor feed-in tariff revisions and municipal heat planning cycles to time capacity commitments.
Market Dynamics
Swedish geothermal deployment pivots on the tension between mature ground-source heat pump saturation in residential suburbs and emerging Enhanced Geothermal Systems targeting deep crystalline bedrock for district heating feedstock expansion.
Growth Catalysts
- Boverket Building Codes:Mandated renewable heat shares in new construction direct developers toward geothermal compliance, locking in project pipelines across Stockholm and Malmö metropolitan zones.
- Swedish Energy Agency Subsidies:Heat pump installation grants reduce payback periods for residential retrofits, sustaining replacement cycles in Västra Götaland County's established drilling corridors.
- District Heating Network Expansion:Municipal utilities in southern Sweden integrate geothermal feedstock into legacy pipe infrastructure, diversifying baseload away from biomass and waste heat.
Market Restraints
- Drilling Cost Volatility:Steel casing and bentonite prices fluctuate with Nordic construction cycles, compressing project margins for deep boreholes exceeding 3,000 meters.
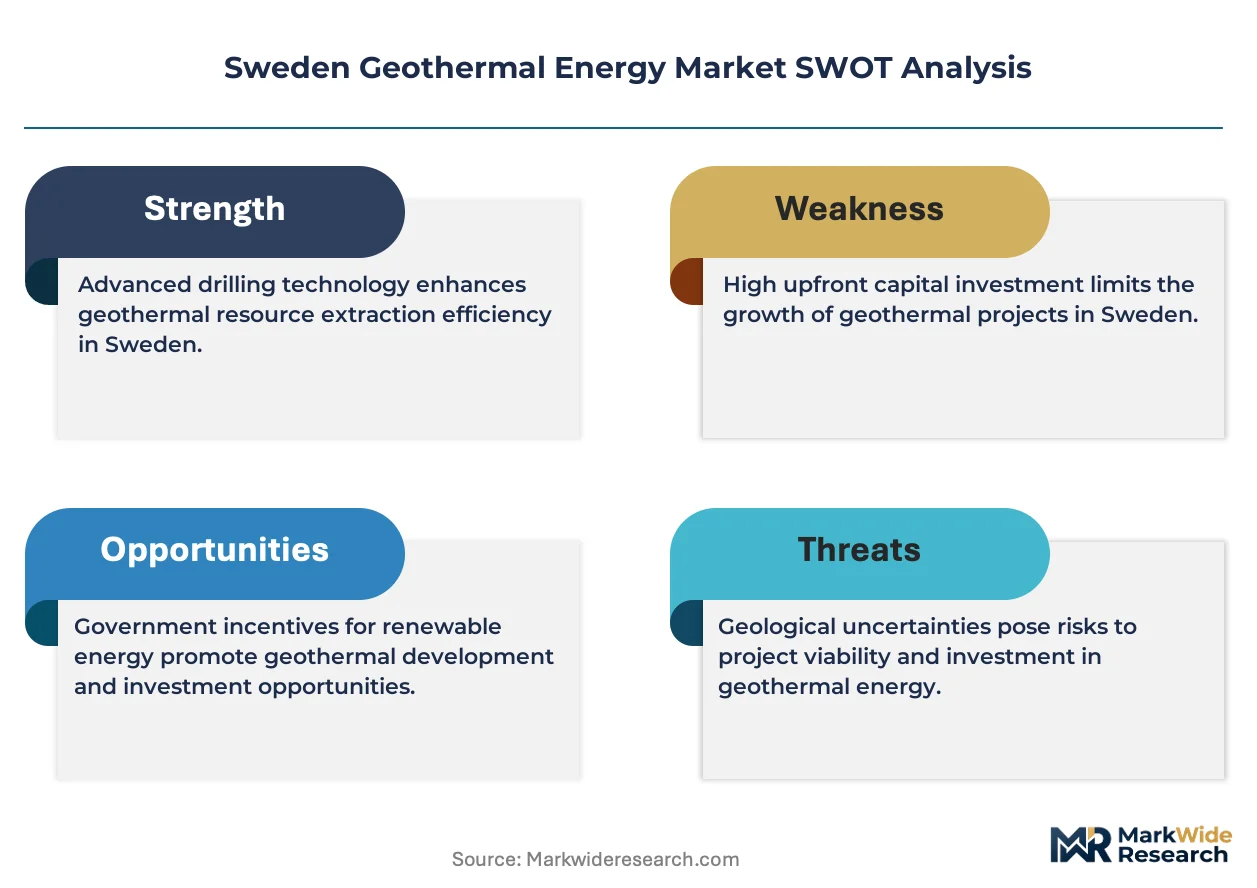
- Crystalline Formation Uncertainty:Enhanced Geothermal Systems face permeability unpredictability in Swedish bedrock, requiring costly stimulation testing before commercial commitment.
- Groundwater Protection Friction:Swedish Environmental Code permitting mandates extensive hydrogeological impact assessments, extending pre-construction timelines by 18-24 months in sensitive aquifer zones.
Strategic Opportunities
- Industrial Process Heat:Pulp and paper mills in Norrland seek geothermal substitution for fossil thermal inputs, opening megawatt-scale direct-use contracts outside district heating tariffs.
- Binary-Cycle Convergence:Low-temperature power modules paired with existing district heating return lines enable distributed electricity generation from sub-100°C brine.
- Municipal Heat Planning Cycles:Svenska Kraftnät grid connection standards revisions create procurement windows for developers timing capacity commitments to 2027-2028 network investment waves.
Industry Challenges
- Deep Drilling Specialist Scarcity:Competent crews for crystalline bedrock penetration above 4,000 meters concentrate in Västra Götaland, creating bottleneck risk for simultaneous project execution.
- Legacy System Integration:District heating networks built for high-temperature fossil inputs require heat exchanger retrofits to accommodate lower geothermal delivery temperatures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Geothermal Energy Market |
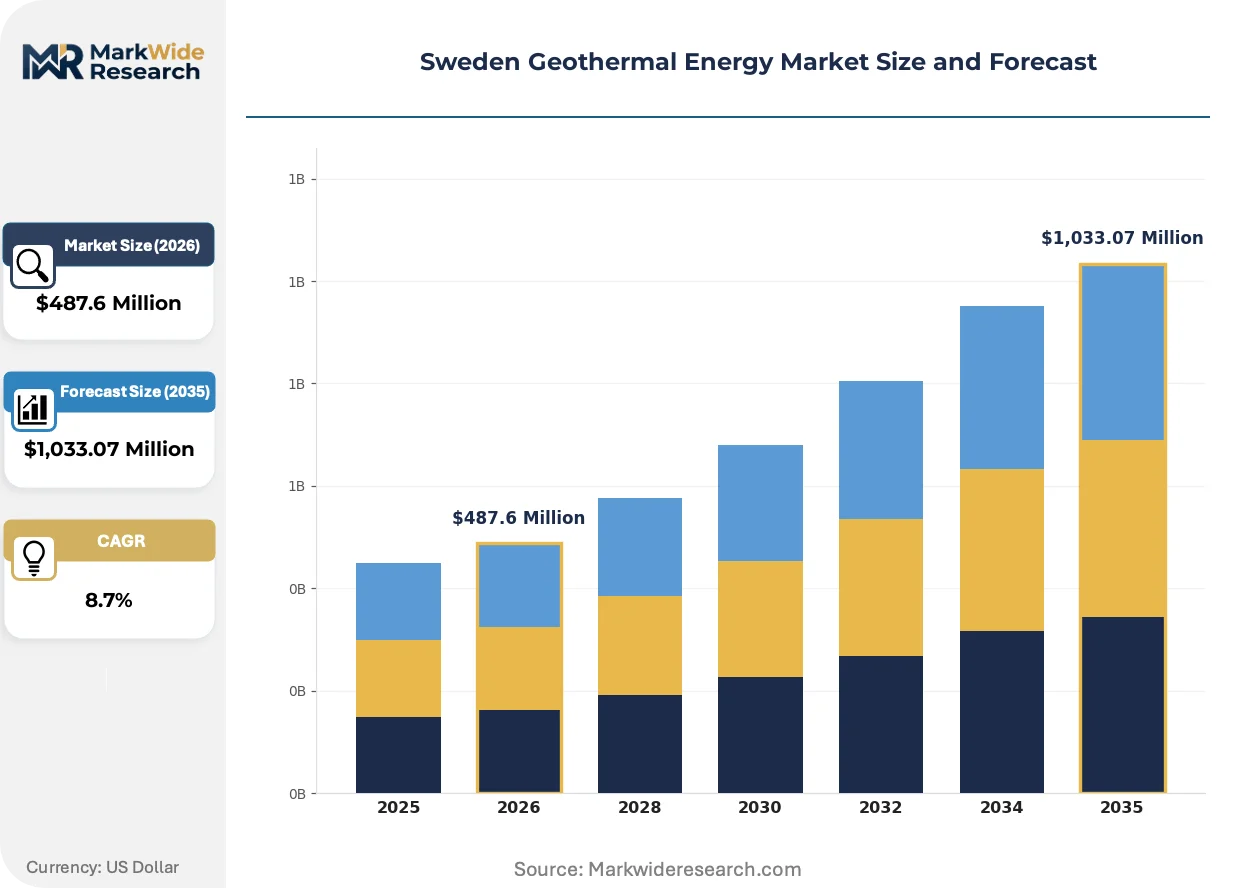
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: District Heating, Power Generation, Greenhouse Heating, Industrial Process Heating Technology: Enhanced Geothermal Systems, Ground Source Heat Pumps, Hydrothermal Technology, co-production End User: Residential, Commercial, Agricultural, Industrial Service Type: Consulting, Installation, Maintenance, Operation |
| Companies Covered | WSP Global Inc., Climeon AB, Baseload Capital AB, MalmbergGruppen AB, Rototec AB, Mincon Group Plc, E.ON SE, NIBE Industrier AB, Thermia AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Geothermal Energy Market Evolving Landscape
Modular low-temperature power technology and binary-cycle system refinement are compressing the viable depth-to-output ratio, enabling distributed deployment across Sweden's fragmented subsurface geology.
Closed-loop heat exchanger designs are consolidating as the preferred architecture for residential and light commercial ground-source installations. These systems eliminate groundwater interaction entirely, reducing Swedish Environmental Code compliance burden while shortening permitting timelines. Installers in Skåne County report 40% faster project completion versus open-loop alternatives.
The Swedish Energy Agency's revised heat pump subsidy tiers now weight system efficiency coefficients more heavily than capital cost, redirecting manufacturer R&D toward variable-speed compressors and smart grid integration. This recalibration favors Nordic climate-optimized equipment over generic European imports in public procurement.
Buyers in Stockholm's municipal housing associations now aggregate retrofit demand through cooperative procurement platforms, compressing vendor margins while securing volume pricing and standardized installation protocols. This collective purchasing model has migrated to Malmö and Gothenburg, displacing individual household contracting in multi-unit residential segments.
Sweden Geothermal Energy Market Segmentation
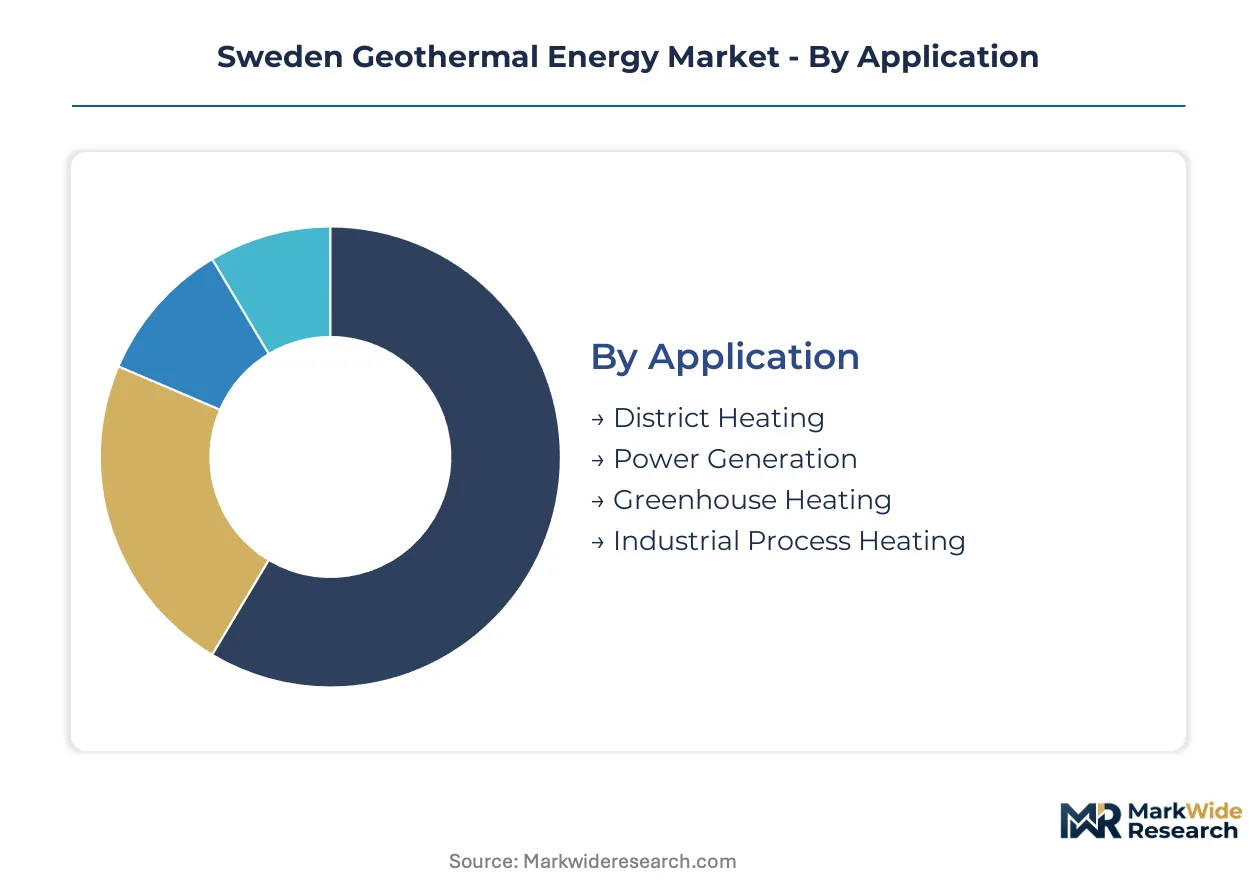
Swedish geothermal deployment fragments across distinct technical and commercial layers. Each segment carries unique regulatory exposure and capital intensity profiles that shape procurement patterns across municipal utilities and private developers.
Application:
Customization intensity varies sharply across this category, with standardized district heating contracts contrasting against bespoke industrial heat integration projects requiring site-specific engineering.
- District Heating:Municipal utilities in Stockholm and Malmö procure geothermal feedstock through long-term power purchase agreements tied to existing pipe infrastructure. Boverket renewable heat mandates lock in baseline demand volumes across southern county networks.
- Power Generation:Binary-cycle turbines extract electricity from sub-100°C brine through modular low-temperature modules. Climeon AB technology deployments concentrate around Västra Götaland County where crystalline formation depth permits viable flow rates.
- Greenhouse Heating:Controlled-environment agriculture in Skåne County leverages stable geothermal temperatures for year-round crop production. Operators favor direct-use heat exchangers over electricity conversion to preserve thermal efficiency.
- Industrial Process Heating:Pulp and paper mills in Norrland substitute geothermal for fossil thermal inputs in drying and chemical recovery processes. Megawatt-scale contracts sit outside standard district heating tariff structures.
Leading the category by volume: District Heating. Expanding most quickly: Industrial Process Heating.
Technology:
Cost tier separation dominates here, with mature shallow drilling technologies commanding low capital thresholds while deep crystalline penetration requires specialist equipment and extended payback horizons.
- Ground Source Heat Pumps:Closed-loop heat exchanger designs eliminate groundwater interaction entirely, compressing Swedish Environmental Code permitting timelines by 40% versus open-loop alternatives in Skåne County residential corridors.
- Enhanced Geothermal Systems:Deep boreholes penetrating 4,000+ meters into crystalline bedrock target permeability stimulation for power-grade output. Drilling crew scarcity in Västra Götaland creates execution bottlenecks for simultaneous project ramps.
- Hydrothermal Technology:Natural aquifer exploitation at 100-500 meter depths serves light commercial and agricultural direct-use applications. Svenska Kraftnät grid connection standards govern electricity export from viable hydrothermal sites.
- Co-production:Simultaneous oil or gas extraction with geothermal heat recovery remains nascent in Sweden's limited petroleum provinces. Technical feasibility studies concentrate on legacy Scanian Basin wellbores.
Dominating by installed base: Ground Source Heat Pumps. Steepest expansion trajectory: Enhanced Geothermal Systems.
End User:
Customer type fragmentation creates divergent procurement behaviors, from individual household retrofits to aggregated municipal housing association tenders.
- Residential:Single-family and multi-unit buildings in Stockholm's municipal housing associations now deploy cooperative procurement platforms. Volume pricing compression displaces individual household contracting across metropolitan zones.
- Commercial:Office and retail developers face Boverket renewable heat mandates in new construction, directing compliance toward ground-source heat pump specification.
- Agricultural:Greenhouse operators and dairy facilities in southern counties favor direct-use thermal extraction over electricity generation to maximize coefficient of performance.
- Industrial:Process heat buyers negotiate bespoke contracts outside regulated district heating tariffs, with Norrland pulp mills representing the largest uncontracted demand pool.
Highest volume concentration: Residential. Gaining share fastest: Industrial.
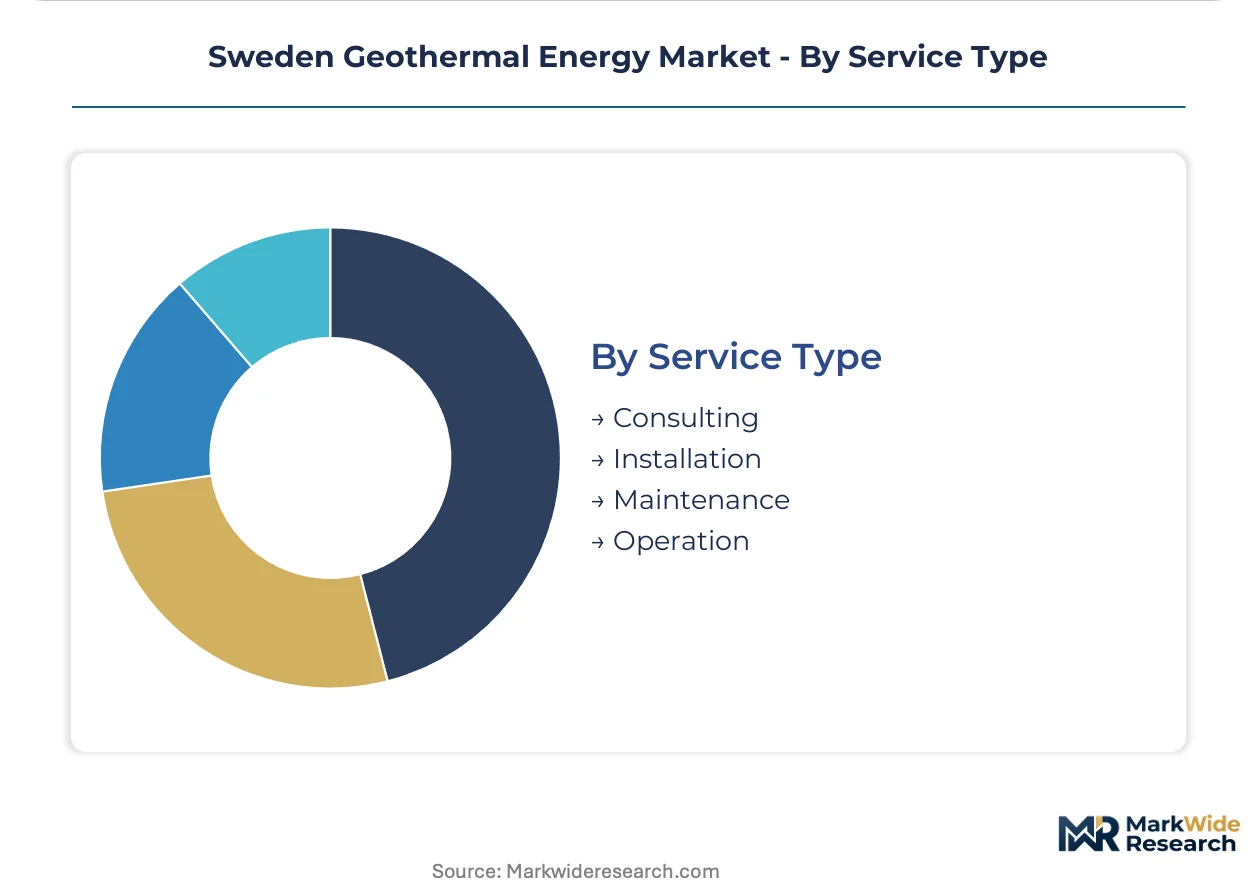
Service Type:
Margin structure varies by activity maturity, with installation services facing price pressure from standardized drilling corridors while operations command recurring revenue premiums.
- Installation:Drilling services concentrate demand around Västra Götaland County where established supply chains serve residential heat pump retrofit waves. Steel casing price volatility compresses margins on deep borehole projects.
- Maintenance:Heat pump efficiency coefficient requirements under revised Swedish Energy Agency subsidy tiers redirect service contracts toward variable-speed compressor optimization and smart grid integration protocols.
- Consulting:Hydrogeological impact assessments for Swedish Environmental Code compliance extend pre-construction timelines by 18-24 months in sensitive aquifer zones, creating specialized advisory demand.
- Operation:District heating utilities assume long-term geothermal plant operation through integrated procurement models, capturing lifecycle value beyond equipment supply.
Largest revenue pool: Installation. Fastest margin expansion: Operation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crystalline bedrock formations across southern Sweden anchor geothermal extraction economics. Västra Götaland County drilling corridors concentrate specialist contractor capacity. Stockholm and Malmö metropolitan zones drive district heating network integration demand.
Västra Götaland County
Deep borehole projects targeting 4,000+ meter crystalline penetration concentrate drilling service demand here. The Swedish Environmental Code governs groundwater protection assessments for aquifer-sensitive zones. Gothenburg anchors the region's geothermal plant construction pipeline alongside established residential heat pump retrofit corridors.
Stockholm County
Municipal housing associations aggregate cooperative procurement for multi-unit residential retrofits. Boverket building codes mandate renewable heat shares in new construction across metropolitan development zones. The city district heating utility integrates geothermal feedstock into legacy pipe infrastructure serving suburban expansion corridors.
Skåne County
Greenhouse operators leverage direct-use thermal extraction for year-round controlled-environment agriculture. Closed-loop heat exchanger designs compress permitting timelines by eliminating groundwater interaction entirely. Malmö anchors southern Sweden's district heating network expansion with geothermal baseload diversification from biomass dependence.
Norrland Region
Pulp and paper mills seek megawatt-scale geothermal substitution for fossil thermal inputs in drying processes. Industrial process heat contracts sit outside standard district heating tariff structures. The region represents the largest uncontracted demand pool for bespoke geothermal direct-use applications.
Sweden Geothermal Energy Market Competitive Landscape
Global majors compete with regional champions across drilling technology and power generation equipment. The market structure tilts toward specialized Nordic engineering firms with crystalline bedrock expertise rather than integrated energy conglomerates. Three archetypes dominate: modular low-temperature power technology developers, residential heat pump manufacturers, and deep drilling service contractors. Capacity expansion and technology licensing represent the primary competitive moves as players position for municipal heat planning cycle procurement windows.
Within the Nordic specialist tier, Climeon AB and MalmbergGruppen AB exemplify distinct archetypes. Climeon represents modular power technology developers targeting distributed deployment from sub-100°C brine. MalmbergGruppen anchors drilling and plant construction competence for domestic project pipelines. NIBE Industrier occupies the residential equipment manufacturing position, supplying climate-optimized ground-source heat pumps for Nordic loads. These three illustrate how Swedish geothermal competition fragments across technology layers rather than consolidating vertically.
| Leading Market Players |
|---|
| WSP Global Inc. |
| Climeon AB |
| Baseload Capital AB |
| MalmbergGruppen AB |
| Rototec AB |
| Mincon Group Plc |
| E.ON SE |
| NIBE Industrier AB |
| Thermia AB |
| Others |
Value Network & Pricing Analysis
Modular low-temperature power technology deployment is compressing viable depth-to-output ratios while simultaneously concentrating procurement around Västra Götaland County drilling corridors. This technological shift tightens margins for shallow residential heat pump installers even as deep crystalline projects command premium pricing from municipal utilities.
Pricing Analysis
Warranty and maintenance bundling separates district heating utility contracts from unbundled residential retrofit quotes. Project-based long-term offtake agreements dominate municipal procurement, while transactional per-unit sales govern household ground-source heat pump purchases. Price differentiation rests on drilling depth certification and after-sales service coverage, with Stockholm housing associations least sensitive due to cooperative volume aggregation. Cost compression in shallow residential installations is intensifying because standardized closed-loop designs displace customized open-loop engineering.
Supply Chain Analysis
CE marking and Boverket compliance certification gate entry for heat pump manufacturers serving Swedish residential markets. Steel casing draws from Germany and China, while bentonite drilling fluids source from Norway and Denmark. Single-source vulnerability concentrates in Västra Götaland deep drilling crews for crystalline bedrock penetration above 4,000 meters. Distribution runs through municipal utility procurement platforms for district heating integration and specialized HVAC contractors for residential retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deep drilling specialist scarcity props pricing power for crystalline bedrock projects, creating a supply-constrained market structure where capacity bottlenecks in Västra Götaland determine project execution timelines.
For Market Incumbents: To counter emerging modular power technology entrants from distributed energy segments, anchor drilling competence through backward integration into specialist crew training programs in Västra Götaland. Secure long-term steel casing supply agreements with Nordic mills to offset commodity volatility compression on deep borehole margins. For New Entrants and Emerging Players: Digital-channel cooperative procurement platforms offer the lowest-friction route to aggregate residential demand in Stockholm and Malmö municipal housing associations. Target industrial process heat in Norrland pulp mills as the most penetrable segment outside regulated district heating tariffs, leveraging direct-use thermal contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to Nordic engineering conglomerates seeking crystalline bedrock competence. Five-to-ten year viability hinges on Enhanced Geothermal Systems proving commercial flow rates. Watch Swedish Energy Agency subsidy tier revisions as the signal for inflection in residential heat pump replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Deep Drilling Capacity Expansion | Västra Götaland crew additions unlock crystalline bedrock project execution bottlenecks. |
| Closed-Loop Heat Exchanger Certification | Boverket compliance accelerates Swedish Environmental Code permitting timelines. |
| Municipal Utility Partnership | Stockholm district heating integration secures long-term offtake baseload contracts. |
| Industrial Process Heat Contracting | Norrland pulp mill direct-use agreements bypass regulated district heating tariffs. |
| Binary-Cycle Technology Licensing | Climeon AB modular deployment enables distributed sub-100°C brine electricity generation. |
Research Methodology
Document review covered Swedish Energy Agency subsidy filings, Boverket building code mandates, and Svenska Kraftnät grid connection standards, complemented by interviews with utility planning officers, EPC contractors, drilling service managers, and municipal procurement leads. Secondary validation drew from project development databases, environmental permitting records under the Swedish Environmental Code, and district heating network investment disclosures. Bottom-up installation volume estimates and top-down market value triangulation anchored the analytical framework.
Installed capacity and revenue outputs were derived through segmentation modeling across technology type, application, end user, and service category dimensions throughout the forecast period. CAGRs were computed from year-over-year growth trajectories applied to base-year market sizing. Forecast inputs incorporated Boverket renewable heat mandate compliance schedules and Swedish Energy Agency subsidy tier efficiency weightings.
The model holds under stable regulatory subsidy frameworks and continued crystalline formation permeability testing success; deviation in drilling cost volatility or groundwater protection enforcement intensity would shift project economics. A model refresh is warranted upon material change in municipal heat planning cycle procurement windows or feed-in tariff revision timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geothermal Energy
Global Geothermal Heat Pumps Market
Geothermal Energy
Enhanced Geothermal System Market
Geothermal Energy
Geothermal Power Infrastructure and Components Market
Geothermal Energy
Netherlands Geothermal Energy Market
Geothermal Energy
Indonesia Geothermal Energy Market
Geothermal Energy
Geothermal Energy Market
Geothermal Energy
Geothermal Power Market
Geothermal Energy
Hungary Geothermal Energy Market
Geothermal Energy
US Geothermal Heat Pump Market
Geothermal Energy
Geothermal Power Generation Market
Geothermal Energy
Asia-Pacific Geothermal Energy Market
Geothermal Energy
Geothermal Power Infrastructure Market
Geothermal Energy
United Kingdom Geothermal Energy Market
Geothermal Energy
Philippines Geothermal Energy Market
Geothermal Energy
Denmark Geothermal Energy Market