
 Geothermal Power Market | 2026-2036
Geothermal Power Market Size, Share, and Industry Trends Forecast 2026-2036
Geothermal Power Market Intelligence
A capital-intensity divergence between integrated developers and equipment suppliers is redrawing competitive boundaries in geothermal power. Ormat Technologies leverages vertical integration across project development, plant construction, and long-term operations to sustain margin capture across the full value chain. Mitsubishi Heavy Industries anchors its position through specialized turbine manufacturing scale for high-enthalpy flash steam installations. SLB competes by extending its drilling and subsurface analytics capabilities from oilfield services into enhanced geothermal systems development.
Geothermal power harnesses heat from the Earth's crust through wells tapping hydrothermal reservoirs at temperatures ranging from 150°C to 370°C, converting thermal energy to electricity via steam-driven turbines or binary working-fluid cycles. Its primary purpose is dispatchable baseload renewable generation with capacity factors exceeding 90%, distinct from intermittent wind and solar alternatives. Binary cycle technology dominates new installations where moderate-temperature resources prevail, while flash steam retains leadership in high-temperature volcanic zones such as Iceland and the Philippines. Enhanced geothermal systems represent the fastest-growing technology segment as hydraulic stimulation and directional drilling unlock hot dry rock formations previously uneconomic to exploit.
The US Federal Energy Regulatory Commission governs grid interconnection standards for geothermal plants, while the Environmental Protection Agency regulates geothermal brine reinjection under the Safe Drinking Water Act UIC program. Indonesia's Ministry of Energy and Mineral Resources sets feed-in tariff ceilings through MEMR Regulation No. 12/2017, directly shaping project bankability across the archipelago. Stakeholders must monitor permitting velocity for exploratory drilling rights, as lease approval timelines remain the critical bottleneck separating resource identification from commercial operation.
Market Dynamics
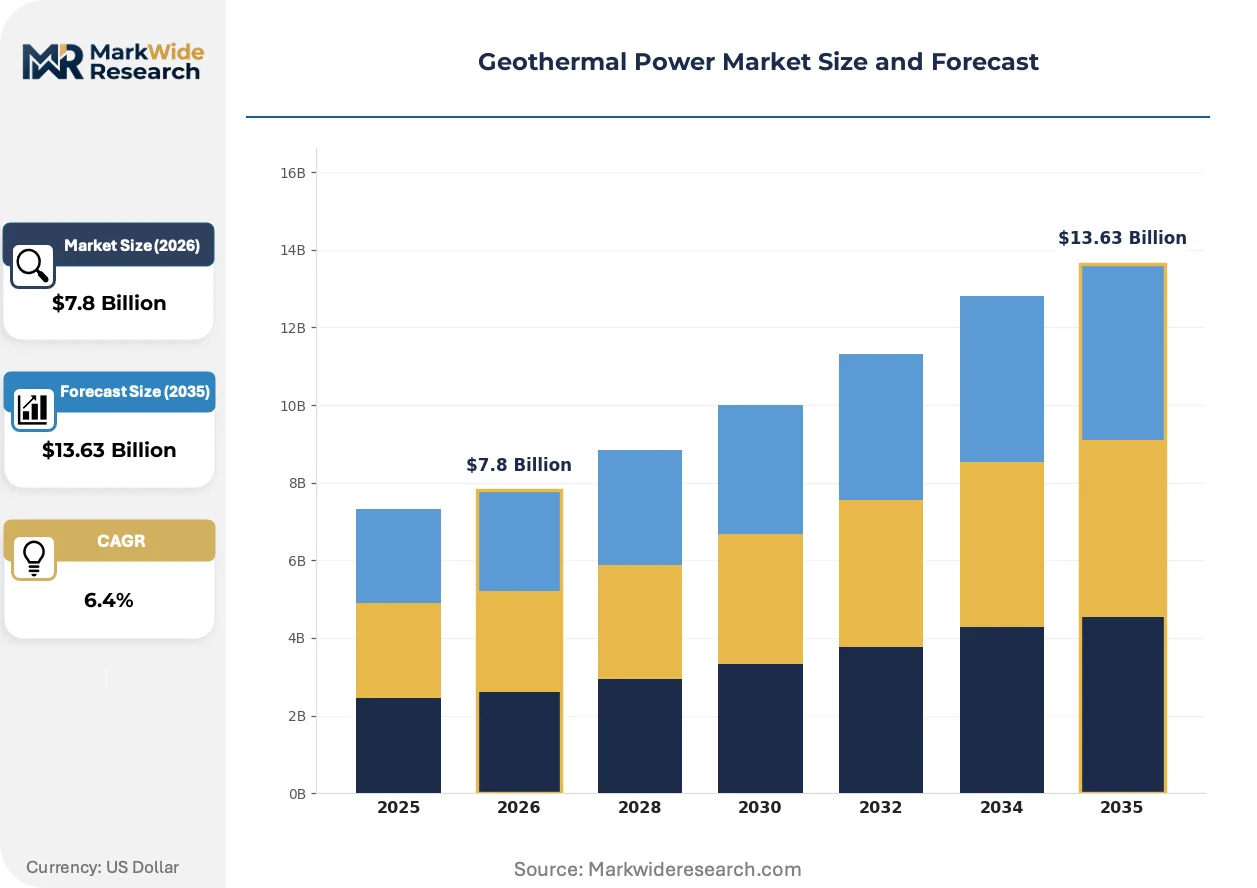
The US Inflation Reduction Act production tax credits are compressing project development timelines and redrawing developer economics, while enhanced geothermal systems technology unlocks hot dry rock formations previously beyond commercial reach.
Growth Catalysts
- Production Tax Credits:The US IRA's 30% investment tax credit and production tax credit extensions improve project IRRs sufficiently to move marginal resources into development queues.
- Industrial Baseload Contracts:Food processing and pulp and paper end users are signing long-term power purchase agreements to lock in dispatchable renewable supply against volatile natural gas benchmarks.
- Binary Cycle Technology:Closed-loop binary plants operating at 150-180°C are opening moderate-temperature sedimentary basins in Germany, France, and the Netherlands to commercial exploitation.
Market Restraints
- Exploratory Drilling Costs:Dry hole risk in greenfield geothermal development requires $5-15 million per exploratory well with no guaranteed resource confirmation.
- Permitting Velocity:US Bureau of Land Management lease approval timelines stretch 5-7 years from nomination to drilling rights, creating capital lockup that deters portfolio investors.
- Interconnection Queue Congestion:Federal Energy Regulatory Commission interconnection study backlogs delay grid connection for otherwise ready-to-build projects in Western states.
Strategic Opportunities
- Enhanced Geothermal Systems:Hydraulic stimulation and directional drilling adapted from oilfield services enable resource extraction from hot dry rock in regions lacking natural hydrothermal circulation.
- Indonesia's Volcanic Corridor:State utility PLN holds priority offtake agreements across Sumatra, Java, and Sulawesi, creating de-risked revenue streams for developers willing to navigate local partnership structures.
- Binary-District Heating Hybrids:Cascading thermal use from power generation to district heating networks maximizes exergy extraction in European sedimentary basins.
Industry Challenges
- Subsurface Characterization Expertise:Reservoir engineering talent trained specifically in geothermal temperature-pressure regimes remains concentrated in Iceland, New Zealand, and select US universities.
- Brine Chemistry Management:Scaling and corrosion from aggressive geothermal fluids requires specialized metallurgy and continuous monitoring that extends OPEX beyond initial projections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geothermal Power Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Enhanced Geothermal Systems, Flash Steam, Binary Cycle, Dry Steam Application: Electricity Generation, Direct Heating, Water Heating, District Heating End User: Residential, Commercial, Industrial, Government Installation Type: Onshore, Offshore, Ground Source, Deep Aquifer |
| Companies Covered | Ormat Technologies, Mitsubishi Heavy Industries, SLB, Turboden S.p.A., TAS Energy, Atlas Copco Group, Exergy, General Electric, Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geothermal Power Market Strategic Shifts & Innovations
Technology trajectories in geothermal power center on unlocking previously inaccessible resources while regulatory frameworks accelerate deployment timelines through financial engineering rather than technical mandate alone.
Closed-loop advanced geothermal systems are supplanting traditional hydrothermal dependency by eliminating the need for natural water-bearing formations. Developers including Eavor Technologies and Fervo Energy are deploying closed-loop horizontal well architectures that circulate working fluid through engineered fractures, enabling project siting in Texas, Utah, and Nevada sedimentary basins devoid of conventional geothermal indicators. This technology is compressing the addressable resource base from volcanic corridors to any region with adequate thermal gradient and drilling access.
The US Inflation Reduction Act's 48E clean electricity production credit extends through 2032 with full value contingent on prevailing wage and apprenticeship requirements. Project sponsors must now structure engineering-procurement-construction contracts to qualify for the maximum 30% investment tax credit, reshaping contractor selection criteria toward unionized labor capacity. Western US developers are responding by front-loading community benefit agreements to secure local permitting support.
Corporate offtakers are bypassing traditional utility intermediaries to contract directly with geothermal developers for 24/7 carbon-free energy. Data center operators in Arizona and Nevada are negotiating sleeved power purchase agreements that attribute specific generation assets to facility load rather than purchasing renewable energy credits. This behavior is most visible in hyperscale cloud computing, where Microsoft and Google have established 100% renewable targets that intermittent wind and solar cannot satisfy without massive overbuild and storage.
Geothermal Power Market Segmentation
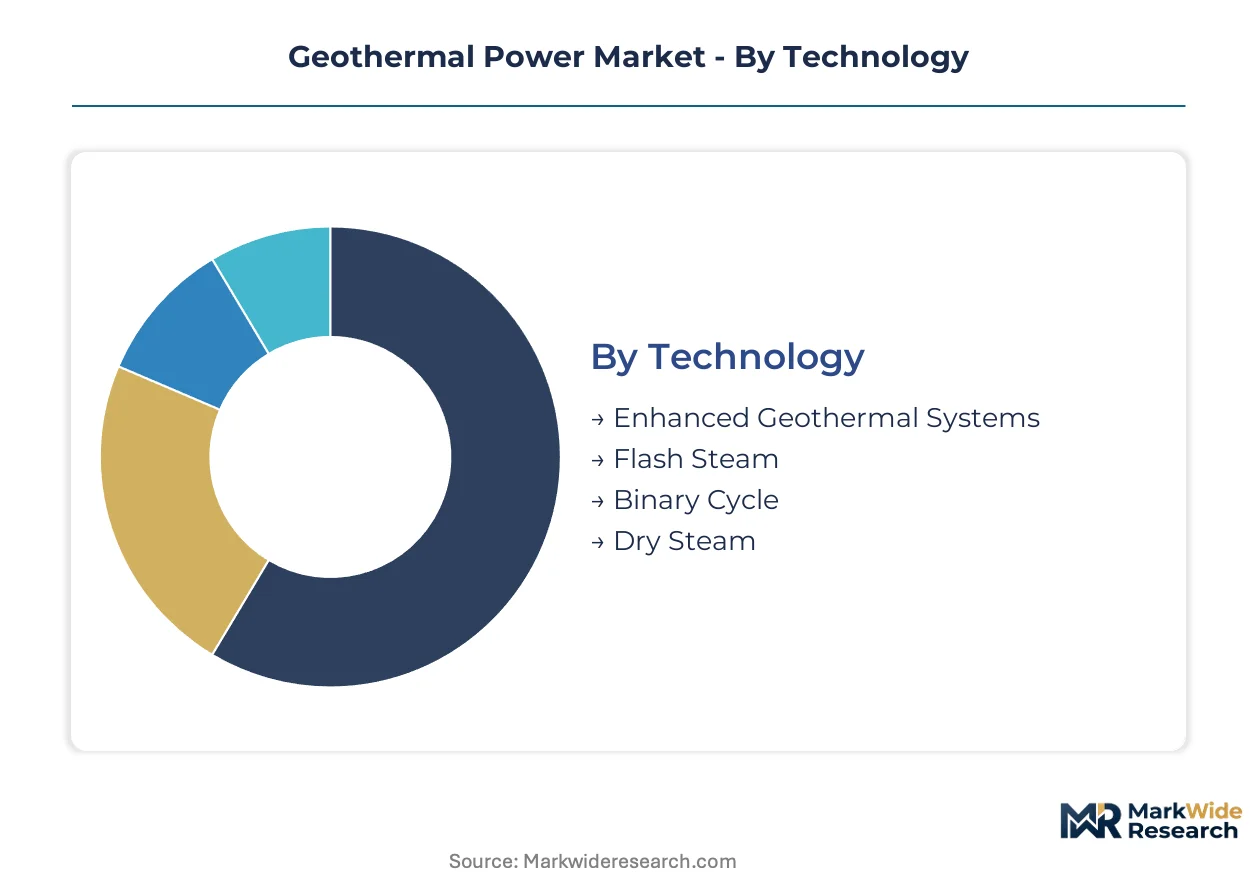
Technology choices determine capital intensity and resource access for geothermal developers. Application focus shapes regulatory pathways and offtake contract structures. End user targeting drives financing models and project scale economics.
Technology:
Flash steam and binary cycle plants flow through utility-scale EPC contractors with established turbine supply chains, while enhanced geothermal systems reach developers via oilfield services partnerships repurposing drilling assets.
- Enhanced Geothermal Systems:Hydraulic stimulation and directional drilling unlock hot dry rock formations lacking natural hydrothermal circulation. Developers in Utah and Texas sedimentary basins are deploying closed-loop horizontal architectures that eliminate dry hole risk. This segment is expanding most quickly as SLB and Fervo Energy adapt oilfield techniques to geothermal temperatures.
- Flash Steam:Direct steam extraction from high-temperature reservoirs above 180°C drives turbines without heat exchangers. Indonesia's volcanic corridor and Iceland's rift zones concentrate deployment where reservoir temperatures exceed 200°C. PLN's priority offtake agreements de-risk capital commitment for flash steam developers.
- Binary Cycle:Closed-loop organic Rankine cycle plants operate at moderate temperatures using secondary working fluids. Sedimentary basins in Germany and the Netherlands favor this technology for grid-scale deployment.
- Dry Steam:Rare natural steam reservoirs at The Geysers in California and Larderello in Italy support direct turbine feeding without brine separation.
By volume, flash steam leads due to decades of installed base in volcanic zones. By growth pace, enhanced geothermal systems are ahead as hydraulic stimulation unlocks previously inaccessible resources.
Application:
Electricity generation commands premium equipment specifications and grid interconnection investment, while direct heating applications flow through municipal procurement channels with lower technical barriers.
- Electricity Generation:Grid-connected power plants above 5 MW capacity require FERC interconnection standards in the US and feed-in tariff alignment under Indonesia's MEMR Regulation No. 12/2017. Baseload contracts from food processing and pulp and paper end users are concentrating demand in Western US states.
- Direct Heating:Industrial process heat below 150°C serves greenhouses, aquaculture, and mineral drying operations. Iceland's district heating network demonstrates cascading thermal use from power generation to municipal distribution.
- Water Heating:Residential and commercial building applications utilize ground-source heat pumps with coefficient of performance advantages over conventional HVAC.
- District Heating:Urban thermal networks in Paris and Munich integrate geothermal base load with seasonal storage to displace natural gas peaking.
Electricity generation captures the largest share of capital deployment. District heating is climbing the fastest as European decarbonization mandates accelerate municipal network conversion.
End User:
Industrial offtakers negotiate long-term power purchase agreements directly with developers, bypassing utility intermediaries and reshaping revenue certainty structures.
- Industrial:Food processing and pulp and paper operations require dispatchable baseload supply to maintain continuous production schedules. Microsoft and Google data centers in Arizona and Nevada are contracting sleeved agreements attributing specific geothermal assets to facility load.
- Commercial:Hotels, hospitals, and retail chains utilize ground-source heat pumps for HVAC and water heating with payback periods sensitive to natural gas price volatility.
- Residential:Single-family ground-source installations depend on federal tax credit qualification and local installer availability.
- Government:Military bases and federal facilities prioritize energy security through islanded microgrids with geothermal anchoring renewable portfolios.
Industrial end users dominate contract value. Government procurement is gaining share fastest as defense and civilian agencies mandate carbon-free baseload under federal sustainability directives.
Installation Type:
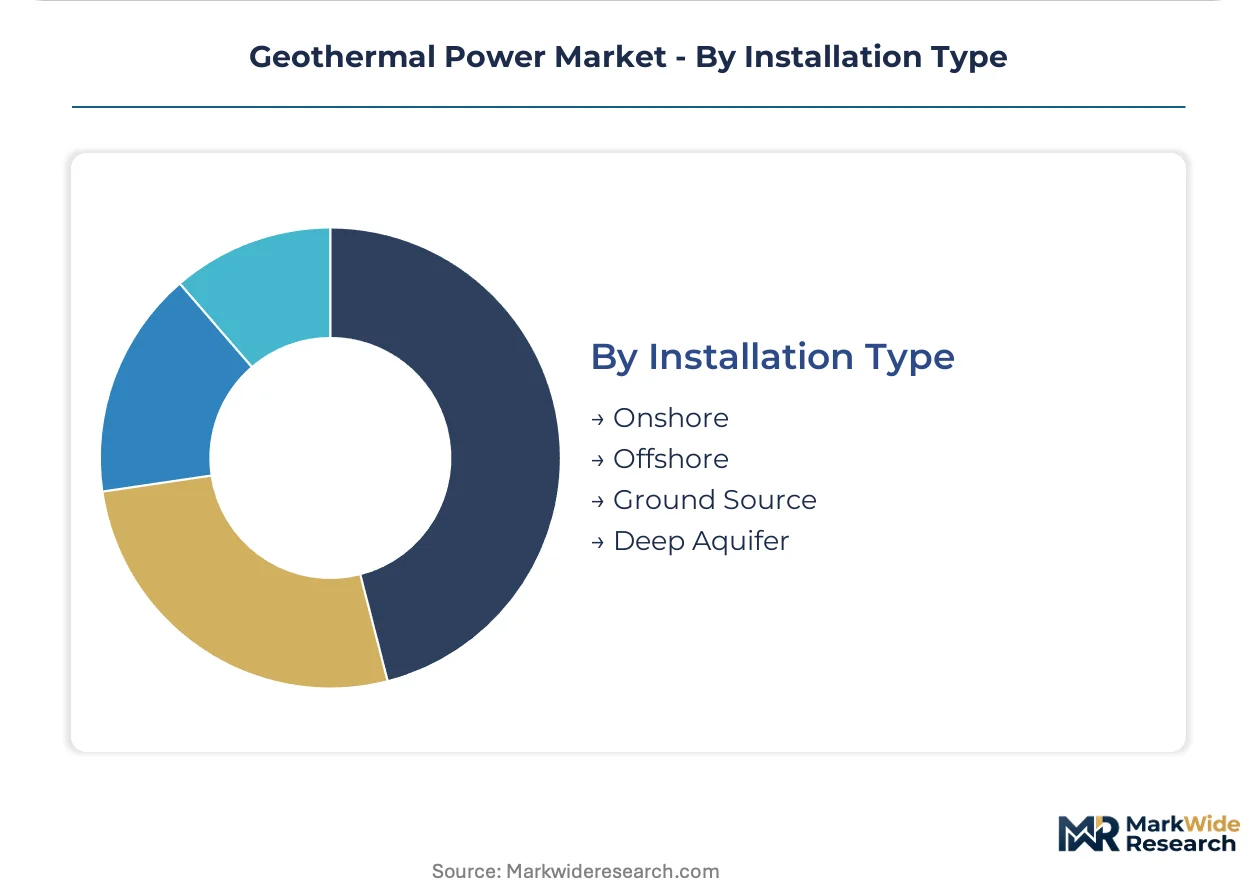
Onshore drilling accounts for nearly all operational capacity, with ground-source shallow systems reaching residential markets through HVAC contractor networks.
- Onshore:Conventional hydrothermal and enhanced geothermal projects utilize directional drilling from surface pads in Nevada, Utah, and Indonesia's Sumatra corridor. BLM lease approval timelines of 5-7 years create the primary bottleneck for greenfield development.
- Ground Source:Closed-loop vertical borefields at 100-400 meter depth serve building-scale heating and cooling with minimal surface footprint.
- Deep Aquifer:Sedimentary basin doublet systems in the Paris and Munich regions circulate brine through permeable carbonate formations for district heating supply.
- Offshore:Experimental concepts target submarine volcanic systems with no commercial deployment to date.
Onshore installations hold the entire operating fleet. Deep aquifer systems are expanding most quickly as European sedimentary basins prove commercial viability at moderate depths.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia commands project-level pricing power through PLN's priority offtake agreements, while US developers absorb permitting delays that stretch 5-7 years before drilling rights materialize. This asymmetry concentrates capital deployment in volcanic corridor markets with de-risked revenue streams.
United States
Western states host binary cycle and enhanced geothermal deployments targeting data center offtakers in Arizona and Nevada. The FERC governs grid interconnection standards while the IRA's 48E clean electricity production credit extends through 2032. The Bureau of Land Management's lease approval timelines create capital lockup that deters portfolio investors from greenfield development.
Indonesia
Sumatra, Java, and Sulawesi corridors concentrate flash steam installations above 180°C reservoir temperatures. The Ministry of Energy and Mineral Resources sets feed-in tariff ceilings through MEMR Regulation No. 12/2017. PLN's priority offtake agreements de-risk capital commitment for developers navigating local partnership structures.
Iceland
Rift zone high-temperature fields support dry steam and flash steam baseload generation with capacity factors exceeding 90%. National regulatory frameworks prioritize renewable export and aluminum smelter supply contracts. The Reykjanes Peninsula demonstrates cascading thermal use from power generation to municipal district heating networks.
Germany
Sedimentary basins in the Upper Rhine Graben and North German Plain favor binary cycle plants at 150-180°C operating temperatures. The country's national energy regulator oversees grid access for geothermal generators under renewable energy priority dispatch rules. Munich's district heating network integrates geothermal base load with seasonal thermal storage to displace natural gas peaking.
Philippines
Volcanic corridors on Luzon and Mindanao host flash steam capacity serving industrial zones and export-oriented manufacturing. The national renewable energy board administers feed-in tariff and renewable portfolio standard mechanisms. Leyte Island's geothermal cluster supplies dispatchable power to nickel processing facilities with continuous thermal demand.
Geothermal Power Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with integrated developers capturing margin across the full value chain while equipment suppliers anchor position through specialized manufacturing scale. The market structures around three tiers: vertically integrated project developers, turbine and plant equipment specialists, and oilfield services firms repurposing drilling assets. Competitive moves concentrate on strategic partnerships between technology holders and capital providers, plus portfolio diversification into enhanced geothermal systems development.
Within the integrated developer tier, Ormat Technologies occupies a position exemplifying captive supply across project development, construction, and long-term operations. Among turbine specialists, Mitsubishi Heavy Industries and Toshiba Corporation represent manufacturing scale leadership for high-enthalpy flash steam installations. At the oilfield services intersection, SLB anchors the segment extending subsurface analytics and directional drilling capabilities into enhanced geothermal systems.
| Leading Market Players |
|---|
| Ormat Technologies |
| Mitsubishi Heavy Industries |
| SLB |
| Turboden S.p.A. |
| TAS Energy |
| Atlas Copco Group |
| Exergy |
| General Electric |
| Toshiba Corporation |
| Others |
Cost & Logistics Intelligence
Binary cycle equipment substitution for flash steam turbines in moderate-temperature sedimentary basins simultaneously shifts manufacturing demand toward European and Japanese suppliers while compressing project-level capital cost structures in Germany and the Netherlands.
Pricing Analysis
The customization-premium spread between configured-to-order binary plants and standardized flash steam installations runs 15-25% above base equipment costs, with price differentiation anchored in reservoir temperature certification and grid interconnection complexity. Project-based long-term offtake contracts dominate, though spot procurement for replacement turbines occurs in Iceland and the Philippines. Cost compression in standardized binary packages is intensifying because Chinese component suppliers are entering the organic Rankine cycle heat exchanger segment. Industrial offtakers in food processing show highest price sensitivity, while data center operators in Arizona and Nevada prioritize dispatchability over unit cost.
Supply Chain Analysis
Port congestion on transpacific lanes from Japanese turbine manufacturers to US West Coast project sites has extended inbound logistics cycles for Mitsubishi Heavy Industries and Toshiba Corporation deliveries to Nevada and Utah developments. Manufacturing concentrates in Japan, Italy, and the United States for precision turbomachinery, while drilling equipment draws from Texas and Oklahoma oilfield services bases. Supply chain risk centers on single-source dependency for high-temperature corrosion-resistant alloys from Japanese metallurgical suppliers. Distribution runs through EPC contractor networks with captive installation crews rather than open merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enhanced geothermal systems technology represents a high-growth disruption trajectory, with the US Inflation Reduction Act's production tax credit extensions creating a regulatory inflection that compresses development timelines and redraws competitive economics.
For Market Incumbents: Consolidate reservoir engineering capabilities through targeted hiring from Icelandic and New Zealand technical institutes to defend against oilfield services firms repurposing directional drilling talent. Lock in long-term turbine supply agreements with Japanese manufacturers before capacity constraints emerge from competing LNG power project demand. Priority lever: captive brine chemistry management expertise to differentiate on plant availability guarantees.
For New Entrants and Emerging Players: Anchor in Indonesia's Sumatra corridor where PLN priority offtake agreements de-risk revenue streams for developers navigating local partnership structures. Target Texas and Utah sedimentary basins for closed-loop enhanced geothermal deployments using oilfield drilling contractor relationships as go-to-market channel. White space exists in binary-district heating hybrid configurations for European municipal networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed renewable IPP platforms that acquired geothermal portfolios during the 2015-2020 clean energy expansion. Long-term viability hinges on reservoir productivity sustaining across 30-year power purchase agreement tenors. Acquisition target archetype: developers with permitted drilling rights in Western US states but lacking construction capital. Signal to watch: Bureau of Land Management lease approval velocity as indicator of pipeline conversion rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Geothermal Systems Capacity Buildout | SLB and Fervo Energy deploying closed-loop architectures unlocks hot dry rock formations in Texas sedimentary basins. |
| Power Purchase Agreement Structuring | Microsoft and Google data centers in Arizona negotiate sleeved agreements attributing specific geothermal assets to facility load. |
| Technology Licensing Partnerships | Ormat Technologies licenses binary cycle designs to European developers targeting district heating networks in Munich and Paris. |
| Vertical Integration into Drilling Services | Integrated developers acquiring directional drilling capabilities reduce dependency on SLB and oilfield services pricing. |
| Green Certification Program Alignment | Project sponsors structuring engineering-procurement-construction contracts to qualify for maximum IRA investment tax credit value. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across utility planning officers, IPP project developers, EPC contractors, grid operators, and geothermal reservoir engineers. Secondary validation drew from EIA generation data, IEA renewable energy reports, FERC interconnection filings, and Indonesia MEMR regulatory gazettes. Bottom-up project pipeline aggregation triangulated against top-down macroeconomic energy demand modeling.
Across the analysis window, forecasts incorporated technology segmentation by flash steam, binary cycle, enhanced geothermal systems, and dry steam configurations. Project scale tiers, regulatory framework clusters, and regional grid interconnection types shaped the analytical framework. CAGRs derived from installed capacity build rates, capacity factor assumptions, and levelized cost trajectories. Key inputs included BLM lease approval timelines, PLN offtake contract structures, and IRA tax credit qualification pathways.
Underlying assumptions cover sustained production tax credit availability, stable geothermal reservoir productivity, and moderate drilling cost inflation, with deviation risk concentrated in permitting velocity delays and subsurface characterization uncertainty. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geothermal Energy
Global Geothermal Heat Pumps Market
Geothermal Energy
Philippines Geothermal Energy Market
Geothermal Energy
Enhanced Geothermal System Market
Geothermal Energy
Netherlands Geothermal Energy Market
Geothermal Energy
Hungary Geothermal Energy Market
Geothermal Energy
Geothermal Power Generation Market
Geothermal Energy
Denmark Geothermal Energy Market
Geothermal Energy
Geothermal Energy Market
Geothermal Energy
Geothermal Power Infrastructure and Components Market
Geothermal Energy
Geothermal Power Infrastructure Market
Geothermal Energy
Asia-Pacific Geothermal Energy Market
Geothermal Energy
United Kingdom Geothermal Energy Market
Geothermal Energy
US Geothermal Heat Pump Market
Geothermal Energy
Indonesia Geothermal Energy Market
Geothermal Energy
Sweden Geothermal Energy Market