
 Geothermal Power Infrastructure and Components Market | 2026-2036
Geothermal Power Infrastructure and Components Market Size, Share, and Industry Trends Forecast 2026-2036
Geothermal Power Infrastructure and Components Market Foresight
Geothermal drilling engineer availability is rotating toward binary cycle and EGS specializations as flash steam project pipelines mature in Indonesia and Kenya. Mitsubishi Heavy Industries leverages its turbine manufacturing scale to dominate large flash steam installations across the Pacific Ring of Fire. Ormat Technologies sustains technology leadership in binary cycle systems through proprietary air-cooled condenser designs that reduce water consumption in arid basins. Fuji Electric anchors Asian supply chains with vertically integrated production of geothermal turbines and generators.
Geothermal power infrastructure and components encompass the subsurface drilling assemblies, above-ground turbine-generator sets, heat exchangers, pumps, cooling towers, and control systems that convert underground thermal energy into electricity or direct heat, typically operating at reservoir temperatures between 150°C and 300°C and requiring corrosion-resistant alloys to withstand brine chemistry. Flash steam technology occupies the largest installed base globally due to decades of deployment in high-enthalpy volcanic zones, though Enhanced Geothermal Systems represents the fastest-growing technology segment as directional drilling and hydraulic stimulation techniques unlock hot dry rock formations previously considered uneconomic. Binary cycle equipment commands premium margins in moderate-temperature reservoirs where Organic Rankine Cycle working fluids maximize energy extraction efficiency.
The EPA enforces underground injection control permits that govern geothermal brine reinjection and protect aquifer integrity, while the EU Green Deal and F-Gas Regulation phase down fluorinated working fluids in binary cycle plants and push adoption of natural hydrocarbon refrigerants. Indonesia's MEMR and Kenya's EPRA administer feed-in tariff frameworks and resource risk guarantees that determine project bankability and equipment procurement timelines. Stakeholders must monitor permitting velocity for EGS demonstration projects and working fluid substitution timelines as regulatory chemistry constraints tighten across OECD geothermal markets.
Market Dynamics
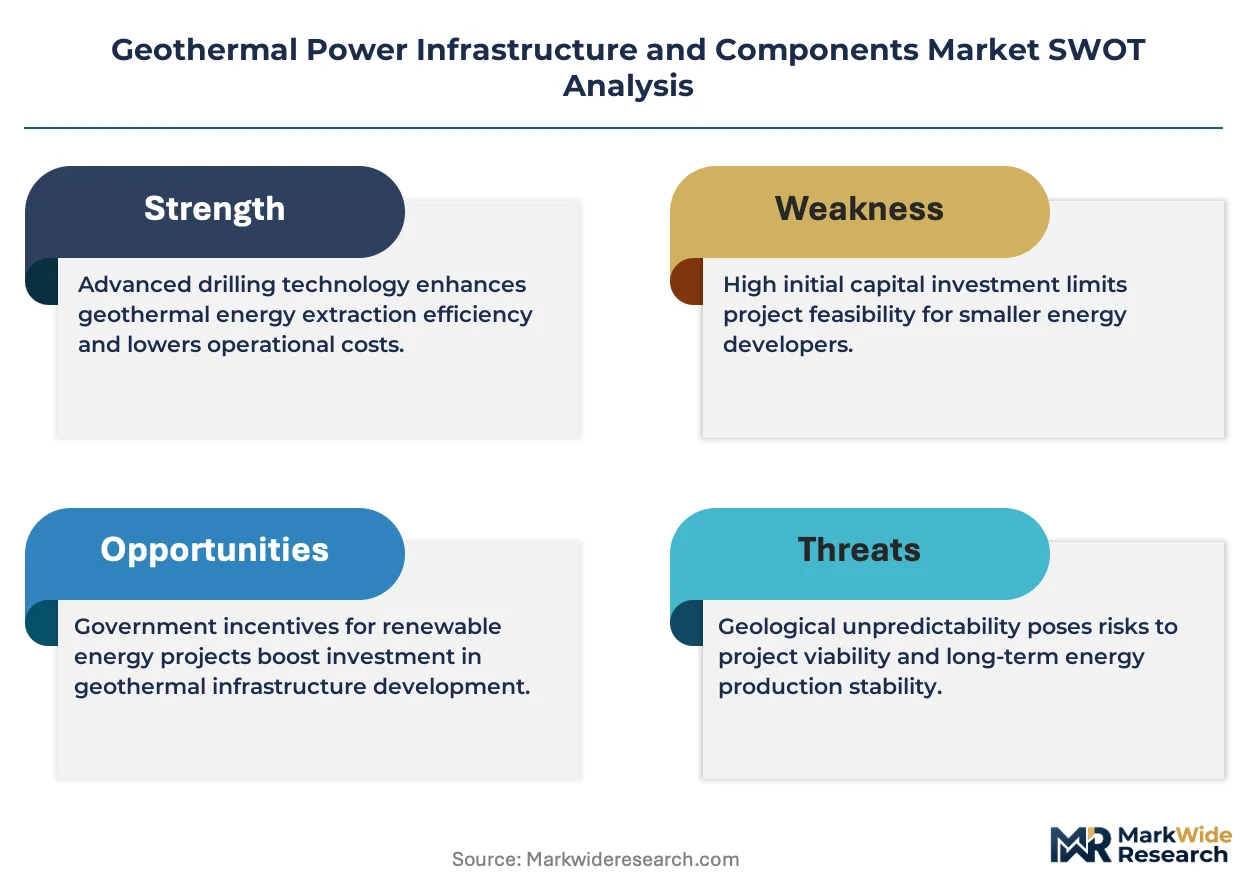
Enhanced Geothermal Systems (EGS) technology is fragmenting traditional project economics by enabling commercial extraction from hot dry rock formations previously excluded from development, forcing established flash steam suppliers to diversify binary cycle capabilities or lose procurement relevance.
Growth Catalysts
- Indonesia's MEMR feed-in tariff framework:The ministry's resource risk guarantees and long-term power purchase agreements accelerate binary cycle turbine procurement for moderate-temperature reservoirs across the archipelago.
- Binary cycle Organic Rankine Cycle advancement:Air-cooled condenser designs reduce water consumption in arid basins, opening development in Kenya's Rift Valley where freshwater scarcity previously constrained project siting.
- Corrosion-resistant superalloy deployment:Nickel-based alloys in heat exchangers extend equipment lifespan in high-salinity brine environments, lowering lifecycle costs for Philippine utility-scale installations.
Market Restraints
- Specialized drilling rig scarcity:Directional drilling equipment capable of EGS wellbore complexity concentrates among North American and European suppliers, creating 18-24 month procurement queues.
- Fluorinated working fluid phase-down:The EU F-Gas Regulation mandates hydrocarbon refrigerant substitution in binary cycle plants, requiring costly plant redesigns and retooling of European turbine manufacturing lines.
- Geologic resource uncertainty:Subsurface temperature gradient variability in greenfield sites demands expensive exploratory drilling before project financing closes, elevating development risk premiums.
Strategic Opportunities
- Turkey's untapped Western Anatolia reserves:Moderate-temperature fields below 200°C remain undeveloped due to flash steam technology dominance, creating first-mover advantage for binary cycle specialists.
- Direct use district heating convergence:Combined heat and power configurations in Iceland and New Zealand extract cascading thermal value, doubling revenue streams per megawatt installed.
- US DOE EGS demonstration funding:The Infrastructure Investment and Jobs Act allocates capital cost sharing for hot dry rock pilots, de-risking technology adoption for independent power producers.
Industry Challenges
- Directional drilling engineer scarcity:EGS wellbore complexity requires geosteering expertise concentrated in shale oil regions, creating talent poaching competition with petroleum operators.
- Underground injection control compliance:EPA UIC permit timelines for brine reinjection wells extend 24-36 months in seismically sensitive basins, compressing project development schedules.
- Binary cycle working fluid chemistry standardization:Absence of unified ISO protocols for hydrocarbon refrigerant blends forces plant-by-plant engineering validation, inflating engineering procurement costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geothermal Power Infrastructure and Components Market |
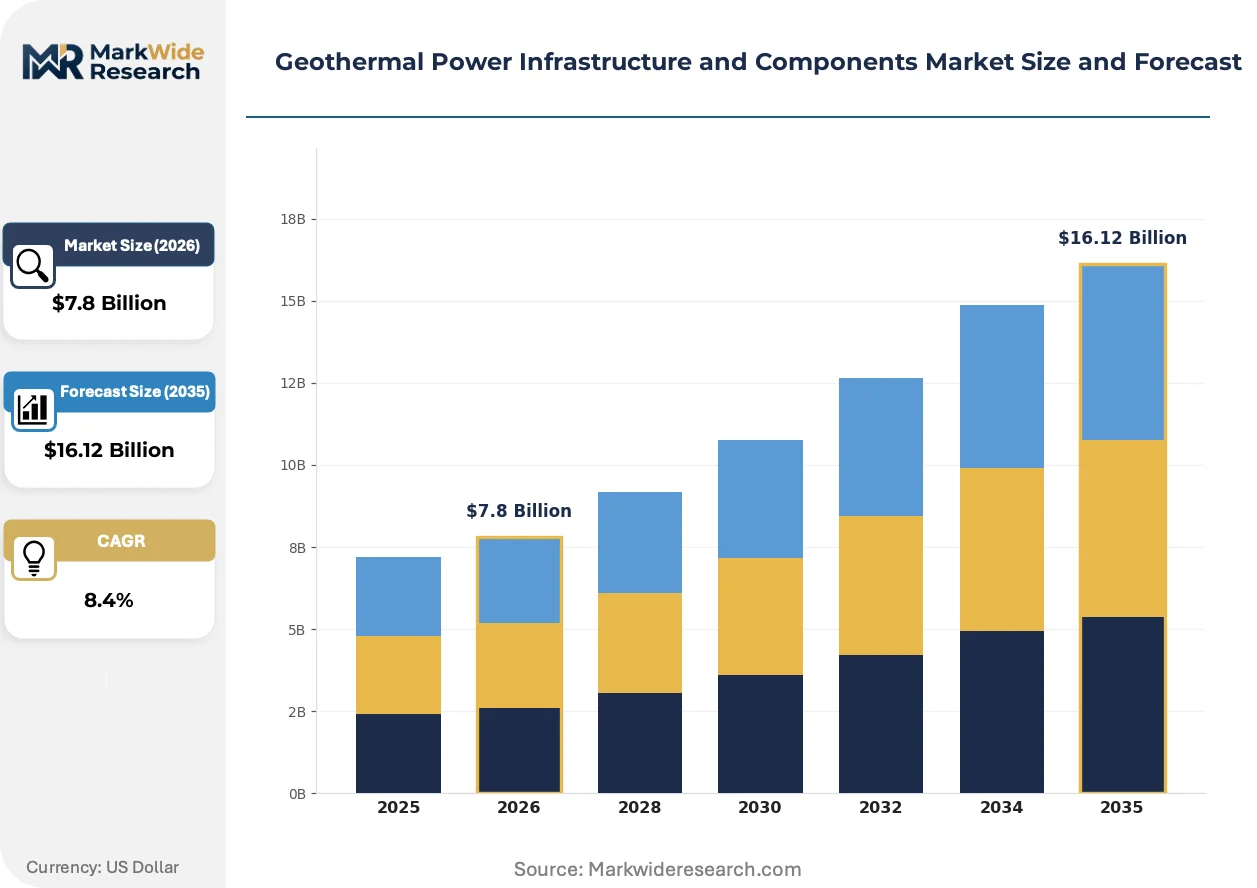
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Turbines, Heat Exchangers, Pumps, Cooling Towers, Control Systems Technology: Flash Steam, Binary Cycle, Dry Steam, Enhanced Geothermal Systems, Hydrothermal Application: Electricity Generation, District Heating, Direct Use, Agriculture Processing, Greenhouse Heating End User: Power Plants, Independent Energy Producers, Construction Contractors, Equipment Suppliers |
| Companies Covered | Mitsubishi Heavy Industries, Fuji Electric, Ormat Technologies, Mannvit HF, Tetra Tech Inc., Calpine Corporation, Toshiba Energy Systems & Solutions Corporation, Terra-Gen Power, Turboden S.p.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geothermal Power Infrastructure and Components Market Shifts & Advancements
Drilling automation and closed-loop working fluid systems are compressing project development cycles while regulatory chemistry constraints force equipment redesign across OECD markets.
Closed-loop binary cycle architecture is fragmenting conventional flash steam dominance in moderate-temperature reservoirs. Rural electric cooperatives in the western United States are specifying air-cooled Organic Rankine Cycle packages for 150-180°C resources. The technology is fragmenting equipment supplier hierarchies by enabling industrial process heat offtakers to enter power generation without steam turbine expertise.
The EU F-Gas Regulation mandates 79% reduction in hydrofluorocarbon consumption by 2030, prohibiting their use in new binary cycle plants. European turbine manufacturers are reconfiguring production lines for isobutane and propane working fluid packages. German and Italian equipment suppliers face compressed redesign timelines as the 2027 prohibition deadline approaches for utility-scale installations.
Utility procurement committees now require bankable resource temperature guarantees before equipment tender release. Indonesian state-owned enterprises are inserting subsurface verification clauses into engineering procurement contracts, displacing traditional geologic risk allocation to developers. Kenya's EPRA-mandated resource assessment protocols extend pre-qualification phases by 8-12 months, favoring developers with captive drilling capabilities over pure project finance vehicles.
Geothermal Power Infrastructure and Components Market Segmentation
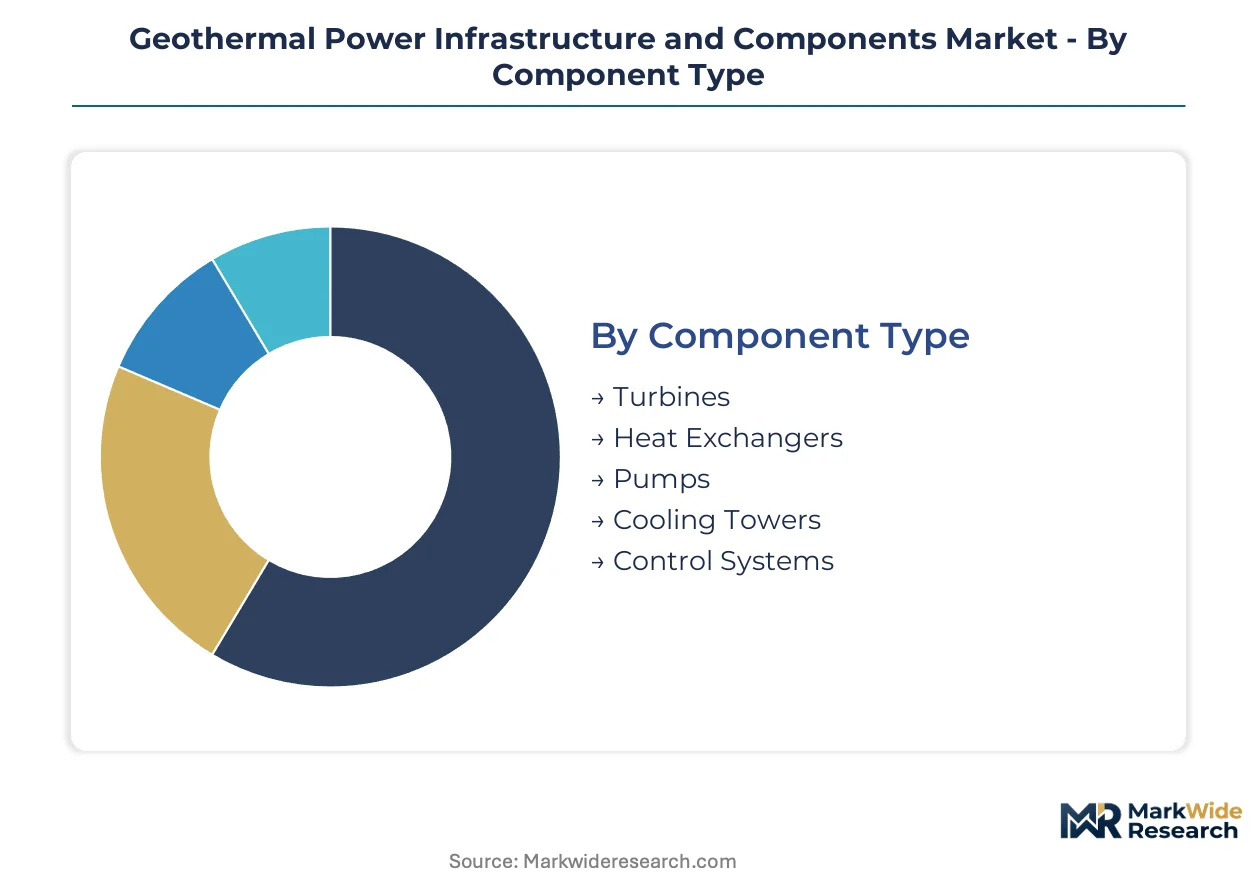
Equipment specification varies sharply across reservoir temperature and enthalpy conditions, dictating alloy selection and working fluid chemistry. Procurement committees segment vendor qualification by technology maturity and component criticality, with binary cycle turbines commanding premium engineering margins.
Component Type:
Margin pools concentrate in precision-manufactured rotating equipment and corrosion-resistant heat transfer surfaces where material specifications determine field lifespan.
- Turbines:Axial-flow and radial-inflow designs convert geothermal steam or vaporized working fluid into mechanical rotation. Flash steam turbines dominate procurement volumes in Indonesia's volcanic belt, while binary cycle expanders capture premium pricing in moderate-temperature reservoirs.
- Heat Exchangers:Shell-and-tube and plate-type configurations transfer thermal energy between brine and working fluid circuits. Nickel-based superalloy construction commands 40-60% price premiums over carbon steel in Philippine high-salinity fields, where chloride stress corrosion dictates material selection.
- Pumps:Vertical turbine and submersible designs handle geothermal brine reinjection and production well flow.
- Cooling Towers:Wet mechanical draft and air-cooled configurations manage condenser heat rejection.
- Control Systems:Distributed control platforms monitor reservoir pressure, turbine vibration, and chemistry parameters.
The dominant share belongs to Turbines, while Heat Exchangers is closing the gap fastest as binary cycle deployment accelerates.
Technology:
Application temperature bands fragment vendor capabilities, with equipment suppliers specializing by reservoir enthalpy class and working fluid thermodynamics.
- Flash Steam:High-enthalpy reservoirs above 180°C drive steam separation and turbine expansion. Indonesian state-owned utilities anchor global procurement for 50+ MW units, though project pipelines are maturing as volcanic field saturation approaches.
- Binary Cycle:Closed-loop Organic Rankine Cycle systems extract energy from moderate-temperature resources. Kenya's Rift Valley developers specify air-cooled condenser packages to circumvent freshwater scarcity constraints, opening arid basin development previously excluded from economic models.
- Dry Steam:Rare natural steam reservoirs at Larderello, Italy and The Geysers, California support direct turbine admission without separation equipment.
- Enhanced Geothermal Systems:Directional drilling and hydraulic stimulation unlock hot dry rock formations. US DOE demonstration funding is compressing technology adoption timelines for independent power producers seeking baseload renewable capacity.
- Hydrothermal:Convective circulation systems in permeable formations represent the traditional development class.
Flash Steam retains the largest installed base, though Enhanced Geothermal Systems is expanding most quickly as drilling automation reduces subsurface risk.
Application:
Revenue per megawatt installed varies by thermal cascade utilization, with combined heat and power configurations capturing multiple value streams from single resource extraction.
- Electricity Generation:Grid-connected baseload power plants feed utility transmission networks. Feed-in tariff structures in Indonesia and Kenya determine project bankability and equipment procurement specifications for 25-100 MW installations.
- District Heating:Cascading thermal distribution networks supply municipal heating loads. Iceland's Reykjavik system demonstrates 90%+ resource utilization efficiency through successive temperature-grade applications.
- Direct Use:Industrial process heat offtakers bypass power generation for thermal applications.
- Agriculture Processing:Drying and pasteurization operations exploit moderate-temperature brine.
- Greenhouse Heating:Controlled environment agriculture integrates geothermal thermal loops.
Electricity Generation commands procurement volumes, while District Heating is gaining share fastest as European decarbonization mandates accelerate thermal network investment.
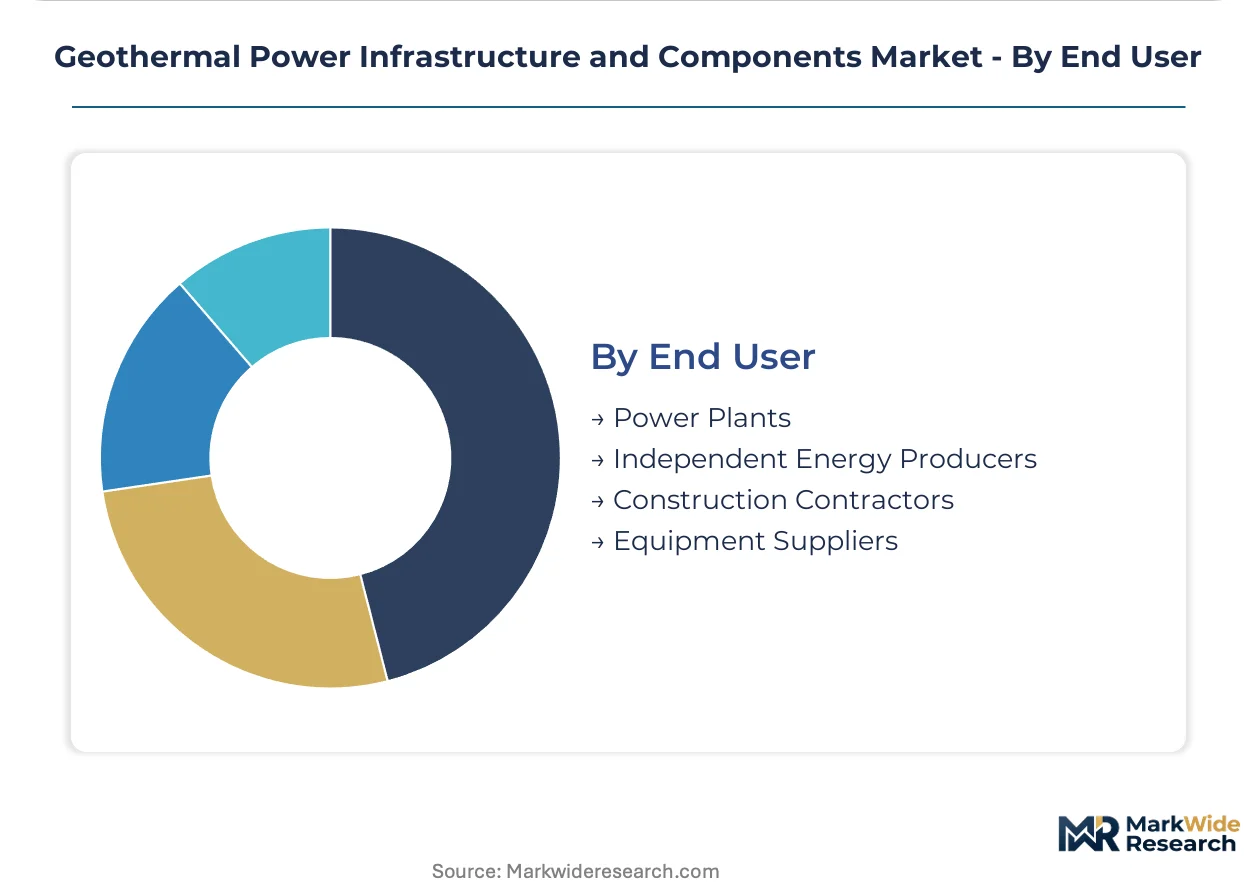
End User:
Contracting structures differentiate risk allocation, with engineering-procurement-construction firms capturing equipment specification influence in turnkey arrangements.
- Power Plants:Utility and independent power producer owner-operators specify long-life cycle equipment. Indonesian PLN and Kenyan KenGen anchor regional procurement through feed-in-tariff-backed project pipelines with 25-year power purchase agreements.
- Independent Energy Producers:Non-utility developers seek modular binary cycle packages for distributed resource exploitation. US western states rural electric cooperatives specify 5-20 MW air-cooled Organic Rankine Cycle units for 150-180°C resources.
- Construction Contractors:EPC firms bundle equipment procurement within turnkey construction contracts.
- Equipment Suppliers:Component manufacturers sell direct for replacement and expansion cycles.
Power Plants dominate capital deployment, while Independent Energy Producers is climbing the fastest as US DOE cost-sharing de-risks smaller-scale development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA's underground injection control framework anchors United States geothermal development, while Indonesia's MEMR feed-in tariffs and Kenya's EPRA resource guarantees concentrate procurement demand across distinct volcanic belts. Equipment specification varies sharply by reservoir chemistry and temperature gradient across these dominant geographies.
United States
The DOE's EGS demonstration funding and Infrastructure Investment and Jobs Act cost-sharing accelerate hot dry rock pilot deployment. EPA UIC permit timelines extend 24-36 months in seismically sensitive basins, compressing development schedules. The Geysers field in northern California and Imperial Valley in southern California anchor flash steam and binary cycle procurement respectively.
Indonesia
PLN's 25-year power purchase agreements and resource risk guarantees mature flash steam project pipelines across volcanic fields. MEMR's feed-in tariff framework determines binary cycle turbine procurement for moderate-temperature reservoirs. The Wayang Windu and Salak fields in West Java concentrate large-unit installation demand as volcanic field saturation approaches.
Kenya
EPRA-mandated resource assessment protocols extend pre-qualification phases by 8-12 months, favoring developers with captive drilling capabilities. Feed-in tariff structures determine project bankability for Rift Valley installations. The Olkaria field anchors binary cycle deployment where air-cooled condenser designs circumvent freshwater scarcity constraints.
Philippines
High-salinity brine chemistry in volcanic reservoirs drives nickel-based superalloy specification in heat exchangers. National utility procurement committees require corrosion-resistant alloy construction for 40-60% price premiums over carbon steel. The Leyte and Mindanao geothermal provinces concentrate binary cycle and flash steam installation demand.
Turkey
Untapped Western Anatolia reserves below 200°C remain undeveloped due to flash steam technology dominance, creating first-mover positioning for binary cycle specialists. The country's energy ministry administers licensing frameworks for moderate-temperature field development. The Aydın-Denizli corridor anchors emerging procurement demand as European equipment suppliers seek market entry.
Geothermal Power Infrastructure and Components Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale-driven turbine manufacturers and corrosion-resistant alloy fabricators occupying distinct competitive positions. Flash steam technology maturity concentrates procurement influence among established Pacific Rim suppliers, while binary cycle advancement fragments equipment hierarchies. Three archetypes dominate: vertically integrated turbine-generator conglomerates, ORC working fluid specialists, and subsurface drilling engineering firms. Competitive dynamics center on technology licensing partnerships and backward integration into superalloy supply chains.
Within the integrated conglomerate tier, Mitsubishi Heavy Industries and Fuji Electric represent scale-driven manufacturing positions, while Ormat Technologies exemplifies binary cycle specialization through proprietary system architectures. These three anchors demonstrate how geographic origin and corporate structure align with distinct technology archetypes: Japanese heavy industry conglomerates leverage turbine manufacturing scale, while Nevada-based technology developers concentrate closed-loop working fluid expertise.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| Fuji Electric |
| Ormat Technologies |
| Mannvit HF |
| Tetra Tech Inc. |
| Calpine Corporation |
| Toshiba Energy Systems & Solutions Corporation |
| Terra-Gen Power |
| Turboden S.p.A |
| Others |
Supply & Pricing Matrix
EPA underground injection control permits and EU F-Gas Regulation compliance gates simultaneously determine supplier qualification tiers and price stratification across geothermal equipment markets. These regulatory frameworks bifurcate vendor pools into certified premium suppliers and uncertified economy alternatives while embedding compliance costs into delivered equipment pricing.
Pricing Analysis
Geographic price spreads of 40-60% separate Philippine nickel-superalloy heat exchangers from Indonesian carbon-steel equivalents. Project-based long-term offtake contracts dominate, with price differentiation hinging on corrosion-resistance certification grade and captive drilling capability. Cost compression in flash steam turbines intensifies as volcanic field saturation in Indonesia concentrates procurement leverage among state utilities. Independent power producers exhibit highest price sensitivity, while national utilities with feed-in-tariff backing absorb premium alloy specifications.
Supply Chain Analysis
Directional drilling rig availability from North American and European specialist manufacturers constitutes the critical chokepoint compressing EGS project timelines. Manufacturing concentration centers on Japan, Germany, and the United States for precision turbines and generators, while Indonesia and the Philippines anchor field assembly and brine chemistry adaptation. Raw material dependencies span nickel-based superalloys, high-grade steel forgings, and hydrocarbon working fluid blends. Single-source vulnerability in EGS drilling engineer talent pools threatens supply continuity. Distribution runs through engineering-procurement-construction contractors bundling turnkey installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology fragmentation across flash steam, binary cycle, and EGS architectures creates specialist niche opportunities as reservoir-specific expertise displaces one-size-fits-all procurement. Moderate-temperature field development and closed-loop working fluid systems represent the most penetrable white spaces.
For Market Incumbents: Consolidate backward integration into nickel-based superalloy supply chains to defend margin position against corrosion-resistant alloy price volatility. Acquire captive drilling engineering capabilities in Kenya and Indonesia before EGS talent poaching by petroleum operators accelerates. Lock in long-term power purchase agreement structures with PLN and KenGen to secure procurement pipeline visibility. For New Entrants and Emerging Players: Differentiate on air-cooled Organic Rankine Cycle system integration for arid basin applications where freshwater scarcity excludes flash steam competitors. Target Turkey's Western Anatolia moderate-temperature reserves below 200°C where binary cycle first-mover positioning remains uncontested. Pursue rural electric cooperative procurement channels in the western United States specifying 5-20 MW modular packages. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across binary cycle manufacturing as standardized hydrocarbon working fluid packages displace custom engineering. Long-term viability favors equipment suppliers with technology licensing revenue streams over pure manufacturing plays. Watch EGS demonstration project permitting velocity as the inflection signal for hot dry rock commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Supply | Captive nickel sourcing insulates margin from Philippine chloride corrosion specification premiums. |
| Air-Cooled Condenser Platform Launch | Ormat Technologies' proprietary designs open Kenya Rift Valley development previously excluded by water scarcity. |
| EGS Drilling Engineering Acquisition | Shale oil geosteering talent pools in North America compress EGS wellbore complexity timelines. |
| Hydrocarbon Working Fluid Certification | EU F-Gas Regulation compliance enables continued European binary cycle market participation. |
| Feed-in-Tariff Backed PPA Structuring | Indonesia MEMR resource risk guarantees determine project bankability and equipment procurement release. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and geothermal drilling engineers; and secondary validation against EIA geothermal statistics, IEA renewable technology reports, FERC interconnection filings, and national regulatory databases. Bottom-up project pipeline enumeration triangulated against top-down market sizing from equipment manufacturer capacity disclosures.
Across the analysis window, forecasts applied capacity-weighted average growth derivation segmented by technology type, reservoir temperature class, project scale tier, and regional regulatory framework. Modeled inputs incorporated feed-in-tariff revision schedules, EGS demonstration funding allocation trajectories, and working fluid chemistry substitution timelines under EU F-Gas phase-down mandates.
Material uncertainties — regulatory permit delays, subsurface temperature gradient variability, and hydrocarbon refrigerant supply constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding technology adoption curves and policy continuity. Practitioners should keep alternative scenarios live as EPA UIC timeline compression and EU working fluid prohibition deadlines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geothermal Energy
United Kingdom Geothermal Energy Market
Geothermal Energy
US Geothermal Heat Pump Market
Geothermal Energy
Geothermal Power Market
Geothermal Energy
Asia-Pacific Geothermal Energy Market
Geothermal Energy
Netherlands Geothermal Energy Market
Geothermal Energy
Indonesia Geothermal Energy Market
Geothermal Energy
Global Geothermal Heat Pumps Market
Geothermal Energy
Denmark Geothermal Energy Market
Geothermal Energy
Sweden Geothermal Energy Market
Geothermal Energy
Hungary Geothermal Energy Market
Geothermal Energy
Philippines Geothermal Energy Market
Geothermal Energy
Enhanced Geothermal System Market
Geothermal Energy
Geothermal Power Generation Market
Geothermal Energy
Geothermal Power Infrastructure Market
Geothermal Energy
Geothermal Energy Market