
 Philippines Geothermal Energy Market | 2026-2036
Philippines Geothermal Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Geothermal Energy Market Analytics
Industrial offtakers is rotating toward long-term power purchase agreements as utility companies diversify procurement portfolios. Energy Development Corporation leverages its integrated drilling and plant operations across Leyte and Negros Island. First Gen Corporation sustains its Luzon baseload position through the 1,200 MW Bacon-Manito and Malitbog facilities. Aboitiz Power Corporation anchors its growth pipeline with greenfield exploration in Mindanao.
Philippines geothermal energy harnesses heat from volcanic reservoirs to drive steam turbines generating baseload electricity, with flash technology plants typically operating at reservoir temperatures between 150°C and 300°C and binary cycle units capturing lower-grade heat below 150°C for sustained power output. Flash technology dominates installed capacity due to mature reservoir engineering and lower levelized costs across existing Philippine fields. Binary cycle represents the fastest-growing type segment as developers target marginal temperature resources in unexplored volcanic zones. Utility companies command the largest end-user share through regulated offtake structures, while industrial facilities represent the emerging margin pool as direct power agreements bypass traditional distribution layers.
The Department of Energy enforces renewable portfolio standards requiring distribution utilities to source specified percentages from geothermal and other eligible resources. The Energy Regulatory Commission reviews feed-in tariff applications and sets allowable returns under performance-based regulation. The Philippine Geothermal Production Company navigates service contract renewals under the Department of Energy's geothermal reservation framework. Stakeholders must monitor transmission queue congestion in Southern Luzon and inter-island grid stability as new capacity seeks connection points.
Market Dynamics
The Philippines geothermal energy market is being fundamentally restructured by the Renewable Energy Act of 2008 and its implementing feed-in tariff mechanisms, which are compressing project development timelines and redirecting capital toward baseload renewable capacity. This regulatory architecture is simultaneously pulling industrial offtakers away from spot market exposure while pushing developers toward long-term power purchase agreements with distribution utilities.
Growth Catalysts
- Feed-in Tariff Mechanisms:The Energy Regulatory Commission's approved tariff schedules provide revenue certainty for geothermal developers, reducing financing costs for greenfield projects in Batangas and Leyte-Samar corridors.
- Industrial Baseload Demand:Manufacturing facilities across Luzon and Mindanao are executing direct power agreements to secure 24/7 renewable supply, bypassing distribution utility markups.
- Flash Technology Maturation:Reservoir engineering advances at 150°C to 300°C temperature bands are unlocking marginal field economics in previously uneconomic volcanic zones.
Market Restraints
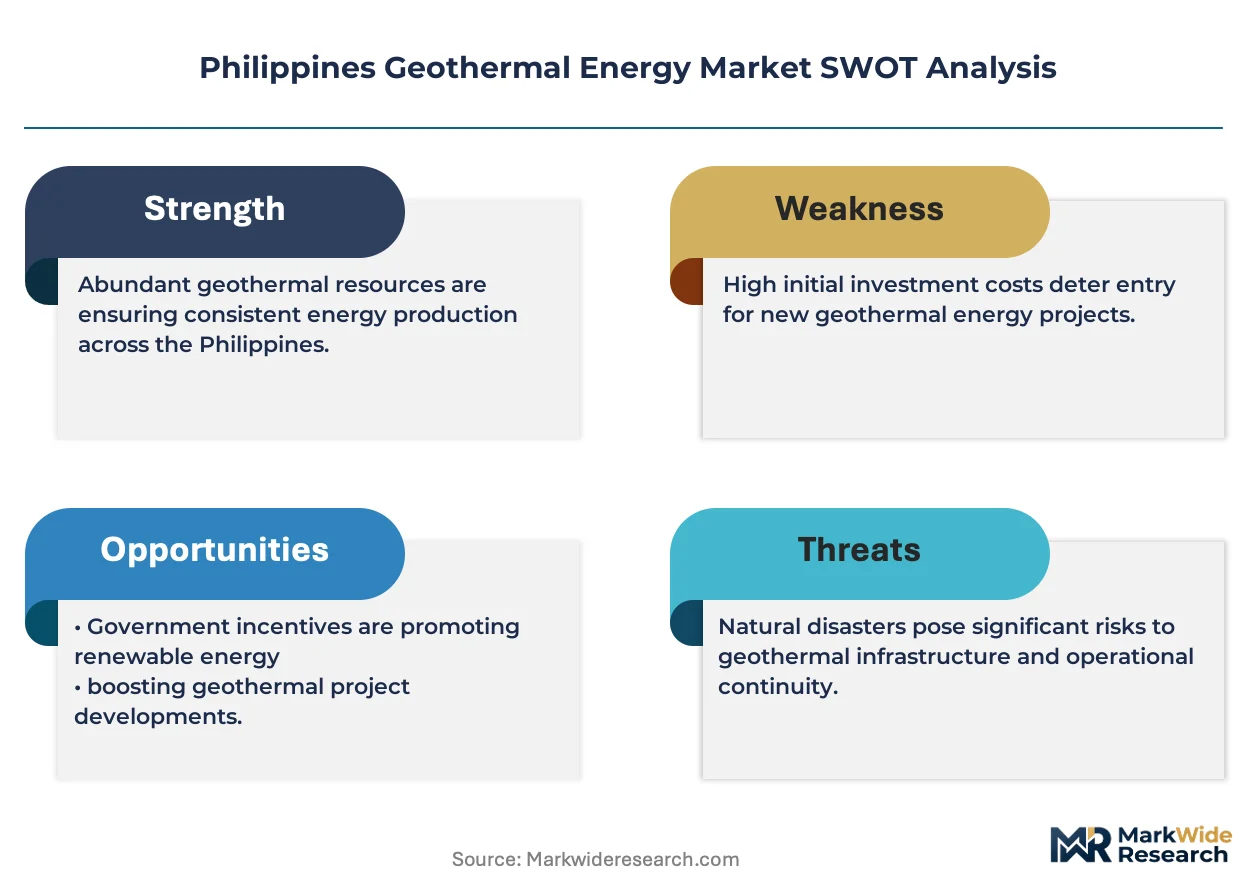
- Exploration Capital Intensity:Geothermal drilling carries front-loaded capital requirements with dry hole risk, constraining participation to integrated operators with captive balance sheets.
- Transmission Queue Congestion:Southern Luzon interconnection bottlenecks delay commercial operation dates for completed plant capacity seeking grid access.
- Binary Cycle Cost Premium:Lower-temperature binary systems face levelized cost disadvantages against flash plants, limiting deployment below 150°C reservoirs.
Strategic Opportunities
- Mindanao Greenfield Expansion:Unexplored volcanic zones in the southern island offer untapped resource potential with limited incumbent competition.
- Direct Industrial Contracts:Bypass structures allowing generators to contract directly with large electricity consumers are proliferating outside traditional utility procurement.
- Reservoir Hybridization:Convergence of flash and binary cycle technologies enables staged development of single geothermal fields across multiple temperature bands.
Industry Challenges
- Geoscience Talent Scarcity:Reservoir engineering and subsurface characterization expertise concentrates within a narrow pool of specialized practitioners.
- Service Contract Renewal Complexity:The Department of Energy's geothermal reservation framework imposes procedural friction on exploration rights extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Geothermal Energy Market |
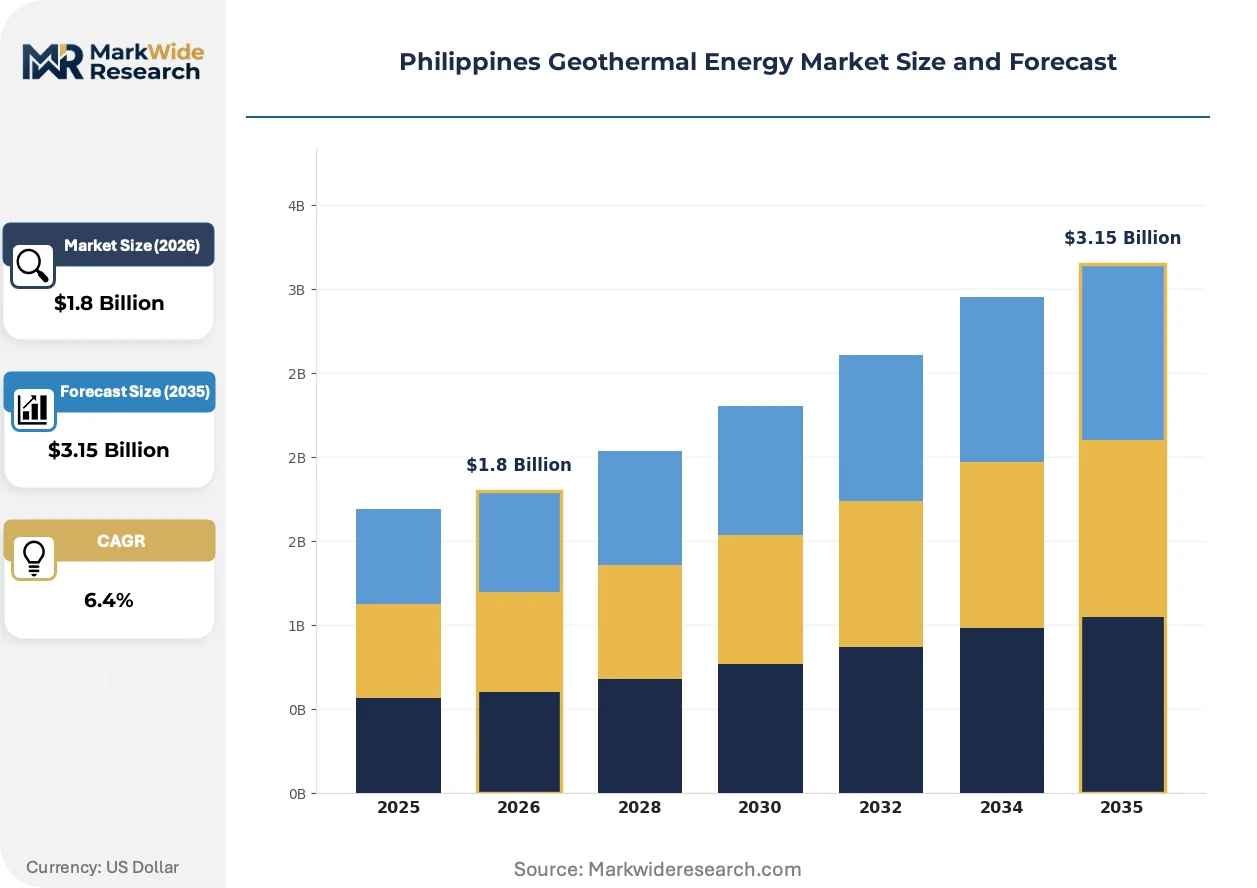
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Flash Technology, Binary Cycle, Dry Steam, Enhanced Geothermal Systems End User: Utility Companies, Industrial Facilities, Residential Users, Commercial Buildings Installation: Onshore, Offshore, Integrated Systems, Standalone Units Operation Mode: Base Load, Peak Load, Intermediate Load, Load Following |
| Companies Covered | Aragorn Power and Energy Corporation, First Gen Corporation, Energy Development Corporation, Maibarara Geothermal Inc., Pure Energy Holdings Corporation, Philippine Geothermal Production Company, Inc., National Power Corporation, PetroGreen Energy Corporation, Aboitiz Power Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Geothermal Energy Market Evolving Landscape
Technology deployment patterns across Philippine geothermal fields are fragmenting along temperature-band lines, with developers optimizing plant configurations against specific reservoir characteristics rather than applying standardized designs. This specialization is accelerating capital efficiency gains while complicating equipment procurement strategies.
Binary cycle technology is bifurcating the lower-temperature segment of the market. These systems capture heat below 150°C that flash plants cannot economically utilize. Energy Development Corporation and emerging developers are deploying modular binary units at marginal fields previously deemed subeconomic. The technology is bifurcating project economics by allowing staged field development and reducing upfront capital exposure.
The Department of Energy's renewable portfolio standards are tightening compliance obligations for distribution utilities. These mandates require specified percentages of electricity from geothermal and other eligible renewable resources. Luzon-based utilities with limited indigenous renewable capacity are contracting across inter-island transmission links, reshaping power flow patterns and grid investment priorities.
Industrial electricity buyers are restructuring procurement toward long-term direct agreements with generators. Large manufacturing and processing facilities in Batangas and Cebu are abandoning traditional distribution utility relationships. This channel disintermediation is most visible among cement, steel, and chemical producers with continuous process loads requiring baseload supply certainty.
Philippines Geothermal Energy Market Segmentation
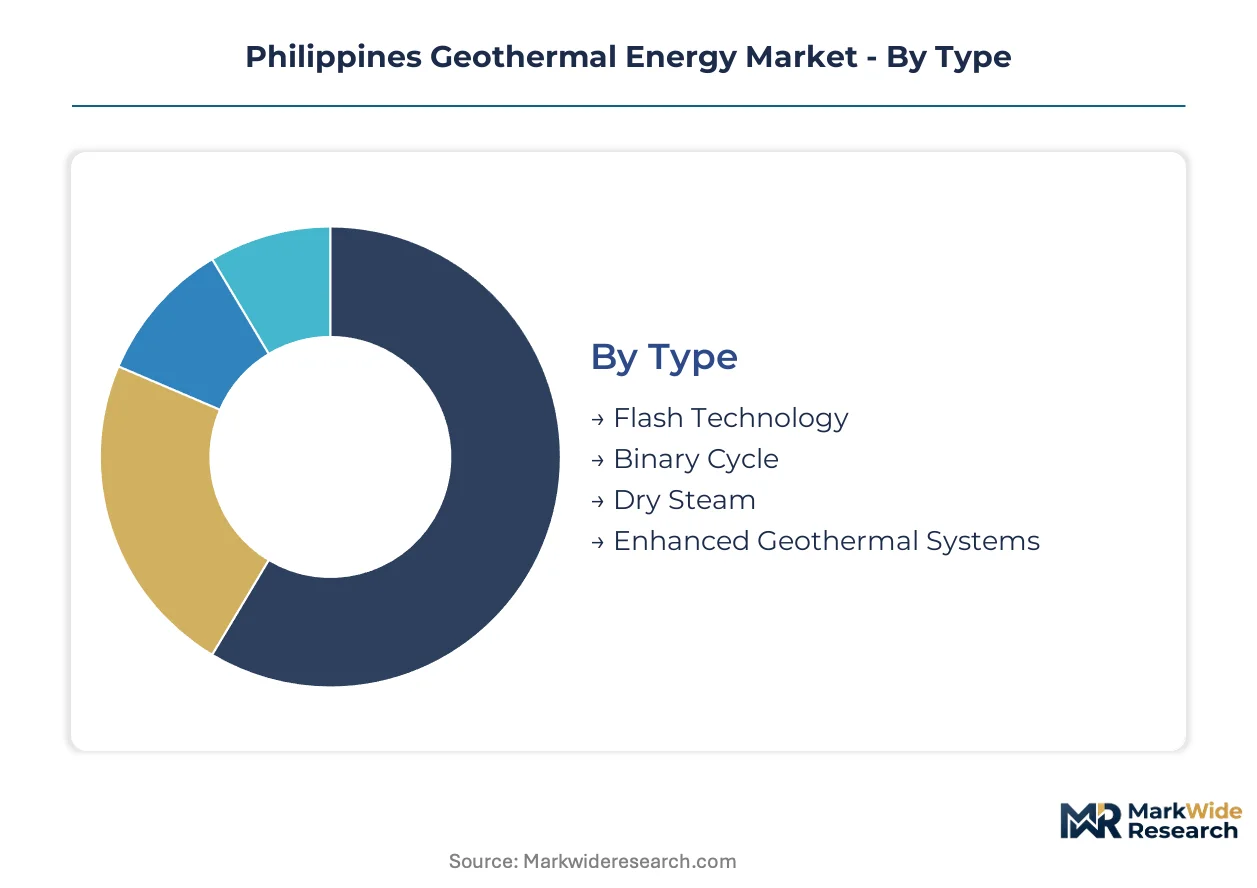
Philippine geothermal developers configure plant technology against reservoir temperature profiles and negotiate offtake structures through distinct procurement channels. Segmentation choices directly determine capital efficiency, revenue certainty, and grid connection pathways across the archipelago.
Type:
Channel flows split along technology maturity lines, with established flash plants securing utility PPAs while binary systems penetrate direct industrial contracts.
- Flash Technology:Plants extract steam from reservoirs between 150°C and 300°C through pressure-reducing separators, driving conventional turbine generators. Batangas and Leyte-Samar corridors concentrate installed capacity where reservoir engineering maturity supports baseload dispatch contracts with Manila Electric and Visayan Electric.
- Binary Cycle:Organic Rankine cycle units capture heat below 150°C using secondary working fluids, enabling economic extraction from marginal temperature resources. Mindanao greenfield developers deploy modular binary systems under direct supply agreements with cement and nickel processing facilities seeking 24/7 renewable baseload.
- Dry Steam:Direct turbine drive from superheated vapor reservoirs eliminates brine handling complexity. Limited Philippine applicability due to scarce vapor-dominated resource geology.
- Enhanced Geothermal Systems:Hydraulic stimulation creates artificial permeability in hot dry rock formations. Pre-commercial in Philippine context pending subsurface risk mitigation frameworks.
Flash technology dominates installed base. Binary cycle is where expansion concentrates.
End User:
Customer type determines tariff structure, contract duration, and regulatory oversight intensity across the value chain.
- Utility Companies:Distribution utilities procure under renewable portfolio standards with feed-in tariff ceilings set by the Energy Regulatory Commission. Luzon-based Manila Electric and Visayan Electric anchor procurement volumes through 20-25 year power supply agreements.
- Industrial Facilities:Direct bilateral contracts bypass distribution markups. Cement producers in Batangas and nickel smelters in Surigao execute long-term supply agreements with generators, securing price certainty for continuous process loads.
- Residential Users:Limited direct geothermal access due to distribution utility monopoly over retail supply. Net metering applications negligible for geothermal given plant scale economics.
- Commercial Buildings:Large-load commercial offtakers in Cebu and Davao explore direct access arrangements where distribution franchise boundaries permit wheeling agreements.
Utility companies anchor revenue stability. Industrial facilities offer the steepest expansion trajectory.
Installation:
Physical configuration options reflect resource geography and grid infrastructure constraints rather than offshore resource availability.
- Onshore:Conventional surface plant construction adjacent to production well pads. Negros Island and Leyte fields deploy standardized onshore configurations with established transmission interconnection protocols.
- Offshore:Not applicable to Philippine geothermal given volcanic resource distribution on terrestrial volcanic arcs.
- Integrated Systems:Combined drilling, power generation, and grid interconnection under single development entity. Energy Development Corporation operates integrated assets across multiple service contract areas.
- Standalone Units:Modular binary plants serving isolated industrial loads without grid export obligation. Emerging deployment model for Mindanao mining operations.
Integrated systems dominate operational complexity. Standalone units are gaining share fastest in remote industrial applications.
Operation Mode:
Dispatch profile selection hinges on reservoir productivity characteristics and offtake contract flexibility provisions.
- Base Load:Continuous 24/7 operation matching geothermal reservoir steady-state output. Philippine geothermal plants predominantly operate baseload given high-capacity factor resource economics and utility preference for firm renewable supply.
- Peak Load:Scheduled dispatch during high-price periods requiring reservoir drawdown management. Limited Philippine application due to baseload contract structures and reservoir sustainability constraints.
- Intermediate Load:Daily cycling between minimum and rated capacity. Occasional deployment for grid balancing in Luzon where geothermal complements variable solar penetration.
- Load Following:Real-time output adjustment to grid frequency signals. Technically feasible with binary cycle units but rarely contracted given baseload revenue premium.
Base load commands contract premiums. Intermediate load is emerging where solar penetration reshapes grid dispatch economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Leyte-Samar grid interconnection and Batangas transmission corridor anchor the Philippines geothermal energy market's geographic concentration. These infrastructure assets channel baseload power from volcanic resource zones to demand centers across Luzon and the Visayas.
Luzon
Batangas province hosts the 1,200 MW Bacon-Manito and Malitbog facilities serving Manila Electric's baseload requirements. The Energy Regulatory Commission's feed-in tariff schedules provide revenue certainty for developers expanding capacity in Southern Luzon. Transmission queue congestion at the Batangas substation delays commercial operation dates for completed plant capacity.
Visayas
Leyte Island concentrates flash technology plants exploiting 150°C to 300°C reservoir temperatures through integrated drilling and generation operations. The Leyte-Samar transmission backbone enables inter-island power flows to Cebu-based industrial offtakers. Visayan Electric procures firm renewable supply under 20-25 year power purchase agreements.
Mindanao
Surigao and Davao del Sur host greenfield exploration targeting marginal temperature resources below 150°C for binary cycle deployment. Nickel smelters and cement producers execute direct bilateral contracts bypassing distribution utility markups. The Department of Energy's geothermal reservation framework governs service contract renewals in unexplored volcanic zones.
Negros Island
Negros Occidental fields deploy standardized onshore configurations with established interconnection protocols to Panay and Cebu grids. Sugar milling and bioethanol facilities anchor industrial demand for continuous process power. Distribution utilities source renewable portfolio standard compliance through contracted geothermal baseload.
Philippines Geothermal Energy Market Competitive Landscape
Listed leaders compete with private specialists across integrated generation and exploration capabilities. The market structure concentrates around vertically integrated operators with captive drilling assets and balance sheet capacity to absorb dry hole risk. Three archetypes dominate: legacy integrated developers with service contract portfolios, utility-affiliated generators securing renewable portfolio standard compliance, and emerging specialists targeting direct industrial offtake structures. Competitive moves center on greenfield exploration rights acquisition and long-term power purchase agreement execution with bypass structures.
Within the integrated developer tier, Energy Development Corporation and First Gen Corporation exemplify operators combining reservoir engineering expertise with plant construction capabilities. Aboitiz Power Corporation occupies a position among utility-affiliated generators expanding through Mindanao greenfield exploration. These three entities anchor competitive dynamics through differentiated access to transmission interconnection points and industrial customer relationships.
| Leading Market Players |
|---|
| Aragorn Power and Energy Corporation |
| First Gen Corporation |
| Energy Development Corporation |
| Maibarara Geothermal Inc. |
| Pure Energy Holdings Corporation |
| Philippine Geothermal Production Company, Inc. |
| National Power Corporation |
| PetroGreen Energy Corporation |
| Aboitiz Power Corporation |
| Others |
Value Network & Pricing Analysis
Long-term power purchase agreements with take-or-pay provisions lock in both geothermal supply access and price visibility for industrial offtakers across Batangas and Leyte-Samar corridors. These contract structures insulate developers from spot market volatility while giving buyers cost predictability for continuous process loads.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the Philippine geothermal market by reservoir temperature grade and contract duration. Premium tiers attach to baseload utility PPAs with 20-25 year tenors and flash technology plants above 200°C reservoirs. Standard tiers cover intermediate-term industrial direct contracts with binary cycle systems between 100-150°C. Economy tiers serve standalone modular units for remote mining operations with shorter durations and higher per-kWh rates reflecting transmission avoidance. Price differentiation hinges on reservoir productivity certification by the Department of Energy and guaranteed capacity factor commitments. Pricing pressure stems from binary cycle cost premiums against mature flash economics, compressing margins in the sub-150°C segment. Industrial facilities exhibit highest price sensitivity due to bypass structure alternatives, while utility offtakers accept premium pricing for renewable portfolio standard compliance certainty.
Supply Chain Analysis
Japan and Germany anchor precision turbine manufacturing and high-temperature drilling equipment supply for Philippine geothermal development. China dominates steel casing, cementing materials, and modular binary cycle component fabrication. The Philippines sources specialized geothermal logging tools and reservoir simulation software from the United States. Raw material dependencies include nickel-based superalloys for turbine blades, high-grade Portland cement for wellbore integrity, and synthetic drilling mud formulations for high-temperature formations. Single-source vulnerability concentrates in advanced downhole measurement-while-drilling systems where two Japanese suppliers control global capacity. Distribution runs through integrated developers with captive procurement arms rather than independent equipment distributors, compressing vendor access for emerging players.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large industrial offtakers executing direct bilateral contracts, fragmenting traditional utility procurement dominance and reshaping price negotiation leverage across the Philippine archipelago.
For Market Incumbents: Shield service contract portfolios from expiration risk by accelerating renewal filings with the Department of Energy's geothermal reservation framework. Incumbents should deepen backward integration into drilling asset ownership to capture margin from exploration through generation, countering emerging competitors leasing third-party rigs. The priority defensive lever anchors transmission interconnection queue positions in Southern Luzon before congestion worsens. Certification investment in reservoir hybridization capabilities—combining flash and binary cycle technologies—creates differentiation against pure-play developers. For New Entrants and Emerging Players: Remote industrial load serving represents the most penetrable white-space target, where standalone binary units bypass grid connection queues entirely. Mindanao greenfield exploration offers limited incumbent competition and direct contract access to nickel smelters and cement producers with unmet baseload demand. New entrants should pursue joint development structures with integrated drilling contractors to transfer dry hole risk while retaining plant ownership. The optimal go-to-market angle positions modular binary systems as transmission-independent solutions for mining operations with 24/7 power requirements. For Investors and Strategic Acquirers: Developers holding expired or near-expiration service contracts with proven but undeveloped resource indicators present the most attractive acquisition archetype. These assets carry suppressed valuations due to renewal uncertainty yet offer rapid capacity expansion potential once regulatory clarity emerges. Long-term viability hinges on the Philippine government's commitment to renewable portfolio standard enforcement and feed-in tariff continuity. The critical inflection signal to monitor is inter-island transmission capacity expansion announcements affecting Leyte-Samar to Cebu power flows.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Flash plant expansion in Batangas secures Manila Electric baseload procurement under renewable portfolio standards. |
| Power Purchase Agreement | Direct bilateral contracts with Surigao nickel smelters bypass distribution utility markups and transmission congestion. |
| Technology Licensing | Binary cycle module partnerships reduce capital exposure for marginal temperature resource development in Mindanao. |
| Backward Integration | Captive drilling asset ownership absorbs dry hole risk and accelerates exploration timelines across service contract areas. |
| Green Certification Program | Department of Energy reservoir productivity certification unlocks premium feed-in tariff tiers for high-capacity factor plants. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews across the Philippine geothermal value chain. Utility planning officers at Manila Electric and Visayan Electric, independent power producer project developers, engineering-procurement-construction contractors with active geothermal portfolios, and grid operators managing Leyte-Samar interconnection flows provided operational perspectives. Secondary validation drew from Department of Energy service contract registries, Energy Regulatory Commission feed-in tariff filings, National Grid Corporation interconnection queue data, and project finance disclosure documents. Bottom-up capacity aggregation across individual plant configurations was triangulated against top-down renewable portfolio standard compliance demand projections.
Across the analysis window, the forecasting framework modeled capacity and revenue outputs through segmented build-up across technology type, end-user channel, and regional grid zone. Segmentation dimensions included flash versus binary cycle deployment, utility PPA versus direct industrial contract structures, and Luzon-Visayas-Mindanao geographic clusters. CAGRs were derived from regression-based capacity addition curves calibrated against historical commissioning timelines and transmission interconnection bottlenecks. Key forecast inputs incorporated reservoir temperature band availability from geologic surveys and industrial load growth trajectories for cement, nickel, and steel processing sectors.
Underlying assumptions cover sustained renewable portfolio standard enforcement, feed-in tariff schedule continuity, and inter-island transmission expansion delivery, with deviation risk concentrated in service contract renewal delays and binary cycle cost curve movements. Forecasts reflect these documented assumptions without probabilistic scenario weighting. Recalibration cycles align with material shifts in Department of Energy regulatory announcements and National Grid Corporation transmission investment disclosures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geothermal Energy
United Kingdom Geothermal Energy Market
Geothermal Energy
Geothermal Energy Market
Geothermal Energy
Asia-Pacific Geothermal Energy Market
Geothermal Energy
Geothermal Power Infrastructure Market
Geothermal Energy
Geothermal Power Infrastructure and Components Market
Geothermal Energy
Hungary Geothermal Energy Market
Geothermal Energy
US Geothermal Heat Pump Market
Geothermal Energy
Geothermal Power Market
Geothermal Energy
Netherlands Geothermal Energy Market
Geothermal Energy
Global Geothermal Heat Pumps Market
Geothermal Energy
Indonesia Geothermal Energy Market
Geothermal Energy
Geothermal Power Generation Market
Geothermal Energy
Enhanced Geothermal System Market
Geothermal Energy
Denmark Geothermal Energy Market
Geothermal Energy
Sweden Geothermal Energy Market