
 Vietnam Power Generation EPC Market | 2026-2036
Vietnam Power Generation EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Power Generation EPC Market Analytics
Independent power producers are reorganizing Vietnam's power generation EPC demand, displacing traditional utility-led procurement as private capital flows into LNG and renewable projects. Samsung C&T leverages its integrated construction-engineering platform to anchor mega-project execution along Vietnam's coastal corridor. GE Vernova competes through gas turbine technology leadership and localized service partnerships. Lilama Corporation sustains domestic market presence through state-backed infrastructure relationships and heavy fabrication capabilities.
Vietnam power generation EPC encompasses the full-scope engineering, procurement, and construction of electricity generating facilities, spanning civil works, equipment installation, grid interconnection, and commissioning to achieve commercial operation dates typically ranging from 24 to 60 months depending on technology and scale. The primary purpose is delivering turnkey generation assets that synchronize with Vietnam's national grid under power purchase agreements governed by EVN. Thermal and solar technologies dominate current contract pipelines, with thermal EPC retaining larger absolute contract values while solar installation velocity accelerates fastest due to modular deployment timelines. Mega projects above 1,000 MW concentrate margin pools and foreign contractor participation, whereas small-to-medium scale distributed solar and industrial captive plants expand addressable volume for domestic EPC firms.
Vietnam's Ministry of Industry and Trade implements Power Development Plan 8, which mandates technology-specific capacity targets and licensing pathways that directly shape EPC contractor qualification requirements and project bankability. The country's national construction standards and EVN technical codes govern equipment specifications, interconnection protocols, and environmental compliance thresholds for all generation assets. Stakeholders must monitor PDP8 implementation pace, LNG import infrastructure readiness, and offshore wind regulatory framework finalization to align bidding strategies with actual project commissioning timelines.
Market Dynamics
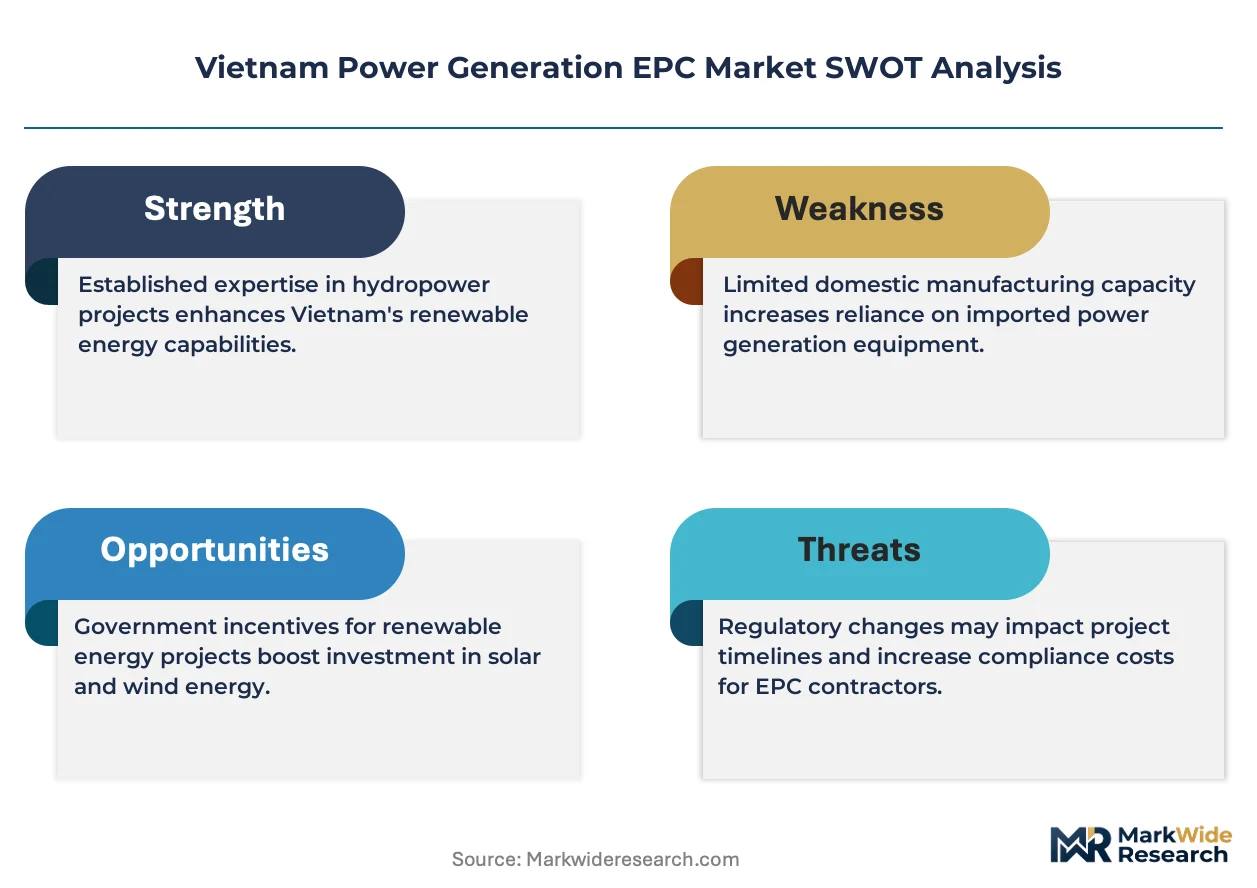
Vietnam's power generation EPC sector is being restructured by the Ministry of Industry and Trade's enforcement of PDP8 technology mandates, which are redirecting contractor qualification requirements toward LNG infrastructure and offshore wind capabilities while phasing out coal-fired development approvals.
Growth Catalysts
- PDP8 renewable targets:Vietnam's Power Development Plan 8 mandates specific capacity additions for solar and offshore wind, creating licensed project pipelines that require EPC execution under standardized technical codes.
- LNG import terminal buildout:Thi Vai and Son My LNG receiving infrastructure is reaching operational readiness, enabling gas-to-power EPC contracts that synchronize generation assets with fuel supply certainty.
- Industrial zone load centers:Manufacturing clusters in Binh Duong, Bac Ninh, and Hai Phong are driving captive power demand that bypasses EVN grid dependency and accelerates distributed EPC awards.
Market Restraints
- Equipment import dependency:Heavy gas turbines, offshore wind foundations, and high-voltage transformers concentrate supply among Korean, Japanese, and European fabricators, exposing projects to currency volatility and extended lead times.
- Offshore wind regulatory latency:Vietnam's marine spatial planning and seabed leasing frameworks remain under inter-ministerial negotiation, compressing bankability timelines for coastal EPC bids.
- Grid interconnection bottlenecks:EVN's transmission expansion in the Central Highlands and Mekong Delta lags behind generation capacity additions, forcing EPC contractors to absorb commissioning delay risks.
Strategic Opportunities
- Floating solar on hydropower reservoirs:Da Mi, Tri An, and Hoa Binh reservoir surfaces offer combined gigawatt-scale potential with simplified permitting and existing transmission access.
- Green hydrogen pilot integration:PDP8's exploratory hydrogen provisions position EPC firms to bundle electrolyzer installation with renewable generation assets for industrial offtake.
- Just Energy Transition Partnership financing:International donor commitments to Vietnam's coal phase-down are unlocking concessional capital that reduces project cost of capital and expands EPC contract viability.
Industry Challenges
- Specialized marine construction skills:Vietnam's domestic labor pool lacks experience in pile driving, heavy-lift vessel coordination, and subsea cable installation required for offshore wind EPC.
- EVN power purchase agreement renegotiation:Retroactive tariff adjustments and delayed payment settlements are eroding investor confidence and complicating EPC contract security structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Power Generation EPC Market |
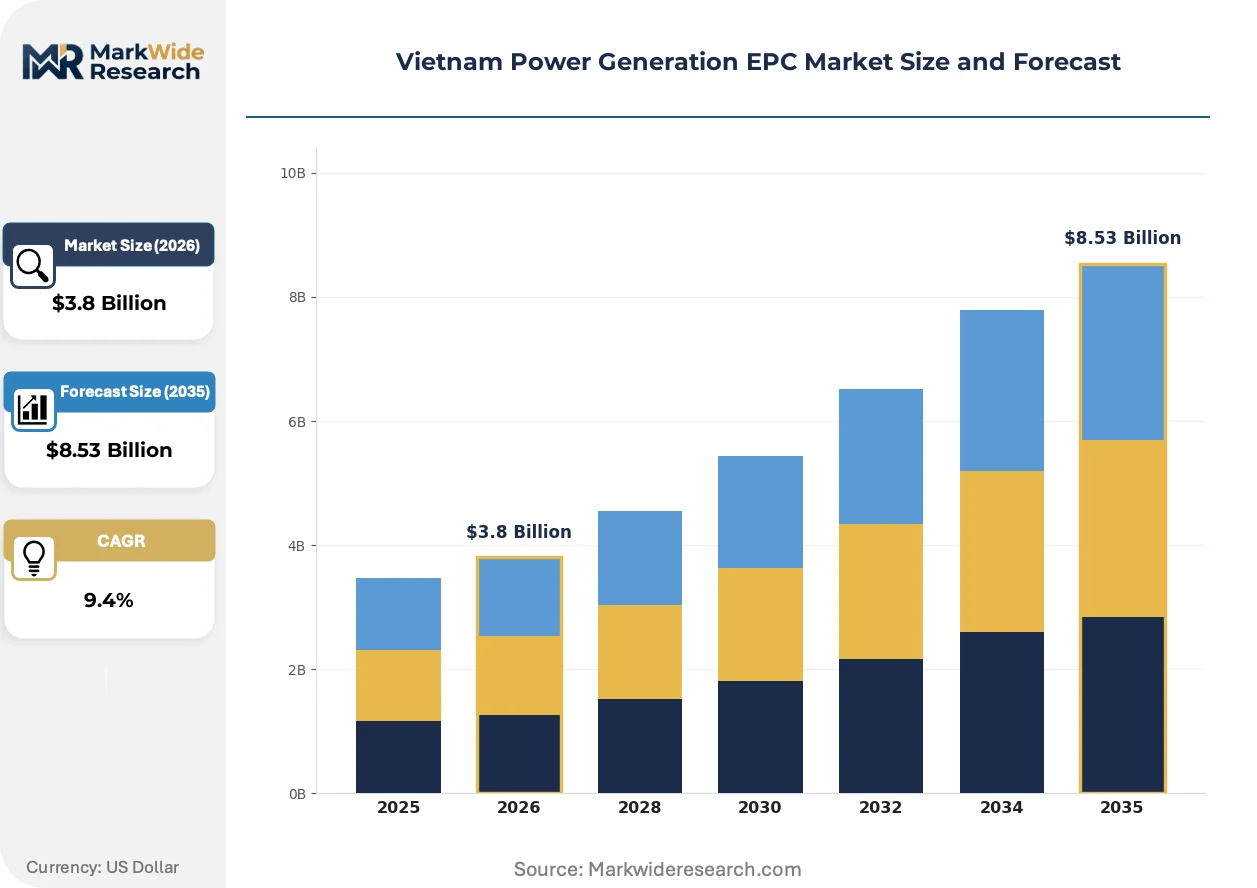
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Procurement, Construction, Commissioning Technology: Thermal, Hydro, Wind, Solar End User: Utilities, Independent Power Producers, Government, Industrial Users Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | GE Vernova, JGC Holdings Corporation, Samsung C&T, Toshiba Corporation, IHI Corporation, Lilama Corporation, Siemens Energy, Power Engineering Consulting JSC 2 (PECC2), Doosan Enerbility, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Power Generation EPC Market Evolving Landscape
Technology convergence and procurement model evolution are compressing project delivery timelines and reshaping contractor competitive requirements across Vietnam's generation infrastructure pipeline.
Modular floating solar platforms are supplanting fixed-tilt ground-mount installations in the Mekong Delta's flood-prone provinces. Industrial developers in Long An and Tien Giang are adopting prefabricated pontoon systems that reduce civil works duration by half. This technology is compressing EPC mobilization schedules and enabling year-round construction windows independent of seasonal hydrology.
Power Development Plan 8's technology-specific licensing pathways are mandating stricter EPC qualification thresholds for offshore wind and LNG-to-power categories. The Ministry of Industry and Trade requires demonstrated marine construction experience and integrated fuel supply chain capabilities as preconditions for bid participation. Domestic contractors without international joint venture partnerships are being excluded from mega-project tenders.
Independent power producers are consolidating engineering and procurement functions in-house while outsourcing construction execution to specialized civil contractors. This unbundling displaces traditional turnkey EPC contracts in distributed solar and industrial captive segments. The restructuring is most visible in southern provinces where Samsung, Foxconn, and Formosa operate multi-site manufacturing footprints requiring standardized but rapidly deployable generation assets.
Vietnam Power Generation EPC Market Segmentation
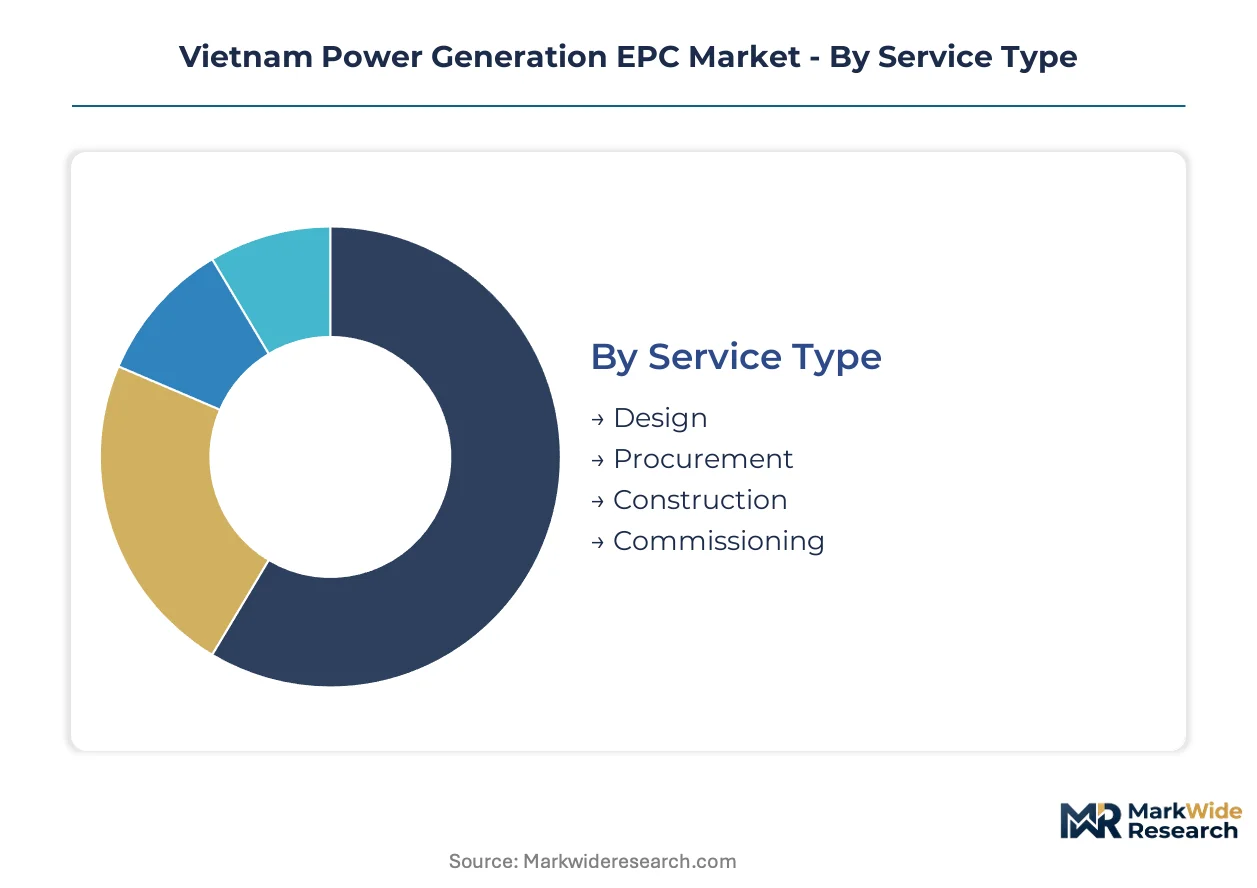
Vietnam's Power Development Plan 8 mandates technology-specific licensing pathways that reshape contractor qualification requirements across each EPC segment. Procurement patterns diverge sharply between state-backed utility projects and private industrial developments, creating distinct margin and risk profiles.
Service Type:
EVN technical codes and Ministry of Industry and Trade construction standards govern deliverable specifications and contractor certification thresholds differently across each service phase.
- Design:Front-end engineering packages must incorporate PDP8-mandated grid interconnection protocols and environmental compliance thresholds. Demand concentrates among international engineering firms bidding LNG-to-power and offshore wind clusters where marine spatial planning requirements add complexity.
- Procurement:Heavy gas turbines, offshore wind foundations, and high-voltage transformers concentrate supply among Korean, Japanese, and European fabricators. Currency volatility and extended lead times are compressing procurement windows for Thi Vai and Son My synchronized projects.
- Construction:Civil works execution spans foundation preparation, equipment installation, and grid interconnection infrastructure. Domestic contractors dominate distributed solar and industrial captive segments while foreign joint ventures capture mega-project awards.
- Commissioning:Final testing and commercial operation date achievement requires EVN grid synchronization approval. Contractors absorb delay risks where transmission expansion in the Central Highlands and Mekong Delta lags generation capacity additions.
Established volume favors Construction; emerging adoption favors Commissioning.
Technology:
PDP8 capacity targets redirect EPC demand toward licensed technology categories while phasing out coal-fired development approvals.
- Thermal:Gas-to-power projects dominate absolute contract values as LNG import terminals reach operational readiness. Thi Vai and Son My infrastructure synchronization is enabling pipeline projects that require integrated fuel supply chain capabilities.
- Solar:Modular deployment timelines are accelerating installation velocity fastest among all technologies. Floating solar platforms on Da Mi, Tri An, and Hoa Binh reservoirs offer gigawatt-scale potential with simplified permitting and existing transmission access.
- Wind:Offshore clusters along the south-central coast concentrate developer interest pending marine spatial planning finalization. Domestic labor pools lack pile driving, heavy-lift vessel coordination, and subsea cable installation experience.
- Hydro:Reservoir-based floating solar hybridization is extending asset utilization of existing infrastructure. Run-of-river developments face site saturation in the Central Highlands.
Thermal commands current margin pools; solar climbs the fastest.
End User:
Procurement authority fragmentation between state and private capital is restructuring contract security structures and payment terms.
- Utilities:EVN-led procurement anchors mega-project pipelines under standardized power purchase agreement frameworks. Retroactive tariff adjustments and delayed payment settlements are eroding contractor confidence.
- Independent Power Producers:Private developers in LNG and renewable segments are consolidating engineering and procurement in-house while outsourcing construction execution. This unbundling displaces traditional turnkey contracts in distributed solar.
- Government:Ministry of Industry and Trade direct awards support strategic infrastructure and Just Energy Transition Partnership financed projects. Concessional capital reduces project cost of capital.
- Industrial Users:Manufacturing clusters in Binh Duong, Bac Ninh, and Hai Phong are driving captive power demand that bypasses EVN grid dependency. Samsung, Foxconn, and Formosa operate multi-site footprints requiring standardized rapid deployment.
Utilities retain project scale; industrial users gain share fastest.
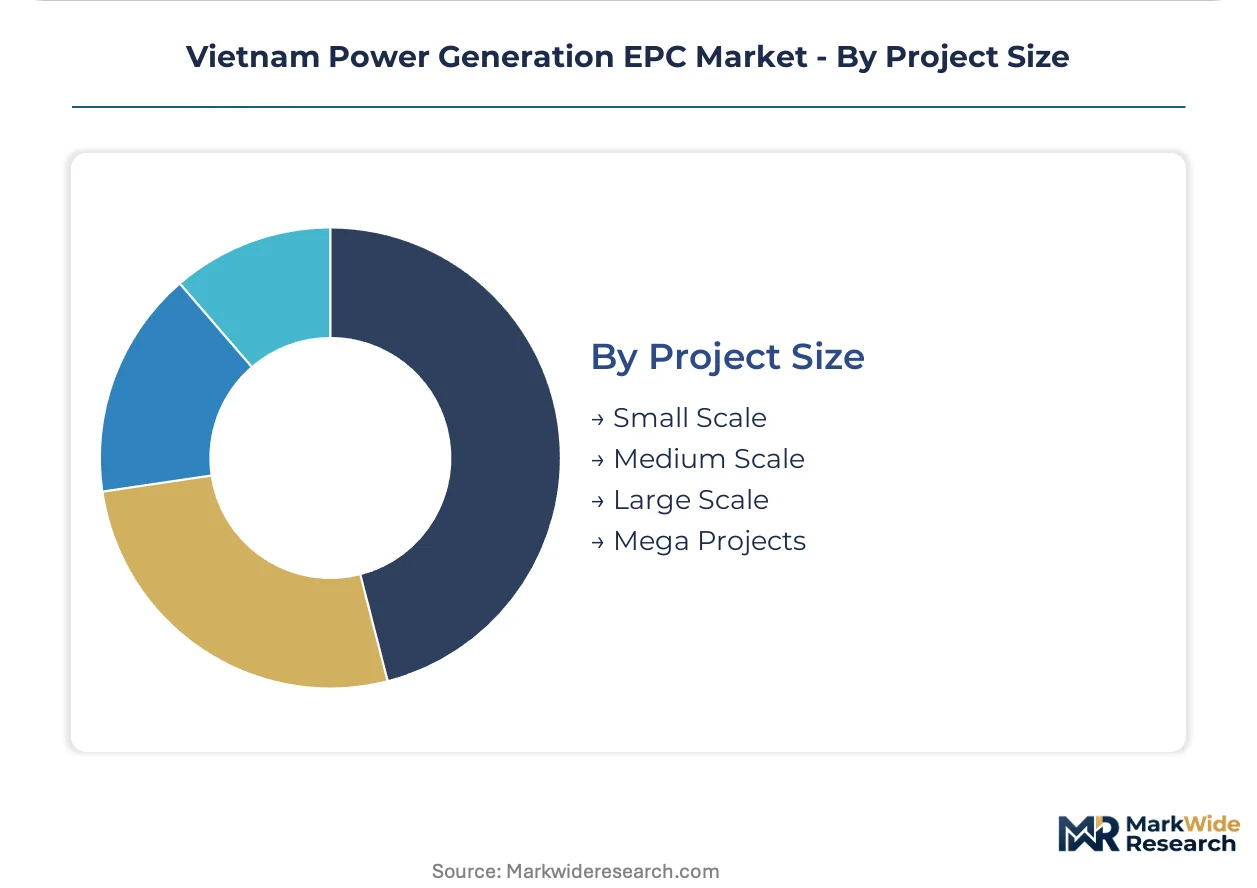
Project Size:
Contractor qualification thresholds and financing structures diverge across scale tiers, concentrating foreign participation at the upper end.
- Mega Projects:Developments above 1,000 MW concentrate margin pools and require demonstrated marine construction experience or integrated fuel supply chain capabilities. International joint venture partnerships are mandatory for bid participation.
- Large Scale:Grid-connected assets between 500-1,000 MW balance domestic and foreign contractor involvement. EVN technical codes govern equipment specifications and interconnection protocols.
- Medium Scale:Distributed generation and industrial captive plants expand addressable volume for domestic EPC firms. Prefabricated pontoon systems are compressing mobilization schedules.
- Small Scale:Rooftop and behind-the-meter installations serve manufacturing load centers with rapid deployment timelines. Standardized but rapidly deployable assets dominate procurement.
Mega projects capture premium margins; small scale expands volume fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Independent power producers and state utilities concentrate EPC procurement across Vietnam's coastal and delta regions, with project pipelines clustering where LNG terminals, industrial zones, and renewable resources align.
Southeast Region
Ho Chi Minh City and surrounding provinces anchor gas-to-power demand as Thi Vai LNG terminal reaches operational readiness. The Ministry of Industry and Trade licenses projects under PDP8 mandates that synchronize generation assets with fuel supply infrastructure. Dong Nai and Ba Ria-Vung Tau host manufacturing clusters driving captive power EPC awards.
Mekong Delta
Floating solar platforms on Da Mi and Tri An reservoirs concentrate developer interest due to simplified permitting and existing transmission access. EVN technical codes govern interconnection protocols for reservoir-based hybridization projects. Long An and Tien Giang provinces adopt prefabricated pontoon systems that compress civil works duration.
South-Central Coast
Offshore wind clusters along Binh Thuan and Ninh Thuan coastlines await marine spatial planning finalization. The country's national construction standards impose qualification thresholds requiring demonstrated marine construction experience for bid participation. Domestic contractors lacking international joint venture partnerships face exclusion from mega-project tenders.
Red River Delta
Hanoi-centered load growth drives transmission expansion requirements that lag behind generation capacity additions. Bac Ninh and Hai Phong industrial zones bypass EVN grid dependency through captive power procurement. Northern provinces absorb commissioning delay risks where grid interconnection bottlenecks persist.
Central Highlands
Run-of-river hydro site saturation redirects EPC attention toward reservoir floating solar hybridization. EVN procurement anchors utility-scale pipelines under standardized power purchase agreement frameworks. Gia Lai and Dak Lak provinces face grid interconnection constraints that compress contractor margin structures.
Vietnam Power Generation EPC Market Competitive Landscape
Player mix skews toward integrated construction-engineering platforms and specialized technology providers, with foreign joint ventures capturing mega-project awards above 1,000 MW. Market structure concentrates premium margin pools among contractors possessing marine construction capabilities or integrated fuel supply chain expertise. Three archetypes dominate: Korean-Japanese conglomerates with heavy fabrication heritage, European turbine technology specialists, and domestic state-linked builders with infrastructure relationships. Competitive moves center on strategic partnerships for technology licensing and capacity expansion into floating solar and LNG infrastructure segments.
Among Korean-Japanese conglomerates, Samsung C&T and JGC Holdings Corporation exemplify the integrated construction-engineering archetype, while GE Vernova occupies a position within the turbine technology specialist tier. Lilama Corporation anchors the domestic state-linked builder category with heavy fabrication capabilities. These three companies represent the competitive spectrum spanning foreign technology leadership to local infrastructure relationships.
| Leading Market Players |
|---|
| GE Vernova |
| JGC Holdings Corporation |
| Samsung C&T |
| Toshiba Corporation |
| IHI Corporation |
| Lilama Corporation |
| Siemens Energy |
| Power Engineering Consulting JSC 2 (PECC2) |
| Doosan Enerbility |
| Others |
Value Network & Pricing Analysis
Long-term power purchase agreements with EVN lock in supply access and price visibility for EPC contractors executing PDP8-mandated projects, synchronizing fuel cost pass-through mechanisms with LNG import terminal readiness. This contract structure concentrates pricing power among integrated developers capable of underwriting fuel supply chain integration and grid interconnection risk.
Pricing Analysis
Cost-plus contracts with steel and copper indexation dominate thermal EPC awards, protecting margins against raw material volatility while compressing absolute returns through competitive bidding. Price differentiation separates turnkey mega-project premiums from unbundled construction-only awards in distributed solar. Pricing pressure stems from EVN payment settlement delays and retroactive tariff adjustments eroding investor confidence. Industrial captive buyers in Bac Ninh and Hai Phong exhibit highest price sensitivity due to standardized equipment specifications, while LNG-to-power developers absorb premium engineering costs for bankability assurance.
Supply Chain Analysis
Japan and South Korea anchor heavy gas turbine fabrication, with Mitsubishi Power and Doosan Enerbility controlling high-capacity unit supply for Thi Vai-synchronized projects. China dominates photovoltaic module and floating solar pontoon manufacturing, while European fabricators supply offshore wind foundations and high-voltage transformers. Raw material dependencies rest on nickel-alloy forgings for turbine rotors, rare earth elements for permanent magnet generators, and copper for submarine cable cores. Single-source vulnerability concentrates in Korean heavy-lift vessel chartering for offshore wind installation. Distribution runs through state-linked procurement portals for EVN-awarded contracts and direct bilateral negotiation for industrial captive developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's power generation EPC market rewards service-attach strategies as commissioning and long-term O&M contracts expand faster than hardware installation revenue, driven by EVN's operational outsourcing mandates and IPP asset management unbundling.
For Market Incumbents: Fortify marine construction capabilities through Korean or European joint venture partnerships to qualify for offshore wind mega-project tenders under PDP8 licensing thresholds. Deepen backward integration into LNG fuel supply chain coordination, as Thi Vai terminal synchronization becomes a decisive bid evaluation criterion displacing pure engineering competence.
For New Entrants and Emerging Players: Lead with floating solar installation specialization targeting Da Mi and Tri An reservoir hybridization projects, where simplified permitting and existing transmission access lower capital barriers. Penetrate industrial captive segments in Long An and Tien Giang through standardized prefabricated pontoon systems that compress mobilization schedules against traditional civil contractors.
For Investors and Strategic Acquirers: Domestic EPC firms with state-backed infrastructure relationships and heavy fabrication yards represent acquisition targets positioned for PDP8 implementation acceleration. Long-term viability hinges on contractor qualification threshold compliance rather than pure scale. Monitor marine spatial planning finalization as the inflection indicator unlocking offshore wind bankability and coastal EPC contract velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Marine Construction Joint Venture | Korean-European partnerships satisfy PDP8 offshore wind qualification thresholds for bid participation. |
| LNG Supply Chain Integration | Fuel terminal synchronization capabilities differentiate Thi Vai-linked project execution. |
| Floating Solar Platform Specialization | Prefabricated pontoon systems capture reservoir hybridization demand under expedited permitting. |
| Commissioning Service Expansion | EVN outsourcing mandates accelerate O&M contract attach rates beyond hardware installation. |
| Industrial Captive Standardization | Multi-site deployment protocols serve Samsung and Foxconn manufacturing footprint requirements. |
Research Methodology
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings across Vietnam's power generation EPC landscape. Utility planning officers at EVN, IPP project developers executing PDP8-licensed pipelines, EPC contractors bidding LNG and offshore wind clusters, grid operators managing Central Highlands interconnection constraints, and fuel supply specialists coordinating Thi Vai terminal synchronization provided structured input. Secondary validation drew from Ministry of Industry and Trade licensing disclosures, EVN technical code publications, project development databases tracking commercial operation dates, and Power Development Plan 8 implementation bulletins. Bottom-up project pipeline aggregation and top-down macro capacity target reconciliation ensured triangulated demand estimation.
Sensitivity analysis around PDP8 implementation pace, LNG import infrastructure readiness, and offshore wind regulatory finalization frames the forecast uncertainty. Segmentation dimensions span fuel source, generation capacity tier, project scale, procurement authority, and regional grid type. CAGRs derive from technology-specific installation velocity differentials and contract value concentration patterns across mega-project and distributed segments. Forecast inputs incorporate marine construction labor pool development timelines and floating solar platform cost curves.
The analysis sits within stated boundaries; outcomes outside PDP8 enforcement consistency, EVN payment settlement reliability, or marine spatial planning resolution would require recalibration. Forecasts reflect documented assumptions regarding technology licensing pathway stability and international donor financing disbursement for Just Energy Transition Partnership projects. Recalibration cycles align with material shifts in PDP8 implementation pace and LNG terminal operational commissioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Venezuela Power Market
Power Generation
Subsea Power Grid System Market
Power Generation
Peaking Power Plant Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
United Kingdom Combined Heat and Power (CHP) Market
Power Generation
Thermal Power Market
Power Generation
Mexico Combined Heat and Power Market
Power Generation
Residential Solar Generator Market
Power Generation
Global Gensets Market
Power Generation
Global Power Grid System Market
Power Generation
Combined Cycle Gas Turbine Market
Power Generation
South East Asia Power Market
Power Generation
North America Distributed Power Generation Market
Power Generation
Power Generation Technologies Market
Power Generation
Malaysia Power Market
Power Generation
On-Grid Combined Heat and Power Market