
 Australia Smart Furniture Market | 2026-2036
Australia Smart Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Smart Furniture Market Insights
Mid-range specification tiers with embedded sensor arrays and programmable height memory is collapsing into premium positioning as Australian buyers expect app connectivity at mainstream price points. Steelcase leverages its ergonomic research legacy to dominate commercial fit-outs in Melbourne and Sydney. MillerKnoll anchors its presence through design-forward smart seating that competes in high-end residential channels. Ergotron specializes in monitor-arm-integrated desk systems that control the corporate wellness segment.
Smart furniture comprises electronically augmented seating, surfaces, and storage systems incorporating sensors, actuators, and network interfaces to enable automated positional adjustment, environmental feedback, or power delivery. These systems typically integrate load cells for posture detection, linear actuators rated to 150 kg dynamic capacity, and Bluetooth Low Energy modules for smartphone pairing, serving to reduce musculoskeletal strain and optimize spatial utilization in occupied environments. Smart desks with IoT-enabled height tracking and wireless charging pads currently lead product-type revenue pools, while voice control modules represent the fastest-expanding technology layer as natural-language processing migrates from consumer electronics into built environments. Commercial offices command the dominant end-user share, though educational institutions are emerging as a concentrated growth corridor as Australian universities retrofit collaborative learning spaces.
TGA electrical safety standards and the EESS registration framework govern embedded power systems and battery-operated furniture components sold in Australia, creating compliance barriers that favor established suppliers with in-house certification capabilities. The ACCC's mandatory reporting requirements for consumer goods with integrated electronics further shape product development cycles and warranty structures. Stakeholders must monitor how impending updates to AS/NZS 3820 electromagnetic compatibility standards will affect sensor density and wireless protocol choices in next-generation designs.
Market Dynamics
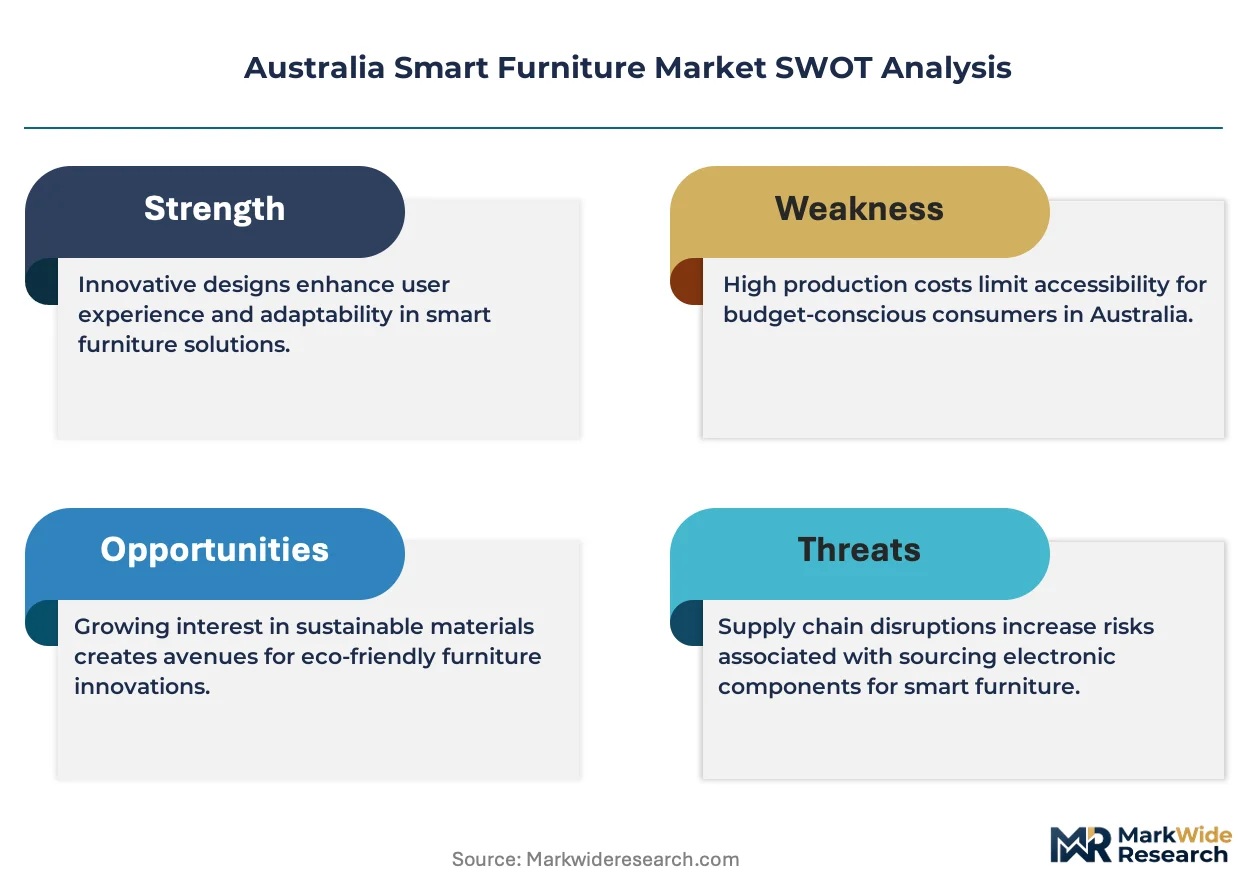
The Therapeutic Goods Administration's EESS registration framework and ACCC product safety mandates are compressing supplier margins while accelerating consolidation among manufacturers with in-house certification capabilities. Embedded sensor transparency requirements and electromagnetic compatibility standards are forcing redesign cycles that favor capital-rich incumbents over import-dependent distributors.
Growth Catalysts
- ACCC Consumer Goods Safety Mandates:Mandatory reporting for integrated electronics is pushing commercial buyers toward certified suppliers with traceable component chains, locking out gray-market imports.
- New South Wales Commercial Fit-Out Density:Sydney's premium office stock renewal is concentrating demand for IoT-enabled ergonomic workstations with programmable height memory.
- Bluetooth Low Energy Module Costs:Declining semiconductor pricing is enabling app connectivity at mid-range specification tiers, collapsing the premium-mainstream boundary.
Market Restraints
- AS/NZS 3820 Compliance Burden:Electromagnetic compatibility testing for sensor-dense furniture adds 8-14 weeks to product development cycles, freezing smaller competitors.
- Linear Actuator Supply Concentration:Dynamic load-rated actuators above 150 kg capacity source primarily from German and Chinese suppliers, exposing Australian assemblers to freight cost volatility.
- Manual Height-Adjustable Desks:Crank-operated alternatives without embedded electronics satisfy price-sensitive segments in regional Queensland and Western Australia, capping smart furniture penetration.
Strategic Opportunities
- Victorian Educational Institution Retrofit:Melbourne and Geelong universities are replacing static lecture hall seating with collaborative smart benches, creating a concentrated public-sector demand corridor.
- Voice Control Module Integration:Natural-language processing hardware from consumer electronics supply chains is converging with furniture embedded systems, enabling hands-free positional adjustment.
- Climate-Responsive Surface Coatings:Phase-change materials that regulate thermal comfort are opening specification opportunities in Perth's extreme-temperature commercial environments.
Industry Challenges
- Firmware Security Certification:TGA's pending guidance on networked medical-adjacent furniture is creating uncertainty around penetration testing requirements for posture-monitoring seats.
- Legacy Building Electrical Infrastructure:Pre-2010 commercial stock in Brisbane and Adelaide lacks sufficient outlet density and circuit capacity for powered furniture deployment at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Smart Furniture Market |
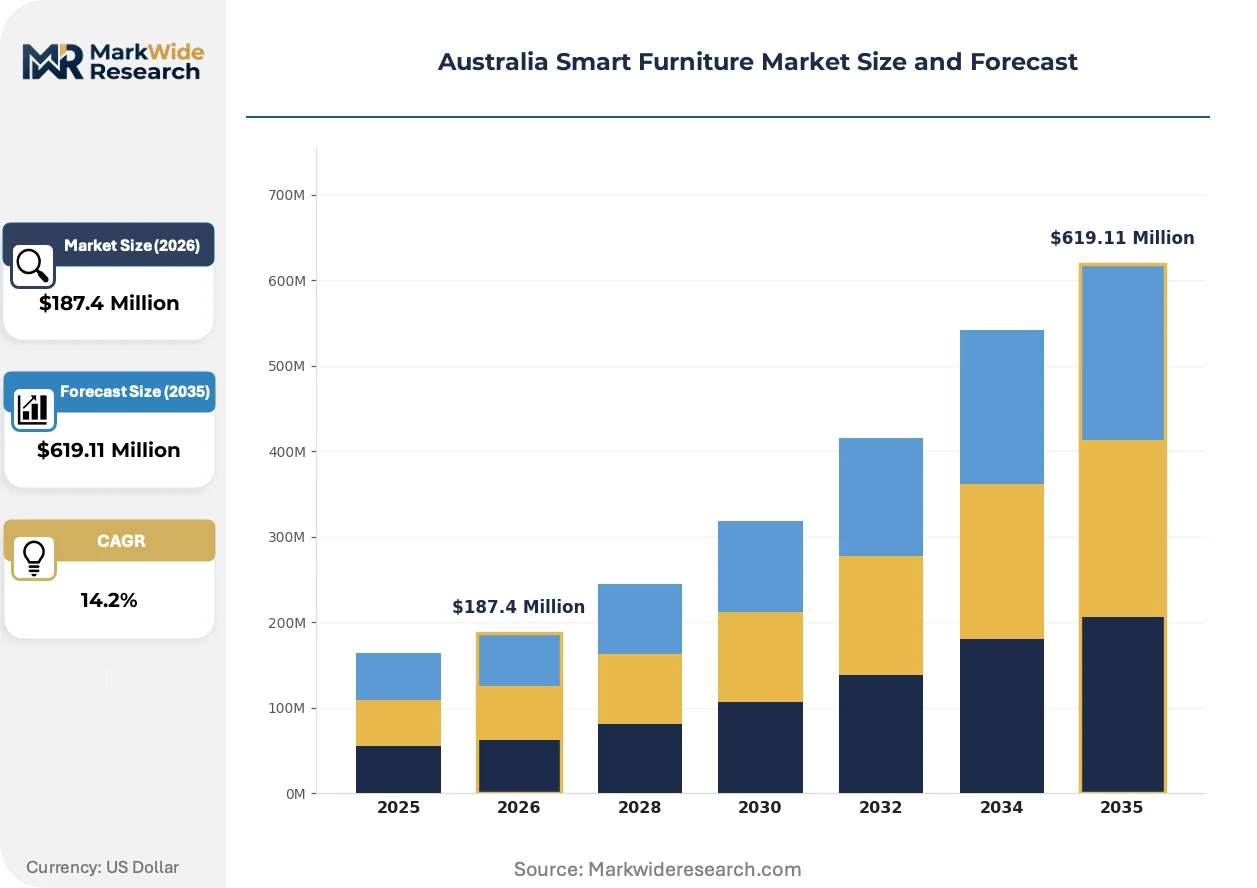
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Desks, Smart Chairs, Smart Sofas, Smart Tables Technology: IoT Enabled, Wireless Charging, Voice Control, App Integration End User: Residential, Commercial Offices, Educational Institutions, Hospitality Functionality: Ergonomic Adjustability, Space Optimization, Environmental Monitoring, Energy Efficiency |
| Companies Covered | Steelcase, MillerKnoll, Haworth, Humanscale, IKEA, Vitra, Okamura Corporation, Ergotron, HNI Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Smart Furniture Market Trends and Innovations
Sensor-augmented furniture is fragmenting into two divergent design philosophies: wellness-optimized systems with biometric feedback loops versus productivity-focused configurations emphasizing spatial analytics. This technical schism is reshaping how manufacturers allocate R&D resources and which buyer segments they prioritize.
Capacitive load cells with real-time posture detection is bifurcating the ergonomic seating category. Corporate wellness programs in Melbourne's financial district are specifying biometric-enabled chairs at triple the rate of standard smart seating. This capability compression is collapsing the distinction between premium ergonomic brands and mid-tier suppliers with white-label sensor integration.
The ACCC's mandatory reporting requirements for consumer goods with integrated electronics is tightening warranty liability frameworks. Manufacturers must now maintain 10-year component traceability records, favoring vertically integrated production over outsourced assembly. Commercial office specifiers in Sydney are demanding documented compliance chains before contract execution.
Facility managers are unbundling furniture procurement from integrated technology service contracts. Direct purchasing of smart desks through procurement platforms is displacing bundled fit-out packages previously dominated by interior design consultancies. This channel fragmentation is most pronounced in Victorian government office renewals, where separate IT and facilities budgets prevent consolidated vendor selection.
Australia Smart Furniture Market Segmentation
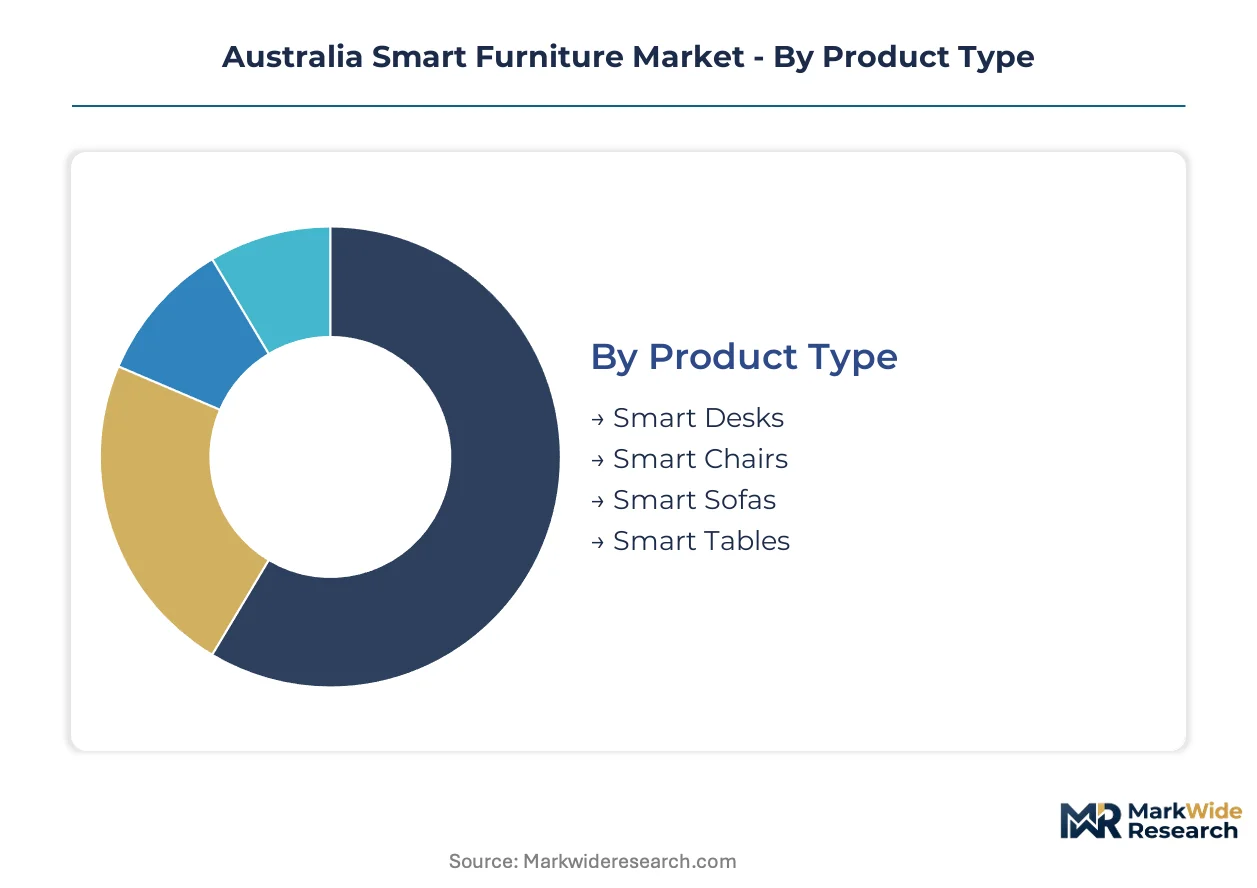
Segmentation reveals how TGA electrical safety standards and ACCC reporting mandates reshape competitive positioning across product tiers. Certification requirements fragment the supplier base differently across residential, commercial, and institutional channels.
Product Type:
Regulatory differentiation separates certified electrical assemblies from gray-market imports, with TGA's EESS registration creating tiered compliance barriers that favor capitalized manufacturers.
- Smart Desks:Linear actuator systems with programmable height memory and embedded load cells dominate commercial fit-outs in Sydney and Melbourne. New South Wales office renewals specify IoT-enabled height tracking with wireless charging pads, though AS/NZS 3820 electromagnetic testing adds 8-14 weeks to development cycles.
- Smart Chairs:Capacitive load cells with real-time posture detection bifurcate the ergonomic seating category. Melbourne's financial district corporate wellness programs specify biometric-enabled chairs at triple the rate of standard smart seating, compressing the premium-mid-tier boundary.
- Smart Sofas:Climate-responsive surface coatings with phase-change materials open specification opportunities in Perth's extreme-temperature environments.
- Smart Tables:Collaborative smart benches with embedded power delivery gain traction in Victorian educational retrofits.
Established volume favors smart desks; emerging adoption favors smart chairs.
Technology:
Cost tier stratification collapses as declining semiconductor pricing enables premium connectivity features at mainstream price points.
- IoT Enabled:Bluetooth Low Energy modules paired with cloud analytics platforms enable posture tracking and usage analytics. Victorian government office renewals separate IT and facilities budgets, fragmenting procurement channels for networked furniture systems.
- Voice Control:Natural-language processing hardware from consumer electronics supply chains converges with furniture embedded systems. This layer expands most quickly as hands-free positional adjustment migrates from smart speakers into built environments.
- Wireless Charging:Qi-standard pads integrated into desk surfaces satisfy commercial office power delivery requirements without cable management.
- App Integration:Smartphone pairing with programmable memory settings now expected at mid-range specification tiers.
Volume concentration sits with IoT-enabled systems; steepest expansion trajectory belongs to voice control modules.
End User:
Customer type determines warranty liability exposure, with ACCC's 10-year component traceability requirements favoring vertically integrated suppliers in institutional channels.
- Commercial Offices:Sydney's premium office stock renewal concentrates demand for ergonomic workstations with embedded sensor arrays. Facility managers unbundle furniture procurement from technology service contracts, displacing bundled fit-out packages.
- Residential:Sydney and Melbourne buyers upgrade living spaces with app-controlled seating and climate-responsive surfaces, expecting premium connectivity at mainstream price points.
- Educational Institutions:Melbourne and Geelong universities replace static lecture hall seating with collaborative smart benches, creating concentrated public-sector demand.
- Hospitality:Phase-change material surfaces address thermal comfort in Perth's extreme-temperature commercial environments.
Revenue scale favors commercial offices; policy tailwinds favor educational institutions.
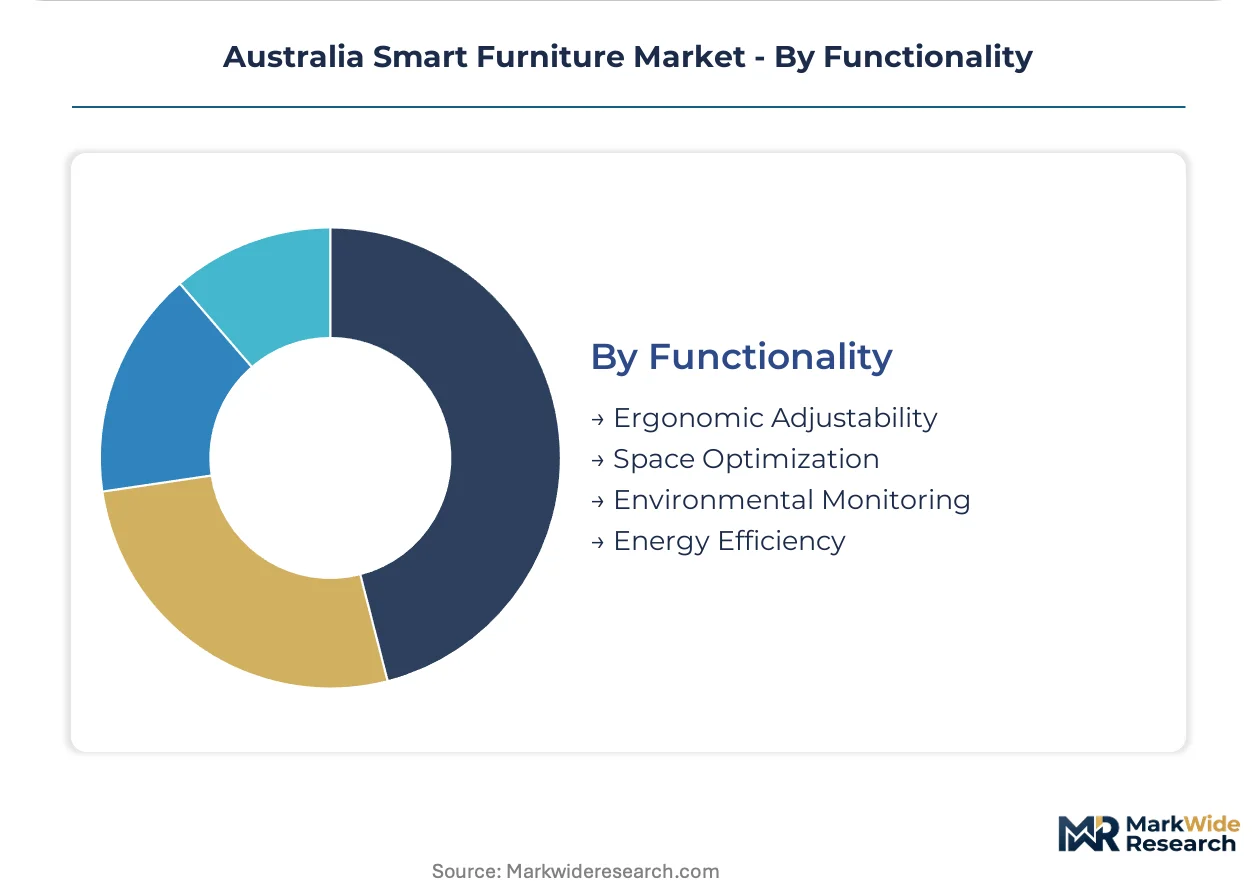
Functionality:
Application focus splits between wellness-optimized biometric feedback and productivity-focused spatial analytics, reshaping R&D allocation across manufacturer portfolios.
- Ergonomic Adjustability:Programmable height memory and automated positional adjustment reduce musculoskeletal strain in occupied environments. Demand clusters heavily around this capability in New South Wales and Victoria commercial offices.
- Environmental Monitoring:Embedded sensors track thermal comfort, air quality, and occupancy patterns. Firmware security certification uncertainty around TGA's pending guidance on networked medical-adjacent furniture creates compliance hesitation.
- Space Optimization:Usage analytics enable facility managers to right-size floor plates and reduce real estate overhead.
- Energy Efficiency:Power management systems reduce standby consumption in battery-operated furniture components governed by EESS registration.
Specification frequency favors ergonomic adjustability; regulatory complexity favors environmental monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component sourcing for smart furniture tilts heavily toward German and Chinese linear actuator suppliers, exposing Australian assemblers to freight cost volatility and extended lead times. New South Wales and Victoria absorb the bulk of domestic demand, driven by commercial office renewals and educational institution retrofits.
New South Wales
Sydney's premium office stock renewal concentrates procurement for IoT-enabled ergonomic workstations with programmable height memory. The ACCC's mandatory reporting requirements for integrated electronics push facility managers toward certified suppliers with traceable component chains. Parramatta and North Sydney financial districts specify embedded sensor arrays at triple the rate of standard adjustable furniture.
Victoria
Melbourne's corporate wellness programs drive specification of biometric-enabled chairs with capacitive load cells for real-time posture detection. The state's educational procurement frameworks favor collaborative smart benches in university retrofit projects across Melbourne and Geelong. TGA electrical safety standards govern embedded power systems in public-sector deployments.
Queensland
Brisbane's pre-2010 commercial stock limits powered furniture deployment due to insufficient outlet density and circuit capacity. Manual height-adjustable desks without embedded electronics satisfy price-sensitive segments in regional markets. The EESS registration framework creates compliance barriers for battery-operated furniture components entering from interstate suppliers.
Western Australia
Perth's extreme-temperature commercial environments open specification opportunities for climate-responsive surface coatings with phase-change materials. Mining sector procurement favors durable ergonomic adjustability over IoT connectivity in remote site deployments. The state's distance from eastern manufacturing clusters amplifies freight cost sensitivity for heavy actuator components.
South Australia
Adelaide's legacy building electrical infrastructure constrains large-scale smart furniture rollout in government office renewals. Smaller commercial fit-outs prioritize wireless charging pads and app integration over full sensor arrays. Pending updates to AS/NZS 3820 electromagnetic compatibility standards create hesitation among local specifiers regarding sensor-dense configurations.
Australia Smart Furniture Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Research-intensive incumbents dominate commercial fit-outs with certified electrical assemblies, while import-dependent distributors compete on price in residential channels. Two strategic archetypes prevail: ergonomic research specialists with in-house certification capabilities, and design-forward seating manufacturers targeting high-end residential buyers. Competitive moves center on unbundling furniture procurement from technology service contracts, and accelerating firmware security certification ahead of TGA guidance.
Among research-led ergonomic specialists, Steelcase leverages its legacy to anchor commercial positioning in Melbourne and Sydney. MillerKnoll occupies a position within the design-forward tier, competing through aesthetic differentiation in premium residential channels. Ergotron exemplifies the monitor-arm-integrated specialization that controls corporate wellness segments. These three represent distinct archetype anchors rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Steelcase |
| MillerKnoll |
| Haworth |
| Humanscale |
| IKEA |
| Vitra |
| Okamura Corporation |
| Ergotron |
| HNI Corporation |
| Others |
Pricing and Supply Chain Analysis
TGA's EESS registration framework gates both supply qualification and price differentiation simultaneously, compressing margins for uncertified imports while enabling certified Australian assemblers to command premium positioning in commercial fit-outs.
Pricing Analysis
ACCC product safety mandates dictate the pricing tier structure across the Australian smart furniture landscape. Three-tier pricing structure across premium, standard, and economy levels separates EESS-registered assemblies with full sensor arrays from gray-market imports and manual-adjustable alternatives. Cost compression in mid-range tiers is intensifying because Bluetooth Low Energy module prices are declining, collapsing the premium-mainstream boundary. Residential buyers in Sydney and Melbourne exhibit the least price sensitivity, while regional Queensland and Western Australia markets remain tethered to crank-operated desks.
Supply Chain Analysis
Strategic stockpiling of linear actuators dominates inventory strategy given eight-to-fourteen-week lead times from German and Chinese suppliers. Component sourcing draws from Germany, China, and Taiwan for dynamic load-rated actuators, semiconductor modules, and capacitive sensor arrays. Freight cost volatility from Shanghai and Hamburg ports creates persistent margin exposure for Australian assemblers lacking captive supply of heavy actuator components. Distribution runs through commercial fit-out contractors in New South Wales and Victoria, with direct procurement platforms fragmenting traditional interior design consultancy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's smart furniture sector sits in early-cycle expansion, with Victorian educational retrofits and voice control module adoption providing durable penetration tailwinds through the projection horizon.
For Market Incumbents: Fortify certification capabilities ahead of pending TGA guidance on networked medical-adjacent furniture firmware security. Backward integration into actuator assembly reduces exposure to German and Chinese supplier freight volatility. Channel control through direct procurement platform partnerships locks out import-dependent distributors competing on price. For New Entrants and Emerging Players: Anchor in Queensland and Western Australia regional markets where manual-adjustable alternatives still dominate price-sensitive segments. Perth's extreme-temperature commercial environments present the most penetrable geography for climate-responsive surface coatings. A go-to-market angle targeting mining sector procurement with durable ergonomic adjustability bypasses IoT connectivity requirements that strain legacy electrical infrastructure. For Investors and Strategic Acquirers: TGA's pending EESS registration updates reshape the acquisition landscape toward vertically integrated manufacturers with in-house electromagnetic compatibility testing. Long-term viability over a five-to-ten-year window rests on controlling certification capabilities rather than distribution reach. The signal to watch is AS/NZS 3820 standard revision timing, which would trigger consolidation among sensor-dense furniture specialists unable to absorb redesign cycle costs.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Security Certification | TGA guidance on networked medical-adjacent furniture creates first-mover advantage for compliant suppliers. |
| Voice Control Module Integration | Natural-language processing hardware from consumer electronics supply chains enables hands-free positional adjustment. |
| Educational Institution Retrofit | Melbourne and Geelong universities replace static lecture hall seating with collaborative smart benches. |
| Climate-Responsive Surface Development | Phase-change materials address thermal comfort in Perth's extreme-temperature commercial environments. |
| Direct Procurement Platform Partnership | Victorian government office renewals separate IT and facilities budgets, fragmenting traditional channels. |
Research Methodology
A spread of perspectives from commercial facilities managers, ergonomic furniture procurement officers, university estate directors, and TGA regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against EESS registration databases, ACCC product safety reporting records, and Australian Bureau of Statistics construction activity indices. Bottom-up demand modeling from commercial fit-out permits and top-down market sizing from import trade data were triangulated to establish volume baselines.
Segmentation dimensions modeled include product type, technology layer, end-user category, and functionality focus across the analysis window. CAGRs were derived from regression analysis of historical adoption curves in comparable smart building product categories, adjusted for regulatory compliance lag effects. Key forecast inputs include Bluetooth Low Energy module cost decline trajectories and New South Wales premium office stock renewal pipelines.
Decision-makers should treat outputs as directional under assumptions of stable EESS registration requirements and no major electromagnetic compatibility standard revisions; material deviation would warrant model refresh. Revision becomes warranted when TGA firmware security guidance crosses implementation thresholds or when linear actuator supply concentration shifts dramatically.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Asia-Pacific Luxury Furniture Market
Furniture
Asia Pacific Multifunctional Furniture Market
Furniture
Europe Multifunctional Furniture Market
Furniture
Poland Home Furniture Market
Furniture
Spain Furniture Market
Furniture
India Upholstered Furniture Market
Furniture
Vietnam Furniture Market
Furniture
Pool Tables Market
Furniture
Europe and Middle East Demountable Partitions Market
Furniture
Europe Sustainable Mattress Market
Furniture
Taiwan Home Furniture Market
Furniture
Japan Home Furniture Market
Furniture
Middle East and Africa Free Standing Electrical Height-Adjustable Tables Market
Furniture
Piano Stools Market
Furniture
Canada Secondary Wood Products Market
Furniture
Europe High-End Furniture Market