
 Luxury RTA (Ready-To-Assemble) Furniture Market | 2026-2036
Luxury RTA (Ready-To-Assemble) Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury RTA (Ready-To-Assemble) Furniture Market Insights
Aftermarket service revenue is narrowing as manufacturers integrate white-glove assembly and extended warranties into core offerings. IKEA leverages its global retail footprint to sustain volume leadership in accessible luxury RTA. Herman Miller anchors its position through ergonomic specialization in premium office RTA segments. Poltrona Frau competes on artisan upholstery craftsmanship, occupying a distinct tier above mass-market alternatives.
Luxury RTA furniture denotes high-design, precision-engineered flat-pack products utilizing CNC-machined hardwood substrates, metal cam-and-dowel joinery, and performance-grade fabrics rated for residential or commercial duty cycles, engineered to deliver elevated aesthetics without permanent installation infrastructure. Sofas and cabinets carry the deepest margin pools due to complexity premiums and storage functionality requirements. The hospitality end-user segment registers the fastest structural ascent as boutique hotels adopt luxury RTA for rapid renovation cycles. Wood and upholstery materials dominate value capture, though metal-framed tables gain traction in minimalist commercial interiors.
EPA formaldehyde emission standards and California Air Resources Board (CARB) Phase 2 compliance constrain substrate selection for US-bound manufacturers, while EU REACH and FSC chain-of-custody certification govern European material sourcing. ECHA substance restrictions are progressively eliminating certain flame retardants and finishes, forcing reformulation of premium coatings. Stakeholders must monitor evolving chemical disclosure mandates across multiple jurisdictions to preempt supply chain disruption and sustain market access.
Market Dynamics
REACH substance restrictions and EPA formaldehyde standards are forcing substrate reformulation across the luxury RTA supply chain, compressing margin pools for manufacturers dependent on conventional engineered wood products.
Growth Catalysts
- Boutique Hotel Renovation Cycles:Hospitality operators in Germany and the United States are adopting luxury RTA for rapid room refreshes without structural modification.
- FSC Chain-of-Custody Certification:European sourcing mandates are rewarding manufacturers with verified sustainable timber programs.
- Urban Premium Housing Density:Apartment dwellers in Shanghai and Manhattan are prioritizing space-efficient, high-design flat-pack solutions.
Market Restraints
- Hardwood Substrate Cost Volatility:Baltic birch and white oak pricing swings constrain finished goods margin stability.
- Coating Reformulation Burden:ECHA flame retardant eliminations force premium finish suppliers into multi-year R&D cycles.
- White-Glove Assembly Integration:Consumer expectation of included professional assembly compresses aftermarket service revenue.
Strategic Opportunities
- India Premium Residential:Mumbai and Bangalore luxury apartment stock is expanding faster than domestic high-end furniture supply.
- Metal-Frame Minimalist Tables:Commercial interiors in Copenhagen and Amsterdam are specifying powder-coated steel bases over traditional wood.
- Extended Warranty Bundling:Manufacturers can capture lifetime value through integrated protection plans replacing third-party insurers.
Industry Challenges
- CNC Programming Talent Scarcity:Precision joinery engineering requires specialized operators in short supply across manufacturing clusters.
- Multi-Jurisdiction Chemical Disclosure:California Prop 65, EU SCIP database, and emerging state-level mandates create overlapping compliance documentation.
- Legacy Retailer Integration:Traditional furniture showrooms lack technical infrastructure to display RTA assembly quality effectively.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury RTA (Ready-To-Assemble) Furniture Market |
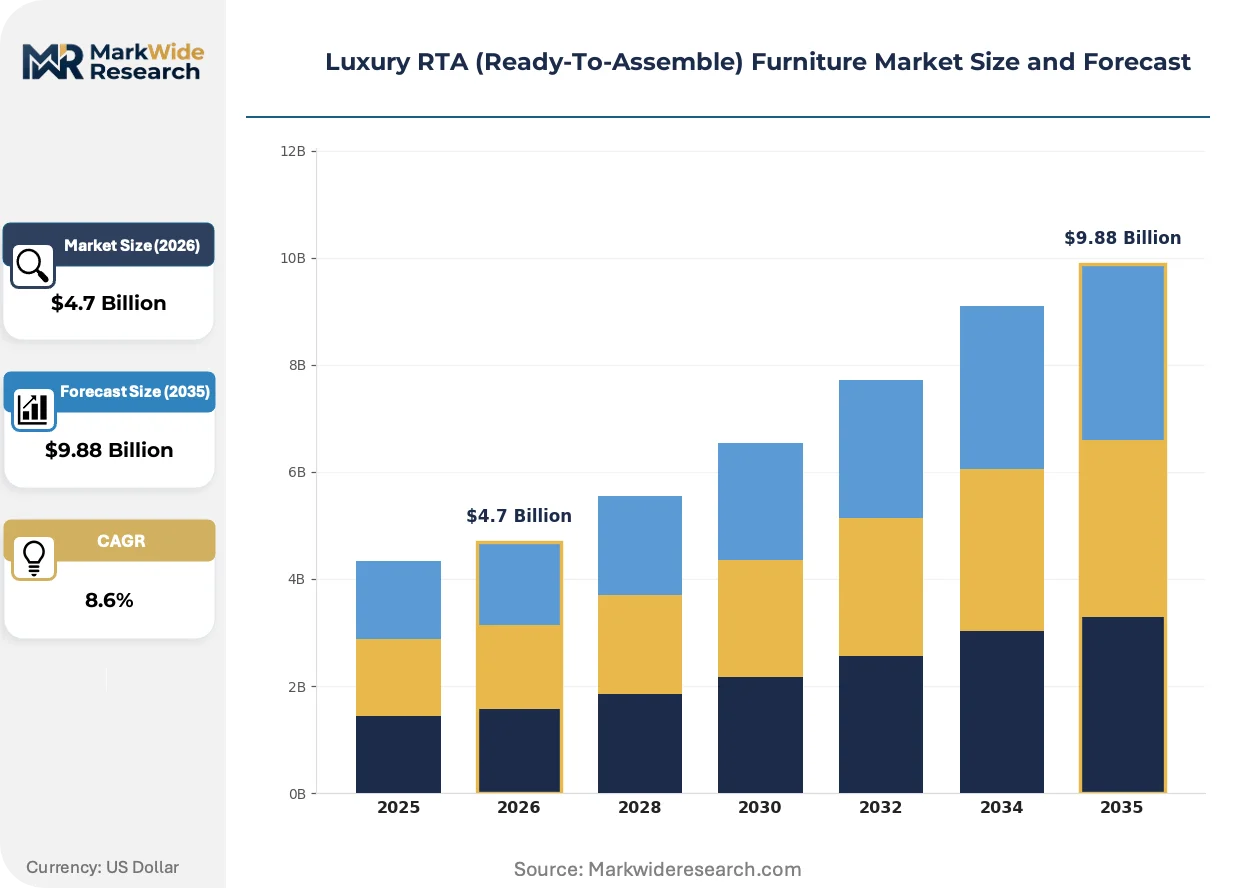
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Cabinets Material: Wood, Metal, Glass, Upholstery End User: Residential, Commercial, Office, Hospitality Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | IKEA, Herman Miller, Steelcase, Poltrona Frau, B&B Italia, Cassina, Roche Bobois, Minotti, Dorel Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury RTA (Ready-To-Assemble) Furniture Market Trends and Innovations
Digital fabrication and material science advances are compressing production lead times while elevating precision tolerances in luxury flat-pack manufacturing.
CNC-machined hardwood substrates with metal cam-and-dowel joinery systems are migrating from niche artisan producers to scaled manufacturing operations. Boutique hotel procurement teams in Copenhagen and Austin are specifying these systems for three-year renovation cycles. The shift is compressing traditional upholstery lead times from twelve weeks to under four.
EU REACH substance restrictions on halogenated flame retardants are forcing coating suppliers into bio-based alternative development. German and Italian finish manufacturers face reformulation timelines extending through certification backlog. Residential upholstery lines bound for European distribution are absorbing the bulk of compliance cost pass-through.
After-sales service unbundling is reversing as manufacturers internalize white-glove assembly and extended protection plans. Direct-to-consumer channels in the United States and Germany are replacing third-party logistics providers with captive installation networks. Hospitality procurement teams now treat bundled service as a table-stakes requirement rather than premium upgrade.
Luxury RTA (Ready-To-Assemble) Furniture Market Segmentation
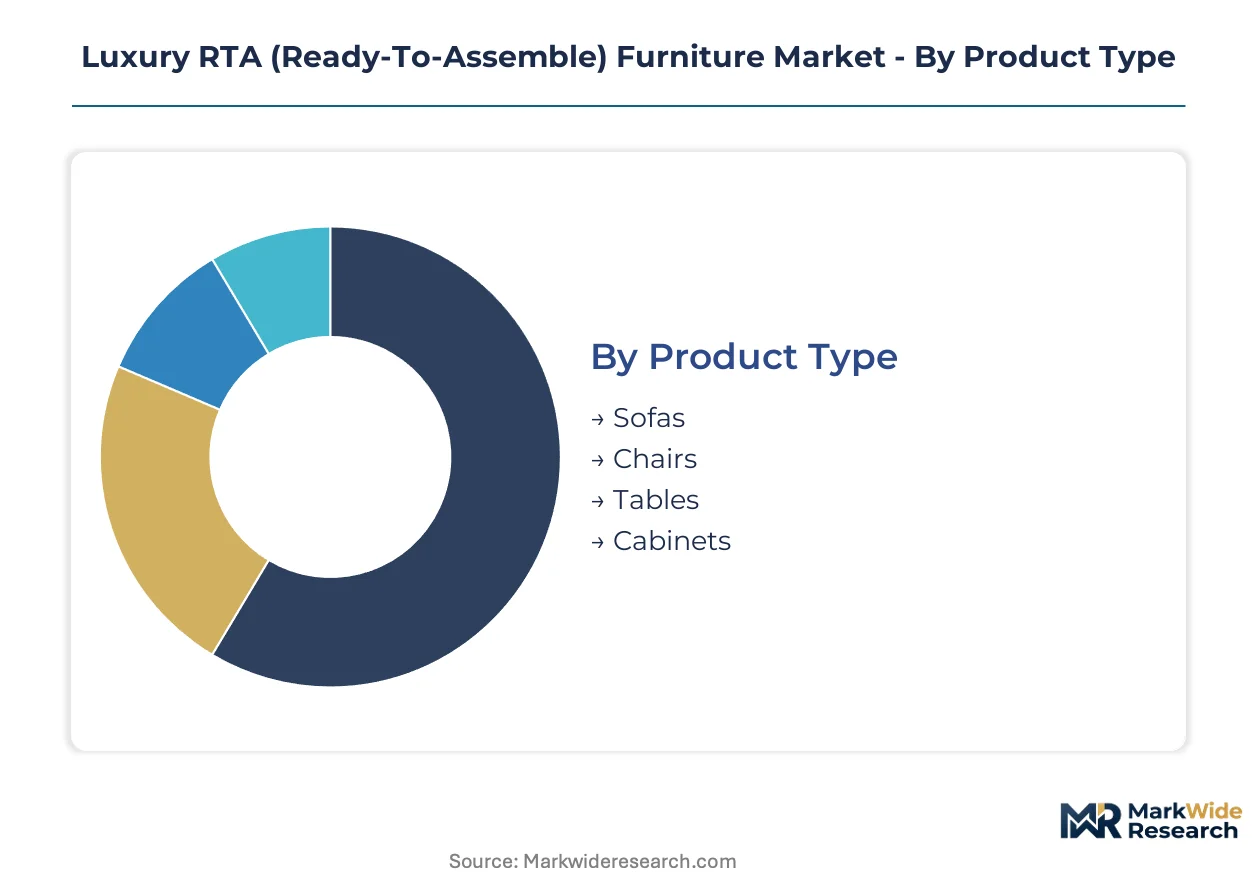
Segmentation in luxury RTA furniture reveals how precision engineering requirements and end-use duty cycles create distinct margin architectures. Product type and material composition determine CNC programming complexity, while distribution channel selection shapes assembly service bundling economics.
Product Type:
Cost tier differentiation separates entry luxury from artisan-grade RTA through joinery precision and upholstery complexity.
- Sofas:Multi-component upholstery systems with CNC-cut hardwood frames and cam-lock joinery engineered for repeated assembly cycles. Demand concentrates in Manhattan and Shanghai luxury apartments where space constraints meet high-design requirements, with hospitality procurement teams specifying these for rapid renovation turnover.
- Cabinets:Modular storage systems utilizing Baltic birch plywood substrates with metal dowel reinforcement and soft-close hardware integration. German boutique hotel operators are standardizing these for bathroom and minibar configurations, driven by three-year refresh cycles without structural permits.
- Chairs:Ergonomic shell constructions with upholstered seat pans and precision-machined leg attachments.
- Tables:Tension-loaded surface systems with leg-to-apron joinery engineered for flat-pack shipment and tool-free assembly.
Cabinets command the established base. The steepest expansion runs through Sofas.
Material:
Application environment dictates substrate selection, with commercial duty cycles requiring performance-grade finishes absent in residential specifications.
- Wood:CNC-machined hardwood substrates including white oak, walnut, and FSC-certified Baltic birch plywood with CARB Phase 2 compliant adhesives. Copenhagen and Amsterdam commercial interiors specify these for durability in high-traffic settings, constrained by EPA formaldehyde emission standards and ECHA substance restrictions on conventional binders.
- Upholstery:Performance-grade fabrics rated for residential or commercial duty cycles with bio-based flame retardant treatments replacing halogenated alternatives. European distribution channels absorb compliance cost pass-through as German and Italian finish manufacturers navigate REACH certification backlogs.
- Metal:Powder-coated steel frames and table bases specified for minimalist commercial interiors.
- Glass:Tempered surface elements with metal edge banding for dining and accent tables.
Wood commands the established base. Upholstery is gaining share fastest.
End User:
Customer type determines assembly service expectations, with commercial accounts demanding white-glove integration unavailable to residential direct-to-consumer channels.
- Hospitality:Boutique hotel and serviced apartment procurement requiring rapid room refresh capability without structural modification. Operators in Germany and the United States specify luxury RTA for three-year renovation cycles, treating bundled assembly and extended warranties as table-stakes rather than premium upgrades.
- Residential:Urban apartment dwellers in premium housing segments prioritizing space-efficient, high-design flat-pack solutions. Shanghai and Manhattan density patterns concentrate demand here, with direct-to-consumer channels replacing third-party logistics with captive installation networks.
- Commercial:Co-working and flexible office space operators specifying ergonomic RTA for rapid layout reconfiguration.
- Office:Corporate procurement of premium ergonomic RTA for satellite locations and expansion floors.
Residential commands the established base. Hospitality shows the steepest climb.
Distribution Channel:
Volume concentration and margin capture diverge sharply between direct channels with captive assembly networks and wholesale relationships with service unbundling.
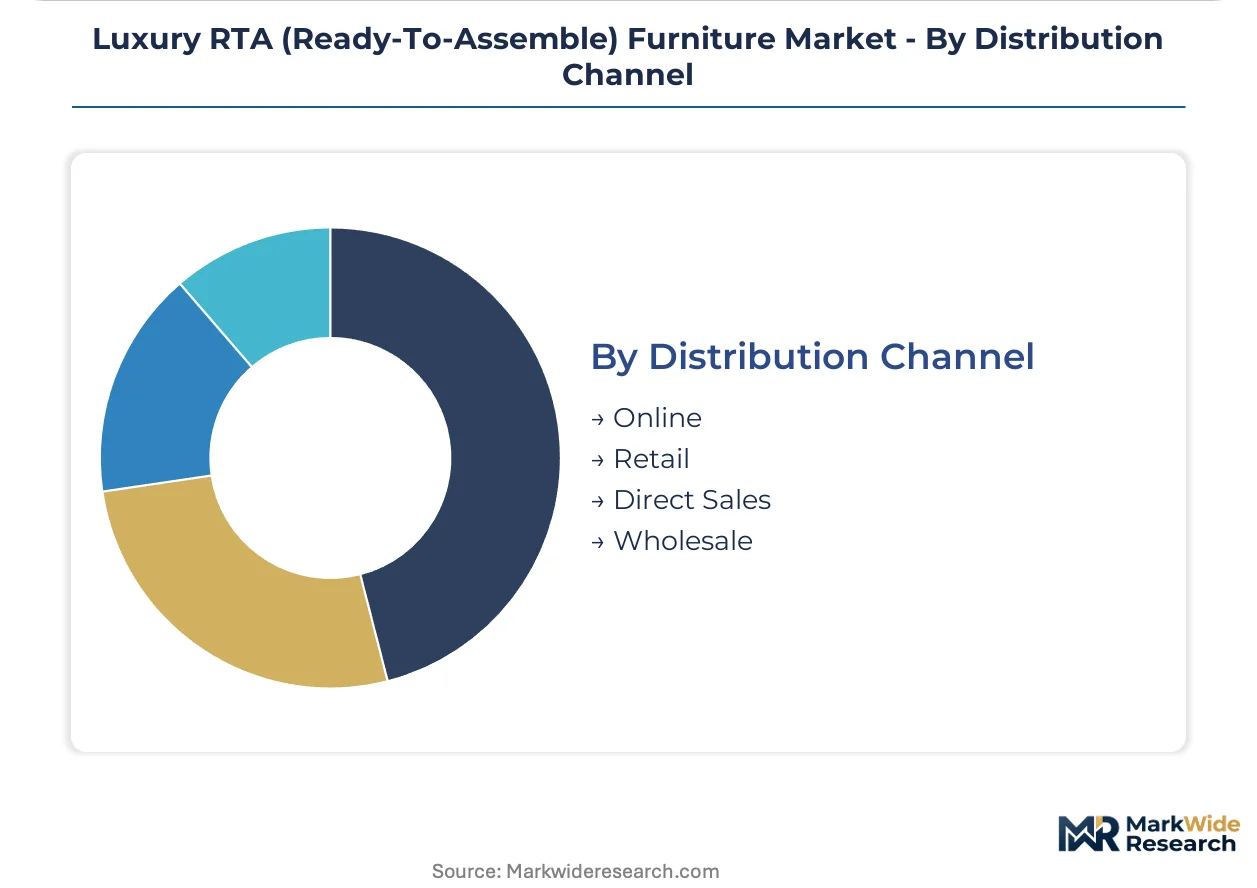
- Online:Direct-to-consumer platforms with integrated white-glove assembly and extended protection plan bundling. United States and Germany channels are internalizing installation networks previously outsourced to third-party logistics providers, compressing aftermarket service revenue for independent operators.
- Retail:Physical showrooms with technical infrastructure challenges in displaying RTA assembly quality effectively.
- Direct Sales:Hospitality and commercial account management with specification consulting and project-based procurement.
- Wholesale:Third-party furniture retailers lacking technical capacity for assembly demonstration and service integration.
Retail commands the established base. Online channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany treats luxury RTA as a compliance-forward procurement category, while the United States consumes it through direct-to-consumer convenience channels. China concentrates demand in premium urban housing clusters. This consumption-mix differential shapes how manufacturers configure assembly service bundling and material certification investments across markets.
United States
Manhattan and Los Angeles luxury apartment dwellers drive demand for space-efficient, high-design flat-pack solutions with integrated white-glove assembly. EPA formaldehyde emission standards and California Air Resources Board Phase 2 compliance constrain substrate selection for domestic manufacturers. Austin and Brooklyn hospitality procurement teams specify CNC-machined hardwood RTA for rapid boutique hotel renovation cycles.
Germany
Berlin and Munich boutique hotel operators adopt luxury RTA for three-year room refresh cycles without structural permits. EU REACH substance restrictions and FSC chain-of-custody certification govern material sourcing requirements for European distribution. Cologne manufacturing clusters specialize in Baltic birch plywood substrates with metal cam-and-dowel joinery systems.
China
Shanghai and Shenzhen premium housing density concentrates demand for precision-engineered flat-pack furniture with performance-grade upholstery. The country's national environmental standards and evolving green building certification programs reshape material compliance frameworks. Guangzhou industrial zones supply CNC-machined hardwood components to domestic and export markets.
Italy
Milan and Rome commercial interiors specify artisan upholstery craftsmanship in RTA configurations for flexible workspace reconfiguration. ECHA flame retardant restrictions force bio-based coating reformulation across Italian finish manufacturers. Brianza manufacturing clusters anchor European production of premium upholstered RTA seating systems.
United Kingdom
London luxury residential developments prioritize flat-pack solutions that navigate tight urban delivery constraints and assembly labor shortages. The country's building safety regulations and post-Grenfell material certification requirements affect specification patterns. Manchester and Birmingham hospitality projects increasingly source EU-compliant RTA for rapid fit-out timelines.
Luxury RTA (Ready-To-Assemble) Furniture Market Competitive Landscape
Capability concentration sits with artisan-grade upholstery specialists; scale advantage sits with global retail fabricators with captive distribution networks. The market structures around three tiers: mass-market accessible luxury, premium ergonomic specialization, and artisan craftsmanship. Consolidation pressure runs through direct-to-consumer channels internalizing assembly services. Dominant competitive moves include backward integration into captive installation networks and portfolio diversification across hospitality and residential end-use segments.
Within the accessible luxury tier, IKEA anchors volume leadership through global retail footprint and integrated supply chain control. Herman Miller occupies a position in premium office RTA through ergonomic specialization and commercial specification relationships. Poltrona Frau exemplifies the artisan-grade tier through heritage upholstery craftsmanship and made-to-order production positioning. These three archetypes represent the competitive vectors shaping margin architecture across mass-market, premium, and luxury positioning.
| Leading Market Players |
|---|
| IKEA |
| Herman Miller |
| Steelcase |
| Poltrona Frau |
| B&B Italia |
| Cassina |
| Roche Bobois |
| Minotti |
| Dorel Industries |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Baltic birch plywood mills across the Baltic states is compressing supplier flexibility and amplifying cost pass-through to finished goods manufacturers. This utilization squeeze simultaneously elevates raw material pricing power and forces buyers into longer-term offtake commitments to secure substrate allocation.
Pricing Analysis
Long-term offtake agreements dominate procurement between major manufacturers and Baltic birch suppliers, insulating volume buyers from spot price volatility while locking in premium tier positions. Price differentiation rests on FSC chain-of-custody certification and white-glove assembly bundling, with certified sustainable lines commanding substantial premiums over conventional alternatives. Cost compression in entry-luxury upholstery is intensifying because REACH compliance costs concentrate disproportionately in fabric treatment processes. Hospitality procurement teams demonstrate lowest price sensitivity, absorbing bundled service premiums; residential direct-to-consumer channels exhibit highest sensitivity, driving unbundled self-assembly options.
Supply Chain Analysis
Extended payment terms from German and Italian finish manufacturers to coating raw material suppliers indicate working capital strain from multi-year bio-based flame retardant reformulation cycles. Manufacturing concentration centers on Germany, Italy, and China, with CNC-machined hardwood components feeding assembly operations across all three markets. Raw material dependencies include Baltic birch plywood, performance-grade upholstery fabrics, and powder-coated steel substrates. Single-source vulnerability runs through REACH-certified coating suppliers facing ECHA certification backlogs. Distribution runs through captive online channels with integrated installation networks replacing third-party logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards precision engineering talent that remains scarce across manufacturing clusters, creating asymmetric returns for firms that secure CNC programming capabilities and certified sustainable timber programs before competitors.
For Market Incumbents: Pre-empt margin erosion in entry-luxury segments by accelerating backward integration into captive Baltic birch plywood supply from certified Baltic sources. Channel control through owned installation networks represents the critical defensive lever against direct-to-consumer entrants unbundling assembly services. ECHA substance restriction timelines threaten conventional finish suppliers; incumbents must secure bio-based coating partnerships before certification backlogs deepen. For New Entrants and Emerging Players: Boutique hotel renovation procurement in secondary German cities represents the most penetrable entry point, as operators there prioritize rapid refresh cycles over brand heritage requirements. Metal-frame minimalist tables for Copenhagen and Amsterdam commercial interiors offer white-space expansion with lower upholstery compliance burdens than seating categories. A specification-consultant go-to-market angle bypasses legacy retailer technical infrastructure gaps. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with integrated white-glove assembly and extended protection plan bundling, as hospitality procurement teams now treat these services as non-negotiable table stakes. Over the medium-term horizon, acquisition targets should display verified FSC chain-of-custody programs and captive CNC machining capacity. The signal to watch is boutique hotel procurement team consolidation around preferred vendor lists with bundled service requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Timber Supply | FSC chain-of-custody programs from Baltic sources preempt REACH-driven substrate shortages. |
| Captive Installation Network Buildout | Owned white-glove assembly teams replace third-party logistics and capture lifetime customer value. |
| Bio-Based Coating Reformulation Partnership | REACH-compliant finish development with German and Italian suppliers eliminates regulatory exclusion risk. |
| Hospitality Procurement Direct Sales Expansion | Specification relationships with Berlin and Austin boutique hotel operators secure three-year renovation cycles. |
| Extended Warranty Productization | Lifetime protection plans replace third-party insurers and deepen revenue per customer relationship. |
Research Methodology
A standing panel of boutique hotel procurement directors, CNC programming engineers, FSC certification auditors, and coating R&D specialists provided ongoing calibration against secondary validation sources. Primary fieldwork combined structured interviews with manufacturing plant managers and hospitality specification consultants with trade data from customs records, furniture industry association filings, and ECHA substance restriction databases. Bottom-up segment sizing triangulated against top-down market value reconstruction across product type, material, end user, and distribution channel dimensions.
Scenario bracketing around REACH implementation timelines and Baltic birch supply elasticity framed the projection horizon. The analytical framework modeled sofa, cabinet, chair, and table segments across wood, upholstery, metal, and glass materials, with hospitality, residential, commercial, and office end users distributed through online, retail, direct sales, and wholesale channels. CAGR derivation incorporated duty cycle assumptions for commercial versus residential applications and white-glove assembly penetration curves. Forecast inputs included boutique hotel renovation cycle frequency and urban premium housing density projections.
Macroeconomic conditions sit as an overlay; deviation in construction activity, hardwood commodity pricing, or cross-border logistics costs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation schedules and certification backlog resolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
US Sustainable Furniture Market
Furniture
School Furniture Market
Furniture
Kids Storage Furniture Market
Furniture
Europe Outdoor Furniture Market
Furniture
Europe School Furniture Market
Furniture
Italy Office Furniture Market
Furniture
Armchair on Casters Market
Furniture
Plastic Furniture Market
Furniture
UAE Home Furniture Market
Furniture
Exam Tables Market
Furniture
Upholstered Furniture Market
Furniture
Japan Home Furniture Market
Furniture
Chaises Longue Market
Furniture
Europe Bamboo Furniture Market
Furniture
USA and Canada Teak Veneer Sheet Market
Furniture
India Luxury Furniture Market