
 North America Slide Rails Market | 2026-2036
North America Slide Rails Market Size, Share, and Industry Trends Forecast 2026-2036
North America Slide Rails Market Analytics
Industrial distribution channels serving original equipment manufacturers are reshaping procurement patterns across the North America slide rails landscape. Accuride International Inc. leverages its deep vertical manufacturing footprint to control supply continuity for heavy-duty transportation applications. THK Co., Ltd. anchors premium positioning through precision-grade linear motion technology leadership. King Slide USA, Inc. competes aggressively on cost-engineered solutions for mid-market furniture and cabinetry producers.
North America slide rails are mechanical bearing assemblies—typically fabricated from cold-rolled steel or extruded aluminum with hardened ball-retainer races—engineered to enable controlled linear displacement under rated load capacities. These components serve as critical motion interfaces in industrial machinery, commercial furniture, and vehicle interiors where repetitive extension and retraction cycles must maintain positional tolerance. Telescopic rails command the dominant share of furniture and cabinet applications due to standardized three-stage travel ratios and established builder familiarity. Linear rails lead machinery-component installations where micron-level repeatability justifies higher per-unit cost. Heavy-duty rails represent the fastest-expanding category as automated material-handling systems and industrial robotics penetrate warehousing and logistics operations across the continent.
The EPA and OSHA jointly govern workplace exposure and material safety standards affecting slide rail finishing processes, particularly chromium and nickel compound handling in electroplating operations. NHTSA crashworthiness protocols indirectly shape automotive interior rail specifications through occupant-compartment intrusion and projectile-prevention requirements. Buyers and suppliers must track evolving EPA restrictions on per- and polyfluoroalkyl substances, as PFAS-free lubricant formulations will soon become a compliance gate for rail assemblies deployed in food-service and medical equipment environments.
Market Dynamics
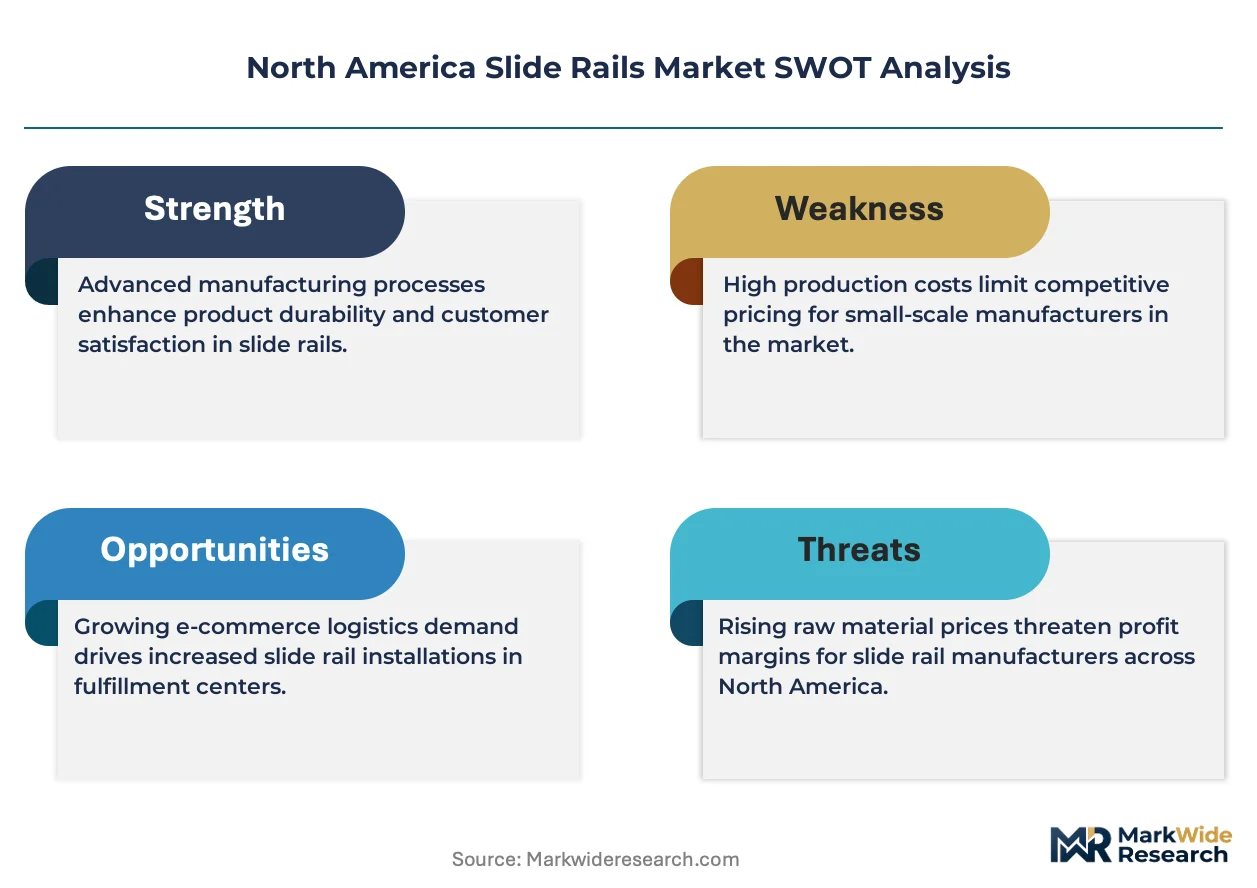
Hyperscale data center construction is compressing procurement cycles and forcing slide rail suppliers to certify products for seismic load ratings and hot-aisle containment specifications simultaneously. This infrastructure buildout is concentrating demand among a handful of rack-integrator OEMs who now dictate interoperability standards across the continent.
Growth Catalysts
- ENERGY STAR framework tightening:EPA specifications for energy-efficient building components are mandating low-friction rail assemblies in commercial furniture, expanding addressable volume for certified suppliers.
- Automated material-handling systems:Warehousing and logistics operations across the Texas corridor are deploying heavy-duty rails for robotic picking arms and conveyor transfers.
- PFAS-free lubricant transition:Food-service equipment manufacturers are pre-emptively sourcing rail assemblies with compliant coatings to avoid EPA enforcement windows.
Market Restraints
- Cold-rolled steel input volatility:Mill capacity constraints and scrap metal pricing swings are compressing margin predictability for mid-tier fabricators.
- Electroplating concentration:Chromium and nickel compound finishing operations cluster in legacy industrial zones with limited EPA discharge permitting capacity.
- Linear rail cost premium:Micron-grade ball screw and guideway assemblies face substitution pressure from belt-driven actuators in lower-precision automation cells.
Strategic Opportunities
- Medical equipment PFAS compliance:FDA-cleared device manufacturers represent an underserved segment requiring lubricant-free rail architectures for cleanroom deployment.
- Mexico nearshoring corridors:Appliance and automotive interior suppliers are relocating assembly operations, creating localized demand for just-in-time rail delivery.
- OSHA ergonomic mandates:Revised workplace lifting guidelines are accelerating sit-stand workstation retrofits requiring telescopic rail mechanisms.
Industry Challenges
- Precision grinding skill scarcity:Ball race honing and preload calibration require journeyman-level machinists in short supply across the Midwest manufacturing belt.
- NHTSA crashworthiness recertification:Automotive interior rail suppliers face extended validation timelines when polymer or metallurgy changes trigger new occupant-compartment intrusion testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Slide Rails Market |
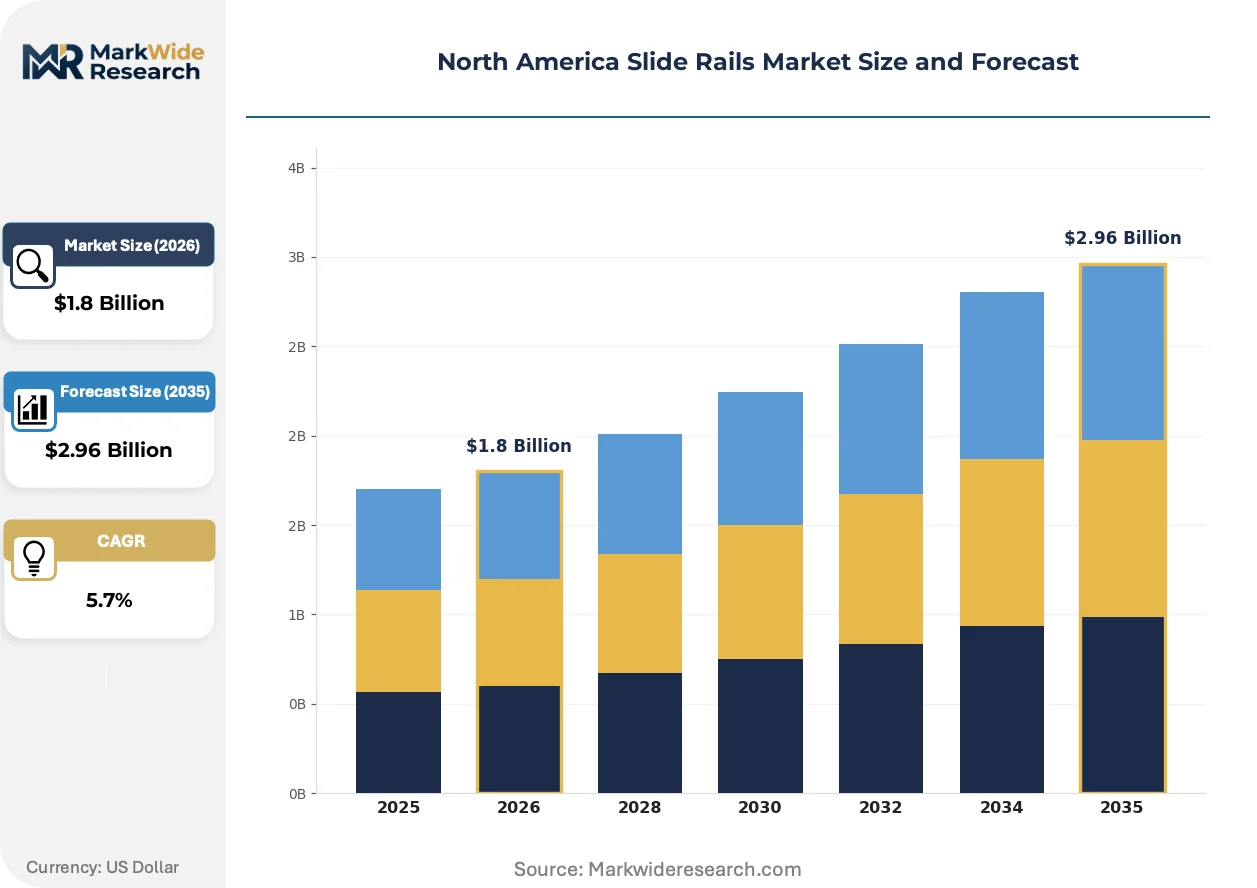
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telescopic Rails, Linear Rails, Heavy-Duty Rails, Specialty Rails End User: Furniture Manufacturers, Automotive Industry, Aerospace Sector, Electronics Assemblers Material: Aluminum, Steel, Plastic, Composite Application: Drawer Systems, Cabinet Structures, Machinery Components, Automotive Interiors |
| Companies Covered | Accuride International Inc., THK Co., Ltd., King Slide USA, Inc., SCHNEEBERGER Inc., HIWIN Corporation, SBC Linear Co., Ltd., Del-Tron Precision, Inc., Pacific Bearing Corp., Repon International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Slide Rails Market Evolving Landscape
Digital twin integration is compressing design-to-production cycles for custom rail lengths and load ratings. Suppliers now simulate fatigue life and deflection profiles before cutting steel, reducing prototype iterations and field failure exposure.
Sensor-embedded slide rails are virtualizing predictive maintenance protocols in automated warehousing. Load cells and accelerometers mounted directly on rail carriages transmit wear-state data to facility management systems. Amazon Robotics and similar operators are piloting these assemblies in high-cycle retrieval systems. The technology is virtualizing traditional time-based replacement schedules with condition-triggered interventions.
EPA restrictions on hexavalent chromium electroplating are accelerating trivalent chrome and zinc-nickel alloy adoption across finishing operations. The regulatory shift is forcing capital retooling at captive plating shops serving the furniture and transportation sectors. Texas and Ohio-based fabricators are absorbing compliance costs fastest, creating geographic divergence in delivered pricing.
Direct procurement from rail specialists is displacing distributor intermediation among large OEM rack builders. Vertiv and Schneider Electric units are negotiating frame-and-rail package specifications directly with Accuride and King Slide engineering teams. This channel compression is most visible in Phoenix and Ashburn data center clusters where integrators consolidate supplier bases to reduce qualification overhead.
North America Slide Rails Market Segmentation
Slide rail architectures diverge sharply across load-bearing requirements, precision tolerances, and environmental exposure conditions. Procurement specifications in North America increasingly bundle material certification, seismic rating, and PFAS compliance into unified sourcing criteria.
Product Type:
Application stress ranges from light-cycle furniture deployment to continuous-duty industrial automation, driving specification fragmentation across the product spectrum.
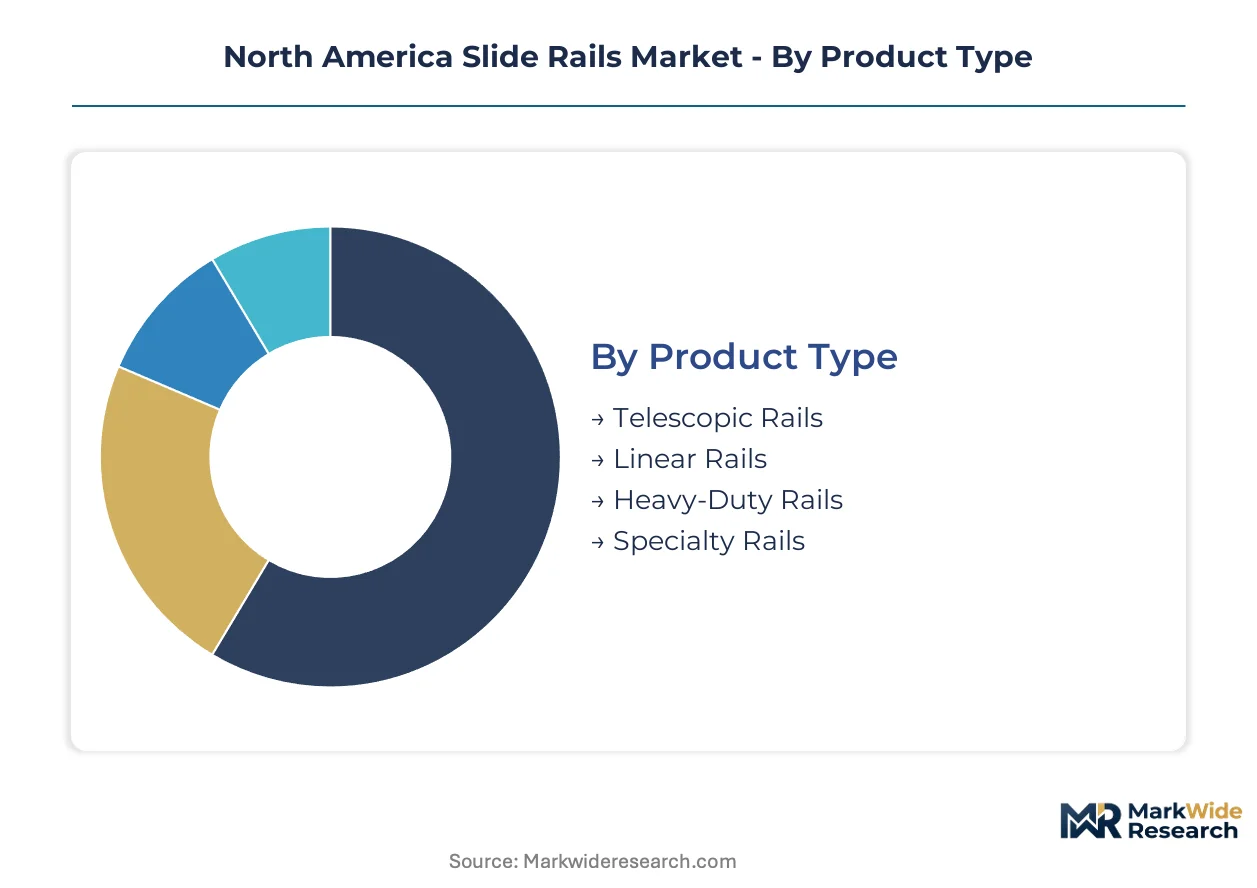
- Telescopic Rails:Three-stage ball-bearing assemblies fabricated from cold-rolled steel with zinc-nickel surface treatment dominate residential and commercial furniture installations. EPA ENERGY STAR friction specifications are tightening qualification thresholds for cabinet OEMs sourcing across the Texas corridor.
- Heavy-Duty Rails:Reinforced carriages with hardened raceways support robotic material-handling systems in automated warehousing. Demand concentrates among logistics operators deploying high-bay retrieval systems in Phoenix and Ashburn data center clusters where seismic load ratings intersect with hot-aisle containment requirements.
- Linear Rails:Micron-grade guideway assemblies with preloaded ball screws serve precision machinery axes. Machine tool builders in the Midwest manufacturing belt specify these for repeatability-critical cutting and positioning operations.
- Specialty Rails:Custom-length fabrications with integrated damping or locking mechanisms address medical equipment and cleanroom deployments. FDA-cleared device manufacturers are pre-emptively specifying lubricant-free architectures ahead of anticipated PFAS enforcement windows.
Established volume favors Telescopic Rails; emerging adoption favors Heavy-Duty Rails.
End User:
Buyer sophistication spans from cost-engineered furniture producers to crashworthiness-certified automotive tier suppliers, compressing margin structures at the mid-market.
- Furniture Manufacturers:Cabinet and workstation builders drive standardized telescopic rail procurement through distributor channels. OSHA ergonomic mandates for sit-stand workstations are accelerating retrofit cycles among commercial office furniture producers.
- Automotive Industry:Tier suppliers engineer interior storage and seat-track assemblies under NHTSA occupant-compartment intrusion protocols. Polymer or metallurgy changes trigger extended recertification timelines at validation laboratories.
- Aerospace Sector:Airframe and cabin interior specialists specify lightweight aluminum rail systems with traceable heat treatment documentation. Weight-reduction priorities favor titanium and composite alternatives in next-generation platforms.
- Electronics Assemblers:Rack-integrator OEMs for hyperscale data centers negotiate frame-and-rail packages directly with rail engineering teams. Direct procurement is displacing distributor intermediation among Vertiv and Schneider Electric units consolidating supplier bases.
Volume leadership sits with Furniture Manufacturers; steepest expansion trajectory belongs to Electronics Assemblers.
Material:
Raw material selection trades off strength-to-weight ratios against surface finishing compatibility and regulatory compliance pathways.
- Steel:Cold-rolled and hardened alloy grades anchor heavy-load industrial applications with established electroplating finishing infrastructure. Mill capacity constraints and scrap metal pricing volatility are compressing margin predictability for mid-tier fabricators.
- Aluminum:Extruded 6061 and 7075 series profiles serve aerospace and weight-sensitive automotive interiors where anodizing replaces chromium plating. Texas and Ohio-based fabricators are absorbing EPA trivalent chrome conversion costs fastest.
- Plastic:Glass-reinforced nylon and acetal homopolymer rails address corrosion-exposed marine and food-service environments. PFAS-free lubricant formulations are becoming compliance gates for assemblies deployed in commercial kitchen equipment.
- Composite:Carbon-fiber and hybrid matrix structures penetrate motorsport and premium aerospace seating where specific stiffness requirements justify unit cost premiums. Limited domestic fabrication capacity constrains near-term supply expansion.
Steel retains cost-position dominance; Aluminum gains share fastest in transportation lightweighting.
Application:
Functional deployment contexts determine load-cycle specifications, environmental sealing requirements, and maintenance accessibility architectures.
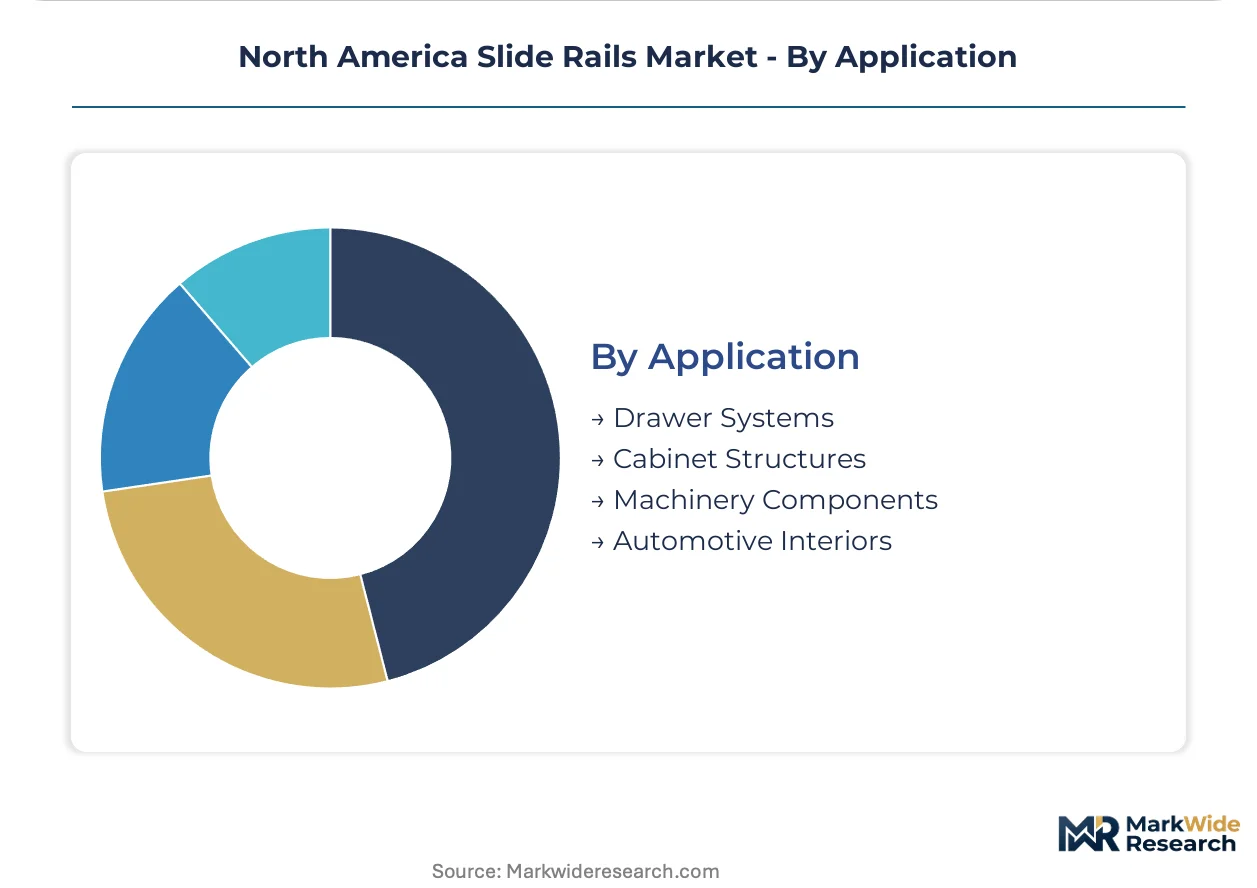
- Drawer Systems:Telescopic mechanisms in residential, commercial, and medical furniture require smooth extension ratios and soft-close damping. ENERGY STAR low-friction mandates are expanding certified supplier addressable volume.
- Machinery Components:Linear motion axes in CNC equipment, packaging lines, and robotic cells demand micron-level repeatability. Belt-driven actuator substitution pressure is mounting in lower-precision automation cells.
- Cabinet Structures:Server rack and electrical enclosure rail systems integrate grounding continuity and tool-less mounting features. Seismic zone 4 ratings are becoming baseline requirements in California and Pacific Northwest installations.
- Automotive Interiors:Glovebox, center console, and seat-track assemblies must satisfy NHTSA projectile prevention and occupant-compartment integrity standards. Extended validation timelines accompany any material or geometry revision.
Drawer Systems anchor current shipment volumes; Machinery Components climb the fastest on automation penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-35 corridor freight rail network underwrites Texas's dominance in industrial slide rail consumption, while the Great Lakes manufacturing belt anchors precision-grade production capacity.
United States
Hyperscale data center construction in Phoenix and Ashburn compresses procurement cycles for seismic-rated rack rails. EPA ENERGY STAR friction mandates expand certified supplier volume for commercial furniture. The Texas corridor concentrates heavy-duty rail demand from automated warehousing and logistics hub development.
Canada
Aerospace manufacturing in Quebec and Ontario drives lightweight aluminum rail specifications with traceable heat treatment documentation. Health Canada device regulations intersect with anticipated PFAS enforcement, pushing medical equipment builders toward lubricant-free architectures. The Pacific Northwest corridor links Vancouver port logistics to Seattle-Tacoma warehousing demand.
Mexico
Appliance and automotive interior nearshoring into Nuevo León and the Bajío Region creates localized demand for just-in-time rail delivery. Mexico's automotive regulator enforces occupant-compartment safety standards that cascade into tier supplier specifications. Querétaro's aerospace cluster sources precision linear rails for machining centers.
California
Seismic zone 4 building codes mandate structural rail ratings for server rack installations from San Francisco to Los Angeles. The state's air quality management districts impose chromium plating discharge limits that accelerate trivalent chrome adoption. Central Valley distribution centers deploy heavy-duty rails for robotic material-handling systems.
Ohio
Midwest machine tool builders specify micron-grade linear rails for repeatability-critical cutting operations. EPA trivalent chrome conversion costs concentrate among legacy plating shops serving the furniture and transportation sectors. Cleveland-Akron automotive tier suppliers face extended NHTSA validation timelines for interior rail assemblies.
North America Slide Rails Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with fabrication and finishing expertise. The vendor base stratifies across three performance tiers: precision-grade linear motion providers, cost-engineered furniture rail fabricators, and heavy-duty industrial specialists. Two strategic archetypes dominate: vertically integrated manufacturers controlling cold-rolled steel input through captive mill relationships, and precision grinding houses with journeyman-level honing capabilities. Competitive moves concentrate on direct procurement channel compression with rack-integrator OEMs and capital retooling for trivalent chrome compliance.
Among the named fabricators, Accuride International Inc. and THK Co., Ltd. occupy positions at opposite ends of the precision spectrum, with King Slide USA, Inc. representing the cost-engineered mid-market tier. Accuride exemplifies the vertically integrated archetype with deep manufacturing footprint control. THK anchors premium positioning through precision-grade technology leadership. King Slide competes aggressively on cost-engineered solutions. SCHNEEBERGER Inc., HIWIN Corporation, and SBC Linear Co., Ltd. represent specialized linear motion providers with geographic origins in European and East Asian precision manufacturing traditions. Del-Tron Precision, Inc., Pacific Bearing Corp., and Repon International Corporation sit within the component specialist tier serving distributor and direct OEM channels.
| Leading Market Players |
|---|
| Accuride International Inc. |
| THK Co., Ltd. |
| King Slide USA, Inc. |
| SCHNEEBERGER Inc. |
| HIWIN Corporation |
| SBC Linear Co., Ltd. |
| Del-Tron Precision, Inc. |
| Pacific Bearing Corp. |
| Repon International Corporation |
| Others |
Value Network & Pricing Analysis
The I-35 corridor freight rail network compresses logistics costs for cold-rolled steel shipments into Texas fabrication clusters, concentrating supply-side leverage among mill-adjacent processors while downstream price differentiation widens between seismic-certified data center rails and commodity furniture-grade assemblies.
Pricing Analysis
Volume-discount tiering structures separate rack-integrator OEMs negotiating frame-and-rail package specifications from mid-market furniture producers purchasing through distributor channels. Pricing stratifies across premium precision-grade linear rails, standard heavy-duty industrial assemblies, and economy telescopic mechanisms for residential cabinetry. Cost compression in the standard tier intensifies as belt-driven actuators substitute for ball-screw linear rails in lower-precision automation cells. Furniture manufacturers exhibit highest price sensitivity due to thin margin structures, while hyperscale data center builders prioritize seismic certification and PFAS compliance over unit cost.
Supply Chain Analysis
Export-control restrictions on precision grinding equipment limit domestic capacity expansion for micron-grade linear rail production, concentrating advanced manufacturing in Japan and Germany while North American fabricators rely on imported honing machinery. Raw material flows draw from domestic cold-rolled steel mills, Chinese aluminum extrusion, and Taiwanese ball-bearing components. Single-source vulnerability sits with journeyman-level machinist scarcity across the Midwest manufacturing belt. Distribution runs through direct procurement channels displacing distributor intermediation among large OEM rack builders, alongside traditional industrial distribution serving smaller furniture and automotive tier suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability standardization among rack-integrator OEMs is consolidating supplier bases into platform-economics dynamics where direct engineering relationships replace transactional procurement, compressing qualification overhead for certified rail specialists.
For Market Incumbents: Entrench position by deepening captive relationships with cold-rolled steel mills to buffer scrap metal pricing volatility, while accelerating trivalent chrome finishing retooling ahead of EPA enforcement windows. Prioritize certification investment for seismic zone 4 and PFAS-free lubricant architectures to defend against emerging precision grinding houses in Mexico nearshoring corridors.
For New Entrants and Emerging Players: Establish a beachhead in medical equipment rail architectures where FDA-cleared device manufacturers face underserved demand for lubricant-free cleanroom deployments. Target the Pacific Northwest data center cluster with localized just-in-time delivery capabilities, leveraging digital twin simulation services to compress design-to-production cycles without capital-intensive grinding infrastructure.
For Investors and Strategic Acquirers: Precision grinding houses with journeyman-level honing capabilities and established automotive tier relationships represent the most defensible acquisition archetype in a five-to-ten-year horizon. Monitor NHTSA crashworthiness recertification timelines as an inflection signal—extended validation windows will strain capital reserves at mid-tier automotive interior suppliers, creating distressed acquisition opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Trivalent Chrome Conversion | EPA hexavalent chromium restrictions force capital retooling at legacy plating shops serving furniture and transportation sectors. |
| Digital Twin Integration | Simulation of fatigue life and deflection profiles reduces prototype iterations for custom rail lengths and load ratings. |
| PFAS-Free Lubricant Transition | Food-service and medical equipment manufacturers pre-emptively source compliant coatings to avoid enforcement windows. |
| Direct Procurement Channel Compression | Vertiv and Schneider Electric units negotiate frame-and-rail packages directly with engineering teams to reduce qualification overhead. |
| Sensor-Embedded Rail Development | Amazon Robotics pilots load-cell and accelerometer assemblies for condition-triggered maintenance in high-cycle retrieval systems. |
Research Methodology
A standing panel of rack-integrator procurement directors, automotive tier supplier engineers, furniture OEM sourcing managers, and precision grinding shop owners provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders against secondary validation from EPA ENERGY STAR specifications, NHTSA crashworthiness protocols, OSHA workplace guidelines, and customs data tracking cold-rolled steel and aluminum extrusion flows. Bottom-up shipment analysis by product type and end-use segment was triangulated with top-down macroeconomic indicators across the North American industrial construction and logistics automation sectors.
Scenario-bracketing around steel input volatility, PFAS regulatory acceleration, and data center construction cyclicality bounded high-low growth paths across the projection horizon. The analytical framework modeled demand by product architecture, material grade, end-use industry, and regional construction cluster, with CAGRs derived from regression against industrial production indices and capital expenditure disclosures from hyperscale facility operators. Forecast inputs incorporated seismic code adoption timelines, electroplating compliance cost curves, and journeyman machinist labor availability by state.
Stress conditions across scrap metal pricing swings, EPA enforcement intensity, and NHTSA validation timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding data center buildout pacing and Mexico nearshoring momentum. Material shifts in PFAS regulatory scope or trivalent chrome conversion cost trajectories would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Kids and Nursery Furniture Market
Furniture
India Home Furniture Market
Furniture
Ready-To-Assemble (RTA) Furniture Market
Furniture
Indonesia Home Furniture Market
Furniture
Armchairs with Footrest Market
Furniture
Furniture Laminate Market
Furniture
North America Secondary Wood Products Market
Furniture
School Furniture Market
Furniture
Piano Stools Market
Furniture
United Kingdom Furniture Market
Furniture
Asia Pacific Multifunctional Furniture Market
Furniture
Asia-Pacific Home Furniture Market
Furniture
Kids Table and Chair Market
Furniture
Europe Home Furniture Market
Furniture
UK Sustainable Home Furniture Market
Furniture
Plastic Furniture Market