
 Coffee Pouch Market | 2026-2036
Coffee Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Pouch Market Outlook
Premium barrier-grade specifications is rotating demand toward high-performance multilayer structures with extended oxygen and moisture protection. Amcor plc leverages proprietary polymer science to sustain North American supply relationships with major roast houses. Mondi Plc anchors European volume through integrated kraft paper and barrier film operations. ProAmpac LLC differentiates via specialized degassing valve integration for whole bean formats.
A coffee pouch is a flexible primary package, typically constructed from laminated films incorporating polyethylene terephthalate, aluminum oxide coatings, or ethylene vinyl alcohol layers, engineered to preserve volatile aromatic compounds while resisting puncture during distribution and retail handling. Stand-up pouches with integrated zip lock closures dominate retail shelf presence and command margin premiums due to resealability and billboard graphics area. Biodegradable films represent the fastest-growing material trajectory, though plastic laminates retain cost advantages in high-volume food service channels where single-use disposal predominates.
EU REACH and the Packaging and Packaging Waste Regulation constrain material selections and mandate recyclability disclosures across European supply chains, directly elevating compliant substrate costs. The US FDA maintains strict indirect food additive standards for pouch layers contacting roasted coffee oils. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between reformulating barrier structures or absorbing compliance premiums.
Market Dynamics
Specialty coffee roasters are forcing a format migration from rigid metal cans to flexible pouches, compressing traditional packaging equipment depreciation cycles and rewiring converter capacity allocation across North American and European supply chains.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandates for recyclable and biodegradable materials are accelerating converter investment in compostable film extrusion lines, pulling demand toward certified sustainable substrates.
- Degassing valve integration:One-way valve technology for whole bean formats preserves aromatic volatile compounds during post-roast off-gassing, enabling extended shelf life claims that command retail price premiums.
- German artisanal coffee culture:Dense networks of small-batch roasters in Berlin, Hamburg, and Munich generate concentrated demand for short-run, high-graphic pouch orders with rapid turnaround requirements.
Market Restraints
- Aluminum oxide barrier coating cost volatility:Energy-intensive vapor deposition processes tie substrate pricing to natural gas and electricity input swings, squeezing converter margins during peak demand seasons.
- Biodegradable film performance gaps:Current polylactic acid and cellulose-based structures fail to match multilayer laminates on oxygen transmission rates, limiting adoption in premium whole bean segments where six-month shelf life is standard.
- Extended producer responsibility fee structures:Germany's Verpackungsgesetz and France's Citeo modulation criteria impose per-unit compliance costs that disadvantage smaller roasters lacking scale to absorb administrative burden.
Strategic Opportunities
- Home composting certification pathways:TÜV Austria's OK Compost HOME and DIN CERTCO home compostable marks unlock premium positioning in urban consumer segments with municipal composting infrastructure gaps.
- Direct-to-subscription channel expansion:Roasters bypassing retail shelf presence can specify thinner gauge films and simplified barrier structures, reducing material cost per unit while maintaining freshness through rapid consumption cycles.
- Digital printing convergence with short-run flexo:Hybrid press configurations enable economical production runs below five thousand units, matching the batch economics of craft roasting operations in Portland, Melbourne, and Copenhagen.
Industry Challenges
- Multilayer film recycling infrastructure gaps:Current mechanical separation systems cannot disaggregate polyethylene terephthalate, ethylene vinyl alcohol, and polyethylene layers, forcing reliance on nascent chemical recycling pilot facilities with limited geographic coverage.
- Barrier certification timeline compression:Migration testing protocols under FDA indirect food additive standards and EU 10/2011 plastic regulation require twelve to eighteen month validation cycles that misalign with seasonal product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Pouch Market |
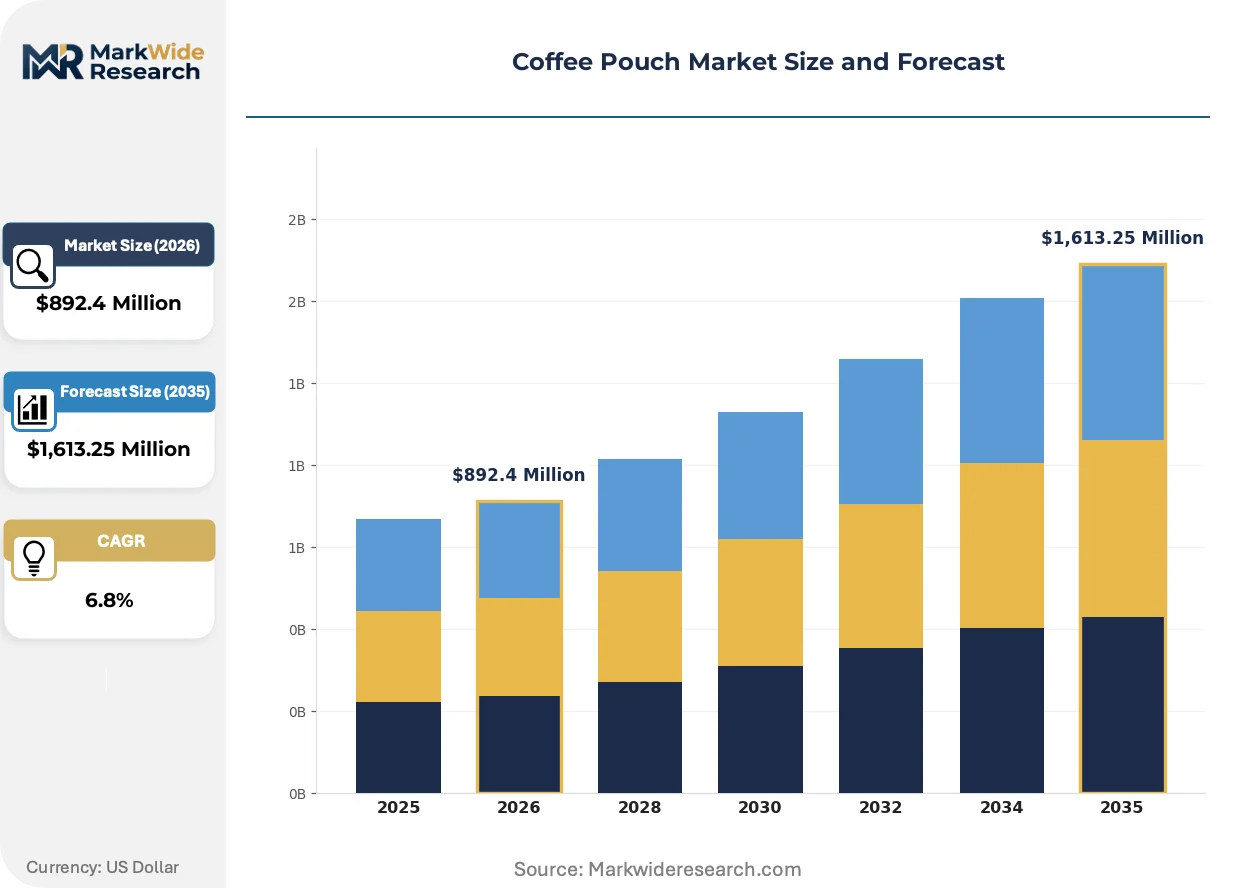
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,613.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Block Bottom Pouches, Flat Pouches, Vacuum Pouches Material: Plastic, Aluminum, Paper, Biodegradable Films Closure Type: Zip Lock, Heat Seal, Tear Notch, Tapered Closure End User: Retail, Food Service, E-Commerce, Wholesale |
| Companies Covered | WestRock Company, ProAmpac LLC, Mondi Plc, CarePac, Sonoco Products Company, MTPak Coffee Limited, DS Smith plc, PBFY Flexible Packaging, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Pouch Market Strategic Shifts
Active and intelligent packaging technologies are rewriting freshness guarantees, while regulatory material bans and consumer disposal preferences are fragmenting substrate standardization across regional supply chains.
High-barrier metallized films incorporating aluminum oxide coatings are displacing conventional foil laminates in premium coffee applications. Medium-sized roasters in the Pacific Northwest and Nordic markets have accelerated adoption over the past eighteen months, driven by microwaveability claims and metal detector compatibility at retail. This displacement is compressing demand for traditional aluminum foil suppliers while expanding capacity utilization at vapor deposition specialists.
The EU Packaging and Packaging Waste Regulation's 2030 recyclability targets are forcing reformulation of legacy multilayer structures. Industrial consequence includes mandatory design-for-recycling assessments and standardized Extended Producer Responsibility fee modulation based on recyclability scores. Small-format flexible packaging for single-serve coffee portions faces the steepest compliance cost escalation, pushing converters toward paper-based barrier alternatives with limited runnability on existing form-fill-seal equipment.
Roaster procurement patterns are consolidating around integrated packaging suppliers capable of delivering pre-formed pouches with inline degassing valve application and digital print customization. Traditional film converters without downstream pouch converting capabilities are losing share to vertically integrated competitors offering design-to-delivery workflows. This consolidation is most visible in the United Kingdom and Netherlands, where specialty coffee subscription volumes have compressed supplier qualification cycles from annual to quarterly review.
Coffee Pouch Market Segmentation
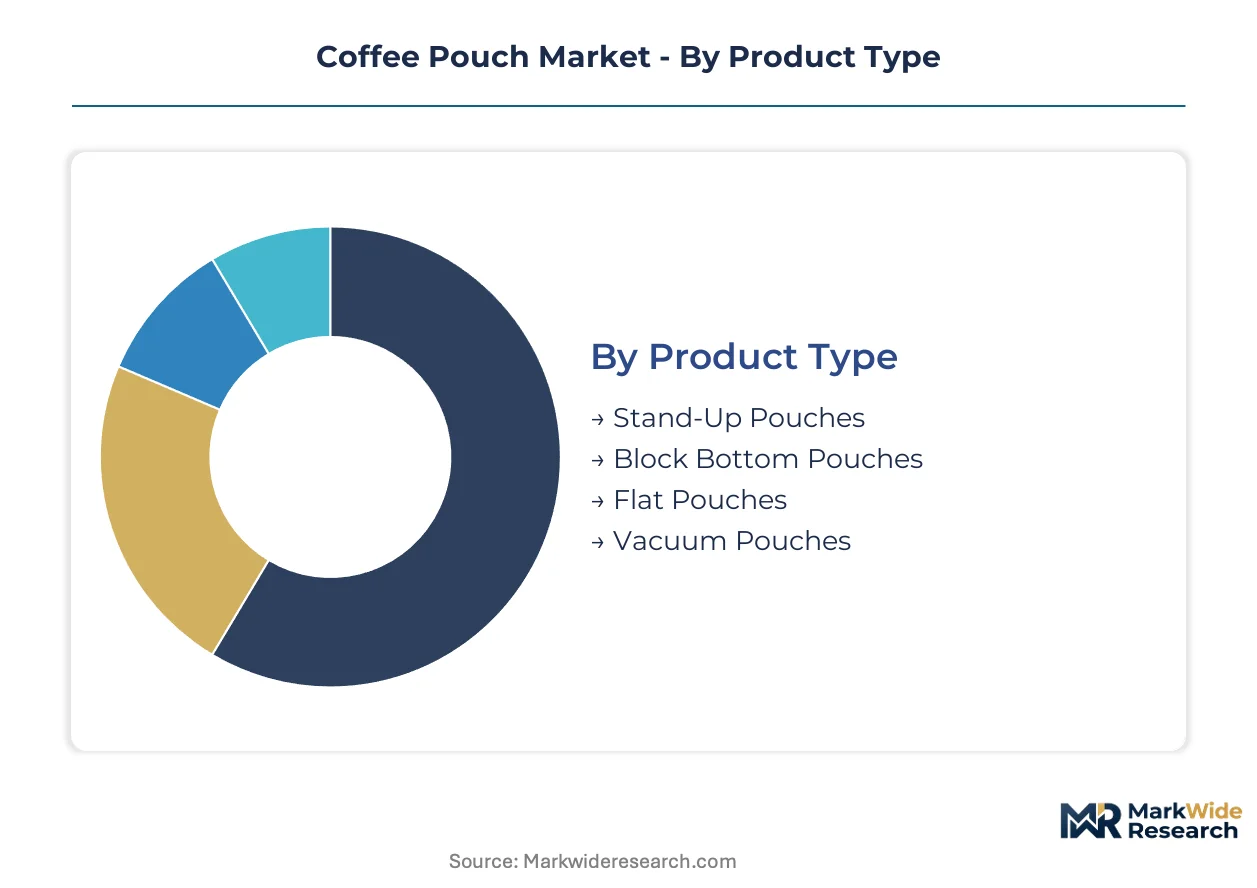
Coffee pouch segmentation reveals divergent technical requirements between artisanal roasters prioritizing shelf differentiation and food service operators optimizing for throughput. Format selection directly constrains barrier architecture, degassing valve placement, and print customization capabilities.
Product Type:
Stand-up pouches dominate domestic consumption across Germany, Italy, and the United States, while vacuum formats concentrate in export-led specialty channels requiring extended ocean transit stability.
- Stand-Up Pouches:These structures incorporate gusseted bases and front-facing billboard panels optimized for retail shelf presence. German artisanal roasters in Berlin and Hamburg specify these formats for rapid-turnover specialty releases requiring maximum graphic impact in direct-to-consumer channels.
- Vacuum Pouches:Multi-layer laminates with aluminum oxide barrier coatings eliminate headspace oxygen to arrest lipid oxidation during prolonged storage. Nordic export specialists targeting Japanese and Australian markets mandate these specifications for six-month shelf life guarantees across temperature-variable supply chains.
- Block Bottom Pouches:Rectangular bases enable stable pallet stacking for food service bulk formats. Institutional buyers in the United States specify these for back-of-house efficiency.
- Flat Pouches:Minimal material gauge suits single-serve portion packs with immediate consumption profiles. Hotel and airline channel procurement concentrates here.
Stand-up pouches command the established base. The steepest expansion runs through vacuum formats.
Material:
Cost tier stratification separates premium barrier laminates from economy polyethylene structures, with biodegradable alternatives occupying an emerging premium position constrained by performance gaps.
- Plastic:Polyethylene terephthalate and ethylene vinyl alcohol multilayers deliver sub-1 cc oxygen transmission rates essential for whole bean volatile retention. High-volume food service procurement in the United States anchors demand for these cost-optimized structures despite limited end-of-life pathways.
- Biodegradable Films:Polylactic acid and cellulose-based substrates certified under TÜV Austria OK Compost HOME standards enable premium positioning in German and French markets where extended producer responsibility fees penalize conventional plastics. Current oxygen barrier performance lags metallized alternatives by 40-60%, restricting adoption to short-shelf-life ground coffee segments.
- Aluminum:Foil laminates and vapor-deposited aluminum oxide coatings provide absolute light and moisture barriers for premium whole bean formats. Energy-intensive production ties pricing to European natural gas benchmarks.
- Paper:Kraft-based structures with dispersed barrier coatings serve sustainability-positioned brands prioritizing tactile shelf differentiation over maximum shelf life. Scandinavian retail channels show concentrated uptake.
Plastic laminates retain volume leadership. Biodegradable films are climbing the fastest as EU Packaging and Packaging Waste Regulation compliance deadlines approach.
Closure Type:
Customer type dictates resealability requirements, with subscription channel operators accepting simpler seals than retail formats requiring repeated consumer access.
- Zip Lock:Integrated slider or press-to-close mechanisms enable repeated resealing without compromising barrier integrity. Retail-facing roasters in Portland and Copenhagen specify these for consumer convenience premiums.
- Heat Seal:Permanent fusion barriers maximize shelf life for single-use food service portions where resealability adds no value. Institutional procurement channels concentrate demand here.
- Tear Notch:Laser-scored opening features balance accessibility with tamper evidence for travel and hospitality single-serve formats.
- Tapered Closure:Fold-and-tuck designs with adhesive strips serve economy retail tiers prioritizing material minimization over resealability durability.
Zip lock configurations dominate retail-facing production. Heat seal formats show stable demand in food service contracting.
End User:
Application-specific requirements fragment specifications, with e-commerce channels imposing transit durability standards distinct from retail shelf conditions.
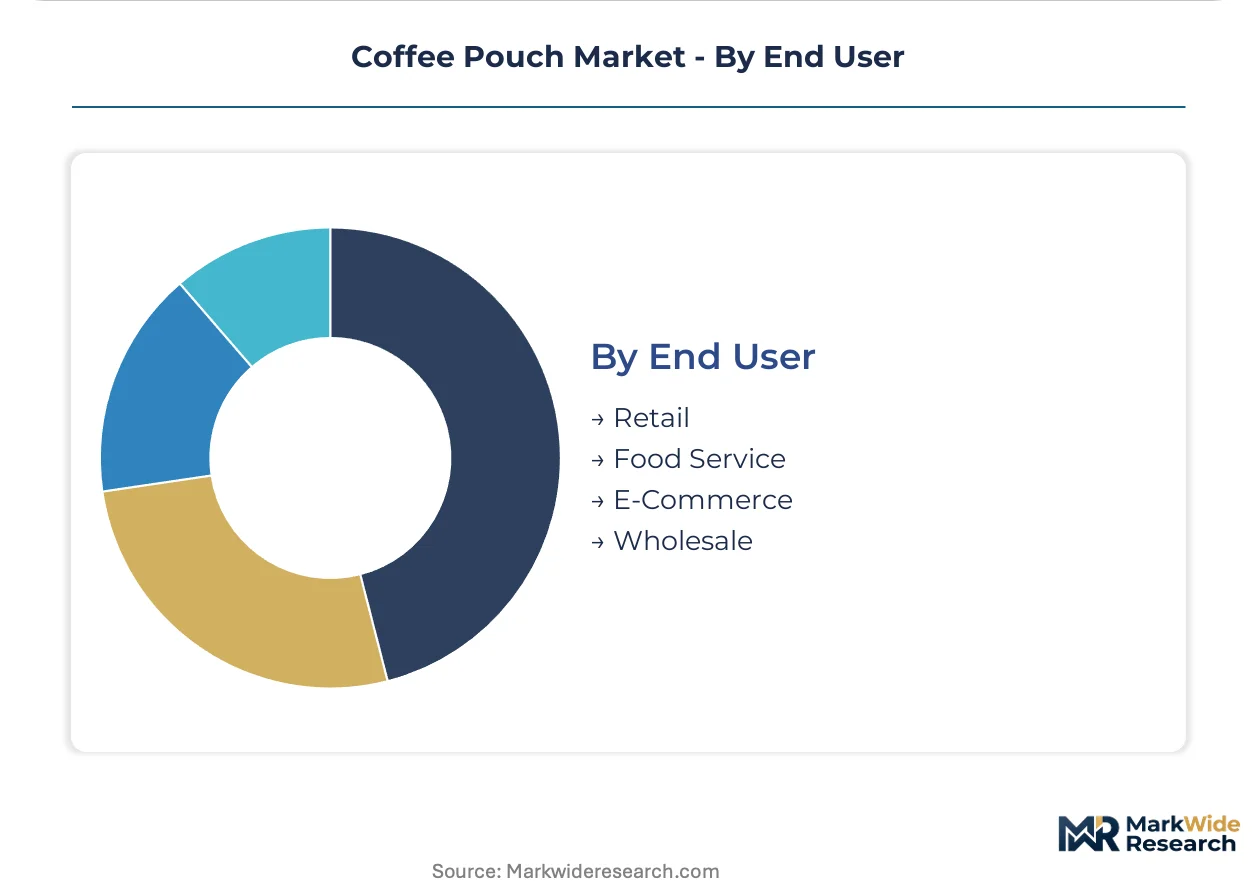
- Retail:Brick-and-mortar distribution demands puncture resistance against carton compression and vertical shelf presentation optimization. German supermarket chains and United States specialty grocers drive specification standardization here.
- E-Commerce:Direct-to-subscription fulfillment requires enhanced side-seal strength and exterior print durability against corrugated abrasion during individual parcel handling. Melbourne and Copenhagen subscription roasters have compressed supplier qualification cycles to quarterly review for these channels.
- Food Service:Bulk formats with simplified graphics and maximum fill efficiency predominate. Back-of-house handling tolerates thinner gauge materials.
- Wholesale:Pallet-scale packaging with minimal unit-level customization serves distributor intermediaries with private-label programs.
Retail channels command the established base. E-commerce is gaining share fastest as subscription roasting operations expand fulfillment infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters in Germany, the United States, and Australia, with each hub serving distinct regulatory and demand environments. Artisanal roasting density and packaging waste legislation determine substrate specifications across these markets.
Germany
Berlin and Hamburg host Europe's densest specialty roaster networks, generating concentrated demand for short-run digital print orders. The Verpackungsgesetz imposes strict extended producer responsibility fees that elevate compliant substrate costs. Bavarian converters operate integrated kraft paper and barrier film lines serving TÜV Austria-certified compostable pouch programs.
United States
Pacific Northwest roasting clusters in Portland and Seattle drive specification innovation for subscription channel formats. FDA indirect food additive standards govern migration testing protocols for multilayer structures contacting roasted coffee oils. California's SB 54 plastic pollution regulations are accelerating converter trials of home compostable alternatives ahead of 2032 compliance deadlines.
United Kingdom
London and Manchester subscription roasters have compressed supplier qualification cycles to quarterly review, favoring vertically integrated pouch converters. The Plastic Packaging Tax levies charges on packaging with less than 30 percent recycled content. Midlands-based suppliers are expanding digital print capacity to match craft roasting batch economics.
Australia
Melbourne's specialty coffee culture sustains premium pouch demand with emphasis on microwaveable metallized films. The Australian Packaging Covenant Organisation mandates industry-led recycling targets with annual reporting requirements. Sydney converters are piloting chemical recycling partnerships to address multilayer film disaggregation gaps.
Japan
Tokyo and Osaka import channels specify vacuum pouch formats with six-month shelf life guarantees for temperature-variable ocean transit. METI's resource circulation policy framework guides packaging material selection toward recyclable and renewable substrates. Nagoya-based converters supply aluminum oxide barrier coatings displacing conventional foil laminates in premium segments.
Coffee Pouch Market Competitive Environment
Concentration sits with integrated multinational converters possessing captive film extrusion and downstream pouch forming capabilities. The vendor base separates into three tiers: global packaging conglomerates with polymer science divisions, regional specialists in degassing valve integration, and emerging biodegradable film developers. Strategic moves center on backward integration into barrier coating deposition and geographic expansion through roasting hub proximity.
Among the integrated tier, Amcor plc and Mondi Plc exemplify scale-driven archetypes with polymer science capabilities spanning multiple continents. ProAmpac LLC occupies a specialist position within North American supply chains. WestRock Company and DS Smith plc represent paper-based packaging conglomerates expanding flexible format portfolios. MTPak Coffee Limited anchors the craft-focused segment with short-run digital print specialization for artisanal roasters.
| Leading Market Players |
|---|
| WestRock Company |
| ProAmpac LLC |
| Mondi Plc |
| CarePac |
| Sonoco Products Company |
| MTPak Coffee Limited |
| DS Smith plc |
| PBFY Flexible Packaging |
| Amcor plc |
| Others |
Value Chain & Pricing Dynamics
Aluminum oxide vapor deposition displacing conventional foil laminates simultaneously concentrates supply geography around German and Japanese coating specialists and compresses pricing premiums for barrier-grade substrates. This substitution dynamic rewires converter procurement patterns as energy-intensive deposition processes tether substrate costs to European natural gas benchmarks and Japanese electricity tariffs.
Pricing Analysis
The EU Packaging and Packaging Waste Regulation dictates the pricing tier structure across European supply chains, elevating compliant biodegradable substrates above conventional plastic laminates. Three-tier pricing structure across premium barrier-coated, standard multilayer, and economy polyethylene formats separates TÜV Austria-certified compostable pouches from uncertified alternatives. Pricing pressure stems from extended producer responsibility fee modulation in Germany and France, where per-unit compliance costs disadvantage smaller roasters. Food service operators exhibit highest price sensitivity due to single-use disposal profiles, while German artisanal roasters absorb premiums for rapid-turnaround digital print customization.
Supply Chain Analysis
Germany and the United States anchor flexible film extrusion and pouch converting capacity, with Bavarian converters operating integrated kraft paper and barrier film lines and Pacific Northwest suppliers specializing in subscription-channel formats. Raw material dependencies center on polyethylene terephthalate resin, ethylene vinyl alcohol copolymers, and aluminum oxide deposition feedstocks. Single-source vulnerability concentrates in vapor-deposited barrier coating capacity, where limited geographic coverage of chemical recycling pilot facilities constrains end-of-life pathways. Distribution runs through vertically integrated converters offering design-to-delivery workflows, bypassing traditional film suppliers lacking downstream pouch forming capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Degassing valve integration and digital print customization services are expanding faster than base pouch manufacturing, creating attach-rate opportunities for converters bundling hardware with recurring design and freshness-technology layers.
For Market Incumbents: Consolidate backward integration into barrier coating deposition to capture margin compression from aluminum oxide cost volatility, while locking in multi-year supply agreements with Pacific Northwest and Nordic roasting clusters facing quarterly supplier qualification cycles. Threat substitution from paper-based barrier alternatives demands captive polymer science capabilities to maintain performance parity with metallized films. For New Entrants and Emerging Players: Differentiate on home composting certification pathways targeting German and French urban consumer segments with municipal infrastructure gaps, where TÜV Austria OK Compost HOME marks unlock premium positioning. The most penetrable white space sits in short-run flexo-digital hybrid production below five thousand units, matching craft roasting batch economics in Melbourne and Copenhagen with rapid-turnaround value propositions. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors vertically integrated converters with captive film extrusion and downstream pouch forming capabilities. Long-term viability across the next decade hinges on chemical recycling infrastructure buildout addressing multilayer disaggregation gaps. The signal to watch is California SB 54 implementation acceleration, which will force converter trials of home compostable alternatives and reshape acquisition premiums for certified substrate capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Coating Deposition | Captures margin from aluminum oxide cost volatility tied to German natural gas benchmarks. |
| Home Composting Certification Investment | Unlocks TÜV Austria OK Compost HOME positioning in German and French urban segments. |
| Digital Print Capacity Expansion | Matches craft roasting batch economics in Portland and Copenhagen below five thousand units. |
| Degassing Valve Technology Acquisition | Secures aromatic volatile retention capabilities for whole bean premium shelf life claims. |
| Chemical Recycling Partnership Development | Addresses multilayer film disaggregation gaps constraining EU Packaging and Packaging Waste Regulation compliance. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with flexible packaging converters, specialty coffee roasters, and regulatory compliance officers, and secondary validation through EU regulatory filings, FDA indirect food additive standards documentation, and trade association substrate cost surveys. Primary fieldwork engaged plant managers at German and US film extrusion facilities, procurement leads at Berlin and Hamburg artisanal roasting operations, and technical directors overseeing barrier coating deposition lines. Secondary sources included Packaging and Packaging Waste Regulation impact assessments, TÜV Austria certification databases, and customs records tracking polyethylene terephthalate resin flows. Bottom-up volume modeling triangulated against top-down converter capacity estimates.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product type, material substrate, closure mechanism, and end-user channel, with geographic regulatory clusters treated as distinct scenario inputs. CAGRs derived from annualized growth rate calculations applied to base-year market sizing validated through supply-side capacity utilization rates and demand-side roasting operation expansion plans. Industry-specific forecast inputs incorporated EU extended producer responsibility fee modulation schedules and California SB 54 plastic pollution regulation compliance timelines.
Material uncertainties — regulatory enforcement variance across EU member states, biodegradable film oxygen barrier performance gaps, and chemical recycling infrastructure deployment delays — sit outside the modeled envelope. Forecasts reflect assumptions about converter investment continuity and roasting operation format migration velocity. Recalibration cycles align with material shifts in Packaging and Packaging Waste Regulation implementation guidance and home composting certification adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
North America Chewing Gum Market
Packaged Foods
Packaged Rice Noodles Market
Packaged Foods
Instant Cereals Market
Packaged Foods
Canned Tropical Fruit Market
Packaged Foods
Rice Noodles Market
Packaged Foods
Sugar Free Cookies Market
Packaged Foods
Canned Mushroom Market
Packaged Foods
Non-Fried Instant Noodles Market
Packaged Foods
Ready Meals Market
Packaged Foods
Wet Food Pouch Market
Packaged Foods
Dried Honey Market
Packaged Foods
Sausage Casing Market
Packaged Foods
Asia-Pacific Breakfast Cereals Market
Packaged Foods
Japan Packaged Food Products Market
Packaged Foods
Iran Breakfast Cereals Market
Packaged Foods
Global Breakfast Cereals Market