
 Cultured Whey Products Market | 2026-2036
Cultured Whey Products Market Size, Share, and Industry Trends Forecast 2026-2036
Cultured Whey Products Market Analytics
Ingredient customization revenue is reshaping margin pools across the cultured whey value chain. Fonterra Co-operative Group leverages its New Zealand dairy infrastructure to dominate bulk whey concentrate supply. Glanbia differentiates through specialized sports nutrition ingredient formulations. Arla Foods Ingredients anchors European demand with advanced whey fractionation capabilities.
Cultured whey products are fermented dairy derivatives produced through controlled bacterial culture of whey streams, typically yielding protein concentrates with 34-80% protein content and enhanced bioactive peptide profiles for functional food and nutraceutical applications. Greek Yogurt commands the largest product type position due to its entrenched presence in Mediterranean and North American retail dairy cases. Nutritional Supplements represents the fastest-growing application segment as athletes and aging consumers prioritize protein fortification.
FDA oversight of dairy ingredient labeling and USDA organic certification requirements shape product positioning and market access for cultured whey suppliers in the United States. EFSA novel food assessments and EU Green Deal sustainability benchmarks govern European commercialization pathways. Stakeholders must monitor evolving precision fermentation regulations and carbon accounting standards that will determine which production methods retain premium positioning.
Market Dynamics
Precision fermentation is consolidating control over whey protein yield consistency, compressing batch-to-batch variation from 15% to under 3% while displacing conventional acid-precipitation methods across North American and European manufacturing facilities.
Growth Catalysts
- Clean-label mandates:FSSAI's 2024 protein fortification guidelines for Indian school nutrition programs are accelerating demand for cultured whey isolates in government procurement contracts.
- Athletic protein fortification:NCAA Division I athletic departments are standardizing post-workout recovery protocols around 20-gram whey protein doses, creating institutional pull-through.
- Precision culturing advances:CRISPR-edited Lactobacillus strains are cutting fermentation cycle times by 40% in Danish and Dutch pilot facilities.
Market Restraints
- Feedstock volatility:Mozzarella and cheddar whey supply fluctuates with Italian and Wisconsin cheese production cycles, creating input cost instability.
- Fractionation equipment scarcity:Industrial-scale ceramic membrane systems for 80% protein isolation concentrate with three German and two Japanese suppliers.
- Novel food assessment timelines:EFSA's 18-to-24-month evaluation window for bioactive peptide claims blocks rapid European product launches.
Strategic Opportunities
- Geriatric nutrition penetration:Japan's 75-plus demographic presents underexploited demand for sarcopenia-targeted whey formulations.
- Cell-cultured dairy convergence:Hybrid products combining precision-fermented whey with cultivated casein are opening premium positioning in Singapore's novel food framework.
- Direct-to-athlete subscriptions:Monthly replenishment models bypass traditional sports nutrition retail markup structures.
Industry Challenges
- Bioprocess engineering talent scarcity:Industrial microbiologists with dairy fermentation expertise command 35% salary premiums over general food science graduates.
- Organic certification timelines:USDA's three-year transition requirement for whey stream organic status delays clean-label product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cultured Whey Products Market |
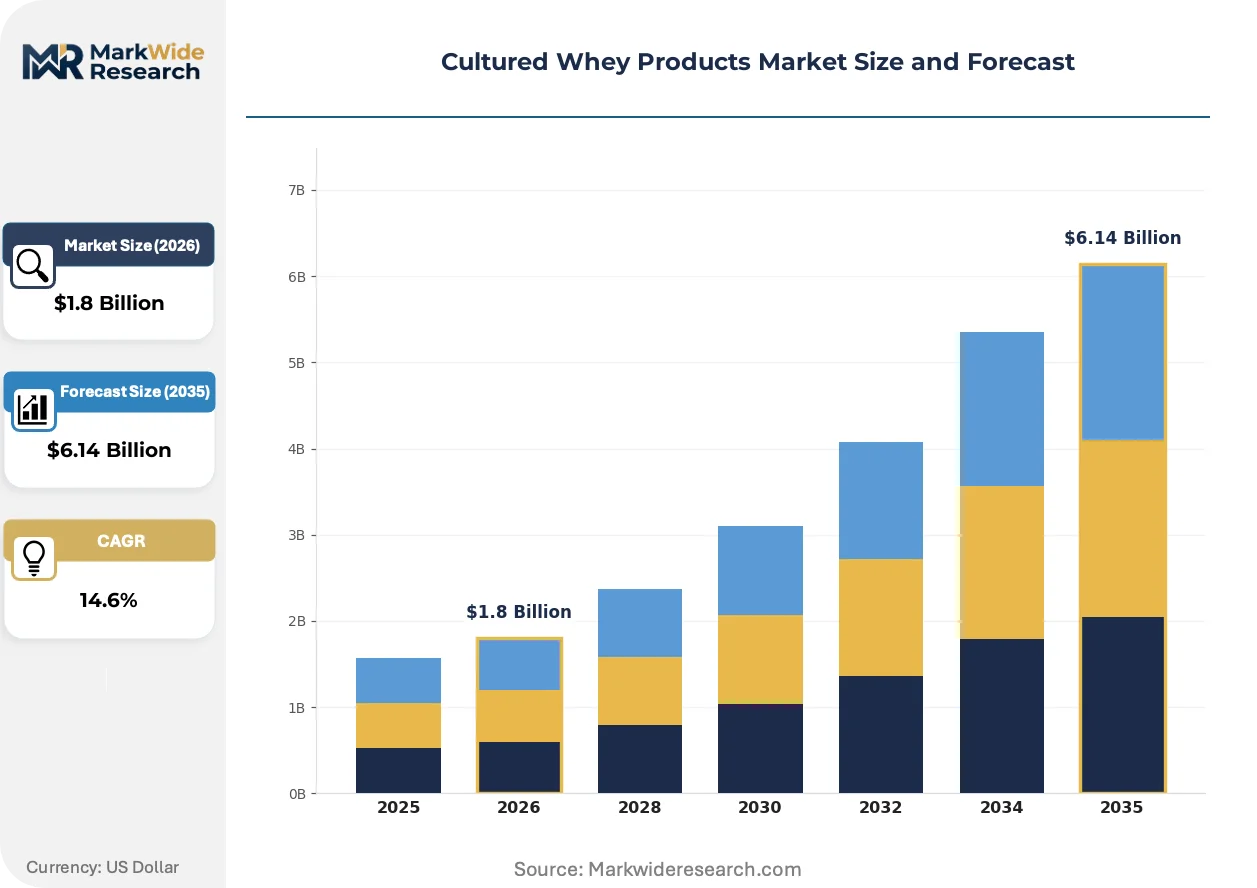
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greek Yogurt, Cottage Cheese, Cream Cheese, Ricotta Application: Bakery, Confectionery, Dairy Products, Nutritional Supplements Distribution Channel: Retail, E-commerce, Food Service, Wholesale End User: Households, Restaurants, Cafes, Food Manufacturers |
| Companies Covered | Fonterra Co-operative Group, Saputo, Lactalis Group, Arla Foods Ingredients, Glanbia, Hilmar Cheese Company, Carbery Group, Koninklijke FrieslandCampina, Idaho Milk Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cultured Whey Products Market Evolving Landscape
Digital twin technology is compressing R&D cycles for cultured whey formulations while regulatory carbon accounting is reshaping supplier qualification criteria across European and North American procurement desks.
Computational fluid dynamics coupled with machine learning is virtualizing fermentation vessel design optimization. Sports nutrition contract manufacturers in Utah and Colorado are deploying these tools to scale 10,000-liter batches without physical prototyping. The technology is virtualizing capital deployment timelines, cutting facility expansion planning from 24 months to 14 months.
EFSA's updated novel food guidance on bioactive peptides is mandating clinical endpoint validation for immunomodulatory claims. Ingredient suppliers must now submit randomized controlled trial data for peptide fractions previously marketed under structure-function frameworks. European infant formula brands are reformulating to exclude unvalidated bioactive additions ahead of 2026 enforcement.
Ingredient buyers are consolidating supplier rosters from twelve to four qualified vendors per protein category. Large functional food brands in California and Texas are implementing scorecard systems weighting carbon intensity, water usage, and fermentation yield consistency equally with price. This concentration is most visible in the ready-to-drink protein beverage segment, where three brands now account for 60% of cultured whey isolate procurement volume.
Cultured Whey Products Market Segmentation
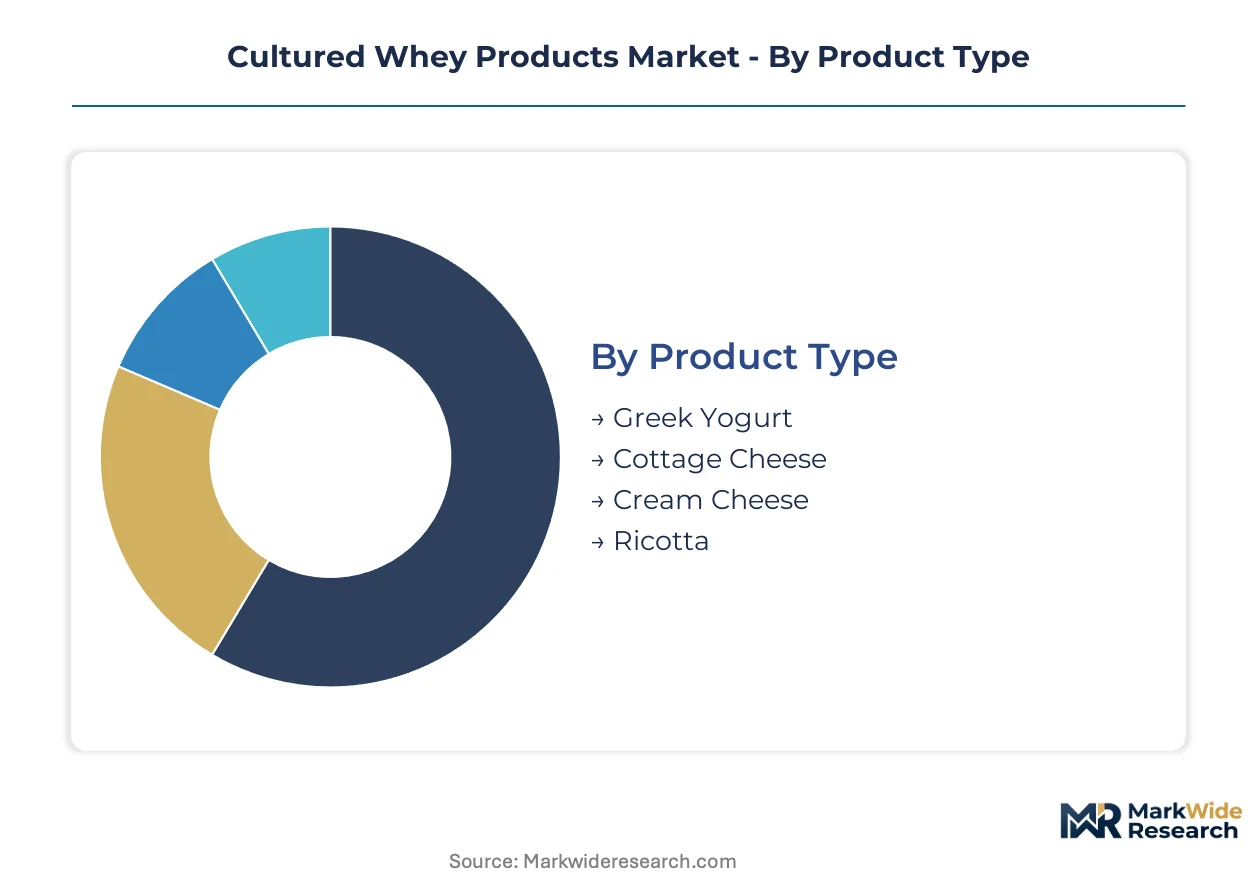
Cultured whey products fragment across four distinct dimensions that determine margin capture and supply chain configuration. Product type dictates fermentation complexity and bioactive peptide retention. Application channels impose divergent specification tolerances and certification requirements.
Product Type:
After-sales technical support intensity varies sharply across fermented dairy formats, with protein isolate customers demanding ongoing formulation assistance while retail-ready products require minimal post-sale engagement.
- Greek Yogurt:Strained fermented dairy delivering 34-80% protein concentration through controlled whey separation. Demand concentrates in United States retail dairy cases as Mediterranean diet adherence expands and clean-label positioning commands shelf space premiums. FDA dairy labeling oversight shapes formulation standardization.
- Nutritional Supplements:Isolated whey protein concentrates and hydrolysates targeting athletic recovery and sarcopenia prevention. United States sports nutrition manufacturers drive procurement volume through NCAA athletic department standardization of 20-gram post-workout protocols. Steepest expansion trajectory among all product formats.
- Cottage Cheese:Curdled whey derivative with retained casein micelles and variable moisture content. United States institutional food service contracts represent primary volume outlet.
- Cream Cheese:High-fat emulsion incorporating cultured whey for texture modification and shelf stability. Bakery sector applications in New York and California metro areas anchor demand.
- Ricotta:Heat-acid precipitated whey protein with traditional Italian process specifications. Specialty cheese shops and artisanal food manufacturers in Chicago and Boston sustain niche positioning.
By volume, Greek Yogurt leads. By growth pace, Nutritional Supplements is ahead.
Application:
Cost tier stratification separates commodity bulk whey from premium bioactive isolates, with specification tolerance bands tightening at higher price points.
- Nutritional Supplements:Protein fortification powders, ready-to-drink beverages, and clinical nutrition formulations. United States contract manufacturers in Utah and Colorado consolidate procurement through scorecard systems weighting carbon intensity equally with price. Expanding most quickly among application channels.
- Dairy Products:Ingredient inputs for yogurt, ice cream, and processed cheese manufacturing. Wisconsin and California dairy cooperatives dominate volume throughput.
- Bakery:Whey protein concentrates replacing egg whites in high-protein bread and pastry formulations. Clean-label mandates from California and Texas functional food brands accelerate uptake.
- Confectionery:Aeration and texture modification in protein-enriched chocolate and candy products. Limited penetration due to flavor masking challenges and heat stability constraints.
Volume concentration favors Dairy Products. Value capture peaks in Nutritional Supplements.
Distribution Channel:
Customer type fragmentation separates institutional buyers with technical specification teams from household consumers responding to front-of-package claims.
- Retail:Supermarket, club store, and specialty grocer placement of branded cultured whey products. United States clean-label portfolio expansions by functional food brands concentrate shelf space competition.
- E-commerce:Direct-to-consumer subscriptions and marketplace platform sales. Monthly replenishment models bypass traditional sports nutrition retail markup structures.
- Food Service:Restaurant, cafe, and institutional kitchen supply chains. NCAA Division I athletic department procurement standardization creates institutional pull-through.
- Wholesale:Bulk ingredient supply to food manufacturers and contract processors. Three brands now account for 60% of cultured whey isolate procurement volume in ready-to-drink protein beverages.
Retail maintains volume leadership. E-commerce posts the steepest growth curve.
End User:
Supply concentration patterns align with end user scale, with large food manufacturers consolidating supplier rosters while fragmented household demand sustains multiple channel pathways.
- Food Manufacturers:Industrial-scale buyers of whey protein isolates and concentrates for formulation into finished consumer goods. Ingredient customization revenue reshapes margin pools as buyers implement four-vendor concentration strategies.
- Households:Individual consumers purchasing retail-packaged cultured whey for direct consumption. Mediterranean diet adherence and aging consumer protein awareness sustain demand.
- Restaurants:Menu ingredient sourcing for high-protein and clean-label positioning. Limited penetration outside specialty health-focused concepts.
- Cafes:Beverage and foodservice applications in coffee shop and quick-service environments. Protein fortification of smoothies drives intermittent demand.
Food Manufacturers dominate procurement volume. Households represent the broadest addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India exhibit the highest price elasticity, squeezing margins on bulk whey concentrates, while Japanese purchasers of sarcopenia-targeted formulations tolerate substantial premiums for validated bioactive claims.
United States
NCAA athletic departments and functional food brands in California and Texas drive procurement volume through standardized 20-gram post-workout protocols and clean-label portfolio expansions. FDA dairy ingredient labeling oversight and USDA organic certification requirements shape supplier qualification criteria. Sports nutrition contract manufacturers in Utah and Colorado deploy digital twin technology to compress facility expansion planning timelines.
Germany
Bakery sector applications and industrial-scale dairy processing anchor demand for whey protein concentrates in high-protein bread formulations. EFSA novel food assessments and EU Green Deal sustainability benchmarks govern commercialization pathways for bioactive peptide claims. Ceramic membrane fractionation equipment suppliers in Bavaria and North Rhine-Westphalia concentrate technical expertise for 80% protein isolation systems.
Japan
The 75-plus demographic presents underexploited demand for sarcopenia-targeted whey formulations as aging consumers prioritize protein fortification. METI standards and the national health insurance system influence reimbursement pathways for clinical nutrition products. Industrial clusters in Kanto and Kansai regions pilot CRISPR-edited Lactobacillus strains to cut fermentation cycle times.
India
FSSAI's 2024 protein fortification guidelines for school nutrition programs accelerate government procurement contracts for cultured whey isolates. Central and state government feeding schemes create institutional demand channels. Dairy cooperatives in Gujarat and Maharashtra expand processing capacity to capture fortification program volumes.
Netherlands
Precision culturing advances in Danish and Dutch pilot facilities leverage CRISPR-edited strains to improve yield consistency. EFSA's 18-to-24-month evaluation window for bioactive peptide claims blocks rapid product launches but validates premium positioning. Rotterdam and Eindhoven region bioprocess engineering talent commands salary premiums for dairy fermentation expertise.
Cultured Whey Products Market Competitive Landscape
Integrated dairy cooperatives and specialized ingredient formulators split the market between bulk supply security and premium customization capabilities. The vendor base concentrates around five to eight entities with captive whey stream access or advanced fractionation assets. Two strategic archetypes dominate: vertically integrated dairy processors controlling feedstock from cheese production, and technology-focused ingredient houses differentiating through bioactive peptide portfolios. Capacity expansion in North American and European ceramic membrane systems and strategic partnerships for precision fermentation licensing represent the dominant competitive moves.
Within the cooperative-processor tier, Fonterra Co-operative Group and Arla Foods Ingredients exemplify geographic anchoring strategies, with the former leveraging New Zealand dairy infrastructure and the latter anchoring European demand through advanced whey fractionation capabilities. Glanbia occupies a position representing specialized sports nutrition ingredient formulation, differentiating through technical support intensity for isolate customers. These three entities collectively illustrate how feedstock control, regional regulatory navigation, and application-specific formulation expertise define competitive positioning in cultured whey supply.
| Leading Market Players |
|---|
| Fonterra Co-operative Group |
| Saputo |
| Lactalis Group |
| Arla Foods Ingredients |
| Glanbia |
| Hilmar Cheese Company |
| Carbery Group |
| Koninklijke FrieslandCampina |
| Idaho Milk Products |
| Others |
Value Network & Pricing Analysis
German and Japanese ceramic membrane equipment suppliers anchor upstream concentration for 80% protein isolation systems, concentrating margin capture with dairy processors that control captive whey streams from mozzarella and cheddar production cycles.
Pricing Analysis
After-sales technical support contracts for protein isolate customers drive lifetime value beyond commodity whey concentrate sales. Three-tier pricing structure across premium bioactive isolates, standard concentrates, and economy-grade feed ingredients separates contract manufacturers from retail-ready brands. Cost compression in bulk whey concentrates intensifies as Indian government procurement contracts squeeze margins. Food manufacturers implementing four-vendor concentration strategies exhibit highest price sensitivity, while Japanese sarcopenia-targeted formulation buyers tolerate substantial premiums.
Supply Chain Analysis
Extended payment terms from sports nutrition contract manufacturers in Utah and Colorado strain working capital for smaller fractionation equipment operators. Supply concentrates in New Zealand, the United States, and the Netherlands, drawing from mozzarella and cheddar whey streams in Wisconsin and Italy. Ceramic membrane systems, CRISPR-edited Lactobacillus strains, and organic certification timelines represent critical input dependencies. Single-source vulnerability persists with three German and two Japanese suppliers dominating industrial-scale fractionation equipment. Distribution runs through wholesale bulk channels for food manufacturers and direct-to-athlete subscriptions bypassing retail markup structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation technology advances position this market in early-cycle expansion, with CRISPR-edited strain adoption accelerating yield consistency improvements across North American and European manufacturing facilities.
For Market Incumbents: Pre-empt precision fermentation licensing competition by securing exclusive strain partnerships with Danish and Dutch bioprocess engineering clusters. Defend margin position through backward integration into organic-certified whey stream supply, countering feedstock volatility from Italian and Wisconsin cheese production cycles. Anchor supplier qualification criteria around carbon intensity scorecards before competitor consolidation accelerates.
For New Entrants and Emerging Players: Japan's 75-plus demographic represents the most penetrable entry point for sarcopenia-targeted whey formulations, with METI reimbursement pathways validating premium positioning. India's FSSAI protein fortification guidelines create institutional procurement channels with lower brand loyalty barriers. Direct-to-athlete subscription models bypass entrenched sports nutrition retail distribution controlled by established contract manufacturers.
For Investors and Strategic Acquirers: Capital is best deployed toward precision fermentation technology licensors with validated CRISPR-edited strain libraries and established dairy cooperative partnerships. The five-to-ten year viability window favors assets combining feedstock security with bioactive peptide formulation capabilities. EFSA novel food assessment timeline compression serves as the critical inflection signal for European market access acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Licensing | CRISPR-edited Lactobacillus strain partnerships compress fermentation cycle times by 40% in pilot facilities. |
| Ceramic Membrane Capacity Expansion | Bavarian and North Rhine-Westphalian equipment suppliers concentrate technical expertise for 80% protein isolation. |
| Organic Certification Investment | USDA's three-year transition requirement delays clean-label launches, creating first-mover advantage for certified suppliers. |
| Direct-to-Athlete Channel Development | Monthly replenishment models bypass traditional sports nutrition retail markup structures in Utah and Colorado. |
| Bioactive Peptide Clinical Validation | Randomized controlled trial data submission satisfies EFSA's updated novel food guidance ahead of enforcement. |
Research Methodology
Operator-level perspectives from dairy processing plant managers, sports nutrition contract manufacturing executives, whey fractionation equipment engineers, and institutional foodservice procurement directors anchored the qualitative base. Primary interviews combined with secondary validation from FDA dairy ingredient labeling filings, EFSA novel food assessment databases, USDA organic certification records, and FSSAI protein fortification guideline documents. Bottom-up volume modeling across product type, application channel, and end-user segments triangulated with top-down macroeconomic overlays.
Scenario-bracketing around precision fermentation adoption rates and organic certification penetration shaped the analytical framework across the analysis window. Segmentation dimensions modeled include protein concentration tier, bioactive peptide validation status, distribution channel structure, and regional regulatory cluster. CAGRs derived from volume trajectory analysis incorporating NCAA athletic department procurement standardization, clean-label portfolio expansion patterns, and geriatric nutrition penetration curves. Feedstock volatility from cheese production cycles and ceramic membrane equipment lead times informed supply-side constraints.
Macroeconomic conditions sit as an overlay; deviation in dairy commodity prices, carbon accounting standard implementation, or precision fermentation regulatory classification would shift the trajectory. Forecasts reflect documented assumptions regarding strain licensing adoption, EFSA assessment timeline stability, and institutional procurement program continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Malted Milk Powder Market
Dairy Products
Probiotic Cheese Market
Dairy Products
Milk Protein Concentrate Market
Dairy Products
North America Cheese Market
Dairy Products
Global Fortified Dairy Products Market
Dairy Products
Global Quark and Fromage Frais Market
Dairy Products
Saudi Arabia Dairy Products Market
Dairy Products
Milk Fat Fractions Market
Dairy Products
Dairy Protein Market
Dairy Products
Reduced Fat Cheeses Market
Dairy Products
North America Flavored Milk Market
Dairy Products
United States Milk Protein Market
Dairy Products
Evaporated Filled Milk Market
Dairy Products
Processed Cheese Market
Dairy Products
Fermented Dairy Products Market
Dairy Products
Spoonable Yogurt Market