
 Aseptic Processing Equipment Market | 2026-2036
Aseptic Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Aseptic Processing Equipment Market Analytics
A shift from single-source to multi-source equipment procurement is rebalancing supply relationships across the aseptic processing landscape. Robert Bosch GmbH leverages its integrated automation portfolio to anchor long-term contracts with major fill-finish operators. Syntegon Technology competes through specialized isolator and restricted access barrier systems for high-potency drug handling. GEA Group extends its position via advanced cleanroom engineering combined with process analytical technology integration.
Aseptic processing equipment encompasses sterilized machinery designed to maintain microbiological integrity during the filling, sealing, and transfer of pharmaceutical, biologic, or food products without terminal sterilization, typically operating within ISO 5 environments with HEPA-filtered unidirectional airflow. Filling machines dominate capital expenditure as biologics and vaccine production require precision dosing at high speeds with minimal human intervention. Continuous processing technology is gaining fastest traction among biotechnology firms seeking to reduce batch failure rates and accelerate time-to-market for cell and gene therapies.
FDA cGMP guidelines and EMA Annex 1 revisions on sterile product manufacturing are forcing equipment upgrades across installed bases, particularly for isolator-based filling lines and automated viable monitoring systems. The EU MDR and ISO 13485 standards for medical device aseptic assembly add parallel compliance layers for contract manufacturers serving dual pharmaceutical and device markets. Stakeholders must monitor regulatory divergence between FDA and EMA on closed-system requirements, as this will determine which equipment architectures become the investable standard.
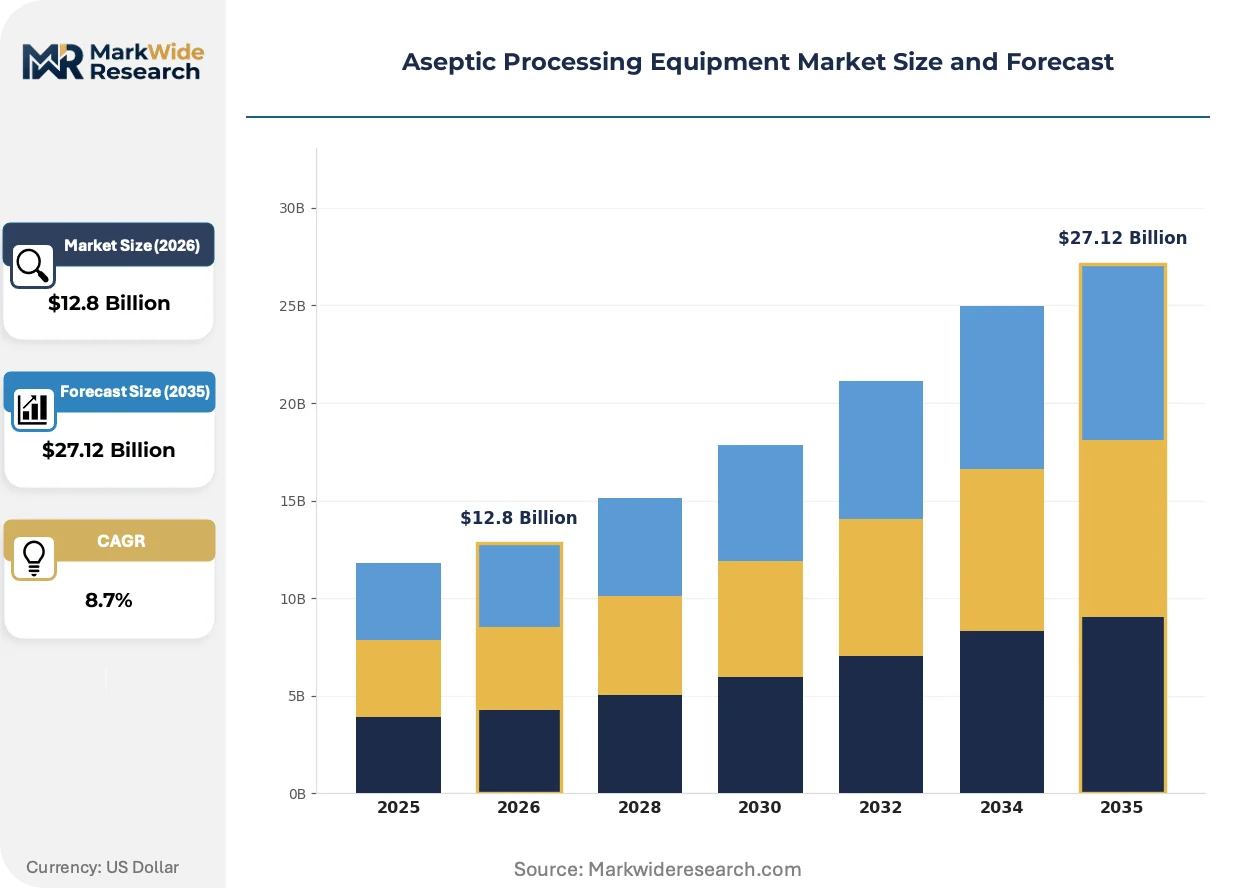
Market Dynamics
The transition from batch to continuous manufacturing is compressing equipment replacement cycles as biologics manufacturers pursue real-time release testing and reduced hold times.
Growth Catalysts
- EMA Annex 1 revisions:The 2022 update mandates isolator-based filling for high-risk sterile products, forcing equipment upgrades across European manufacturing sites.
- Cell and gene therapy expansion:Personalized medicine pipelines require flexible, small-batch aseptic systems with rapid changeover capabilities.
- Germany:The country's cluster of biologics fill-finish facilities in Bavaria and Baden-Württemberg drives concentrated demand for advanced barrier technology.
Market Restraints
- Stainless steel price volatility:Equipment fabricators face margin pressure from nickel and chromium input cost swings, particularly affecting large-scale tank and vessel production.
- Specialized component suppliers:Critical subsystems including HEPA filtration modules and robotic dosing arms concentrate among German and Swiss precision engineering firms.
- Terminal sterilization alternatives:Advancements in gamma and electron beam sterilization for certain biologic containers reduce aseptic processing necessity for select product categories.
Strategic Opportunities
- India:Contract manufacturing organizations in Hyderabad and Bengaluru are building greenfield sterile facilities without legacy equipment constraints.
- Process analytical technology integration:Converging spectroscopic sensors with isolator systems enables real-time contamination monitoring and predictive maintenance.
- Closed-system requirements:FDA draft guidance on closed aseptic processing creates specification advantages for vendors with pre-validated single-use fluid paths.
Industry Challenges
- Cleanroom engineering expertise:Shortages of qualified HVAC and unidirectional airflow designers extend facility commissioning timelines by 6-12 months.
- Legacy system integration:Brownfield sites struggle to retrofit isolator lines into existing Grade A/B suite configurations without full production shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aseptic Processing Equipment Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filling Machines, Sealing Machines, Sterilizers, Conveyors End User: Pharmaceutical Companies, Biotechnology Firms, Contract Manufacturers, Hospitals Technology: Batch Processing, Continuous Processing, Cold Sterilization, Hot Water Sterilization Application: Liquid Products, Powder Products, Medical Devices, Vaccine Production |
| Companies Covered | Robert Bosch GmbH, Rommelag, DuPont, SPX Flow, Inc., Becton, Dickinson, and Company, GEA Group, AMCOR plc, John Bean Technologies Corporation, Syntegon Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aseptic Processing Equipment Market Evolving Landscape
Automation architectures are converging with pharmaceutical quality systems to enable autonomous aseptic operations with minimal human intervention.
Single-use isolator systems are absorbing capital expenditure preference among multi-product biologics facilities. Contract manufacturers in the United States and Germany are specifying disposable glove ports and beta-bag transfer systems for campaign-based production. This shift is absorbing maintenance labor from stainless steel cleaning validation toward consumables supply chain management.
REACH restrictions on per- and polyfluoroalkyl substances are compelling equipment seal and gasket material substitutions. European manufacturers must validate alternative elastomers for barrier integrity without compromising ISO 5 classification. Isolator vendors serving EMA-regulated sites are accelerating fluoropolymer-free component qualification programs.
Equipment-as-a-service arrangements are displacing traditional capital purchase models for mid-scale biotechnology firms. CDMOs in India and the United States are subscribing to isolator lines with bundled validation and maintenance packages. This restructuring is most visible among emerging cell therapy developers lacking in-house sterile engineering capabilities.
Aseptic Processing Equipment Market Segmentation
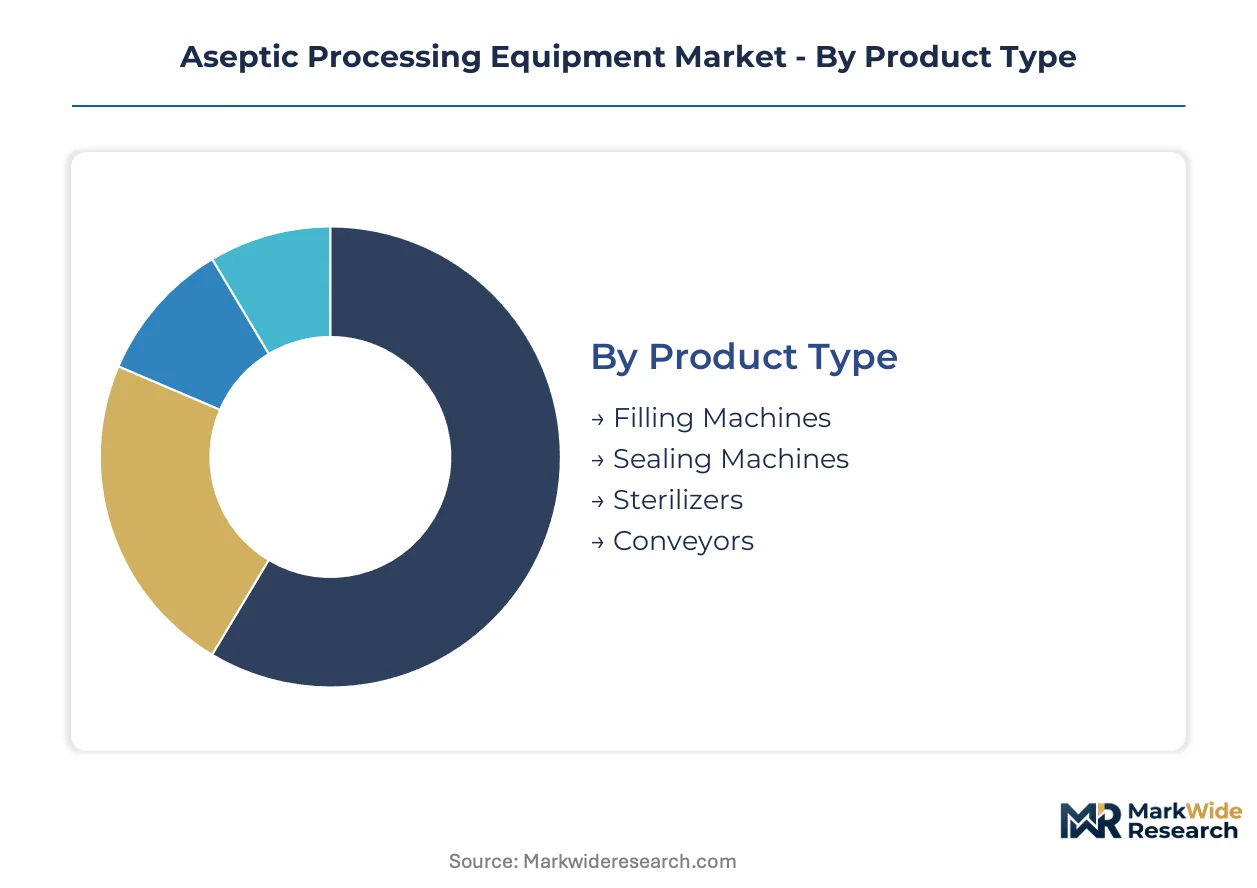
Aseptic processing equipment procurement splits across four dimensions that determine validation complexity, capital intensity, and regulatory exposure. Product type governs installed base economics. End user concentration shapes service contract structures. Technology choice locks in operational flexibility for decades. Application specificity dictates barrier system architecture.
Product Type:
Supply concentrates among German and Swiss precision engineering houses for high-speed dosing subsystems, creating procurement bottlenecks for multi-line facility expansions.
- Filling Machines:Rotary piston and peristaltic dosing systems dominate capital expenditure in biologics fill-finish suites. Pharmaceutical companies in Germany and the United States are specifying isolator-integrated lines with 100% checkweighing to meet FDA cGMP and EMA Annex 1 contamination control mandates.
- Sealing Machines:Aluminum crimping and laser welding systems for vial and syringe closure require validated seal integrity testing. Demand clusters in vaccine production facilities across India and the United States as these countries expand pandemic preparedness manufacturing capacity.
- Sterilizers:Saturated steam and vaporized hydrogen peroxide systems provide terminal decontamination for equipment surfaces and packaging components.
- Conveyors:Restricted access barrier-compatible transport systems move containers between processing stations with minimal human intervention.
Today's leader: Filling Machines. Tomorrow's challenger: Sealing Machines.
End User:
Cost tier stratification separates multi-billion-dollar pharmaceutical conglomerates from emerging cell therapy developers with constrained capital budgets.
- Pharmaceutical Companies:Large-scale sterile product manufacturers operate integrated fill-finish networks with dedicated engineering teams. These buyers in the United States and Germany favor long-term service agreements with single-source automation vendors to minimize validation burden.
- Biotechnology Firms:Cell and gene therapy developers require flexible, small-batch systems with rapid changeover protocols. Facilities in Boston and San Diego are absorbing equipment-as-a-service arrangements to avoid upfront capital deployment.
- Contract Manufacturers:CDMOs in Hyderabad and Bengaluru specify disposable isolator components for campaign-based multi-product manufacturing.
- Hospitals:Compounding pharmacies and centralized sterile preparation facilities operate at smaller scale with simplified barrier technology.
Pharmaceutical Companies command volume. Biotechnology Firms are climbing the fastest.
Technology:
Volume distribution favors batch architectures in legacy facilities, though greenfield investments are tilting toward continuous modalities.
- Batch Processing:Traditional start-stop manufacturing with defined hold times and intermediate testing remains prevalent in brownfield pharmaceutical sites. EMA Annex 1 revisions are forcing these installed bases toward isolator retrofits with automated viable monitoring.
- Continuous Processing:Real-time release testing and reduced hold-time manufacturing compress equipment replacement cycles. Biotechnology firms in Germany and the United States are piloting these systems for cell therapy media preparation and final fill operations.
- Cold Sterilization:Vaporized hydrogen peroxide and chlorine dioxide systems decontaminate heat-sensitive materials and barrier enclosures.
- Hot Water Sterilization:Saturated steam cycles provide validated kill assurance for stainless steel equipment and resistant packaging.
Batch Processing holds installed base dominance. Continuous Processing shows the steepest expansion trajectory.
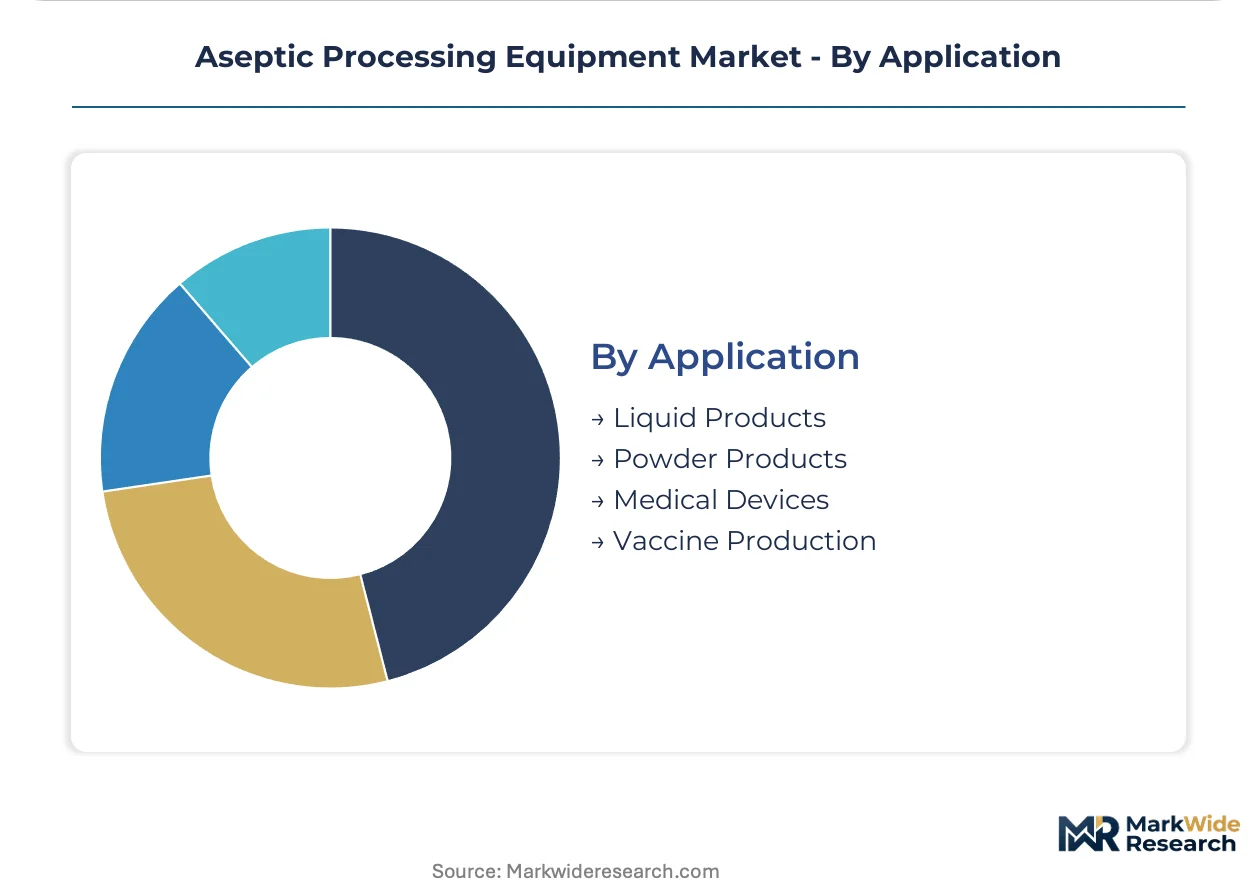
Application:
Customer type differentiation separates high-value biologics requiring absolute barrier integrity from commoditized products tolerating conventional cleanroom processing.
- Liquid Products:Parenteral solutions, suspensions, and emulsions demand precision dosing with minimal particulate generation. Vaccine production facilities in India and the United States are specifying isolator-based lines with 100% visual inspection integration.
- Vaccine Production:Pandemic preparedness investments and routine immunization programs are driving fill-finish capacity expansion. Manufacturers in Germany and India are building dedicated sterile facilities with advanced barrier technology and automated component handling.
- Powder Products:Lyophilized and spray-dried formulations require specialized powder handling systems with containment and moisture protection.
- Medical Devices:Implantable and combination products must meet ISO 13485 quality standards alongside pharmaceutical GMP requirements.
Liquid Products anchor current procurement. Vaccine Production is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's biologics manufacturing corridor anchors demand concentration for advanced barrier systems and isolator-integrated filling lines across the aseptic processing equipment landscape.
United States
Cell and gene therapy developers in Boston and San Diego drive procurement of flexible, small-batch aseptic systems with rapid changeover protocols. FDA draft guidance on closed aseptic processing shapes equipment specifications for fill-finish operators. The Greater Boston biotechnology cluster absorbs equipment-as-a-service arrangements to avoid upfront capital deployment for personalized medicine production.
Germany
Large-scale sterile product manufacturers in Baden-Württemberg operate integrated fill-finish networks with dedicated engineering teams favoring long-term service agreements. EMA Annex 1 revisions mandate isolator-based filling for high-risk sterile products, forcing upgrades across European manufacturing sites. The Stuttgart precision engineering ecosystem supplies critical subsystems including HEPA filtration modules and robotic dosing arms.
India
Contract manufacturing organizations in Hyderabad and Bengaluru build greenfield sterile facilities without legacy equipment constraints. CDSCO regulations on sterile product manufacturing guide validation requirements for multi-product campaign-based operations. The Hyderabad pharmaceutical corridor specifies disposable isolator components and beta-bag transfer systems for flexible manufacturing.
Switzerland
Swissmedic oversight of biologics manufacturing drives demand for advanced cleanroom engineering combined with process analytical technology integration. Precision engineering firms concentrate supply of critical dosing subsystems for high-speed aseptic lines. The Basel biopharmaceutical cluster purchases isolator-integrated lines with 100% checkweighing for contamination control compliance.
United Kingdom
MHRA alignment with EMA Annex 1 standards shapes equipment upgrade trajectories for existing fill-finish facilities. The Oxford-Cambridge biotech arc pilots continuous processing technology to reduce batch failure rates and accelerate time-to-market for cell therapies. London-based contract manufacturers retrofit isolator lines into Grade A/B suite configurations to meet tightening validation requirements.
Aseptic Processing Equipment Market Competitive Landscape
Global majors compete with regional champions across automation integration and barrier system specialization, producing a tiered structure where integrated portfolios anchor long-term contracts while niche specialists capture high-potency drug handling segments. Three archetypes dominate: diversified industrial conglomerates with pharmaceutical automation divisions, pure-play aseptic equipment fabricators, and precision engineering houses supplying critical subsystems. M&A activity concentrates on isolator technology acquisitions and strategic partnerships for process analytical technology integration.
Within the diversified industrial tier, Robert Bosch GmbH exemplifies the automation-anchored model through its integrated portfolio approach. Syntegon Technology occupies a position among specialized barrier system providers, representing the pure-play archetype focused on isolator and restricted access barrier systems. GEA Group sits within the engineering-heavy segment, anchoring the cleanroom integration and process technology convergence pattern. These three entities collectively illustrate the competitive vectors shaping procurement relationships across biologics fill-finish networks.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Rommelag |
| DuPont |
| SPX Flow, Inc. |
| Becton, Dickinson, and Company |
| GEA Group |
| AMCOR plc |
| John Bean Technologies Corporation |
| Syntegon Technology |
| Others |
Value Network & Pricing Analysis
Large-scale pharmaceutical conglomerates in Germany and the United States anchor procurement volume for aseptic processing equipment, locking in long-term service agreements with single-source automation vendors that compress pricing flexibility for mid-tier buyers. This buyer concentration tilts contract structures toward bundled validation and maintenance packages, forcing smaller biotechnology firms toward equipment-as-a-service subscriptions.
Pricing Analysis
Input-cost pass-through from stainless steel price volatility shapes equipment quotations, with nickel and chromium swings compressing fabricator margins on large-scale tank and vessel production. Three-tier pricing structure across premium isolator-integrated lines, standard restricted access barrier systems, and economy-grade cleanroom equipment reflects certification grade and after-sales service bundling. Pricing pressure stems from REACH restrictions on per- and polyfluoroalkyl substances compelling fluoropolymer-free component requalification. Biotechnology firms with constrained capital budgets exhibit highest price sensitivity, while pharmaceutical conglomerates prioritize compliance assurance over unit cost.
Supply Chain Analysis
Workforce availability constraints in Baden-Württemberg and Bavaria extend commissioning timelines for cleanroom engineering projects by six to twelve months. Supply concentrates among German and Swiss precision engineering houses for HEPA filtration modules and robotic dosing arms, with India emerging as an alternative fabrication hub for standardized conveyor systems. Raw material dependencies span high-grade stainless steel, specialized elastomer seals, and precision-machined dosing components. Single-source vulnerability concentrates in critical subsystem suppliers, particularly for isolator glove ports and beta-bag transfer systems. Distribution runs through direct OEM relationships for large pharmaceutical accounts and regional equipment distributors serving emerging biotechnology clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aseptic processing equipment market functions as a geographic-arbitrage play where contract manufacturers in India capture cost advantages from greenfield construction without legacy retrofit burdens, while German facilities absorb EMA Annex 1 compliance premiums.
For Market Incumbents: Acquire isolator technology specialists to anchor barrier system capabilities against pure-play competitors. Consolidate position by expanding process analytical technology integration offerings, as real-time contamination monitoring becomes a mandatory specification. Lock in long-term service agreements with fill-finish operators in Bavaria and Baden-Württemberg before EMA Annex 1 upgrade cycles peak. For New Entrants and Emerging Players: Cell therapy developers in Boston and San Diego represent an underserved buyer archetype seeking flexible, small-batch systems with rapid changeover protocols. Penetrate this segment through equipment-as-a-service arrangements that eliminate upfront capital barriers. Target the Hyderabad pharmaceutical corridor with disposable isolator components designed for campaign-based multi-product manufacturing. For Investors and Strategic Acquirers: Pharmaceutical automation divisions of diversified industrial conglomerates are the most active acquirer in this space, seeking to fill isolator and restricted access barrier system gaps. Position portfolios for a five-to-ten year window where EMA-FDA regulatory divergence on closed-system requirements determines which equipment architectures become investable standards. Monitor FDA draft guidance finalization as the critical inflection signal for specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Acquisition | EMA Annex 1 mandates isolator-based filling for high-risk sterile products across European sites. |
| Process Analytical Technology Integration | FDA cGMP guidelines favor real-time contamination monitoring for accelerated release testing. |
| Equipment-as-a-Service Launch | Boston cell therapy clusters absorb subscription models to avoid upfront capital deployment. |
| Fluoropolymer-Free Component Qualification | REACH restrictions on per- and polyfluoroalkyl substances force seal and gasket material substitutions. |
| Greenfield Facility Partnership | Hyderabad CDMOs build sterile capacity without legacy equipment constraints for flexible manufacturing. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fill-finish engineering directors, regulatory affairs leads at pharmaceutical manufacturers, cleanroom HVAC designers, and CDMO procurement managers with secondary validation against FDA cGMP guidance documents, EMA Annex 1 revision texts, CDSCO sterile product regulations, and ISO 14644 cleanroom classification standards. Bottom-up equipment shipment data triangulated against top-down pharmaceutical capital expenditure disclosures.
Comparable-period anchoring linked projection assumptions to historical validation cycles across prior regulatory guideline revisions. Segmentation modeling spanned product type, end user category, technology modality, and application specificity with regional regulatory cluster overlays. CAGRs derived from equipment replacement cycle compression rates and greenfield facility investment trajectories. Forecast inputs incorporated stainless steel price indices and precision engineering labor availability metrics.
Underlying measurement precision varies by segment; filling machine and isolator system data carry tighter precision than emerging single-use component categories. Forecasts reflect documented assumptions on regulatory timeline adherence and commodity price stabilization. Material deviation in EMA-FDA closed-system guidance divergence or sustained nickel price volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Individual Quick Freezing Market
Food Processing Equipment
Brewing Thermometer Market
Food Processing Equipment
Cookers and Ovens Market
Food Processing Equipment
Global Conveyor Oven Market
Food Processing Equipment
Small Brewery Equipment Market
Food Processing Equipment
Bakery Processing Equipment Market
Food Processing Equipment
Salmon Fish Scaling Machine Market
Food Processing Equipment
Insect Protein Processing Equipment Market
Food Processing Equipment
Corn Puff Making Machine Market
Food Processing Equipment
Tube Ice Machine Market
Food Processing Equipment
Pasty Products Filling Machine Market
Food Processing Equipment
Food Disinfection Equipment Market
Food Processing Equipment
Smart Bread Machine Market
Food Processing Equipment
Oven Market
Food Processing Equipment
Coffee Processing Machine Market
Food Processing Equipment
Commercial Winery Equipment Market