
 Batter Mixer Machines Market | 2026-2036
Batter Mixer Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Batter Mixer Machines Market Outlook
Artisan and mid-sized commercial bakeries is redrawing procurement patterns across the batter mixer landscape. Hobart Corporation leverages its century-long brand strength in planetary mixer design to command premium positioning in North American foodservice channels. DIOSNA Dierks & Söhne GmbH anchors its competitive stance through specialized spiral mixer engineering for industrial dough applications. Marel competes by extending automation integration from mixing through downstream portioning systems.
Batter mixer machines are electromechanical or pneumatic devices designed to homogenize viscous batter formulations through controlled rotational shear, typically operating at 20–200 RPM with bowl capacities from 10 to 800 liters depending on configuration. These systems serve primarily to ensure uniform hydration of dry ingredients, stable emulsion of fats, and consistent aeration for baked goods, snack coatings, and prepared foods manufacturing. Planetary mixers capture the broadest installed base due to versatile attachment compatibility across bakery sub-segments, while automated technology lines command the fastest expansion as labor costs escalate and batch consistency requirements tighten. Horizontal mixers occupy specialized positions in high-throughput cracker and wafer operations where continuous processing margins justify capital intensity.
FDA Title 21 CFR food-contact surface regulations and NSF/ANSI sanitation standards govern equipment design, material selection, and cleanability validation for US-market batter mixers, directly elevating stainless steel specification rates and welded-seam construction requirements. The EU Machinery Directive and CE marking obligations impose additional safety interlock and ergonomic load specifications for European export-bound equipment. Stakeholders must monitor evolving allergen-control protocols and energy-efficiency benchmarks as these frameworks increasingly differentiate market-access eligibility across jurisdictions.
Market Dynamics
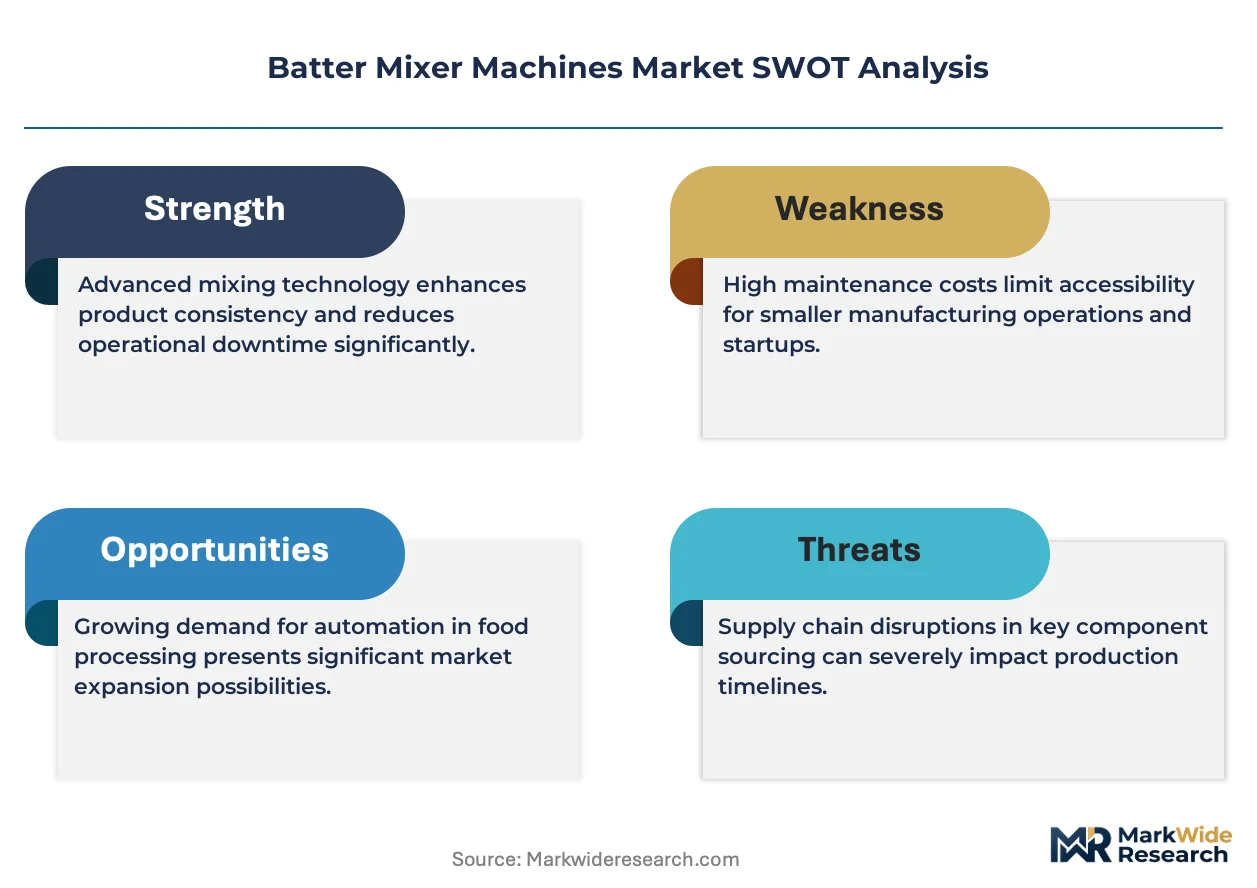
Automation of mixing operations is compressing replacement cycles across commercial bakeries as labor availability tightens and batch consistency requirements intensify. Equipment buyers now prioritize integrated systems that reduce manual intervention and enable real-time viscosity monitoring.
Growth Catalysts
- NSF/ANSI sanitation mandates:Tightening food-contact surface standards in the United States are accelerating stainless steel equipment upgrades and welded-seam construction adoption across industrial bakery installations.
- Commercial bakery automation:Large-scale producers are replacing legacy planetary mixers with continuous processing lines to achieve throughput targets and reduce per-batch labor hours.
- Energy-efficiency benchmarking:EU Green Deal performance standards are creating specification advantages for variable-frequency drive systems and heat-recovery mixing configurations in European export markets.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 stainless price swings directly compress equipment margins and extend quote validity periods for manufacturers.
- Specialized component concentration:Precision gearbox and servo motor supply concentrates in German and Japanese industrial clusters, exposing lead time risk for non-integrated producers.
- Continuous mixer technical ceiling:Viscous batters with high inclusion loads remain difficult to process without batch interruption, limiting penetration in specialty bakery segments.
Strategic Opportunities
- India commercial bakery expansion:FSSAI food safety modernization and organized retail growth are creating first-time automation demand among mid-tier biscuit and cake producers in Maharashtra and Karnataka.
- IoT-enabled predictive maintenance:Convergence of vibration sensors and cloud analytics platforms is opening recurring revenue streams through subscription-based uptime guarantees.
- Clean-label formulation adaptation:Reduced-emulsifier and alternative-fat batters require modified shear profiles, creating retrofit attachment markets for installed planetary mixer bases.
Industry Challenges
- Controls engineering talent scarcity:Integration of servo-driven bowl lift systems and programmable recipe management demands specialized automation expertise that outpaces vocational training pipeline output.
- Legacy equipment interoperability:Retrofitting data acquisition modules to 15-20 year old mixer fleets requires custom mechanical adaptation and creates warranty boundary disputes.
- FDA validation documentation burden:Food-contact surface compliance timelines extend 8-14 weeks for new material formulations, compressing product development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Batter Mixer Machines Market |
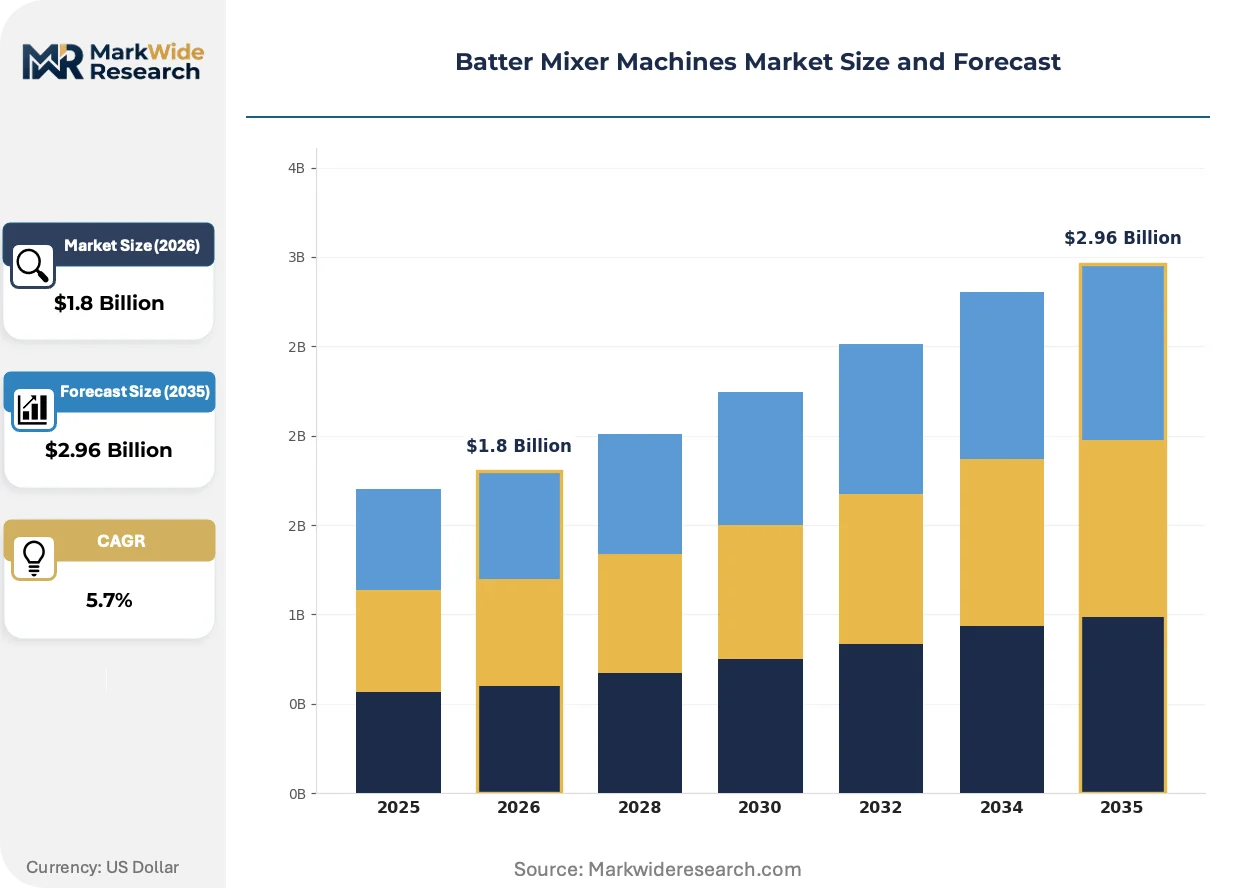
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Mixers, Horizontal Mixers, Planetary Mixers, Spiral Mixers Capacity: Small Scale, Medium Scale, Large Scale, Industrial Grade Technology: Electric, Manual, Automated, Hybrid End User: Commercial Bakeries, Restaurants, Catering Services, Household Use |
| Companies Covered | Jas Enterprises, Hobart Corporation, DIOSNA Dierks & Söhne GmbH, Sri Lakshmi Food Machines, Trident Engineers, Hamburg Dresdner Maschinenfabriken, Univex, Marel, Baker Perkins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Batter Mixer Machines Market Strategic Shifts
Digitalization of mixing parameters and modular equipment architecture are redefining how bakeries configure production lines. Real-time viscosity feedback and recipe-driven automation are becoming baseline expectations rather than premium features.
Variable-frequency drive technology is replacing fixed-speed transmission systems in mid-capacity planetary mixers. Artisan and mid-sized commercial bakeries are adopting these retrofits to reduce energy consumption and enable gentle folding speeds for delicate batters. The technology is miniaturizing control footprints while expanding torque precision across bowl sizes from 20 to 140 liters.
EU Machinery Directive safety interlock requirements are mandating two-hand operation protocols and emergency stop redundancy for export-bound equipment. Manufacturers serving European markets must redesign guard systems and load-handling ergonomics to maintain CE marking eligibility. Industrial bakery operators in Germany and the Netherlands are prioritizing these certified configurations to satisfy insurer liability requirements.
Equipment-as-a-service contracting is displacing traditional capital purchase models among multi-site bakery chains. Third-party financing entities now own mixer assets and charge per-batch processing fees, transferring obsolescence risk from operators to vendors. This arrangement concentrates in the United States where tax-advantaged leasing structures and private equity-backed bakery rollouts accelerate adoption.
Batter Mixer Machines Market Segmentation
Batter mixer machine procurement diverges sharply by operational scale and regulatory exposure. Equipment specification now tracks end-use intensity, with industrial buyers demanding continuous-duty architectures that household and small commercial segments cannot justify.
Product Type:
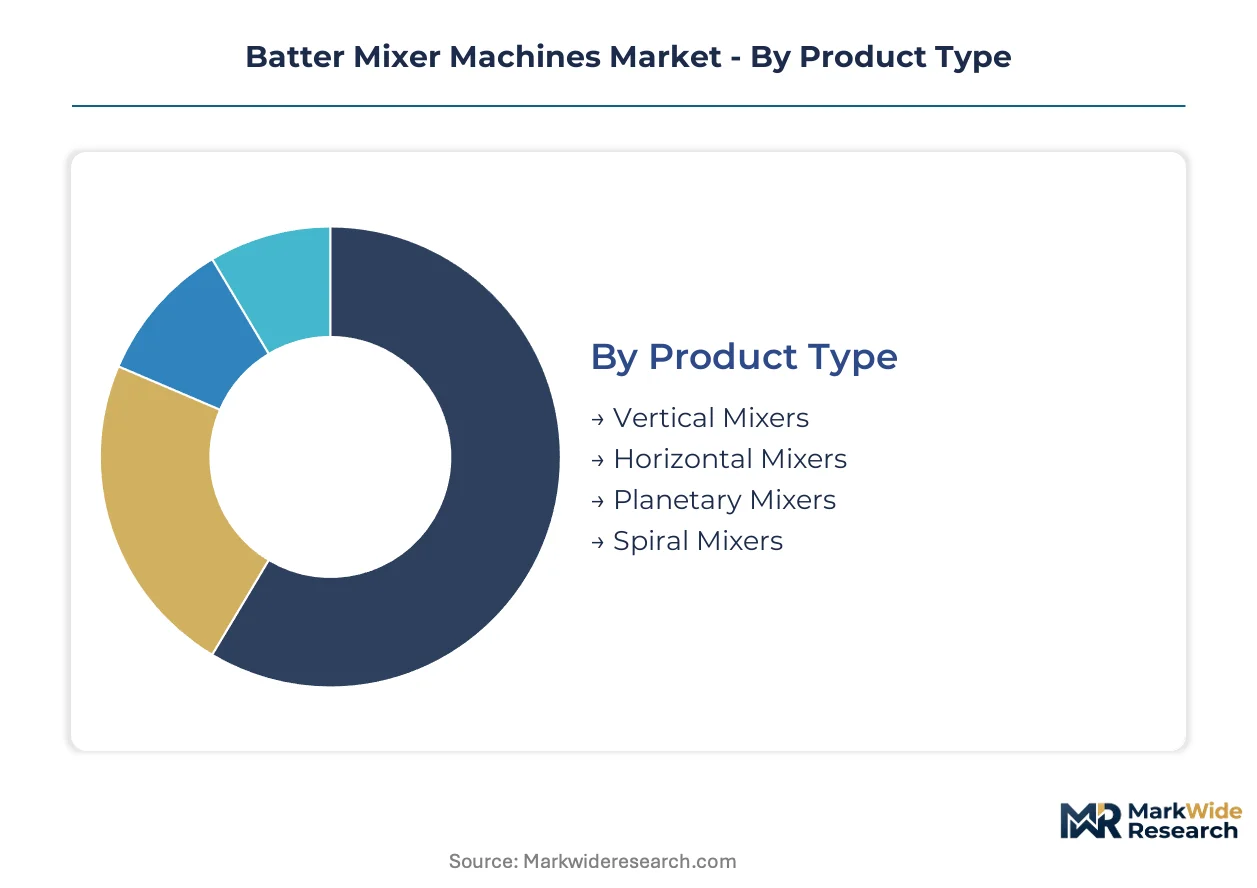
Domestic demand concentrates in planetary and vertical configurations, while horizontal and spiral variants dominate export shipments to industrial bakery clusters.
- Planetary Mixers:Rotating bowl and orbiting agitator geometry enables attachment interchangeability across whisk, paddle, and dough hook configurations. Commercial bakeries in the United States specify these for 60-quart through 140-quart capacities where batch versatility outweighs throughput maximization. NSF/ANSI sanitation compliance costs elevate stainless steel specification rates above import alternatives.
- Horizontal Mixers:Twin-shaft or single-shaft ribbon agitators process stiff, high-inclusion doughs through extended barrel chambers. German and Dutch industrial cracker manufacturers deploy these for continuous 24-hour operations where thermal management and shaft seal longevity determine total cost of ownership. CE marking requirements under the EU Machinery Directive mandate redundant safety interlocks for export-bound units.
- Vertical Mixers:Bowl-lift or tilt-head designs optimize floor space in mid-capacity installations. Small commercial bakeries and catering operations favor these for cake batter and icing preparation where portability and rapid bowl exchange matter more than raw throughput.
- Spiral Mixers:Rotating bowl with fixed-center spiral hook kneads dough with minimal friction heating. Artisan bread producers and pizza chains specify these for gluten development without temperature spikes that compromise yeast viability.
Planetary mixers hold the largest share; momentum sits with horizontal configurations in export markets.
Capacity:
Cost tier stratification separates premium industrial-grade systems from economy small-scale alternatives, with mid-tier equipment capturing replacement demand from maturing commercial bakery fleets.
- Industrial Grade:400-liter through 800-liter bowl volumes with programmable recipe management and automated ingredient staging. Large-scale United States biscuit and cake manufacturers specify these for continuous processing lines where labor substitution drives capital allocation decisions.
- Large Scale:200-liter to 400-liter configurations bridging batch and semi-continuous operations. Regional bakery chains in Texas, California, and Illinois deploy these for multi-shift production without full automation capital commitment.
- Medium Scale:60-liter to 140-liter planetary and spiral variants dominate independent commercial bakery procurement. Equipment-as-a-service financing models concentrate in this tier among multi-site operators seeking to transfer obsolescence risk.
- Small Scale:10-liter to 60-liter countertop and floor-standing units serve catering services and specialty dessert producers. Price sensitivity here compresses margin structures and favors Asian manufacturing origins.
Industrial grade systems command premium pricing; medium scale configurations are expanding most quickly through equipment-as-a-service adoption.
Technology:
Application intensity determines technology selection, with high-throughput environments demanding servo-driven automation that manual and basic electric systems cannot deliver.
- Automated:PLC-controlled bowl positioning, ingredient dosing integration, and real-time viscosity feedback. Large commercial bakeries specify these for reduced batch-to-batch variation and labor hour compression.
- Electric:Fixed or variable-frequency drive motors dominate mid-capacity installations. Variable-frequency retrofits are gaining share among artisan bakeries seeking energy reduction and gentle folding capability.
- Hybrid:Pneumatic bowl lift with electric agitation combines reliability and precision. European export markets favor these for ergonomic load-handling compliance under EU Machinery Directive specifications.
- Manual:Hand-crank or basic gear-driven systems persist in household and ultra-small commercial niches where capital constraints override productivity concerns.
Electric systems retain volume leadership; automated technology is gaining share fastest as labor costs escalate.
End User:
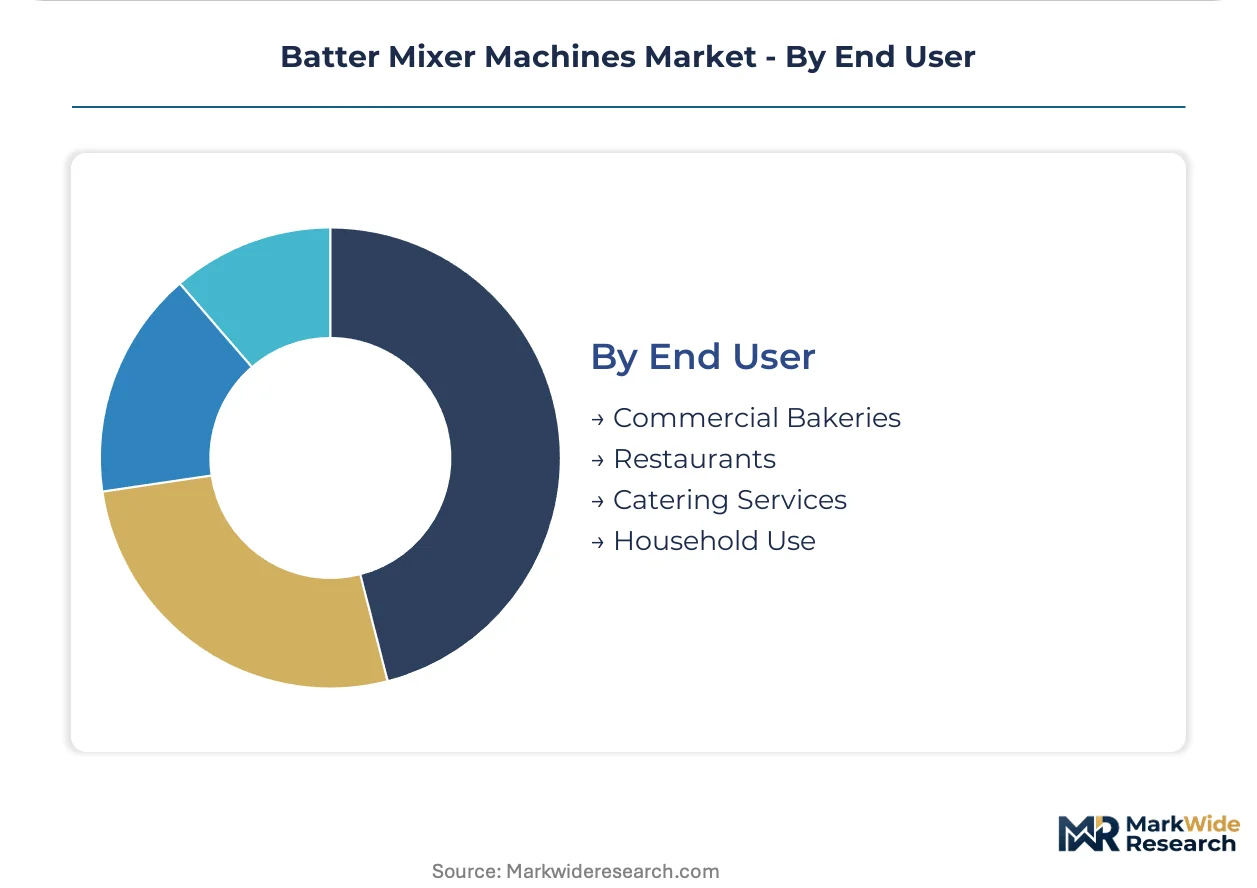
Customer type segmentation reveals divergent procurement authority structures, with commercial bakeries consolidating purchasing decisions at regional or national levels while restaurants and catering services delegate to individual locations.
- Commercial Bakeries:Centralized procurement of 80-quart and larger planetary mixers with sanitation certification requirements. United States industrial operators drive replacement cycles as FDA food-contact surface standards tighten.
- Restaurants:Smaller countertop and floor-standing units for in-house bread and dessert programs. Full-service chains specify NSF-certified equipment to satisfy health department inspection protocols.
- Catering Services:Portability and rapid setup dominate specification criteria. Tilt-head vertical mixers with caster-mounted bases capture preference for off-site event deployment.
- Household Use:Stand mixers with aesthetic-driven design and limited-duty cycle ratings. This segment sits outside commercial-grade manufacturer focus but influences attachment standardization.
Commercial bakeries anchor demand volume; catering services show steepest expansion trajectory through event-sector recovery and ghost kitchen proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Italian equipment manufacturers dominate export flows to North American commercial bakeries, while Asian fabrication clusters increasingly supply price-sensitive mid-tier segments across emerging markets.
United States
Large-scale industrial bakeries in Texas and Illinois drive replacement cycles for 80-quart and larger planetary configurations. FDA Title 21 CFR food-contact surface regulations mandate stainless steel construction and welded-seam validation, extending procurement timelines. Chicago and Dallas-Fort Worth anchor concentrated demand from multi-site biscuit and cake producers consolidating mixing operations.
Germany
Industrial cracker and wafer manufacturers in Lower Saxony and Baden-Württemberg specify horizontal mixers for continuous 24-hour throughput. EU Machinery Directive safety interlock requirements and CE marking obligations shape guard system redesigns for export-bound equipment. Hamburg and Dresden host precision gearbox and servo motor suppliers that concentrate component sourcing for European mixer fabricators.
India
FSSAI food safety modernization and organized retail expansion create first-time automation demand among mid-tier biscuit producers in Maharashtra and Karnataka. Central excise incentives for capital goods imports reduce effective equipment costs for commercial bakeries in Pune and Bangalore. Mumbai and Bangalore industrial corridors concentrate procurement authority for regional bakery chains upgrading from manual preparation.
China
Domestic bakery automation accelerates in Yangtze River Delta and Pearl River Delta manufacturing belts as labor costs escalate. GB standards for food machinery safety and SAMR market access protocols elevate stainless steel specification rates above legacy cast alternatives. Shanghai and Guangzhou anchor equipment distribution networks serving both domestic processors and Southeast Asian export markets.
Netherlands
Industrial bakery operators in North Brabant prioritize CE-certified configurations to satisfy insurer liability requirements under EU Machinery Directive specifications. Variable-frequency drive retrofits gain share among artisan bakeries seeking energy reduction and gentle folding capability. Eindhoven and Rotterdam clusters concentrate R&D activity for real-time viscosity monitoring and recipe-driven automation integration.
Batter Mixer Machines Market Competitive Environment
Player mix skews toward specialized industrial equipment fabricators with century-long brand recognition in planetary and spiral mixer engineering. Market structure consolidates around three tiers: premium European specialists commanding specification authority in export markets, mid-tier Asian manufacturers capturing price-sensitive commercial bakery demand, and regional assemblers serving localized aftermarket service requirements. Dominant competitive moves include equipment-as-a-service financing model expansion and IoT-enabled predictive maintenance subscription offerings.
Within the premium European specialist tier, Hobart Corporation and DIOSNA Dierks & Söhne GmbH exemplify divergent specialization strategies—Hobart anchoring North American foodservice channel presence through planetary mixer heritage, DIOSNA occupying industrial dough application positioning through spiral engineering focus. Marel represents the automation-integrated archetype, extending control systems from mixing through downstream portioning. Hamburg Dresdner Maschinenfabriken and Baker Perkins occupy horizontal mixer specialization for continuous cracker and wafer operations.
| Leading Market Players |
|---|
| Jas Enterprises |
| Hobart Corporation |
| DIOSNA Dierks & Söhne GmbH |
| Sri Lakshmi Food Machines |
| Trident Engineers |
| Hamburg Dresdner Maschinenfabriken |
| Univex |
| Marel |
| Baker Perkins |
| Others |
Value Chain & Pricing Dynamics
Industrial-grade capacity utilization above 80 percent in German and Italian manufacturing clusters concentrates pricing power among premium European specialists while compressing margin structures for mid-tier Asian fabricators serving price-sensitive commercial bakery segments. This scale asymmetry creates divergent price floors: automated continuous-mixer platforms command premium positioning through NSF/ANSI certification bundling, while basic planetary configurations face cost compression from stainless steel input volatility and extended quote validity periods.
Pricing Analysis
Current-generation automated technology lines with PLC-controlled bowl positioning and real-time viscosity feedback command substantial premiums over prior-generation fixed-speed electric systems, while next-generation IoT-enabled predictive maintenance subscriptions are displacing traditional capital purchase models. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with FDA food-contact surface compliance and CE marking under EU Machinery Directive creating specification tiers that separate Hobart and DIOSNA positioning from Asian import alternatives. Pricing pressure stems from Grade 304 and 316 stainless price swings that compress equipment margins and extend quote validity periods for non-integrated producers. Small-scale catering and household segments exhibit highest price sensitivity, while large-scale United States industrial bakeries prioritize total cost of ownership and uptime guarantees over initial capital outlay.
Supply Chain Analysis
Strategic stockpiling of precision gearboxes and servo motors characterizes European mixer fabricator procurement strategies, contrasting with just-in-time inventory preferences among Asian mid-tier assemblers exposed to component lead time volatility. Manufacturing concentration centers on Germany, Italy, and China, with Hamburg and Dresden hosting precision gearbox suppliers that feed German industrial equipment clusters while Yangtze River Delta fabrication belts serve domestic Chinese and Southeast Asian export markets. Raw material dependencies rest on Grade 304/316 stainless steel, precision servo motors, and specialized shaft seals. Single-source vulnerability concentrates in German and Japanese industrial clusters for precision gearbox and servo motor supply, exposing non-integrated producers to lead time risk. Distribution runs through OEM-direct channels for large industrial accounts and regional distributor networks for mid-tier commercial bakery segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across artisan and mid-sized commercial bakery tiers where automation requirements outpace incumbent service coverage, with equipment-as-a-service financing models creating niche entry points for specialized players.
For Market Incumbents: Shield installed base revenue through backward integration into precision gearbox and servo motor supply chains, reducing single-source exposure that extends lead times and compresses margins. Prioritize NSF/ANSI certification investment and welded-seam construction validation to maintain specification authority as FDA Title 21 CFR food-contact surface regulations tighten. Defensive consolidation through regional aftermarket service network acquisition protects against emerging IoT-native entrants offering subscription-based uptime guarantees. For New Entrants and Emerging Players: Lead with equipment-as-a-service financing models targeting mid-tier commercial bakery chains in Texas, California, and Illinois where capital constraints and obsolescence risk transfer create first-mover advantage. White-space opportunity concentrates in India commercial bakery expansion across Maharashtra and Karnataka, where FSSAI food safety modernization drives first-time automation demand among biscuit and cake producers upgrading from manual preparation. Go-to-market angle emphasizes per-batch processing fees with tax-advantaged leasing structures rather than traditional capital sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automation-integrated equipment fabricators extending control systems from mixing through downstream portioning, creating predictable subscription income streams that outperform transactional capital sales. Long-term viability over the five-to-ten year horizon favors targets with established IoT-enabled predictive maintenance platforms and cloud analytics integration. Acquisition target archetype: mid-cap specialists with CE marking eligibility and existing United States distribution footprint. Signal to watch: FSSAI enforcement intensity in India crossing thresholds that accelerate organized retail bakery automation adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Reduces German and Japanese supply concentration exposure for gearbox and servo motor sourcing. |
| IoT-Enabled Predictive Maintenance Platform Launch | Converts transactional capital sales into recurring subscription revenue with vibration sensor analytics. |
| CE Marking and FDA Dual Certification Investment | Unlocks specification authority in United States industrial bakeries and EU export markets simultaneously. |
| Equipment-as-a-Service Financing Model Expansion | Transfers obsolescence risk from operators to vendors through per-batch processing fee structures. |
| Regional Aftermarket Service Network Acquisition | Captures installed base maintenance revenue and defends against IoT-native competitive entrants. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads at commercial bakeries and equipment fabricators; and secondary validation through customs and trade data, SEC 10-K filings, NSF/ANSI certification databases, and EU Machinery Directive CE marking registries. Bottom-up triangulation across equipment shipment records and top-down reconciliation against capital expenditure disclosures at large-scale United States biscuit and cake producers ensured cross-verification of market sizing assumptions.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation across product type, capacity tier, technology generation, and end-use intensity, with additional dimensioning by regional regulatory cluster and automation adoption phase. CAGRs were derived from regression analysis of historical replacement cycle compression and labor cost escalation patterns, incorporating stainless steel price volatility indices and energy-efficiency benchmarking trajectories under EU Green Deal specifications as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement intensity, stable stainless steel input pricing, and continued commercial bakery labor availability would require recalibration. Forecasts reflect documented assumptions regarding equipment-as-a-service financing penetration rates and IoT platform adoption curves. Revision becomes warranted when FSSAI modernization enforcement in India or EU Machinery Directive safety interlock mandate expansion crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Mooncake Production Line Market
Food Processing Equipment
Smart Bread Machine Market
Food Processing Equipment
Cider Brewing Equipment Market
Food Processing Equipment
Shawarma Grill Machine Market
Food Processing Equipment
Granular Ice Machine Market
Food Processing Equipment
Automatic Deboner Market
Food Processing Equipment
Tea Processing Machine Market
Food Processing Equipment
Freeze Thaw Chambers Market
Food Processing Equipment
Middle East and Africa Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Food Extrusion Market
Food Processing Equipment
Water Pod Soluble Machines Market
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
Milk Sterilizer Machine Market
Food Processing Equipment
Industrial Planetary Mixers Market
Food Processing Equipment
Deep Fryer Oil Filtration Market
Food Processing Equipment
Wine Processing Equipment Market