
 Flake Ice Machines Market | 2026-2036
Flake Ice Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Flake Ice Machines Market Foresight
Remote monitoring and predictive maintenance subscriptions is restructuring how flake ice machine vendors capture lifetime value from commercial buyers. Hoshizaki Corporation leverages its Japanese manufacturing base to sustain premium positioning in precision ice production systems. Scotsman Ice Systems anchors North American distribution through extensive dealer and foodservice channel control. Focusun competes aggressively on cost-engineered units for emerging-market cold chain infrastructure.
Flake ice machines produce thin, irregular ice fragments through a rotating cylindrical evaporator drum, typically operating at evaporating temperatures between minus 20°C and minus 25°C to achieve rapid surface cooling and maximum contact area for industrial applications. Air-cooled systems dominate installed base economics where water scarcity or discharge restrictions elevate operating costs, while water-cooled configurations retain share in coastal seafood processing plants with abundant seawater access. Solar-powered units represent the fastest-growing product category as off-grid aquaculture operations and remote concrete batching sites seek to eliminate diesel generator dependence. Application demand concentrates in seafood processing and concrete cooling, where flake ice's moldable, low-temperature properties deliver irreplaceable functional performance.
EPA SNAP program restrictions on high-GWP hydrofluorocarbons are forcing refrigerant transitions across US-manufactured equipment, while REACH compliance in Europe governs material safety in evaporator coatings and contact surfaces. ISO 22000 and HACCP frameworks shape hygiene design requirements for food-contact ice production systems in regulated export markets. Buyers must weigh total refrigerant transition costs against emerging natural refrigerant platforms when evaluating replacement cycles.
Market Dynamics
Refrigerant transition mandates across multiple jurisdictions are forcing simultaneous redesign of compressor architectures and evaporator materials, compressing product development cycles while expanding compliance costs for manufacturers serving regulated export markets.
Growth Catalysts
- EU F-Gas Regulation Phase-Down:Mandatory hydrofluorocarbon quotas are accelerating adoption of ammonia and CO₂-based systems in European seafood processing facilities.
- Southeast Asian Aquaculture Expansion:Vietnam's Mekong Delta and Thailand's industrial seafood zones are scaling flake ice infrastructure for post-harvest cold chain preservation.
- Solar Thermal Hybrid Systems:Off-grid concrete batching operations in remote mining corridors are eliminating diesel generator dependence through photovoltaic-integrated ice production.
Market Restraints
- Copper and Aluminum Price Volatility:Evaporator drum and heat exchanger fabrication costs fluctuate with London Metal Exchange commodity cycles, squeezing margin predictability for mid-scale equipment fabricators.
- Compressor Supply Concentration:Precision scroll and screw compressor manufacturing clusters in Germany and Japan create single-source vulnerability for non-integrated machine builders.
- Water Scarcity Constraints:Water-cooled system deployment faces permitting restrictions in drought-prone agricultural regions of Spain, Australia, and California.
Strategic Opportunities
- Remote Monitoring Subscriptions:Predictive maintenance platforms are capturing lifetime value from commercial buyers through recurring revenue streams attached to precision ice production systems.
- India's Cold Chain Infrastructure Gap:The country's PLI scheme for food processing is subsidizing flake ice adoption in dairy and horticulture corridors lacking mechanical refrigeration.
- Natural Refrigerant Convergence:Transcritical CO₂ and ammonia absorption technologies are opening retrofit pathways for installed base equipment facing refrigerant obsolescence.
Industry Challenges
- Refrigerant Handling Certification Bottlenecks:Technician shortages for ammonia and CO₂ system servicing are extending installation timelines and inflating field service costs.
- ISO 22000 Compliance Complexity:Food-contact ice production systems require documented HACCP protocols and third-party audits that strain smaller regional fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flake Ice Machines Market |
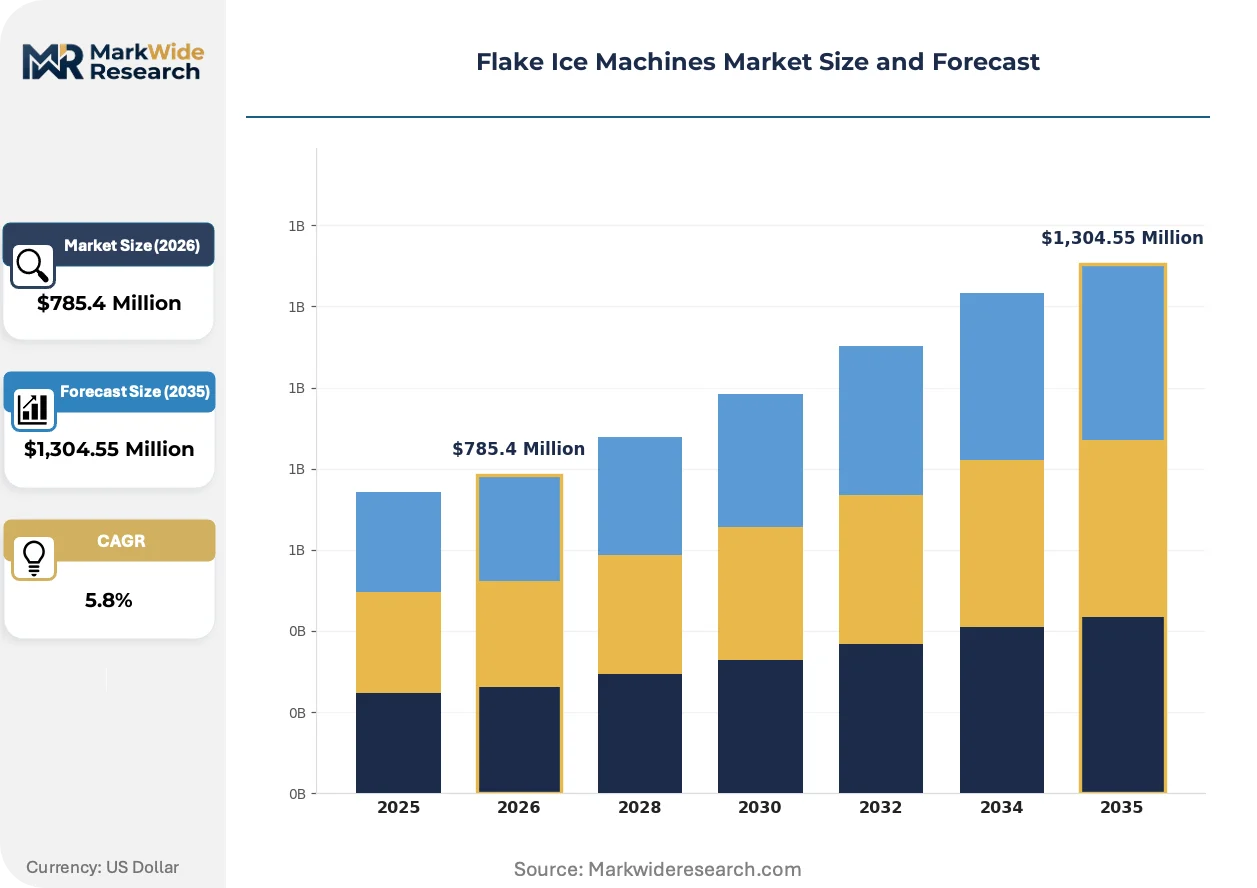
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,304.55 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Hybrid-Cooled, Solar-Powered Application: Seafood Processing, Concrete Cooling, Chemical Preservation, Food Display End User: Cold Storage Facilities, Construction Firms, Aquaculture Farms, Catering Services Distribution Channel: Direct Sales, Retail Outlets, Online Platforms, Wholesale Distributors |
| Companies Covered | Hoshizaki Corporation, Manitowoc Ice, Scotsman Ice Systems, Ice-O-Matic, Focusun, North Star, GEA, KTI, Grant Ice Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flake Ice Machines Market Shifts & Advancements
Equipment architecture is fragmenting into configurable subsystems that allow buyers to scale capacity without full replacement, while refrigerant chemistry and digital service layers undergo parallel transformation.
Evaporator drum design is modularizing around standardized cylindrical segments with quick-release mounting interfaces. Concrete cooling contractors in Australian mining belts and Japanese fishing cooperatives are specifying field-expandable units that add capacity through stacked drum arrays rather than parallel machine installation. This architecture compresses capital deployment timelines and reduces stranded asset risk for seasonal operations.
The EPA SNAP program is prohibiting high-GWP hydrofluorocarbons in new equipment manufacturing, forcing US-based producers to validate alternative refrigerants through accelerated life testing protocols. Seafood export facilities serving EU and Japanese markets face dual compliance burdens, with many converting to ammonia secondary loop systems that satisfy both EPA and F-Gas requirements.
Buyers are unbundling after-sales service from equipment procurement, negotiating predictive maintenance contracts separately from capital expenditure approvals. Large aquaculture operators in Norway and Chile are demanding uptime guarantees with penalty clauses, shifting operational risk onto OEM service organizations. This compression of the traditional bundled sales model is most visible in long-term fleet management agreements for offshore processing vessels.
Flake Ice Machines Market Segmentation
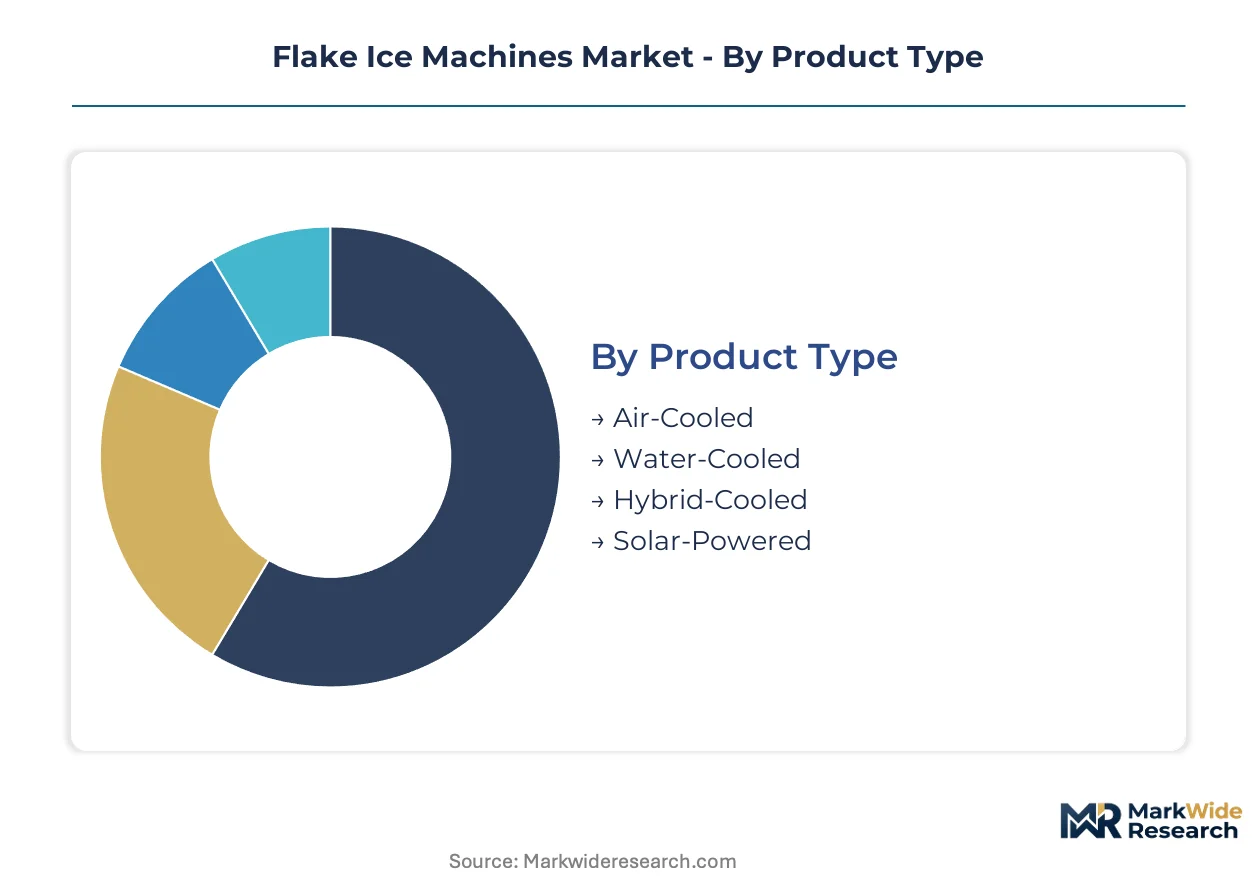
Equipment configuration in flake ice production hinges on site-specific constraints—water availability, energy access, and thermal load profiles—making segment-level specification critical for procurement decisions. Buyers evaluate total lifecycle economics across cooling architectures, end-use intensity, and service reliability requirements.
Product Type:
Capital deployment priorities diverge sharply based on ambient conditions and utility infrastructure at the installation site.
- Air-Cooled:These systems reject heat through forced convection across finned condenser coils, eliminating water discharge compliance burdens. Demand concentrates in drought-prone agricultural zones of Spain, Australia, and California where water-cooled permitting faces regulatory friction.
- Water-Cooled:Shell-and-tube or plate heat exchanger configurations leverage abundant seawater access in coastal seafood processing plants across Vietnam's Mekong Delta and Thailand's industrial seafood zones, delivering superior efficiency in high-ambient environments.
- Hybrid-Cooled:Dual-mode architectures switch between air and water rejection based on seasonal conditions or water availability alerts.
- Solar-Powered:Photovoltaic-integrated units with battery storage eliminate diesel generator dependence for off-grid aquaculture operations and remote concrete batching sites in Australian mining corridors.
Air-cooled systems lead on installed base scale; solar-powered configurations lead on expansion momentum.
Application:
Functional performance requirements dictate ice morphology specifications and production continuity demands.
- Seafood Processing:Rapid surface cooling and moldable packing properties make flake ice irreplaceable for post-harvest preservation. Vietnamese and Thai export facilities are scaling capacity to serve EU and Japanese regulatory compliance requirements under F-Gas and EPA SNAP frameworks.
- Concrete Cooling:Mass pour temperature control in remote mining and infrastructure projects drives demand for field-expandable, modular drum systems. Australian and Chilean contractors specify stacked evaporator arrays to compress capital deployment timelines for seasonal operations.
- Chemical Preservation:Controlled exothermic reaction management in pharmaceutical and specialty chemical synthesis requires precise ice dosing systems.
- Food Display:Visual merchandising applications in retail and catering prioritize ice clarity and structural integrity over cooling capacity.
Seafood processing commands the largest revenue footprint; concrete cooling exhibits the steepest expansion trajectory in mining corridor deployments.
End User:
Operational intensity and uptime risk tolerance shape equipment specification and service contract negotiation.
- Cold Storage Facilities:Centralized ice production serving multi-tenant distribution hubs demands redundancy configurations and predictive maintenance guarantees.
- Construction Firms:Mobile and semi-permanent installations for concrete cooling prioritize rapid deployment and diesel independence through solar hybrid options.
- Aquaculture Farms:Post-harvest preservation infrastructure in Vietnam's Mekong Delta clusters and Norwegian offshore processing vessels requires HACCP-compliant contact surfaces and documented ISO 22000 protocols.
- Catering Services:Smaller-scale, intermittent demand profiles favor compact air-cooled units with minimal installation complexity.
Aquaculture farms anchor volume concentration; construction firms are gaining share fastest through remote infrastructure projects.
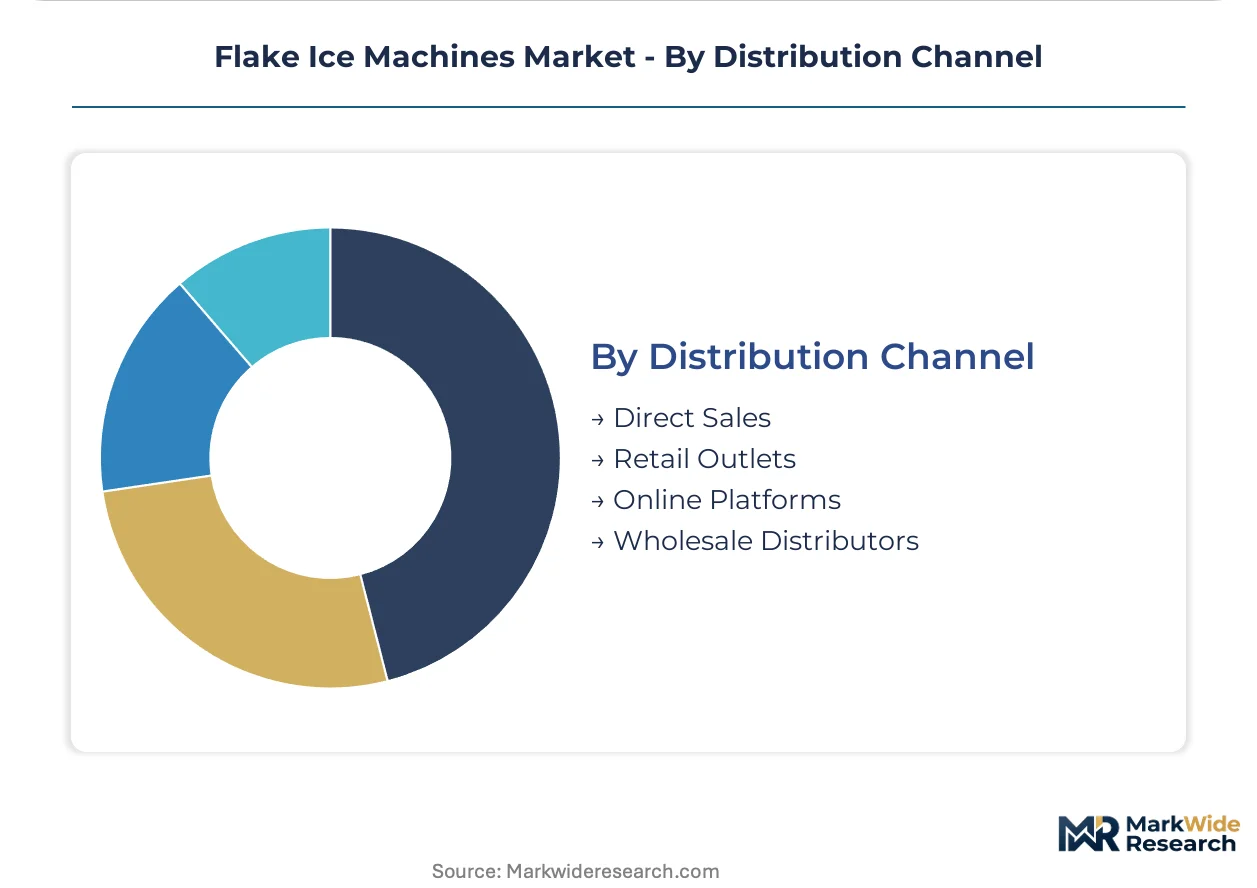
Distribution Channel:
Procurement modality reflects buyer sophistication, fleet scale, and geographic isolation from service networks.
- Direct Sales:Large fleet operators and offshore processing vessels negotiate uptime guarantees with penalty clauses, unbundling after-sales service from capital expenditure approvals.
- Retail Outlets:Smaller commercial buyers with immediate replacement needs source standardized units through dealer networks.
- Online Platforms:Specification-rich procurement for replacement parts and consumables is migrating to digital channels.
- Wholesale Distributors:Regional fabricators in emerging markets rely on distributor networks for compressor and evaporator component access.
Direct sales dominate premium segment value capture; wholesale distributors serve emerging market penetration most intensively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Mekong Delta aquaculture clusters deploy flake ice infrastructure at twice the intensity of Thailand's industrial seafood zones, though both face converging EU F-Gas compliance deadlines for export market access.
United States
Concrete cooling contractors in the Southwest and drought-prone Central Valley drive air-cooled system specification to avoid water discharge permitting. EPA SNAP program restrictions on high-GWP hydrofluorocarbons force refrigerant transitions in new equipment manufacturing. California's agricultural processing corridor leads installed base scale for food-contact ice production systems.
Germany
Precision engineering demand from pharmaceutical chemical synthesis applications sustains premium equipment specification. REACH compliance governs evaporator coating materials and food-contact surface safety. Bavaria's industrial machinery belt hosts compressor technology clusters serving ammonia and CO₂ system transitions.
Japan
Offshore processing vessels and coastal fishing cooperatives require HACCP-compliant flake ice systems for export market access. METI efficiency standards shape equipment energy performance benchmarks. Nagoya's port industrial zone concentrates seafood processing infrastructure modernization.
Australia
Remote mining corridors and off-grid concrete batching operations accelerate solar-powered unit deployment to eliminate diesel generator dependence. Water scarcity constraints in agricultural regions elevate air-cooled system economics. Western Australia's Pilbara mining belt leads field-expandable modular drum adoption.
India
Dairy and horticulture cold chain gaps under the PLI scheme for food processing subsidize flake ice adoption in mechanical refrigeration-deficient corridors. BIS standards govern equipment safety and performance certification. Gujarat's dairy processing clusters and Maharashtra's horticulture export zones anchor demand concentration.
Flake Ice Machines Market Competitive Landscape
Top-tier vendors anchor premium precision segments, while cost-engineered specialists compete on emerging-market penetration. The vendor base spans Japanese precision manufacturers, North American distribution-heavy incumbents, and Chinese fabricators targeting infrastructure gaps. Three archetypes dominate: technology licensors with refrigerant transition expertise, vertically integrated compressor producers, and regional assemblers leveraging distributor networks. Competitive moves concentrate on predictive maintenance service unbundling and natural refrigerant platform development.
Among Japanese precision manufacturers, Hoshizaki Corporation exemplifies the premium-tier archetype through its manufacturing base positioning. Scotsman Ice Systems anchors North American distribution control through extensive dealer and foodservice channel presence. Focusun occupies the cost-engineered tier for emerging-market cold chain infrastructure, competing aggressively on unit economics for aquaculture and concrete cooling applications.
| Leading Market Players |
|---|
| Hoshizaki Corporation |
| Manitowoc Ice |
| Scotsman Ice Systems |
| Ice-O-Matic |
| Focusun |
| North Star |
| GEA |
| KTI |
| Grant Ice Systems |
| Others |
Supply & Pricing Matrix
Large aquaculture operators in Norway and Chile command pricing leverage through fleet-scale procurement and uptime guarantee negotiations, compressing margins for mid-tier fabricators while premium-tier vendors capture value through predictive maintenance unbundling.
Pricing Analysis
Capacity additions in China's cost-engineered tier are reshaping price floors for standard flake ice units across emerging-market cold chain infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates Hoshizaki's precision systems from regional assemblers and Focusun's utility-grade offerings. Price differentiation hinges on refrigerant platform certification and after-sales service bundling. Cost compression in the economy tier is intensifying because copper and aluminum commodity volatility squeezes evaporator drum fabricators. Small-scale catering services exhibit highest price sensitivity; offshore processing vessels demonstrate lowest sensitivity due to uptime penalty clauses.
Supply Chain Analysis
Precision scroll and screw compressor manufacturing rests on German and Japanese production clusters, creating single-source vulnerability for non-integrated machine builders. Evaporator drum fabrication draws from copper and aluminum supply chains anchored in China, Chile, and Australia. Heat exchanger plate stamping and cylindrical drum welding represent critical component dependencies. Supply chain risk centers on London Metal Exchange commodity price volatility for evaporator materials. Distribution runs through extensive dealer networks in North America and direct sales channels for premium fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural refrigerant platform transitions and predictive maintenance service unbundling are expanding premium-tier margin capture, while copper price hedging and modular drum standardization drive cost-down opportunities in volume segments.
For Market Incumbents: To counter refrigerant handling certification bottlenecks for ammonia and CO₂ systems, Hoshizaki and Scotsman should deepen technician training partnerships with vocational institutes in Vietnam and Thailand. Backward integration into compressor technology through Bavarian and Nagoya engineering clusters secures supply continuity during F-Gas transition waves. Channel control investments in Mekong Delta service depots defend installed base retention against cost-engineered entrants. For New Entrants and Emerging Players: Wholesale distributors in India's PLI-subsidized dairy corridors represent the most accessible channel partner type for penetrating mechanical refrigeration-deficient markets. White-space targets include Gujarat's cooperative dairy clusters and Maharashtra's horticulture export zones lacking flake ice infrastructure. Field-expandable modular drum architectures for seasonal concrete cooling contractors in Australian mining belts offer a differentiated go-to-market angle against fixed-capacity incumbents. For Investors and Strategic Acquirers: Cold chain infrastructure funds are the most active acquirer in this space, consolidating regional fabricators to capture India's PLI-driven expansion. Long-term viability favors vendors with proven natural refrigerant platforms and recurring revenue from remote monitoring subscriptions. Acquisition targets should demonstrate ISO 22000 compliance capabilities and established technician certification programs. The signal to watch is EPA SNAP enforcement acceleration triggering replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Platform Transition | Ammonia and CO₂ system validation satisfies EU F-Gas and EPA SNAP dual compliance requirements. |
| Predictive Maintenance Subscription Launch | Recurring revenue capture from Norwegian and Chilean aquaculture fleet operators compresses customer acquisition costs. |
| Modular Drum Capacity Expansion | Field-expandable evaporator arrays reduce stranded asset risk for seasonal Australian mining contractors. |
| Technician Certification Program Investment | Ammonia and CO₂ servicing capability alleviates installation timeline bottlenecks in Southeast Asian seafood zones. |
| Solar Thermal Hybrid Integration | Photovoltaic-integrated units eliminate diesel dependence for remote concrete batching in Pilbara mining corridors. |
Research Methodology
Direct dialogue with plant engineers at Vietnamese seafood processing facilities, maintenance directors at Australian mining operations, OEM procurement teams, and aftermarket service heads grounded qualitative assessments in operational reality. Secondary validation drew from SEC filings of listed refrigeration equipment manufacturers, customs and trade data for compressor and evaporator component flows, EU F-Gas Regulation implementation reports, and EPA SNAP program dockets. Bottom-up equipment shipment tallies and top-down cold chain infrastructure investment tracking were triangulated to constrain estimate variance.
Segment-level value and volume trajectories across the projection horizon reflect discrete modeling of air-cooled, water-cooled, and solar-powered configurations by application intensity in seafood processing, concrete cooling, and chemical preservation. CAGRs were derived from installed base turnover rates, refrigerant transition compliance deadlines, and PLI scheme subsidy disbursement pacing. Industry-specific forecast inputs include London Metal Exchange copper price scenarios and F-Gas quota phase-down trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to refrigerant transition technology adoption curves and Southeast Asian aquaculture export demand volatility. Forecasts reflect documented assumptions regarding technician certification pipeline expansion and solar hybrid cost parity achievement. A small set of named triggers warrants ongoing watch: EPA SNAP enforcement acceleration, EU F-Gas quota auction price spikes, and India's PLI scheme revision cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Fermenters Market
Food Processing Equipment
Food Ultrasound Market
Food Processing Equipment
Cider Brewing Equipment Market
Food Processing Equipment
Food Disinfection Equipment Market
Food Processing Equipment
Brining Systems Market
Food Processing Equipment
Commercial Oven Market
Food Processing Equipment
Commercial Oven for Bakery Market
Food Processing Equipment
Alternative Protein Processing Equipment Market
Food Processing Equipment
Brewing Equipment Market
Food Processing Equipment
Pet Food Extrusion Market
Food Processing Equipment
Food Industry Pulsed Electric Field (PEF) Systems Market
Food Processing Equipment
Freeze-Drying Market
Food Processing Equipment
Defrosting & Thawing Equipment for Food Market
Food Processing Equipment
Pet Food Processing Market
Food Processing Equipment
Cookie Dropper Machine Market
Food Processing Equipment
Commercial Kettles and Braising Pans Market