
 Hand Blender Market | 2026-2036
Hand Blender Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Blender Market Outlook
Asset-light leasing models for commercial kitchen equipment is narrowing the competitive field for premium hand blender manufacturers. Ninja leverages direct-to-consumer channel control to sustain margin capture outside traditional retail. Hamilton Beach competes on manufacturing scale, anchoring volume supply across North American foodservice distributors. Braun extends its position through in-house motor production, differentiating on durability benchmarks for professional users.
A hand blender is a motorized kitchen appliance comprising an elongated shaft with rotating blades at its terminus, typically operating between 200W and 1000W to puree, emulsify, or whip ingredients directly within containers. Cordless variants with detachable wands now command the fastest expansion as lithium-ion power density improves and commercial users prioritize maneuverability over tethered operation. The home user segment remains the largest volume pool, though professional chef and restaurant applications generate disproportionate margin contribution due to replacement frequency and specification requirements. Turbo mode and variable speed settings concentrate feature differentiation at the premium tier, while easy-clean designs penetrate mid-market positioning.
CE marking under EU safety directives and FDA compliance for food-contact materials shape product design and market access requirements across major jurisdictions. Ecodesign regulations in Europe and DOE efficiency standards in the United States progressively constrain motor specifications, compelling manufacturers to redesign power systems. Stakeholders must monitor battery chemistry regulations and emerging right-to-repair mandates, as these frameworks will determine which product architectures sustain market presence.
Market Dynamics
Cordless lithium-ion battery systems are compressing the addressable market for wired hand blenders as commercial kitchens prioritize maneuverability over tethered power reliability.
Growth Catalysts
- EU Ecodesign mandates:Efficiency standards under the EU Green Deal are compelling motor redesigns that favor brushless DC architectures, creating upgrade cycles across European foodservice operations.
- Restaurant kitchen densification:Space-constrained commercial layouts in urban centers are driving specification shifts toward compact, multi-function equipment that reduces countertop footprint.
- Lithium-ion energy density gains:Improved battery chemistry is extending runtime-to-weight ratios, enabling cordless units to match corded performance thresholds for sustained commercial use.
Market Restraints
- Critical mineral supply concentration:Cobalt and lithium processing capacity concentrates in limited jurisdictions, exposing manufacturers to input cost volatility and supply disruption risks.
- Right-to-repair compliance friction:Emerging EU and US state-level repairability mandates are forcing architectural redesigns that increase unit costs and complicate sealed motor housings.
- Immersion circulator substitution:Sous-vide equipment is capturing some emulsification tasks in high-end restaurant settings, narrowing the task envelope for premium hand blenders.
Strategic Opportunities
- Indian foodservice modernization:The country's PLI scheme for appliance manufacturing is reducing import duties on components, creating localized assembly opportunities for mid-tier brands.
- Cloud kitchen equipment-as-a-service:Rental and subscription models for commercial kitchen equipment are opening channel access without traditional distributor margin stacking.
- Cross-appliance battery platforms:Shared battery ecosystems across hand blenders, stick vacuums, and power tools are enabling ecosystem lock-in strategies and reducing customer acquisition costs.
Industry Challenges
- Motor-winding automation talent scarcity:Precision manufacturing of compact high-RPM motors requires specialized technicians that command premium wages in established manufacturing clusters.
- FDA food-contact certification timelines:Material approvals for new polymer formulations in blade housings and seals extend product development cycles by 12-18 months.
- Legacy distributor integration complexity:Established foodservice supply chains resist direct-to-commercial relationships, forcing parallel channel investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Blender Market |
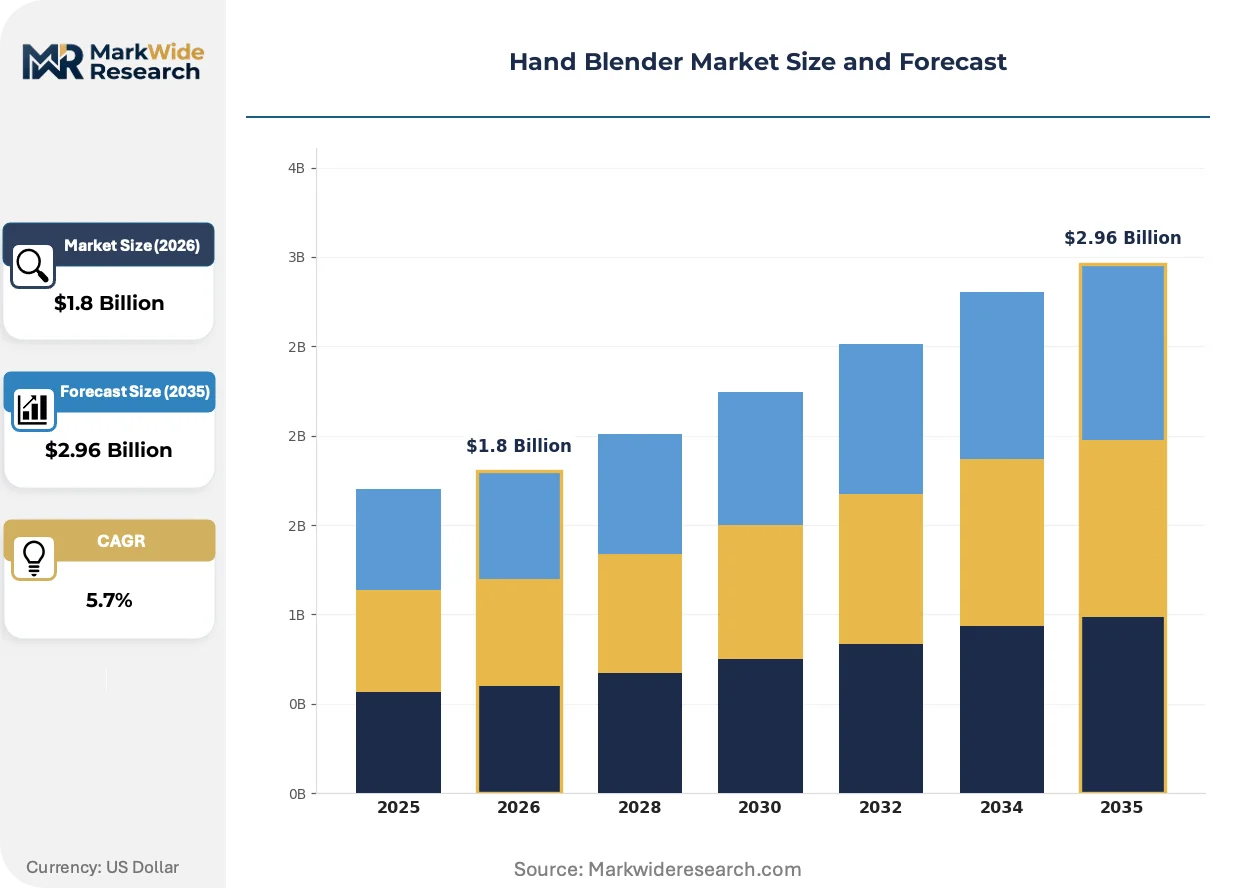
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Cordless, Immersion, Countertop Power Rating: 200W, 300W, 500W, 1000W Features: Turbo Mode, Speed Settings, Detachable Wand, Easy Clean End User: Home Users, Professional Chefs, Restaurants, Catering Services |
| Companies Covered | Ninja, MuellerLiving, Vitamix, Hamilton Beach, All-Clad, Braun, KitchenAid, Bosch, Cuisinart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Blender Market Strategic Shifts
Battery chemistry improvements and regulatory pressure on motor efficiency are converging to reshape product architectures and procurement patterns across foodservice and residential segments.
Brushless DC motor technology is rendering obsolete traditional brushed motor designs in premium hand blender segments. Professional kitchen operators in Germany and France are specifying brushless units for 3,000+ hour operational lifespans. The shift is compressing warranty cost structures and enabling sealed-unit designs that withstand commercial dishwasher cycles.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of non-stick blade coatings and gasket materials. Manufacturers are accelerating ceramic and silicone-alternative testing programs to maintain EU market access. The transition imposes material cost premiums that concentrate in mid-market product tiers where price elasticity remains acute.
Equipment leasing through foodservice procurement platforms is displacing outright purchase for multi-unit restaurant operators. Third-party managed service providers are bundling hand blenders into comprehensive kitchen packages with maintenance and replacement guarantees. The model is most visible in US urban markets where capital-light expansion strategies dominate multi-location rollout planning.
Hand Blender Market Segmentation
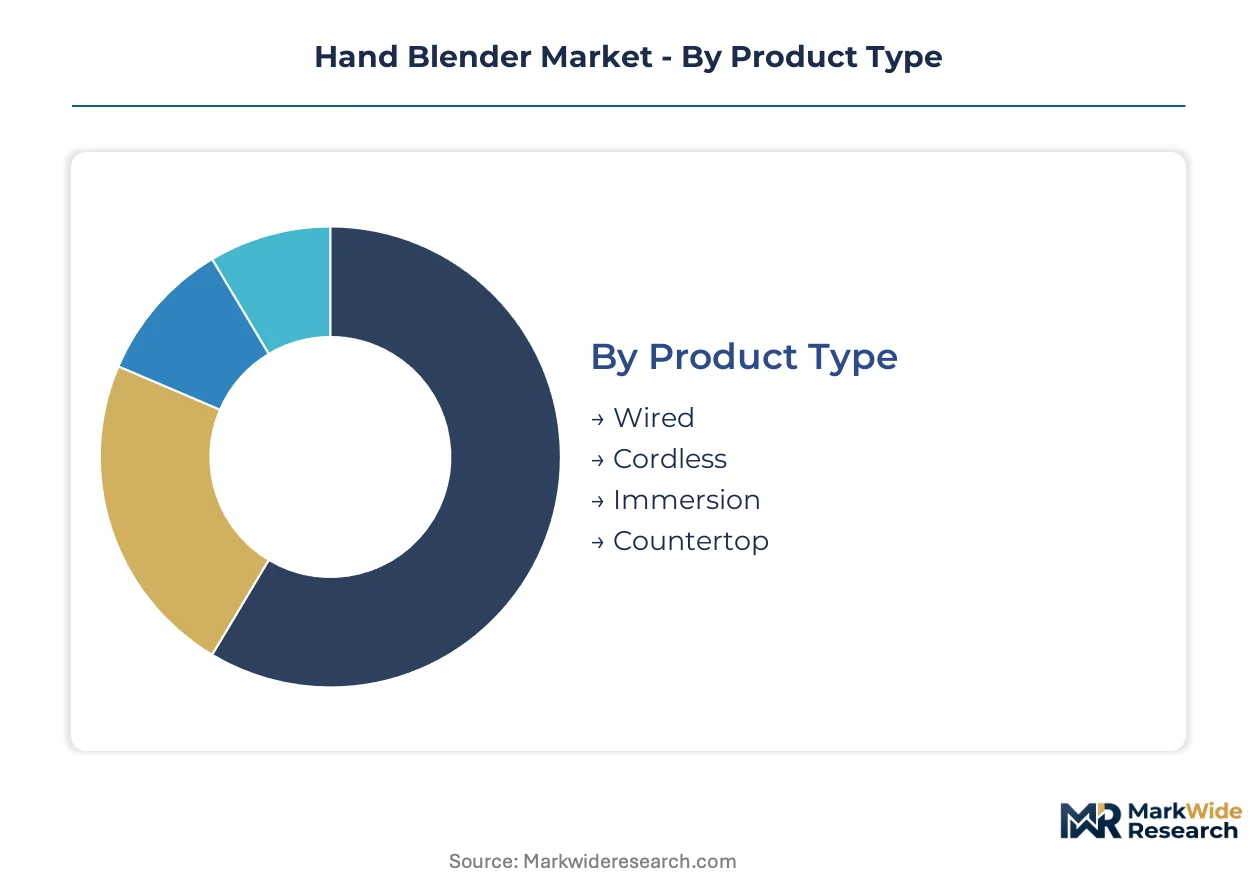
Hand blender procurement patterns diverge sharply across user contexts, with commercial kitchens prioritizing runtime durability and residential buyers emphasizing storage economy. Segment boundaries are blurring as lithium-ion power density improvements enable cordless units to penetrate professional workflows previously reserved for corded equipment.
Product Type:
Mature wired configurations still anchor volume production, though cordless architectures are accelerating fastest as battery chemistry advances.
- Wired:Continuous power delivery suits high-throughput commercial stations where outlet density eliminates mobility constraints. German foodservice distributors specify wired units for fixed prep stations in institutional catering operations. Wired retains volume leadership; cordless holds the steepest expansion curve.
- Cordless:Lithium-ion battery systems now sustain 45-minute runtime thresholds at 500W+ output, matching corded performance for intermittent blending tasks. North American cloud kitchen operators prioritize cordless maneuverability in compact ghost kitchen layouts where outlet positioning limits workflow efficiency.
- Immersion:Shaft-integrated designs dominate sous-vide and sauce preparation in French and Italian restaurant training programs, where direct-container operation reduces transfer waste.
- Countertop:Stationary base configurations with detachable wands serve hybrid users seeking blender versatility without dedicated appliance redundancy.
Wired configurations retain volume leadership; cordless architectures hold the steepest expansion curve.
Power Rating:
Cost tier stratification concentrates manufacturing investment at mid-wattage nodes where motor efficiency regulations intersect with consumer price elasticity.
- 200W:Entry-tier motors serve occasional residential pureeing with minimal thermal load tolerance. Indian urban households favor 200W units for spice grinding and chutney preparation where intermittent duty cycles suffice.
- 300W:The commercial sweet spot balances runtime thermal management against capital cost constraints for independent restaurant operators.
- 500W:Brushless DC architectures at this threshold achieve commercial dishwasher compatibility and 3,000-hour service intervals specified by German catering procurement standards. 500W cordless units are gaining share fastest in European foodservice leasing portfolios.
- 1000W:Premium torque output supports nut butter processing and frozen ingredient breakdown in professional pastry applications. Japanese commercial bakery chains specify 1000W immersion units for matcha and bean paste emulsification where particle consistency determines product grade.
300W-500W brackets dominate unit economics; 1000W commands the premium margin pool.
Features:
Application-specific feature bundling separates residential convenience positioning from professional durability specifications.
- Turbo Mode:Burst power delivery clears blade jamming in fibrous vegetable processing. Turbo-equipped units carry price premiums in UK and Australian markets where root vegetable soup preparation drives seasonal demand spikes.
- Speed Settings:Variable RPM control enables graduated emulsification for mayonnaise and vinaigrette stability. French culinary schools specify multi-speed units for sauce curriculum standardization.
- Detachable Wand:Shaft separation simplifies commercial dishwasher loading and cross-contamination protocol compliance. Detachable configurations are expanding most quickly in US hospital and aged-care foodservice contracts.
- Easy Clean:Seamless shaft housings without crevices or screw joints reduce bacterial harborage risk. Easy-clean designs penetrate mid-market residential positioning where maintenance convenience influences repurchase intent.
Detachable wands lead professional specification; easy-clean drives residential conversion.
End User:
Customer type determines replacement frequency, warranty cost exposure, and channel access strategy across divergent procurement workflows.
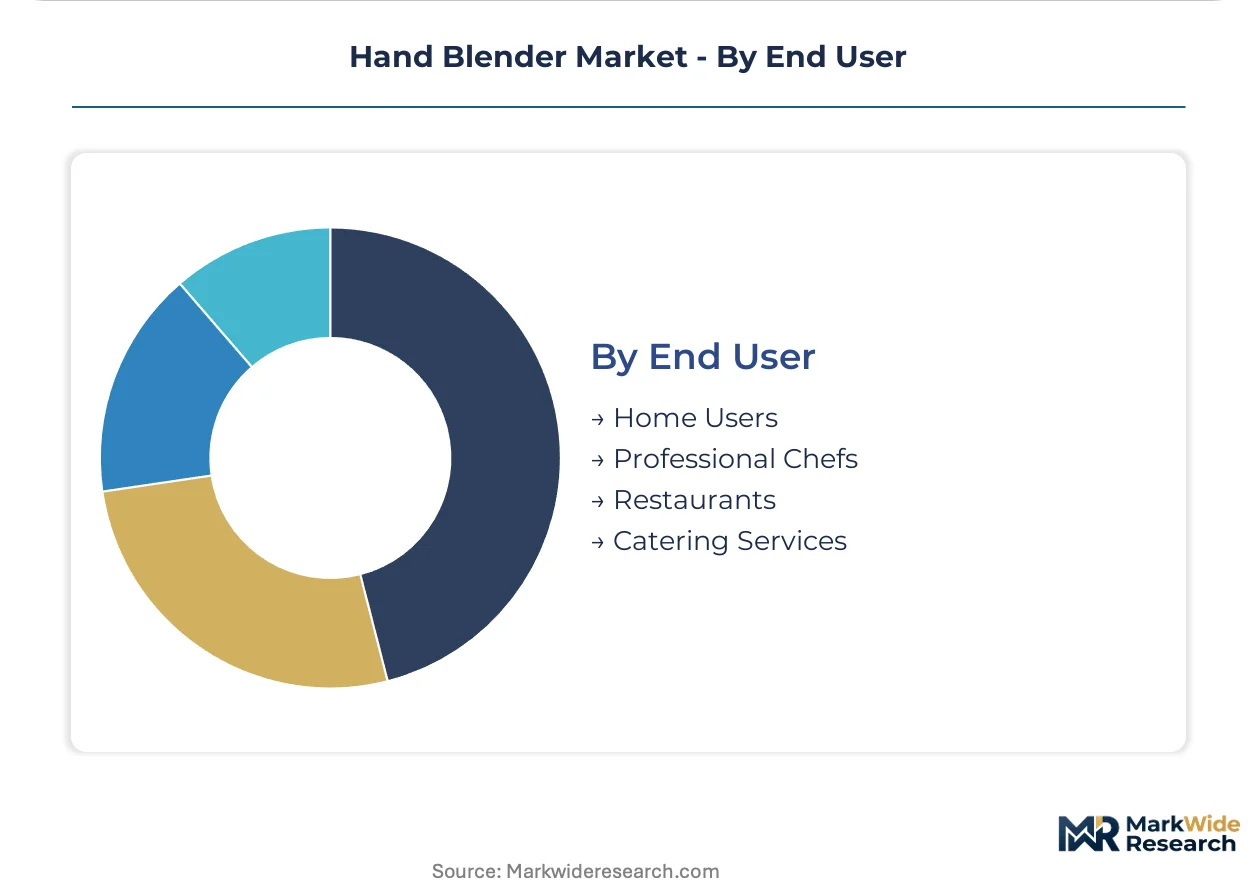
- Home Users:Residential volume concentrates in 200W-300W cordless segments where countertop storage constraints and intermittent usage patterns dominate purchase criteria. German and Japanese households show elevated attachment rates for accessory bundles including whisk and chopper attachments.
- Professional Chefs:Individual practitioners prioritize motor longevity and repairability over initial acquisition cost. Right-to-repair compliance is reshaping chef purchasing criteria in EU jurisdictions with emerging repairability mandates.
- Restaurants:Multi-unit operators are shifting toward equipment-as-a-service models that bundle maintenance and replacement guarantees. US urban restaurant groups favor leasing platforms that convert capital expenditure to operational flexibility.
- Catering Services:Mobile food preparation demands battery redundancy and rapid swap protocols. Catering represents the fastest-growing end-user category as event-based foodservice expands and commercial kitchens prioritize space-efficient equipment portfolios.
Home users anchor absolute volume; catering services command the steepest growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium cordless units in Germany command pricing multiples above comparable products in India, reflecting divergent regulatory compliance burdens and battery chemistry sourcing costs across manufacturing clusters.
Germany
Bosch and Braun anchor manufacturing clusters in Baden-Württemberg with strong export orientation toward EU foodservice markets. EU Ecodesign mandates under the Green Deal compel brushless DC motor adoption, accelerating upgrade cycles across commercial kitchens. Stuttgart-based engineering centers concentrate motor-winding automation expertise that commands premium wages.
United States
Cloud kitchen operators in urban centers prioritize cordless maneuverability where outlet positioning limits workflow efficiency. FDA food-contact certification timelines for new polymer formulations extend product development cycles by 12-18 months. Chicago and Dallas foodservice distributors specify wired units for fixed prep stations in institutional catering operations.
India
Urban households favor 200W units for spice grinding and chutney preparation where intermittent duty cycles suffice. The PLI scheme for appliance manufacturing reduces import duties on components, creating localized assembly opportunities for mid-tier brands. Maharashtra and Gujarat host emerging assembly operations targeting domestic foodservice modernization.
Japan
Commercial bakery chains specify high-torque immersion units for matcha and bean paste emulsification where particle consistency determines product grade. METI efficiency standards constrain motor specifications, compelling power system redesigns. Osaka and Nagoya manufacturing clusters specialize in precision motor components for professional-grade equipment.
United Kingdom
Turbo-equipped units carry price premiums where root vegetable soup preparation drives seasonal demand spikes. Emerging right-to-repair mandates force architectural redesigns that increase unit costs for sealed motor housings. London procurement platforms bundle hand blenders into comprehensive kitchen packages with maintenance guarantees.
Hand Blender Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in motor and battery supply. The vendor base separates into consolidated premium brands with captive manufacturing and distributed mid-tier assemblers sourcing modular subsystems. Three archetypes dominate: engineering-led heritage manufacturers with in-house motor production, direct-to-consumer challengers controlling channel economics, and scale-driven volume suppliers anchoring foodservice distributor relationships. Competitive moves concentrate on cross-appliance battery ecosystem development and cloud kitchen equipment-as-a-service partnerships.
Within the heritage engineering tier, Braun and Bosch exemplify vertical control over motor production and durability benchmarking for professional users. Ninja occupies a direct-to-consumer position that sustains margin capture outside traditional retail margin stacking. Hamilton Beach represents scale-driven manufacturing anchoring volume supply across North American foodservice distributors.
| Leading Market Players |
|---|
| Ninja |
| MuellerLiving |
| Vitamix |
| Hamilton Beach |
| All-Clad |
| Braun |
| KitchenAid |
| Bosch |
| Cuisinart |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp freight corridors carry lithium-ion cells from Asian manufacturing hubs into European assembly plants, with container rates compressing margin structures for cordless hand blender producers while amplifying price spreads between premium brushless units and entry-tier wired alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the hand blender market. Price differentiation rests on motor architecture certification and volume procurement scale, with CE-marked brushless DC units commanding premiums over brushed motor alternatives. Pricing pressure stems from cobalt and lithium cost volatility in battery supply chains. Catering services and cloud kitchen operators show acute price sensitivity, while German institutional foodservice buyers prioritize durability specifications over unit cost.
Supply Chain Analysis
Contract manufacturing capacity for compact motor assemblies concentrates in Dongguan and Shenzhen facilities serving mid-tier brands, with premium heritage manufacturers retaining in-house production in Baden-Württemberg. Component sourcing draws from China for lithium-ion cells, Germany for precision motor windings, and Japan for ceramic blade coatings. Single-source vulnerability in cobalt processing from the DRC exposes manufacturers to input disruption. Distribution runs through foodservice equipment distributors in North America and specialized kitchen retail chains in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as lithium-ion power density gains splinter demand across cordless commercial, cordless residential, and legacy wired segments, each with distinct specification requirements and channel access patterns.
For Market Incumbents: Harden supply chain resilience through backward integration into brushless DC motor production and captive battery pack assembly. Lock in multi-year lithium supply offtakes before critical mineral processing capacity tightens further. Defend against immersion circulator substitution in high-end restaurant settings by emphasizing sauce emulsification speed and container versatility. For New Entrants and Emerging Players: Establish a beachhead in India's foodservice modernization wave by leveraging PLI scheme component duty reductions for localized assembly. Target Maharashtra and Gujarat cloud kitchen clusters with rental-model equipment partnerships. Lead with detachable-wand configurations that satisfy hospital and aged-care contract specifications in North America. For Investors and Strategic Acquirers: Component-specialist foundries with precision motor-winding automation capabilities represent the most defensible acquisition profile in a five-to-ten-year window. Battery chemistry platform players enabling cross-appliance ecosystems command structural optionality. Monitor EU right-to-repair mandate implementation timelines as inflection signals for sealed-unit versus repairable-design valuation spreads.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Appliance Battery Platform Development | Ecosystem lock-in across hand blenders, stick vacuums, and power tools reduces customer acquisition costs for Milwaukee and Ryobi parent TTI. |
| Cloud Kitchen Equipment-as-a-Service Launch | Subscription models convert capital expenditure to operational flexibility for US urban multi-unit restaurant groups. |
| Brushless DC Motor Architecture Transition | Sealed-unit designs withstand commercial dishwasher cycles and compress warranty cost structures for German catering procurement. |
| Localized Assembly Under India's PLI Scheme | Component duty reductions enable mid-tier brands to serve domestic foodservice modernization in Maharashtra and Gujarat. |
| Alternative Coating Material Certification | Ceramic and silicone alternatives to PFAS coatings maintain EU market access under REACH restrictions for Braun and Bosch portfolios. |
Study Parameters
A spread of perspectives from foodservice equipment procurement managers, commercial kitchen operators, motor manufacturing engineers, battery supply specialists, and retail category buyers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against customs trade records, EU Ecodesign directive filings, FDA food-contact material approvals, and foodservice distributor sales databases. Bottom-up unit shipment estimates triangulated against top-down value projections across product type, power rating, and end-user segmentation.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include cordless versus wired architecture, brushless versus brushed motor technology, residential versus commercial end-use, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, lithium-ion energy density improvement curves, and foodservice equipment leasing penetration rates. Industry-specific inputs incorporated cloud kitchen rollout timelines and EU right-to-repair mandate implementation schedules.
Stress conditions across cobalt price volatility, lithium processing capacity constraints, and foodservice capital expenditure contraction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding battery chemistry improvement trajectories and regulatory compliance timelines. Quarterly review of critical mineral spot prices, EU repairability mandate court rulings, and US cloud kitchen vacancy rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Global Non-Thermal Pasteurization Market
Food Processing Equipment
Contact and Convective Dryers Market
Food Processing Equipment
Global Food and Beverage Processing Equipment Market
Food Processing Equipment
Walk-In Refrigerator Market
Food Processing Equipment
Pasteuriser Market
Food Processing Equipment
Spray Drying Equipment Market
Food Processing Equipment
Tunnel Oven Market
Food Processing Equipment
Butcher Equipment Market
Food Processing Equipment
Global Carbonated Beverage Processing Equipment Market
Food Processing Equipment
Global Powder Processing Equipment Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Brewing Equipment Market
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
Countertop Food Blenders Market
Food Processing Equipment
Industrial Planetary Mixers Market