
 Argentina Gellan Gum Market | 2026-2036
Argentina Gellan Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Gellan Gum Market Insights
ANMAT's food additive registration cycle is reorganizing competitive access for imported hydrocolloids. CP Kelco leverages its global fermentation expertise to sustain supply continuity into Argentine ports. Hebei Xinhe Biochemical Co. Ltd. anchors its position through bulk powder specialization for South American distributors. Jungbunzlauer differentiates via dual-certification coverage spanning food and pharmaceutical grades.
Gellan gum is a high-molecular-weight extracellular polysaccharide produced by Sphingomonas elodea fermentation, composed of repeating tetrasaccharide units with glucuronic acid, rhamnose, and glucose in variable acyl substitution patterns that determine gel texture and thermal stability. High acyl gellan forms soft, elastic gels valued in dairy desserts and beverage suspensions, while low acyl gellan dominates pharmaceutical capsule and tablet binding applications where brittle, firm gel structures are required. The food and beverage end-user segment occupies the dominant margin pool given Argentina's concentrated dairy processing base, whereas pharmaceutical applications are expanding fastest as local generics manufacturers adopt gellan for controlled-release formulations.
ANMAT enforces food additive purity standards aligned with Mercosur resolutions, while the National Institute of Industrial Technology (INTI) certifies manufacturing process compliance for imported biopolymers. BIS-equivalent conformity assessments from supplier countries determine customs clearance speed at Buenos Aires port. Stakeholders must monitor Mercosur harmonization timelines and INTI audit schedules to preempt supply disruptions.
Market Dynamics
ANMAT's tightening additive disclosure requirements are reorganizing supplier qualification protocols across Argentina's Pampas food processing corridor. Formulators now face mandatory INTI process audits for imported hydrocolloids, compressing procurement timelines and elevating certified fermentation suppliers.
Growth Catalysts
- Clean-label dairy alternatives:Buenos Aires formulators are expanding gellan gum adoption in oat and almond milk suspensions to replace carrageenan and achieve ANMAT-compliant simplified ingredient panels.
- ANMAT Resolution 269/2022:Updated food additive purity standards under Mercosur alignment are disqualifying non-certified hydrocolloid imports, creating preferential access for INTI-audited suppliers.
- Controlled-release pharmaceuticals:Córdoba generics manufacturers are adopting low-acyl gellan for tablet binding applications, displacing traditional gelatin in moisture-sensitive formulations.
Market Restraints
- Fermentation feedstock volatility:Sucrose and glucose substrate costs fluctuate with Argentina's sugar harvest cycles, compressing margins for domestic toll manufacturers dependent on imported fermentation inputs.
- Port concentration risk:Buenos Aires handles over 80% of hydrocolloid imports, creating single-point vulnerability for Pampas dairy processors during customs clearance delays.
- Xanthan gum substitution:Cost-sensitive beverage formulators in Mendoza are reverting to xanthan for basic suspension applications where thermal stability requirements permit.
Strategic Opportunities
- Patagonia aquaculture nutrition:Experimental feed pellet applications using gellan as a water-stable binding matrix remain underpenetrated in Chubut and Santa Cruz salmon farming operations.
- Dual-certification positioning:Suppliers achieving simultaneous ANMAT food-grade and pharmaceutical-grade registrations can capture premium positioning in Córdoba's expanding generics cluster.
- Direct-procurement platforms:Large Pampas dairy cooperatives are piloting digital tender systems that disintermediate traditional distributor markups for bulk hydrocolloid volumes.
Industry Challenges
- Fermentation technologist scarcity:Argentina's biotechnology programs produce insufficient Sphingomonas cultivation specialists, forcing toll manufacturers to recruit from Brazil or import technical services.
- INTI audit timeline compression:Certification backlogs extending six to nine months are delaying new supplier market entry and freezing procurement decisions during peak formulation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Gellan Gum Market |
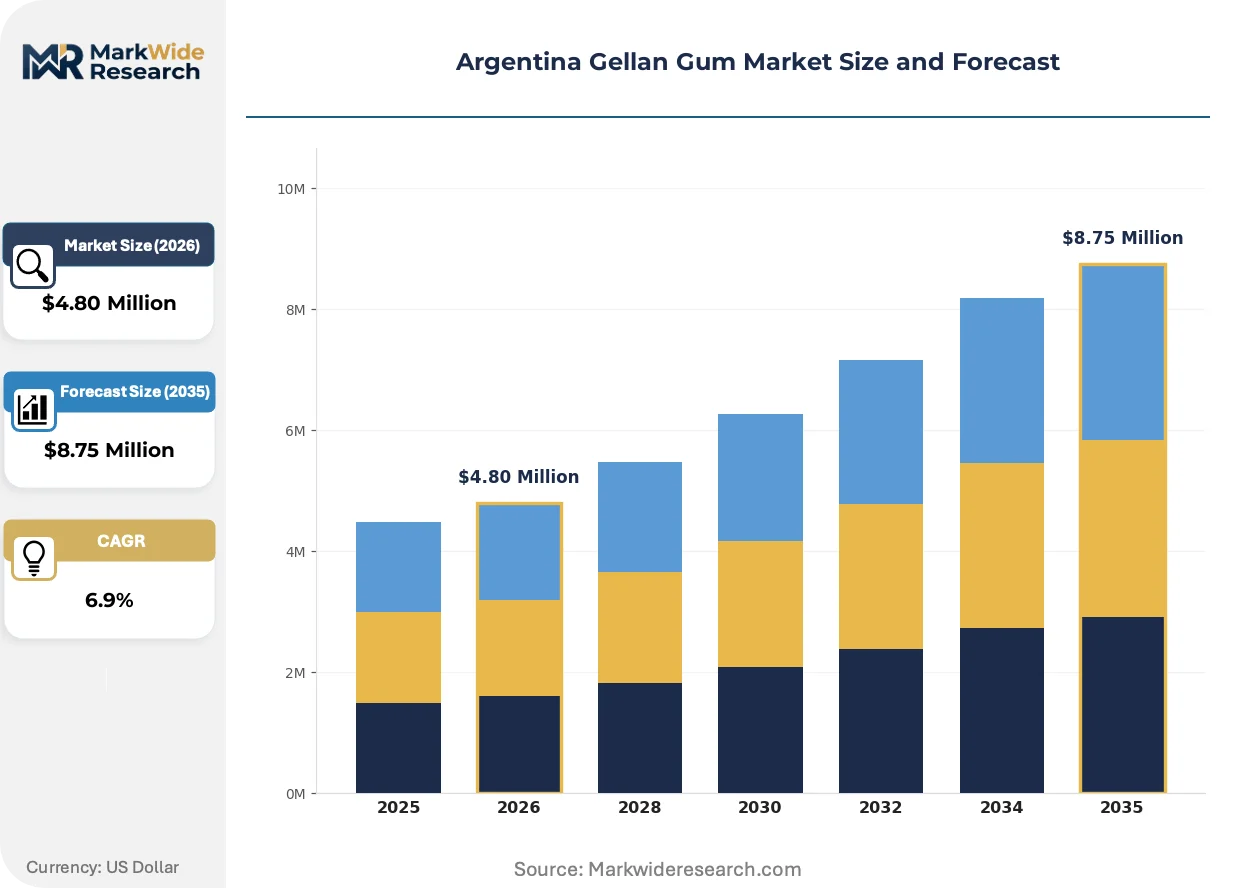
| Market Size in 2026 | $4.80 Million |
| Market Size in 2035 | $8.75 Million |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Acyl Gellan, Low Acyl Gellan, Powdered Gellan, Liquid Gellan End User: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals Application: Thickening Agent, Gelling Agent, Stabilizer, Emulsifier Distribution Channel: Direct Sales, Online Retail, Wholesale, B2B Supply |
| Companies Covered | Hebei Xinhe Biochemical Co. Ltd., Jungbunzlauer, CP Kelco, H & A Canada Inc., DSM, Dancheng Caixin Sugar Industry Co. Ltd., Fufeng Group, Zhengzhou Cinogel Biotech Co. Ltd., Zhejiang Tech-Way Biochemical Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Gellan Gum Market Trends and Innovations
Fermentation-derived hydrocolloid functionality is splitting along acyl-substitution gradients as formulators demand precision-tailored gel textures. Regulatory digitization and procurement platform evolution are simultaneously compressing supplier qualification cycles and expanding direct-access channels.
Gellan gum functionality is bifurcating along acyl-substitution patterns as Argentine formulators reject one-size-fits-all hydrocolloids. High-acyl variants now dominate dairy dessert applications in Buenos Aires where soft elastic textures are specified, while low-acyl grades capture pharmaceutical binding contracts in Córdoba requiring brittle firm gels. This technical segmentation is compressing commodity hydrocolloid margins and rewarding suppliers with dual-production fermentation capacity.
ANMAT's alignment with Mercosur Resolution GMC/RES No. 14/21 is mandating blockchain-traceable additive documentation for all imported hydrocolloids. Industrial consequence includes mandatory supplier QR-code integration into Argentine food labels, with non-compliant shipments detained at Buenos Aires port. Dairy processors in Santa Fe and Córdoba provinces are responding by pre-qualifying only INTI-audited fermentation facilities with existing Mercosur certification.
Buyer concentration among Pampas dairy cooperatives is consolidating procurement decisions into fewer technical sourcing committees. Traditional distributor networks serving Mendoza and Tucumán beverage formulators are losing volume to direct-manufacturer relationships where fermentation batch documentation can be customized. This channel compression is most visible in Santa Fe province where SanCor and Mastellone Hnos. have established captive hydrocolloid supply agreements with audited international fermentation specialists.
Argentina Gellan Gum Market Segmentation
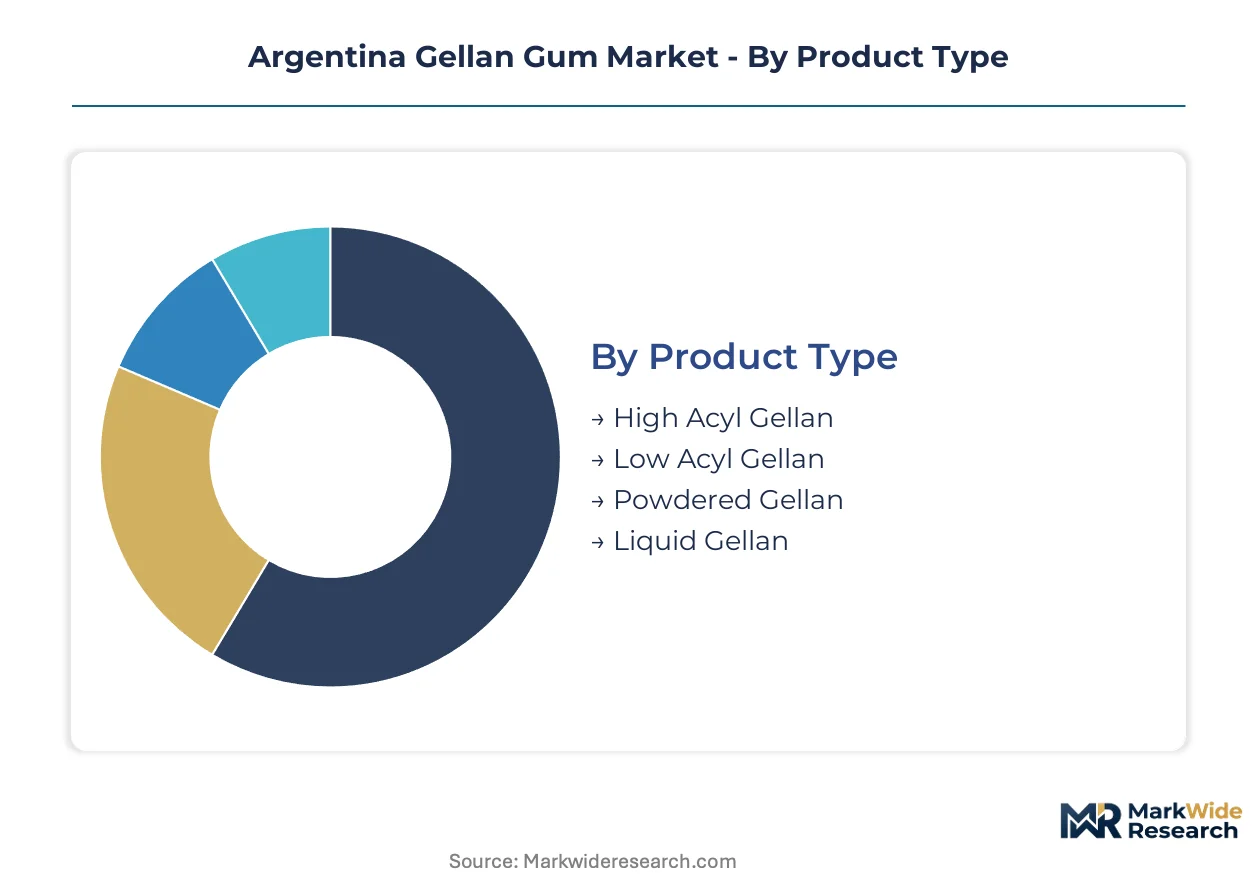
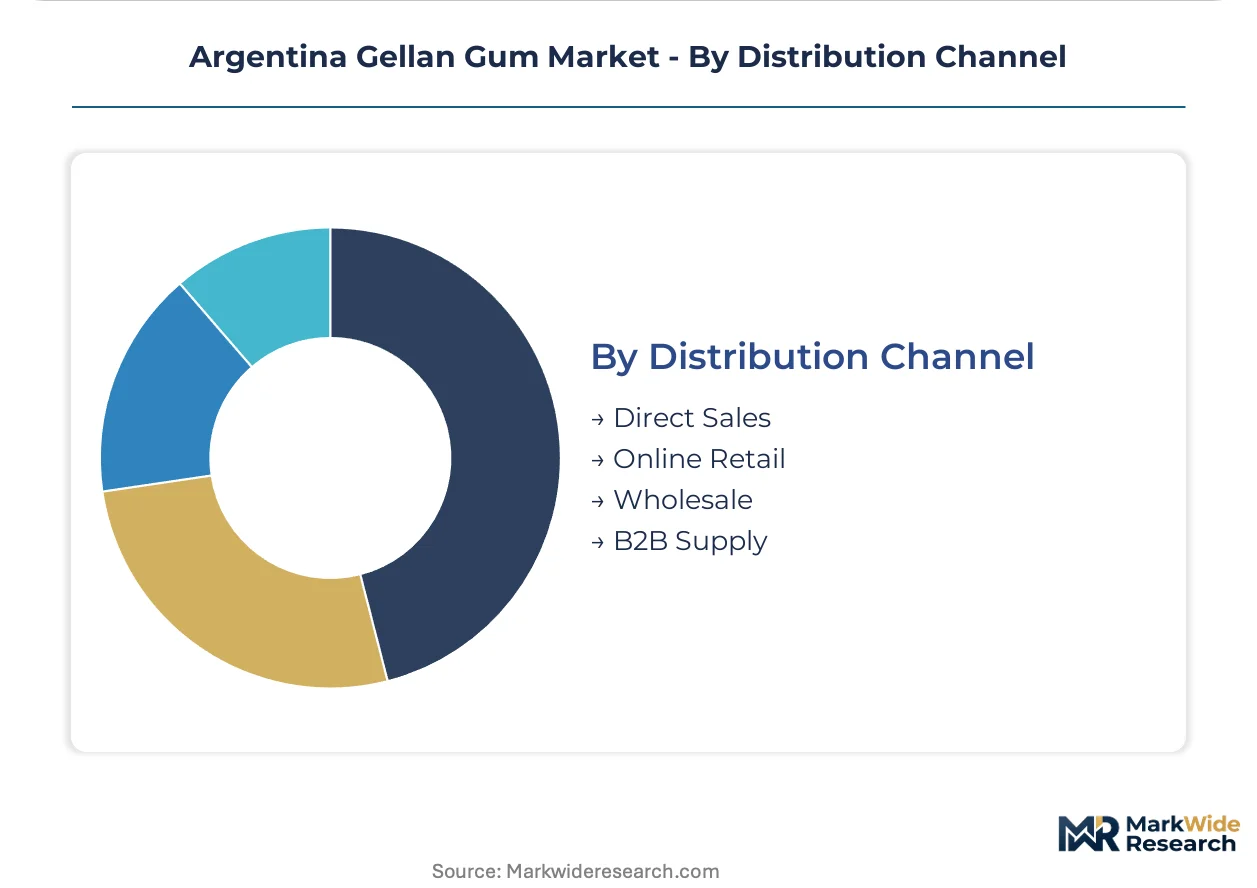
Gellan gum procurement in Argentina splits across technical specifications and regulatory pathways that determine supplier qualification intensity. Channel selection varies sharply by buyer scale, with Pampas dairy cooperatives bypassing traditional distribution while smaller Mendoza beverage formulators remain distributor-dependent.
Product Type:
Channel mix diverges by acyl content: high-acyl variants move through B2B supply agreements with audited fermentation specialists, while powdered grades dominate wholesale distributor networks serving smaller formulators.
- High Acyl Gellan:Tetrasaccharide units retain acetyl and glyceryl substituents, producing soft elastic gels with thermal reversibility. Buenos Aires dairy dessert formulators specify this grade for clean-label pudding and yogurt applications where carrageenan replacement is mandated by ANMAT disclosure rules.
- Low Acyl Gellan:Deacylated through alkaline treatment, yielding brittle firm gels with sharp thermal setting. Córdoba pharmaceutical manufacturers source this grade for controlled-release tablet matrices, displacing gelatin in moisture-sensitive generics formulations.
- Powdered Gellan:Standardized particle size distribution enables dry-blend compatibility with dairy protein powders. Bulk procurement concentrates in Santa Fe province through SanCor cooperative tender systems.
- Liquid Gellan:Pre-hydrated dispersions reduce processing time for beverage suspension applications. Mendoza wine and juice formulators access this grade through regional chemical distributors.
By volume, powdered gellan leads. By growth pace, low-acyl pharmaceutical grades are climbing the fastest.
End User:
Cost tier stratification separates commodity food applications from premium pharmaceutical certifications that command INTI audit premiums.
- Food & Beverage:Dominant margin pool concentrated in Pampas dairy processing corridor. Mastellone Hnos. and La Serenísima specify high-acyl gellan for plant-based milk suspensions requiring ANMAT-compliant simplified labels.
- Pharmaceuticals:Expanding most quickly as Córdoba generics cluster adopts low-acyl grades for modified-release oral solid dosage forms. Dual-certification suppliers capture premium positioning.
- Cosmetics:Emerging demand for suspension stability in Buenos Aires skincare manufacturing. Regulatory pathway remains less stringent than food or pharmaceutical grades.
- Nutraceuticals:Functional beverage applications in Tucumán and Salta provinces. Smaller volume base dependent on import distributor relationships.
Food and beverage commands current procurement volumes. Pharmaceutical adoption shows the steepest expansion trajectory.
Application:
Volume concentration aligns with Pampas dairy processor technical requirements, while margin distribution favors precision gelling applications with specification customization.
- Thickening Agent:Viscosity modification in neutral pH beverage systems. Oat and almond milk producers in Buenos Aires province specify high-acyl gellan for suspension stability without carrageenan.
- Gelling Agent:Thermal gelation control for dairy desserts and pharmaceutical matrices. Low-acyl grades dominate Córdoba tablet binding contracts requiring brittle gel structures.
- Stabilizer:Protein suspension and emulsion integrity in acidified dairy drinks. Santa Fe processing facilities integrate this function into continuous production lines.
- Emulsifier:Secondary functionality in fat-reduced formulations. Limited penetration compared to dedicated emulsifier hydrocolloids.
Thickening applications absorb the largest tonnage. Gelling agent specifications generate the highest unit margins.
Distribution Channel:
Customer scale determines channel selection: large cooperatives pursue direct manufacturer relationships while mid-tier formulators remain locked into distributor networks.
- Direct Sales:Captive supply agreements between Pampas dairy cooperatives and INTI-audited international fermentation specialists. SanCor's digital tender platform exemplifies this channel compression.
- B2B Supply:Technical service relationships with customized batch documentation. Pharmaceutical manufacturers in Córdoba require this channel for ANMAT registration compliance.
- Wholesale:Regional chemical distributors serving Mendoza and Tucumán beverage formulators with standardized powder grades.
- Online Retail:Minimal penetration limited to small-scale cosmetic and nutraceutical producers. Documentation gaps restrict food-grade procurement through this channel.
Direct sales channels handle the largest volume flows. B2B supply relationships are gaining share fastest among quality-sensitive buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANMAT's alignment with Mercosur Resolution GMC/RES No. 14/21 is reorganizing hydrocolloid procurement across Argentine provinces. Buenos Aires port concentration and Pampas dairy processor scale create distinct regional demand patterns.
Buenos Aires Province
Plant-based milk formulators in Greater Buenos Aires specify high-acyl gellan for oat and almond beverage suspensions. ANMAT's updated disclosure requirements under Resolution 269/2022 mandate simplified ingredient panels. Mastellone Hnos. and La Serenísima operate captive supply agreements with INTI-audited fermentation specialists.
Santa Fe Province
SanCor cooperative's digital tender platform consolidates bulk hydrocolloid procurement for acidified dairy drinks. The National Institute of Industrial Technology certifies manufacturing process compliance for imported biopolymers. Continuous production lines in Rosario integrate stabilizer functions directly into protein suspension systems.
Córdoba Province
Generics manufacturers adopt low-acyl gellan for controlled-release tablet matrices displacing gelatin. Dual-certification suppliers capture premium positioning in this expanding pharmaceutical cluster. Local toll manufacturers face fermentation technologist scarcity, forcing recruitment from Brazilian biotechnology programs.
Mendoza Province
Wine and juice formulators access liquid gellan grades through regional chemical distributors. Cost-sensitive beverage producers revert to xanthan gum for basic suspension applications where thermal stability permits. Regional distributor networks remain dependent on Buenos Aires port clearance timelines.
Chubut and Santa Cruz Provinces
Patagonia aquaculture operations experiment with gellan as a water-stable binding matrix for feed pellets. Salmon farming in these provinces remains underpenetrated for hydrocolloid applications. Supply chain extension from Pampas processing corridors limits commercial scale.
Argentina Gellan Gum Market Competitive Landscape
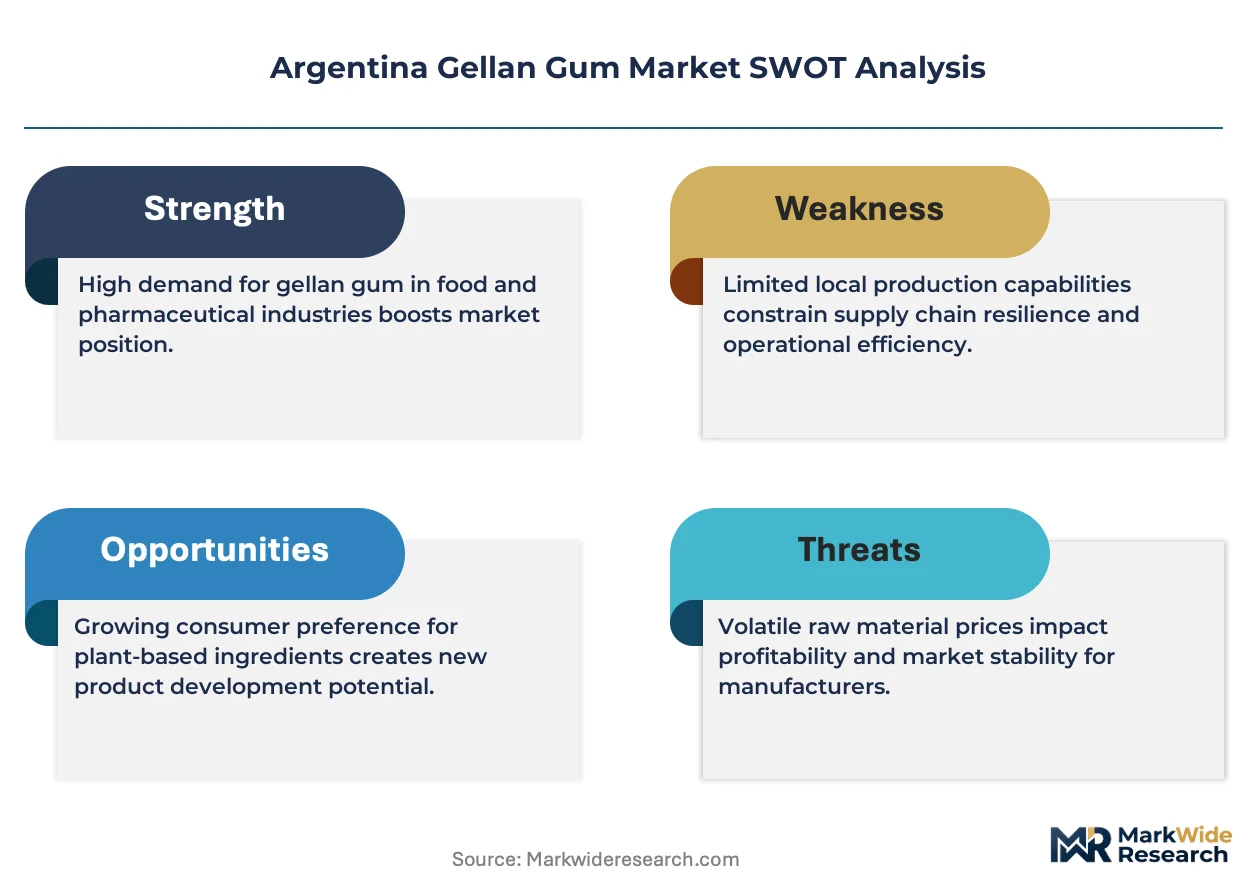
Player mix skews toward multinational fermentation specialists with Mercosur certification and Chinese bulk powder exporters with distributor anchoring. The supplier base concentrates around dual-certification capability and INTI audit compliance. Strategic archetypes include global hydrocolloid majors with fermentation expertise and regional bulk specialists with South American distribution networks. Competitive moves center on direct-procurement platform participation and pharmaceutical-grade registration expansion.
Within the multinational specialist tier, CP Kelco and Jungbunzlauer occupy positions defined by global fermentation infrastructure and dual-certification coverage spanning food and pharmaceutical grades. Hebei Xinhe Biochemical Co. Ltd. anchors the bulk powder specialist archetype through South American distributor relationships. Chinese-origin suppliers including Zhengzhou Cinogel Biotech Co. Ltd. and Zhejiang Tech-Way Biochemical Co. Ltd. represent the cost-optimized export tier serving Mendoza and Tucumán beverage formulators through wholesale chemical distribution.
| Leading Market Players |
|---|
| Hebei Xinhe Biochemical Co. Ltd. |
| Jungbunzlauer |
| CP Kelco |
| H & A Canada Inc. |
| DSM |
| Dancheng Caixin Sugar Industry Co. Ltd. |
| Fufeng Group |
| Zhengzhou Cinogel Biotech Co. Ltd. |
| Zhejiang Tech-Way Biochemical Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
INTI audit compliance gates both supplier qualification and price differentiation across Argentine gellan gum procurement, compressing uncertified competitors into commodity tiers while rewarding dual-certification specialists with premium positioning in pharmaceutical and clean-label food segments.
Pricing Analysis
Cost-plus contracts indexed to sucrose futures dominate procurement between Pampas dairy cooperatives and international fermentation suppliers, with price adjustments triggered quarterly. Pharmaceutical-grade low-acyl gellan commands substantial premiums over food-grade high-acyl variants due to ANMAT dual-registration requirements. Pricing pressure stems from xanthan gum substitution in Mendoza beverage applications where thermal stability specifications permit. Small-scale cosmetic and nutraceutical formulators exhibit highest price sensitivity, while SanCor and Mastellone Hnos. leverage volume scale for contracted rate stability.
Supply Chain Analysis
Buenos Aires port clearance functions as the critical chokepoint for Argentina's hydrocolloid supply, with over 80% of gellan gum imports flowing through this single customs node. Fermentation capacity concentrates in China, Denmark, and Austria, with Chinese suppliers dominating bulk powder grades and European specialists controlling pharmaceutical-certified production. Raw material dependencies span sucrose and glucose feedstocks, fermentation nutrient media, and specialized bioreactor equipment. Single-source vulnerability intensifies around INTI-audited suppliers with existing Mercosur certification. Distribution runs through three channels: direct manufacturer relationships for Pampas dairy cooperatives, B2B technical supply for Córdoba pharmaceutical manufacturers, and regional chemical distributors serving Mendoza and Tucumán beverage formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping Argentine hydrocolloid procurement as SanCor's digital tender system and ANMAT's blockchain-traceable additive documentation create interoperability standards that favor suppliers with integrated certification and batch-customization capabilities.
For Market Incumbents: Secure captive fermentation capacity through toll manufacturing partnerships in Brazil to bypass Argentine technologist scarcity. Deepen INTI audit relationships to preempt competitor qualification during Resolution 269/2022 enforcement waves. Defend against xanthan substitution by demonstrating gellan's superior thermal reversibility in clean-label dairy suspensions.
For New Entrants and Emerging Players: Anchor in Patagonia aquaculture feed applications where gellan's water-stable binding matrix remains underpenetrated in Chubut and Santa Cruz salmon farming operations. Target Córdoba pharmaceutical generics cluster with low-acyl grades displacing gelatin in moisture-sensitive tablet formulations. Pursue dual-certification positioning as the primary go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational food ingredient parents seeking to divest non-core hydrocolloid divisions lacking pharmaceutical-grade fermentation infrastructure. Long-term viability hinges on suppliers' capacity to serve both ANMAT-regulated food applications and expanding controlled-release pharmaceutical demand. Monitor INTI audit backlog duration as the critical inflection signal—compression below six months would accelerate new supplier market entry and intensify pricing competition.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | Simultaneous ANMAT food-grade and pharmaceutical-grade registrations capture premium positioning in Córdoba's expanding generics cluster. |
| Backward Integration into Fermentation Feedstock | Upstream control over sucrose and glucose substrate sourcing insulates margins from Argentine sugar harvest volatility. |
| Digital Tender Platform Participation | Direct-procurement integration with SanCor and Mastellone Hnos. disintermediates distributor markups for bulk hydrocolloid volumes. |
| Blockchain-Traceable Documentation | QR-code integration into Argentine food labels ensures compliance with Mercosur Resolution GMC/RES No. 14/21 and prevents port detention. |
| Technical Service Expansion | Customized fermentation batch documentation strengthens B2B supply relationships with Córdoba pharmaceutical manufacturers requiring ANMAT registration compliance. |
Research Methodology
A standing panel of fermentation plant managers, hydrocolloid procurement leads at Pampas dairy cooperatives, ANMAT regulatory affairs specialists, and pharmaceutical formulation scientists provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with downstream formulators and toll manufacturers with secondary validation against customs import records, INTI certification databases, ANMAT resolution filings, and Mercosur regulatory harmonization documents. Bottom-up volume estimates triangulated against top-down market sizing derived from fermentation capacity disclosures and end-use consumption patterns.
Consistency checks validated volume and value outputs against external benchmarks including hydrocolloid trade flow data and regional food processing production statistics across the analysis window. Segmentation modeling incorporated acyl-substitution grade, end-use industry, application function, and distribution channel dimensions. CAGRs were derived from fitted growth curves applied to base-year estimates, with cross-validation against historical elasticity patterns in substitute hydrocolloid markets. Industry-specific forecast inputs included Sphingomonas cultivation yield trends and ANMAT regulatory implementation timelines.
Decision-makers should treat outputs as directional under assumptions of continued Mercosur regulatory alignment and stable Pampas dairy processor consolidation; material deviation in INTI audit throughput or feedstock cost volatility would warrant model refresh. Practitioners should keep alternative scenarios live as blockchain-traceable additive documentation requirements and direct-procurement platform adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
South Africa Food Additives Market
Food Additives and Ingredients
China Food Emulsifiers Market
Food Additives and Ingredients
Brazil Food Emulsifiers Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Argentina Sodium Reduction Ingredient Market
Food Additives and Ingredients
Neohesperidin Market
Food Additives and Ingredients
Lactoperoxidase Market
Food Additives and Ingredients
Cocoglycerides Market
Food Additives and Ingredients
South America Food Enzymes Market
Food Additives and Ingredients
Spain Food Additives Market
Food Additives and Ingredients
Carob Bean Gum Market
Food Additives and Ingredients
United Kingdom Food Colorants Market
Food Additives and Ingredients
Food Grade Sodium Selenite Market
Food Additives and Ingredients
Carmine Alternatives Market
Food Additives and Ingredients
Ascorbyl Palmitate Market