
 Lipase Food Enzymes Market | 2026-2036
Lipase Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Lipase Food Enzymes Market Foresight
Asset-light contract fermentation models is reconfiguring competitive entry barriers for mid-tier enzyme suppliers. Novozymes A/S leverages its integrated strain development and large-scale bioreactor networks to sustain cost leadership across European dairy applications. Chr. Hansen Holding A/S anchors its position through specialized lipase cultures tailored to protected designation of origin cheese protocols. AB Enzymes competes by controlling regional distribution partnerships that extend technical service reach into smaller bakery and confectionery operations.
Lipase food enzymes comprise triacylglycerol hydrolases that catalyze ester bond cleavage at lipid-water interfaces, typically operating optimally between pH 6.0 and 8.0 with temperature stability up to 50°C in most food-grade formulations. These biocatalysts serve primary industrial functions in flavor development, fat modification, and dough conditioning across processed food manufacturing. Microbial lipase variants dominate volume given their scalable fermentation production and consistent activity profiles, while fungal-derived enzymes command premium positioning in artisanal dairy applications where specific positional specificity determines flavor outcome. Powder formulations lead industrial procurement due to extended shelf stability and standardized dosing, though liquid concentrates are gaining traction in automated beverage processing lines where inline metering reduces handling steps.
EFSA and FDA standards govern food enzyme safety evaluations, with EFSA's 2021 updated guidance requiring comprehensive dietary exposure assessments that extend approval timelines for novel lipase strains. REACH and F-Gas Regulation in Europe further constrain solvent-based extraction alternatives, indirectly steering formulation chemists toward enzymatic processing routes. Stakeholders must monitor evolving strain qualification pathways and build regulatory dossiers before competitor submissions create exclusivity windows for preferred lipase categories.
Market Dynamics
Precision fermentation clusters near Frankfurt and Eindhoven are compressing production economics for microbial lipase variants, forcing asset-heavy incumbents to defend margin structures against contract manufacturers with lower fixed-cost bases.
Growth Catalysts
- EU F-Gas Regulation:The phase-down of hydrofluorocarbon solvents in food processing is redirecting formulation chemists toward enzymatic fat modification routes, particularly in continental dairy operations.
- Protected designation of origin cheese protocols:Artisanal producers in Italy and France require lipase cultures with precise positional specificity, creating premium demand for fungal-derived biocatalysts with documented terroir alignment.
- Inline metering systems:Automated beverage processing lines in Germany and the Netherlands are adopting liquid lipase concentrates to reduce handling steps and standardize dosing accuracy.
Market Restraints
- EFSA strain qualification timelines:The 2021 updated guidance requiring comprehensive dietary exposure assessments extends approval windows for novel lipase variants, freezing pipeline commercialization.
- Fermentation feedstock volatility:Corn-derived glucose and yeast extract prices fluctuate with agricultural commodity cycles, compressing margin predictability for bulk microbial lipase producers.
- Supply concentration in Danish bioreactor networks:Integrated strain-to-scale operations controlled by two major suppliers create bottleneck risk for mid-tier dairy processors seeking alternative sourcing.
Strategic Opportunities
- Spanish and Portuguese dairy expansion:Iberian processors are retrofitting facilities for flavor-modified cheese production, opening procurement windows for lipase suppliers with technical service presence.
- REACH-compliant solvent substitution:The European Chemicals Agency's tightening restrictions on petrochemical extraction processes create regulatory tailwinds for enzymatic alternatives in edible oil refining.
- CRISPR-edited strain development:Convergence of gene editing and automated bioreactor control is enabling custom lipase variants with tailored temperature stability profiles for specific food matrices.
Industry Challenges
- Fermentation scale-up expertise:The shortage of process engineers capable of translating lab-scale strain performance to industrial bioreactor consistency delays commercialization timelines for novel suppliers.
- Legacy powder-to-liquid formulation conversion:Bakery and confectionery operations with established dry-blend workflows face integration friction when adopting liquid concentrate delivery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lipase Food Enzymes Market |
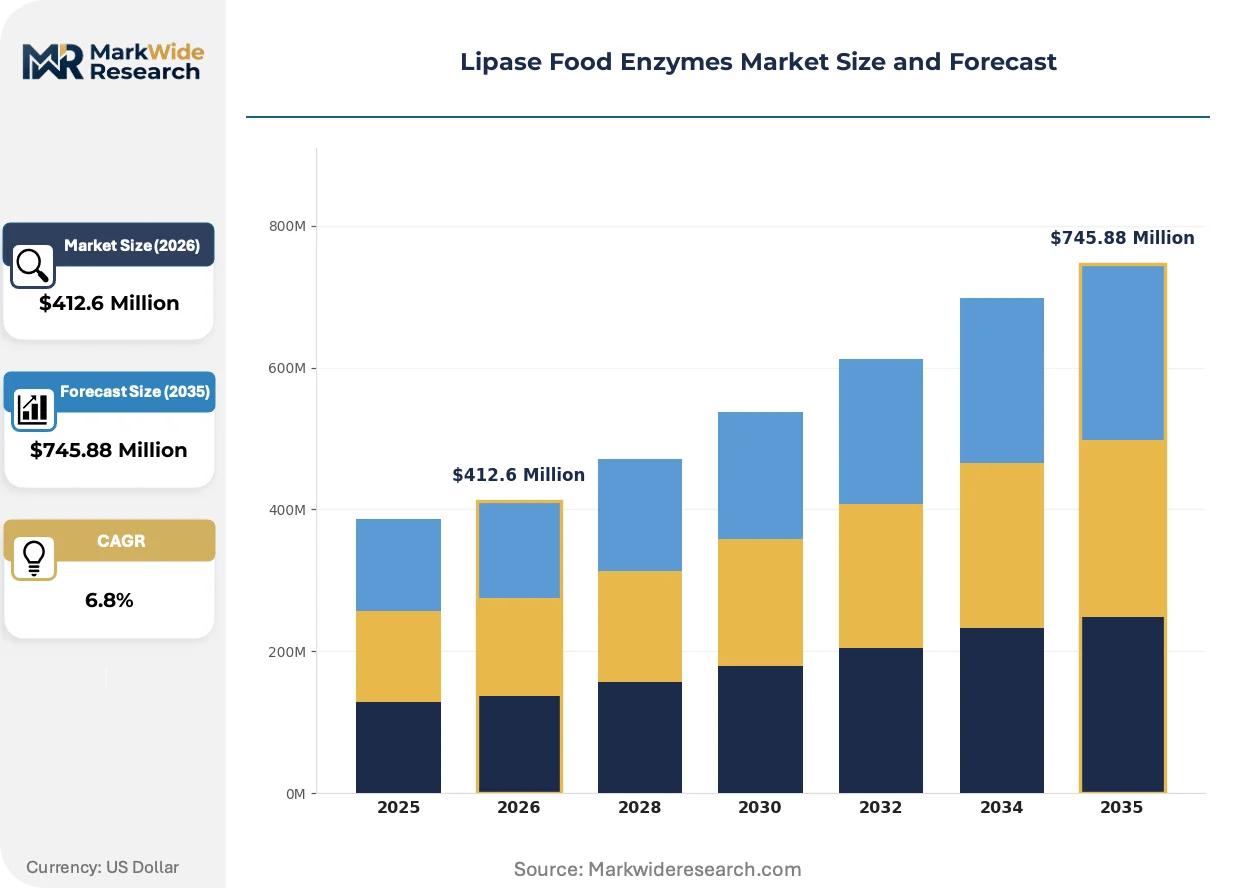
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial, Fungal, Animal, Plant Application: Dairy, Bakery, Confectionery, Beverages Form: Powder, Liquid, Granular, Concentrate End User: Food Manufacturers, Restaurants, Catering Services, Retail |
| Companies Covered | Novozymes A/S, Chr. Hansen Holding A/S, BASF SE, AB Enzymes, Enzyme Development Corporation, Biocatalysts Limited, Creative Enzymes, Advanced Enzymes, Infinita Biotech Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lipase Food Enzymes Market Shifts & Advancements
Digital process control systems and regulatory chemistry mandates are restructuring how lipase suppliers demonstrate value, shifting competitive advantage from raw activity metrics to documented compliance and real-time performance optimization.
Automated bioreactor sensor arrays is digitizing fermentation process monitoring across European production facilities. Dairy enzyme manufacturers in the Netherlands are deploying these systems to capture pH, dissolved oxygen, and biomass density data at 30-second intervals. The technology is digitizing quality assurance workflows, enabling predictive intervention before batch deviations compromise lipase activity profiles.
REACH authorization requirements for solvent-based extraction alternatives are tightening process chemistry standards throughout the European Union. Formulation chemists in edible oil and dairy sectors face mandatory substitution timelines for legacy petrochemical routes. German refiners are responding fastest, retrofitting degumming and interesterification lines with immobilized lipase columns to preempt regulatory non-compliance.
Specification-driven procurement contracts are displacing traditional spot purchasing for food-grade enzymes. Large dairy cooperatives in Denmark and the Netherlands now require documented batch-to-batch consistency metrics and regulatory dossier completeness before supplier qualification. This pattern is most visible in German precision fermentation clusters, where buyers consolidate volumes with fewer vendors capable of delivering integrated technical service and compliance documentation.
Lipase Food Enzymes Market Segmentation
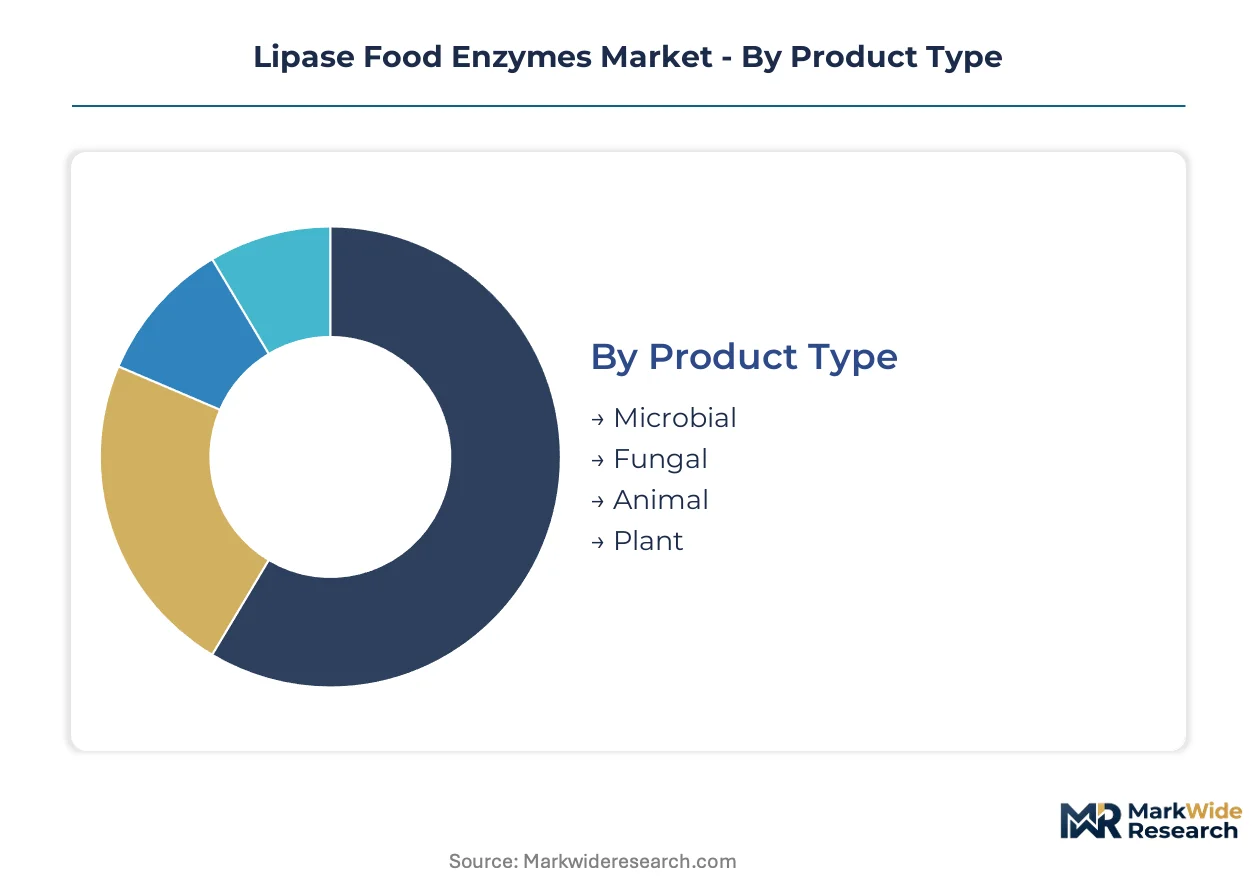
Lipase enzyme procurement patterns diverge sharply across product origins and application matrices, with technical service intensity and formulation compatibility driving vendor selection criteria. The report dissects four structural dimensions that determine pricing tiers, regulatory qualification burdens, and supply chain configurations for enzyme suppliers.
Product Type:
After-sales technical support intensity varies dramatically by biocatalyst origin, with microbial and fungal variants demanding sustained strain optimization consulting while animal-derived enzymes require stability monitoring protocols.
- Microbial:Bacterial and yeast-derived lipases dominate industrial volumes through scalable submerged fermentation production. Precision fermentation clusters in Germany and the Netherlands supply standardized activity profiles for bulk dairy processing, though EFSA strain qualification timelines freeze novel variant commercialization.
- Fungal:Aspergillus and Rhizopus species generate lipases with precise positional specificity for protected designation of origin cheese protocols. Artisanal producers in Italy and France pay premiums for documented terroir alignment and batch-to-batch flavor consistency.
- Animal:Pancreatic and gastric extracts from porcine and bovine sources retain niche positions in traditional European cheese-making. Supply security concerns and halal certification complexity constrain procurement expansion.
- Plant:Cereal germ and latex-derived enzymes occupy experimental positions in clean-label formulations. Limited thermal stability and extraction yield economics restrict commercial scale.
Microbial lipases hold the largest share; momentum sits with fungal variants as artisanal dairy premiums expand.
Application:
Cost tier stratification separates commodity volume applications from specialty flavor-development contracts, with dairy commanding the highest technical service margins and beverages driving automation-compatible formulation demand.
- Dairy:Flavor-modified cheese production and fat interesterification consume the majority of food-grade lipase volumes. German processors retrofitting degumming lines under REACH solvent substitution mandates accelerate immobilized enzyme column adoption.
- Bakery:Dough conditioning and shelf-life extension utilize lipases for phospholipid modification and crumb structure optimization. Powder formulations dominate procurement given established dry-blend workflows and extended shelf stability.
- Confectionery:Cocoa butter equivalent production and chocolate viscosity control employ lipase-catalyzed transesterification. Regional distribution partnerships with technical service reach determine supplier qualification for mid-tier operations.
- Beverages:Automated processing lines in Germany and the Netherlands adopt liquid concentrates for inline metering accuracy. Inline delivery systems reduce handling steps but require reformulation of legacy powder-based protocols.
Dairy commands the dominant revenue position; beverages are climbing the fastest as liquid concentrate infrastructure spreads.
Form:
Customer type segmentation separates industrial manufacturers with integrated quality labs from food service operators prioritizing handling convenience and dosing simplicity.
- Powder:Spray-dried formulations with standardized activity units lead procurement across bakery and confectionery sectors. Extended shelf stability and established logistics infrastructure reinforce incumbent supplier positions.
- Liquid:Concentrated aqueous suspensions enable precise inline metering in automated beverage and dairy processing. German refiners retrofitting under EU F-Gas Regulation timelines favor liquid delivery for continuous reactor integration.
- Granular:Agglomerated particles balance flowability with controlled dissolution kinetics. Niche positioning in artisanal operations with manual dosing requirements.
- Concentrate:Ultra-high activity formulations reduce shipping volumes and cold chain burdens for remote processing facilities. Technical service intensity peaks with custom dilution protocol development.
Powder retains volume leadership; liquid forms gain share fastest as automation investment concentrates in Northern European processing hubs.
End User:
Supply concentration patterns align with end-user scale, with food manufacturers consolidating volumes through specification-driven procurement while fragmented food service operators rely on distributor technical support.
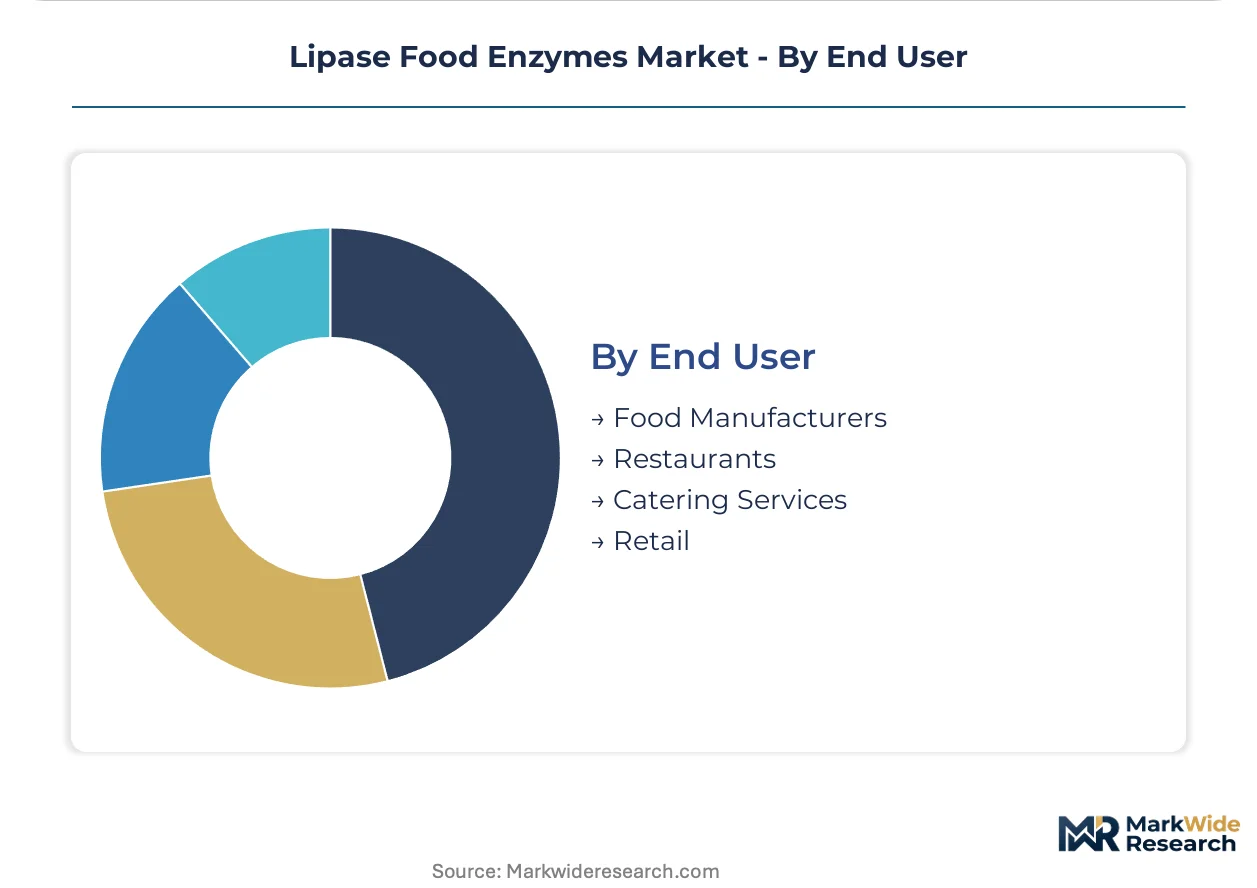
- Food Manufacturers:Large dairy cooperatives in Denmark and the Netherlands mandate documented batch consistency metrics and complete regulatory dossiers. Supplier qualification windows favor integrated strain-to-scale operators with captive bioreactor networks.
- Restaurants:Limited penetration given ingredient cost sensitivity and lack of in-house enzymology expertise. Specialty fermentation houses supply small-batch lipase cultures for experimental menu development.
- Catering Services:Centralized production kitchens explore lipase applications for texture modification and shelf-life extension in prepared meal lines. Procurement runs through broadline distributors with limited technical support capacity.
- Retail:Consumer-facing enzyme preparations for home cheese-making and baking occupy marginal positions. Regulatory labeling requirements and storage stability concerns constrain mass-market expansion.
Food manufacturers absorb the dominant procurement volume; catering services show steepest expansion trajectory as centralized kitchen automation spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in lipase food enzymes tilt toward European processing hubs importing specialized biocatalysts for dairy and edible oil applications, while Asian fermentation facilities supply standardized microbial variants to global food manufacturers seeking cost-competitive inputs.
Germany
Precision fermentation clusters near Frankfurt supply immobilized lipase columns to refiners retrofitting degumming lines under REACH solvent substitution mandates. The F-Gas Regulation accelerates enzymatic fat modification adoption across continental dairy operations. Bavarian processing facilities integrate automated bioreactor sensor arrays for real-time quality assurance.
Netherlands
Large dairy cooperatives in the Netherlands consolidate procurement through specification-driven contracts requiring complete regulatory dossiers. EFSA strain qualification timelines freeze novel variant commercialization for domestic suppliers. Eindhoven-based contract manufacturers compress production economics for mid-tier enzyme buyers.
France
Artisanal producers in France pay premiums for fungal-derived lipases with documented terroir alignment for protected designation of origin cheese protocols. The country's national food safety regulator enforces comprehensive dietary exposure assessments under updated EFSA guidance. Lyon-area dairy processors retrofit facilities for flavor-modified cheese production.
Italy
Italian cheese-makers require lipase cultures with precise positional specificity for traditional production methods. REACH authorization requirements tighten process chemistry standards for edible oil refiners in Northern Italy. Emilia-Romagna processing clusters adopt fungal-derived biocatalysts for batch-to-batch flavor consistency.
Spain
Iberian dairy processors retrofit facilities for flavor-modified cheese production, opening procurement windows for suppliers with technical service presence. The European Chemicals Agency's solvent restrictions create regulatory tailwinds for enzymatic alternatives. Catalonian refining operations pioneer immobilized enzyme column integration.
Lipase Food Enzymes Market Competitive Landscape
On the supply side, the industry is consolidating around integrated strain-to-scale operators with captive bioreactor networks, while contract fermentation specialists erode incumbent margin structures through asset-light production models. Three archetypes dominate: diversified biocatalyst conglomerates with global distribution reach, precision fermentation specialists serving artisanal dairy protocols, and regional distributors controlling technical service access for mid-tier processors. Dominant competitive moves include backward integration into strain development capabilities and geographic expansion through distribution partnerships.
Within the integrated conglomerate tier, Novozymes A/S and Chr. Hansen Holding A/S exemplify scale-driven positioning through captive production infrastructure. BASF SE occupies a diversified chemical-industry position that spans enzyme portfolios beyond food-grade applications. AB Enzymes represents the regional-distribution archetype, anchoring competitive presence through partnerships that extend technical reach into smaller operations.
| Leading Market Players |
|---|
| Novozymes A/S |
| Chr. Hansen Holding A/S |
| BASF SE |
| AB Enzymes |
| Enzyme Development Corporation |
| Biocatalysts Limited |
| Creative Enzymes |
| Advanced Enzymes |
| Infinita Biotech Private Limited |
| Others |
Supply & Pricing Matrix
Danish bioreactor networks and German precision fermentation clusters concentrate upstream biocatalyst production, anchoring margin pools with integrated strain-to-scale operators while contract manufacturers erode pricing power through asset-light alternatives. EFSA strain qualification timelines and REACH solvent substitution mandates reshape where buyers capture value versus where suppliers defend premiums.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with volume-tier discounts and regulatory dossier bundling. Price differentiation separates fungal-derived specialty grades with documented terroir alignment from standardized microbial bulk variants. Pricing pressure intensifies in commodity dairy applications as Eindhoven contract manufacturers compress production economics. Mid-tier processors show highest price sensitivity given limited technical service budgets, while artisanal PDO cheese producers accept premiums for batch-to-batch flavor consistency.
Supply Chain Analysis
EU dual-use technology controls on precision fermentation equipment constrain bioreactor exports to certain jurisdictions, fragmenting capacity expansion timelines. Supply concentrates in Denmark, Germany, and the Netherlands, with Asian fermentation facilities feeding cost-sensitive commodity tiers. Corn-derived glucose and yeast extract feedstocks draw from agricultural commodity cycles, exposing margin predictability to harvest volatility. Single-source vulnerability runs through integrated conglomerates controlling captive bioreactor networks. Distribution runs through regional technical service partnerships extending into smaller bakery and confectionery operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial-scale fermentation expertise and regulatory dossier compilation capability represent the critical scarcity layer separating viable suppliers from stranded capacity. The gap between lab-scale strain performance and industrial bioreactor consistency determines which players capture procurement consolidation benefits.
For Market Incumbents: Insulate margin structures by deepening backward integration into CRISPR-edited strain development capabilities before contract manufacturers replicate precision fermentation economics. Prioritize certification investment for REACH-compliant solvent substitution protocols to preempt regulatory non-compliance windows. Channel control through specification-driven procurement contracts with Dutch and Danish dairy cooperatives defends against technical service erosion. For New Entrants and Emerging Players: Pursue Iberian dairy processor retrofit cycles in Spain and Portugal where technical service presence gaps create qualification windows. Target automated beverage processing lines in Germany and the Netherlands adopting liquid concentrate infrastructure. Anchor go-to-market positioning through distribution partnerships with regional enzyme distributors lacking in-house fermentation capacity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed contract fermentation specialists near Frankfurt and Eindhoven lacking downstream customer integration. Long-term viability favors platforms with demonstrated EFSA strain qualification pathways and captive bioreactor networks over pure-play distribution assets. Monitor EFSA approval velocity for novel lipase variants as inflection indicator for pipeline commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | Captive CRISPR-edited lipase variants reduce dependency on external research houses and accelerate EFSA timelines. |
| Long-term Supply Agreement | Specification-driven contracts with Dutch dairy cooperatives lock in volume commitments and technical service margins. |
| Capacity Expansion | Additional precision fermentation capacity near Frankfurt serves REACH-driven solvent substitution demand from German refiners. |
| Joint Venture | Partnerships with Iberian distributors extend technical service reach into Spanish and Portuguese dairy retrofit projects. |
| Regulatory Approval Pathway | EFSA dossier completeness for novel lipase strains creates exclusivity windows before competitor submissions freeze categories. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with fermentation process engineers, regulatory affairs directors at enzyme suppliers, dairy procurement managers at cooperatives, and technical service leads at regional distributors; alongside secondary validation through EFSA guidance documents, REACH authorization databases, EU F-Gas Regulation implementation records, and customs trade flows for food-grade enzyme categories. Bottom-up strain-level production estimates and top-down dairy processing capacity assessments were triangulated against documented procurement contract values.
Forecast inputs considered product origin segmentation across microbial, fungal, animal, and plant-derived variants; application matrices spanning dairy, bakery, confectionery, and beverages; form factors distinguishing powder, liquid, granular, and concentrate delivery; and end-user scale differentiating food manufacturers from food service operators. CAGRs were derived from production capacity buildouts, EFSA approval velocity assumptions, and REACH substitution timeline enforcement patterns across the projection horizon.
Sensitivities concentrate around EFSA strain qualification timeline extensions, fermentation feedstock price volatility, and REACH solvent restriction acceleration. Forecasts reflect assumptions about regulatory enforcement consistency and bioreactor scale-up success rates without guarantee. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
Food Acidulants Market
Food Additives and Ingredients
Methyl Oleate Market
Food Additives and Ingredients
North America Feed Additives Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
Egypt Feed Additives Market
Food Additives and Ingredients
Food Phosphate Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
Chymosine Market
Food Additives and Ingredients
Dairy Enzymes Market
Food Additives and Ingredients
Cook-Up Starch Market
Food Additives and Ingredients
Annatto Food Colors Market
Food Additives and Ingredients
Global Gamma Linolenic Acid Market
Food Additives and Ingredients
South Africa Food Preservatives Market
Food Additives and Ingredients
Carrageenan Gum Market
Food Additives and Ingredients
Natural Food Additives Market