
 India Online Insurance Market | 2026-2036
India Online Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
India Online Insurance Market Insights
The IRDAI's regulatory sandbox framework for insurtech experimentation is consolidating digital-first distribution across India. PolicyBazaar leverages its aggregator platform to dominate comparison-driven customer acquisition in tier-2 and tier-3 cities. Acko differentiates through its direct-to-consumer mobile app infrastructure, while Bajaj Finserv sustains its position via embedded insurance partnerships with consumer finance products.
India online insurance denotes digitally underwritten and distributed risk-transfer contracts where policy issuance, premium collection, and claims processing occur through web or mobile interfaces without physical agent mediation. The sector operates on API-driven core systems enabling real-time risk scoring and automated underwriting decisions. Health insurance leads premium volume among product types as hospitalization cost inflation drives first-time buyers online. Aggregators capture the dominant share of distribution channel flow by concentrating policy comparison and instant issuance in unified interfaces. Individual consumers represent the fastest-growing customer type as smartphone penetration dissolves traditional agent dependency.
IRDAI governs product approval, solvency requirements, and digital distribution norms, while BIS standards for data security shape platform infrastructure compliance. The RBI's oversight of payment aggregators constrains premium collection architectures, forcing insurtechs to maintain dual regulatory alignment. Stakeholders must monitor how IRDAI's Bima Sugya mandate for simplified products intersects with state-level motor vehicle digitization timelines.
Market Dynamics
IRDAI's sandbox framework is compressing product approval timelines and enabling real-time underwriting infrastructure that bypasses traditional agent networks entirely. This regulatory architecture is redistributing market power toward platforms with direct digital distribution capabilities.
Growth Catalysts
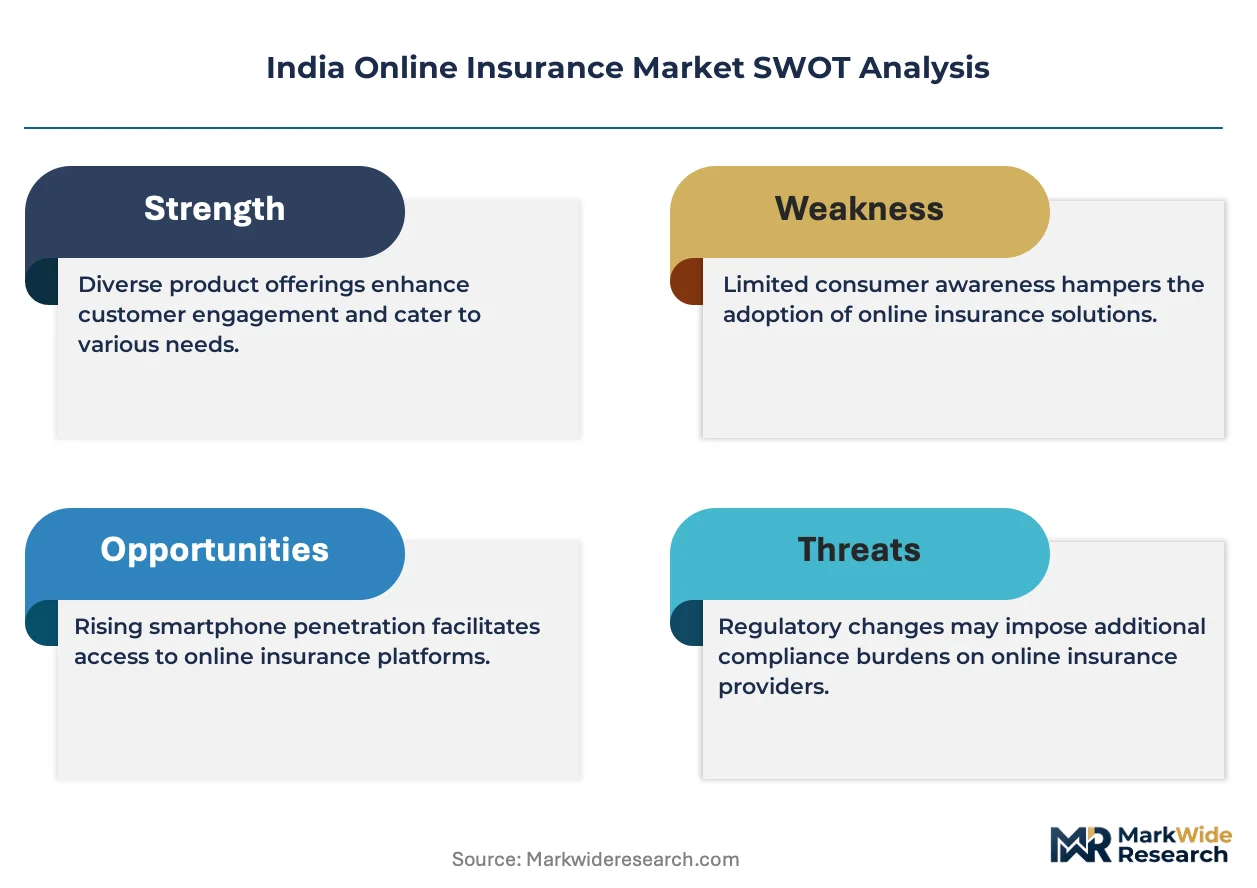
- IRDAI Sandbox Framework:The regulatory sandbox permits live testing of algorithmic underwriting models without full certification, accelerating insurtech product launches into tier-2 city markets.
- Smartphone Penetration:Mobile-first policy issuance is dissolving historical dependency on physical agent networks across Maharashtra, Karnataka, and Gujarat.
- Hospitalization Cost Inflation:Escalating medical expenses are pushing first-time buyers toward instant digital health policy comparison and purchase.
Market Restraints
- Dual Regulatory Alignment:RBI oversight of payment aggregators forces insurtechs to maintain parallel compliance architectures for premium collection, elevating operational complexity.
- Data Localization Requirements:BIS standards for data security mandate domestic server infrastructure, constraining cloud cost optimization for smaller platforms.
- Legacy Core System Integration:Incumbent insurers face technical debt from mainframe-based policy administration systems that resist API-driven connectivity.
Strategic Opportunities
- Tier-2 City Penetration:Households in secondary urban centers remain underpenetrated for digital health coverage despite accelerating smartphone adoption.
- Bima Sugya Mandate:IRDAI's simplified product directive creates regulatory tailwind for standardized micro-policies targeting mass-market segments.
- Embedded Distribution:Integration with consumer finance and e-commerce checkout flows opens alternative acquisition channels beyond standalone insurance platforms.
Industry Challenges
- Actuarial Talent Scarcity:Shortage of professionals combining traditional risk modeling expertise with machine learning implementation delays algorithmic underwriting deployment.
- Claims Fraud Detection:Real-time digital claims processing requires sophisticated anomaly detection systems that many platforms lack capital to build.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Online Insurance Market |
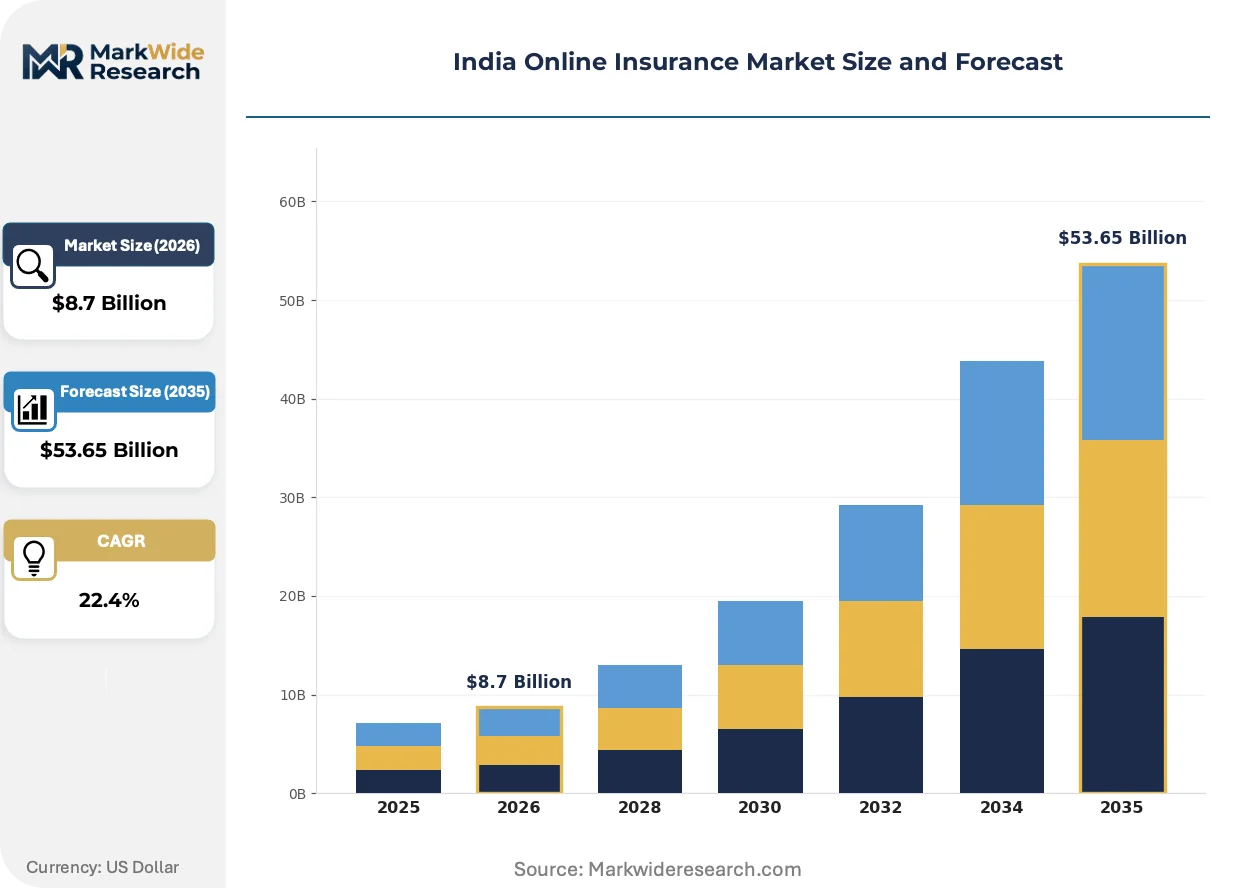
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Health Insurance, Motor Insurance, Life Insurance, Travel Insurance Customer Type: Individual Consumers, Corporates, Small Businesses, Startups Policy Duration: Short-Term, Long-Term, Annual, Multi-Year Distribution Channel: Direct Online, Aggregators, Insurance Brokers, Mobile Apps |
| Companies Covered | PolicyX, RenewBuy, PolicyBazaar, Bajaj Finserv, Turtlemint, Acko, Coverfox, Digit Insurance, Go Digit, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Online Insurance Market Trends and Innovations
API-driven core systems are compressing the policy lifecycle from quote to issuance into minutes rather than days. This infrastructure shift is enabling new competitive vectors around speed and embedded distribution.
Telematics integration for motor coverage is unifying vehicle data streams with dynamic premium calculation engines. Fleet operators and individual vehicle owners in Gujarat and Maharashtra are adopting usage-based policies at accelerating rates. The technology is unifying risk assessment with real-time driving behavior, compressing traditional annual renewal cycles into continuous pricing adjustments.
IRDAI's Bima Sugya mandate for simplified product structures is forcing product teams to strip complexity from policy wordings. The regulation compresses actuarial review timelines and reduces compliance documentation burdens. Health and motor segments are responding fastest, with platforms launching pre-approved micro-products that require no manual underwriting intervention.
Aggregator platforms are capturing an expanding share of customer acquisition as comparison behavior becomes habitual among digital-native buyers. Traditional agent channels face displacement in tier-2 and tier-3 cities where PolicyBazaar and similar interfaces dominate search and purchase journeys. This channel rotation is most visible in Karnataka, where smartphone penetration has crossed critical thresholds for standalone digital purchase confidence.
India Online Insurance Market Segmentation
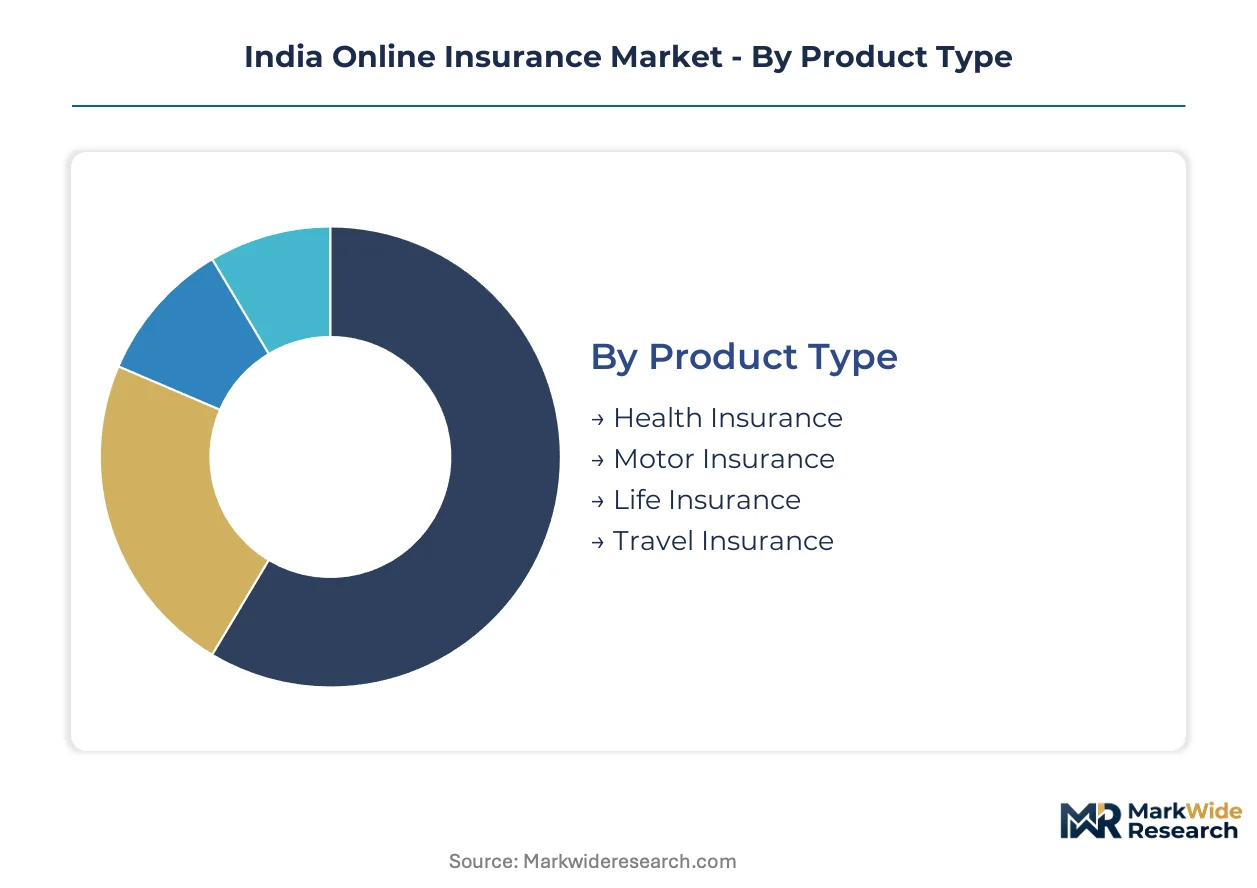
Segmentation in India's online insurance market reveals how digital infrastructure reshapes product design and customer targeting. Each dimension exposes distinct growth vectors from tier-2 city penetration to embedded distribution partnerships.
Product Type:
Customization intensity varies sharply across this category, with standardized motor products at one pole and bespoke corporate health plans at the other.
- Health Insurance:Digitally underwritten policies covering hospitalization expenses with real-time claims settlement through API-connected provider networks. Demand concentrates in Maharashtra and Karnataka as hospitalization cost inflation pushes first-time buyers toward instant comparison platforms.
- Motor Insurance:Vehicle coverage products integrating telematics for dynamic premium calculation based on driving behavior data streams. Gujarat fleets and individual owners are adopting usage-based policies as vehicle digitization spreads through RTO integration.
- Life Insurance:Term and investment-linked products distributed through simplified digital journeys with reduced medical underwriting requirements.
- Travel Insurance:Short-duration coverage for domestic and international trips with automated claim processing for flight delays and medical emergencies abroad.
Leading the category by volume: Health Insurance. Growing fastest: Motor Insurance.
Customer Type:
Cost tier stratification dominates here, from mass-market individual premiums to enterprise-scale corporate negotiations.
- Individual Consumers:Smartphone-enabled policyholders purchasing directly through mobile interfaces without agent mediation. Tier-2 city households in Uttar Pradesh and Rajasthan are accelerating adoption as digital literacy spreads.
- Corporates:Large enterprises procuring group health and term life coverage through dedicated account management with customized benefits structures.
- Small Businesses:Micro-enterprises and shop owners seeking affordable bundled coverage with simplified underwriting through Bima Sugya-compliant products.
- Startups:Technology companies and venture-backed firms prioritizing flexible, month-to-month coverage aligned with variable headcount.
Dominating premium volume: Individual Consumers. Expanding most quickly: Startups.
Policy Duration:
Application context drives selection here, with transactional short-term products contrasting against loyalty-building multi-year structures.
- Short-Term:Coverage periods under one year for travel, temporary vehicle use, or project-specific liability needs with minimal underwriting friction.
- Long-Term:Multi-decade life and health products with guaranteed renewal provisions and locked-in premium rates.
- Annual:Standard one-year renewable contracts dominating motor and health segments with automated renewal workflows.
- Multi-Year:Two-to-three year policies offering premium discounts and reduced administrative burden for stable risk profiles.
Highest transaction frequency: Annual. Gaining share fastest: Multi-Year.
Distribution Channel:
Supply concentration patterns differentiate this category, from captive direct platforms to fragmented broker networks.
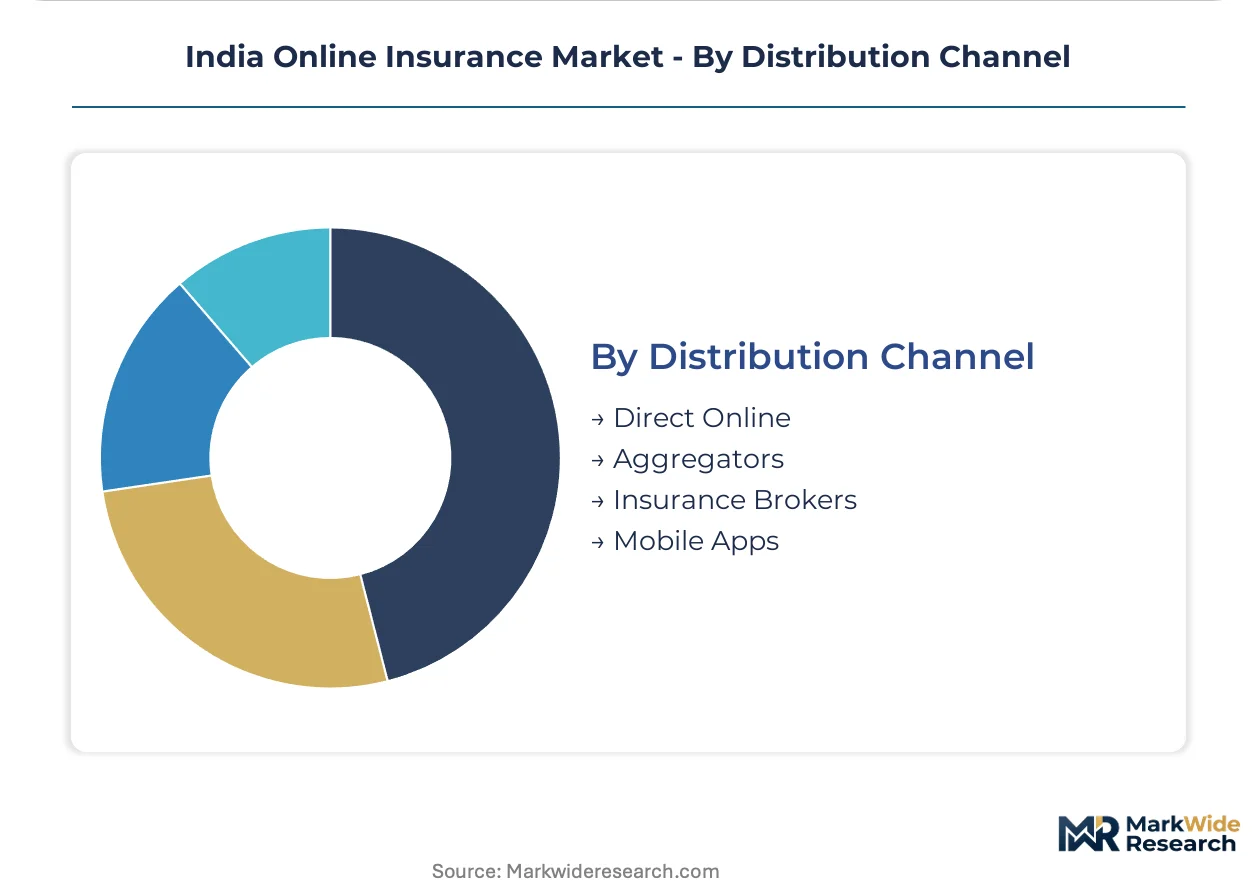
- Direct Online:Insurer-owned websites and portals capturing full margin without intermediary commissions. Acko's mobile-first infrastructure exemplifies this model.
- Aggregators:Comparison platforms consolidating multiple insurers in unified search interfaces. PolicyBazaar dominates customer acquisition in tier-2 and tier-3 cities through this channel.
- Insurance Brokers:Licensed intermediaries providing advisory services for complex commercial risks with hybrid digital-physical engagement.
- Mobile Apps:Embedded distribution through super-apps and fintech wallets with insurance as add-on at checkout.
Capturing dominant flow: Aggregators. Climbing the fastest: Mobile Apps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors India's online insurance infrastructure through its concentration of aggregator headquarters, insurtech development centers, and regulatory coordination with IRDAI. The metropolitan corridor channels premium flows from Maharashtra's industrial belts while serving as the technical backbone for platforms expanding into secondary cities.
Maharashtra
Mumbai-Pune corridor households drive health policy digitization as hospital networks integrate with insurer APIs for cashless settlement. IRDAI's sandbox approvals for algorithmic underwriting concentrate here before national rollout. Thane and Nashik satellite markets absorb platform expansion as smartphone penetration crosses critical mass for standalone digital purchase.
Karnataka
Bengaluru's technology workforce sustains demand for flexible, month-to-month coverage products through employer-embedded distribution. The state's RTO digitization timeline accelerates motor policy issuance through real-time vehicle data verification. Mysuru and Mangaluru tier-2 clusters exhibit comparison-shopping behavior on aggregator platforms as digital literacy spreads.
Gujarat
Ahmedabad-Surat industrial corridors generate fleet motor insurance demand through telematics-enabled usage-based pricing. State-level vehicle registration digitization permits instant policy binding without physical document submission. Vadodara and Rajkot manufacturing hubs drive small business liability coverage through Bima Sugya-compliant simplified products.
Telangana
Hyderabad's pharmaceutical and IT services sectors channel group health procurement through digital broker platforms with customized benefits structures. The state's startup density pushes demand for flexible coverage aligned with variable headcount. Warangal and Nizamabad emerging markets show accelerating individual policy adoption through mobile-first issuance.
Tamil Nadu
Chennai's automotive supply chain concentrates commercial motor coverage demand among logistics operators and component manufacturers. State-level hospital network digitization enables real-time claims settlement integration with health platforms. Coimbatore and Madurai tier-2 manufacturing centers exhibit rising comparison-driven purchase behavior for term life products.
India Online Insurance Market Competitive Landscape
The competitive structure tilts toward aggregator-dominated distribution with direct-to-consumer platforms capturing secondary growth vectors. Market power concentrates in comparison-engine interfaces that consolidate multiple underwriters, while embedded distribution partnerships with consumer finance products sustain parallel channel importance. Three archetypes define positioning: pure-play aggregators, insurer-owned direct platforms, and embedded distribution specialists. Consolidation pressure manifests through strategic technology licensing and API infrastructure partnerships rather than horizontal mergers.
Among aggregator platforms, PolicyBazaar and Coverfox occupy positions defined by comparison-driven customer acquisition infrastructure. Acko exemplifies the direct-to-consumer mobile-first archetype through its app-based issuance model. Bajaj Finserv represents embedded distribution integration with consumer finance products, anchoring the alternative channel vector. These three patterns illustrate how regulatory sandbox approvals and tier-2 city penetration strategies differentiate competitive positioning without requiring scale-driven M&A.
| Leading Market Players |
|---|
| PolicyX |
| RenewBuy |
| PolicyBazaar |
| Bajaj Finserv |
| Turtlemint |
| Acko |
| Coverfox |
| Digit Insurance |
| Go Digit |
| Others |
Pricing and Supply Chain Analysis
API-driven backward integration into claims processing infrastructure anchors both supply position and pricing power for dominant platforms. Insurtechs with captive underwriting engines command premium positioning while smaller distributors face margin compression from RBI payment aggregator compliance costs.
Pricing Analysis
Outcome-linked pricing tied to claims settlement speed anchors premium differentiation across the market. Three-tier pricing structure across premium, standard, and economy levels segments buyers by underwriting complexity and service bundling. Cost compression in the economy tier intensifies because aggregator commissions and regulatory compliance stack operational overhead. Individual consumers in tier-2 cities exhibit highest price sensitivity, while corporate group policies show lowest elasticity due to bundled benefits requirements.
Supply Chain Analysis
Freight cost exposure remains minimal as digital policy delivery eliminates physical distribution entirely. Core technology supply concentrates in India, Singapore, and the United States through cloud infrastructure providers and API middleware vendors. Data center capacity, cybersecurity certification, and payment gateway licenses constitute critical input dependencies. Single-source vulnerability in cloud infrastructure creates concentration risk for smaller platforms without multi-region redundancy. Distribution runs through direct-to-consumer apps and aggregator platforms with embedded finance partnerships gaining downstream share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from IRDAI's Bima Sugya standardization mandate is forcing sub-scale distributors toward acquisition or exit. Platforms lacking captive underwriting technology face irreversible margin erosion.
For Market Incumbents: Anticipate regulatory tightening on algorithmic underwriting transparency by investing in explainable AI documentation and actuarial audit trails. Defend channel position through exclusive embedded partnerships with consumer finance platforms before fintech wallets capture distribution. Prioritize API standardization investments to reduce legacy system integration costs that currently constrain product launch velocity. For New Entrants and Emerging Players: The mid-market price-point gap between Acko's premium direct-to-consumer positioning and mass-market aggregator products creates white-space opportunity. Target small business segments in Gujarat and Maharashtra manufacturing corridors with Bima Sugya-compliant simplified liability products. Establish go-to-market presence through RTO-integrated motor policy issuance before incumbent insurers complete digitization. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic technology licensing to incumbent insurers seeking digital transformation acceleration. Long-term viability hinges on underwriting margin sustainability rather than distribution scale alone across the five-to-ten year horizon. Acquisition targets should demonstrate captive API infrastructure with IRDAI sandbox approval history. Watch for inflection when tier-2 city smartphone penetration crosses threshold for standalone digital purchase confidence without agent mediation.| Strategic Initiative | Industry Significance |
|---|---|
| API Infrastructure Partnership | Enables real-time underwriting bypassing legacy mainframe constraints for tier-2 city expansion. |
| Embedded Distribution Integration | Positions insurance at consumer finance checkout flows in Maharashtra and Karnataka markets. |
| Telematics Platform Development | Unifies vehicle data streams with dynamic pricing for Gujarat fleet operator segments. |
| Bima Sugya Product Line Launch | Accelerates regulatory approval through simplified micro-policy structures for mass-market penetration. |
| Claims Automation Investment | Reduces fraud exposure through anomaly detection systems critical for digital-native customer retention. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with IRDAI compliance officers, insurtech product managers, aggregator platform engineers, and hospital network procurement leads combined with secondary validation from RBI payment system disclosures, IRDAI annual reports, and BIS cybersecurity standards. Bottom-up policy volume estimates and top-down premium flow analysis were triangulated against sandbox approval timelines and state-level RTO digitization schedules.
Reconciliation of premium volume streams, distribution channel flows, and customer acquisition cost data shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, customer archetype, policy duration tier, and distribution channel with regional adoption patterns as an insurance-specific overlay. CAGRs were derived from compound growth trajectory analysis incorporating smartphone penetration curves, hospitalization cost inflation indices, and motor vehicle registration digitization timelines as key forecast inputs.
Inputs from IRDAI regulatory databases and state transport authority digitization schedules were available through the study window; gaps in real-time claims settlement performance metrics introduce uncertainty bands around profitability assumptions. Forecasts reflect documented assumptions about regulatory sandbox expansion pace and tier-2 city digital literacy progression. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Embedded Insurance Market
Insurance
Critical Illness Insurance Market
Insurance
Germany Health and Medical Insurance Market
Insurance
Asia-Pacific Livestock Insurance Market
Insurance
Europe Electronic Gadgets Insurance Market
Insurance
Asia-Pacific Extended Warranty Market
Insurance
China Group Health Insurance Market
Insurance
Peer to Peer Insurance Market
Insurance
Insurance Aggregators Market
Insurance
North America Car Insurance Aggregators Market
Insurance
Title Insurance Market
Insurance
Greece Property and Casualty Insurance Market
Insurance
Saudi Arabia Travel Insurance Market
Insurance
Singapore Business Income Insurance Market
Insurance
Germany Property and Casualty Insurance Market
Insurance
United States Insurance Brokerage Market