
 United States Aircraft Health Monitoring System Market | 2026-2036
United States Aircraft Health Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
United States Aircraft Health Monitoring System Market Intelligence
Domestic avionics manufacturing capacity is restructuring around digital twin integration and edge-computing sensor architectures. GE Aerospace leverages its turbofan installed base to bundle prognostic subscriptions with engine overhaul contracts. Honeywell International Inc. sustains channel control through proprietary data bus protocols that lock in airline customers. Safran SA anchors its position via in-house production of fiber-optic strain sensors for composite airframe monitoring.
An aircraft health monitoring system comprises distributed sensor networks, onboard data acquisition units, and ground-based analytics platforms that capture vibration, temperature, pressure, and structural load parameters to forecast component failures before they trigger operational disruptions. Predictive analytics and machine learning segments are capturing expanding margin pools as airlines shift from calendar-based to condition-based maintenance regimes. Military end users are driving demand for hardened data acquisition systems that operate across encrypted tactical data links, while MRO service providers compete on proprietary algorithm libraries that differentiate turnaround pricing.
FAA airworthiness directives and DOD MIL-STD-810H environmental testing requirements shape hardware certification pathways and software validation protocols for domestic suppliers. The Department of Transportation's ongoing safety management system mandates are forcing regional carriers to adopt continuous monitoring architectures that were previously exclusive to major fleet operators. Stakeholders must decide whether to build predictive maintenance platforms in-house or accept vendor lock-in through integrated sensor-to-cloud subscriptions.
Market Dynamics
Commercial airlines are compressing maintenance windows through condition-based monitoring architectures, forcing hardware suppliers to bundle predictive analytics with sensor hardware rather than selling discrete components.
Growth Catalysts
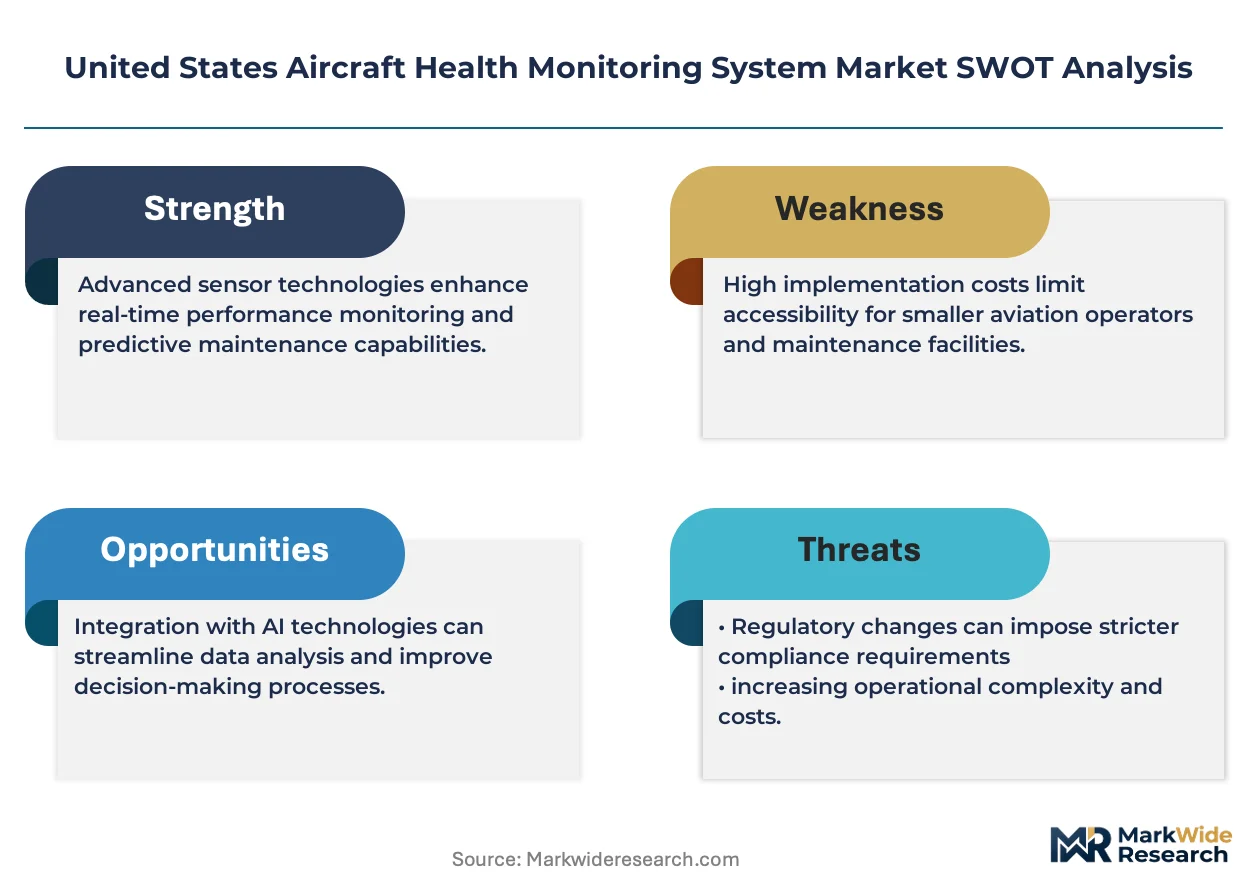
- FAA Airworthiness Directives:Continuous airworthiness mandates require fleet-wide sensor retrofits on aging narrow-body aircraft, creating replacement demand for data acquisition units.
- Edge Computing Architectures:Onboard processing capabilities reduce latency for critical failure predictions, enabling real-time structural load analysis during flight operations.
- Southwest Regional Hub Concentration:Dallas-Fort Worth and Houston maintenance bases generate concentrated procurement volume for integrated health monitoring platforms.
Market Restraints
- Specialized Sensor Supply Concentration:Fiber-optic strain sensor production concentrates among limited domestic foundries, creating input bottlenecks for composite airframe monitoring systems.
- MIL-STD-810H Certification Friction:Military environmental testing requirements extend hardware validation timelines by twelve to eighteen months for dual-use suppliers.
- Proprietary Data Bus Lock-in:Airlines face switching costs from vendor-specific communication protocols that fragment fleet-wide data integration.
Strategic Opportunities
- Regional Carrier Underpenetration:Part 121 operators with fewer than fifty aircraft lack continuous monitoring infrastructure, representing greenfield deployment potential.
- Encrypted Tactical Data Links:Military end users are driving demand for hardened acquisition systems that operate across secure airborne networks.
- Department of Transportation SMS Mandates:Safety management system requirements force adoption of continuous monitoring architectures previously exclusive to major fleet operators.
Industry Challenges
- Prognostics Engineering Talent Scarcity:Machine learning specialists with aviation domain expertise command premium compensation, constraining algorithm development capacity.
- Legacy Avionics Integration Complexity:ARINC 429 and MIL-STD-1553 bus architectures require custom interface hardware for modern ethernet-based sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Aircraft Health Monitoring System Market |
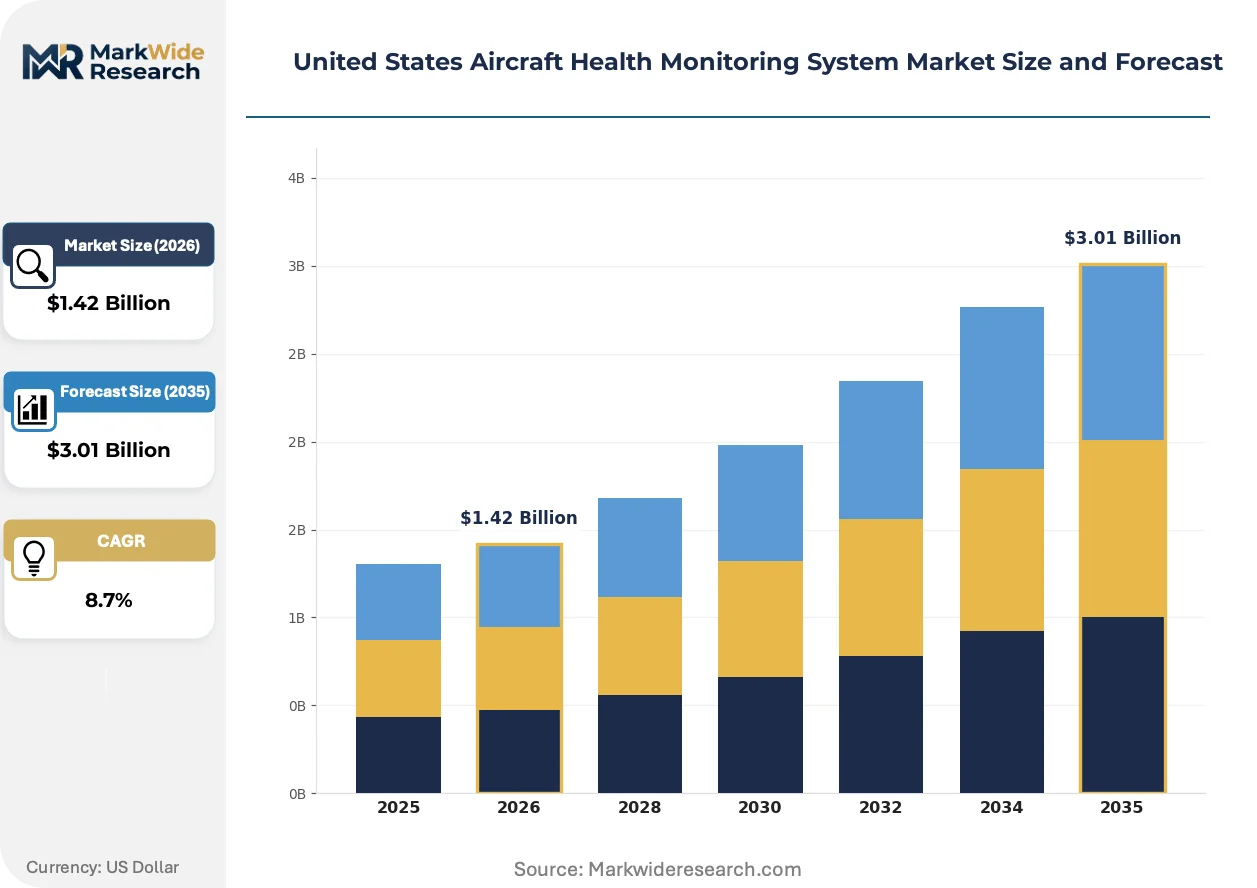
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitoring Software, Sensors, Data Acquisition Systems, Maintenance Tools End User: Airlines, Military, OEMs, MRO Service Providers Technology: Predictive Analytics, Internet of Things, Machine Learning, Big Data Application: Performance Monitoring, Condition-Based Maintenance, Predictive Maintenance, Safety Assurance |
| Companies Covered | GE Aerospace, Safran SA, The Boeing Company, Curtiss-Wright Corporation, Teledyne Controls LLC, Honeywell International Inc., Airbus SE, Meggitt PLC, RTX Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Aircraft Health Monitoring System Market Strategic Shifts & Innovations
Digital twin architectures are displacing reactive maintenance calendars across commercial and defense fleets, compressing the value capture window from hardware sales toward subscription-based analytics.
Fiber-optic strain sensing is converging with composite airframe manufacturing, embedding structural health monitoring directly into wing and fuselage layups during production. Boeing and Airbus tier-one suppliers are specifying sensor-integrated prepregs for next-generation single-aisle programs. This convergence is collapsing the distinction between manufacturing quality control and in-service monitoring, forcing MRO providers to develop composite-specific diagnostic competencies.
FAA continued airworthiness directives are accelerating hardware refresh cycles for aging fleet segments, particularly ADS-B Out mandate compliance driving replacement of legacy data acquisition units. The directives compress supplier lead times and favor domestic manufacturers with established Parts Manufacturer Approval pathways. Narrow-body operators in the Southeast maintenance corridor are consolidating procurement to reduce certification documentation burden.
Airline engineering departments are unbundling predictive maintenance subscriptions from engine overhaul contracts, seeking direct relationships with specialized algorithm developers. This procurement fragmentation disrupts OEM bundled service models and creates channel conflict between airframe manufacturers and independent software vendors. The shift is most visible among ultra-low-cost carriers operating high-utilization single-aisle fleets from Florida and Texas bases.
United States Aircraft Health Monitoring System Market Segmentation
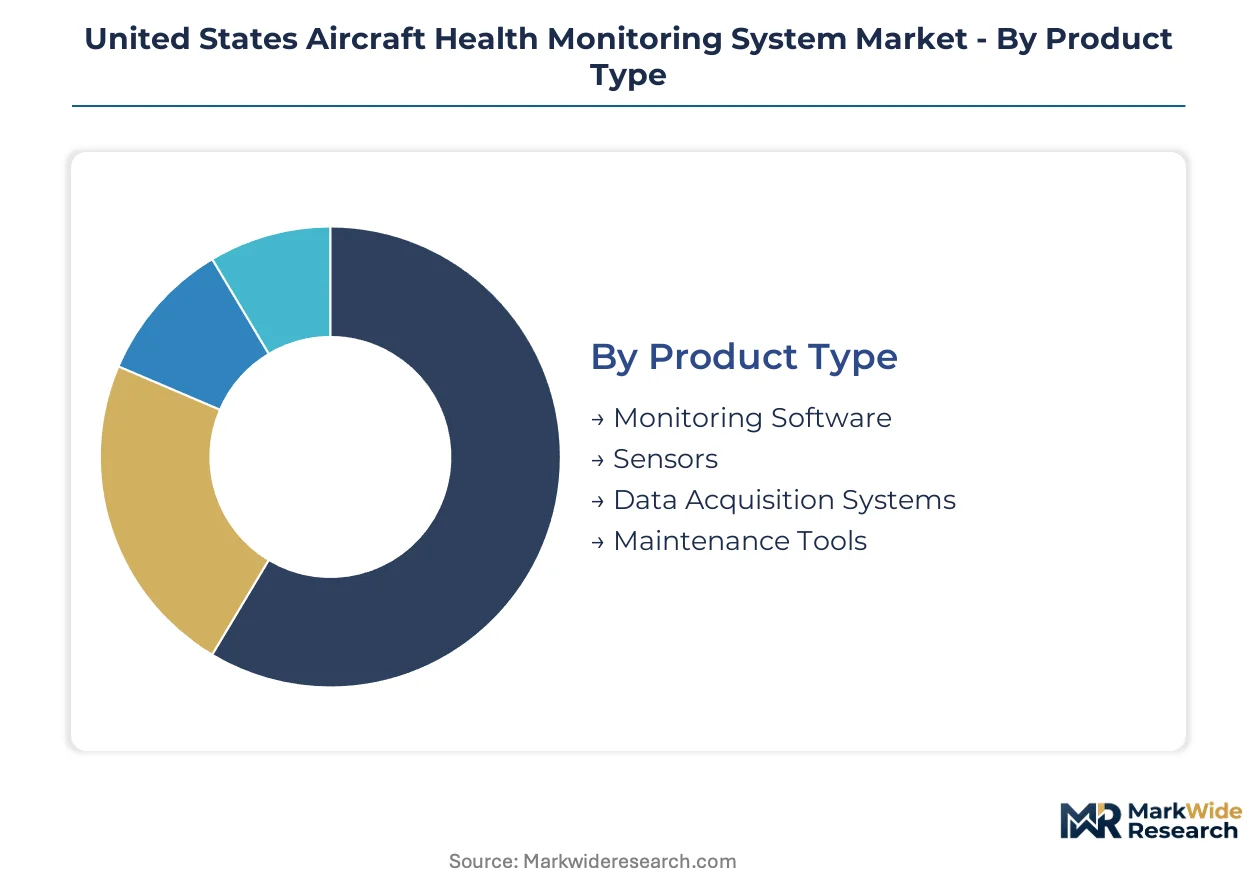
Hardware refresh cycles and FAA mandate compliance reshape procurement patterns across product categories. Airlines prioritize integrated platforms over discrete components, while military buyers demand hardened specifications. Understanding segment boundaries clarifies where vendor lock-in risks concentrate versus where greenfield deployment opportunities exist.
Product Type:
Upgrade timelines vary sharply by hardware vintage, with legacy data acquisition units facing forced replacement under continued airworthiness directives while software layers refresh on independent cycles.
- Sensors:Distributed networks capture vibration, temperature, pressure, and structural load parameters through piezoelectric accelerometers and fiber-optic strain gauges. Demand clusters in Texas and Florida maintenance corridors where composite airframe retrofits require embedded sensing infrastructure.
- Data Acquisition Systems:Onboard units aggregate sensor streams for edge processing or ground transmission, with ARINC 429 and MIL-STD-1553 interface requirements dominating military specifications. Southwest regional carriers are consolidating procurement to reduce certification documentation burden.
- Monitoring Software:Analytics platforms host predictive algorithms and digital twin simulations.
- Maintenance Tools:Ground-based diagnostic equipment supports turnaround scheduling.
Sensors sit at the top of the volume ranking, with data acquisition systems climbing the fastest.
End User:
Customer procurement authority determines pricing leverage, with large fleet operators extracting volume discounts while smaller carriers face premium terms for low-quantity orders.
- Airlines:Major carriers deploy fleet-wide architectures to compress maintenance windows and eliminate unscheduled events. Ultra-low-cost operators in Florida and Texas are unbundling predictive subscriptions from engine overhaul contracts to secure direct algorithm vendor relationships.
- Military:Defense end users require hardened systems certified to MIL-STD-810H environmental standards, extending validation timelines. Encrypted tactical data links and anti-jam specifications create dedicated supply channels distinct from commercial hardware.
- OEMs:Airframe and engine manufacturers integrate health monitoring into original equipment specifications.
- MRO Service Providers:Independent maintenance shops compete on proprietary diagnostic libraries and turnaround speed.
Airlines command the highest absolute spend, with MRO service providers expanding most quickly as outsourcing accelerates.
Technology:
Margin capture shifts upstream from hardware toward algorithmic layers, with machine learning and predictive modules commanding recurring revenue structures.
- Predictive Analytics:Statistical models forecast component failures from operational parameter trends, enabling condition-based maintenance regimes. FAA safety management system mandates are forcing regional carriers to adopt continuous monitoring architectures previously exclusive to major operators.
- Machine Learning:Neural architectures process unstructured sensor data to identify anomaly patterns invisible to threshold-based rules. Talent scarcity for aviation-domain ML engineers constrains development capacity and inflates compensation costs.
- Internet of Things:Connected sensor networks enable real-time data streaming to ground operations centers.
- Big Data:Fleet-scale historical repositories train fleet-wide reliability models and inform spare parts positioning.
Predictive analytics holds the largest installed base, with machine learning gaining share fastest as airlines seek failure-mode detection beyond human-engineered thresholds.
Application:
Use case maturity determines integration complexity, with performance monitoring representing baseline capability while predictive maintenance demands full-stack sensor-to-cloud deployment.
- Condition-Based Maintenance:Operational decisions trigger from real-time component health status rather than fixed calendar intervals, eliminating unnecessary inspections. Southeast narrow-body operators are consolidating procurement to streamline certification workflows.
- Predictive Maintenance:Failure forecasting enables pre-positioning of replacement components and scheduling of maintenance during planned ground time. Southwest hub concentration in Dallas-Fort Worth and Houston generates concentrated procurement volume for integrated platforms.
- Performance Monitoring:Real-time tracking of engine and airframe efficiency parameters supports fuel optimization.
- Safety Assurance:Continuous structural load monitoring validates airworthiness between scheduled inspections.
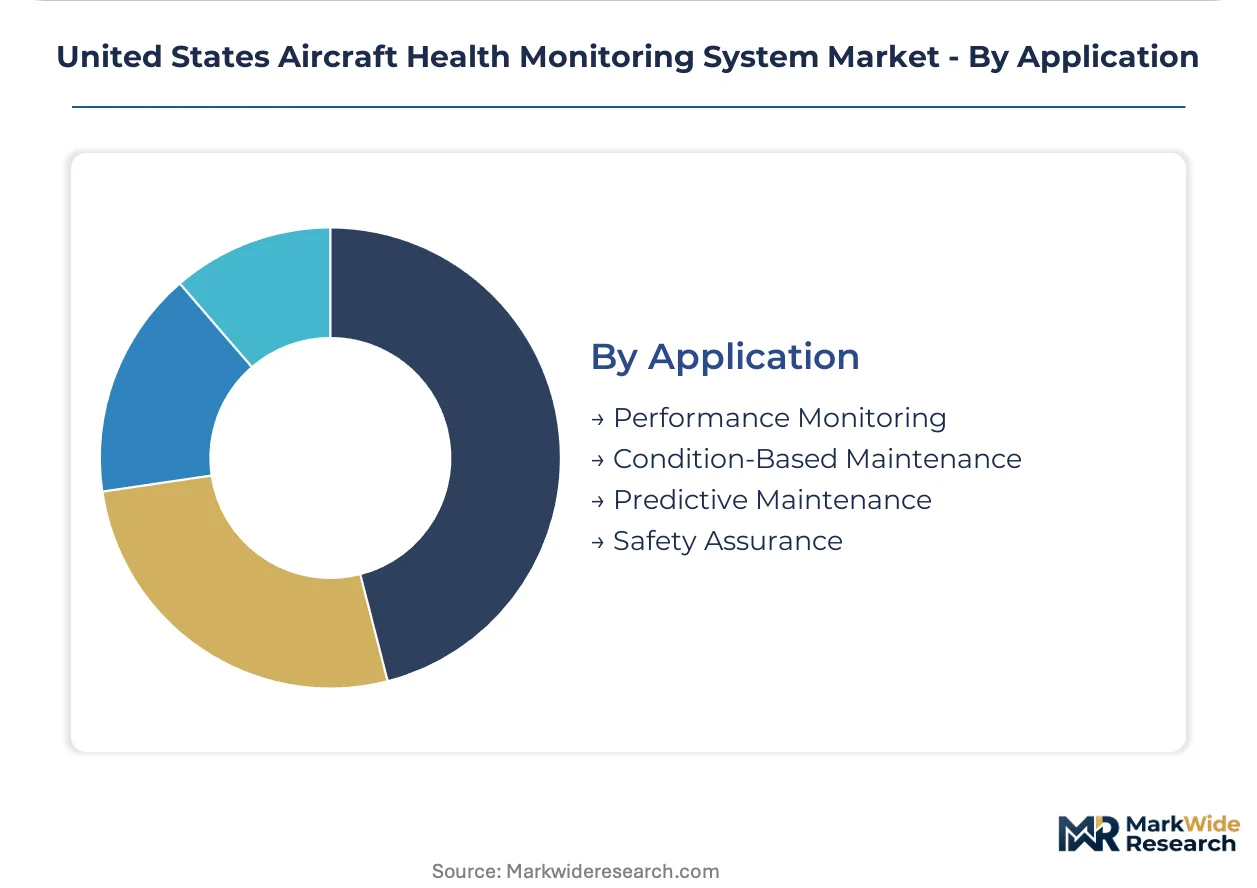
Condition-based maintenance dominates current deployment, with predictive maintenance showing the steepest expansion trajectory as digital twin architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas maintenance bases generate procurement volumes that dwarf Pacific Northwest clusters, while Florida's ultra-low-cost carrier density creates concentrated demand for integrated health monitoring platforms.
Southwest
Dallas-Fort Worth and Houston anchor the nation's densest aircraft maintenance corridor, with American Airlines and Southwest Airlines driving fleet-wide sensor retrofits. FAA continued airworthiness directives for aging narrow-body fleets accelerate hardware replacement cycles at these hubs. Texas-based defense contractors in the Dallas-Fort Worth metroplex procure hardened data acquisition systems for military aviation programs.
Southeast
Florida's high-utilization single-aisle operations generate concentrated demand for predictive maintenance subscriptions unbundled from engine overhaul contracts. The Department of Transportation safety management system mandates force regional carriers across Georgia and the Carolinas to adopt continuous monitoring architectures. Miami and Orlando maintenance bases specialize in composite airframe retrofits requiring embedded fiber-optic strain sensing infrastructure.
West Coast
California's aerospace manufacturing clusters in Los Angeles County integrate health monitoring sensors into original equipment specifications for next-generation programs. Boeing's supplier network in the Pacific Northwest embeds structural monitoring into wing and fuselage layups during production. Seattle-area engineering talent pools support algorithm development for machine learning-based prognostics.
Midwest
Illinois and Ohio maintenance facilities serve as consolidation points for legacy fleet sensor upgrades driven by ADS-B Out mandate compliance. The FAA's Parts Manufacturer Approval pathways favor domestic suppliers with established certification documentation in this region. Chicago-based airline operations centers demand real-time data streaming capabilities for fleet-wide reliability modeling.
United States Aircraft Health Monitoring System Market Key Industry Players
Domestic producers anchor the premium tier; European specialists hold adjacent positions through composite sensor integration. The vendor base stratifies across three tiers: diversified aerospace conglomerates bundling hardware with service contracts, avionics specialists controlling proprietary data bus protocols, and emerging algorithm developers unbundling predictive analytics from OEM relationships. Consolidation pressure intensifies as airlines seek single-source accountability for sensor-to-cloud deployments. Strategic moves center on backward integration into fiber-optic sensor manufacturing and exclusive partnerships with composite airframe tier-one suppliers.
Within the diversified conglomerate tier, GE Aerospace and Honeywell International Inc. occupy positions defined by installed base leverage and channel control through proprietary protocols. Safran SA exemplifies the European specialist archetype with captive production of fiber-optic strain sensors for composite monitoring. These three entities represent contrasting competitive models: turbofan bundling, avionics lock-in, and materials-integrated sensing.
| Leading Market Players |
|---|
| GE Aerospace |
| Safran SA |
| The Boeing Company |
| Curtiss-Wright Corporation |
| Teledyne Controls LLC |
| Honeywell International Inc. |
| Airbus SE |
| Meggitt PLC |
| RTX Corporation |
| Others |
Cost & Logistics Intelligence
Major airline fleet operators in the Southwest maintenance corridor command subscription-based pricing leverage through consolidated procurement volumes, compressing margins for discrete hardware vendors while rewarding integrated sensor-to-cloud platform providers.
Pricing Analysis
Capacity additions in Texas and Florida are reshaping price floors for data acquisition units as regional carriers consolidate orders to reduce FAA certification documentation burden. Three-tier pricing structure across premium, standard, and economy levels separates MIL-STD-810H certified military systems from commercial aviation hardware and uncertified aftermarket components. Price differentiation rests on certification tier and volume scale, with ultra-low-cost carriers in Florida extracting steep discounts for fleet-wide deployments. Margins are tightening due to unbundling pressure as airlines seek direct algorithm vendor relationships outside OEM engine overhaul contracts. Regional Part 121 operators with sub-fifty aircraft fleets exhibit highest price sensitivity, while defense procurement programs demonstrate lowest sensitivity due to anti-jam and encrypted tactical data link requirements.
Supply Chain Analysis
Refurbishment flows for legacy ARINC 429 interface hardware create secondary supply channels that compete with new ethernet-based sensor network deployments. Fiber-optic strain sensor production concentrates in domestic foundries near Dallas-Fort Worth and Houston, with specialized composite sensing inputs drawn from European tier-one suppliers. Raw material dependencies center on piezoelectric ceramics, single-mode optical fiber, and high-temperature aerospace-grade polymers. Single-source vulnerability in fiber-optic strain gauge manufacturing creates bottleneck risk for composite airframe monitoring retrofits. Distribution runs through FAA Parts Manufacturer Approval holders and direct OEM procurement channels, with MRO service providers increasingly sourcing through consolidated aerospace distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Texas-based suppliers leverage proximity to American Airlines and Southwest Airlines maintenance hubs to offset higher domestic labor costs against reduced logistics expenditure and faster FAA certification turnaround.
For Market Incumbents: Extend proprietary data bus protocol ecosystems to lock in airline customers against unbundling trends, while deepening backward integration into fiber-optic sensor manufacturing to capture margin pools threatened by European specialists. Channel control through ARINC 429 and MIL-STD-1553 interface dominance remains the critical defensive lever against emerging ethernet-native competitors. For New Entrants and Emerging Players: Cloud-native predictive analytics platforms offer the most penetrable entry vector, targeting regional Part 121 carriers in Georgia and the Carolinas forced into continuous monitoring adoption by Department of Transportation safety management system mandates. A direct-to-airline algorithm licensing model bypasses OEM bundled service relationships and exploits procurement fragmentation among ultra-low-cost operators. For Investors and Strategic Acquirers: Tier-one composite airframe suppliers are the most active acquirer in this space, seeking captive sensor-integrated prepreg capabilities for next-generation single-aisle programs. Long-term viability hinges on algorithm differentiation rather than hardware scale, making specialized machine learning development teams with aviation domain expertise the priority acquisition archetype. Practitioners should monitor FAA continued airworthiness directive issuance velocity for early signals of replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber-Optic Sensor Manufacturing | Captures margin pools in composite airframe monitoring while reducing dependency on limited domestic foundries. |
| Direct Airline Algorithm Licensing | Bypasses OEM bundled service models and exploits procurement fragmentation among ultra-low-cost carriers. |
| MIL-STD-810H Certification Investment | Opens encrypted tactical data link segments with extended validation timelines that deter commercial competitors. |
| Regional Carrier Platform Deployment | Addresses greenfield opportunity among Part 121 operators with fewer than fifty aircraft lacking monitoring infrastructure. |
| Digital Twin Architecture Development | Shifts revenue capture from hardware sales toward recurring subscription models across commercial and defense fleets. |
Research Approach
Multiple input streams — primary interviews with fleet engineering directors and MRO procurement managers, FAA airworthiness directive filings, and Department of Transportation safety management system compliance databases — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from SEC 10-K disclosures of diversified aerospace conglomerates, Parts Manufacturer Approval holder records, and military aviation program budget justifications. Conversations with algorithm development leads at independent software vendors and composite manufacturing engineers at tier-one suppliers informed technology adoption assumptions.
Data-stream reconciliation across sensor hardware shipment volumes, predictive analytics subscription bookings, and maintenance event frequency statistics anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type, end user procurement authority, technology maturity tier, and application use case complexity. CAGRs were derived from installed base expansion rates and replacement cycle compression under continued airworthiness mandates, with specific weighting applied to edge-computing architecture adoption curves and machine learning prognostics penetration patterns.
The model assumes a particular technology adoption path; alternative pathways for fiber-optic strain sensing integration into original equipment manufacturing would alter the outlook for aftermarket retrofit demand. Forecasts reflect assumptions regarding FAA directive issuance timing and defense procurement prioritization for hardened tactical data link systems. Practitioners should monitor regional carrier bankruptcy filings and fleet consolidation activity for early signals of greenfield deployment opportunity contraction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Flight Line Testing Equipment Market
Aircraft Data and Diagnostics
Aircraft Flight Recorder Market
Aircraft Data and Diagnostics
Aircraft Health Monitoring System (AHMS) Market
Aircraft Data and Diagnostics
Aerospace and Defense Telemetry Market
Aircraft Data and Diagnostics
Aircraft Control Software Market
Aircraft Data and Diagnostics
Global Connected Aircraft Solutions Market
Aircraft Data and Diagnostics
Helicopter Aeronautical Software Market
Aircraft Data and Diagnostics
Attitude and Heading Reference System (AHRS) Market
Aircraft Data and Diagnostics
Air Data Systems Market
Aircraft Data and Diagnostics
Automated Composite Structure Inspection Systems for Aerospace Market
Aircraft Data and Diagnostics
Commercial Aviation Crew Management Systems Market
Aircraft Data and Diagnostics
Air Data Testers Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Flight Data Monitoring Market
Aircraft Data and Diagnostics
Europe Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Air Data Calibrators Market