
 Global Human Augmentation Market | 2026-2036
Global Human Augmentation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Human Augmentation Market Foresight
Carbon fiber composites are expanding their share in exoskeleton limb structures, displacing aluminum alloys that previously dominated lower-limb frames due to fatigue-weight tradeoffs. Ekso Bionics Holdings, Inc. leverages its FDA-cleared EksoNR platform to anchor rehabilitation center penetration across North American hospital networks. Cyberdyne Inc. dominates the Japanese regulatory pathway with its HAL hybrid assistive limb system, sustaining reimbursement advantages under the country's national health insurance framework. ReWalk Robotics Ltd. competes in personal exoskeletons for spinal cord injury patients, specializing in lightweight frame designs that navigate home-use mobility requirements.
Human augmentation encompasses wearable and implantable technologies that extend, restore, or enhance physical and cognitive capabilities through electromechanical actuation, neural signal processing, or sensory overlay interfaces. Exoskeletons integrate torque-limiting servo motors with rigid kinematic chains to deliver gait-assisted locomotion for paraplegic rehabilitation and industrial load handling. Augmented reality devices command the largest addressable consumer base, though neural implants capture disproportionate R&D investment intensity as brain-computer interface protocols mature from laboratory calibration to chronic implantation standards. Medical rehabilitation applications lead volume deployment, while military and defense segments concentrate margin pools through classified procurement channels and performance-specification contracting.
FDA breakthrough device designation and the EU AI Act's high-risk system classification jointly determine market access timelines for neural implant and autonomous exoskeleton developers, with CE marking under MDR requirements adding European validation costs. Japan's PMDA operates a separate sakigake fast-track pathway that accelerates domestic approval for B-Temia Inc.'s Keeogo powered orthosis, creating regulatory arbitrage opportunities for firms with multi-jurisdiction filing capabilities. Stakeholders must monitor divergence between FDA's risk-based software-as-medical-device framework and emerging EU algorithmic transparency mandates, as compliance strategy choices made now will lock in territorial competitive positioning before standards crystallize.
Market Dynamics
Neural signal processing hardware is compressing the latency gap between cortical intention and electromechanical response, forcing exoskeleton and implant developers to redesign control architectures around real-time edge computing rather than cloud-dependent inference.
Growth Catalysts
- FDA Breakthrough Device Designation:The pathway accelerates clinical validation timelines for brain-computer interface developers, reducing pre-market review periods for neural implant candidates targeting paralysis restoration.
- Carbon fiber composite adoption:Advanced polymer matrices are displacing aluminum in lower-limb exoskeleton frames, cutting fatigue-weight ratios by half and enabling longer ambulation sessions for rehabilitation patients.
- Japanese national health insurance:Reimbursement coverage for powered orthoses under the PMDA sakigake fast-track creates sustainable revenue streams for wearable robotics vendors serving aging populations.
Market Restraints
- Titanium alloy supply concentration:Cranial implant fabrication depends on specialized biomedical-grade titanium suppliers concentrated in a limited set of foundries, exposing neural device manufacturers to input volatility.
- EU AI Act high-risk classification:Autonomous exoskeletons with adaptive gait algorithms face mandatory conformity assessments under MDR requirements, extending European market access timelines by 18-24 months.
- Invasive surgery requirement:Utah array and stentrode electrode technologies demand neurosurgical implantation, limiting addressable patient populations to tertiary medical centers with specialized surgical capacity.
Strategic Opportunities
- Industrial load-bearing exoskeletons:Logistics and warehousing operations in Germany present underpenetrated demand for passive and powered back-support systems reducing musculoskeletal injury rates.
- Non-invasive BCI peripherals:EEG-based control interfaces for gaming and productivity applications bypass regulatory barriers facing implantable devices, opening consumer revenue streams.
- Dual-use military-civilian technology transfer:DARPA-funded powered exoskeleton programs for infantry load carriage spin out hardware architectures adaptable to construction and emergency response applications.
Industry Challenges
- Neuroelectrode engineering talent scarcity:The intersection of materials science, signal processing, and neurobiology commands premium compensation, constraining R&D team scaling for mid-stage ventures.
- Chronic biocompatibility validation:Neural implants must demonstrate stable performance across multi-year implantation periods, requiring longitudinal clinical studies that compress cash runway.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Human Augmentation Market |
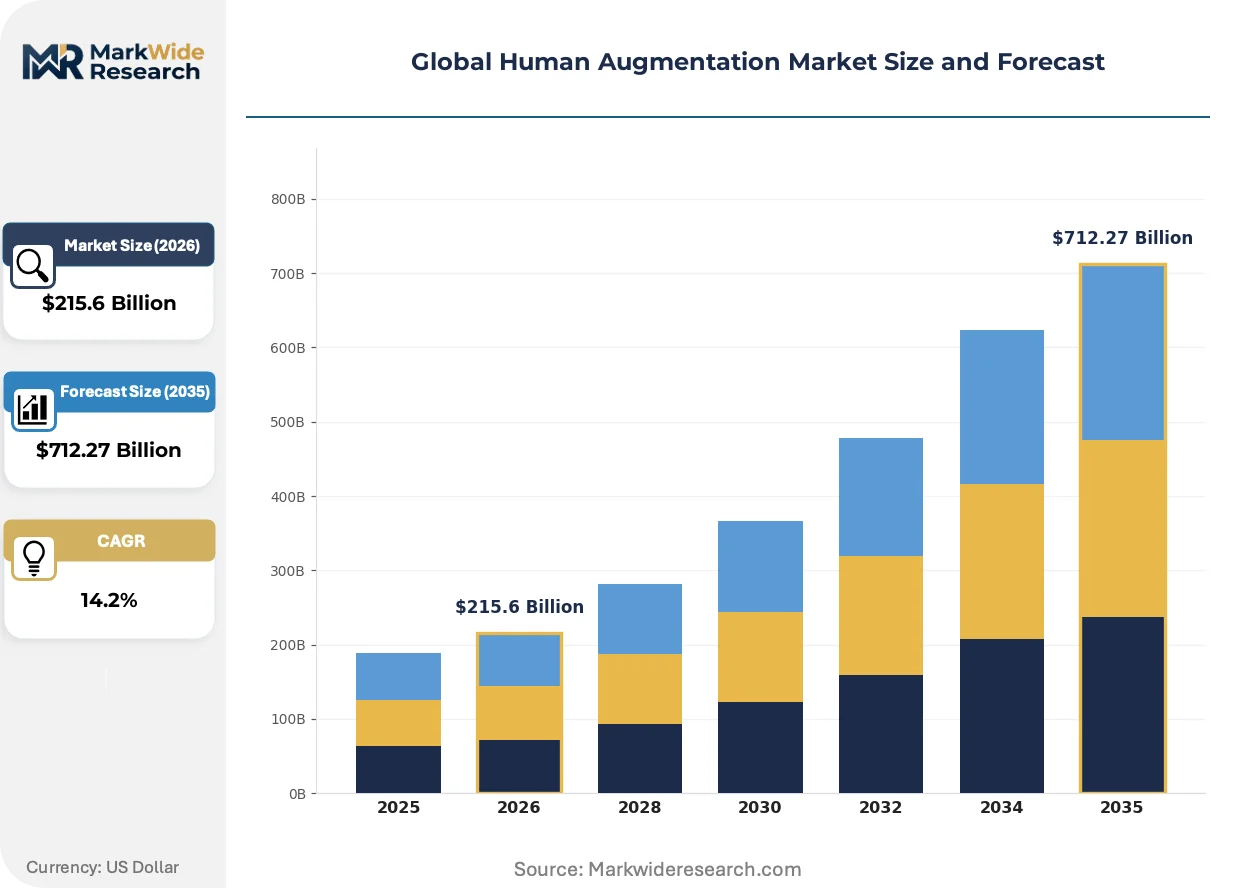
| Market Size in 2026 | $215.6 Billion |
| Market Size in 2035 | $712.27 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exoskeletons, Neural Implants, Augmented Reality Devices, Prosthetics, Wearable Robots Application: Military & Defense, Manufacturing Assistive, Sports Performance, Medical Rehabilitation, Entertainment End User: Defense Personnel, Factory Operators, Athletes, Physical Therapists, Gamers Deployment Mode: On-Premises, Cloud-Based Platforms, Edge Computing, Hybrid Systems |
| Companies Covered | Ekso Bionics Holdings, Inc., ReWalk Robotics Ltd., Cyberdyne Inc., Samsung Electronics Co., Ltd., Google LLC, Vuzix Corporation, B-Temia Inc., Magic Leap, Inc., Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Human Augmentation Market Shifts & Advancements
Silicon carbide power electronics and soft polymer actuators are converging to reshape electromechanical architectures across both wearable and implantable augmentation platforms.
Soft pneumatic artificial muscles are rewriting force-to-weight benchmarks for upper-limb exoskeletons. Rehabilitation centers in the United States and Japan are piloting fabric-based actuation systems that eliminate rigid kinematic chains. This technology is compressing device costs and enabling home-use form factors previously unattainable with servo motor arrays.
The EU AI Act's high-risk system classification for autonomous medical devices is forcing algorithmic transparency documentation for adaptive exoskeleton control systems. Developers must now submit technical files demonstrating interpretability of machine learning gait models. European neural implant ventures are responding by segregating training data governance functions into standalone compliance subsidiaries.
Hospital procurement departments are unbundling hardware acquisition from rehabilitation service contracts. North American health networks now lease exoskeleton units with per-session usage fees rather than capital purchases. This shift concentrates vendor relationships around service delivery capabilities and remote monitoring infrastructure rather than device manufacturing scale.
Global Human Augmentation Market Segmentation
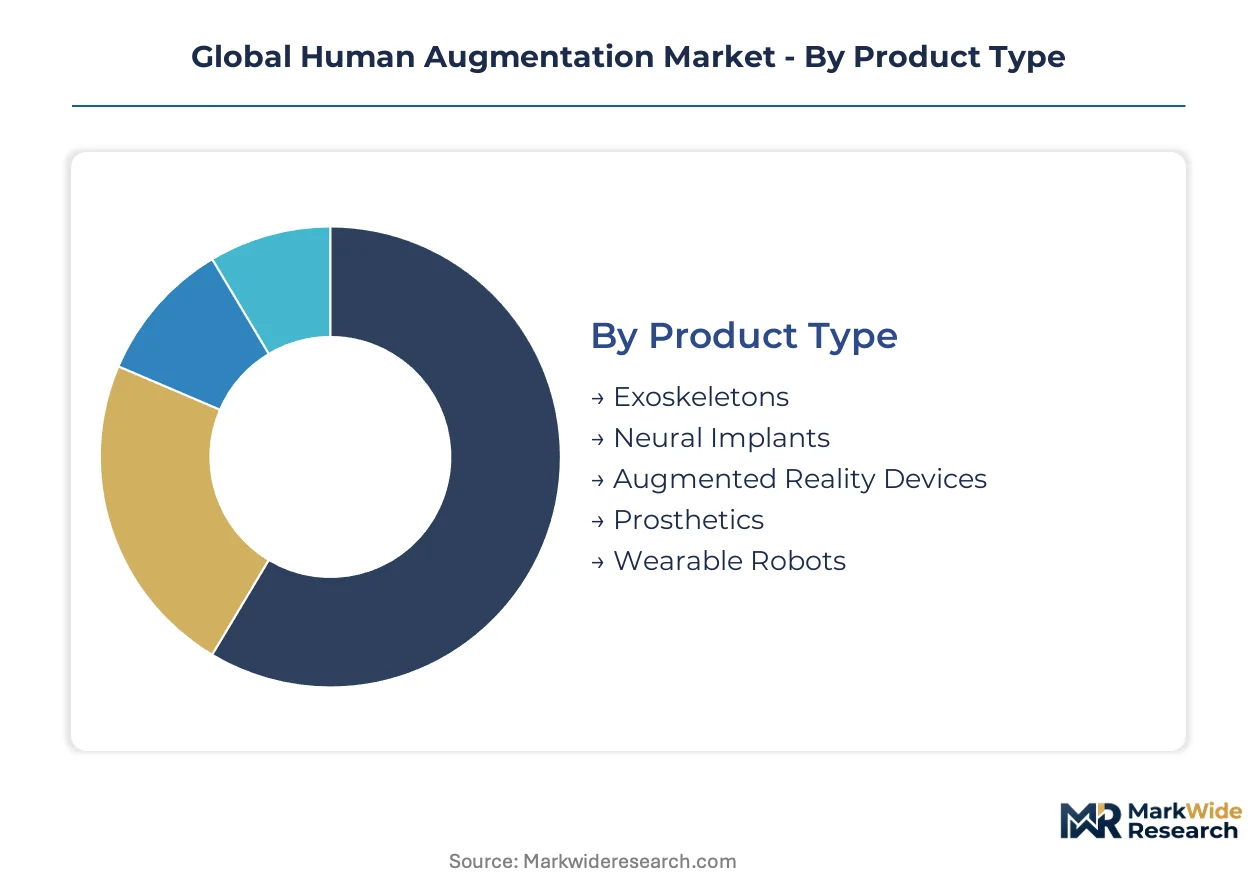
Human augmentation technologies span electromechanical, neural, and sensory interface domains with divergent regulatory pathways. FDA breakthrough designation, EU AI Act high-risk classification, and Japan's PMDA sakigake fast-track create tiered certification burdens across product categories. Segmentation reveals which configurations concentrate R&D investment versus which capture volume deployment.
Product Type:
FDA breakthrough device designation concentrates on neural implants and autonomous exoskeletons, while augmented reality devices face lighter software-as-medical-device scrutiny. CE marking under MDR requirements adds European validation costs for implantable electrodes and powered orthoses.
- Exoskeletons:Rigid kinematic chains integrate torque-limiting servo motors with carbon fiber composite frames for gait-assisted locomotion. Demand clusters in North American hospital networks for paraplegic rehabilitation and German logistics operations for load-bearing injury prevention. FDA 510(k) clearance and EU MDR conformity assessments dominate market access timelines.
- Neural Implants:Utah array and stentrode electrode technologies demand neurosurgical implantation with chronic biocompatibility validation across multi-year periods. R&D investment concentrates in Boston and San Francisco clusters around DARPA-funded brain-computer interface programs. Invasive surgery requirements limit addressable populations to tertiary medical centers.
- Augmented Reality Devices:Consumer-facing sensory overlay interfaces command the largest addressable user base with lighter regulatory burdens.
- Prosthetics:Myoelectric and body-powered limb replacements serve traumatic injury and congenital deficiency populations.
- Wearable Robots:Soft pneumatic artificial muscle systems enable fabric-based upper-limb actuation for home-use form factors.
Exoskeletons sit at the top of the volume ranking, with neural implants climbing the fastest.
Application:
Cost tier stratification separates classified military procurement from reimbursed medical rehabilitation and out-of-pocket consumer purchases. Performance-specification contracting in defense segments commands premium pricing against standardized clinical protocols.
- Medical Rehabilitation:Hospital procurement departments unbundle hardware acquisition from service contracts, shifting toward per-session leasing models. North American health networks and Japanese national health insurance reimbursement sustain revenue visibility for powered orthoses. Remote monitoring infrastructure becomes a competitive differentiator.
- Military & Defense:NATO member states accelerate powered exoskeleton procurement for infantry load-bearing operations through classified channels. DARPA-funded programs spin out hardware architectures adaptable to civilian construction and emergency response. Margin pools concentrate here through performance-specification contracting.
- Manufacturing Assistive:Passive and powered back-support systems target musculoskeletal injury reduction in warehousing and assembly operations.
- Sports Performance:Wearable robotics and sensory feedback systems serve professional and amateur athlete training regimens.
- Entertainment:Non-invasive BCI peripherals and haptic interfaces target gaming and immersive experience applications.
Medical rehabilitation captures the largest volume base, while military and defense segments concentrate the highest margin pools.
End User:
Customer type determines procurement authority structure, from defense acquisition offices to hospital supply chain departments to individual consumer purchases.
- Physical Therapists:Clinical operators drive rehabilitation center adoption with per-session usage models replacing capital purchases. Training requirements and technical support demands shape vendor selection criteria. Service delivery capabilities outweigh device manufacturing scale in procurement decisions.
- Defense Personnel:Load-bearing exoskeleton deployment requires interoperability with existing tactical equipment and battlefield durability standards. Procurement runs through defense acquisition offices with extended validation timelines. Dual-use technology transfer creates civilian market spillover.
- Factory Operators:Industrial users demand musculoskeletal injury prevention through passive and powered assistive systems.
- Athletes:Performance optimization drives adoption of wearable robotics and sensory feedback training systems.
- Gamers:Consumer segment purchases non-invasive BCI peripherals and haptic interfaces for entertainment applications.
Physical therapists represent the most concentrated volume demand, with defense personnel generating the steepest expansion trajectory.
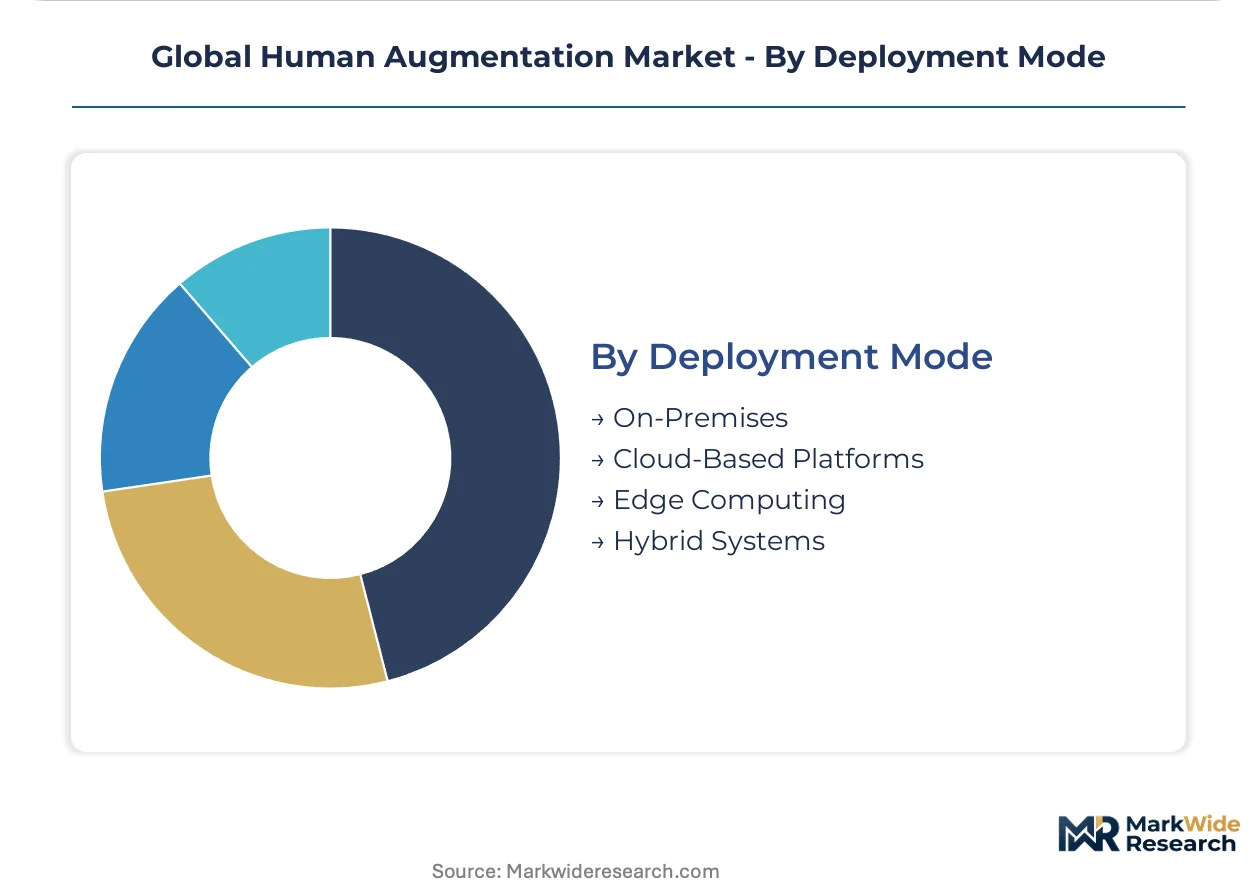
Deployment Mode:
Latency requirements and data sovereignty concerns drive architecture selection between cloud-dependent inference and real-time edge computing.
- Edge Computing:Neural signal processing hardware compresses latency between cortical intention and electromechanical response. Exoskeleton and implant developers redesign control architectures around real-time local processing rather than cloud-dependent inference. EU AI Act algorithmic transparency mandates complicate distributed learning approaches.
- Cloud-Based Platforms:Remote monitoring infrastructure supports rehabilitation service contracts with usage-based pricing models. Data governance functions segregate into standalone compliance subsidiaries for European market access. Longitudinal performance tracking enables predictive maintenance.
- On-Premises:Localized systems serve facilities with data sovereignty requirements or limited connectivity.
- Hybrid Systems:Architectures combine edge responsiveness with cloud analytics for adaptive algorithm training.
Edge computing sits at the top of the volume ranking, with hybrid systems climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston and San Francisco anchor neural implant R&D concentration, while Tokyo and Osaka sustain powered orthosis commercialization through national reimbursement frameworks.
United States
DARPA-funded brain-computer interface programs and FDA breakthrough device designation accelerate clinical validation timelines for neural implant developers. The FDA's risk-based software-as-medical-device framework streamlines market access for autonomous exoskeleton candidates. Boston and San Francisco clusters concentrate venture-backed neurotechnology firms and military-civilian technology transfer programs.
Germany
Logistics and warehousing operations generate underpenetrated demand for passive and powered back-support exoskeletons targeting musculoskeletal injury reduction. The EU AI Act's high-risk system classification and MDR conformity assessments extend market access timelines for adaptive gait algorithms. Industrial automation hubs in Bavaria and North Rhine-Westphalia pilot manufacturing assistive deployments.
Japan
Aging population demographics sustain reimbursement coverage for powered orthoses under the PMDA sakigake fast-track pathway. METI coordinates national health insurance frameworks with robotics commercialization priorities. Tokyo and Osaka metropolitan areas concentrate Cyberdyne Inc.'s HAL hybrid assistive limb system deployment and rehabilitation center networks.
Switzerland
Swissmedic operates parallel regulatory pathways for cranial implant fabrication using biomedical-grade titanium alloys. Precision manufacturing capabilities in the Basel region and Zurich cluster support neural device component supply chains. The country's pharmaceutical and medtech infrastructure attracts implant developers seeking European validation anchor points.
South Korea
MFDS fast-track designations for wearable robotics align with national smart healthcare initiatives. Seoul Capital Area concentrates consumer electronics integration capabilities for augmented reality device manufacturing. Government-funded research institutes in Daejeon-Sejong collaborate with industrial partners on soft actuator development programs.
Global Human Augmentation Market Competitive Landscape
Strategic partnerships dominate the current landscape as developers seek regulatory expertise and distribution infrastructure. The vendor base fragments across venture-backed neural implant specialists, diversified electronics conglomerates, and rehabilitation-focused exoskeleton pure-plays. Two archetypes define competitive positioning: FDA-cleared medical device incumbents with hospital network relationships, and dual-use technology spinouts from defense research programs. M&A activity concentrates on algorithmic control software assets, while geographic expansion targets Japanese and German reimbursement jurisdictions.
Within the rehabilitation-focused tier, Ekso Bionics Holdings, Inc. and ReWalk Robotics Ltd. exemplify FDA-cleared platform strategies, while Cyberdyne Inc. occupies a distinct position through Japanese regulatory pathway dominance. These three firms represent contrasting geographic anchoring approaches—North American hospital network penetration, personal exoskeleton specialization, and national insurance reimbursement integration respectively.
| Leading Market Players |
|---|
| Ekso Bionics Holdings, Inc. |
| ReWalk Robotics Ltd. |
| Cyberdyne Inc. |
| Samsung Electronics Co., Ltd. |
| Google LLC |
| Vuzix Corporation |
| B-Temia Inc. |
| Magic Leap, Inc. |
| Microsoft Corporation |
| Others |
Supply & Pricing Matrix
Biomedical-grade titanium alloy feedstock moves through Swiss and Japanese precision foundries before reaching cranial implant fabricators, with carbon fiber composite prepregs from German and US suppliers feeding exoskeleton limb production. Input cost pass-through varies by tier: FDA-cleared neural implants absorb specialty material premiums into value-based hospital contracts, while industrial load-bearing systems face commodity aluminum pricing pressure.
Pricing Analysis
Input-cost pass-through operates asymmetrically across product tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated neural implants from CE-marked rehabilitation exoskeletons and unclassified consumer peripherals. Price differentiation hinges on certification level — FDA 510(k) versus MDR conformity — and after-sales service bundling. Pricing pressure stems from carbon fiber composite oversupply in aerospace-adjacent supply chains compressing frame material costs. Hospital procurement committees show highest price sensitivity, while defense acquisition offices tolerate premium positioning for performance-specification load-bearing systems.
Supply Chain Analysis
Neuroelectrode fabrication rests on biomedical-grade titanium suppliers concentrated in Switzerland, Japan, and select US specialty foundries. Control electronics draw from South Korean semiconductor packaging facilities and Taiwanese fabless design houses. Soft pneumatic actuators source from German polymer engineering specialists and Japanese precision rubber processors. Single-source vulnerability concentrates in Utah array electrode substrate supply, where two foundries dominate cranial implant-grade material output. Distribution runs through hospital GPO contracts in North America, national health insurance procurement channels in Japan, and defense acquisition offices for NATO military programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Human Augmentation Market reads as a late-cycle quality story. Rehabilitation centers and defense agencies alike are shifting procurement specifications toward chronic biocompatibility validation and real-time edge computing latency benchmarks.
For Market Incumbents: Extend FDA-cleared platform positions into remote monitoring service contracts before hospital procurement departments complete their shift toward per-session leasing models. Cyberdyne Inc.'s Japanese reimbursement integration and Ekso Bionics Holdings, Inc.'s North American hospital network relationships exemplify defensible channel control. Counter emerging soft actuator specialists by acquiring algorithmic gait control software assets. Certification investment in EU MDR conformity assessments locks in European positioning before algorithmic transparency mandates crystallize. For New Entrants and Emerging Players: The premium-economy price-point gap in industrial load-bearing exoskeletons opens white-space targeting for German logistics operations and warehousing injury prevention programs. Non-invasive BCI peripherals for gaming and productivity applications bypass invasive surgery regulatory barriers facing implantable devices. Target acquisition profile centers on algorithmic control software assets with adaptive gait modeling capabilities. Go-to-market positioning as construction and emergency response spinouts from DARPA-funded military programs builds technical credibility without defense procurement timeline exposure. For Investors and Strategic Acquirers: Consolidation pressure builds where neuroelectrode engineering talent scarcity constrains R&D team scaling for mid-stage ventures. Long-term viability favors platforms with multi-jurisdiction regulatory filing capabilities spanning FDA breakthrough designation, EU MDR conformity, and Japan PMDA sakigake fast-track pathways. Acquisition target archetype: mid-cap ventures with chronic biocompatibility validation datasets and hospital system pilot contracts. Watch neural signal processing hardware latency benchmarks as the inflection indicator for control architecture redesign cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy Development | Japan's PMDA sakigake fast-track creates sustainable revenue visibility for powered orthosis vendors. |
| Algorithmic Control Software Acquisition | Adaptive gait modeling assets concentrate competitive differentiation as EU AI Act transparency mandates tighten. |
| Remote Monitoring Infrastructure Buildout | Hospital procurement unbundling makes service delivery capabilities outweigh device manufacturing scale in vendor selection. |
| Dual-Use Technology Spinout Formation | DARPA-funded infantry load carriage programs yield hardware architectures adaptable to civilian construction applications. |
| CE Marking Pathway Investment | EU MDR conformity assessments extend European market access timelines, rewarding early filing commitment. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's regulatory and procurement stakeholder base. Primary interviews with rehabilitation center clinical operators, hospital GPO contracts managers, defense acquisition officers, neural implant biomedical engineers, and exoskeleton manufacturing procurement leads combined with secondary validation. Secondary sources include FDA 510(k) and breakthrough device designation filings, EU MDR technical documentation databases, Japan PMDA sakigake approval records, hospital procurement contract repositories, and defense research program budget disclosures. Bottom-up unit deployment estimates triangulated against top-down addressable population modeling.
Rate-of-change decomposition across the analysis window isolates volume drivers from pricing dynamics and mix shifts. Segmentation dimensions modeled include product type, application, end user, and deployment mode, with neural signal processing latency tier and chronic biocompatibility validation status as industry-specific stratifiers. CAGRs derived from logistic diffusion curves fitted to reimbursement coverage expansion and military procurement cycle timing. Forecast inputs incorporate carbon fiber composite cost trajectories, neurosurgical capacity constraints at tertiary medical centers, and EU AI Act implementation timeline uncertainty.
Caveats apply where titanium alloy supply concentration, EU algorithmic transparency mandate enforcement intensity, or neural implant chronic biocompatibility study outcomes could materially shift the outlook. Forecasts reflect assumptions about regulatory pathway continuity and defense procurement priority stability. A small set of named triggers — PMDA reimbursement expansion decisions, FDA software-as-medical-device framework evolution, and DARPA program budget reallocation — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Wood Stoves Market
Others
Global Thermally Conductive Grease Market
Others
Edible Insects for Animal Feed Market
Others
Smart-Connected Power Plug Socket Market
Others
Middle East & Africa Air Insulated Switchgear Market
Others
North America Astrology Market
Others
Receiving Scales Market
Others
Europe Meditation Market
Others
Delumper Market
Others
Singapore Retail Market
Others
Asia Pacific Contract Packaging Market
Others
High Voltage Measuring Equipment Market
Others
Duty Free Retail Market
Others
Global Luxury High End Furniture Market
Others
Infant Positioning Aids Market
Others
Sprockets Market