
 United States Flexible Plastic Packaging Market | 2026-2036
United States Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States Flexible Plastic Packaging Market Insights
FDA food-contact notification compliance is bifurcating the supplier base into qualified and non-qualified tiers. Berry Global Group leverages multi-layer coextrusion capabilities to sustain institutional supply relationships. Sealed Air Corporation anchors its position through integrated barrier film technologies. Amcor Group GmbH differentiates via pharmaceutical-grade cleanroom production protocols.
United States flexible plastic packaging comprises polymer-based structures—typically polyethylene, polypropylene, or laminated constructions between 0.5 and 10 mils thick—engineered to conform to product geometry while providing moisture, oxygen, and light barriers. These materials replace glass, metal, and rigid plastics across distribution chains to reduce shipping weight and shelf-space requirements. Pouches capture the fastest structural expansion as retort and spouted formats displace cans and bottles in shelf-stable food segments. Polyethylene retains volume dominance in bags and wraps for grocery and industrial applications. Biodegradable materials occupy a narrow but strategically significant niche as brand owners face extended producer responsibility pressures.
FDA food-contact regulations, EPA resin identification and recycling standards, and state-level extended producer responsibility frameworks in California and Maine collectively determine material permissibility and design constraints. California's SB 54 mandates source reduction and recyclability benchmarks that redirect R&D spending toward mono-material structures. Stakeholders must monitor state legislative divergence and preemption litigation to avoid fragmented compliance architectures.
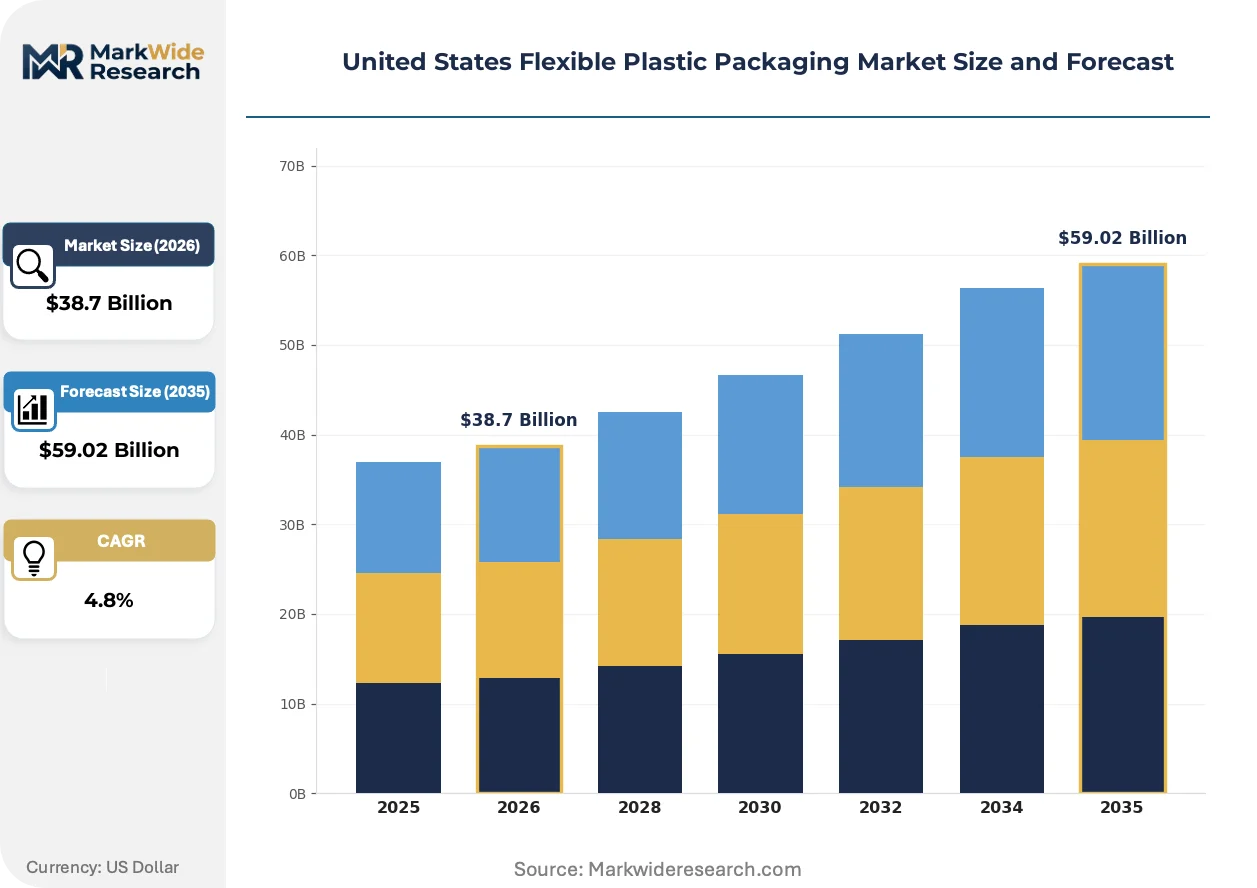
Market Dynamics
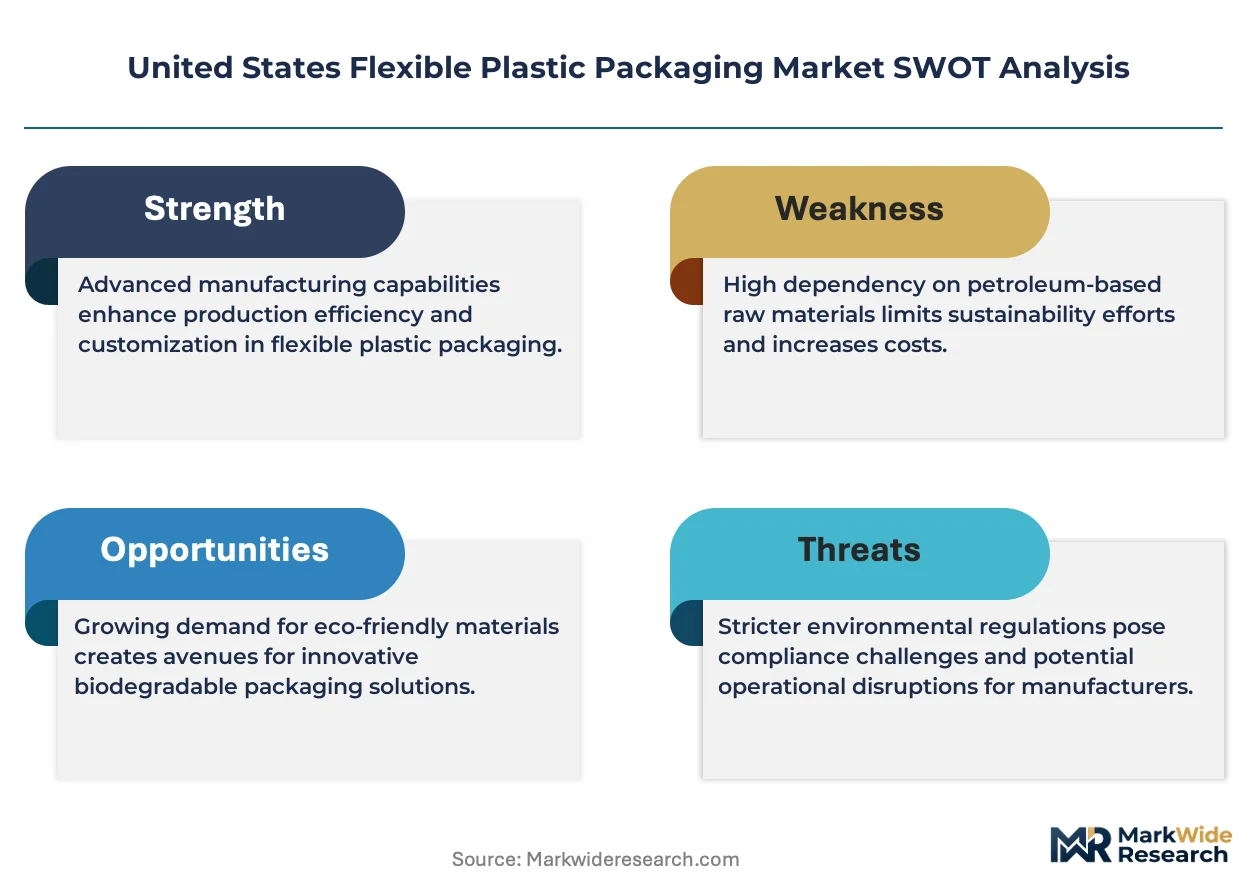
California's SB 54 mandates are forcing a wholesale redesign of multi-layer flexible packaging structures toward mono-material recyclability, compressing qualification timelines and redirecting capital from barrier performance toward sortability engineering.
Growth Catalysts
- Retort pouch adoption:Shelf-stable food processors are abandoning metal cans for high-barrier pouches that reduce shipping cube and heating energy.
- Extended producer responsibility frameworks:Maine's packaging stewardship law creates compliance-driven demand for certified recyclable structures.
- Upper Midwest manufacturing corridor concentration:Wisconsin-Illinois-Michigan resin compounding and converting clusters shorten supply chains for food processors.
Market Restraints
- Ethylene feedstock volatility:Crackers along the Gulf Coast face hurricane disruption risk that propagates through polyethylene pricing.
- Multi-layer incompatibility with mechanical recycling:Current sortation infrastructure cannot separate adhesive-laminated films, limiting circular pathways.
- FDA food-contact notification delays:Novel barrier coatings face 120-day review cycles that extend new product launch timelines.
Strategic Opportunities
- Mono-material barrier films:Polyethylene-based structures with vapor-deposited coatings bypass multi-layer recycling penalties.
- Pharmaceutical cold-chain expansion:Biologics distribution growth creates demand for insulated flexible shippers with phase-change liners.
- Digital printing integration:HP Indigo and similar platforms enable SKU proliferation without plate costs, serving craft food brands.
Industry Challenges
- Barrier engineer scarcity:Fewer than two hundred specialists understand coextrusion die design and polymer rheology interaction.
- Legacy extruder retrofit costs:Nine-figure capital requirements for nine-layer lines strand mid-tier converters in commodity grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Flexible Plastic Packaging Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Wraps, Films Material: Polyethylene, Polypropylene, PVC, Biodegradable Application: Food Packaging, Personal Care, Pharmaceuticals, Industrial End User: Retail, Manufacturing, Healthcare, E-Commerce |
| Companies Covered | Sonoco Products Company, Sealed Air Corporation, Berry Global Group, C-P Flexible Packaging, American Packaging Corporation, Proampac LLC, Amcor Group GmbH, ePac Holdings LLC, Novolex Holdings Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Flexible Plastic Packaging Market Trends and Innovations
Active and intelligent packaging functions are migrating from rigid formats into flexible substrates, driven by food safety traceability mandates and e-commerce shelf-life verification requirements.
High-barrier ethylene vinyl alcohol coextrusion is displacing metallized films in snack and pet food applications. Mid-sized regional brands are adopting these structures at 15-20% annual conversion rates. The shift is compressing aluminum vapor deposition capacity utilization while expanding blown film line orders for oriented coextrusion.
EPA's forthcoming resin identification code updates will require flexible packaging to carry detectable markers for near-infrared sortation. This industrial consequence forces reformulation of black carbon-loaded films and adhesive selection. The snack food segment is responding fastest, with pilot lines running modified polyethylene terephthalate glycol detection standards.
Brand owners are consolidating supplier relationships around converters with in-house laboratory testing for migration and shelf-life validation. This consolidation is displacing arms-length purchasing of commodity films through distributors. The shift is most visible among organic and natural food companies operating direct-to-consumer channels.
United States Flexible Plastic Packaging Market Segmentation
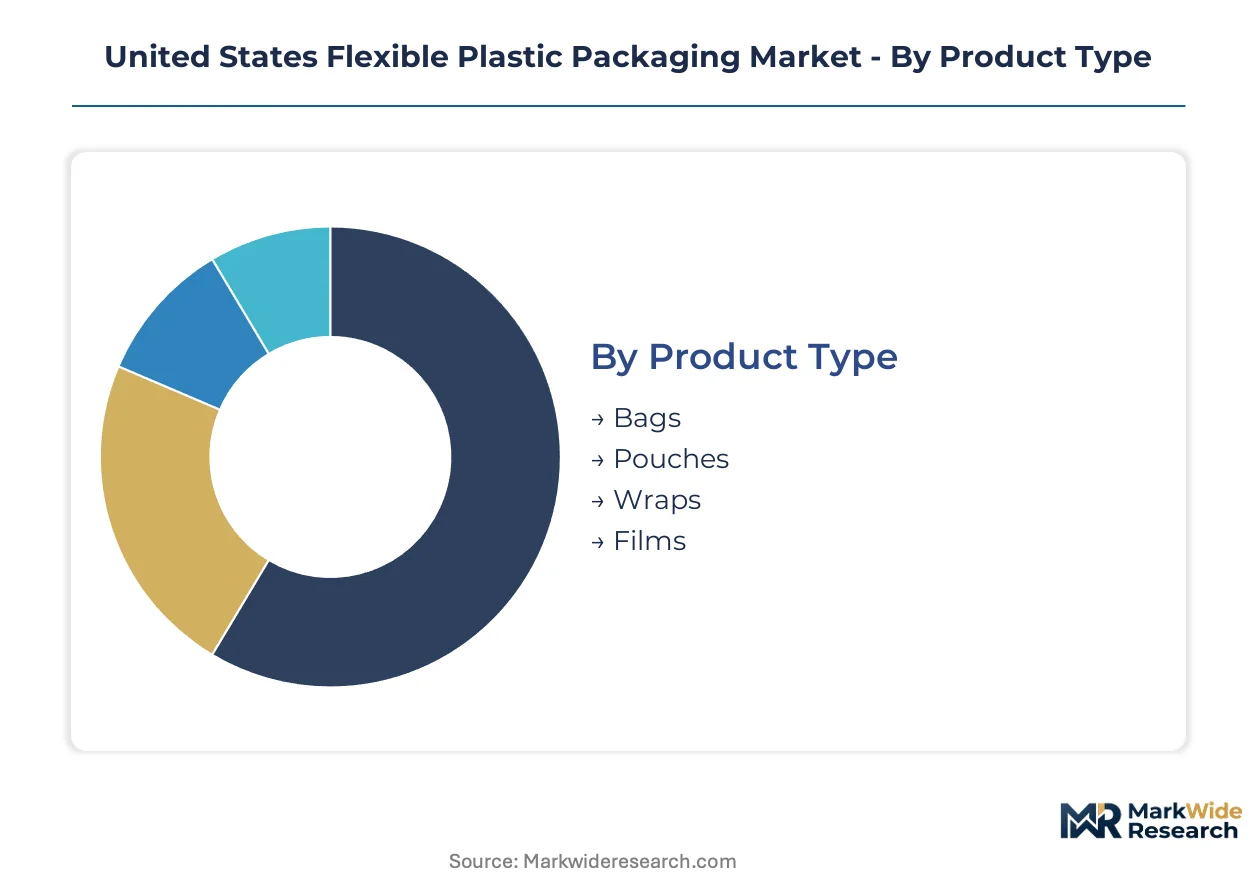
Flexible plastic packaging segmentation reveals how FDA material classifications, state recycling mandates, and end-use barrier requirements partition demand into technically distinct supply tiers. Each dimension carries compliance implications that reshape converter capabilities and customer procurement patterns.
Product Type:
FDA food-contact notification tiers separate retort-capable structures from commodity formats, with sterilization compatibility driving supplier qualification.
- Pouches:Multi-layer coextrusions with ethylene vinyl alcohol barriers enable retort sterilization for shelf-stable proteins. Wisconsin and Illinois converters dominate supply to Upper Midwest food processors converting from metal cans. FDA notification timelines for novel adhesive systems compress new entrant windows.
- Films:Blown and cast polyethylene structures between 0.5 and 10 mils thickness provide moisture and oxygen barriers for snack and produce applications. California SB 54 recyclability mandates force mono-material redesign of previously laminated constructions.
- Bags:Linear low-density polyethylene dominates grocery and industrial bulk formats with standard load-bearing specifications.
- Wraps:Cling films and stretch hoods serve palletization and fresh produce bundling with emphasis on tear propagation resistance.
Established volume favors bags; emerging adoption favors pouches.
Material:
Resin selection traces directly to EPA recycling code compatibility and state extended producer responsibility liability exposure.
- Polyethylene:Low-density and linear low-density grades anchor grocery bags, shrink films, and industrial liners. Michigan compounding clusters supply Upper Midwest converters with hurricane-disrupted Gulf Coast cracker feedstock creating price volatility.
- Biodegradable:Polylactic acid and polyhydroxyalkanoate structures address Maine packaging stewardship law compliance for certified compostable formats. Limited thermal stability restricts applications to ambient dry goods.
- Polypropylene:Oriented films provide clarity and stiffness for snack and confectionery with higher melting points than polyethylene.
- PVC:Remains in shrink sleeve and medical blister applications despite recycling infrastructure limitations.
Polyethylene commands current volume; biodegradable formats climb the fastest under state EPR pressure.
Application:
Barrier performance requirements and migration testing protocols create distinct material qualification pathways across end-use categories.
- Food Packaging:Retort pouches, vacuum bags, and modified atmosphere structures require FDA food-contact substance notification for adhesives and coatings. Shelf-stable protein processors in the Upper Midwest drive demand for high-barrier coextrusion.
- Pharmaceuticals:Cleanroom-produced barrier films for blister packs and cold-chain shippers demand USP Class VI compliance and extractables testing. Biologics distribution expansion creates demand for insulated flexible shippers.
- Personal Care:Stand-up pouches for liquids and creams emphasize puncture resistance and aesthetic printing surfaces.
- Industrial:Heavy-duty sacks and drum liners prioritize load-bearing strength over oxygen barrier performance.
Food packaging anchors revenue concentration; pharmaceutical applications gain share fastest on cold-chain investment.
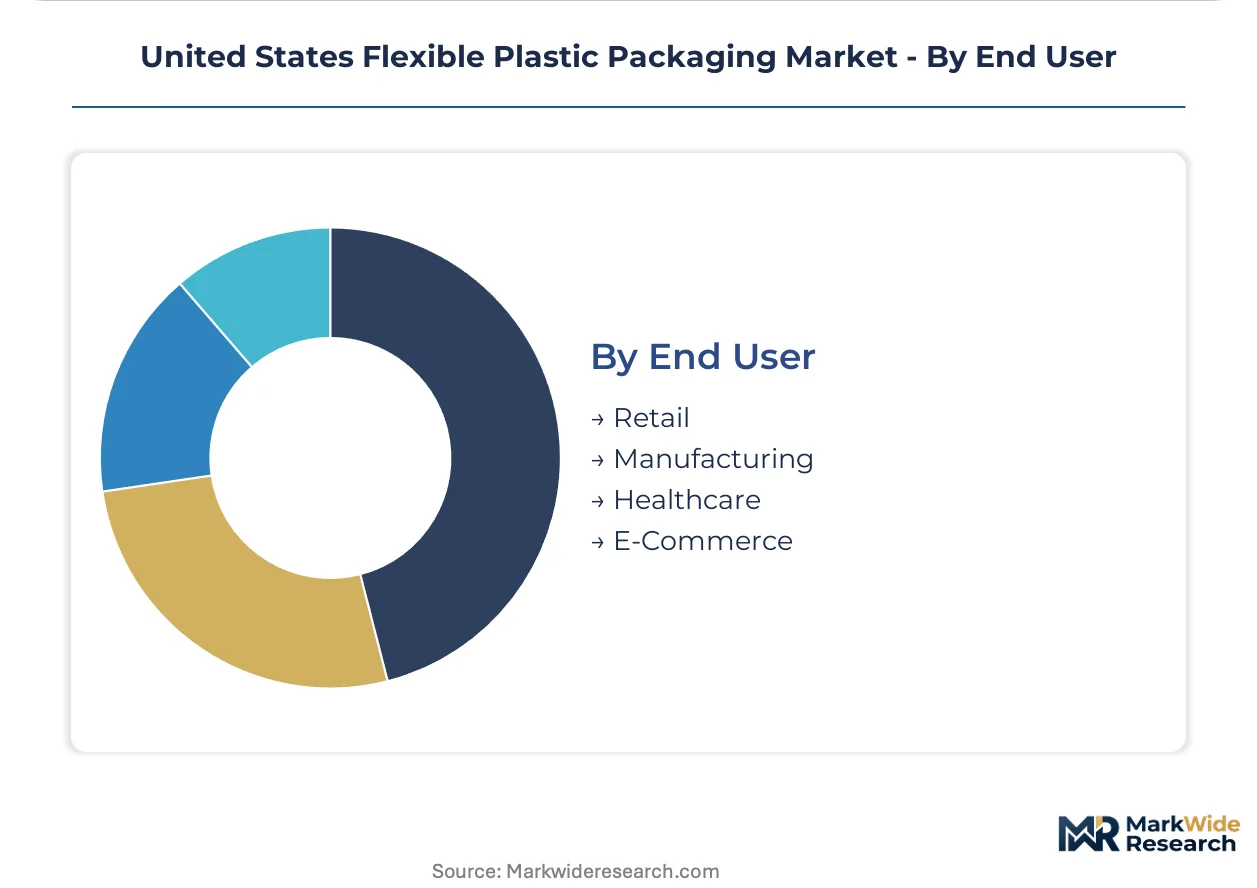
End User:
Procurement scale and technical specification authority separate direct manufacturer relationships from distributor-mediated purchasing.
- Manufacturing:Food processors and consumer goods companies specify custom barrier structures with direct converter relationships. In-house laboratory testing for migration and shelf-life validation consolidates supply around qualified tier-one converters.
- E-Commerce:Direct-to-consumer food brands drive SKU proliferation through digital printing platforms, demanding short-run flexibility without plate costs.
- Retail:Private label programs and stock keeping unit standardization favor commodity film purchasing through distributors.
- Healthcare:Hospital and pharmacy networks prioritize pharmaceutical-grade compliance documentation and lot traceability.
Manufacturing commands specification authority; e-commerce channels expand most quickly on digital printing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food processors and pharmaceutical distributors concentrate procurement authority in the Upper Midwest, Gulf Coast resin corridors, and California compliance zones. FDA notification timelines and state EPR mandates reshape supplier qualification geography. Hurricane exposure along Texas and Louisiana crackers propagates price volatility through polyethylene supply chains.
California
SB 54 mandates force mono-material redesign of multi-layer snack and produce films. The state's packaging stewardship benchmarks redirect R&D spending from barrier performance toward near-infrared detectability. Los Angeles and Central Valley converting clusters pilot modified polyethylene terephthalate glycol standards for automated sortation compatibility.
Texas
Gulf Coast ethylene crackers supply low-density polyethylene feedstock to national bag and film markets. Hurricane disruption risk concentrates procurement hedging activity among Upper Midwest converters. Houston-area resin trading desks propagate price volatility through linear low-density polyethylene contracts.
Wisconsin
Retort pouch demand from shelf-stable protein processors anchors blown film line investment. The state's food-contact laboratory infrastructure accelerates FDA notification qualification for novel adhesive systems. Milwaukee and Fox River Valley converting clusters dominate supply relationships with institutional food manufacturers.
Illinois
Chicago logistics corridors integrate flexible packaging distribution with national food processor networks. The state's compounding capacity supplies oriented polypropylene films to snack and confectionery markets. Rockford and Peoria extrusion facilities specialize in nine-layer coextrusion for high-barrier applications.
Michigan
Automotive component suppliers drive industrial liner and protective film specifications. The state's resin compounding infrastructure buffers Upper Midwest converters from Gulf Coast feedstock disruptions. Grand Rapids and Detroit-area converters serve pharmaceutical cold-chain shippers with cleanroom production protocols.
United States Flexible Plastic Packaging Market Competitive Landscape
Player mix skews toward integrated resin-to-film conglomerates and specialized mid-tier converters. The supplier base stratifies into qualified FDA-tier vendors and commodity distributors facing qualification barriers. Three archetypes dominate: multi-layer coextrusion specialists, digital printing-integrated short-run converters, and pharmaceutical-grade cleanroom operators. Competitive moves concentrate on backward integration into resin compounding and geographic expansion into California compliance zones.
Among integrated packaging conglomerates, Berry Global Group and Sealed Air Corporation exemplify the scale-driven archetype with captive multi-layer technology portfolios. Amcor Group GmbH occupies a position within the pharmaceutical-grade tier, leveraging cleanroom production protocols for barrier film applications. C-P Flexible Packaging and Proampac LLC represent the mid-tier converter segment, specializing in FDA-qualified structures for regional food processor relationships. ePac Holdings LLC anchors the digital-native archetype, serving craft food brands through short-run flexibility without plate costs.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Sealed Air Corporation |
| Berry Global Group |
| C-P Flexible Packaging |
| American Packaging Corporation |
| Proampac LLC |
| Amcor Group GmbH |
| ePac Holdings LLC |
| Novolex Holdings Inc. |
| Others |
Pricing and Supply Chain Analysis
Sixty-day FDA food-contact notification cycles compress converter inventory positions and amplify polyethylene price pass-through power for Gulf Coast resin suppliers. This lead-time compression concentrates pricing leverage upstream while forcing mid-tier converters into spot-market exposure during hurricane season disruptions.
Pricing Analysis
Cost-plus contracts indexed to Gulf Coast ethylene spot benchmarks dominate linear low-density polyethylene purchasing for Upper Midwest converters. Pricing stratifies across FDA-qualified premium tiers, standard multi-layer grades, and economy commodity films based on barrier performance certification and volume scale. Pricing pressure stems from California SB 54 compliance costs that force mono-material redesign investments. Brand-owner direct relationships show lowest price sensitivity; distributor-mediated retail procurement exhibits highest.
Supply Chain Analysis
Inbound logistics costs from Houston resin trading desks to Wisconsin converting clusters fluctuate with Gulf Coast hurricane disruption frequency and railcar availability. Raw material sourcing draws from Texas ethylene crackers, Michigan compounding facilities, and Illinois additive suppliers. Single-source vulnerability concentrates around Gulf Coast petrochemical infrastructure. Distribution runs through Chicago logistics corridors to national food processor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California's SB 54 recyclability mandates constitute a regulatory inflection that will reshape material specifications faster than converter qualification capacity can expand. This disruption creates asymmetric opportunity for prepared participants.
For Market Incumbents: Shield institutional supply relationships by accelerating in-house FDA food-contact laboratory capabilities before notification backlogs extend qualification windows. Backward integration into Michigan resin compounding buffers feedstock volatility exposure. Prioritize mono-material barrier film R&D to preempt California sortability requirements.
For New Entrants and Emerging Players: FDA fast-track notification partnerships with Wisconsin food-contact laboratories offer entry acceleration for regional craft food brands. Digital printing-integrated short-run production serves e-commerce SKU proliferation demands with minimal capital intensity. White-space concentration sits with pharmaceutical cold-chain shippers seeking USP Class VI compliant flexible shippers.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because barrier engineering talent scarcity and nine-figure extruder capital requirements strand mid-tier converters. Target acquisition archetypes include FDA-qualified regional converters with established Upper Midwest food processor relationships. Watch for EPA resin identification code finalization as inflection signal for detectable marker formulation winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier Film Development | California SB 54 compliance redirects R&D spending from multi-layer performance toward recyclability engineering. |
| FDA Food-Contact Laboratory Investment | In-house migration testing capability accelerates notification timelines and consolidates brand-owner supply relationships. |
| Digital Printing Platform Integration | HP Indigo and similar systems enable craft food brand SKU proliferation without plate cost barriers. |
| Upper Midwest Geographic Expansion | Wisconsin-Illinois-Michigan corridor proximity shortens supply chains for shelf-stable protein processors. |
| Pharmaceutical Cleanroom Certification | USP Class VI compliance opens biologics cold-chain shipper demand with premium pricing power. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with blown film plant managers, FDA regulatory affairs specialists, food processor procurement directors, and resin compounding technical leads; and secondary validation through FDA food-contact substance notification databases, EPA resin identification code proceedings, California SB 54 implementation documents, and SEC filings from integrated packaging conglomerates. Bottom-up converter capacity estimates triangulated against top-down end-use demand modeling.
Across the projection horizon, the analytical framework modeled polyethylene grade tier, packaging structure type, barrier performance specification, end-use application, and state-level regulatory compliance cluster. CAGRs derived from historical volume progression adjusted for SB 54 implementation phasing and retort pouch substitution rates. Forecast inputs incorporated ethylene cracker capacity expansion timelines and FDA notification backlog duration assumptions.
Decision-makers should treat outputs as directional under base assumptions of stable Gulf Coast petrochemical infrastructure and consistent FDA review cycle duration; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Thailand Flexible Plastic Packaging Market
Flexible Packaging
Egypt Flexible Plastic Packaging Market
Flexible Packaging
Flexible Intermediate Bulk Container Market
Flexible Packaging
Europe Flexible Plastic Packaging Market
Flexible Packaging
ASEAN Flexible Packaging Market
Flexible Packaging
Thermoforming Packaging Market
Flexible Packaging
Mexico Flexible Plastic Packaging Market
Flexible Packaging
Canada Flexible Plastic Packaging Market
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
Saudi Arabia Flexible Plastic Packaging Market
Flexible Packaging
Global Flexible Packaging Market
Flexible Packaging
Flexible Packaging Paper Market
Flexible Packaging
Flexible Paper for Food & Beverages Packaging Market
Flexible Packaging
Asia-Pacific Flexible Plastic Packaging Market
Flexible Packaging
Morocco Flexible Packaging Market
Flexible Packaging
Indonesia Flexible Plastic Packaging Market