
 UAE Flexible Packaging Market | 2026-2036
UAE Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Flexible Packaging Market Analytics
Asset-light leasing models for extrusion and printing equipment is narrowing the capital barrier for mid-tier entrants in the UAE flexible packaging sector. Huhtamaki Flexibles UAE leverages its European parent technology base to sustain premium barrier film production at its Dubai facility. Arabian Flexible Packaging LLC anchors domestic supply for regional dairy and snack brands through its integrated converting operations. Amber Packaging Industries LLC differentiates via specialized shrink film formulations serving the personal care export segment.
Flexible packaging comprises multi-layer polymer laminates, typically incorporating polyethylene, polyester, polypropylene, or biaxially oriented polypropylene substrates, engineered through coextrusion, lamination, or coating processes to deliver moisture, oxygen, and light barrier protection for shelf-sensitive goods. Stand-up pouches command expanding share among food and beverage applications due to their material efficiency and retail shelf differentiation versus rigid alternatives. Roll stock maintains stable volume through downstream converter relationships, while shrink films capture margin in personal care and electronics export bundling where optical clarity and seal integrity carry premium specifications.
MOHAP oversees food contact material safety assessments and migration testing protocols, while the Emirates Authority for Standardization and Metrology mandates UAE.GSO technical regulations aligning with Gulf Standardization Organization frameworks for plastic packaging composition and labeling. These dual compliance layers elevate testing costs but simultaneously screen out low-grade imports, reinforcing domestic converter quality positioning. Stakeholders must monitor evolving extended producer responsibility consultations and their implications for multi-material laminate recyclability design requirements.
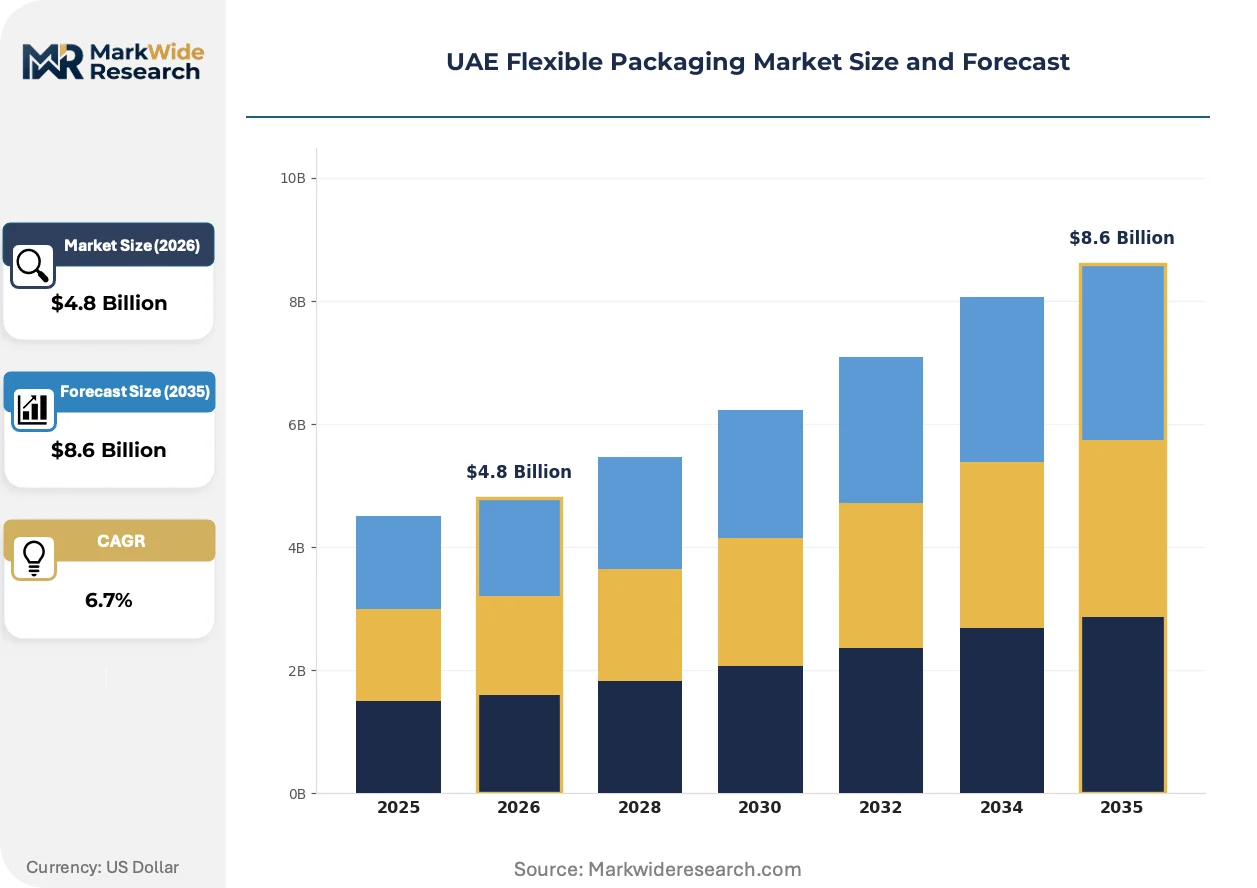
Market Dynamics
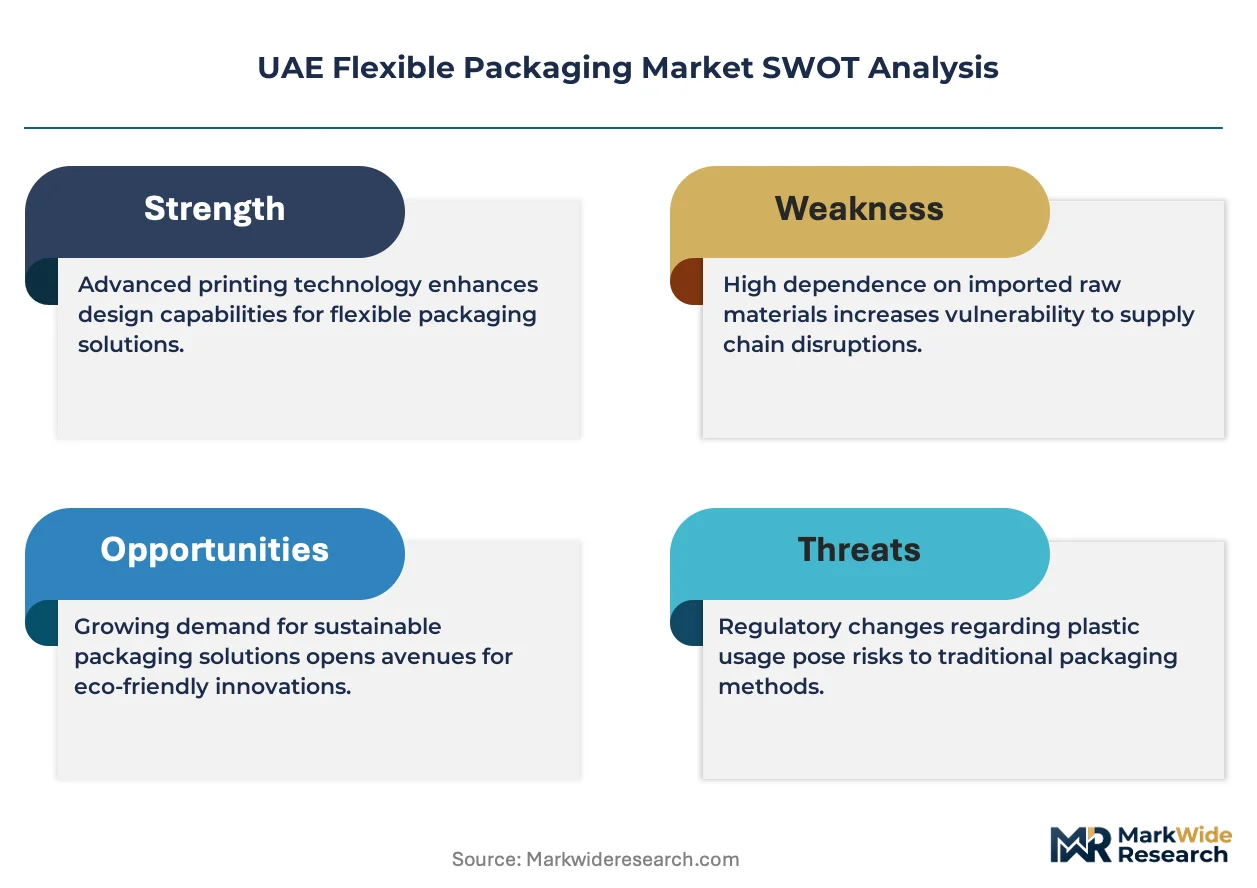
MOHAP's tightening migration limits for food contact materials are forcing converters to revalidate laminate formulations and absorb elevated testing costs, compressing margins for mid-tier players while advantaging integrated producers with captive laboratory capabilities.
Growth Catalysts
- High-barrier pouch adoption:Food and beverage manufacturers are expanding ambient-stable product lines using coextruded multi-layer structures that extend shelf life without refrigeration infrastructure.
- Jebel Ali logistics clustering:Free-zone tariff advantages and bonded warehousing capacity concentrate converter operations within Dubai's industrial corridor, reducing landed costs for re-export to GCC markets.
- UAE.GSO alignment with Gulf Standardization Organization frameworks:Technical regulations harmonizing plastic packaging composition standards across member states create scale economies for domestic producers serving regional demand.
Market Restraints
- Polymer input cost volatility:Ethylene and propylene derivative prices track naphtha feedstock swings, compressing converter margins during upstream petrochemical price spikes.
- Multi-material laminate recyclability constraints:Extended producer responsibility consultations under MOHAP review threaten to impose design-for-recycling mandates that conflict with current barrier performance specifications.
- Specialized equipment supplier concentration:High-performance printing and lamination machinery sources cluster in German and Italian manufacturing bases, exposing buyers to euro-denominated capex and extended lead times.
Strategic Opportunities
- Abu Dhabi industrial zone expansion:KIZAD free zone infrastructure investments attract secondary converter capacity seeking lower operating costs than Jebel Ali saturation permits.
- Pharmaceutical serialization integration:Track-and-trace compliance requirements for UAE pharmaceutical exports create demand for smart packaging incorporating printed electronics and variable data capabilities.
- Mono-material pouch development:Advances in oriented polyethylene film barrier properties enable single-substrate structures that satisfy emerging recyclability thresholds without sacrificing product protection.
Industry Challenges
- Migration testing specialist scarcity:MOHAP-registered analytical laboratories face capacity constraints, extending product approval timelines for new laminate introductions.
- Legacy solvent-based adhesive replacement:Waterborne and solventless lamination chemistry transitions require press retrofits and operator retraining, disrupting production continuity during conversion periods.
- Recyclability claim substantiation:Emirates Authority for Standardization and Metrology verification protocols for recyclability labeling demand third-party certification that few domestic converters currently possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Flexible Packaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Shrink Films, Roll Stock, Bags Material: Polyethylene, Polyester, Polypropylene, BOPP Application: Food & Beverage, Personal Care, Healthcare, Electronics End User: Manufacturers, Retailers, Distributors, E-Commerce |
| Companies Covered | Arabian Flexible Packaging LLC, Amber Packaging Industries LLC, Hot Pack Packaging Industries LLC, Falcon Pack Flexible Pack, Swiss Pac UAE, Integrated Plastics Packaging, Huhtamaki Flexibles UAE, Aalmir Plastic Industries LLC, ENPI Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Flexible Packaging Market Evolving Landscape
Digital printing integration and sustainable material transitions are restructuring converter investment priorities across the Emirates, with equipment financing models adapting to lower capital barriers for technology adoption.
Digital flexographic and inkjet printing systems are migrating from narrow-run label applications into primary flexible packaging production for regional dairy and snack brands seeking shorter order cycles and reduced plate costs. Mid-tier converters in Sharjah industrial zones are piloting hybrid presses combining conventional gravure cylinders with digital print stations for variable data integration. This technology migration from analog-only workflows is compressing minimum viable order quantities from hundreds of thousands to tens of thousands of units, enabling brand proliferation strategies previously uneconomical for regional players.
MOHAP's draft extended producer responsibility framework for plastic packaging waste is mandating design-for-recycling assessments and post-consumer content minimums for food-contact applications. Converter engineering teams are reformulating multi-layer structures to reduce polymer diversity and enable mechanical recycling stream compatibility without compromising oxygen and moisture barrier performance. Dairy and ambient-ready meal segments face the most acute compliance pressure given their reliance on ethylene vinyl alcohol and metallized polyester barrier layers that complicate mono-material recovery.
Brand procurement teams are consolidating supplier relationships around converters offering integrated design-to-delivery services including structural engineering, barrier modeling, and regulatory documentation. This supplier base rationalization displaces transactional spot purchasing for standard roll stock, particularly among personal care exporters seeking optical-grade shrink film with certified batch traceability. The shift is most visible among Dubai-headquartered multinational personal care brands bundling Middle East export requirements into single-source flexible packaging contracts with full quality documentation packages.
UAE Flexible Packaging Market Segmentation
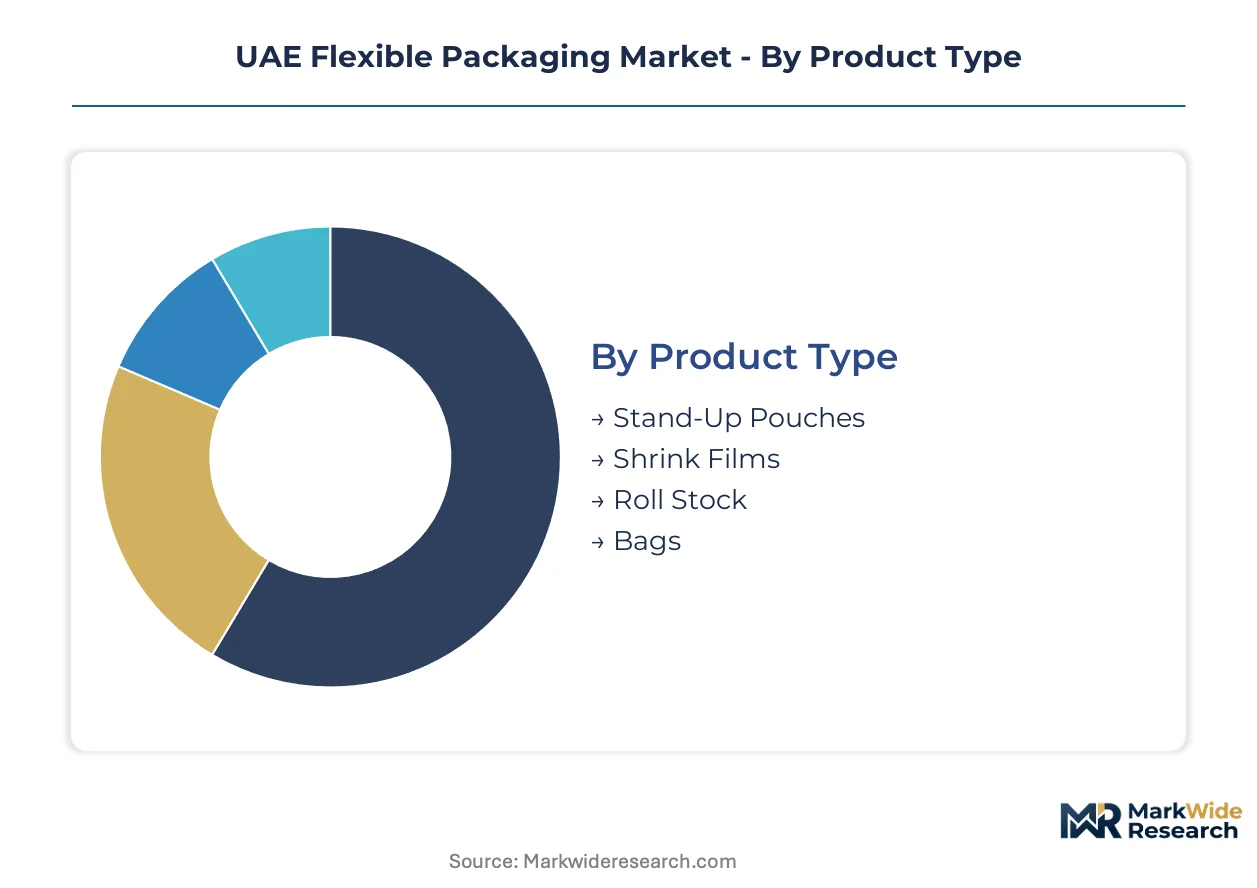
Segmentation in the UAE flexible packaging sector reveals how converter capabilities align with distinct technical requirements across food safety, barrier performance, and logistics specifications. Understanding these divides helps stakeholders identify where capital deployment and regulatory compliance investments yield competitive advantage.
Product Type:
After-sales service intensity varies sharply across product formats, with complex pouch structures demanding ongoing technical support for seal integrity and line-speed optimization while commodity roll stock requires minimal post-delivery engagement.
- Stand-Up Pouches:Multi-layer laminates incorporating zipper closures and spout fitments command premium positioning in ambient-stable food segments. Demand concentrates among Dubai-based dairy and ready-meal brands seeking shelf differentiation and extended shelf life without cold chain dependency.
- Shrink Films:Biaxially oriented polyester or polypropylene substrates deliver optical clarity and tight bundle containment for personal care export applications. Personal care exporters in Jebel Ali free zone drive volume, prioritizing batch traceability documentation and certified seal strength for retail bundling.
- Roll Stock:Unformed flexible substrates supplied to downstream converters for custom pouch and bag fabrication.
- Bags:Pre-formed open-mouth or gusseted configurations serving bulk commodity and industrial packaging needs.
The dominant share belongs to roll stock, while stand-up pouches are closing the gap fastest.
Material:
Material selection directly determines barrier performance tiers and recyclability compliance trajectories under evolving MOHAP mandates.
- Polyethylene:Linear low-density and high-density grades form the substrate foundation for moisture-resistant layers in food-contact laminates. Dairy processors in Sharjah industrial zones favor polyethylene-rich structures for their heat-seal reliability and emerging mono-material recyclability pathways.
- Polyester:Biaxially oriented polyethylene terephthalate delivers dimensional stability and print surface quality for high-graphics applications. Personal care brands specify metallized polyester variants for oxygen barrier in cosmetic sachets, though EVOH coextrusion alternatives are gaining traction amid design-for-recycling pressures.
- Polypropylene:Cast and oriented grades provide stiffness and clarity for retort and microwaveable food packaging.
- BOPP:Biaxially oriented polypropylene offers balanced mechanical properties and water vapor barrier for snack and confectionery wrapping.
Polyethylene holds the volume base, though polyester is expanding most quickly in premium barrier applications.
Application:
Application-driven segmentation reflects divergent regulatory exposure and barrier specification intensity across end-use sectors.
- Food & Beverage:The largest demand concentration spanning ambient-ready meals, dairy, snacks, and beverages requiring oxygen and moisture barrier protection. Food and beverage manufacturers in Dubai's Jebel Ali corridor are expanding high-barrier pouch adoption for shelf-stable product lines that bypass refrigeration infrastructure.
- Personal Care:Shrink films and laminated sachets for cosmetics, toiletries, and household products where optical clarity and seal integrity support retail presentation. Export-oriented personal care brands consolidate supplier relationships around converters offering certified batch traceability and full quality documentation packages.
- Healthcare:Sterile barrier systems and pharmaceutical packaging requiring compliance with serialization and track-and-trace mandates.
- Electronics:Anti-static films and protective wrapping for component shipping and retail bundling applications.
Food and beverage maintains the foundational volume position, while healthcare is climbing the fastest on pharmaceutical export compliance requirements.
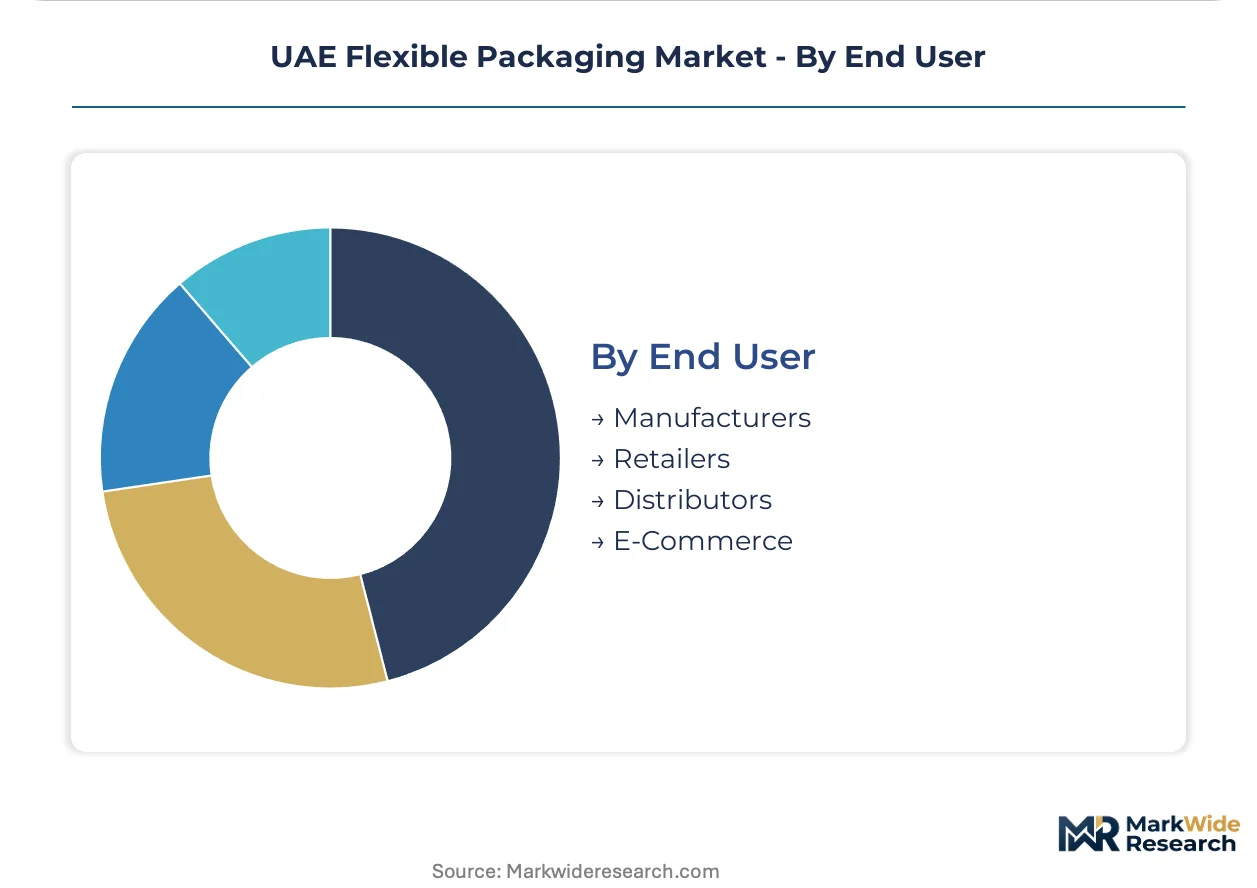
End User:
End user type shapes procurement patterns from long-term contracted supply agreements to spot purchasing and platform-integrated logistics.
- Manufacturers:Brand owners and contract packers requiring integrated design-to-delivery services including structural engineering and regulatory documentation. Regional dairy and snack brands are consolidating around converters offering barrier modeling and MOHAP compliance support.
- Retailers:Private label and store-brand packaging programs with shorter run requirements and rapid turnaround specifications. Retailer procurement teams are shifting from transactional spot purchasing to single-source flexible packaging contracts with full quality documentation.
- Distributors:Intermediary stocking and re-supply operations serving smaller regional brands and food service accounts.
- E-Commerce:Protective and presentation packaging for direct-to-consumer shipment formats.
Manufacturers command the largest procurement scale, while retailers are gaining share fastest through private label expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MOHAP's tightening food contact material regulations and KIZAD free zone incentives are redistributing converter capacity across the Emirates. Sub-regional specialization is emerging as logistics costs and compliance proximity shape facility location decisions.
Dubai
Jebel Ali industrial corridor hosts the densest converter clustering, with free-zone tariff advantages and bonded warehousing supporting re-export to GCC markets. MOHAP-registered laboratories in Dubai Science Park handle migration testing for laminate formulations. Huhtamaki Flexibles UAE operates barrier film production at its Dubai facility, leveraging European parent technology for premium pouch supply to regional dairy brands.
Abu Dhabi
KIZAD free zone infrastructure investments attract secondary converter capacity seeking lower operating costs than Jebel Ali saturation permits. The Emirates Authority for Standardization and Metrology maintains certification facilities in the capital for UAE.GSO compliance verification. Amber Packaging Industries LLC anchors specialized shrink film production serving personal care exporters from Khalifa Port logistics zones.
Sharjah
Mid-tier converters pilot hybrid digital-conventional presses in Sharjah industrial zones, compressing minimum order quantities for regional snack brands. Arabian Flexible Packaging LLC operates integrated converting facilities supplying domestic dairy and snack manufacturers. The emirate's lower industrial real estate costs support asset-light equipment leasing models for extrusion and printing machinery.
Northern Emirates
Ras Al Khaimah and Fujairah industrial zones target commodity roll stock production for downstream converter supply. Hot Pack Packaging Industries LLC maintains manufacturing presence serving bulk food service and institutional packaging demand. These locations prioritize polyethylene-rich substrate production given lower barrier specification requirements and emerging mono-material recyclability pathways.
UAE Flexible Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct value chain positions. The market exhibits tiered concentration with integrated multinational parents, domestic converters with captive laboratory capabilities, and mid-tier specialists with leased equipment models. Strategic archetypes include technology-licensed premium producers, integrated domestic suppliers, and export-focused shrink film specialists. Capacity expansion and portfolio diversification toward pharmaceutical serialization and mono-material pouch development represent dominant competitive moves.
Among UAE-based converters, Arabian Flexible Packaging LLC and Amber Packaging Industries LLC exemplify integrated domestic supply archetypes, while Huhtamaki Flexibles UAE represents technology-licensed multinational positioning. These three entities anchor distinct competitive vectors: integrated converting operations, specialized film formulations, and European parent technology transfer respectively.
| Leading Market Players |
|---|
| Arabian Flexible Packaging LLC |
| Amber Packaging Industries LLC |
| Hot Pack Packaging Industries LLC |
| Falcon Pack Flexible Pack |
| Swiss Pac UAE |
| Integrated Plastics Packaging |
| Huhtamaki Flexibles UAE |
| Aalmir Plastic Industries LLC |
| ENPI Group |
| Others |
Value Network & Pricing Analysis
Jebel Ali's bonded warehousing corridor concentrates converter logistics costs, feeding downstream price differentiation between premium barrier film producers and commodity roll stock suppliers while amplifying margin pressure on mid-tier entrants lacking free-zone tariff advantages.
Pricing Analysis
Certification level (UAE.GSO/MOHAP-registered laboratory validation) creates the primary spread between premium pouch converters and commodity suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects migration testing documentation depth and batch traceability bundling. Cost compression in standard-tier roll stock is intensifying because polyethylene input volatility transmits directly through naphtha-linked feedstock contracts. Regional dairy brands exhibit highest price sensitivity, while personal care exporters prioritize optical-grade shrink film with certified documentation regardless of premium positioning.
Supply Chain Analysis
Extended payment terms from German and Italian equipment manufacturers stretch converter working capital cycles, amplifying reliance on asset-light leasing models. Raw material supply draws from Saudi Arabia, Qatar, and Singapore for polyethylene and polypropylene resins, with specialty polyester films sourcing from South Korea and Japan. Single-source vulnerability concentrates in high-performance gravure cylinder and lamination machinery where euro-denominated capex exposes buyers to currency fluctuation. Distribution runs through Jebel Ali free-zone bonded warehousing for GCC re-export, with secondary channels serving domestic Sharjah and Abu Dhabi industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity where migration testing documentation and barrier modeling support contracts expand faster than base film supply, converting transactional roll stock relationships into recurring technical service engagements.
For Market Incumbents: Insulate premium positioning by deepening captive laboratory capabilities for MOHAP compliance validation, while extending design-to-delivery service bundles that displace spot purchasing relationships. Capacity addition in KIZAD free zone captures cost-sensitive secondary demand fleeing Jebel Ali saturation. Certification investment in mono-material pouch development defends against emerging recyclability mandates threatening multi-material laminate viability. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical serialization integration where track-and-trace compliance creates demand for smart packaging with printed electronics capabilities. Northern Emirates commodity roll stock production offers the most penetrable geography given lower real estate costs and polyethylene-rich substrate specifications. Go-to-market leverage should anchor on asset-light equipment leasing models that narrow capital barriers for extrusion and printing machinery deployment. For Investors and Strategic Acquirers: Carve-out targets emerge from European multinational parents seeking to rationalize non-core flexible packaging assets in the Gulf region. Long-term viability hinges on converters possessing integrated laboratory capabilities and MOHAP registration status that screen out low-grade import competition. The signal to watch is extended producer responsibility framework finalization and its acceleration of design-for-recycling investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Pouch Development | Advances in oriented polyethylene barrier properties enable single-substrate structures satisfying MOHAP recyclability thresholds without sacrificing product protection. |
| Pharmaceutical Serialization Integration | Track-and-trace compliance for UAE pharmaceutical exports creates demand for smart packaging incorporating printed electronics and variable data capabilities. |
| Digital Printing Technology Migration | Hybrid presses combining gravure cylinders with digital stations compress minimum order quantities from hundreds of thousands to tens of thousands for regional brands. |
| KIZAD Free Zone Capacity Expansion | Abu Dhabi industrial zone infrastructure attracts secondary converter capacity seeking lower operating costs than Jebel Ali saturation permits. |
| Captive Laboratory Capability Investment | MOHAP-registered analytical capacity extends product approval timelines for new laminate introductions while screening out mid-tier competitors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across converter engineering teams, brand procurement managers, MOHAP regulatory affairs specialists, and free-zone logistics coordinators. Primary interview insights were cross-validated against UAE.GSO technical regulations, Emirates Authority for Standardization and Metrology certification databases, GCC customs trade flows, and petrochemical feedstock pricing disclosures. Bottom-up capacity assessments at Jebel Ali and KIZAD industrial zones were triangulated with top-down demand modeling across food, personal care, and pharmaceutical end-use segments.
Calibration against historical volume trajectories anchored growth assumptions across the projection horizon. Segmentation dimensions modeled include product format (stand-up pouch, shrink film, roll stock), material substrate (polyethylene, polyester, polypropylene), application vertical (food and beverage, personal care, healthcare), and regional production cluster (Dubai, Abu Dhabi, Sharjah, Northern Emirates). CAGRs were derived from elasticity-adjusted demand curves incorporating polymer input cost pass-through coefficients and regulatory compliance cost absorption rates.
Sensitivities concentrate around MOHAP extended producer responsibility framework implementation timelines and polymer feedstock volatility transmission mechanisms. Forecasts reflect assumptions regarding migration testing laboratory capacity expansion and free-zone tariff regime continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
United States Flexible Plastic Packaging Market
Flexible Packaging
Middle East and Africa Flexible Plastic Packaging Market
Flexible Packaging
UK Flexible Plastic Packaging Market
Flexible Packaging
Canada Multilayer Flexible Packaging Market
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
Spain Flexible Plastic Packaging Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
Japan Flexible Plastic Packaging Market
Flexible Packaging
Converted Flexible Packaging Market
Flexible Packaging
Hygiene Breathable Films Market
Flexible Packaging
Global Flexible Plastic Packaging Market
Flexible Packaging
Metalized Flexible Packaging Market
Flexible Packaging
Morocco Flexible Packaging Market
Flexible Packaging
France Flexible Plastic Packaging Market
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
Latin America Flexible Plastic Packaging Market