
 Citric Acid Market | 2026-2036
Citric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Citric Acid Market Intelligence
Fermentation technologist availability is rotating from mature European facilities toward Chinese and Indian biotech corridors, reshaping where batch optimization and strain engineering expertise accumulates. Shandong Ensign Industry leverages captive molasses supply and coal-fired energy integration to sustain cost leadership in anhydrous output. Jungbunzlauer Suisse AG anchors premium pharmaceutical-grade positioning through Swissmedic-certified facilities. Cargill, Incorporated competes via backward integration into corn dextrose streams across North American processing complexes.
Citric acid is a tricarboxylic acid (C₆H₈O₇) produced industrially through submerged Aspergillus niger fermentation of carbohydrate substrates, typically yielding purity above 99.5% for food-grade material. Its primary function spans pH adjustment, metal chelation, and preservative action across formulations where synthetic alternatives face consumer rejection. Food-grade citric acid occupies the dominant value pool given volume absorption by carbonated and still beverage matrices, while pharmaceutical-grade commands margin premiums tied to USP and EP monograph compliance. Anhydrous variants are gaining formulation share in dry-blend applications where moisture sensitivity determines shelf stability.
FDA food additive regulations and EPA Safer Choice criteria on biodegradable chelating agents are redirecting detergent formulators toward citric acid from phosphonate alternatives. REACH registration requirements and the EU Green Deal bio-based content thresholds are conditioning import access for non-European fermentation supply. Stakeholders must monitor how China's dual carbon goals reshape coal-dependent fermentation energy economics and whether US PLA-derived lactic acid competition erodes citric acid's position in biopolymer acidulant applications.
Market Dynamics
Fermentation capacity concentration in Shandong Province is compressing regional cost curves and forcing European facilities to reposition toward pharmaceutical-grade specialization. China's dual carbon goals are accelerating coal-to-biomass energy transitions in citric acid production corridors.
Growth Catalysts
- Clean-label beverage mandates:Carbonated and still drink formulators are eliminating synthetic acidulants, pulling food-grade citric acid into expanded procurement contracts.
- EPA Safer Choice criteria:Biodegradable chelating specifications are redirecting detergent compounders from phosphonates toward citric acid in household and industrial cleaning matrices.
- Strain engineering advances:CRISPR-optimized Aspergillus niger lines are lifting fermentation yields above 150 grams per liter in Chinese biotech corridors.
Market Restraints
- Molasses supply volatility:Brazilian sugarcane harvest fluctuations and Indian ethanol diversion policies are squeezing carbohydrate feedstock availability for fermentation.
- Shandong supply concentration:Over sixty percent of global anhydrous capacity sits within 200 kilometers of Weifang, creating single-point disruption exposure.
- REACH registration friction:EU bio-based content thresholds and ECHA compliance timelines are conditioning import access for non-European fermentation supply.
Strategic Opportunities
- Pharmaceutical-grade white space:USP and EP monograph compliance gaps in Southeast Asian fermentation infrastructure create margin capture potential for certified producers.
- EU Green Deal bio-based thresholds:Renewable content mandates in packaging and detergents are opening premium positioning for fermentation-derived acidulants with verified carbon credentials.
- PLA acidulant displacement:Polylactic acid-derived lactic acid competition in biopolymer applications is forcing citric acid suppliers to defend position through chelation performance differentiation.
Industry Challenges
- Fermentation technologist scarcity:Batch optimization and strain engineering expertise is rotating toward Chinese and Indian corridors, hollowing European technical depth.
- Swissmedic certification timelines:Pharmaceutical-grade facility audits and USP monograph validation cycles extend eighteen to twenty-four months, compressing product launch windows.
- Coal-dependent energy reconfiguration:China's MEE emission intensity targets are forcing fermentation facilities to retrofit steam and power systems without interrupting continuous production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citric Acid Market |
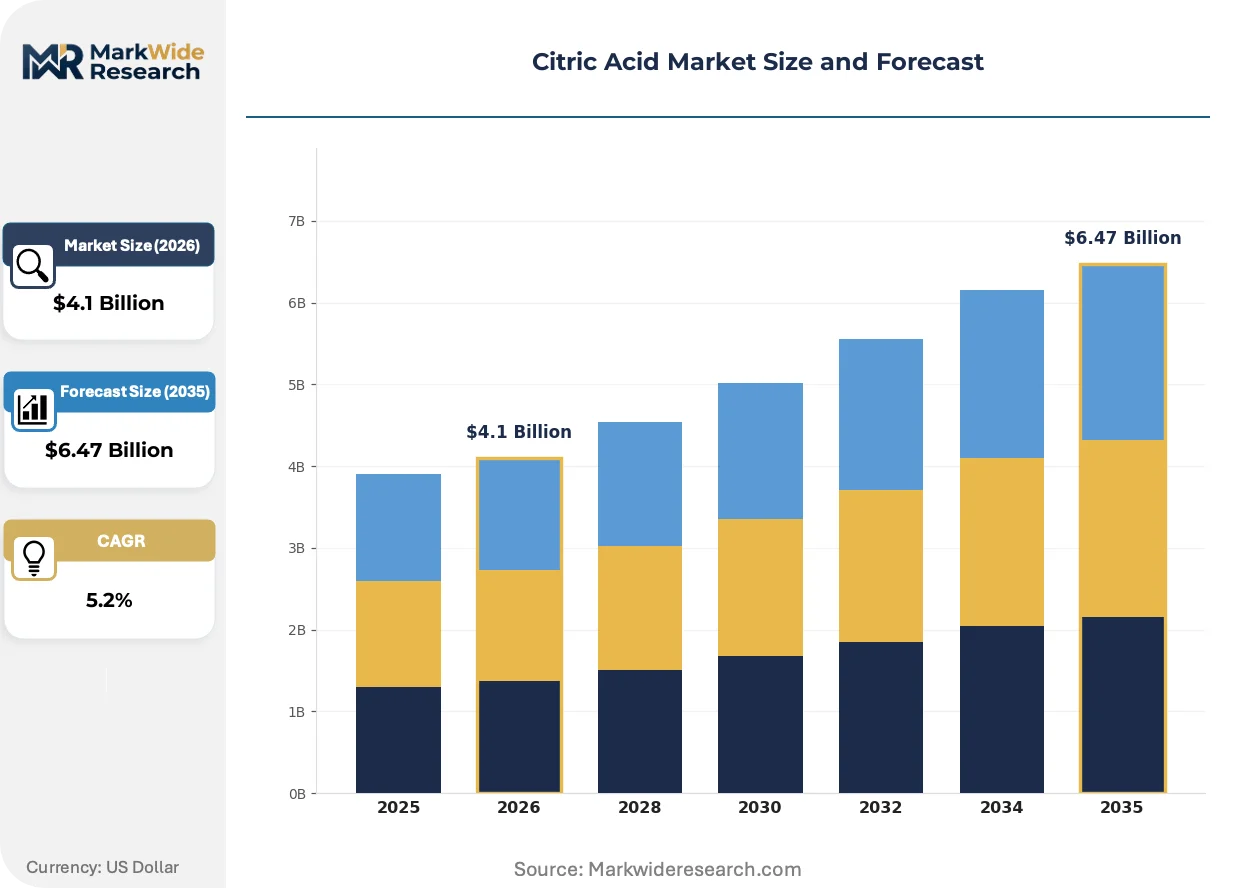
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.47 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monohydrate, Anhydrous, Cleaner Grade, Pharmaceutical Grade, Food Grade Application: Food & Beverages, Pharmaceuticals, Personal Care, Detergents, Water Treatment End User Industry: Food Processing Companies, Cosmetic Manufacturers, Pharmaceutical Firms, Cleaning Solution Providers, Beverage Producers Packaging Type: Bags, Drums, Bulk Containers, Bottles, Pouches |
| Companies Covered | RZBC Group Co., Ltd., Shandong Ensign Industry Co., Ltd., Cargill, Incorporated, Citribel NV, Tate & Lyle PLC, Archer Daniels Midland Company, COFCO Biochemical Co., Ltd., Gadot Biochemical Industries Ltd., Jungbunzlauer Suisse AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citric Acid Market Strategic Shifts & Innovations
Continuous fermentation systems and membrane filtration advances are collapsing batch cycle times while regulatory pressure on synthetic alternatives accelerates biological acidulant substitution. Three developments are restructuring competitive position.
Continuous fermentation technology is fragmenting the traditional batch-dominated production paradigm. Stainless steel bioreactor arrays with real-time dissolved oxygen monitoring are enabling 45-day uninterrupted runs versus 7-day batch cycles. European engineering firms are licensing skid-mounted systems to Indian and Southeast Asian operators, eroding Shandong's historical yield advantage.
REACH registration requirements and the EU Green Deal bio-based content thresholds are tightening import gatekeeping for non-European supply. ECHA documentation burdens and renewable mass-balance verification are extending compliance timelines for Chinese exporters. German and Dutch formulators are consolidating procurement around REACH-registered suppliers with ISO 14001-certified carbon accounting.
Beverage procurement is consolidating around direct molasses-to-acidulant supply partnerships that bypass merchant traders. Coca-Cola and PepsiCo bottling networks are signing toll-manufacturing agreements with Shandong facilities, compressing the traditional three-tier distribution structure. This channel compression is most visible in China and Brazil, where captive fermentation capacity locks in volume commitments at fixed conversion fees.
Citric Acid Market Segmentation
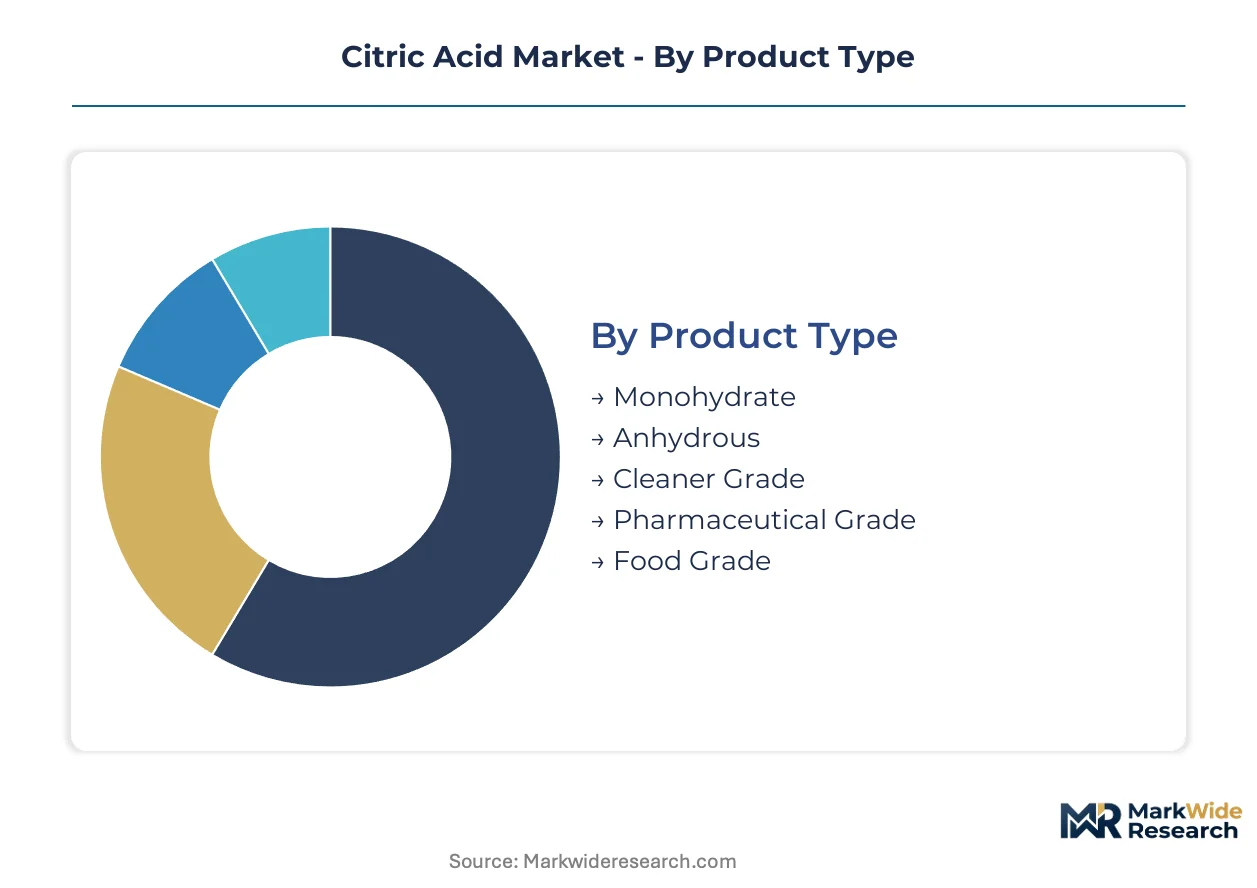
Citric acid procurement patterns diverge sharply across purity grades and end-use specifications. Formulators in beverages and detergents prioritize food-grade and cleaner-grade variants respectively, while pharmaceutical compliance demands isolate premium segments with distinct certification requirements.
Product Type:
Food-grade monohydrate dominates domestic Chinese consumption, while anhydrous variants flow disproportionately toward export markets in North America and Europe where dry-blend formulation standards are stricter.
- Monohydrate:The crystalline form contains one water molecule per citric acid molecule, making it preferred for liquid beverage applications where controlled dissolution rates matter. Beverage producers in Brazil and Mexico specify monohydrate for carbonated drink acidulation, though hygroscopicity limits its suitability for humid climate storage.
- Anhydrous:Water-free powder commands premium positioning in pharmaceutical tablet compression and dry-mix detergent matrices where moisture sensitivity threatens shelf stability. German and Dutch formulators specify anhydrous for automatic dishwasher tablet production, sourcing primarily through REACH-registered Chinese exporters with ISO 14001 carbon accounting.
- Cleaner Grade:Industrial chelation specifications with moderated purity tolerances serve detergent compounders seeking biodegradable alternatives to phosphonates. EPA Safer Choice compliance drives procurement from Shandong facilities with verified renewable energy transitions.
- Pharmaceutical Grade:USP and EP monograph compliance mandates dedicated production lines with Swissmedic-level audit protocols. Southeast Asian fermentation infrastructure gaps create supply bottlenecks for sterile injectable applications.
- Food Grade:Standard purity specifications above 99.5% serve mainstream food processing where FDA food additive regulations apply. Indian ethanol diversion policies are squeezing molasses feedstock availability for this volume tier.
Food-grade monohydrate commands the established base. The steepest expansion runs through pharmaceutical-grade anhydrous as USP compliance gaps in emerging fermentation corridors tighten supply.
Application:
Cost tiers separate commodity acidulation from premium chelation applications, with beverage procurement consolidating around direct supply partnerships that bypass merchant traders.
- Food & Beverages:pH adjustment and preservative action in carbonated and still drink matrices absorbs the largest volume share. Coca-Cola and PepsiCo bottling networks in China and Brazil are signing toll-manufacturing agreements with Shandong facilities at fixed conversion fees.
- Pharmaceuticals:Active pharmaceutical ingredient buffering and effervescent tablet formulations require USP monograph validation cycles extending eighteen to twenty-four months. Swissmedic-certified facilities anchor this margin-intensive tier.
- Personal Care:pH balancing in cosmetic formulations with moderate purity requirements serves cosmetic manufacturers seeking natural acidulant positioning. EU Green Deal bio-based thresholds are opening premium positioning for fermentation-derived supply with verified carbon credentials.
- Detergents:Biodegradable chelating specifications under EPA Safer Choice criteria redirect compounders from phosphonate alternatives. REACH registration requirements condition import access for non-European fermentation supply.
- Water Treatment:Metal chelation in boiler and cooling tower applications with technical-grade tolerances. MEE emission intensity targets in China are forcing facility retrofits without interrupting continuous production for this industrial segment.
Detergent applications are climbing the fastest on regulatory displacement of synthetic chelators. Pharmaceutical buffering maintains the highest margin tier despite extended certification timelines.
End User Industry:
Customer type determines procurement structure, with beverage producers consolidating volumes through captive toll arrangements while pharmaceutical firms enforce strict supplier qualification protocols.
- Food Processing Companies:Broad acidulant demand across preserved foods and confectionery with moderate specification stringency. FSSAI compliance requirements in India are tightening purity benchmarks for imported supply.
- Cosmetic Manufacturers:pH adjustment in skincare and haircare formulations with emerging clean-label positioning. European formulators are consolidating procurement around REACH-registered suppliers with renewable mass-balance verification.
- Pharmaceutical Firms:Stringent USP and EP monograph compliance with dedicated supplier audit programs. Swissmedic certification timelines compress product launch windows for new therapeutic formulations.
- Cleaning Solution Providers:Industrial and household detergent compounders seeking biodegradable chelating agents. EPA Safer Choice criteria are redirecting procurement from phosphonate alternatives toward citric acid.
- Beverage Producers:Carbonated and still drink formulators eliminating synthetic acidulants under clean-label mandates. Direct molasses-to-acidulant supply partnerships are compressing traditional three-tier distribution structures.
Beverage producers command the volume base. Pharmaceutical firms drive the steepest specification escalation as USP compliance gaps in Southeast Asian infrastructure create margin capture potential.
Packaging Type:
Supply concentration in Shandong Province shapes packaging economics, with bulk containers dominating export flows while retail-format pouches serve fragmented downstream compounders.
- Bags:Standard multi-wall paper or woven polypropylene for food-grade powder in 25-50kg units. Humid climate storage limitations favor anhydrous specification for tropical destination markets.
- Drums:Steel or fiber containers for liquid citric acid solutions in pharmaceutical and personal care applications. Swissmedic-certified facilities require dedicated drum handling protocols to prevent cross-contamination.
- Bulk Containers:Intermediate bulk containers and tanker shipments for detergent and beverage compounders with continuous production requirements. Coca-Cola and PepsiCo toll-manufacturing agreements lock in bulk container commitments at fixed conversion fees.
- Bottles:Retail and laboratory-scale packaging for pharmaceutical and cosmetic applications with precise dosing requirements. EP monograph compliance mandates specific closure systems to prevent moisture ingress.
- Pouches:Flexible retail formats for consumer-facing cleaning products and specialty food applications. EU packaging waste directives are conditioning material specifications for this emerging format.
Bulk containers command the established industrial base. Pouch formats are gaining share fastest in consumer-facing cleaning products as retail channel requirements fragment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry separates Shandong Province from European fermentation corridors. Chinese producers leverage captive molasses and coal-fired energy integration to undercut Western supply by double-digit margins. European facilities respond through pharmaceutical-grade specialization and Swissmedic-certified positioning.
China
Shandong Province hosts over sixty percent of global anhydrous capacity within 200 kilometers of Weifang. The NMPA is tightening GB standards on food-grade acidity regulators, forcing purity benchmark elevations. Dual carbon goals are accelerating coal-to-biomass transitions in fermentation energy systems without interrupting continuous production.
Germany
Detergent compounders in the Rhine-Ruhr corridor are redirecting procurement from phosphonates toward citric acid under EPA Safer Choice criteria alignment. REACH registration requirements and ECHA documentation burdens are extending compliance timelines for Chinese exporters. German formulators are consolidating procurement around REACH-registered suppliers with ISO 14001-certified carbon accounting.
United States
Beverage bottling networks are signing toll-manufacturing agreements with fermentation facilities at fixed conversion fees, compressing three-tier distribution structures. FDA food additive regulations govern mainstream food processing applications. Corn belt dextrose streams feed backward-integrated processing complexes across North American supply chains.
Brazil
Sugarcane harvest fluctuations are squeezing molasses feedstock availability for fermentation corridors serving carbonated drink acidulation. Beverage producers specify monohydrate for controlled dissolution rates in humid climate formulations. Ethanol diversion policies are redirecting carbohydrate substrates toward fuel rather than acidulant production.
Switzerland
Swissmedic-certified facilities anchor premium pharmaceutical-grade positioning through eighteen-to-twenty-four-month audit and validation cycles. EP monograph compliance mandates specific closure systems to prevent moisture ingress in sterile injectable applications. Jungbunzlauer Suisse AG exemplifies this margin-intensive tier through dedicated production line protocols.
Citric Acid Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the citric acid value chain. The market structures around a consolidated Shandong-based cost tier and a fragmented European premium tier. Three archetypes dominate: captive-feedstock Chinese producers, Swiss-certified pharmaceutical specialists, and North American corn-integrated processors. Competitive moves center on backward integration into carbohydrate streams and geographic expansion through toll-manufacturing partnerships.
Among Shandong-based producers, RZBC Group Co., Ltd. and Shandong Ensign Industry Co., Ltd. occupy positions within the cost-leadership archetype, leveraging proximity to molasses supply and fermentation corridor density. Jungbunzlauer Suisse AG represents the pharmaceutical-grade specialization tier, exemplifying Swissmedic-certified positioning that commands margin premiums through regulatory compliance depth.
| Leading Market Players |
|---|
| RZBC Group Co., Ltd. |
| Shandong Ensign Industry Co., Ltd. |
| Cargill, Incorporated |
| Citribel NV |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| COFCO Biochemical Co., Ltd. |
| Gadot Biochemical Industries Ltd. |
| Jungbunzlauer Suisse AG |
| Others |
Cost & Logistics Intelligence
Shandong Province's fermentation corridor density compresses unit economics below achievable thresholds elsewhere, anchoring global price floors while concentrating supply authority within a 200-kilometer radius of Weifang. This scale advantage reshapes procurement patterns as buyers face take-it-or-leave-it terms on anhydrous volumes, while European facilities retreat toward pharmaceutical-grade specialization where certification premiums offset cost disadvantages.
Pricing Analysis
Configured-to-order pharmaceutical-grade shipments command spreads exceeding standard food-grade spot pricing by substantial margins, reflecting Swissmedic audit costs and dedicated line protocols. Three-tier pricing structure across pharmaceutical, food-grade, and cleaner-grade levels segments buyers by compliance burden rather than volume alone. Cost compression in standard food-grade tiers is intensifying because Shandong producers leverage captive molasses and coal-fired energy integration. Beverage producers exhibit highest price sensitivity, sourcing through toll-manufacturing agreements at fixed conversion fees, while pharmaceutical firms accept premium positioning for USP and EP monograph compliance.
Supply Chain Analysis
China, Brazil, and India anchor global fermentation capacity, with Shandong Province alone hosting over sixty percent of anhydrous output. Carbohydrate feedstock draws from Brazilian sugarcane molasses, Indian ethanol diversion-exposed supplies, and North American corn dextrose streams. Single-source vulnerability concentrates in the Weifang corridor, where emission intensity targets from China's MEE force energy retrofits without production interruption. Distribution runs through bulk container and tanker shipments for detergent and beverage compounders, with toll-manufacturing agreements compressing traditional three-tier merchant structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Batch optimization expertise and strain engineering capability accumulate in Chinese and Indian corridors, leaving European facilities dependent on aging technical depth. This geographic skew in fermentation technologist availability constrains how quickly incumbent producers can replicate yield advances elsewhere.
For Market Incumbents: Secure captive molasses supply through long-term offtake agreements with Brazilian and Indian sugar processors before ethanol diversion policies tighten further. Lock in pharmaceutical-grade certification investments at Swissmedic level to defend margin position against Shandong cost leaders expanding into technical-grade segments. Capacity addition in Southeast Asian corridors offers geographic diversification without sacrificing proximity to molasses feedstock. For New Entrants and Emerging Players: Toll-manufacturing service gaps in Southeast Asia present immediate white-space opportunity, as regional beverage and pharmaceutical formulators lack REACH-registered fermentation partners with verified carbon accounting. Under-served cleaner-grade detergent compounders in the EU Green Deal compliance window seek biodegradable chelating alternatives with renewable mass-balance documentation. Target pharmaceutical-grade anhydrous for sterile injectable applications, where USP compliance gaps in emerging infrastructure create supply bottlenecks and pricing power. For Investors and Strategic Acquirers: Swissmedic-certified facilities with dedicated pharmaceutical-grade lines represent the most defensible acquisition archetype, commanding margin premiums through regulatory compliance depth that Chinese cost leaders cannot easily replicate. Long-term viability hinges on whether fermentation-derived acidulants maintain position against PLA-derived lactic acid competition in biopolymer applications. Watch CRISPR-optimized Aspergillus niger yield advances above 150 grams per liter as the inflection indicator for whether technical leadership remains geographically concentrated or disperses through licensed engineering systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Supply | Captive carbohydrate feedstock from Brazilian sugarcane processors locks in cost position against ethanol diversion volatility. |
| Swissmedic Certification Investment | Eighteen-to-twenty-four-month audit cycles create regulatory moats around pharmaceutical-grade margin premiums. |
| Continuous Fermentation Technology Licensing | Skid-mounted bioreactor systems from European engineering firms erode Shandong's historical yield advantage in Asian corridors. |
| REACH Registration Completion | ECHA documentation and renewable mass-balance verification open EU procurement channels for non-European fermentation supply. |
| Coal-to-Biomass Energy Transition | MEE emission intensity compliance in Shandong facilities sustains production continuity under China's dual carbon goals. |
Research Approach
Cross-validation between trade flow databases and facility-level production disclosures anchors the qualitative findings on capacity concentration and yield differentials. Primary interviews with fermentation plant managers, beverage procurement leads, detergent compounder R&D directors, and pharmaceutical regulatory affairs specialists combined with secondary validation through customs records, NMPA GB standard filings, and ECHA REACH registration databases. Bottom-up capacity modeling and top-down demand triangulation from end-use consumption patterns converged on segment-level projections.
Sensitivity analysis across molasses price volatility scenarios, ethanol diversion policy intensities, and Swissmedic certification timeline variations tested projection robustness. The analytical framework spans grade tier, end-use industry, packaging format, and regional production hub dimensions throughout the forecast period. CAGRs derived from fitted growth curves adjusted for regulatory inflection points and technology diffusion rates. Strain engineering yield advances and continuous fermentation adoption curves served as industry-specific forecast inputs.
Underlying assumptions cover sustained clean-label beverage procurement trends, REACH registration compliance timelines, and MEE emission intensity enforcement trajectories, with deviation risk concentrated in Brazilian sugarcane harvest fluctuations and PLA-derived lactic acid substitution rates. Forecasts reflect documented conditions with acknowledged uncertainty around dual carbon goal implementation pacing. Recalibration cycles align with material shifts in NMPA purity benchmark revisions and EPA Safer Choice criteria updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Driveline Additives Market
Additives
Agrochemicals Additives Market
Additives
Indonesia Feed Additives Market
Additives
Nucleating Agents Market
Additives
Glyceryl Caprylate Market
Additives
Global Performance Additives Market
Additives
Japan Sodium Reduction Ingredient Market
Additives
Binding Agents Market
Additives
Phenolic Antioxidant Market
Additives
Automotive Additives Market
Additives
Extrusion Aids Market
Additives
Phthalic Anhydride Derivatives Market
Additives
Coating Additives Market
Additives
Tamarind Gum Derivatives Market
Additives
Asia Pacific Silage Additives Market
Additives
Tartaric Acid Market