
 EDM Oils/Fluids Market | 2026-2036
EDM Oils/Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
EDM Oils/Fluids Market Analysis
Aftermarket fluid analysis and recycling services is reshaping margin pools away from commodity gallon sales in the EDM oils sector. ExxonMobil leverages its integrated base oil supply network to control feedstock costs across synthetic and mineral product lines. Shell anchors its position through specialized dielectric fluid formulations engineered for high-precision wire EDM applications in aerospace and medical device machining.
EDM oils and fluids are dielectric liquids formulated from highly refined hydrocarbons or synthetic esters, characterized by viscosity ranges of 1.5–3.0 cSt at 40°C and dielectric strength exceeding 30 kV, designed to flush debris, stabilize spark gaps, and thermally regulate the erosion machining process. Synthetic oils command premium positioning due to extended service life and superior oxidation stability in high-frequency pulse operations, while water-soluble fluids gain traction in rough-cutting applications where cost efficiency and disposal simplicity outweigh finishing precision requirements. Erosion machining remains the dominant application segment, though surface finishing applications for medical implants and micro-electronics are expanding fastest as tolerances tighten below 0.001 mm.
REACH registration requirements and ECHA substance restrictions are elevating formulation costs for mineral-based EDM fluids containing polycyclic aromatics, while EPA spill prevention rules in the United States mandate secondary containment for bulk dielectric fluid storage. The EU F-Gas Regulation and emerging MEE emissions standards in China are converging to accelerate bio-based and synthetic ester development programs. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation timelines and avoid stranded inventory positions.
Market Dynamics
REACH chemical restrictions and EPA spill prevention mandates are forcing formulators to abandon mineral-based fluids containing polycyclic aromatics, compressing legacy product lifecycles while accelerating synthetic ester and bio-based alternative development timelines.
Growth Catalysts
- Aerospace precision demands:Turbine blade manufacturers in Germany and Japan are specifying high-dielectric-strength synthetic fluids for wire EDM operations requiring sub-0.001 mm tolerances.
- EU Green Deal chemical phase-outs:The European Commission's restriction roadmap is pulling demand toward low-aromatic and biodegradable dielectric formulations ahead of statutory deadlines.
- Medical implant surface finishing:Orthopedic device producers are adopting specialized EDM fluids for controlled surface texturing of titanium and cobalt-chrome components.
Market Restraints
- Base oil supply concentration:Paraffinic feedstock availability depends on a narrow set of Group II/III refinery operators, creating input cost volatility for mineral fluid producers.
- Synthetic ester technical limitations:Current bio-based formulations exhibit hydrolytic instability above 60°C, restricting their deployment in high-pulse-frequency rough-cutting operations.
- REACH registration cost escalation:ECHA substance data requirements for mineral oil distillates are elevating compliance burdens disproportionately for small-batch formulators.
Strategic Opportunities
- Aftermarket fluid analysis services:Condition monitoring and dielectric strength testing programs are creating recurring revenue streams independent of gallon sales.
- China MEE emissions alignment:Provincial environmental bureaus are tightening VOC discharge permits, positioning low-emission synthetic fluids for import substitution.
- Hybrid machining convergence:Laser-assisted EDM and ultrasonic-assisted wire systems are demanding customized dielectric formulations with modified viscosity and thermal conductivity profiles.
Industry Challenges
- Formulation chemist scarcity:Dielectric fluid R&D requires rare expertise spanning high-voltage physics, tribology, and polymer chemistry that industrial chemistry programs no longer emphasize.
- Reformulation timeline compression:ECHA substance restriction proposals are advancing faster than 18-24 month product qualification cycles at major aerospace and medical device OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EDM Oils/Fluids Market |
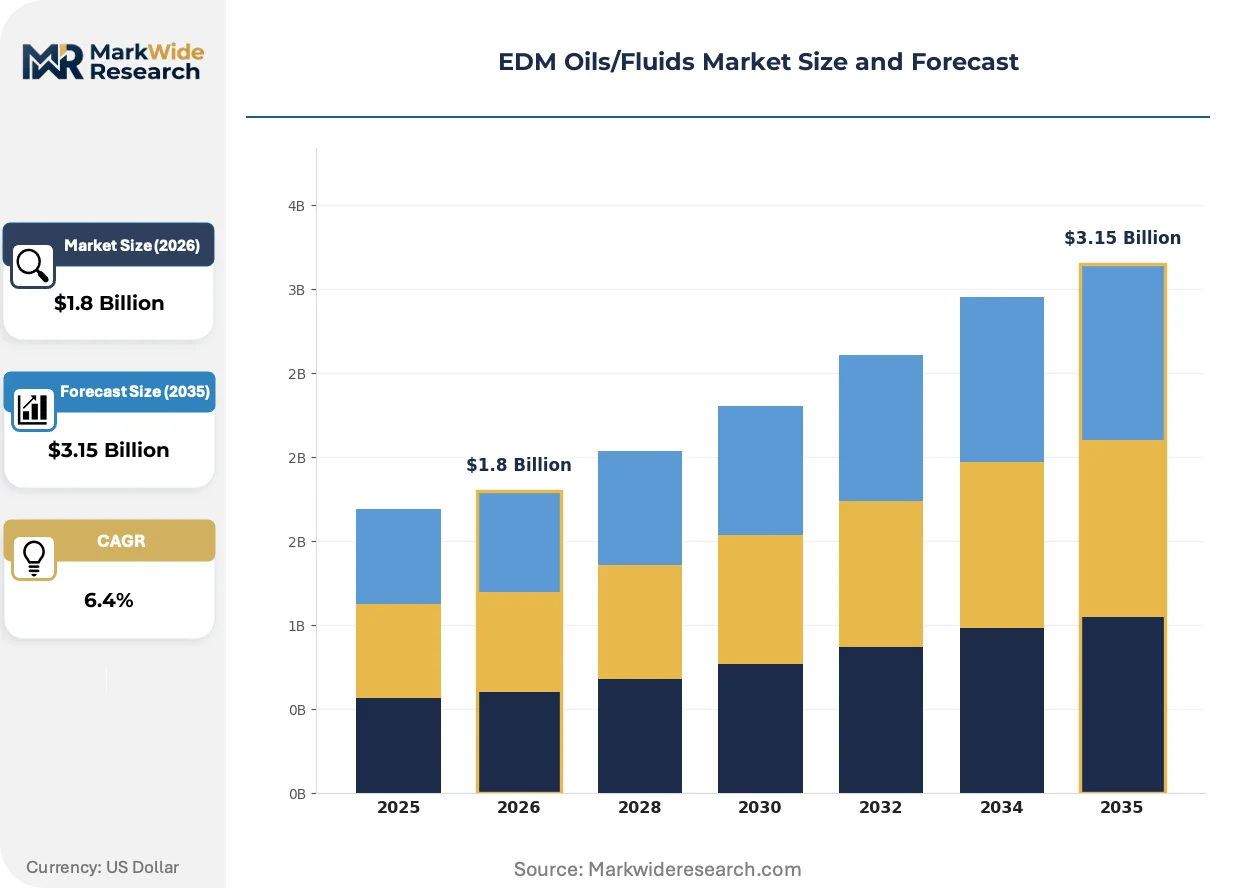
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oils, Synthetic Oils, Water-Soluble Fluids, Emulsifiable Fluids Application: Erosion Machining, Surface Finishing, Drilling, Grinding End User: Aerospace, Automotive, Defense, Electronics Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesalers |
| Companies Covered | ExxonMobil, Shell, TotalEnergies, Chevron, BP, FUCHS Lubricants, Idemitsu Kosan, Petro-Canada Lubricants, Castrol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EDM Oils/Fluids Market Emerging Trajectories
Dielectric fluid performance specifications are tightening as erosion machining applications push into medical micro-implants and aerospace superalloy components, while regulatory chemistry restrictions force simultaneous reformulation of established product lines.
Real-time dielectric monitoring systems using embedded conductivity and temperature sensors are digitizing maintenance scheduling for high-volume wire EDM operations. Automotive and aerospace job shops in Germany and Japan are piloting these systems to extend fluid service intervals. The technology is digitizing fluid management from reactive replacement toward predictive intervention, compressing aftermarket revenue models.
ECHA's 2023-2027 restriction roadmap for polycyclic aromatic hydrocarbons is eliminating mineral oil fractions above three-ring structures from dielectric formulations. Fluid blenders must qualify synthetic and severely hydrotreated base stocks under accelerated timelines. Wire EDM applications in medical device manufacturing face the steepest compliance curves due to biocompatibility certification requirements.
Buyers are unbundling fluid supply from machine tool procurement, treating dielectrics as independent consumables subject to total-cost-of-ownership analysis. Distributors in the US Midwest and German toolmaking clusters are responding with technical service capabilities previously captive to OEMs. This pattern is most pronounced among mid-tier contract manufacturers operating mixed-voltage EDM fleets.
EDM Oils/Fluids Market Segmentation
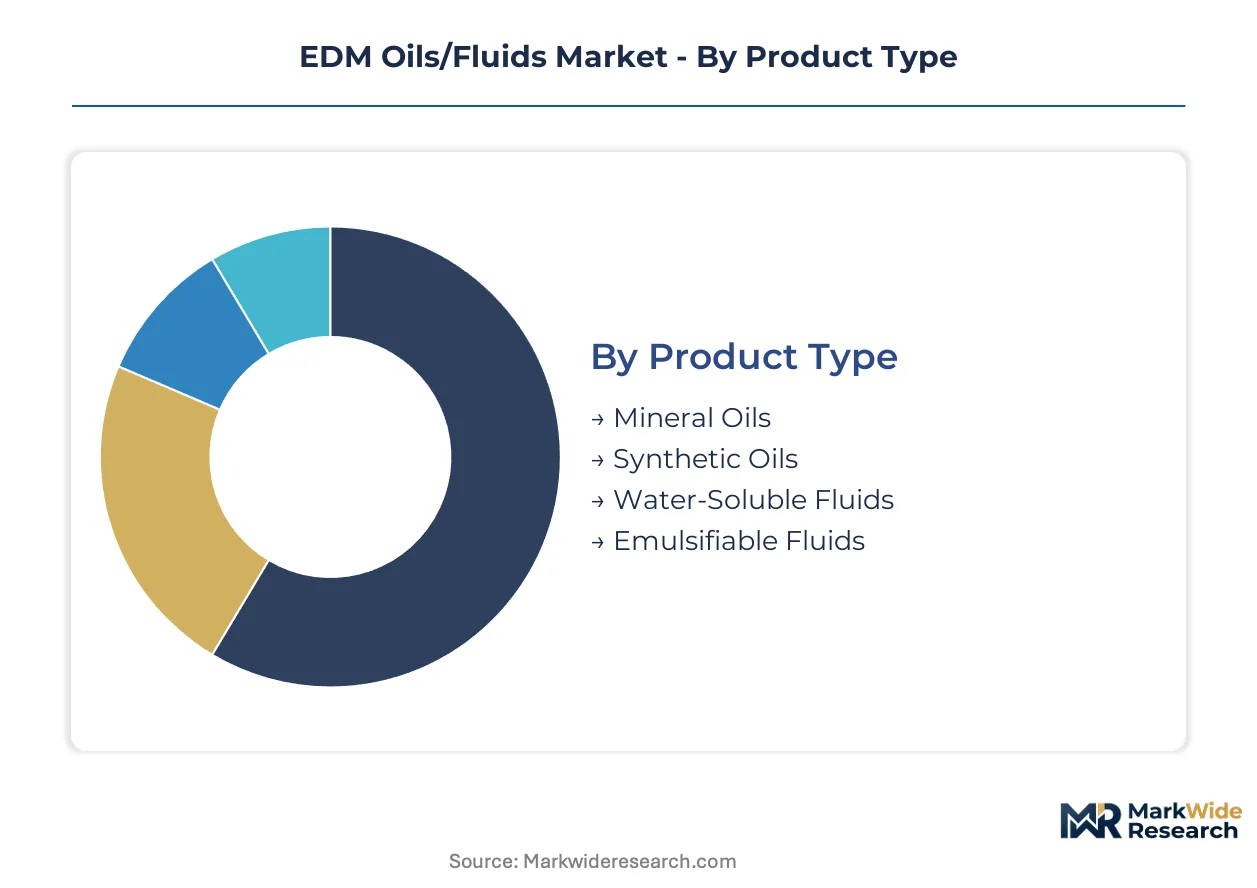
EDM fluid procurement patterns diverge sharply across product chemistries and end-use applications, with aerospace precision requirements pulling toward premium synthetics while automotive rough-cutting tolerates shorter-lived mineral formulations. Understanding these segment dynamics illuminates where formulation R&D investments concentrate versus where volume commoditization pressures dominate.
Product Type:
Mineral oils turn over fastest in high-volume rough-cutting environments, while synthetic esters command extended service intervals in precision wire EDM operations where dielectric stability directly correlates with dimensional tolerance achievement.
- Synthetic Oils:Formulated from severely hydrotreated Group III base stocks or synthetic esters with viscosity indices above 120 and oxidation stability exceeding 3000 hours. Demand concentrates in German and Japanese aerospace turbine blade manufacturing, where sub-0.001 mm tolerances mandate dielectric strength above 35 kV and thermal conductivity control. REACH aromatic restrictions are accelerating synthetic adoption ahead of mineral oil phase-out timelines.
- Mineral Oils:Refined paraffinic distillates with polycyclic aromatic content now constrained under ECHA restriction roadmaps. Automotive job shops in the US Midwest and Chinese rough-cutting operations remain the core consumption base, though regulatory pressure is compressing product lifecycles toward synthetic substitution.
- Water-Soluble Fluids:Semi-synthetic concentrates diluted 5-10% in deionized water for flushing efficiency in high-material-removal-rate applications. Cost-sensitive contract manufacturers favor these formulations for their disposal simplicity and lower fire hazard profiles.
- Emulsifiable Fluids:Oil-in-water emulsions stabilized with surfactant packages for specialized deep-hole drilling applications where chip evacuation challenges exceed straight oil capabilities.
Mineral oils anchor the volume base while synthetic oils gain share at the steepest rate.
Application:
Margin structures invert across the application spectrum, with erosion machining generating recurring gallon sales while surface finishing commands formulation premiums tied to medical device biocompatibility certifications.
- Erosion Machining:Dielectric fluids for sinker and wire EDM operations where spark gap ionization and debris flushing determine material removal rates. German automotive toolrooms and Japanese precision component factories represent the densest demand clusters, with wire EDM specifically driving synthetic fluid specifications.
- Surface Finishing:Controlled spark erosion for titanium and cobalt-chrome orthopedic implant texturing, where surface roughness parameters between Ra 0.5-4.0 μm must meet FDA 510(k) biocompatibility requirements. Swiss and US medical device manufacturers are expanding this segment fastest as additive-manufactured implant surfaces require post-processing refinement.
- Drilling:Deep-hole EDM applications in aerospace landing gear and defense barrel manufacturing, where dielectric circulation pressure and filtration specifications diverge from standard wire EDM requirements.
- Grinding:Hybrid EDM-grinding processes for ceramic and superalloy finishing, a niche application concentrated in Japanese precision grinding equipment installations.
Erosion machining retains the largest revenue pool while surface finishing expands most quickly.
End User:
Procurement sophistication varies dramatically across end-user categories, with aerospace OEMs conducting total-cost-of-ownership fluid analysis while defense contractors prioritize supply security over unit economics.
- Aerospace:Tier-1 turbine manufacturers in Germany, Japan, and the US specify dielectric fluids through approved vendor lists with qualification cycles exceeding 18 months. Wire EDM for nickel superalloy components drives the highest-performance synthetic requirements.
- Automotive:German toolmaking clusters and US Midwest job shops constitute the volume anchor, with mixed EDM fleets consuming mineral oils in rough-cutting and synthetics in precision finishing operations.
- Defense:Barrel rifling and armor component fabrication in the US, France, and South Korea, where national security procurement regulations limit supplier switching regardless of commercial fluid performance metrics.
- Electronics:Micro-EDM for connector and semiconductor tooling, concentrated in Taiwan and South Korea, where dielectric purity specifications for sub-50 μm feature sizes exceed standard industrial grades.
Automotive anchors the volume base while aerospace gains share at the steepest rate.
Distribution Channel:
Channel economics reflect technical service intensity, with direct sales capturing formulation customization premiums while distributors compete on logistics efficiency for standardized mineral oil volumes.
- Direct Sales:Formulator technical service engineers embed with aerospace and medical device OEMs for fluid specification and condition monitoring program design. ExxonMobil and Shell field organizations dominate this channel for synthetic product lines.
- Distributors:Regional fluid blenders and industrial supply houses in German automotive clusters and US Midwest manufacturing corridors, where inventory proximity outweighs technical service depth for mineral oil procurement.
- Online Retailers:Emerging channel for small-batch specialty fluids and analysis kit sales, capturing maintenance procurement from mid-tier job shops with limited technical staff.
- Wholesalers:Bulk mineral oil aggregation for price-sensitive Asian and Eastern European markets, with limited technical differentiation.
Distributors anchor the volume base while direct sales gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refinery capacity for Group II/III base oils concentrates in the US Gulf Coast, Germany's Rhine-Ruhr corridor, and Japan's Chukyo industrial zone, creating geographic asymmetries in synthetic fluid feedstock access. Formulators cluster near aerospace and automotive machining demand centers rather than crude sources.
Germany
Aerospace turbine manufacturers in Bavaria and Baden-Württemberg specify REACH-compliant synthetic dielectrics for nickel superalloy wire EDM operations. The EU Green Deal chemical restriction roadmap accelerates low-aromatic formulation adoption ahead of statutory deadlines. Stuttgart's automotive toolmaking cluster drives premium fluid consumption for mixed-voltage EDM fleets.
United States
Defense contractors in Connecticut and aerospace OEMs in the Pacific Northwest demand high-dielectric-strength synthetics for superalloy component fabrication. EPA spill prevention rules mandate secondary containment for bulk dielectric storage, elevating compliance costs for job shops. The Midwest automotive corridor remains the volume anchor for mineral-based rough-cutting fluids.
Japan
Precision component factories in Aichi Prefecture and medical device manufacturers in Osaka specify synthetic esters for sub-0.001 mm tolerance wire EDM. METI industrial standards for dielectric fluid performance create technical barriers for imported formulations. Nagoya's aerospace supply base anchors synthetic fluid qualification programs.
China
Provincial environmental bureaus under MEE authority are tightening VOC discharge permits for dielectric fluid operations in the Yangtze River Delta. Domestic formulators in Jiangsu and Zhejiang are accelerating synthetic ester development to capture import substitution opportunities. Shenzhen's electronics tooling cluster demands high-purity dielectrics for micro-EDM applications.
Switzerland
Orthopedic implant manufacturers in the Lake Geneva region specify biocompatible-certified dielectrics for titanium surface texturing. Swissmedic medical device regulations extend fluid qualification timelines beyond standard industrial cycles. The country's precision machining ecosystem supports premium pricing for specialized formulations.
EDM Oils/Fluids Market Vendor Landscape
Integrated petrochemical majors and specialized lubricant blenders split the market into feedstock-anchored and formulation-led competitive spheres. The structure tilts toward consolidation at the premium synthetic tier while mineral oil segments fragment across regional blenders. Three archetypes dominate: upstream-integrated oil majors controlling base oil supply, mid-cap specialists with aerospace qualification relationships, and regional distributors competing on logistics proximity. Competitive moves center on backward integration into base oil refining and technical service embedding with medical device OEMs.
Among integrated oil majors, ExxonMobil and Shell exemplify feedstock-anchored positioning through captive Group II/III base oil networks. FUCHS Lubricants occupies a position within the European specialist tier, reflecting German automotive and aerospace cluster proximity. These three entities represent distinct strategic postures: upstream cost control, high-precision application engineering, and regional technical service density.
| Leading Market Players |
|---|
| ExxonMobil |
| Shell |
| TotalEnergies |
| Chevron |
| BP |
| FUCHS Lubricants |
| Idemitsu Kosan |
| Petro-Canada Lubricants |
| Castrol |
| Others |
Supply Flow & Price Mechanics
Rhine-Ruhr freight corridors linking German Group II/III refineries to Bavarian aerospace clusters transmit base oil cost volatility directly into synthetic dielectric fluid premiums, while downstream buyers unbundle fluid procurement from machine tool purchases to exploit price transparency across mineral and synthetic tiers.
Pricing Analysis
REACH aromatic restrictions dictate the pricing tier structure across the EDM fluids sector. Three-tier pricing stratifies across aerospace-qualified synthetics, automotive mineral formulations, and economy water-soluble concentrates. Certification grade and volume scale drive price differentiation, with FDA biocompatibility tiers commanding substantial premiums over standard industrial grades. Cost compression in mineral oil segments is intensifying because ECHA registration fees disproportionately burden small-batch formulators. Automotive job shops in the US Midwest exhibit highest price sensitivity, while German turbine manufacturers prioritize dielectric performance metrics over unit economics.
Supply Chain Analysis
Tariff exposure between US Gulf Coast refiners and European formulators dominates supply chain risk calculations for Group II/III base oil procurement. Feedstock concentration centers on the United States, Germany, and Japan, with paraffinic distillate availability resting on a narrow refinery operator set. Synthetic ester production draws from palm-derived fatty acids and petrochemical alcohols, creating agricultural commodity price tethering. Single-source vulnerability persists for severely hydrotreated base stocks qualified under accelerated REACH timelines. Distribution runs through direct technical service channels for synthetics and regional distributors for mineral oil volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EDM fluid incumbents face substitution defense imperatives as laser-assisted and ultrasonic-assisted hybrid machining systems displace conventional dielectric-dependent processes in high-precision applications.
For Market Incumbents: Build certification moats around FDA biocompatibility and aerospace OEM approval lists. Deepen upstream control over Group II/III base oil refining to offset feedstock cost volatility from narrow refinery operator concentration. Accelerate synthetic ester R&D to counter hydrolytic instability limitations above 60°C that constrain bio-based formulation deployment. Channel control through embedded technical service teams protects against distributor disintermediation. For New Entrants and Emerging Players: Mid-tier Chinese electronics tooling clusters in the Yangtze River Delta represent the most penetrable entry point for import substitution of high-purity micro-EDM dielectrics. Swiss orthopedic implant surface finishing applications offer formulation premium capture for biocompatible-certified specialists. Aftermarket fluid analysis services provide recurring revenue anchoring independent of commodity gallon sales. Partner with provincial environmental bureaus under MEE authority to align low-emission synthetic portfolios with tightening VOC discharge permits. For Investors and Strategic Acquirers: Regional fluid blenders with established aerospace qualification relationships in Germany and Japan present the most attractive acquisition target archetype. Long-term viability hinges on synthetic substitution momentum outpacing mineral oil phase-out timelines. Watch ECHA restriction proposal advancement rates against 18-24 month OEM qualification cycles as the critical inflection indicator for stranded inventory risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Refining | Captive Group II/III supply secures feedstock cost control against narrow operator concentration. |
| Biocompatibility Certification Investment | FDA 510(k) alignment opens orthopedic implant surface finishing premium segments. |
| Aftermarket Fluid Analysis Services | Condition monitoring programs generate recurring revenue independent of gallon volume. |
| Synthetic Ester R&D Expansion | Hydrolytic stability breakthroughs above 60°C unlock high-pulse-frequency rough-cutting applications. |
| Provincial Environmental Bureau Alignment | MEE VOC permit compliance positions low-emission formulations for Chinese import substitution. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with fluid formulators, aerospace procurement directors, automotive toolroom managers, and EDM equipment OEM technical service heads; and secondary validation against customs trade data, ECHA substance registration databases, SEC petroleum segment disclosures, and German automotive cluster production statistics. Bottom-up triangulation across product chemistry segments and top-down validation against refinery capacity data ensured cross-verification.
Forecast inputs considered wire EDM penetration rates in nickel superalloy turbine manufacturing, REACH aromatic restriction implementation phasing, and synthetic ester technical performance evolution. Segmentation modeling spanned product chemistry tiers, application precision requirements, end-user procurement sophistication levels, and regional regulatory framework clusters. CAGRs were derived from demand elasticity analysis against aerospace build rates and automotive toolroom capital expenditure patterns.
Macroeconomic conditions sit as an overlay; deviation in aerospace OEM production schedules or refinery operating rates would shift the trajectory. Forecasts reflect assumptions about ECHA restriction timelines and synthetic ester stability improvement curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Poland Automotive Engine Oils Market
Lubricants
Norway Commercial Vehicles Lubricants Market
Lubricants
Japan Lubricants Market
Lubricants
Engine Oil and Lubricant Market
Lubricants
Hydropower Lubricants Market
Lubricants
US Industrial Lubricants Market
Lubricants
United Arab Emirates Lubricants Market
Lubricants
Brazil Lubricants Market
Lubricants
Philippines Commercial Vehicles Lubricants Market
Lubricants
Germany Lubricants Market
Lubricants
Canada Lubricants Market
Lubricants
Sri Lanka Lubricants Market
Lubricants
India Lubricants Market
Lubricants
Saudi Arabia Lubricants Market
Lubricants
South Korea Lubricants Market
Lubricants
Turkey Automotive Engine Oils Market