

Battery Fire and Explosion Containment Test Chambers Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Fire and Explosion Containment Test Chambers Market Insights
Software-defined remote monitoring is hardening the service layer around physical chamber assets, shifting vendor economics toward recurring diagnostics contracts. Weiss Technik leverages its European installed base to anchor long-term service agreements. Thermotron Industries competes through domestic manufacturing scale in North America. ESPEC extends its position in East Asia with specialized thermal-cycling integration.
Battery fire and explosion containment test chambers are engineered pressure-rated enclosures designed to safely contain thermal runaway events, vent combustion gases, and suppress deflagration during lithium-ion cell abuse testing; typical specifications include reinforced steel construction, multi-layer insulation rated beyond 1,000°C, and integrated gas extraction systems that protect personnel and adjacent laboratory infrastructure. Walk-in and custom-built units command premium positioning due to the engineering intensity of large-format automotive and energy storage system validations. Compact and modular configurations serve high-throughput consumer electronics and research laboratory segments where footprint constraints and test-volume flexibility determine procurement decisions.
UL 9540A, UN 38.3, and IEC 62660 shape chamber design requirements across the United States, European Union, and international trade corridors, mandating reproducible abuse-test documentation that only certified containment infrastructure can generate. The EU AI Act and CSRD reporting obligations further tighten traceability standards for safety-critical testing equipment deployed within European battery supply chains. Stakeholders must weigh capital deployment timing against evolving regulatory harmonization between regional certification regimes.
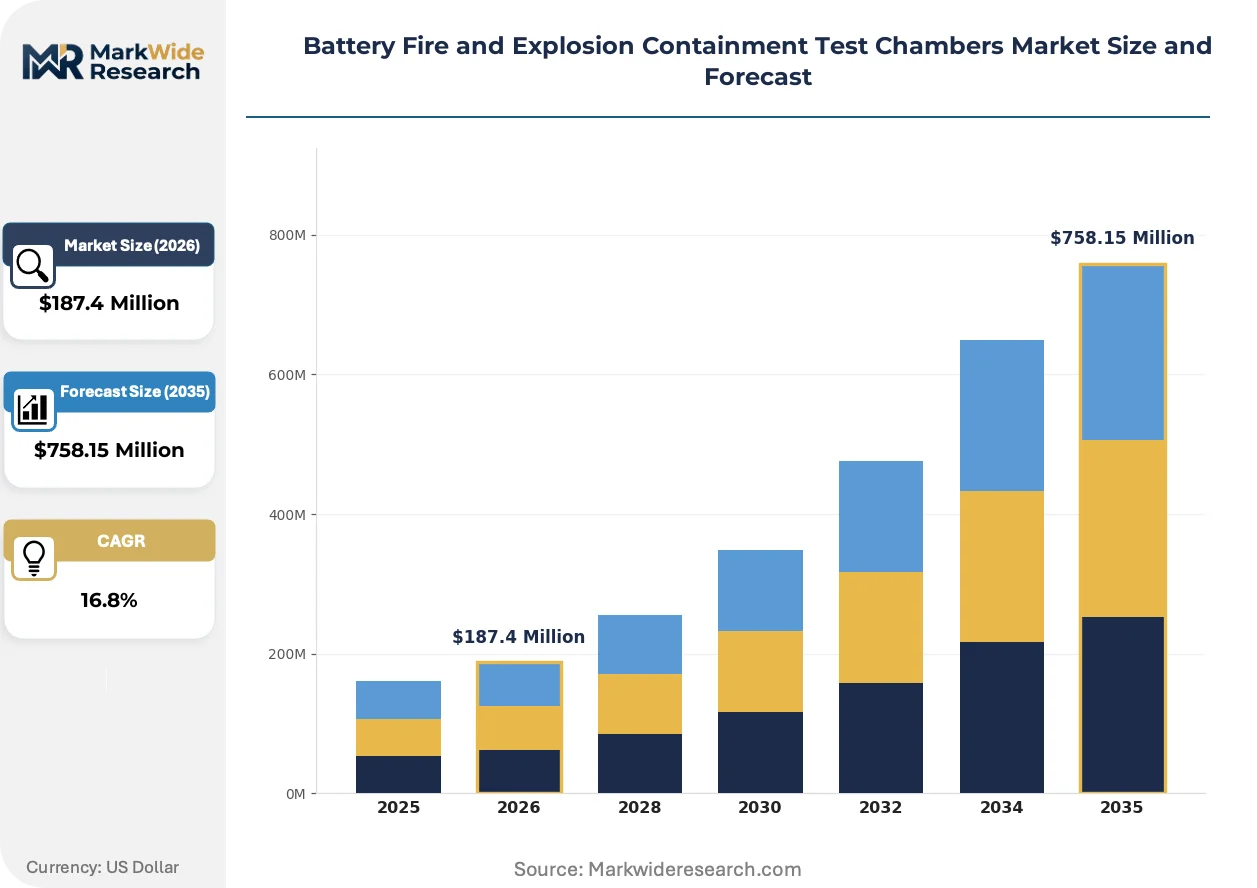
Market Dynamics
Electric vehicle OEMs now mandate certified abuse-testing infrastructure before any cell qualification, forcing battery manufacturers to front-load capital into containment chambers ahead of production ramp decisions.
Growth Catalysts
- UN 38.3 Transport Certification:International air and maritime shipping rules now require documented thermal runaway containment testing, compelling cell producers in China, South Korea, and the United States to install certified chambers before export clearance.
- Automotive Gigafactory Buildouts:Lithium-ion cell manufacturing capacity expansion across Germany, Hungary, and Poland is generating direct procurement pull for walk-in explosion-rated enclosures capable of validating large-format pouch and prismatic designs.
- Energy Storage System Mandates:Grid-scale battery deployments in California, Texas, and Australia now require UL 9540A propagation testing, driving demand for multi-cell chamber arrays that simulate cascading failure scenarios.
Market Restraints
- Specialized Steel Input Volatility:Pressure-rated vessel construction relies on nickel-alloy and high-strength carbon steel grades whose spot pricing fluctuates with stainless scrap and ferrochrome supply from South Africa and Kazakhstan.
- Engineering Talent Bottleneck:Chamber design requires cross-disciplinary expertise combining pressure vessel engineering, thermal dynamics, and gas extraction system integration; qualified practitioners concentrate in Germany, Japan, and select US industrial corridors.
- Extended Certification Timelines:Third-party validation of custom walk-in units against IEC 62660 and UL 9540A protocols routinely spans 18-24 months, compressing vendor cash conversion cycles and limiting rapid scaling capacity.
Strategic Opportunities
- Second-Life Battery Testing:Repurposed EV packs entering stationary storage applications in India and Southeast Asia require abuse-testing infrastructure that most local laboratories currently lack, creating greenfield installation demand.
- Software-Defined Remote Monitoring:Predictive maintenance algorithms and real-time thermal telemetry are enabling vendors to attach recurring diagnostics contracts to chamber hardware, shifting revenue mix toward service annuities.
- Aviation and Maritime Certification:Emerging eVTOL aircraft and electric propulsion marine vessels are subject to novel FAA and IMO thermal runaway containment standards that existing automotive-focused chambers cannot satisfy without redesign.
Industry Challenges
- Integration Complexity with Legacy Laboratory Infrastructure:New containment chambers must interface with existing environmental testing equipment, gas detection networks, and facility HVAC systems without triggering full laboratory recertification.
- Skill Scarcity in Pressure Vessel Welding:ASME Section IX and EN ISO 9606 certified welders capable of executing multi-pass joints on explosion-rated enclosures remain concentrated in Central European and Japanese fabrication yards.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Fire and Explosion Containment Test Chambers Market Trends and Innovations
Containment chamber architecture is fragmenting into configurable subsystems that decouple thermal, pressure, and gas management functions, enabling faster reconfiguration between test protocols without full chamber replacement.
Modular gas extraction skids is modularizing how laboratories scale capacity. These self-contained ventilation and filtration units allow facilities to add throughput incrementally rather than committing to monolithic walk-in installations. Automotive validation centers in Michigan and Bavaria are adopting this approach to parallelize multiple abuse-test sequences. The shift is compressing capital deployment timelines from 24 months to under 12 for expanded thermal runaway testing capacity.
EU AI Act documentation requirements are mandating algorithmic traceability for any automated test-result interpretation deployed within European battery supply chains. Chamber vendors must now embed audit-logging capabilities that record every sensor reading, threshold crossing, and safety-system activation. German OEM qualification labs are demanding this functionality preemptively, anticipating CSRD-aligned reporting obligations that will extend to safety-critical testing equipment.
Buyer preference is hardening around integrated validation partnerships rather than discrete equipment transactions. Cell manufacturers in South Korea and Japan increasingly contract chamber vendors for multi-year test-program management spanning installation, protocol development, and regulatory submission support. This bundling displaces traditional capital-equipment purchasing patterns and concentrates vendor relationships around firms with in-house certification expertise and regional regulatory presence.
Battery Fire and Explosion Containment Test Chambers Market Segmentation
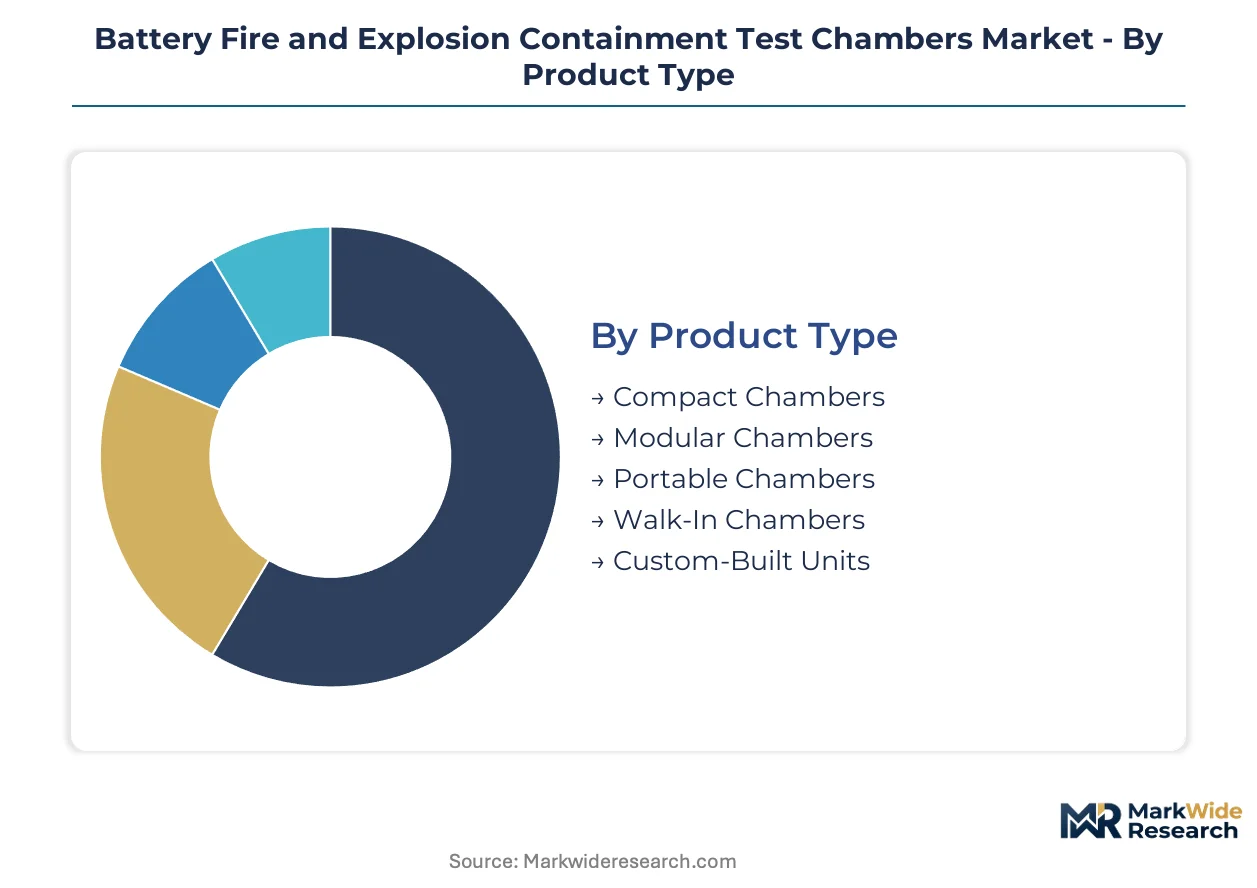
Segmentation in this market tracks how certification requirements fragment procurement decisions across product scales and end-use complexity. Each segment carries distinct regulatory burdens that determine capital deployment timing and vendor selection criteria.
Product Type:
UL 9540A and UN 38.3 certification burdens scale directly with chamber size and customization depth, forcing buyers to match product tier with their validation roadmap.
- Walk-In Chambers:Reinforced steel enclosures exceeding 20 cubic meters accommodate full battery pack assemblies and energy storage system modules. Automotive OEMs in Germany and South Korea are procuring these for gigafactory-adjacent validation centers where IEC 62660 compliance gates cell qualification.
- Custom-Built Units:Engineered-to-specification installations integrate site-specific gas extraction, HVAC coupling, and multi-protocol thermal cycling. These command extended certification timelines but dominate grid-scale battery testing in California and Texas where UL 9540A propagation testing is mandatory.
- Compact Chambers:Footprint-optimized units serve high-throughput consumer electronics validation in Shenzhen and Seoul laboratories.
- Modular Chambers:Configurable subsystems enable incremental capacity expansion without full facility recertification.
- Portable Chambers:Mobile units support field validation and supplier audit programs across dispersed manufacturing footprints.
Leading the category by volume: Walk-In Chambers. Growing fastest: Custom-Built Units.
Technology:
Technology selection determines which regulatory protocols a chamber can execute and how vendors monetize beyond hardware sales.
- Remote Monitoring:Real-time thermal telemetry and predictive maintenance algorithms enable recurring diagnostics contracts. EU AI Act documentation requirements in Germany and France are mandating audit-logging capabilities that this technology segment delivers.
- Pressure Venting:Multi-stage gas release systems prevent deflagration propagation while maintaining test reproducibility. This technology anchors certification against IEC 62660 and UL 9540A standards in automotive validation centers.
- Thermal Resistance:Multi-layer insulation rated beyond 1,000°C contains thermal runaway events without structural compromise.
- Fire Suppression:Integrated agent delivery systems extinguish lithium-ion cell fires without contaminating test specimens.
- Explosion Relief Systems:Rapid-actuation panels and burst-disk assemblies protect personnel during catastrophic failure simulation.
Remote Monitoring commands the highest service-attach margins. Pressure Venting sees the steepest expansion trajectory as UN 38.3 transport certification tightens globally.
Application:
Application segmentation reveals how regulatory jurisdiction shapes chamber specification and procurement urgency.
- Electric Transportation:Cell-to-pack validation for passenger EVs, commercial trucks, and electric buses requires walk-in enclosures capable of simulating cascading thermal runaway. NHTSA and KBA qualification protocols in the United States and Germany are accelerating procurement.
- Energy Storage Systems:Grid-scale and residential battery deployments in California, Texas, and Australia mandate UL 9540A propagation testing that drives multi-cell chamber array installations.
- Consumer Electronics:Smartphone, laptop, and power tool battery testing favors compact, high-throughput configurations.
- Aerospace Components:eVTOL aircraft and electric propulsion systems are subject to emerging FAA thermal containment standards.
- Research Laboratories:Academic and government facilities require flexible protocol support across multiple battery chemistries.
Electric Transportation generates the largest absolute demand. Energy Storage Systems are expanding most quickly as grid deployment accelerates.
End User:
End user type determines procurement authority, budget scale, and whether chambers are deployed captive or through third-party validation services.
- Vehicle OEMs:Tesla, BMW, and Hyundai-Kia are building captive abuse-testing infrastructure to gate cell qualification before production ramp decisions. These buyers specify integrated validation partnerships spanning installation through regulatory submission.
- Battery Manufacturers:CATL, LG Energy Solution, and SK On require chamber arrays for UN 38.3 export certification and customer qualification programs.
- Testing Laboratories:Intertek, SGS, and TÜV Rheinland operate multi-protocol facilities serving fragmented cell producer demand.
- Safety Certification Bodies:UL and DEKRA deploy chambers for standard development and witness testing services.
- Material Developers:Electrolyte and separator innovators use compact units for early-stage thermal stability characterization.
Vehicle OEMs lead procurement by capital commitment. Battery Manufacturers are gaining share fastest as cell production capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chamber production concentrates in Germany, Japan, and the United States, while consumption pulls strongest toward South Korea and China as cell manufacturing scales. This geographic split creates procurement complexity for battery makers seeking qualified containment infrastructure near gigafactory sites.
United States
NHTSA qualification protocols and UL 9540A mandates from grid-scale deployments in Texas and California drive walk-in chamber procurement. The Inflation Reduction Act domestic content provisions incentivize captive testing infrastructure near Michigan and Tennessee automotive clusters. Detroit-area validation centers are expanding multi-cell arrays for cascading failure simulation.
Germany
KBA cell qualification requirements and EU AI Act documentation obligations tighten chamber specifications for BMW and Volkswagen supply chains. The CSRD reporting framework extends traceability demands to safety-critical testing equipment deployed across Bavaria and Lower Saxony. Munich and Stuttgart industrial corridors anchor European chamber fabrication capability.
South Korea
UN 38.3 export certification pressure from LG Energy Solution and SK On forces rapid chamber installation near Gwangju and Ulsan cell plants. MFDS alignment with IEC standards accelerates validation protocol harmonization. The Seoul Capital Area concentrates third-party testing laboratory capacity serving fragmented producer demand.
China
CATL and BYD production scale generates massive chamber demand, though domestic certification against GB standards lags UN 38.3 alignment for export markets. MIIT battery safety regulations tighten thermal runaway documentation requirements. Shenzhen and Ningbo testing hubs are procuring compact high-throughput configurations for consumer electronics validation.
Japan
METI-funded solid-state battery research creates specialized chamber demand for next-generation chemistries beyond lithium-ion. JIS standard development for automotive cells requires reproducible abuse-test infrastructure. Nagoya and Osaka industrial zones maintain pressure vessel welding expertise concentrated in ASME-certified fabrication yards.
Battery Fire and Explosion Containment Test Chambers Market Competitive Landscape
Top-tier vendors anchor integrated validation partnerships, while mid-tier fabricators compete on modular subsystem pricing. The vendor base stratifies across three archetypes: European heritage firms with service-attach economics, North American scale manufacturers with domestic production advantages, and East Asian specialists in thermal-cycling integration. Competitive moves concentrate on multi-year test-program management contracts and software-defined remote monitoring capabilities that shift revenue toward recurring diagnostics.
Within the European heritage tier, Weiss Technik GmbH and Angelantoni Test Technologies S.p.A. represent vendors leveraging regional installed bases to anchor long-term service agreements. Among North American manufacturers, Thermotron Industries occupies a position exemplifying domestic fabrication scale. ESPEC Corp. sits within the East Asian specialist archetype, with its corporate structure indicating Japanese origin and thermal equipment focus. These three anchors illustrate how geographic concentration of engineering talent and certification expertise shapes competitive positioning across procurement decisions.
| Leading Market Players |
|---|
| Weiss Technik |
| Thermotron Industries |
| CSZ Industrial |
| Russells Technical Products |
| TotalShield |
| T3 EnviroCorp |
| Hanse Environmental Testing Equipment |
| Angelantoni Test Technologies |
| ESPEC |
| Others |
Pricing and Supply Chain Analysis
ASME Section IX certified welders concentrated in Central European and Japanese fabrication yards anchor labor-cost differentials that widen pricing-tier spreads between premium custom-built units and economy-grade compact chambers. Buyers in Germany and South Korea absorb 20-35% premiums for documented pressure-vessel pedigree, while procurement officers in China and Southeast Asia prioritize footprint-optimized configurations where welding certification requirements remain less stringent.
Pricing Analysis
Margin tightening in standard-tier walk-in chambers reflects nickel-alloy steel spot volatility and extended ASME certification timelines. Three-tier pricing structure across premium, standard, and economy levels separates custom-built installations with integrated gas extraction from modular configurations with detachable ventilation skids. Price differentiation hinges on UL 9540A pre-certification status and bundled multi-year diagnostics contracts. Battery manufacturers in South Korea exhibit highest price sensitivity due to UN 38.3 export volume pressure, while German automotive OEMs prioritize traceability documentation over unit cost.
Supply Chain Analysis
Domestic-content provisions in the US Inflation Reduction Act and EU Green Deal industrial plans are reshaping sourcing patterns for pressure-rated vessel construction. Fabrication concentrates in Germany, Japan, and the United States, with high-strength carbon steel and nickel-alloy inputs drawing from South African ferrochrome and Kazakh stainless scrap. Single-source vulnerability in ASME-certified welding capacity creates procurement bottlenecks for custom walk-in orders. Distribution runs through direct vendor-OEM partnerships for automotive qualification centers, with third-party testing laboratories sourcing via regional equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a supply-constrained environment where certified pressure-vessel welding capacity limits vendor scaling velocity and props pricing power for incumbent fabricators with established ASME and EN ISO 9606 credentials.
For Market Incumbents: Deploy software-defined remote monitoring capabilities to capture recurring diagnostics revenue and deepen customer switching costs. Anchor multi-year test-program management contracts with German and South Korean automotive OEMs before emerging entrants accumulate IEC 62660 certification expertise. Defend against modular subsystem competitors by integrating predictive maintenance algorithms that satisfy EU AI Act documentation requirements. For New Entrants and Emerging Players: The 40-60% price-point gap between premium custom-built units and economy compact chambers opens white-space targeting in India and Southeast Asia second-life battery testing infrastructure. Target modular gas extraction skid configurations for laboratories seeking incremental capacity expansion without full facility recertification. Pursue go-to-market partnerships with regional testing laboratories lacking captive abuse-testing capabilities. For Investors and Strategic Acquirers: Re-rating potential sits with East Asian thermal-cycling specialists given UN 38.3 transport certification tightening across Chinese and South Korean export corridors. Long-term viability favors vendors with demonstrated pressure-vessel pedigree and in-house regulatory submission expertise. Monitor ASME-certified welding capacity expansion announcements as inflection indicators for vendor scaling velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Investment | UL 9540A pre-certified chamber designs compress customer procurement cycles by 12-18 months. |
| Modular Subsystem Development | Detachable gas extraction skids enable laboratory capacity expansion without full facility recertification. |
| Remote Diagnostics Platform | Real-time thermal telemetry satisfies EU AI Act audit-logging mandates for automated test interpretation. |
| Regional Fabrication Footprint | ASME-certified welding capacity near Michigan and Bavaria automotive clusters reduces logistics exposure. |
| Integrated Validation Partnership | Multi-year test-program management contracts displace discrete equipment purchasing patterns in South Korea. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with pressure-vessel engineering directors, battery manufacturer qualification leads, third-party testing laboratory procurement officers, and automotive OEM safety validation managers. SEC 10-K disclosures, IEC standard development documentation, UN transport regulation submissions, and national customs import records provided demand-side triangulation. Bottom-up chamber installation tracking across Germany, South Korea, and the United States was cross-validated against top-down gigafactory capacity announcements.
Product-type granularity modeled walk-in, custom-built, compact, modular, and portable configurations separately. Technology segmentation tracked remote monitoring, pressure venting, thermal resistance, fire suppression, and explosion relief systems. Application dimensions spanned electric transportation, energy storage systems, consumer electronics, aerospace components, and research laboratories. End-user categories captured vehicle OEMs, battery manufacturers, testing laboratories, safety certification bodies, and material developers. CAGRs were derived from segment-level demand build-ups tied to named gigafactory projects and regulatory mandate implementation schedules. Forecast inputs incorporated UL 9540A propagation testing adoption curves and UN 38.3 export certification volume assumptions.
Underlying measurement precision varies by segment; walk-in and custom-built chamber categories carry tighter precision than portable and modular configurations given concentrated vendor transparency. Forecasts reflect assumptions regarding regulatory harmonization timelines between IEC, UL, and UN certification regimes. Specific risks that could revise projections include ASME-certified welding capacity constraints, nickel-alloy steel price volatility, and extended third-party validation timelines for novel chamber architectures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.